
 Leather Belts Market | 2026-2036
Leather Belts Market Size, Share, and Industry Trends Forecast 2026-2036
Leather Belts Market Outlook
Asset-light licensing and third-party manufacturing partnerships is rewriting competitive entry barriers for mid-tier leather belt producers. Bottega Veneta leverages in-house Italian tannery relationships to sustain premium positioning across formal and designer categories. Tanner Goods anchors its market presence through direct-to-consumer channel control and transparent sourcing narratives. Dunhill competes on heritage craftsmanship while navigating wholesale dependence in department store distribution.
Leather belts are wearable waist accessories constructed from tanned animal hides, typically featuring metal buckles and measuring 28 to 46 inches in length with widths from 1 to 1.5 inches for standard applications. The primary commercial purpose spans functional garment support in workwear and uniform segments through ornamental fashion statements in luxury apparel. Formal belts dominate value pools due to corporate dress code persistence and replacement frequency in professional wardrobes, while online retail channels represent the fastest-growing distribution pathway as digital sizing tools and return logistics mature. Genuine leather commands sustained price premiums over faux leather alternatives despite growing vegan material experimentation in European markets.
REACH regulations administered by ECHA restrict chromium VI and certain azo dyes in leather tanning processes, elevating compliance costs for suppliers serving European Union distribution channels. The US EPA oversees wastewater discharge standards from tannery operations under Clean Water Act provisions, while California's Proposition 65 mandates warning labels for chromium exposure risks on leather goods sold within the state. Stakeholders must monitor evolving chemical restriction proposals across multiple jurisdictions and assess captive tannery investments versus outsourced compliance burden.
Market Dynamics
REACH compliance administered by ECHA is compressing tannery supplier margins while concentrating procurement relationships around certified Italian and Spanish full-grain leather clusters. This regulatory pressure is restructuring competitive entry barriers across formal and designer belt categories.
Growth Catalysts
- Formal Corporate Dress Codes:Sustained office attendance requirements in financial services and legal sectors drive replacement cycles for full-grain leather accessories in professional wardrobes.
- REACH Chemical Restrictions:ECHA's chromium VI and azo dye limitations are accelerating consolidation toward compliant Tuscan tannery clusters serving heritage and direct-to-consumer labels.
- Digital Sizing Tools:Virtual try-on technologies and AI-powered fit algorithms are reducing return rates for online belt purchases, expanding direct-to-consumer channel viability.
Market Restraints
- Hide Price Volatility:Cattle hide costs fluctuate with meat processing volumes and dairy herd cycles, compressing gross margins for mid-tier producers without captive tannery relationships.
- Supply Concentration Risk:Artisanal belt manufacturing clusters in Italy's Tuscany region create geographic vulnerability to regional labor disruptions or energy cost spikes.
- Vegan Material Substitution:Mycelium leather and pineapple fiber alternatives are capturing share in European fashion segments, pressuring traditional hide demand.
Strategic Opportunities
- Underpenetrated Indian Formalwear:Rising white-collar employment in Mumbai and Bangalore metro corridors is expanding addressable demand for corporate leather accessories.
- Repair and Resoling Services:Circular economy frameworks in France and Germany are creating subscription-based belt maintenance models extending product lifecycles.
- Blockchain Traceability:Integration of distributed ledger technology with RFID tagging is enabling premium pricing for verified hide-to-retail supply chain transparency.
Industry Challenges
- Artisan Skill Scarcity:Hand-stitching and edge-burnishing expertise is aging out in Italian manufacturing clusters without structured apprenticeship pipelines.
- Multi-Jurisdiction Compliance:Simultaneous adherence to California Proposition 65 warning requirements and ECHA REACH standards fragments quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leather Belts Market |
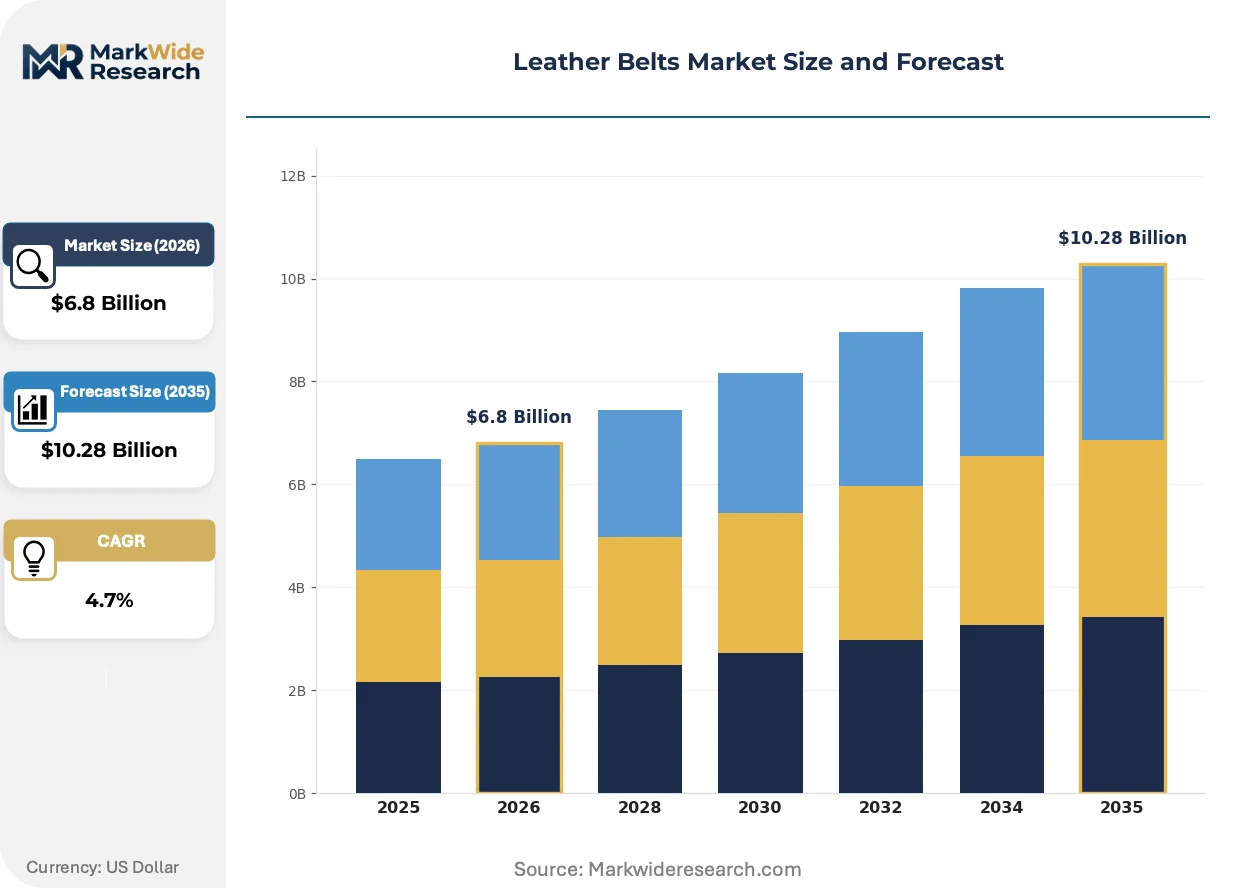
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Formal Belts, Casual Belts, Adjustable Belts, Designer Belts Material: Genuine Leather, Faux Leather, Suede, Nubuck Target Customer: Men, Women, Unisex, Children Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Coronado Leather, Anderson’s, Torino Leather Company, Mulberry, Dunhill, Tanner Goods, Bottega Veneta, Nordform, Scottsdale Belt Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leather Belts Market Strategic Shifts
Material science advances and regulatory transparency mandates are converging to reshape leather belt value chains. Three distinct vectors are compressing traditional production timelines while elevating provenance verification as a pricing determinant.
Laser engraving and CNC buckle fabrication is migrating from high-luxury ateliers to mid-tier producers, compressing customization lead times from weeks to days. Direct-to-consumer brands in the United States and Germany are deploying these tools for monogrammed corporate gifting programs. This technology diffusion is eroding the customization premium historically captured by heritage houses.
ECHA's expanded Substances of Very High Concern candidate list is forcing tannery investments in vegetable tanning alternatives and metal-free dye systems. Compliance costs are concentrating procurement around vertically integrated Italian suppliers with in-house laboratory certification capabilities. Small-batch producers without captive testing facilities are exiting European distribution channels.
Corporate buyers are consolidating vendor relationships around single-source accountability for ESG documentation. Multinational retailers in the United Kingdom and Netherlands are requiring third-party verified hide traceability from slaughterhouse to finished goods. This concentration is displacing fragmented supplier bases that cannot provide batch-level chemical disclosure records.
Leather Belts Market Segmentation
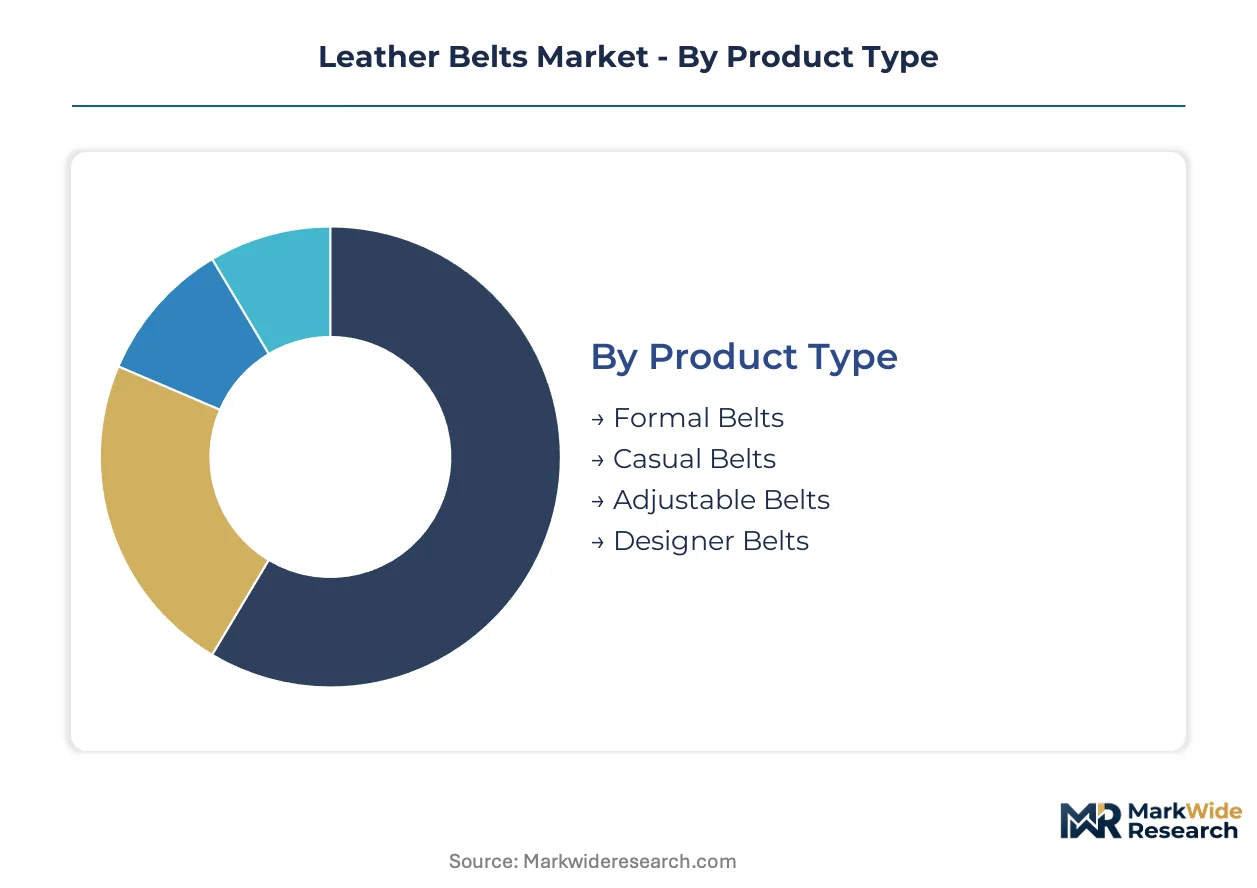
Leather belt segmentation reveals distinct demand patterns across use-case intensity, material authenticity requirements, and channel control preferences. Each dimension carries specific margin implications and regulatory exposure profiles that reshape procurement strategies for heritage houses and direct-to-consumer entrants.
Product Type:
Formal corporate environments generate sustained replacement cycles, while casual and adjustable formats serve intermittent use occasions with divergent price elasticity.
- Formal Belts:Constructed from full-grain leather with uniform 1.25-inch widths and conservative buckle finishes. Financial services and legal sector dress codes in London, New York, and Milan drive consistent procurement volume through heritage wholesale channels.
- Casual Belts:Feature distressed finishes, wider profiles up to 1.5 inches, and matte hardware. Weekend wear occasions in German and French metropolitan markets favor these specifications, though purchase frequency trails formal replacements by roughly half.
- Adjustable Belts:Deploy ratchet mechanisms or micro-hole systems for precise fit customization. Direct-to-consumer brands in California and Texas exploit this format to reduce sizing-related returns in digital channels.
- Designer Belts:Command price premiums through conspicuous hardware, signature stitching patterns, and limited production runs. Italian ateliers in Florence and Parma dominate captive manufacturing for these collections.
Established volume favors Formal Belts; emerging adoption favors Adjustable Belts.
Material:
Cost tiers stratify sharply around tanning method authenticity, with vegetable-tanned full-grain commanding sustained premiums over chrome-tanned alternatives and synthetic substitutes.
- Genuine Leather:Derived from cattle hides processed through chromium or vegetable tanning. Tuscan tanneries certified under ECHA REACH protocols supply heritage brands and emerging labels seeking provenance documentation for European distribution.
- Faux Leather:Polyurethane or polyvinyl chloride compositions mimicking grain patterns. Price-sensitive segments in Spain and Portugal absorb this material, though durability complaints limit repeat purchase rates relative to hide-based alternatives.
- Suede:Split-hide construction with napped surface treatment. Seasonal collections from Paris and Milan fashion houses drive concentrated demand during autumn-winter release cycles.
- Nubuck:Top-grain leather sanded for velvety texture with greater durability than suede. Outdoor and workwear applications in rural England and Scotland favor this specification for belt constructions.
Margin concentration resides in Genuine Leather; volume expansion occurs in Faux Leather.
Target Customer:
Gendered purchasing patterns diverge on replacement frequency, with professional menswear driving predictable refresh cycles and women's collections exhibiting greater style-driven volatility.
- Men:Dominate commercial volume through corporate wardrobe standardization. White-collar employment growth in Mumbai and Bangalore metro corridors is expanding addressable demand for full-grain formal accessories.
- Women:Exhibit higher SKU diversity requirements across width, color, and hardware variations. Direct-to-consumer brands in Berlin and Amsterdam deploy AI-powered recommendation engines to manage this complexity.
- Unisex:Minimalist designs with adjustable lengths and neutral hardware. Sustainability-focused retailers in Copenhagen and Stockholm favor this format for inventory efficiency.
- Children:Smaller scale production with elasticized or adjustable constructions. Back-to-school seasonal concentration creates demand spikes in August across North American and Western European markets.
Current revenue concentration favors Men; steepest expansion trajectory favors Women.
Distribution Channel:
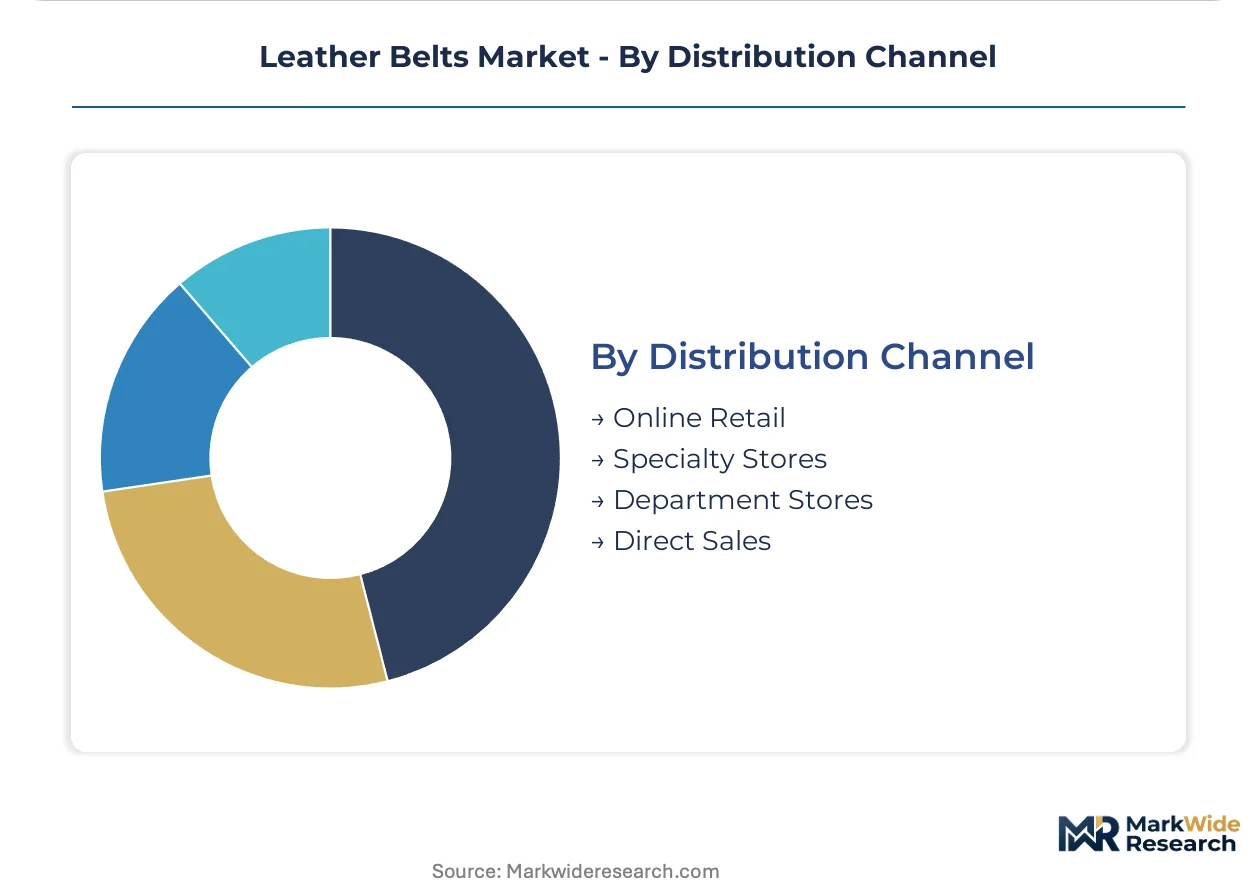
Channel control preferences segment around inventory risk tolerance, with digital-native brands accepting return logistics complexity to capture margin otherwise surrendered to wholesale intermediaries.
- Online Retail:Virtual try-on technologies and AI sizing algorithms are compressing fit-related return rates. German and United States direct-to-consumer operators exploit this infrastructure for monogrammed corporate gifting programs.
- Specialty Stores:Curated assortments with trained staff delivering fit consultation. Italian multi-brand retailers in Rome and Milan maintain this channel's relevance for premium full-grain procurement.
- Department Stores:Consolidated vendor relationships with demanding ESG documentation requirements. British and Dutch multinational retailers are displacing fragmented suppliers lacking batch-level chemical disclosure.
- Direct Sales:Brand-owned flagship locations and trunk show circuits. Heritage houses in Paris and London preserve this channel for experiential positioning and customization services.
Profitability favors Direct Sales; scaling velocity favors Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate procurement managers and heritage fashion buyers concentrate demand in manufacturing clusters with proven ECHA REACH compliance. Italian tanneries anchor premium supply chains while German direct-to-consumer operators exploit digital infrastructure.
Italy
Tuscan artisanal belt manufacturers serve heritage houses and emerging labels from Florence and Parma production clusters. ECHA REACH restrictions on chromium VI and azo dyes elevate compliance costs for tanneries without in-house laboratory certification. Full-grain leather procurement concentrates around Solofra and Santa Croce sull'Arno tanning districts.
United States
Financial services dress codes in New York and Chicago drive formal belt replacement cycles through wholesale and direct-to-consumer channels. California's Proposition 65 mandates chromium exposure warning labels on leather goods sold within the state. Austin and Los Angeles host adjustable belt specialists deploying AI sizing algorithms for digital channels.
Germany
White-collar employment in Frankfurt and Munich sustains corporate accessory demand with sustainability documentation requirements. ECHA-administered SVHC candidate list expansions force vegetable tanning investments among suppliers serving EU distribution. Berlin direct-to-consumer brands exploit circular economy frameworks for subscription maintenance models.
India
Rising professional employment in Mumbai and Bangalore metro corridors expands addressable demand for formal leather accessories. Bureau of Indian Standards quality certification governs domestic market entry for imported finished goods. Kanpur and Kolkata tanning clusters supply mid-tier producers targeting domestic corporate procurement.
United Kingdom
London-based multinational retailers consolidate vendor relationships around single-source ESG accountability. Department store buyers demand third-party verified hide traceability with batch-level chemical disclosure. Heritage houses maintain experiential positioning through Mayfair flagship locations and trunk show circuits.
Leather Belts Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered price positions. The vendor base clusters around heritage Italian ateliers with captive tannery relationships, direct-to-consumer operators exploiting digital infrastructure, and mid-tier producers dependent on third-party manufacturing partnerships. Strategic differentiation runs through backward integration into tanning operations, exclusive distribution arrangements, and customization technology deployment. Consolidation pressure favors players with in-house compliance certification for multi-jurisdiction chemical disclosure.
Among heritage Italian houses, Bottega Veneta exemplifies the vertically integrated archetype through captive Tuscan tannery relationships. Tanner Goods anchors the direct-to-consumer control model with transparent sourcing narratives and monogrammed corporate gifting programs. Dunhill occupies a position within the heritage wholesale tier, navigating department store distribution dependence while competing on craftsmanship positioning.
| Leading Market Players |
|---|
| Coronado Leather |
| Anderson's |
| Torino Leather Company |
| Mulberry |
| Dunhill |
| Tanner Goods |
| Bottega Veneta |
| Nordform |
| Scottsdale Belt Company |
| Others |
Value Chain & Pricing Dynamics
Hide price volatility tethered to cattle herd cycles and meat processing volumes compresses gross margins for mid-tier producers without captive tannery relationships, forcing three-tier pricing structure across premium, standard, and economy levels while driving consolidation toward vertically integrated Italian suppliers.
Pricing Analysis
Cost-plus contracts indexed to Chicago Mercantile Exchange hide futures dominate procurement between Tuscan tanneries and heritage belt manufacturers. Price differentiation centers on vegetable-tanned full-grain certification grade and ECHA REACH compliance documentation. Pricing pressure stems from mycelium leather substitution in European fashion segments. Corporate procurement managers in financial services exhibit lowest price sensitivity; Spanish and Portuguese mass-market buyers absorb greatest cost compression.
Supply Chain Analysis
Supplier financing through extended ninety-day payment terms and supply-chain finance facilities anchors working capital structures for artisanal manufacturers in Solofra and Santa Croce sull'Arno. Raw material sourcing draws from cattle hides processed in Italy, Spain, and Brazil. Single-source vulnerability concentrates in Tuscan tanning districts dependent on consistent energy supply. Distribution runs through heritage wholesale channels, direct-to-consumer digital platforms, and department store consolidators demanding batch-level ESG documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Belt repair and resoling subscription services in France and Germany expand faster than hardware unit sales, transforming transactional accessory purchases into recurring revenue relationships with predictable lifetime value expansion.
For Market Incumbents: Harden captive tannery relationships through in-house laboratory certification capabilities for ECHA REACH and California Proposition 65 compliance. Defend against mycelium leather substitution by investing in blockchain traceability infrastructure that validates hide-to-retail provenance for premium pricing retention.
For New Entrants and Emerging Players: Establish a beachhead in Mumbai and Bangalore formalwear corridors where white-collar employment growth outpaces heritage brand presence. Deploy AI-powered sizing algorithms and monogrammed corporate gifting programs to reduce customer acquisition costs in digital channels.
For Investors and Strategic Acquirers: ECHA's expanded Substances of Very High Concern candidate list reshapes the acquisition landscape by displacing small-batch producers without captive testing facilities. Long-term viability favors vertically integrated Italian ateliers with structured apprenticeship pipelines replacing aging artisan expertise. Monitor consolidation velocity among compliant Tuscan tanning clusters as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tannery Operations | ECHA REACH compliance costs concentrate procurement around certified Italian suppliers with in-house laboratory capabilities. |
| Direct-to-Consumer Channel Launch | Virtual try-on technologies and AI sizing algorithms reduce return rates for online belt purchases in German and United States markets. |
| Blockchain Traceability Implementation | Distributed ledger integration with RFID tagging enables premium pricing for verified hide-to-retail supply chain transparency. |
| Subscription Maintenance Model | Circular economy frameworks in France and Germany create recurring revenue through belt repair and resoling services. |
| Corporate Gifting Program Expansion | Laser engraving and CNC buckle fabrication compress customization lead times from weeks to days for monogrammed orders. |
Study Parameters
Cross-validation between primary interviews with tannery operations managers, heritage brand procurement directors, direct-to-consumer supply chain heads, and department store category buyers anchors the qualitative findings against secondary validation from customs records, SEC 10-K filings of listed leather goods companies, and ECHA substance restriction databases. Bottom-up and top-down triangulation reconciles production capacity data from Tuscan and Spanish tanning clusters with downstream shipment volumes through wholesale and digital channels.
Calibration against historical hide price cycles and regulatory implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material grade tier, target customer gender, and distribution channel control preference. CAGRs derive from regression analysis of replacement frequency data and employment growth in formalwear-dependent sectors. Forecast inputs incorporate ECHA SVHC candidate list expansion velocity and digital sizing technology adoption curves.
Stress conditions across cattle hide price volatility, ECHA compliance cost trajectories, and vegan material substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding dress code persistence in financial services and legal sectors. Macroeconomic contraction in white-collar employment, accelerated ECHA chemical restrictions, or breakthrough mycelium leather durability improvements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Smart Connected Washing Machine Market
Consumer Goods
Mini Refillable Perfume Bottles Market
Consumer Goods
Pet Grooming Products Market
Consumer Goods
Smoking Accessories Market
Consumer Goods
Saudi Arabia Cookware Market
Consumer Goods
Europe Electric Toothbrush Market
Consumer Goods
Italy Small Home Appliances Market
Consumer Goods
UAE Microwave Ovens Market
Consumer Goods
Body Balm Market
Consumer Goods
Brush Cleaner Market
Consumer Goods
Organic Baby Shampoo Market
Consumer Goods
Home Shopping Market
Consumer Goods
Australia Vegan Cosmetics Market
Consumer Goods
India Consumer Electronics Market
Consumer Goods
Global on-Premise-Laundry (OPL) Market
Consumer Goods
Side-By-Side Smart Refrigerator Market