
 Latin America Pet Insurance Market | 2026-2036
Latin America Pet Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Pet Insurance Market Analytics
Veterinary actuarial expertise is unwinding across Latin America as trained underwriters remain scarce outside São Paulo and Mexico City. Trupanion leverages direct-to-consumer digital platforms to bypass traditional broker networks. Royal & Sun Alliance anchors multi-country operations through established property-and-casualty infrastructure. Petplan Pet Insurance specializes in breed-specific pricing models that differentiate its risk assessment capabilities.
Latin America pet insurance constitutes risk-transfer contracts indemnifying owners against veterinary medical expenses, typically covering diagnostic imaging, surgical intervention, and pharmaceutical protocols with specified deductibles and co-payment structures. The primary commercial purpose centers on reducing financial barriers to advanced veterinary care while generating recurring premium revenue for underwriters. Illness Coverage dominates policy value pools as chronic condition treatments escalate, while Wellness Plans represent the fastest-growing segment as preventive care awareness spreads among urban owners. Monthly plan durations capture disproportionate new customer acquisition through lower entry barriers, though Annual contracts sustain superior retention economics.
Brazil's SUSEP and Mexico's CNSF regulate solvency requirements and policy form approvals, creating compliance thresholds that favor established carriers with local licensing. Argentina's SSFN imposes foreign capital restrictions that complicate regional underwriting capacity expansion. Stakeholders must monitor regulatory convergence toward IFRS 17 accounting standards and evolving veterinary telemedicine classification across national insurance codes.
Market Dynamics
SUSEP's regulatory modernization is compressing product approval timelines from eighteen months to under ninety days, enabling carriers to iterate coverage designs faster than legacy actuarial cycles permit.
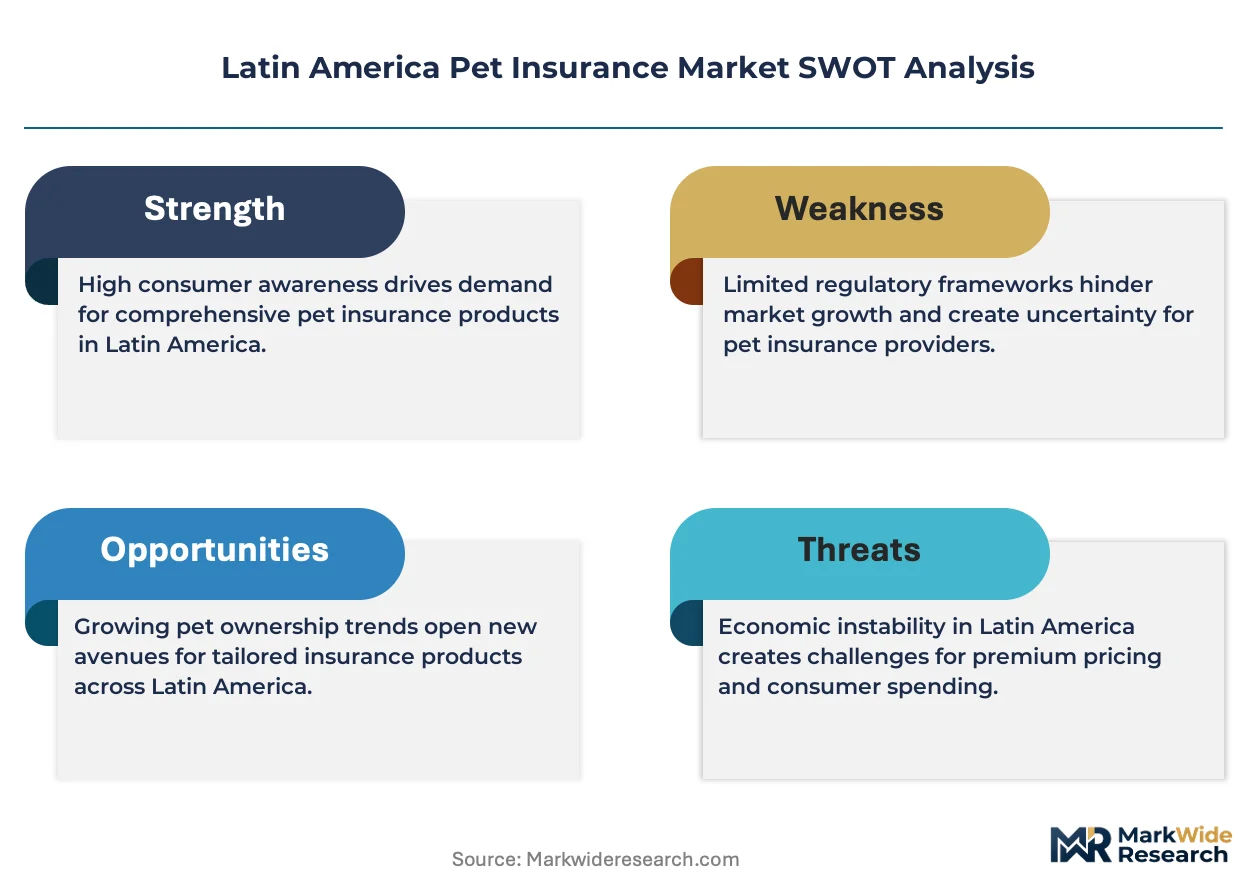
Growth Catalysts
- Telemedicine Classification:Brazil's national insurance code revisions now explicitly cover remote veterinary consultations, expanding reimbursable service categories beyond physical clinic visits.
- Millennial Household Formation:São Paulo and Mexico City apartment dwellers treat companion animals as family substitutes, generating demand for chronic condition riders previously absent in Latin American policy design.
- Embedded Distribution:Veterinary clinic point-of-sale platforms are integrating instant policy activation at checkout, collapsing traditional broker-mediated enrollment friction.
Market Restraints
- Veterinary Cost Volatility:Imported pharmaceutical and imaging equipment pricing fluctuates with peso and real exchange rate swings, compressing loss ratio predictability for underwriters.
- Actuarial Talent Concentration:Trained pet insurance underwriters cluster exclusively in São Paulo and Mexico City, leaving Argentine and Colombian markets dependent on remote pricing models.
- Foreign Capital Restrictions:Argentina's SSFN regulations limit reinsurance capacity from international markets, capping policy issuance volume during demand surges.
Strategic Opportunities
- Colombian Market Entry:Bogotá and Medellín veterinary infrastructure now supports specialty care tiers previously concentrated in Brazil and Mexico, creating first-mover positioning for digital-native carriers.
- Preventive Care Bundling:Wellness Plans covering vaccination schedules and dental cleanings remain underdeveloped outside São Paulo, offering premium expansion vectors.
- IFRS 17 Convergence:Regional accounting standard harmonization will simplify cross-border product portability for multi-country operators.
Industry Challenges
- Veterinary Data Fragmentation:Clinic electronic health record systems lack interoperability standards, forcing manual claims verification that extends loss adjustment expense ratios.
- Legacy Core System Integration:Established property-and-casualty carriers retrofitting pet modules onto decades-old policy administration platforms face eighteen-month implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Pet Insurance Market |
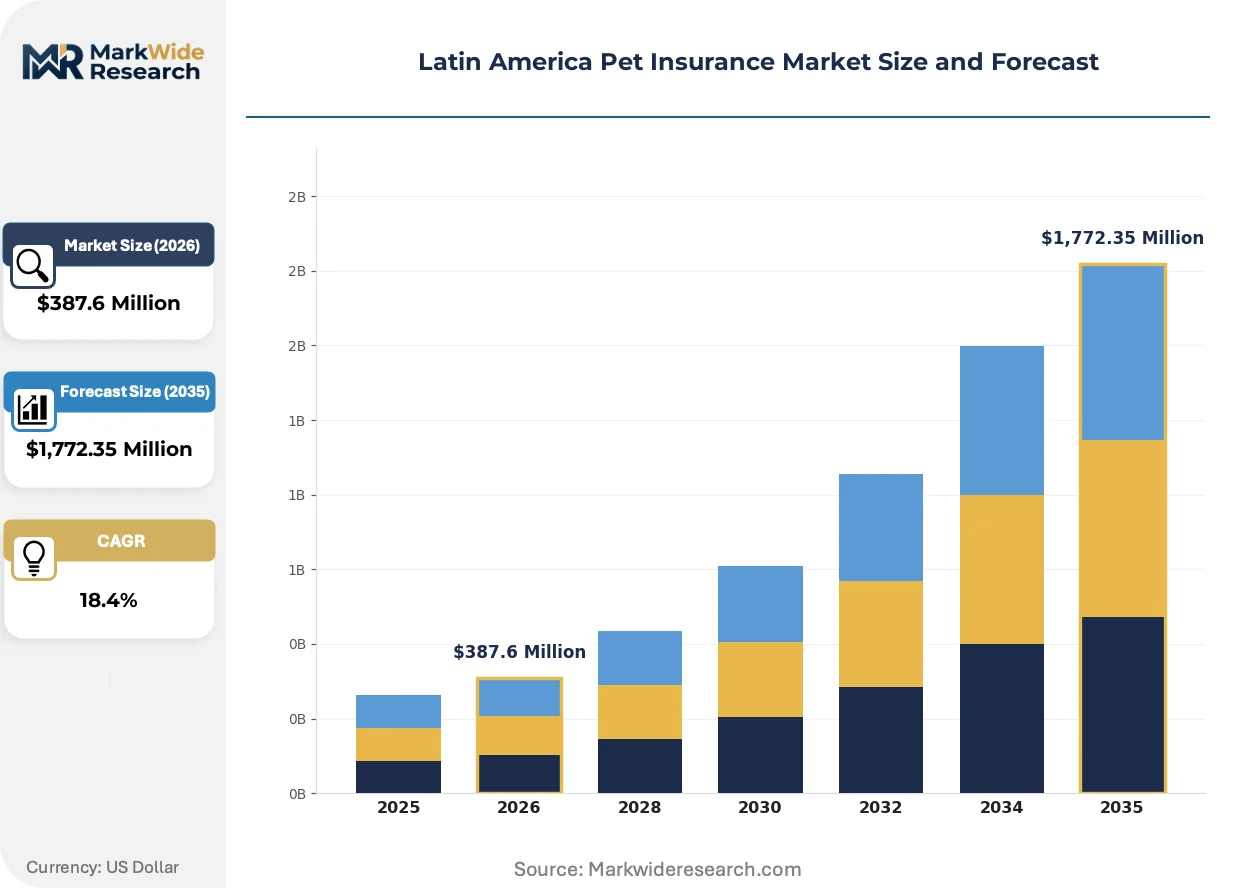
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accident Coverage, Illness Coverage, Wellness Plans, Comprehensive Plans End User: Dog Owners, Cat Owners, Exotic Pet Owners, Breeders Plan Duration: Annual, Monthly, Lifetime, Short-Term Distribution Channel: Online, Veterinary Clinics, Insurance Brokers, Pet Shops |
| Companies Covered | Embrace Pet Insurance Agency, Nationwide, Royal & Sun Alliance (RSA), Petplan Pet Insurance, Trupanion, Figo Pet Insurance, Agria Pet Insurance, Hollard Pet Insurance, Pets Best Insurance Services, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Pet Insurance Market Evolving Landscape
Digital distribution architectures are collapsing traditional broker networks while breed-specific risk modeling and embedded clinic partnerships redefine how policies reach end consumers.
Artificial intelligence-driven claims adjudication is supplanting manual veterinary invoice review. São Paulo-based carriers deploy computer vision algorithms to verify diagnostic imaging necessity within four hours. This compression is eliminating the fourteen-day settlement delays that previously drove policyholder churn.
Brazil's SUSEP has issued circular letters clarifying telemedicine reimbursement parity with in-person visits. The regulatory certainty is prompting carriers to launch app-based symptom triage tools. Mexico's CNSF is expected to issue comparable guidance within eighteen months, creating regulatory arbitrage opportunities for cross-border product designers.
Subscription-based billing is displacing annual lump-sum premiums among urban millennial cohorts. São Paulo fintech-enabled carriers offer monthly debits synchronized to salary cycles. Mexico City veterinary chains now white-label these products at point-of-care, capturing policyholders who abandoned traditional insurance due to upfront cost barriers.
Latin America Pet Insurance Market Segmentation
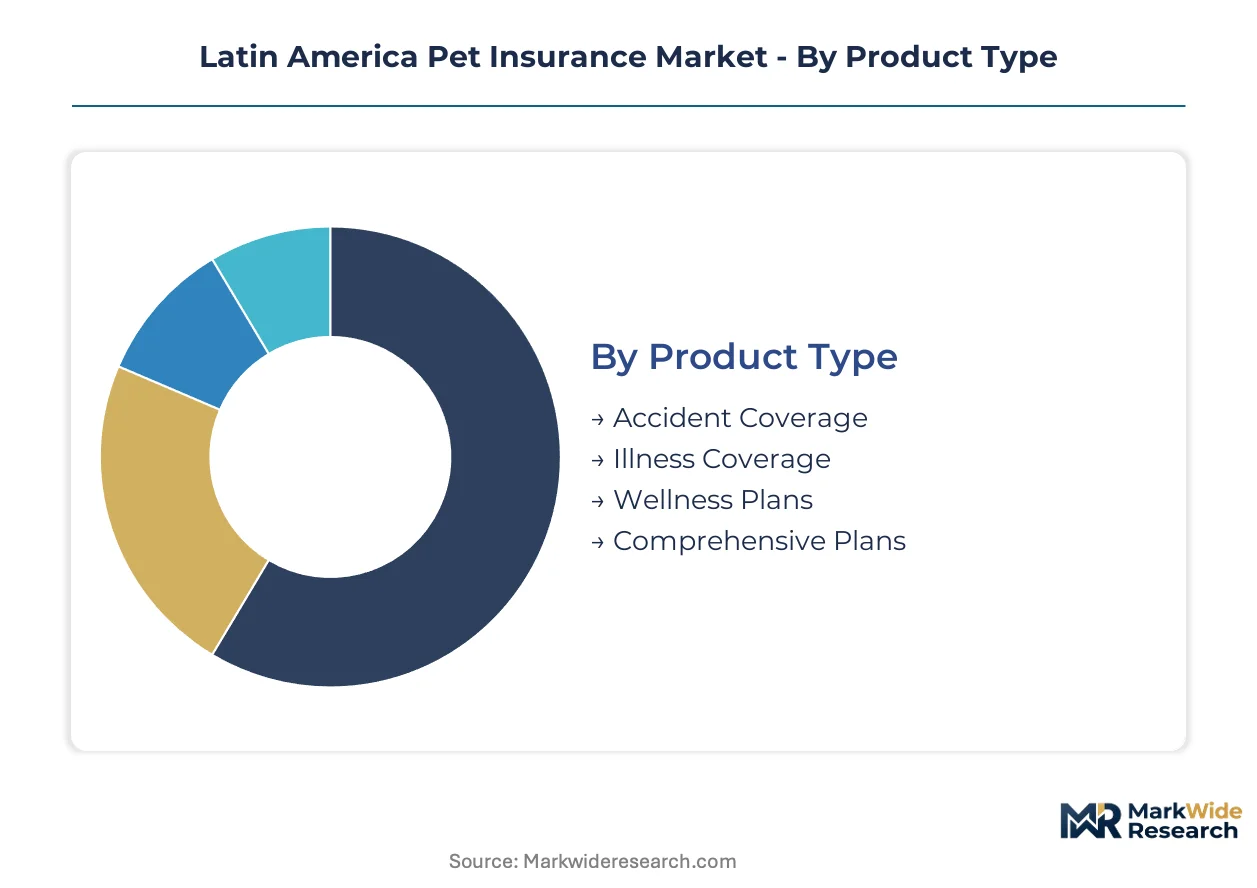
Segmentation in Latin American pet insurance reveals how regulatory frameworks, urban household structures, and veterinary infrastructure shape product design and distribution economics. Each dimension exposes distinct risk pools and acquisition cost structures that carriers must navigate across Brazil, Mexico, and emerging markets.
Product Type:
Brazil's SUSEP and Mexico's CNSF apply differentiated solvency requirements and policy form approval timelines across coverage categories, compressing innovation cycles for some products while extending validation periods for others.
- Illness Coverage:Policies indemnifying owners against diagnostic imaging, surgical intervention, and chronic condition pharmaceutical protocols. São Paulo and Mexico City households concentrate demand here as specialty veterinary infrastructure expands and owners seek financial protection against escalating treatment costs for cancer and renal disease.
- Wellness Plans:Preventive care bundles covering vaccination schedules, dental cleanings, and routine examinations. Urban millennial adopters in Brazil's southeast and Mexico's central region drive expansion here as pet humanization trends elevate routine care expectations.
- Accident Coverage:Emergency-focused policies addressing trauma, fractures, and toxic ingestion events.
- Comprehensive Plans:Combined accident-illness-wellness coverage with tiered deductibles.
Established volume favors Illness Coverage; emerging adoption favors Wellness Plans.
End User:
Customer acquisition costs vary dramatically across owner types, with digital-native urban segments showing 40% lower friction in embedded clinic distribution models compared to traditional broker-mediated channels.
- Dog Owners:The dominant policyholder base across Brazil and Mexico, with demand concentrated in large metropolitan areas where veterinary specialty care has achieved critical mass. Breed-specific pricing models and chronic condition riders generate premium expansion as owners seek coverage for hip dysplasia and cardiac conditions in predisposed breeds.
- Cat Owners:Faster-growing segment among apartment-dwelling millennials in São Paulo, Mexico City, and Bogotá. Lower per-incident claim severity but higher frequency of chronic renal and endocrine conditions shapes actuarial modeling distinct from canine risk pools.
- Exotic Pet Owners:Niche segment requiring specialized veterinary networks.
- Breeders:Commercial policyholders with multi-animal coverage needs.
Commercial concentration sits with Dog Owners; household formation momentum favors Cat Owners.
Plan Duration:
Cash flow predictability and retention economics diverge sharply between subscription and lump-sum billing structures, with fintech-enabled carriers exploiting salary-cycle synchronization to reduce churn.
- Monthly:Subscription-based billing synchronized to urban salary cycles, capturing price-sensitive entrants who abandoned traditional insurance due to upfront cost barriers. São Paulo fintech-enabled carriers and Mexico City veterinary chain white-labels dominate this expansion.
- Annual:Lump-sum premium structures sustaining superior retention economics and lower administrative cost ratios. Established property-and-casualty carriers with legacy core systems favor this structure for its operational simplicity.
- Lifetime:Continuous coverage without age-based renewal exclusions.
- Short-Term:Temporary policies for travel or transitional pet ownership periods.
Retention economics favor Annual contracts; customer acquisition velocity favors Monthly structures.
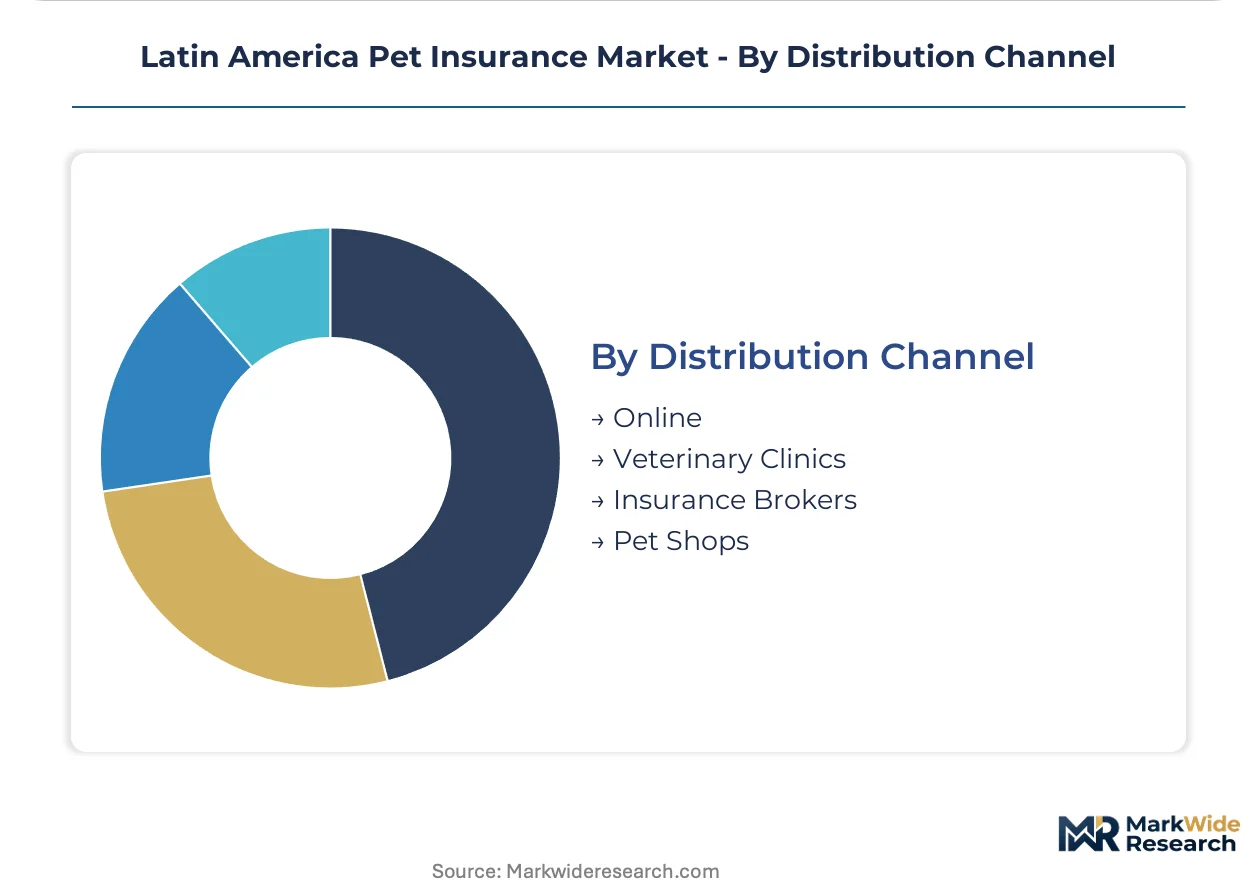
Distribution Channel:
Channel mix determines both customer acquisition cost structures and claims verification efficiency, with embedded clinic platforms collapsing traditional enrollment friction while introducing veterinary data fragmentation challenges.
- Veterinary Clinics:Point-of-sale policy activation at checkout integrates instant enrollment with treatment authorization. São Paulo and Mexico City specialty chains now white-label carrier products, capturing policyholders at moments of acute veterinary need.
- Online:Direct-to-consumer digital platforms bypassing broker networks, enabling Trupanion and digital-native carriers to achieve cost structures traditional insurers cannot match. Computer vision claims adjudication and app-based symptom triage accelerate settlement velocity.
- Insurance Brokers:Traditional intermediary channel with higher acquisition costs.
- Pet Shops:Retail-embedded distribution targeting first-time pet owners.
Cost efficiency favors Online platforms; conversion timing favors Veterinary Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil and Mexico concentrate policy value through chronic condition riders, while Colombia and Chile exhibit divergent consumption patterns favoring accident coverage and wellness bundles respectively.
Brazil
SUSEP's ninety-day approval compression enables faster product iteration than legacy actuarial cycles previously permitted. São Paulo specialty veterinary chains now white-label carrier products at point-of-care, capturing policyholders during acute treatment moments. Millennial apartment dwellers in Brazil's southeast drive chronic condition rider adoption as pet humanization elevates cancer and renal disease coverage expectations.
Mexico
CNSF solvency requirements create compliance thresholds favoring established carriers with local licensing infrastructure. Mexico City fintech-enabled carriers synchronize monthly debits to salary cycles, reducing upfront cost barriers that previously deterred traditional insurance uptake. The central region's veterinary infrastructure expansion now supports specialty care tiers comparable to São Paulo.
Argentina
SSFN foreign capital restrictions limit reinsurance capacity from international markets, capping policy issuance volume during demand surges. Buenos Aires concentrates the limited actuarial talent pool, leaving provincial markets dependent on remote pricing models from São Paulo and Mexico City underwriters. Currency volatility compresses loss ratio predictability for pharmaceutical and imaging equipment imports.
Colombia
Bogotá and Medellín veterinary infrastructure now supports specialty care tiers previously concentrated in Brazil and Mexico, creating first-mover positioning for digital-native carriers. The national insurance regulator has issued draft guidance on telemedicine classification, expected to formalize reimbursable remote consultation categories within eighteen months. Embedded clinic distribution remains underdeveloped outside major metropolitan areas.
Chile
Santiago's urban millennial households exhibit faster wellness plan adoption than regional peers, driven by preventive care awareness campaigns from international veterinary chains. The national insurance supervisor has converged toward IFRS 17 accounting standards ahead of regional peers, simplifying cross-border product portability for multi-country operators. Southern regions lack specialty veterinary density, constraining comprehensive plan penetration.
Latin America Pet Insurance Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with property-and-casualty conglomerates leveraging existing licensing infrastructure while digital-native carriers exploit fintech distribution advantages. The market structure bifurcates between legacy underwriters retrofitting pet modules onto decades-old core systems and cloud-native entrants deploying computer vision claims adjudication. Three archetypes dominate: multi-line insurers with captive distribution, direct-to-consumer digital specialists, and veterinary-chain-embedded white-label providers. Competitive moves concentrate on embedded clinic partnerships and monthly subscription billing synchronization.
Among North American-origin specialists, Trupanion exemplifies the direct-to-consumer digital archetype through app-based symptom triage and rapid settlement velocity. Royal & Sun Alliance anchors the multi-line integrated tier, leveraging established property-and-casualty infrastructure across Brazil and Mexico. Petplan Pet Insurance occupies the breed-specific risk modeling specialization, differentiating actuarial capabilities through granular canine and feline health data pools.
| Leading Market Players |
|---|
| Embrace Pet Insurance Agency |
| Nationwide |
| Royal & Sun Alliance (RSA) |
| Petplan Pet Insurance |
| Trupanion |
| Figo Pet Insurance |
| Agria Pet Insurance |
| Hollard Pet Insurance |
| Pets Best Insurance Services |
| Others |
Value Network & Pricing Analysis
Ninety-day product approval timelines at Brazil's SUSEP compress carrier iteration cycles while simultaneously constraining pricing flexibility, as accelerated regulatory compliance costs concentrate in São Paulo underwriting clusters and feed through to premium structures across the region.
Pricing Analysis
Subscription-based monthly billing dominates new customer acquisition, displacing annual lump-sum structures among fintech-enabled carriers in São Paulo and Mexico City. Price differentiation rests on embedded clinic partnerships versus direct-to-consumer digital platforms, with veterinary-chain white-labels commanding conversion premiums at point-of-care. Pricing pressure stems from exchange rate volatility on imported imaging equipment and pharmaceuticals, compressing loss ratio predictability. Urban millennial households exhibit highest price sensitivity, while specialty veterinary clinic networks show lowest friction for premium tier acceptance.
Supply Chain Analysis
Actuarial talent chokepoints in São Paulo and Mexico City tether regional underwriting capacity to these metropolitan clusters, leaving Bogotá and Buenos Aires dependent on remote pricing models. Brazil, Mexico, and Argentina concentrate veterinary infrastructure investment, though foreign capital restrictions at Argentina's SSFN cap reinsurance inflows during demand surges. Imported diagnostic equipment and specialty pharmaceuticals constitute critical input dependencies, exposing carriers to currency-driven cost volatility. Distribution runs through embedded veterinary clinic point-of-sale platforms, collapsing traditional broker-mediated enrollment friction while introducing claims verification complexity from fragmented electronic health record systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America pet insurance sits in early-cycle expansion as urban millennial household formation and SUSEP regulatory modernization compress product development timelines below legacy actuarial cycles.
For Market Incumbents: Fortify embedded clinic partnerships in São Paulo and Mexico City specialty veterinary chains before digital-native carriers achieve point-of-care saturation. Consolidate actuarial talent pools through targeted hiring in Brazil's southeast, countering remote pricing model dependency that threatens Argentine and Colombian market responsiveness. Invest in computer vision claims adjudication to compress settlement velocity below fourteen-day thresholds that currently drive policyholder churn.
For New Entrants and Emerging Players: Wellness plan bundling in Bogotá and Medellín represents the most penetrable white-space opportunity, as preventive care coverage remains underdeveloped outside Brazil's southeast. Target monthly subscription billing synchronized to salary cycles, exploiting fintech infrastructure gaps that established property-and-casualty carriers with legacy core systems cannot match. Pursue white-label partnerships with emerging veterinary chains in Colombia and Chile to bypass broker network establishment costs.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because embedded distribution and subscription billing create retention economics superior to traditional property-and-casualty lines. Acquisition candidates should demonstrate veterinary clinic partnership density exceeding 50 locations in a single metropolitan cluster, or proprietary breed-specific actuarial datasets that differentiate risk assessment from commodity competitors. Monitor CNSF telemedicine classification guidance issuance as the inflection signal for Mexican market acceleration comparable to Brazil's SUSEP circular letters.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Clinic Partnership Expansion | White-label carrier products at São Paulo specialty chains capture policyholders during acute treatment moments. |
| Computer Vision Claims Adjudication | São Paulo carriers deploy algorithms verifying diagnostic imaging necessity within four-hour settlement windows. |
| Monthly Subscription Billing Synchronization | Fintech-enabled debits aligned to salary cycles reduce upfront cost barriers deterring traditional insurance uptake. |
| Breed-Specific Actuarial Dataset Development | Granular canine and feline health data pools differentiate risk assessment capabilities from commodity competitors. |
| Telemedicine Platform Integration | App-based symptom triage tools leverage SUSEP regulatory certainty on remote consultation reimbursement parity. |
Research Methodology
Desk research of regulatory circular letters, veterinary industry association filings, and insurance supervisor solvency disclosures preceded structured interviews with pet insurance underwriters, veterinary clinic chain operations directors, and fintech platform product managers. Primary fieldwork across São Paulo, Mexico City, and Bogotá captured embedded distribution economics and claims verification workflows. Secondary validation drew from SUSEP policy form approval databases, CNSF insurer licensing records, and veterinary telemedicine regulatory drafts. Bottom-up premium volume estimates triangulated against top-down addressable pet population calculations.
Variance decomposition across product type, plan duration, distribution channel, and metropolitan market cluster shaped the analytical framework over the projection horizon. CAGRs derived from fitted adoption curves reflecting millennial household penetration rates and specialty veterinary infrastructure expansion timelines. Modeled inputs included chronic condition treatment cost trajectories, embedded clinic partnership density thresholds, and regulatory approval timeline compressions at SUSEP and CNSF.
Underlying assumptions cover sustained urban millennial household formation, stable SUSEP ninety-day approval timelines, and Colombian telemedicine classification formalization within eighteen months, with deviation risk concentrated in Argentine foreign capital restriction tightening and exchange rate volatility on imported veterinary equipment. Practitioners should keep alternative scenarios live as CNSF regulatory guidance evolution and IFRS 17 convergence timelines across Chile, Brazil, and Mexico reshape cross-border product portability economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Investment Analysis and Financial Strategies
Payment Security Market
Investment Analysis and Financial Strategies
China Payments Market
Investment Analysis and Financial Strategies
South Korea POS Terminals Market
Investment Analysis and Financial Strategies
UK Anti Money Laundering Solutions Market
Investment Analysis and Financial Strategies
United Kingdom E-Brokerage Market
Investment Analysis and Financial Strategies
Brazil Car Loan Market
Investment Analysis and Financial Strategies
Electronic Bill Presentment and Payment (EBPP) Market
Investment Analysis and Financial Strategies
CFD Trading Affiliate Programs Market
Investment Analysis and Financial Strategies
Global Digital Insurance Platform Market
Investment Analysis and Financial Strategies
Europe Factoring Services Market
Investment Analysis and Financial Strategies
North America Bank Kiosk Market
Investment Analysis and Financial Strategies
Europe Embedded Insurance Market
Investment Analysis and Financial Strategies
Europe Real Time Payments Market
Investment Analysis and Financial Strategies
United Kingdom Health and Medical Insurance Market
Investment Analysis and Financial Strategies
Biometric Payment Cards Market
Investment Analysis and Financial Strategies
US Online Trading Platform Market