
 Latin America Home Mortgage Finance Market | 2026-2036
Latin America Home Mortgage Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Home Mortgage Finance Market Foresight
Secondary market liquidity is tilting toward servicing rights and securitization platforms rather than pure origination volume. Bradesco leverages its retail branch density to dominate fixed-rate origination in Brazil. BBVA Bancomer anchors its position through proprietary digital underwriting engines that compress approval cycles. Caixa Economica Federal sustains the largest government-backed mortgage portfolio across Latin America.
Latin America home mortgage finance encompasses secured lending instruments collateralized by residential real estate, typically structured with loan-to-value ratios between seventy and eighty percent and amortization horizons spanning fifteen to thirty years. These instruments channel household savings into property acquisition while generating interest income for financial intermediaries. Fixed-rate mortgages command the deepest penetration among product types due to borrower preference for payment predictability amid currency volatility. First-time homebuyers represent the fastest-expanding customer segment as governments expand subsidized credit lines. Servicing operations capture disproportionate margin pools relative to origination because of recurring fee structures and lower capital intensity.
Brazil's central bank and Mexico's CNBV impose provisioning requirements and interest rate caps that constrain product design and geographic expansion. Colombia's financial superintendent adds consumer protection layers that lengthen disclosure timelines. Stakeholders must monitor how distributed ledger adoption in property registries alters collateral verification costs and fraud exposure.
Market Dynamics
Digital origination platforms are compressing approval cycles across Latin America, forcing traditional lenders to rebuild their front-end infrastructure around API-based underwriting engines and real-time collateral verification.
Growth Catalysts
- Brazilian Central Bank Housing Credit Policies:Interest rate subsidies and directed lending mandates are expanding first-time homebuyer access beyond major metropolitan centers into secondary cities.
- Blockchain Property Registries:Distributed ledger pilots in Colombia and Mexico are reducing title fraud exposure and collateral verification timelines from weeks to days.
- Urbanization Concentration:São Paulo and Mexico City metro corridors are generating mortgage origination density that justifies specialized servicing infrastructure investments.
Market Restraints
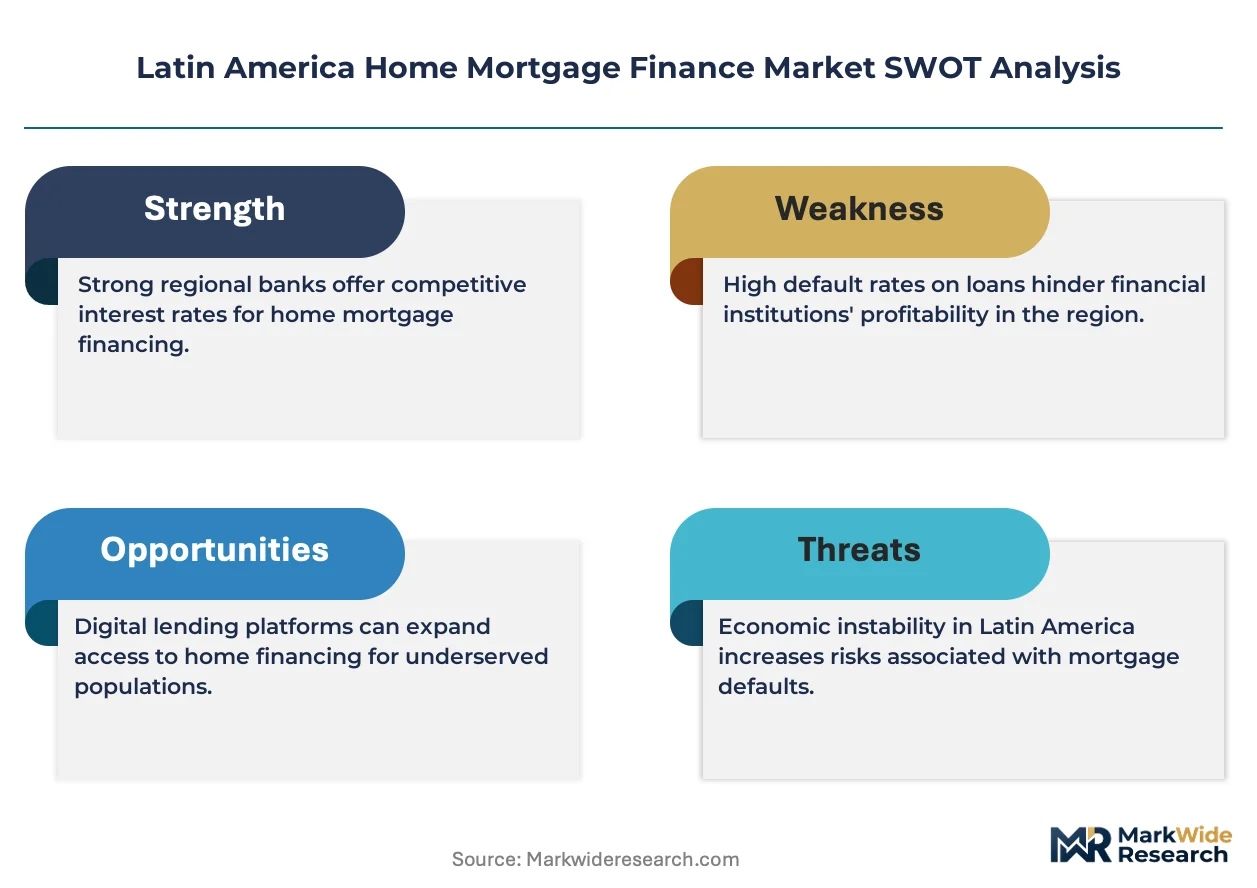
- Provisioning Requirements:Brazil's central bank and Mexico's CNBV impose capital reserves that constrain product design flexibility and geographic expansion into riskier municipalities.
- Currency Volatility:Peso and real fluctuation against dollar-denominated funding sources creates asset-liability mismatch risk for fixed-rate mortgage portfolios.
- Land Titling Deficits:Informal property ownership across Central America and the Andes blocks collateralization for an estimated one-third of residential stock.
Strategic Opportunities
- Colombia's Secondary Cities:Medellín and Cali mortgage penetration rates lag Bogotá by double digits, creating whitespace for digital-first entrants with lean cost structures.
- Green Mortgage Incentives:Energy efficiency certification requirements in Chile and emerging Brazilian federal programs reward sustainable construction with rate discounts.
- Embedded Finance Integration:Retail banking apps and proptech platforms are converging to offer point-of-sale mortgage pre-qualification during property search.
Industry Challenges
- Data Science Talent Scarcity:Credit scoring model development and alternative data integration require specialized analytics capabilities that outpace regional labor supply.
- Legacy Core Banking Migration:Mainframe-dependent institutions face multi-year timelines to modernize loan servicing systems for real-time customer interaction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Home Mortgage Finance Market |
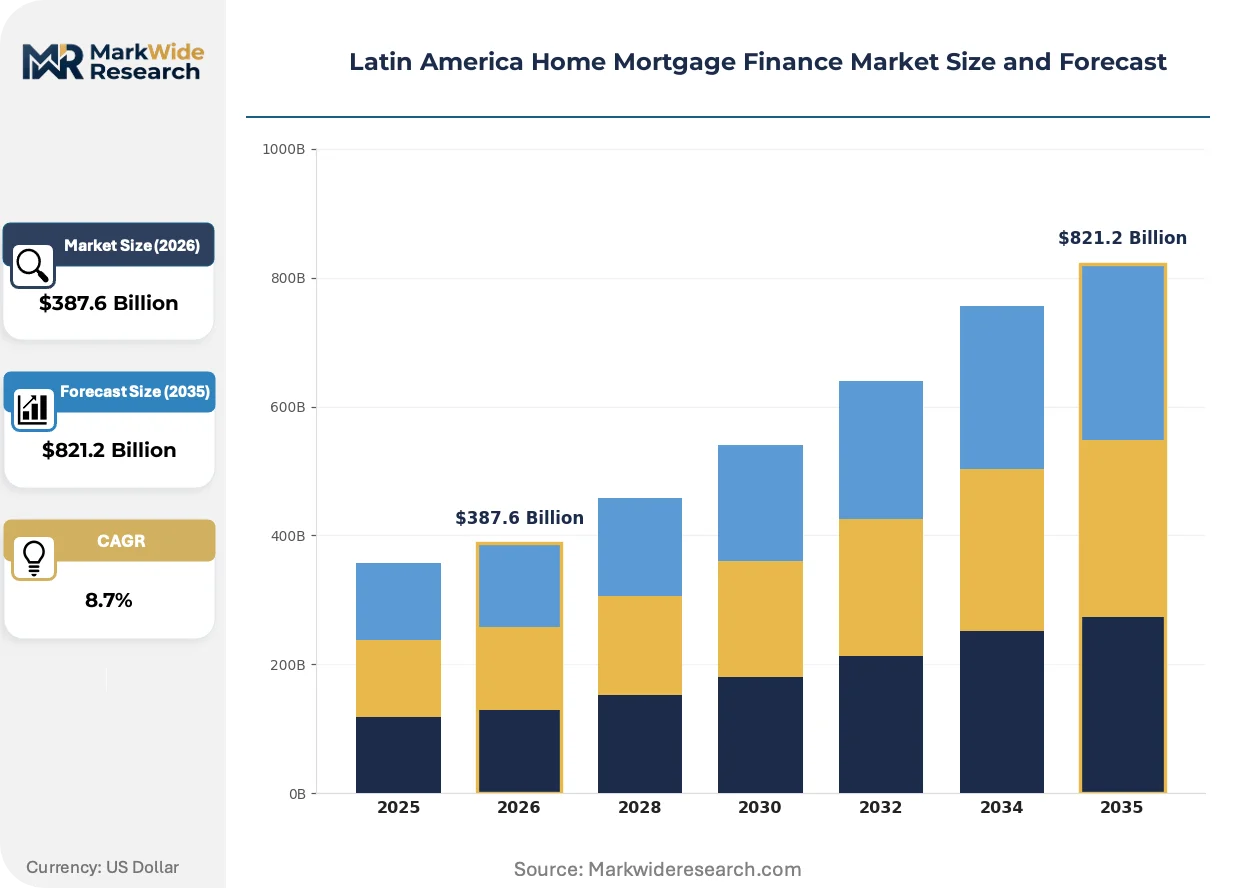
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Rate Mortgage, Variable-Rate Mortgage, Interest-Only Mortgage, Reverse Mortgage Customer Type: First-Time Homebuyers, Real Estate Investors, Homeowners, Refinancing Clients Loan Size: Small Loans, Medium Loans, Large Loans, Jumbo Loans Service Type: Origination Services, Servicing, Refinancing, Closing Services |
| Companies Covered | Bradesco, BBVA Bancomer, Caixa Economica Federal, Scotiabank, Citi Banamex, Banco do Brasil, Santander, Banco de Chile, Itau, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Home Mortgage Finance Market Shifts & Advancements
Artificial intelligence and open banking frameworks are reconfiguring how mortgage risk is priced and distributed across Latin America, shifting competitive advantage from balance sheet scale to algorithmic underwriting speed.
Machine learning credit scoring is digitizing borrower assessment for thin-file applicants previously excluded from formal mortgage markets. Fintech lenders in Mexico and Brazil deploy alternative data streams—utility payments, gig economy income patterns, mobile wallet history—to generate risk scores without traditional credit bureau reliance. This capability is digitizing access for informal workers who constitute forty percent of regional employment.
Brazil's central bank open finance regulations and Mexico's Fintech Law are mandating standardized data sharing protocols across financial institutions. These frameworks enable real-time income verification and cross-bank liability assessment that reduces fraud and default prediction error. Smaller lenders gain competitive parity with incumbents through API access to customer financial footprints previously hoarded by dominant retail banks.
First-time homebuyer segments are gravitating toward fully digital mortgage journeys that eliminate branch visits and notary appointments. Proptech platforms in São Paulo and Mexico City integrate virtual property tours with instant pre-approval and digital closing ceremonies. This channel shift pressures traditional lenders to unbundle origination from servicing and partner with technology intermediaries or risk customer acquisition cost escalation.
Latin America Home Mortgage Finance Market Segmentation
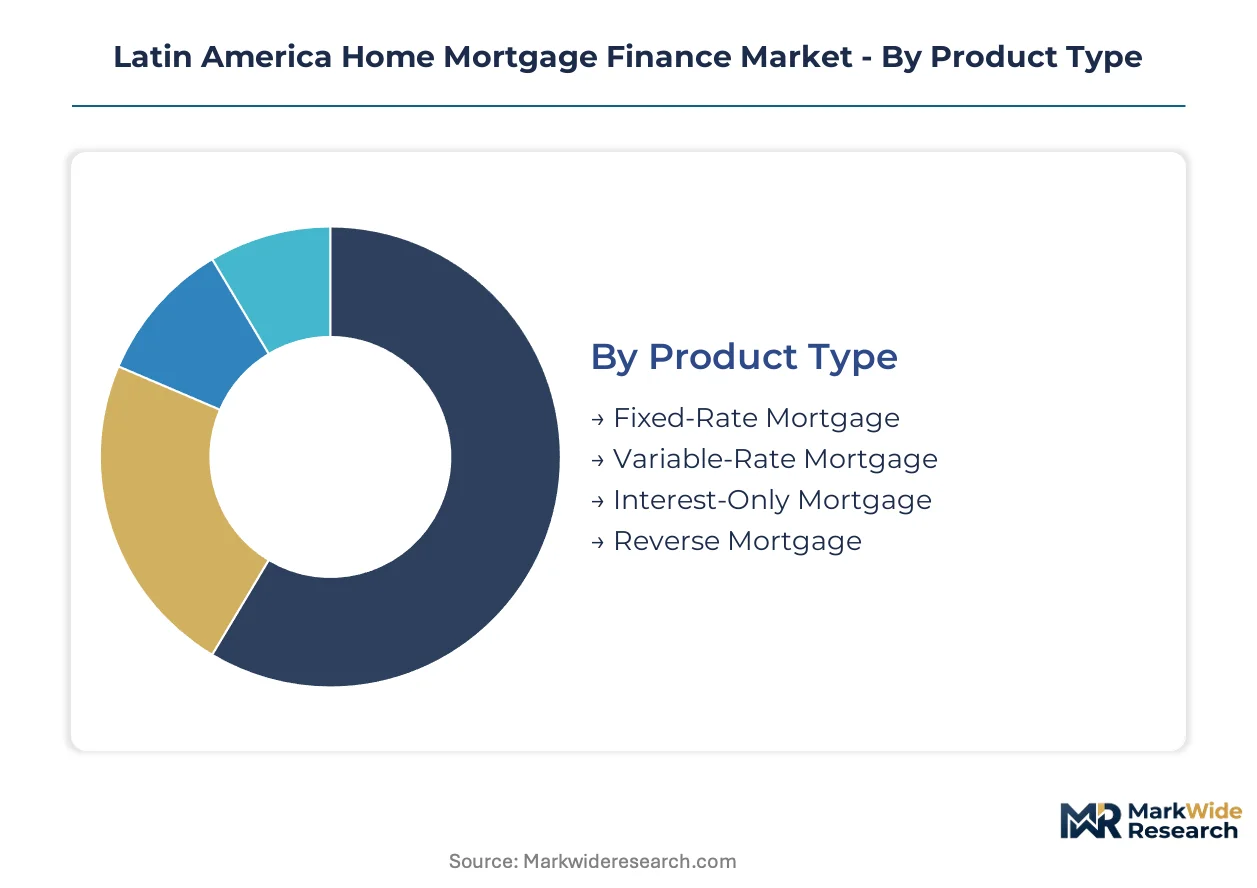
Mortgage product architecture across Latin America reflects borrower risk tolerance shaped by currency volatility and regulatory frameworks. Customer segmentation reveals divergent origination economics between subsidized first-time programs and investor-driven portfolio lending.
Product Type:
Mature fixed-rate instruments dominate balance sheets, while emerging variable structures gain traction among sophisticated borrowers seeking rate arbitrage.
- Fixed-Rate Mortgage:Long-term payment predictability shields Brazilian and Mexican borrowers from exchange rate turbulence. Demand concentrates in São Paulo and Mexico City metro corridors where Caixa Economica Federal and BBVA Bancomer deploy retail density for volume capture.
- Variable-Rate Mortgage:Floating benchmarks tied to central bank policy rates reduce lender funding risk. Penetration is climbing the fastest in Colombia's secondary cities where inflation-indexed instruments appeal to dollar-earning professionals.
- Interest-Only Mortgage:Cash-flow optimization for high-income segments with investable surplus.
- Reverse Mortgage:Liquidity extraction for aging homeowners in Chile's pension-adequate retirement system.
Fixed-Rate Mortgage handles the majority of throughput; Variable-Rate Mortgage is the fastest mover on share.
Customer Type:
Cost tier differentiation separates subsidized access programs from premium-priced investor lending.
- First-Time Homebuyers:Government credit lines and directed lending mandates expand formal market entry. Brazil's central bank housing subsidies and Mexico's INFONAVIT payroll deductions channel forty percent of regional origination volume through this segment.
- Real Estate Investors:Portfolio leverage strategies demand higher LTV tolerance and faster underwriting. Mexico City and Bogotá rental yield calculations drive pre-construction financing structures with balloon payment features.
- Homeowners:Equity release for renovation and education expenses.
- Refinancing Clients:Rate reduction seekers responding to central bank easing cycles.
First-Time Homebuyers handle the majority of throughput; Real Estate Investors are gaining share fastest.
Loan Size:
Volume concentration maps to urban property price gradients across the region's priciest metropolitan zones.
- Small Loans:Subsidized programs and peripheral city expansion. Brazil's Casa Verde e Amarela initiative caps eligible property values, directing small loan origination toward secondary municipalities beyond Rio de Janeiro and São Paulo cores.
- Medium Loans:Standard middle-class acquisition financing in Santiago and Monterrey.
- Large Loans:Premium property collateralization in gated communities and coastal developments.
- Jumbo Loans:Ultra-high-net-worth structuring with cross-border collateral and private banking integration.
Medium Loans handle the majority of throughput; Small Loans are expanding most quickly.
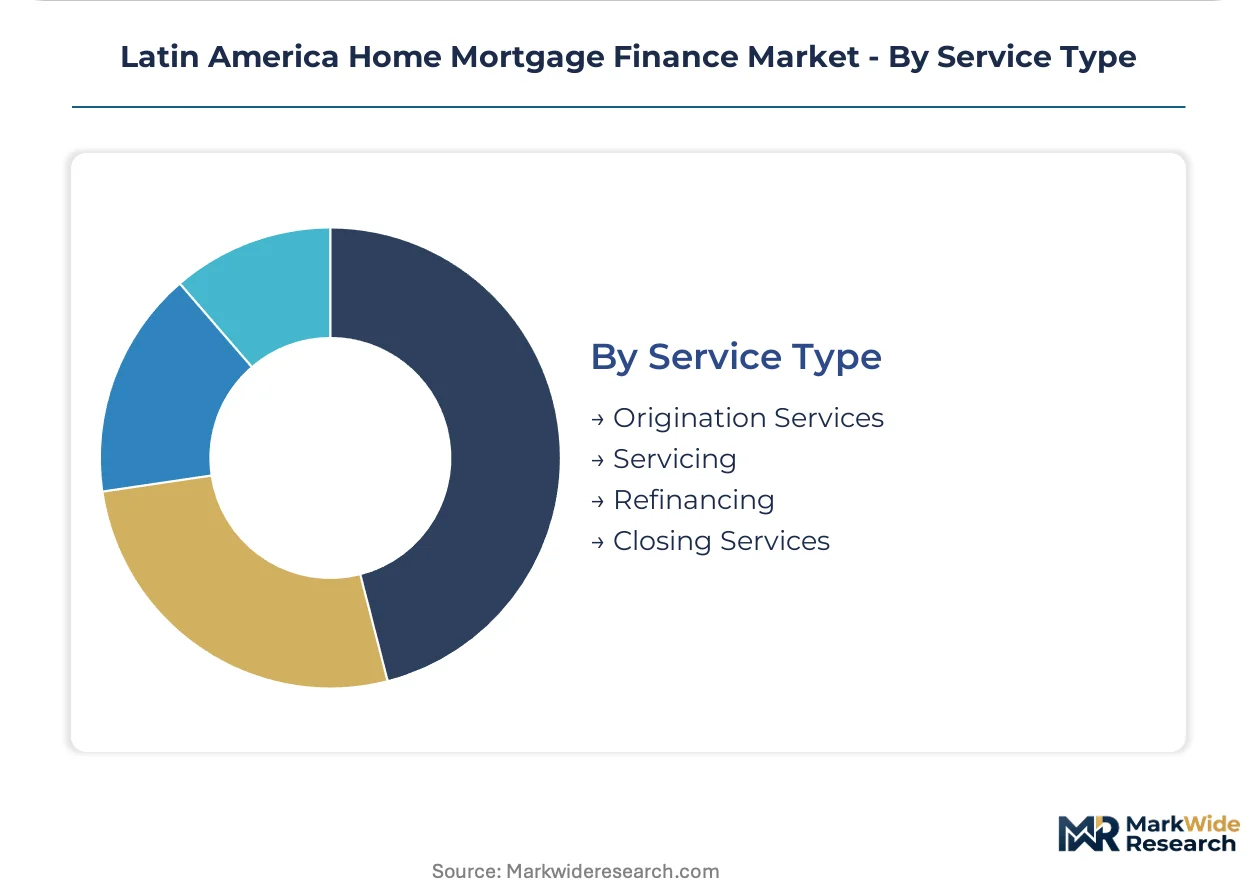
Service Type:
Margin architecture favors recurring revenue streams over transactional origination fees.
- Origination Services:Front-end customer acquisition and underwriting. Digital platforms in Brazil compress approval cycles from weeks to hours, forcing traditional lenders to rebuild API-based infrastructure around real-time collateral verification.
- Servicing:Payment processing, escrow management, and default workout. Lower capital intensity and fee permanence generate disproportionate margin pools relative to origination volume.
- Refinancing:Rate-driven portfolio retention and competitive poaching.
- Closing Services:Notarization, title insurance, and disbursement coordination.
Servicing handles the majority of throughput; Origination Services are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mortgage finance deployment varies sharply across Latin America. Brazil channels subsidized credit through state-directed programs. Mexico leverages payroll-linked housing funds. Colombia and Chile operate market-driven systems with private bank dominance.
Brazil
First-time homebuyer subsidies and directed lending mandates from the central bank accelerate formal market entry. The Casa Verde e Amarela program caps property values to direct credit toward secondary municipalities. São Paulo anchors origination volume while digital platforms compress approval cycles in Rio de Janeiro.
Mexico
INFONAVIT payroll deductions channel forty percent of regional origination through formal employment-linked housing funds. The CNBV imposes provisioning requirements that constrain product design flexibility. Mexico City metro corridors generate mortgage density justifying specialized servicing infrastructure.
Colombia
Medellín and Cali mortgage penetration rates lag Bogotá by double digits, creating whitespace for digital-first entrants. The financial superintendent adds consumer protection layers that lengthen disclosure timelines. Bogotá's rental yield calculations drive pre-construction financing structures.
Chile
Energy efficiency certification requirements reward sustainable construction with rate discounts. The pension-adequate retirement system supports reverse mortgage liquidity extraction for aging homeowners. Santiago concentrates middle-class acquisition financing.
Argentina
Currency volatility against dollar-denominated funding sources creates asset-liability mismatch risk for fixed-rate portfolios. The central bank's interest rate caps limit product variety. Buenos Aires metro area generates the bulk of formal mortgage origination despite macroeconomic headwinds.
Latin America Home Mortgage Finance Market Competitive Landscape
Capability concentration sits with digital-native fintech platforms; scale advantage sits with established retail banking networks. The market structures around three tiers: dominant universal banks with branch density, mid-size specialists with regional focus, and emerging digital lenders with algorithmic underwriting. Competitive moves center on API-based infrastructure partnerships and unbundling of origination from servicing functions.
Within the universal banking tier, Bradesco and Itau exemplify scale-driven origination through retail branch networks. BBVA Bancomer anchors a position through proprietary digital underwriting engines. Caixa Economica Federal occupies a distinct role as the largest government-backed mortgage portfolio holder across the region.
| Leading Market Players |
|---|
| Bradesco |
| BBVA Bancomer |
| Caixa Economica Federal |
| Scotiabank |
| Citi Banamex |
| Banco do Brasil |
| Santander |
| Banco de Chile |
| Itau |
| Others |
Supply & Pricing Matrix
Overcapacity in Brazil's mortgage servicing infrastructure is compressing origination margins while elevating fee-based servicing premiums, forcing lenders to rebalance front-end pricing against back-end recurring revenue capture.
Pricing Analysis
Long-term fixed-rate contracts dominate origination economics, with pricing stratifying across subsidized first-time programs, standard middle-market tiers, and premium investor-facing structures. Rate differentiation hinges on borrower credit bureau depth and geographic collateral risk, with Brazil's central bank policy rates transmitting directly to consumer pricing. Cost compression in digital origination channels is intensifying because fintech platforms eliminate branch overhead, while first-time homebuyers exhibit highest price sensitivity and ultra-high-net-worth segments show lowest elasticity.
Supply Chain Analysis
Upstream funding draws from Brazil, Mexico, and Chile's domestic deposit bases and international wholesale markets, with dollar-denominated liabilities creating currency mismatch exposure for fixed-rate portfolios. Key inputs include central bank liquidity facilities, securitization conduits, and property registry data services. Single-source vulnerability concentrates in legacy core banking systems from a handful of technology vendors. Distribution runs through retail branch networks, digital platforms, and payroll-linked employer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where central bank housing credit mandates and provisioning requirements erect barriers that favor established balance sheets over speculative entrants.
For Market Incumbents: Entrench dominance by acquiring servicing rights portfolios from distressed regional lenders in Colombia's secondary cities, and backward integrate into property registry data services to reduce collateral verification costs. Fintech algorithmic underwriting poses the primary substitution threat.
For New Entrants and Emerging Players: Pursue whitespace in Medellín and Cali mortgage penetration gaps, where digital-first cost structures overcome branch density disadvantages. Target first-time homebuyer segments with alternative-data credit scoring. Partner with proptech platforms for embedded pre-qualification at property search.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among servicing-centric platforms with government-backed portfolio mandates. Long-term viability favors acquirers of specialized servicing operations with central bank contractual relationships. Monitor blockchain property registry adoption velocity as inflection signal for collateral verification cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Servicing Rights Acquisition | Captures recurring fee streams with lower capital intensity than origination. |
| API-Based Underwriting Integration | Compresses approval cycles to match fintech competitor speed in São Paulo. |
| Blockchain Registry Partnership | Reduces title fraud exposure and collateral verification timelines in Colombia. |
| Alternative Data Credit Scoring | Expands addressable market to informal workers via utility payment history. |
| Green Mortgage Certification Program | Accesses rate discounts from Chilean energy efficiency requirements. |
Research Methodology
Initial hypotheses were tested against primary input from mortgage origination executives, servicing operations directors, central bank regulatory affairs officers, and proptech platform engineers, and refined through secondary validation against Brazil's central bank credit statistics, Mexico's CNBV regulatory filings, INFONAVIT annual reports, and regional securitization disclosure documents. Bottom-up origination volume estimates were triangulated with top-down housing stock penetration rates.
Demand-supply balance across the projection horizon was modeled through segmented analysis of product type, customer segment, loan size tier, and service type dimensions, with CAGRs derived from regression against macroeconomic drivers including urbanization rates and policy rate trajectories. Forecast inputs incorporated central bank housing credit allocation mandates and digital platform adoption curves.
Sensitivities concentrate around central bank policy rate shifts, currency volatility against dollar funding, and blockchain registry implementation timelines. Cross-checking against national housing finance authority origination disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Vietnam Self-Storage Market
Real Estate
India Luxury Residential Real Estate Market
Real Estate
Israel Commercial Real Estate Market
Real Estate
Warehousing Services Market
Real Estate
Kuwait Facility Management Market
Real Estate
Latin America Coworking Spaces Market
Real Estate
Latin America Facility Management Market
Real Estate
Greece Facility Management Market
Real Estate
Asia Pacific Co-Working Office Spaces Market
Real Estate
India Residential Real Estate Market
Real Estate
Saudi Arabia Real Estate Market
Real Estate
Airport Retailing Market
Real Estate
France Office Real Estate Market
Real Estate
Bahrain Flexible Office Space Market
Real Estate
Qatar Luxury Residential Real Estate Market
Real Estate
Qatar Facility Management Market