
 Kids Wear Market | 2026-2036
Kids Wear Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Wear Market Intelligence
Subscription box models for children's apparel are rebalancing the traditional, seasonal purchasing cycle toward a recurring revenue stream. Major brands are adapting to this shift in consumer behavior. Gap Kids leverages its extensive retail footprint and brand recognition to compete across both physical and digital channels. Uniqlo Kids specializes in functional, high-quality basics made from innovative materials, differentiating itself on performance and value within the sector. Primary focuses on gender-neutral designs and direct-to-consumer sales.
Kids wear comprises apparel specifically designed and sized for individuals from infancy through the preteen years. Manufacturing prioritizes fabric softness, seam durability, and the use of non-toxic dyes, with designs often incorporating features for ease of dressing and physical activity. Within age groups, the toddler and preschooler segments command significant volume, while the preteen category shows strong value growth. Cotton and cotton blends remain the dominant materials due to their breathability and hypoallergenic properties, while polyester gains share in performance and outerwear categories.
Product safety is governed by regulations like the US Consumer Product Safety Improvement Act (CPSIA), which sets limits on lead and phthalates in children's products. In Europe, REACH regulations restrict the use of certain chemicals in textiles, influencing material sourcing and finishing processes. These standards force manufacturers to maintain strict quality control and supply chain transparency. Brand survival now depends on navigating complex global supply chains while meeting consumer demand for both affordability and sustainable production.
Market Dynamics
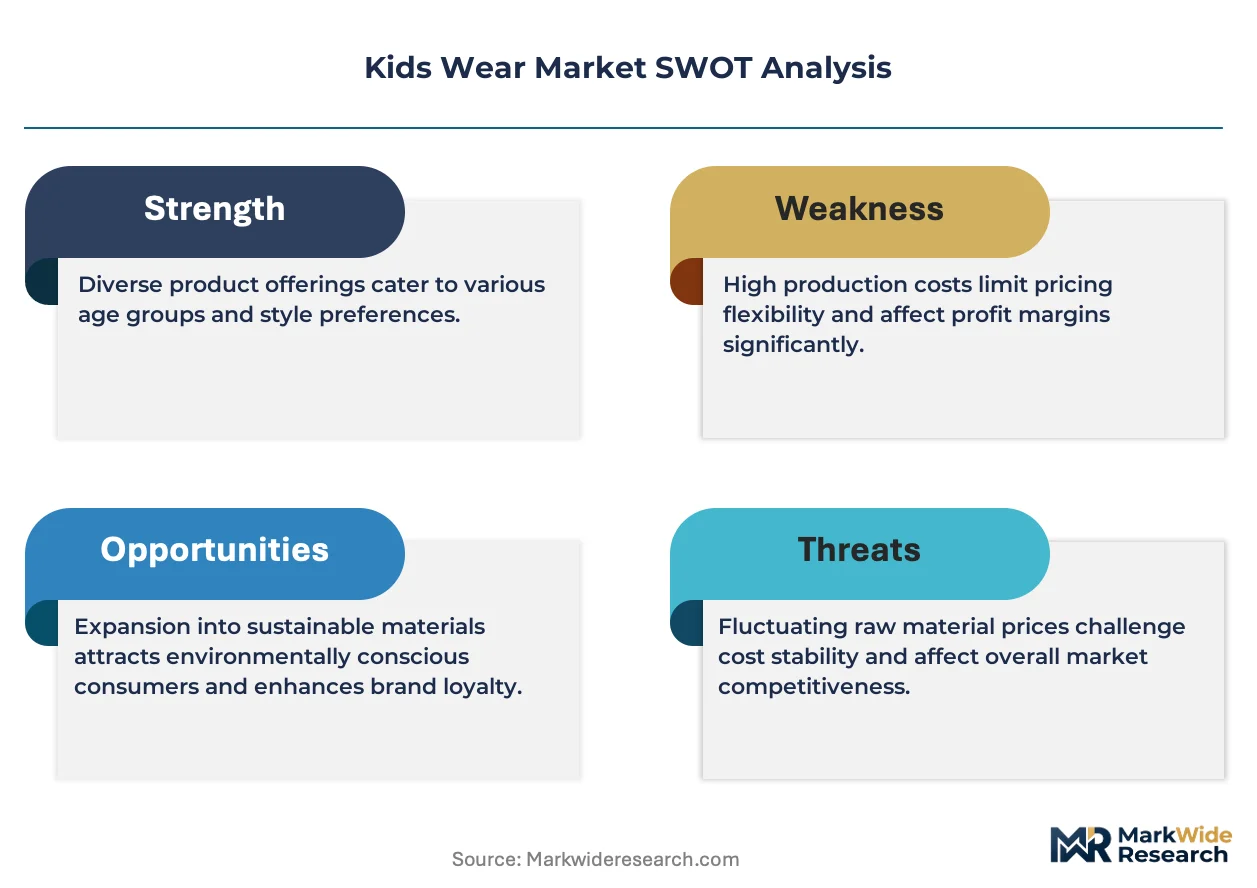
The central dynamic shaping the kids wear market is the structural conflict between parental demand for affordable, trend-driven apparel and escalating regulatory pressure for sustainable, transparent supply chains, a tension intensified by volatile raw material costs.
Growth Catalysts
- Regulatory Mandates:The EU's Corporate Sustainability Reporting Directive (CSRD) is accelerating the adoption of certified organic cotton and recycled polyester, as brands must now disclose environmental impacts, creating a demand pull for sustainable materials.
- Demographic Expansion:Expanding middle-class populations with high disposable incomes in countries such as China and India are driving volume growth, particularly in the premium and branded apparel segments for children.
- E-commerce Proliferation:The rise of direct-to-consumer (DTC) business models, enabled by global e-commerce platforms, allows niche brands focusing on gender-neutral or adaptive clothing to access markets without traditional retail investment.
Market Restraints
- Input Cost Volatility:Price fluctuations for key raw materials like organic cotton and recycled polyester, driven by climate events and inconsistent feedstock supply, directly impact manufacturer margins and final product pricing.
- Regulatory Fragmentation:Divergent chemical safety standards, such as the US Consumer Product Safety Improvement Act (CPSIA) and Europe's REACH regulations, create complex compliance burdens and increase testing costs for global brands.
- Supply Chain Concentration:A heavy reliance on manufacturing clusters in specific regions of Southeast Asia and China exposes the market to geopolitical risks, trade tariffs, and logistical disruptions that can halt production.
Strategic Opportunities
- Circular Economy Models:The expansion of apparel rental services and branded resale platforms for children's clothing presents an opportunity to create recurring revenue streams and appeal to environmentally conscious consumers in North America and Europe.
- Material Innovation:Commercializing next-generation sustainable materials, including plant-based leathers and textiles derived from agricultural byproducts, offers a path for brands to differentiate on performance and environmental credentials.
- Adaptive Wear:Designing apparel with features for children with physical disabilities or sensory sensitivities is an underserved market segment, offering growth potential for brands that invest in inclusive design and specialized materials.
Industry Challenges
- Supply Chain Traceability:Documenting and verifying the entire production chain to comply with forced labor regulations, such as the US Uyghur Forced Labor Prevention Act (UFLPA), requires significant investment in traceability software and supplier audits.
- Inventory Complexity:The proliferation of sizes, styles, and seasonal collections, combined with the rise of fast fashion cycles for kids, creates immense challenges in demand forecasting and inventory management, leading to overstock and markdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Wear Market |
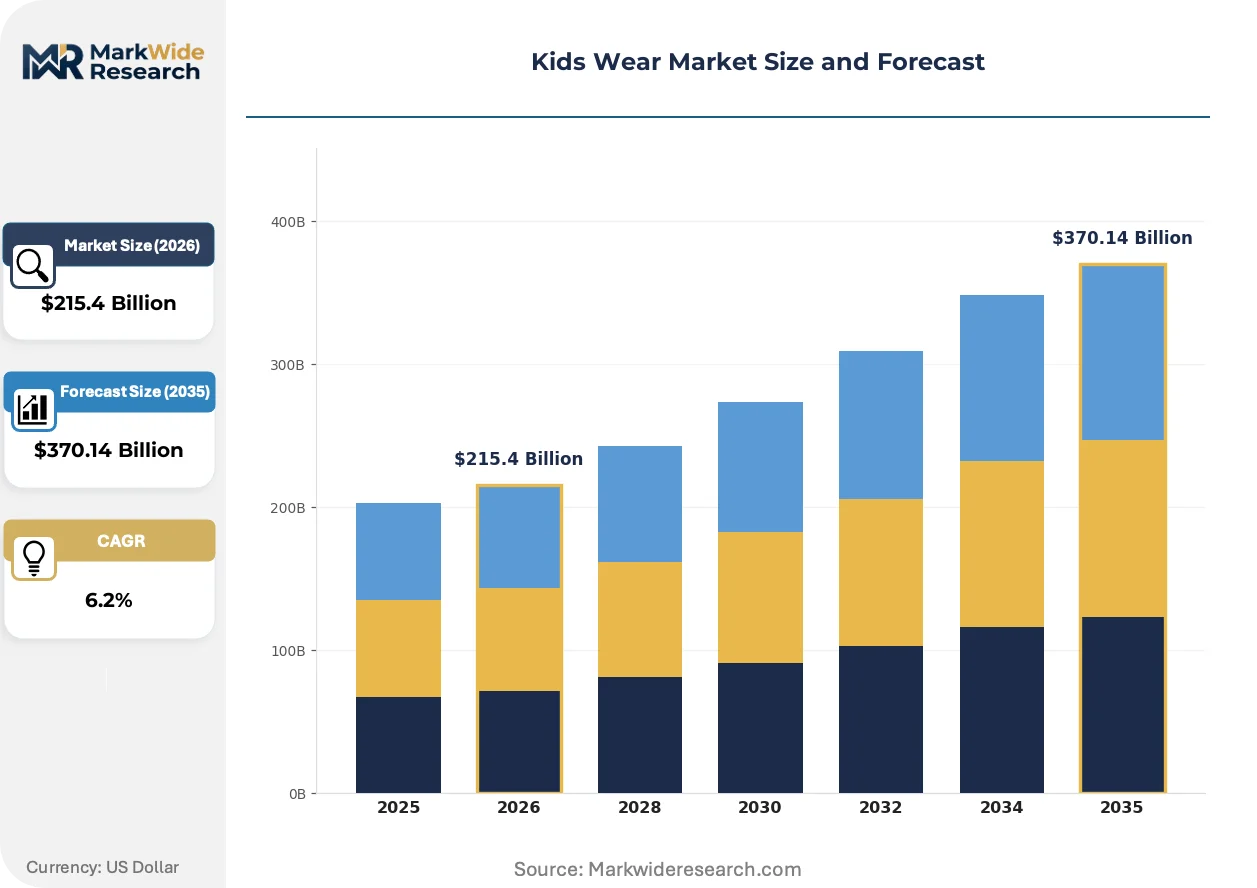
| Market Size in 2026 | $215.4 Billion |
| Market Size in 2035 | $370.14 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-Shirts, Jeans, Dresses, Jackets, Sweaters, Shorts Age Group: Newborns, Toddlers, Preschoolers, Early School Age, Preteens Sales Channel: Department Stores, Specialty Boutiques, E-commerce Platforms, Supermarkets, Direct-to-Consumer Material: Cotton, Polyester, Wool, Denim, Blends |
| Companies Covered | Quince, Gap Kids, Hanna Andersson, Appareify, Penguin Kids Wear, Primary, Uniqlo Kids, MMS Clothing, Old Navy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Wear Market Strategic Shifts & Innovations
The industrialization of sustainable practices and the digital transformation of the consumer experience are defining the current market trajectory. Technology enables brands to meet new ethical standards at scale while delivering more personalized products and services to parents.
Digital textile printing technology allows for rapid, small-batch production runs with minimal water usage compared to traditional dyeing. Direct-to-consumer (DTC) brands and customized apparel startups are the primary adopters of this technology. This on-demand manufacturing capability is decentralizing production from massive offshore factories to smaller, regional hubs that can respond quickly to local trends.
The US Federal Trade Commission's Green Guides are forcing greater accountability in environmental marketing claims. This policy framework requires brands to substantiate claims like "sustainable" or "eco-friendly" with competent and reliable scientific evidence. The baby and infant apparel category is most affected, as parents increasingly scrutinize material safety and sourcing information before purchase.
A fundamental shift from seasonal purchasing to curated, recurring deliveries is altering consumer behavior. The subscription box model directly challenges the traditional retail calendar and the need for parents to actively shop for new sizes and styles. This trend is most prominent within the toddler and preschooler segments in the United States, where convenience is a primary purchasing driver.
Kids Wear Market Segmentation
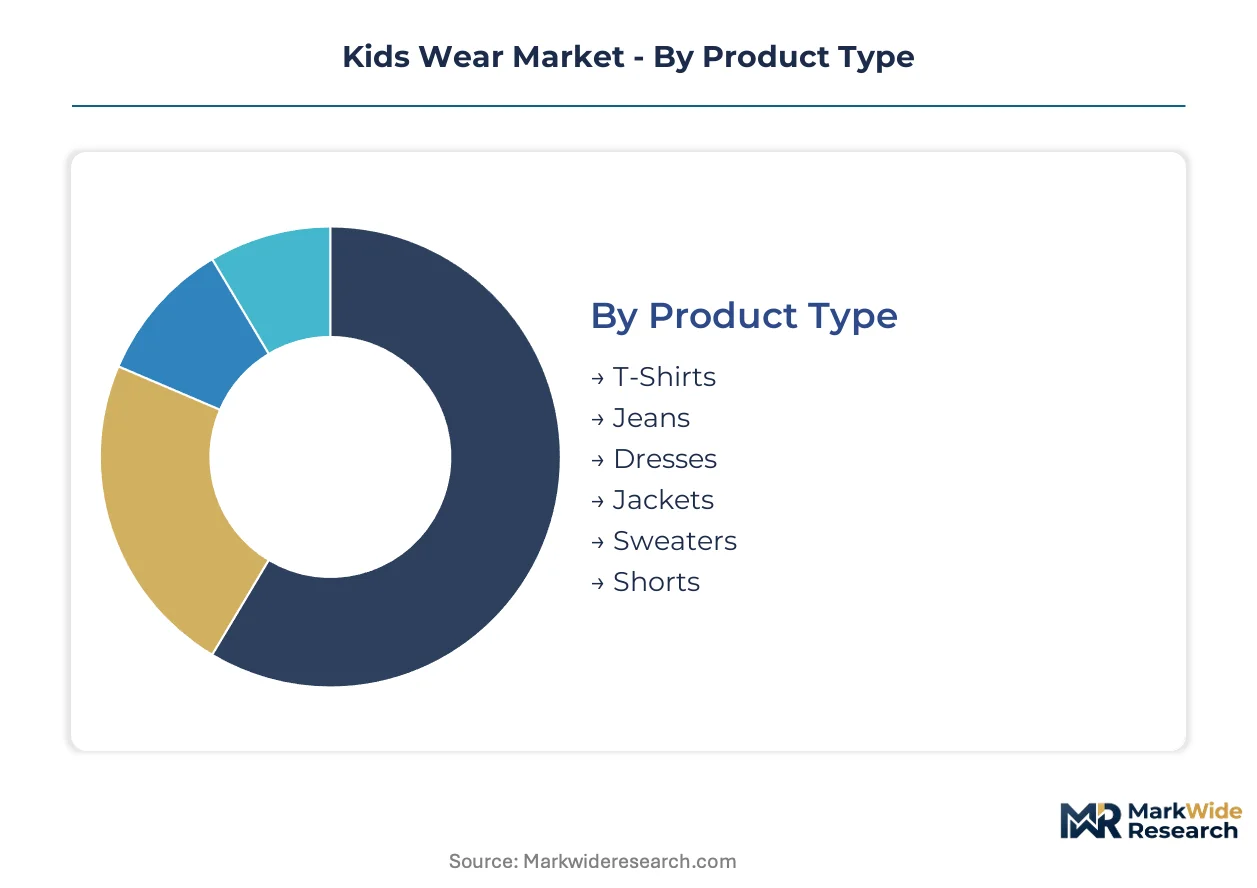
The Kids Wear Market segmentation reveals how product characteristics, consumer demographics, distribution channels, and material choices influence purchasing decisions. Understanding these distinct segments allows brands to tailor their offerings and optimize supply chain strategies for specific market niches.
Product Type:
Supply chain configuration for kids' apparel often dictates the breadth of product types available through specific manufacturing hubs.
- T-Shirts:These casual garments, typically made from cotton or cotton blends, offer comfort and versatility for everyday wear. Demand for T-shirts is consistently high across all age groups, particularly in markets like the United States where casual wear dominates.
- Jeans:Durable denim trousers designed for active children, often featuring adjustable waistbands and reinforced knees. Their robust construction and widespread appeal make them a staple in wardrobes across Europe and Asia.
- Dresses:Garments for girls, ranging from casual play dresses to more formal occasion wear, often incorporating prints and embellishments.
- Jackets:Outerwear items providing warmth and protection, available in various materials such as fleece, denim, and waterproof fabrics for different seasons.
- Sweaters:Knitted garments offering warmth, made from materials like cotton, wool, or acrylic, often featuring playful designs.
- Shorts:Lightweight lower body garments, popular in warmer climates and for active play, commonly made from cotton or polyester blends.
T-Shirts absorbs the bulk of installed capacity; Dresses is expanding most quickly.
Age Group:
Consumer purchasing behavior varies significantly across different age groups, influencing product design and marketing approaches.
- Toddlers:Children aged 1-3 years require clothing that prioritizes comfort, durability, and ease of dressing, often featuring bright colors and simple designs. This segment drives significant volume due to rapid growth and frequent clothing changes in countries like China.
- Preteens:Children aged 9-12 years seek apparel that reflects emerging personal styles and current fashion trends, often influenced by peer groups. This category shows strong value growth, especially in North American markets, as brands introduce more sophisticated designs.
- Newborns:Infants from birth to 12 months need soft, hypoallergenic, and easy-to-fasten clothing, often made from organic cotton.
- Preschoolers:Children aged 3-5 years require comfortable, durable clothing suitable for active play and easy for parents to manage.
- Early School Age:Kids aged 5-8 years begin to express preferences for specific characters or styles, balancing comfort with emerging fashion consciousness.
The Toddlers segment commands the largest purchasing volume; the Preteens category exhibits the steepest expansion trajectory.
Sales Channel:
The distribution landscape for kids wear is diversifying, with digital platforms gaining prominence alongside traditional retail formats.
- E-commerce Platforms:Online marketplaces and brand websites offer convenience, wider product selections, and competitive pricing for parents. This channel is experiencing rapid growth globally, particularly in the United States, due to its accessibility and personalized shopping experiences.
- Direct-to-Consumer:Brands selling directly to consumers through their own websites or pop-up shops allow for greater control over brand messaging and customer relationships. Niche brands, especially those focusing on gender-neutral or adaptive clothing, leverage DTC models to reach specific audiences.
- Department Stores:Large retail establishments offer a curated selection of multiple brands, providing a traditional shopping experience.
- Specialty Boutiques:Smaller, often independent stores focus on unique, high-end, or artisan-made children's clothing, catering to specific tastes.
- Supermarkets:Grocery retailers often include basic and affordable kids' apparel lines, attracting parents seeking convenience during routine shopping.
E-commerce Platforms capture the largest share of new customer acquisition; Direct-to-Consumer models are gaining share fastest.
Material:
Material selection in kids wear is driven by considerations of comfort, safety, durability, and increasingly, sustainability.
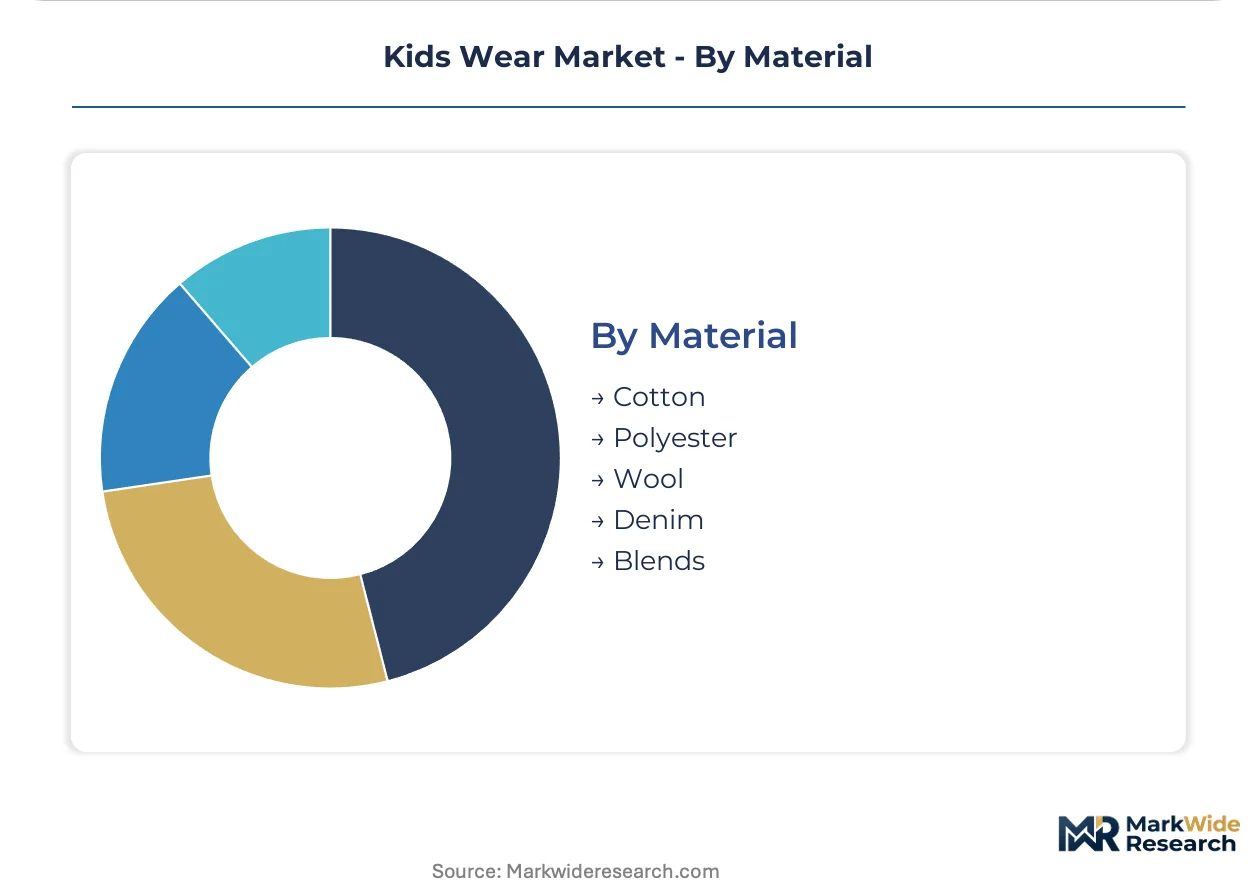
- Cotton:A natural fiber known for its softness, breathability, and hypoallergenic properties, making it a dominant material for infant and toddler wear. Organic cotton adoption is accelerating due to regulatory mandates like the EU's CSRD, particularly in European markets.
- Polyester:A synthetic fiber offering durability, wrinkle resistance, and quick-drying properties, increasingly used in performance wear and outerwear. Recycled polyester demand is rising, influenced by environmental concerns and brand commitments in countries like Germany.
- Wool:A natural fiber providing warmth and moisture-wicking properties, often used in colder climate apparel and for its natural flame resistance.
- Denim:A sturdy cotton twill fabric primarily used for jeans and jackets, valued for its durability and classic aesthetic.
- Blends:Fabrics combining two or more fibers, such as cotton-polyester or cotton-spandex, to achieve desired characteristics like stretch, durability, or softness.
Cotton remains the primary material choice for manufacturers; Polyester is gaining significant traction in performance categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangzhou, a major textile manufacturing hub in China, anchors significant production for global kids wear brands, influencing pricing and supply chain dynamics. E-commerce platforms are accelerating market penetration across diverse geographies. Parental demand for sustainable and affordable apparel continues to shape regional market development.
China
Expanding middle-class populations in China are driving substantial volume growth, particularly for branded and premium children's apparel. The country's GB standards ensure product safety and quality for textiles, influencing local manufacturing practices. Guangzhou and Shenzhen serve as key production and innovation centers for kids wear, integrating design with efficient supply chains.
United States
The US market exhibits strong value growth in the preteen category, with parents seeking trend-driven and functional apparel. The US Consumer Product Safety Improvement Act (CPSIA) sets stringent limits on chemicals like lead and phthalates, mandating rigorous testing. Los Angeles and New York remain pivotal for fashion design and the proliferation of direct-to-consumer brands.
Germany
European regulatory mandates, such as REACH and the Corporate Sustainability Reporting Directive (CSRD), are accelerating the adoption of organic cotton and recycled polyester in Germany. Consumers increasingly prioritize sustainable and ethically sourced children's clothing. Stuttgart and Munich are centers for material innovation and circular economy initiatives within the apparel sector.
India
Demographic expansion and rising disposable incomes in India are fueling demand for both basic and premium kids wear segments. The Bureau of Indian Standards (BIS) outlines quality and safety requirements for textiles, impacting domestic production. Tirupur, known as the knitwear capital, concentrates garment manufacturing for both local and export markets.
Vietnam
Vietnam is a critical manufacturing hub for global kids wear brands, benefiting from favorable trade agreements and a skilled labor force. Government policies support foreign investment in textile and garment production, enhancing export capabilities. Ho Chi Minh City and Hanoi are primary centers for garment production and export operations, attracting international brands.
Kids Wear Market Key Industry Players
Capital-heavy producers compete with asset-light designers for market share in the kids wear sector. The market shows a tiered structure, with established global brands alongside agile, niche direct-to-consumer players. Large retailers leverage extensive distribution networks, while specialists differentiate through material innovation or unique design philosophies. Competitive moves include significant investment in digital channels and strategic partnerships to enhance supply chain transparency.
Established retailers like Gap Kids and Old Navy anchor the mainstream segment, leveraging brand recognition and extensive physical and online footprints. Uniqlo Kids exemplifies a value-driven approach, focusing on high-quality, functional basics made from innovative materials. Primary occupies a position within the niche segment, specializing in gender-neutral designs and a direct-to-consumer sales model that appeals to specific parent cohorts.
| Leading Market Players |
|---|
| Quince |
| Gap Kids |
| Hanna Andersson |
| Appareify |
| Penguin Kids Wear |
| Primary |
| Uniqlo Kids |
| MMS Clothing |
| Old Navy |
| Others |
Cost & Logistics Intelligence
Skilled garment workers concentrated in Southeast Asia establish labor-cost differentials that directly influence pricing tiers across the kids wear market. These regional cost structures dictate final product affordability.
Pricing Analysis
Value for durability and safety anchors pricing in the kids wear market, which primarily uses a transactional structure, complemented by emerging subscription box models. Price differentiation stems from brand recognition and material certifications like organic cotton, separating premium offerings from mass-market apparel. Cost compression in the economy tier intensifies due to competition from fast fashion players. Parents of toddlers and preschoolers exhibit high price sensitivity for everyday wear, while preteen consumers show less sensitivity for trend-driven items.
Supply Chain Analysis
Volatile logistics and freight costs significantly impact the kids wear supply chain, particularly for transcontinental shipments. Manufacturing concentrates heavily in China, Vietnam, and India, drawing from raw material dependencies on cotton, polyester, and non-toxic dyes. Geopolitical risks and trade tariffs present a structural vulnerability to this concentrated production base. Downstream distribution primarily runs through e-commerce platforms and direct-to-consumer channels, optimizing reach and reducing traditional retail overhead.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kids wear market is fundamentally a cost-of-compliance story, where stringent regulations like the US Consumer Product Safety Improvement Act (CPSIA) create a significant barrier-to-entry moat. Adherence to these safety standards ensures product integrity and builds consumer trust.
For Market Incumbents:Anticipate escalating regulatory pressure for sustainable materials and transparent supply chains by investing in advanced traceability software. Expand subscription box models to rebalance seasonal purchasing cycles and secure recurring revenue streams, countering fast fashion's price erosion. Consolidate production with certified suppliers to mitigate risks from divergent chemical safety standards like REACH and CPSIA. Leverage brand recognition to differentiate on trust and verified sustainability credentials.
For New Entrants and Emerging Players:Launch via direct-to-consumer e-commerce platforms to access underserved segments like adaptive wear for children with sensory sensitivities. Focus on material innovation, commercializing plant-based textiles or agricultural byproduct fabrics for a performance and environmental edge. Target the preteen category with unique, trend-driven designs that offer strong value growth. Leverage digital textile printing for rapid, small-batch production, responding quickly to local trends without massive upfront investment.
For Investors and Strategic Acquirers:The window for entry favors strategic acquirers targeting niche direct-to-consumer brands with robust sustainability credentials. Long-term viability, over the next 5-10 years, hinges on navigating complex global supply chains while meeting evolving consumer demands for ethical production. Prioritize companies demonstrating strong performance in material innovation or adaptive wear segments. The signal to watch is the accelerated adoption of circular economy models, such as apparel rental services, indicating market maturity in sustainable consumption.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Supply Chain Traceability | Ensures compliance with forced labor regulations like UFLPA and builds consumer trust. |
| Expand Subscription Box Offerings | Shifts purchasing cycles to recurring revenue streams and enhances customer loyalty for brands. |
| Develop Adaptive Wear Lines | Addresses an underserved market segment and expands brand appeal through inclusive design. |
| Material Innovation Partnerships | Commercializes next-generation sustainable textiles and differentiates products on environmental credentials. |
| Digital Textile Printing Adoption | Enables rapid, small-batch production with reduced water usage, supporting localized trends. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, complemented by primary interviews with industry stakeholders. This involved conversations with brand managers, textile manufacturers, retail buyers, and sustainability officers across key markets. Secondary data was validated against sources like GB standards, CPSIA reports, and REACH documentation. A bottom-up and top-down triangulation approach ensured data consistency and market sizing accuracy.
Data stream reconciliation across multiple inputs informed the quantitative modeling framework over the projection horizon. Segmentation dimensions included product type, age group, sales channel, material, and regional regulatory compliance. Compound annual growth rates were derived from historical trend analysis and projected market dynamics. Key industry-specific forecast inputs included birth rates, disposable income growth, and the adoption rates of sustainable materials.
Volatile raw material costs, evolving regulatory landscapes, and geopolitical trade shifts are the dominant revision risks to market forecasts. These projections reflect assumptions about future market conditions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO