
 Japan Trade Finance Market | 2026-2036
Japan Trade Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Trade Finance Market Foresight
Blockchain-based documentation is broadening the operational scope of letter-of-credit processing across Japanese banking networks. MUFG Bank leverages its correspondent banking relationships across ASEAN to sustain documentary collection volumes for machinery exporters. Sumitomo Mitsui Banking Corporation anchors yen-denominated trade credit insurance for regional supply chains. Mizuho Bank competes through specialized forfaiting desks serving automotive parts manufacturers.
Japan Trade Finance encompasses documentary instruments, credit guarantees, and liquidity facilities that bridge payment gaps between importers and exporters across international transactions. Letter-of-credit instruments require strict compliance with UCP 600 standards, while supply chain finance programs extend payable financing against verified invoice flows. Letters of credit dominate transaction volumes among established trading houses, yet supply chain finance is expanding fastest as manufacturers seek to optimize working capital across multi-tier supplier networks. Export credit maintains stable demand from heavy industrial exporters, with margin pools concentrating in trade credit insurance for emerging-market destinations.
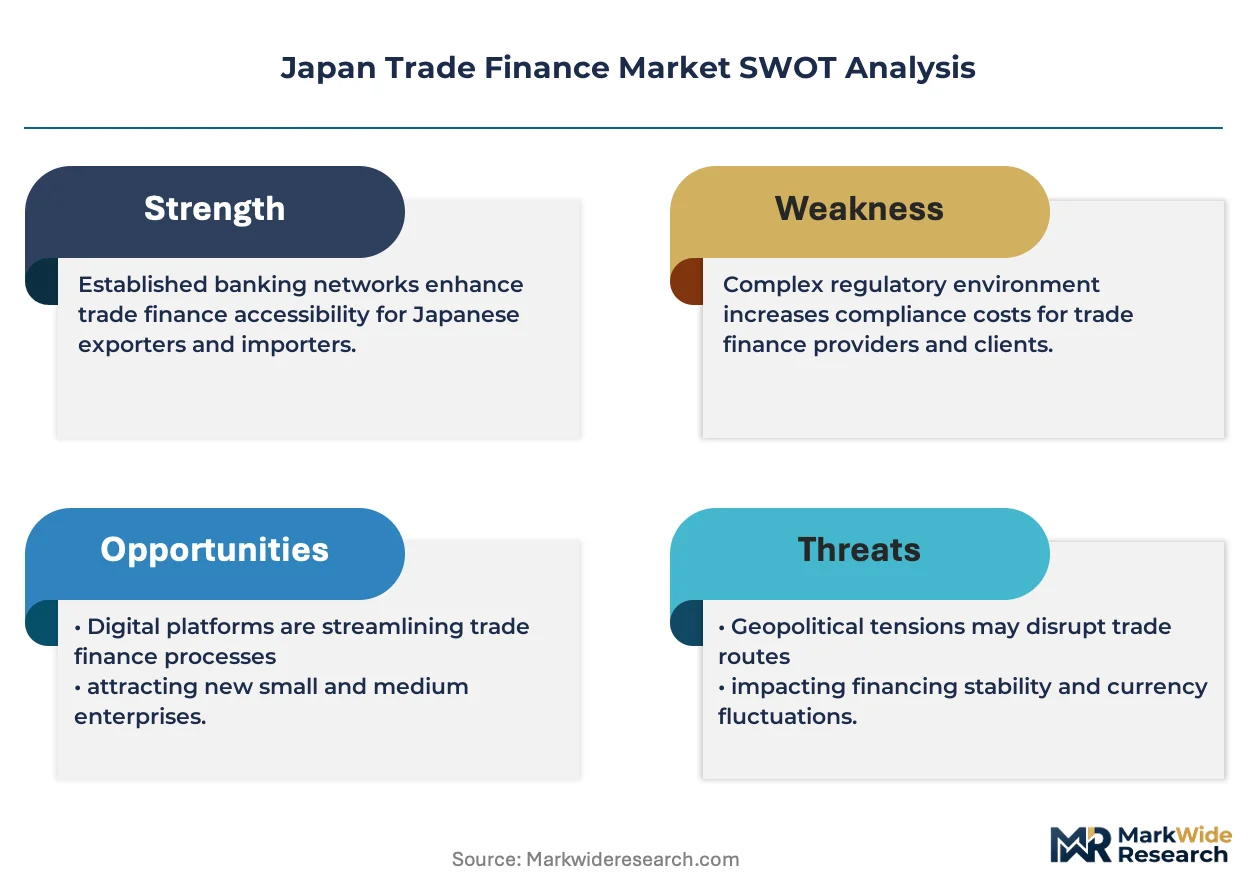
METI's digital trade platform initiatives intersect with JFSA prudential guidelines on cross-border exposure management, shaping how institutions structure documentary collections for SME clients. The Payment Services Act governs fintech platform participation in trade settlement, creating compliance thresholds for non-bank entrants. Stakeholders must monitor how amendments to Japan's foreign exchange regulations affect documentation requirements for yen-invoiced transactions with regional partners.
Market Dynamics
METI's digital trade platform mandates are compressing documentary processing cycles across Japanese banking networks, forcing institutions to restructure correspondent relationships and SME service architectures around real-time data verification protocols.
Growth Catalysts
- Digital Documentation Mandates:METI's platform initiatives eliminate paper-based letter-of-credit workflows, reducing processing friction for machinery exporters in the Osaka-Kobe corridor.
- Automotive Supply Chain Finance:Extended payment terms from ASEAN assemblers are driving adoption of multi-tier supplier financing programs anchored by verified invoice flows.
- Yen-Denominated Regional Trade:Settlement preferences among Southeast Asian importers are expanding demand for yen-invoiced documentary collections and hedging instruments.
Market Restraints
- Correspondent Banking Concentration:Reliance on limited ASEAN banking partnerships for documentary collection creates single-point vulnerability for machinery exporters.
- UCP 600 Compliance Complexity:Strict documentary discrepancy standards generate elevated rejection rates for SME-originated letter-of-credit presentations.
- Fintech Capital Thresholds:JFSA prudential requirements under the Payment Services Act restrict non-bank platform participation in trade settlement infrastructure.
Strategic Opportunities
- Blockchain-Verified Documentation:Distributed ledger integration with METI platforms enables automated compliance checking for cross-border receivables financing.
- SME Import Finance Gap:Underpenetrated documentary collection services in Kyushu manufacturing clusters present white-space for specialized trade credit products.
- Trade Credit Insurance Expansion:Emerging-market destination coverage for heavy industrial exporters aligns with export promotion frameworks.
Industry Challenges
- Legacy System Integration:Core banking architecture replacement requirements consume 18-24 month implementation timelines for digital trade platform connectivity.
- Documentary Examination Expertise:Shrinking talent pools for UCP 600 specialist roles constrain processing capacity expansion at regional branch networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Trade Finance Market |
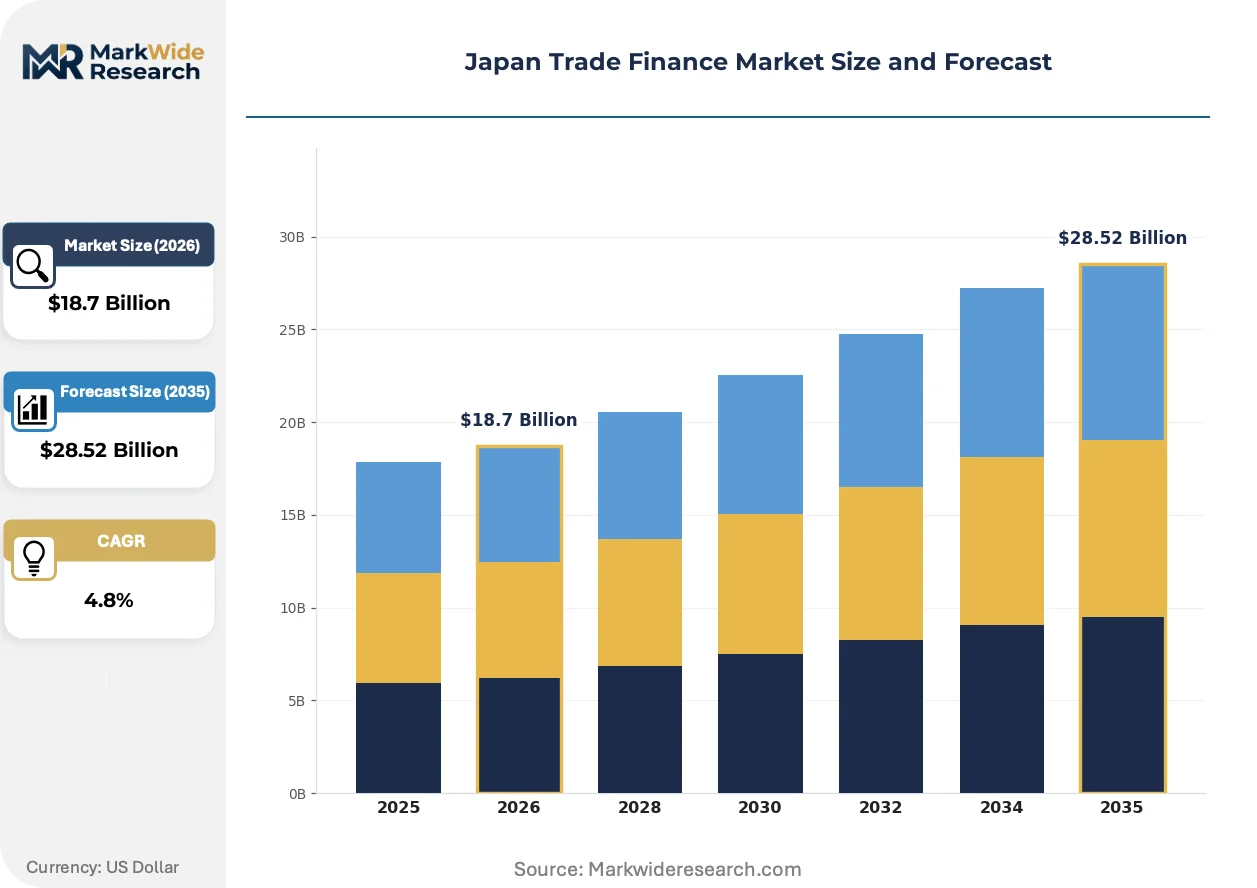
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Letters of Credit, Supply Chain Finance, Export Credit, Trade Credit Insurance Service Type: Documentary Collection, Factoring, Forfaiting, Payment Guarantees End User: Importers, Exporters, SMEs, Large Enterprises Distribution Channel: Banking Institutions, Fintech Platforms, Trade Finance Brokers, Online Marketplaces |
| Companies Covered | MUFG Bank, Ltd., Sumitomo Mitsui Banking Corporation, Mizuho Bank, Ltd., Resona Bank, Ltd., Aozora Bank, Ltd., Japan Finance Corporation, SBI Holdings, Inc., Nomura Holdings, Inc., ORIX Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Trade Finance Market Shifts & Advancements
Distributed ledger infrastructure is compressing settlement timelines for documentary instruments while regulatory data-sharing mandates reshape correspondent banking economics across Japanese trade finance networks.
Blockchain-based trade documentation is integrating smart contract functionality with letter-of-credit workflows, enabling automated payment release upon verified shipment confirmation. Automotive manufacturers in the Toyota supply chain are piloting these systems for ASEAN parts procurement. This compression of verification cycles is integrating documentary risk assessment directly into ERP-based treasury workflows, eliminating manual examination bottlenecks.
METI's cross-border data harmonization framework mandates standardized digital invoice formats for platform-eligible transactions, forcing banks to restructure SME onboarding around API-first documentation. Heavy industrial exporters face accelerated compliance timelines for emerging-market documentary collections. Regional banking networks are responding by centralizing examination functions in Tokyo-Osaka hubs while maintaining local relationship management.
Buyers in the Osaka-Kobe manufacturing corridor are consolidating trade finance relationships around integrated supply chain finance platforms that bundle payable financing with documentary collection services. Traditional letter-of-credit specialists are losing share to bundled service providers offering working capital optimization across multi-tier supplier networks. This consolidation pattern is most pronounced among precision machinery exporters with ASEAN assembly partnerships.
Japan Trade Finance Market Segmentation
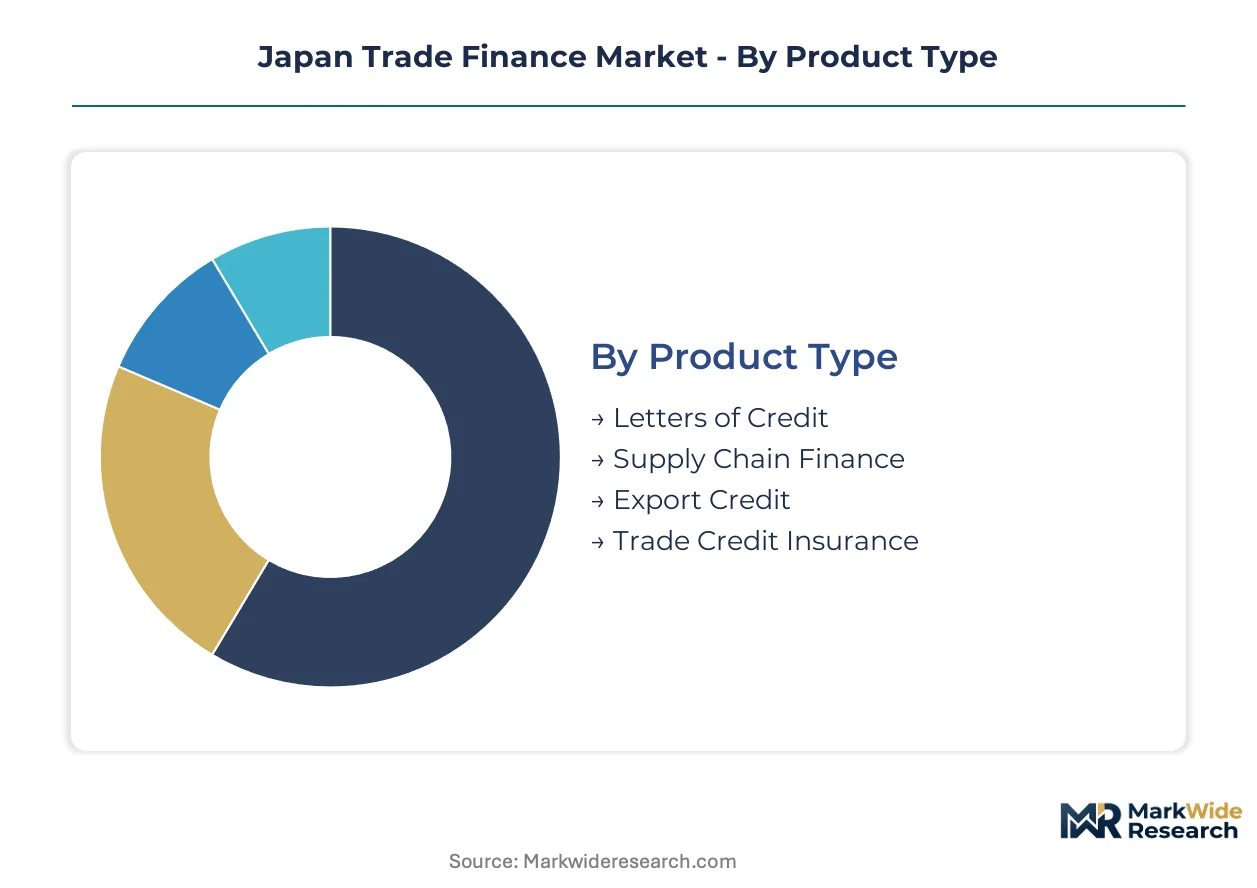
Trade finance instruments in Japan fragment across product maturity, service complexity, and customer sophistication. Each segment demands distinct risk architectures and distribution approaches that shape how METI's digital mandates propagate through banking networks.
Product Type:
Standardization dominates at the documentary instrument end while supply chain finance requires bespoke structuring around verified invoice flows.
- Letters of Credit:UCP 600-governed instruments with strict documentary compliance requirements. Demand concentrates among Osaka-Kobe machinery exporters serving ASEAN assembly partners, where correspondent banking relationships anchor transaction security.
- Supply Chain Finance:Multi-tier payable financing programs integrating ERP-verified invoice data. Automotive manufacturers in Toyota's supplier network are driving adoption fastest as extended payment terms from regional assemblers strain working capital cycles.
- Export Credit:Government-backed financing for heavy industrial shipments with extended tenors. METI's export promotion frameworks sustain stable demand from shipbuilding and steel exporters.
- Trade Credit Insurance:Coverage instruments for emerging-market destination risk. Yen-denominated policies are expanding among regional supply chains seeking protection against ASEAN counterparty defaults.
Most installed capacity flows through Letters of Credit. Expansion is steepest in Supply Chain Finance.
Service Type:
Margin pools concentrate in guarantee instruments while volume throughput favors collection services with streamlined examination protocols.
- Documentary Collection:Bank-intermediated shipping document exchange without payment guarantee. SME importers in Kyushu manufacturing clusters are driving volume as METI platforms reduce processing friction for regional banks.
- Forfaiting:Non-recourse purchase of medium-term receivables from capital goods exporters. Mizuho Bank's specialized desks serve automotive parts manufacturers with ASEAN assembly partnerships, where tenor requirements exceed standard discounting limits.
- Factoring:Receivables purchase with or without recourse, typically shorter-tenor than forfaiting. Domestic SME liquidity needs sustain modest volumes despite fintech platform competition.
- Payment Guarantees:Standalone bank undertakings substituting for commercial letters of credit. Heavy industrial project exports to emerging markets require these instruments where sovereign risk concerns limit open-account terms.
Transaction volume concentrates in Documentary Collection. Fee income growth is climbing the fastest in Forfaiting.
End User:
Customer scale determines service bundling complexity and digital platform integration depth across Japanese banking networks.
- Large Enterprises:Integrated treasury operations with multi-bank trade finance programs. Automotive and precision machinery exporters in the Osaka-Kobe corridor command bespoke supply chain finance architectures spanning ASEAN supplier tiers.
- SMEs:Fragmented banking relationships with limited in-house documentary expertise. Regional manufacturing clusters in Kyushu and Chubu present underpenetrated demand for streamlined collection services as METI digital mandates reduce compliance burdens.
- Exporters:Shipper-side financing needs spanning pre-shipment working capital to post-shipment receivables discounting. Machinery and automotive parts manufacturers dominate transaction origination.
- Importers:Buyer-side instruments including letter-of-credit issuance and import collection. Raw material and component procurement from ASEAN sources drives documentary demand.
Revenue concentration sits with Large Enterprises. Customer acquisition momentum is gaining share fastest among SMEs.
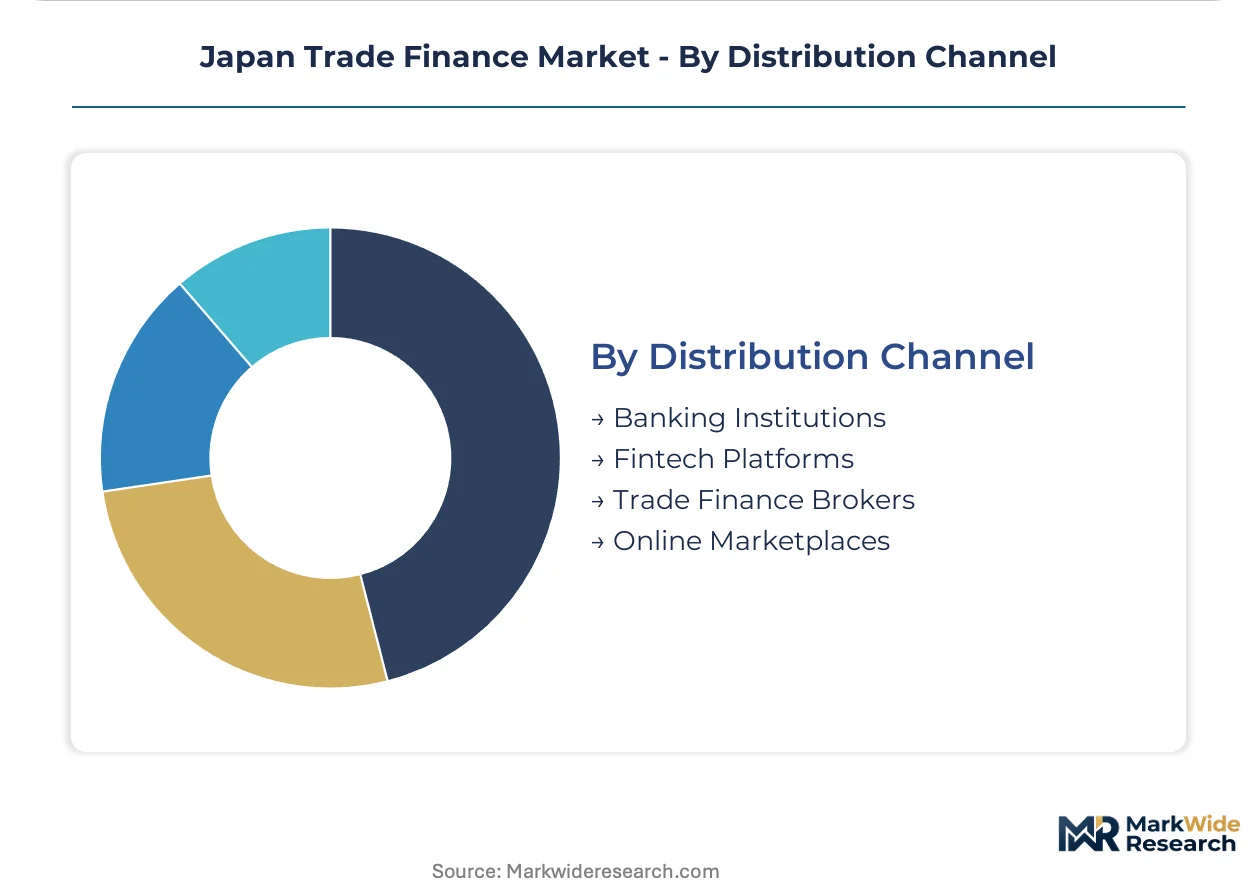
Distribution Channel:
Channel economics diverge sharply between regulated bank infrastructure and platform-based intermediation governed by Payment Services Act thresholds.
- Banking Institutions:MUFG, SMBC, and Mizuho anchor documentary collection through correspondent networks across ASEAN. Core banking replacement timelines of 18-24 months constrain platform connectivity for regional branch networks.
- Fintech Platforms:Non-bank entrants face JFSA capital requirements that restrict direct settlement participation. API-first documentation providers are gaining traction in SME invoice verification.
- Trade Finance Brokers:Intermediaries matching SME clients with bank and non-bank liquidity providers. Commission structures concentrate in complex multi-currency transactions.
- Online Marketplaces:Emerging channels integrating trade finance into B2B procurement platforms. Limited penetration reflects trust barriers in documentary instrument execution.
Transaction flow concentrates through Banking Institutions. Platform enrollment is expanding most quickly in Fintech Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Osaka-Kobe manufacturing corridor anchors Japan's trade finance concentration, with automotive and precision machinery exporters driving documentary instrument demand across ASEAN supply chains.
Kanto/Tokyo
Corporate treasury centers and megabank headquarters concentrate documentary collection processing for large enterprises. METI's digital platform mandates flow through Tokyo-based clearing infrastructure, compressing examination cycles for machinery exporters. The Tokyo-Osaka financial corridor centralizes UCP 600 specialist functions while regional branches retain relationship management.
Kansai/Osaka
Precision machinery manufacturers and automotive parts suppliers generate the highest letter-of-credit volumes for ASEAN destinations. JFSA prudential guidelines intersect with METI's digital trade initiatives, reshaping how regional banks structure SME documentary collections. The Osaka-Kobe port cluster sustains correspondent banking relationships with Southeast Asian partners.
Chubu/Nagoya
Toyota's supplier network drives supply chain finance adoption for multi-tier payable financing programs. Extended payment terms from regional assemblers strain working capital cycles, accelerating ERP-verified invoice integration. Automotive parts manufacturers in Aichi Prefecture anchor forfaiting demand for medium-term receivables.
Kyushu
Underpenetrated SME manufacturing clusters present white-space opportunity for streamlined documentary collection services. Regional banks face 18-24 month core banking replacement timelines to achieve METI platform connectivity. Fukuoka-based manufacturers importing raw materials from ASEAN sources drive buyer-side instrument demand.
Hokkaido
Food processing and agricultural exporters sustain modest export credit utilization for shipments to Asian markets. Limited correspondent banking infrastructure creates reliance on Tokyo-Osaka hubs for documentary examination. Emerging demand for trade credit insurance aligns with METI's export promotion frameworks for regional producers.
Japan Trade Finance Market Competitive Landscape
Global majors compete with regional champions across correspondent banking networks and digital platform integration depth. Three megabanks anchor documentary collection volumes through ASEAN relationships, while specialized lenders occupy niches in supply chain finance and forfaiting. The market structure stratifies into universal banking conglomerates, government-backed development institutions, and fintech-intermediated platforms. Competitive moves concentrate on API-first SME onboarding and blockchain-verified documentation integration.
Within the universal banking tier, MUFG Bank, Ltd., Sumitomo Mitsui Banking Corporation, and Mizuho Bank, Ltd. occupy positions as correspondent network anchors, each representing distinct strategic archetypes across documentary collection, yen-denominated trade credit insurance, and specialized forfaiting services respectively. These institutions exemplify how scale-driven players sustain transaction security for machinery exporters while restructuring regional branch architectures around METI's real-time data verification protocols.
| Leading Market Players |
|---|
| MUFG Bank, Ltd. |
| Sumitomo Mitsui Banking Corporation |
| Mizuho Bank, Ltd. |
| Resona Bank, Ltd. |
| Aozora Bank, Ltd. |
| Japan Finance Corporation |
| SBI Holdings, Inc. |
| Nomura Holdings, Inc. |
| ORIX Corporation |
| Others |
Supply & Pricing Matrix
Blockchain-based documentation infrastructure is compressing processing timelines across Japanese banking networks while simultaneously concentrating margin pools among institutions with legacy system replacement capacity. METI's digital platform mandates force correspondent banking relationships to restructure around real-time data verification, reshaping both cost economics and competitive positioning.
Pricing Analysis
Input-cost pass-through from correspondent banking fees and compliance infrastructure investments shapes pricing structures across documentary instruments. Fee differentiation rests on transaction complexity tiers and UCP 600 specialist availability, with SME-originated presentations commanding premium examination rates. Pricing pressure intensifies in standard documentary collection services as fintech platforms erode volume share. Large enterprises with integrated treasury operations demonstrate lowest price sensitivity; regional SME importers in Kyushu manufacturing clusters exhibit highest elasticity.
Supply Chain Analysis
Reverse-logistics flows for disputed documentary presentations and rejected letter-of-credit documents create processing bottlenecks that inflate operational costs across regional branch networks. Supply concentration centers on Japan, Singapore, and Thailand for correspondent banking partnerships. Critical dependencies include SWIFT infrastructure, UCP 600 examination expertise, and METI platform API connectivity. Single-source vulnerability runs through limited ASEAN banking partnerships for machinery exporters. Distribution runs through Tokyo-Osaka hub-and-spoke architectures with regional relationship management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in digital platform integration and specialized forfaiting services as METI mandates compress processing economics for laggard institutions. Cost compression from automated documentation verification enables premium-tier pricing for real-time settlement capabilities.
For Market Incumbents: Acquire blockchain verification technology assets to defend documentary collection volumes against API-first platform entrants. Consolidate UCP 600 examination functions in Tokyo-Osaka hubs while maintaining regional relationship presence. METI's real-time data mandates threaten branch-network economics for institutions with 18-24 month core banking replacement timelines.
For New Entrants and Emerging Players: Enter via SME documentary collection services in underpenetrated Kyushu manufacturing clusters where regional banks lag platform connectivity. Target automotive parts suppliers in Chubu with ERP-integrated invoice verification tools. White-space exists in trade credit insurance for emerging-market destinations.
For Investors and Strategic Acquirers: Roll-up economics work for specialized forfaiting desks because automotive supply chain finance demands medium-term receivables expertise that universal banks underinvest. Long-term viability favors platforms with METI API certification and correspondent banking license access. Monitor JFSA amendments to Payment Services Act thresholds for non-bank settlement participation as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Platform Integration | Automated compliance checking reduces documentary discrepancy rates for machinery exporters. |
| Correspondent Network Consolidation | Concentrated ASEAN partnerships lower counterparty risk for Osaka-Kobe precision manufacturers. |
| SME Onboarding Digitization | API-first documentation captures underpenetrated demand in Kyushu regional clusters. |
| Forfaiting Desk Specialization | Medium-term receivables expertise serves Toyota supplier network working capital needs. |
| Trade Credit Insurance Expansion | Yen-denominated policies align with METI export promotion for heavy industrial shipments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with trade finance executives at megabanks, UCP 600 specialists at regional branch networks, METI digital platform architects, and SME treasury managers at automotive parts manufacturers. Secondary validation drew from JFSA prudential guidelines, METI digital trade initiative documentation, Payment Services Act amendments, and correspondent banking network disclosures. Bottom-up transaction volume estimates triangulated against top-down banking sector trade finance revenue allocations.
Segment-weighting approaches applied differential growth assumptions across product types, service categories, and end-user scale tiers. The analytical framework modeled letter-of-credit instruments, supply chain finance programs, export credit facilities, and trade credit insurance as distinct revenue pools with varying digital adoption trajectories. CAGRs derived from historical banking sector disclosures and projected METI platform enrollment curves. Forecast inputs incorporated correspondent banking relationship counts, SME platform onboarding rates, and UCP 600 specialist workforce trends.
Inputs from JFSA regulatory filings and METI platform specifications were available through the study window; gaps in real-time transaction-level data from regional banking networks introduce uncertainty bands around SME segment projections. Forecasts reflect documented assumptions regarding digital adoption timelines and correspondent banking consolidation patterns. Practitioners should monitor METI platform API certification milestones and Payment Services Act amendment trajectories for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Russia Data Analytics in Banking Market
Banking
Data Analytics in Banking Market
Banking
US Retail Banking Market
Banking
Smart Banking Solutions Market
Banking
Global Neobanking Market
Banking
Global Banking Systems Software Market
Banking
Core Banking Solutions Market
Banking
Retail Banking IT Spending Market
Banking
UK Banking as a Service Market
Banking
Biometric Banking Wristband Market
Banking
Asia-Pacific Data Analytics in Banking Market
Banking
Global Big Data Analytics in Banking Market
Banking
Africa Data Analytics in Banking Market
Banking
Credit Intermediation Market
Banking
In Vitro Fertilization Banking Services Market
Banking
Europe Neobanking Market