
 India Food Enzymes Market | 2026-2036
India Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
India Food Enzymes Market Outlook
The FSSAI's tightening stance on artificial additives and clean-label mandates is hardening procurement criteria across India's packaged food sector. Novozymes A/S leverages its microbial fermentation expertise to supply protease and amylase solutions to pan-Indian bakery chains. Advanced Enzyme Technologies Limited anchors its position through backward integration into strain development and domestic manufacturing facilities near Mumbai. Kerry Group PLC competes by bundling enzyme systems with taste and nutrition platforms for dairy and meat processing clients.
Food enzymes are proteinaceous biocatalysts, typically operating at 30–70°C and pH 4.0–8.0, that accelerate specific biochemical reactions in food matrices without becoming consumed in the process. These molecules derive from microbial fermentation, plant extraction, or animal tissues, and serve to modify texture, enhance flavor development, improve nutritional bioavailability, or extend shelf stability in processed foods. Amylase dominates the product type landscape due to its indispensability in starch hydrolysis for baking and brewing applications across India's tropical climate conditions. The beverages application segment is gaining structural momentum as enzyme-assisted juice clarification and low-calorie sweetener production expand in Maharashtra and Karnataka. Microbial sources command the largest share of supply volumes given their scalability, cost efficiency, and alignment with vegetarian dietary preferences prevalent among Indian consumers.
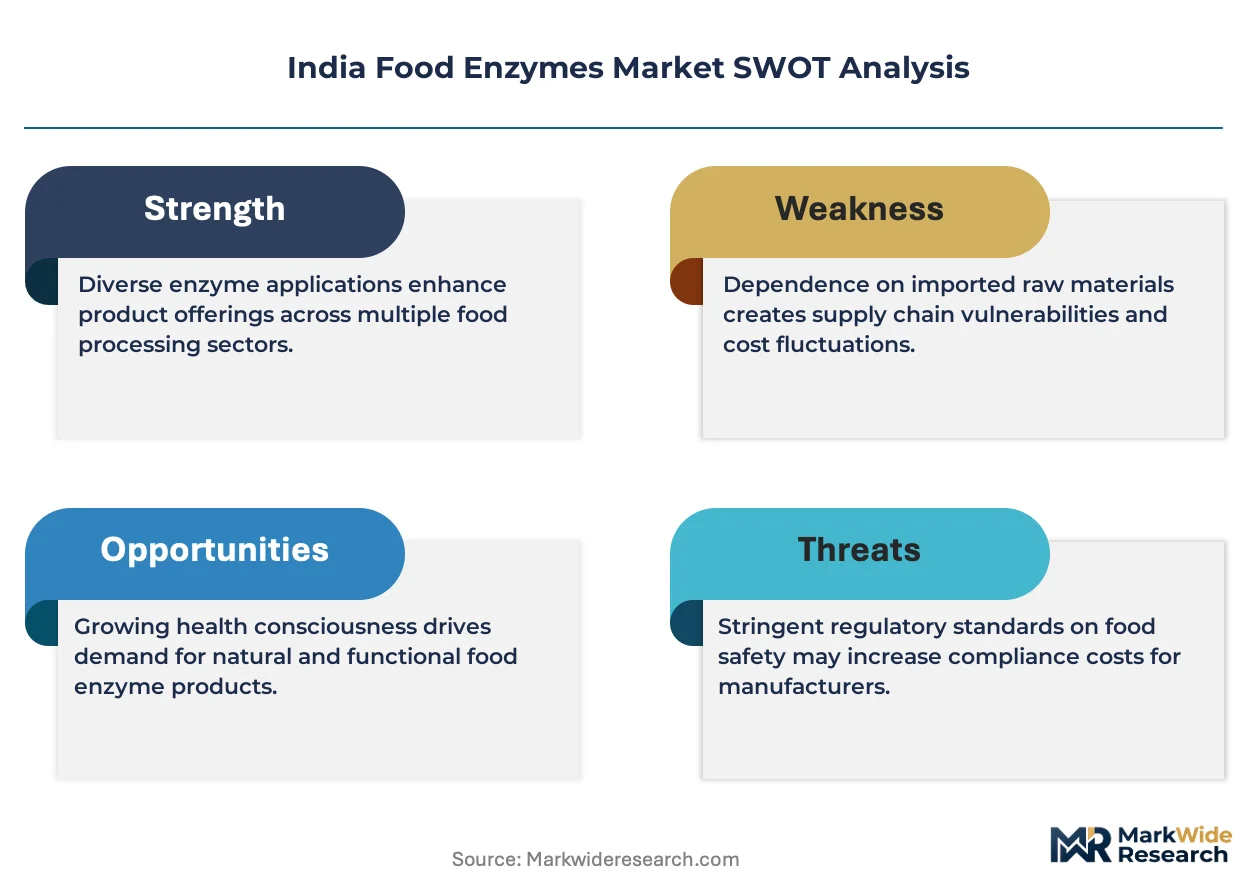
FSSAI standards on food additive purity, BIS certification requirements for imported enzyme preparations, and the PLI scheme for food processing machinery collectively shape compliance costs and market access trajectories for domestic and foreign suppliers. CDSCO oversight on novel enzyme strains used in nutraceutical applications adds a secondary regulatory layer that influences R&D investment priorities. Stakeholders must monitor evolving FSSAI labeling norms and state-level food safety enforcement intensity to anticipate reformulation cycles and procurement timing across India's fragmented but consolidating food manufacturing base.
Market Dynamics
FSSAI's clean-label mandates are compressing reformulation cycles across India's packaged food sector, forcing manufacturers to replace synthetic additives with enzyme-based alternatives at unprecedented speed. This regulatory pressure is reshaping procurement criteria and supplier relationships throughout the value chain.
Growth Catalysts
- PLI scheme for food processing machinery:Central government incentives are lowering capital barriers for enzyme-adopting manufacturers in Maharashtra and Gujarat, accelerating technology upgrades across bakery and dairy clusters.
- Bakery sector expansion:Dough conditioning applications are pulling amylase and protease volumes as pan-Indian biscuit chains scale production to serve tier-2 and tier-3 cities.
- Vegetarian dietary preferences:Microbial-derived enzymes align with cultural consumption patterns, eliminating market friction that animal-sourced alternatives face in India's predominantly vegetarian processing segments.
Market Restraints
- Strain development concentration:Limited domestic capability in novel microbial strain engineering creates dependency on imported starter cultures and fermentation expertise.
- BIS certification timelines:Import clearance delays for enzyme preparations extend working capital cycles for food manufacturers operating on thin inventory margins.
- Temperature sensitivity:Enzyme activity degradation during India's hot-season logistics constrains distribution reach to northern and central hinterlands without cold-chain investment.
Strategic Opportunities
- Karnataka beverage processing:Juice clarification and low-calorie sweetener production present untapped enzyme demand outside the dominant Maharashtra-Gujarat axis.
- Nutraceutical convergence:CDSCO oversight on novel enzyme strains is creating premium positioning opportunities for suppliers capable of dual food-pharma compliance.
- Direct procurement platforms:Digital B2B marketplaces are disintermediating traditional distributor networks, enabling smaller Maharashtra and Gujarat processors to access specialized enzyme formulations.
Industry Challenges
- Fermentation technologist scarcity:Domestic universities produce insufficient graduates with applied microbial process engineering skills, forcing manufacturers to import talent or accept longer ramp-up periods.
- Legacy equipment incompatibility:Retrofitting enzyme dosing systems into existing plant infrastructure requires production downtime that cash-constrained mid-tier processors struggle to absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Food Enzymes Market |
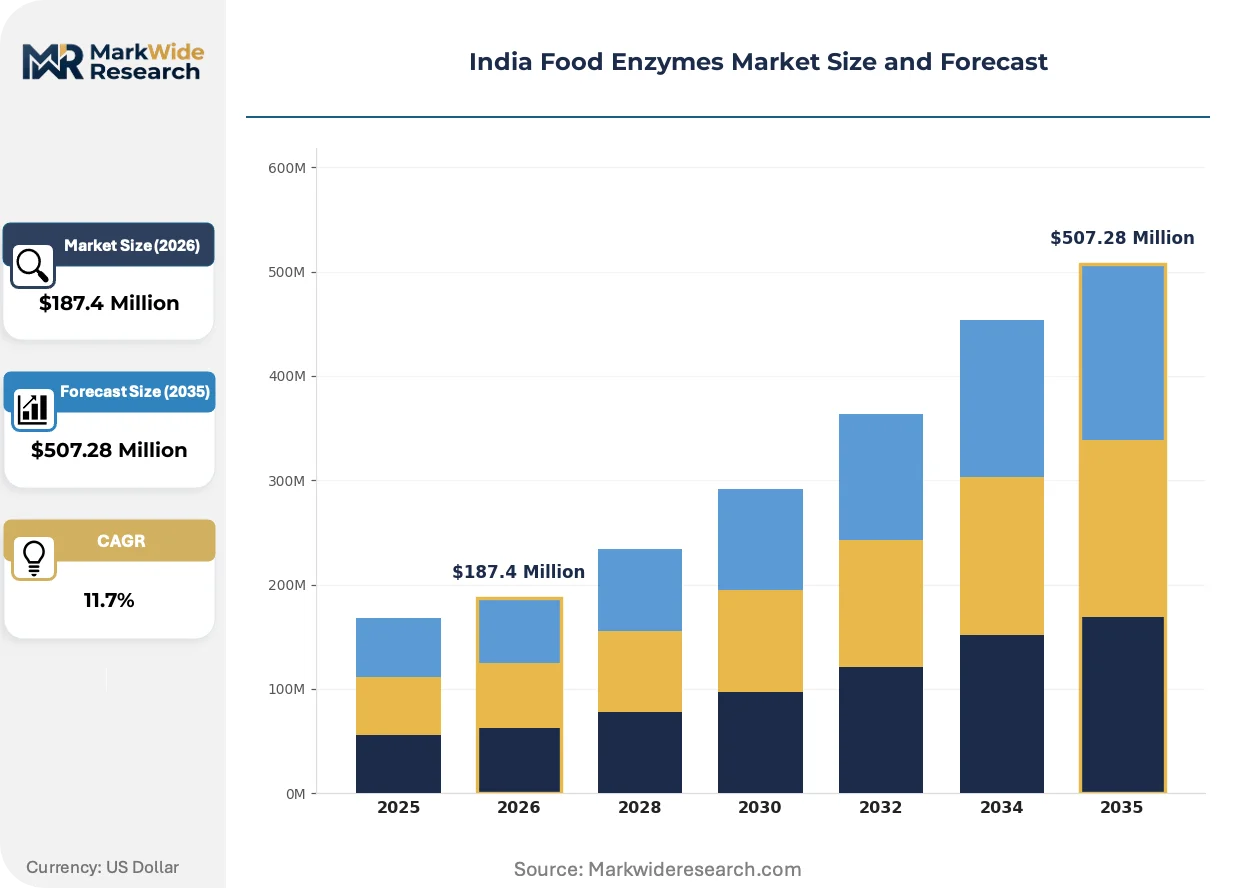
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylase, Protease, Lipase, Cellulase Application: Baking, Dairy, Beverages, Meat Processing End User: Food Manufacturers, Bakeries, Beverage Companies, Dairy Producers Source: Microbial, Plant, Animal, Fermentation |
| Companies Covered | Novozymes A/S, Advanced Enzyme Technologies Limited, Koninklijke DSM N.V., International Flavors & Fragrances, Kerry Group PLC, BASF SE, Lumis Biotech Pvt. Ltd., Chr. Hansen, DuPont de Nemours, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Food Enzymes Market Strategic Shifts
Enzyme engineering and regulatory digitization are compressing product development timelines while procurement centralization among large food manufacturers is consolidating supplier relationships across India's fragmented processing base.
Immobilized enzyme systems are integrating fixed-bed and fluidized-bed reactor designs that enable continuous processing with reduced enzyme consumption. Large-scale starch processors in Gujarat are adopting these configurations to cut unit costs. The technology is integrating batch-to-continuous conversion, compressing capital intensity thresholds for mid-tier entrants.
FSSAI's evolving labeling norms are mandating granular disclosure of enzyme sources and processing aids on packaged food labels. This transparency push is forcing reformulation documentation and supply chain traceability investments. Dairy and meat processing segments in Maharashtra are responding fastest, building audit-ready ingredient dossiers ahead of enforcement intensification.
Consolidated procurement by pan-Indian bakery chains is displacing fragmented spot purchasing with annual volume contracts tied to technical service support. Tier-1 suppliers now embed application laboratories and on-site troubleshooting into standard offerings. This shift concentrates most visible in Gujarat, where large biscuit manufacturers have centralized ingredient buying to leverage scale against formulation complexity.
India Food Enzymes Market Segmentation
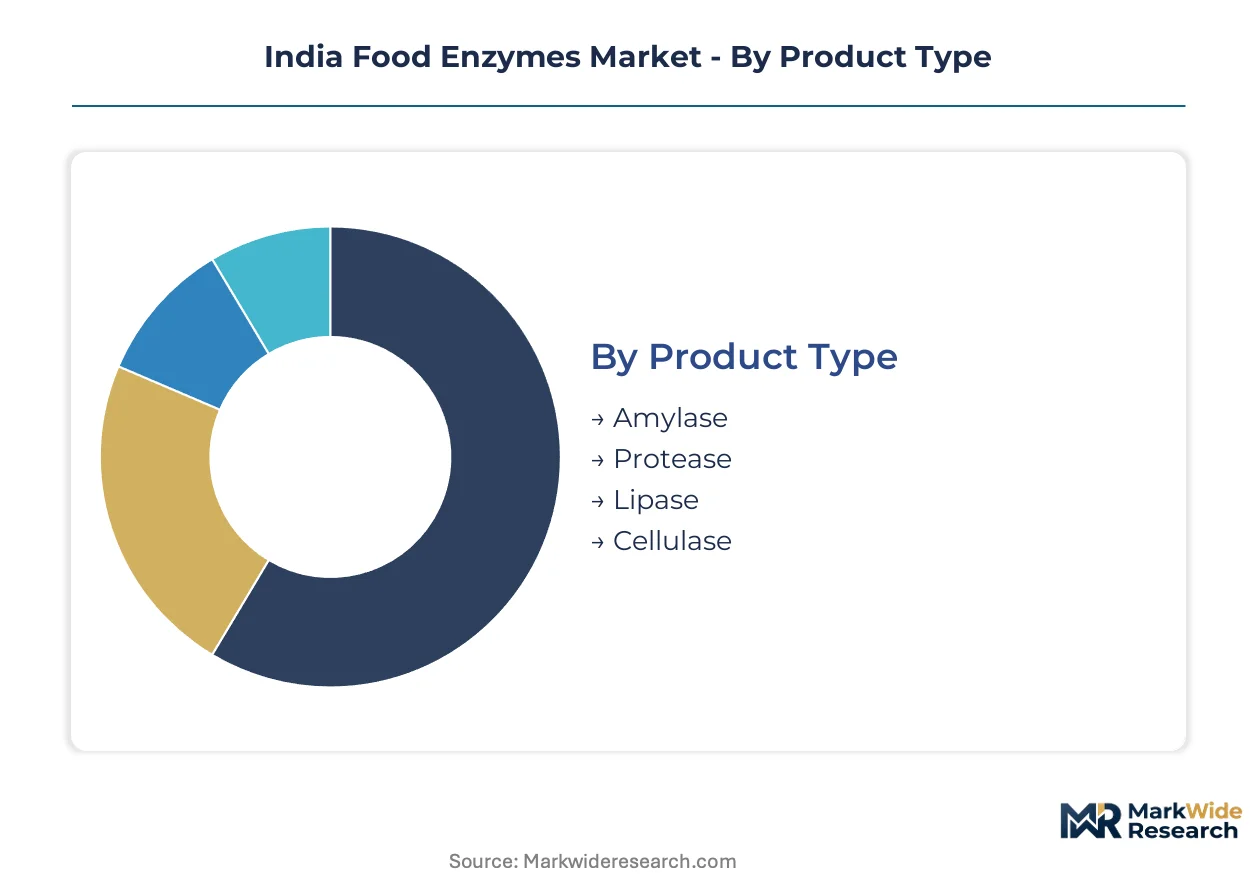
Segmentation in India's food enzymes market reveals how regulatory compliance burdens, production scale requirements, and vegetarian dietary norms reshape procurement patterns across distinct buyer categories. Understanding these divides enables suppliers to align certification investments with addressable revenue pools.
Product Type:
Amylase and protease formulations carry heavier FSSAI documentation requirements due to their prevalence in mass-market baked goods, while lipase and cellulase face lighter scrutiny in niche applications.
- Amylase:Catalytic proteins that hydrolyze starch into dextrins and maltose at 50–70°C. Demand concentrates in Gujarat's biscuit manufacturing corridors where dough conditioning specifications from Britannia and Parle trigger bulk procurement contracts.
- Protease:Enzymes that cleave peptide bonds to modify protein structures and enhance flavor development. Maharashtra's dairy processing belt around Pune and Nashik drives volumes for cheese ripening and whey protein modification applications.
- Lipase:Esterases that catalyze fat hydrolysis for flavor enhancement in dairy and confectionery. Applications remain concentrated in premium chocolate and specialty cheese segments.
- Cellulase:Complex enzymes degrading cellulose fibers for juice clarification and dietary fiber modification. Adoption tracks beverage processing expansion in Karnataka.
Leading the category by volume: Amylase. Growing fastest: Protease.
Application:
Cost tier differentiation separates commodity-scale baking from premium-margin nutraceutical-adjacent segments with divergent technical service requirements.
- Baking:Enzyme systems for dough conditioning, crumb softening, and shelf-life extension in high-output biscuit and bread lines. Gujarat and Maharashtra host the dominant manufacturing clusters with established supplier relationships.
- Dairy:Applications span cheese coagulation, whey processing, and lactose hydrolysis. Procurement concentrates among cooperatives in Maharashtra and private processors in Punjab.
- Beverages:Juice clarification, pectin degradation, and low-calorie sweetener production. Karnataka's mango and grape processing infrastructure anchors emerging demand.
- Meat Processing:Tenderization and flavor development applications serving Kerala and Tamil Nadu's poultry and seafood processing units.
Highest volume concentration: Baking. Steepest expansion trajectory: Beverages.
End User:
Customer type determines whether procurement flows through centralized technical buying teams or fragmented spot-market purchasing with divergent price sensitivity profiles.
- Food Manufacturers:Large integrated processors with dedicated R&D functions and annual volume contracts. These buyers demand embedded application laboratories and regulatory dossier support.
- Bakeries:Mid-tier biscuit and bread producers in tier-2 cities scaling from manual to semi-automated lines. Price sensitivity remains acute with limited technical staff.
- Beverage Companies:Juice and soft drink processors requiring clarification and stability solutions. Procurement centralizes among Mumbai and Bangalore headquartered firms.
- Dairy Producers:Cooperative and private milk processors seeking shelf-life extension and value-added product capabilities.
Most consolidated buying power: Food Manufacturers. Fastest procurement digitization: Bakeries.
Source:
Supply concentration varies dramatically by production biology, with microbial fermentation commanding infrastructure investments that exclude smaller domestic entrants.
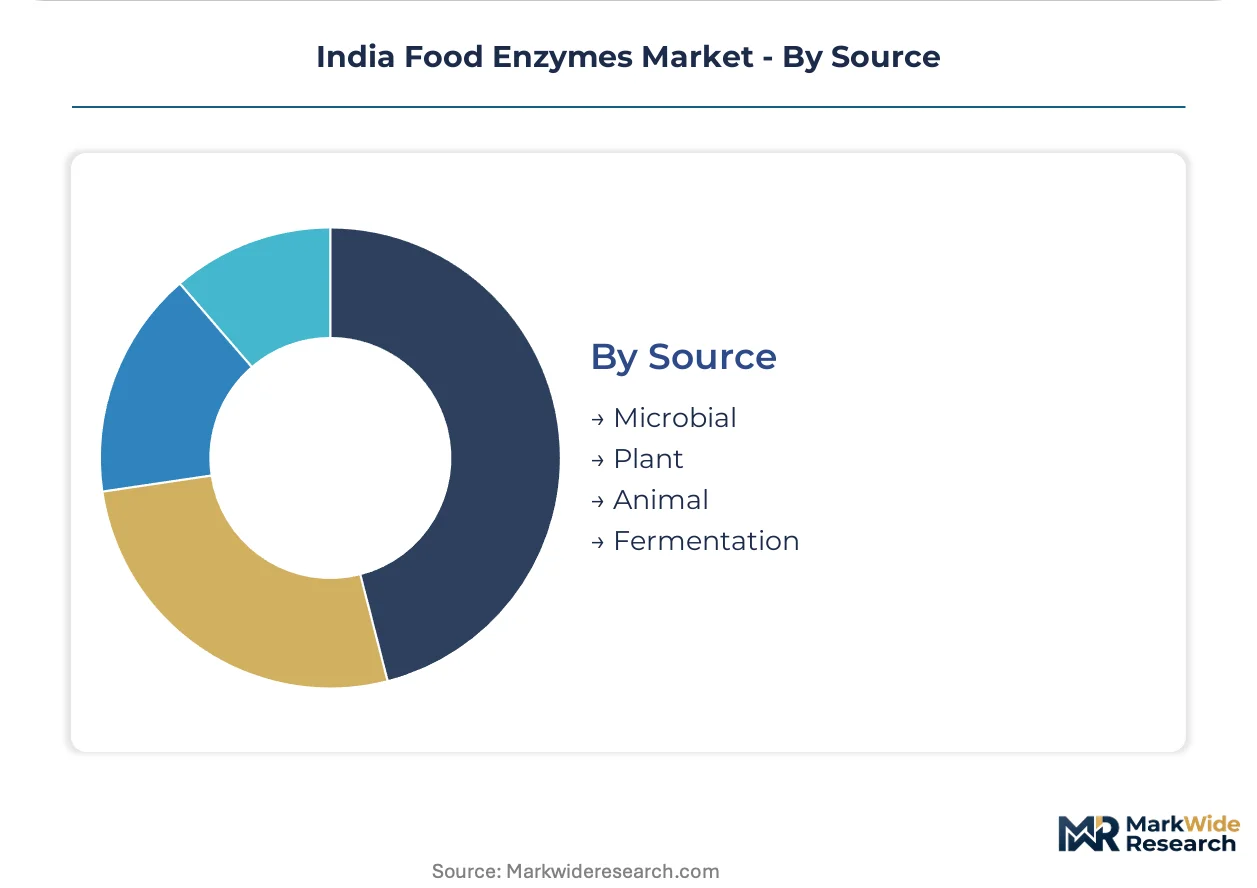
- Microbial:Bacterial and fungal fermentation products scalable to industrial volumes. Alignment with vegetarian dietary preferences eliminates market friction in India's predominantly vegetarian processing segments.
- Plant:Enzymes extracted from papaya, pineapple, and fig sources. Applications concentrate in traditional medicine adjacents and export-oriented organic product lines.
- Animal:Pancreatic and gastric tissue derivatives. Market presence contracts under clean-label pressures and religious dietary restrictions.
- Fermentation:Recombinant DNA and precision fermentation approaches for novel enzyme strains. CDSCO oversight adds compliance layers that favor capitalized multinationals.
Dominant supply share: Microbial. Technology investment focus: Fermentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enzyme production clusters concentrate in western India while consumption spreads across processing belts in the south and north. Maharashtra and Gujarat generate the dominant supply volumes through microbial fermentation infrastructure. Karnataka and Tamil Nadu emerge as demand frontiers for beverage and meat processing applications.
Maharashtra
Dairy processing cooperatives around Pune and Nashik drive protease demand for cheese ripening and whey modification. FSSAI labeling mandates on clean-label ingredients accelerate reformulation timelines among Mumbai-headquartered food manufacturers. The Mumbai-Pune industrial corridor anchors the largest concentration of enzyme application laboratories serving pan-Indian bakery chains.
Gujarat
Large-scale biscuit manufacturers in Ahmedabad and Vadodara trigger bulk amylase procurement for dough conditioning and shelf-life extension. PLI scheme incentives for food processing machinery lower capital barriers for enzyme-adopting manufacturers. The state's dairy belt near Anand connects to enzyme suppliers through established technical service relationships.
Karnataka
Mango and grape processing infrastructure around Bangalore generates emerging demand for juice clarification enzymes. State-level food safety enforcement intensifies ahead of FSSAI's national labeling rollout, forcing documentation investments. The Bangalore-Mysore corridor attracts beverage companies seeking pectinase and cellulase solutions for low-calorie sweetener production.
Tamil Nadu
Poultry and seafood processing units in Chennai and Coimbatore pull protease volumes for tenderization applications. CDSCO oversight on novel enzyme strains influences R&D investment priorities among nutraceutical-adjacent processors. The state's port infrastructure facilitates import clearance for specialized fermentation-derived preparations.
Punjab
Private milk processors in Ludhiana and Amritsar seek shelf-life extension enzymes for value-added dairy products. BIS certification requirements for imported enzyme preparations extend working capital cycles for mid-tier cooperatives. The state's grain processing belt connects to Gujarat suppliers through distributor networks spanning northern hinterlands.
India Food Enzymes Market Competitive Environment
The competitive structure tilts toward multinational specialists with microbial fermentation expertise and domestic integrators with backward strain development capabilities. Tier-1 suppliers embed application laboratories and regulatory dossier support into standard offerings. Tier-2 regional distributors face disintermediation pressure from digital B2B procurement platforms. Dominant competitive moves include capacity expansion near western processing clusters and technology licensing partnerships for novel strain engineering.
Among Danish and Irish multinational anchors, Novozymes A/S and Kerry Group PLC occupy positions exemplifying fermentation-scaled supply archetypes. Advanced Enzyme Technologies Limited represents the domestic integrator model with captive manufacturing infrastructure. These three entities anchor the supplier landscape through divergent geographic and capability positioning strategies.
| Leading Market Players |
|---|
| Novozymes A/S |
| Advanced Enzyme Technologies Limited |
| Koninklijke DSM N.V. |
| International Flavors & Fragrances |
| Kerry Group PLC |
| BASF SE |
| Lumis Biotech Pvt. Ltd. |
| Chr. Hansen |
| DuPont de Nemours, Inc. |
| Others |
Value Chain & Pricing Dynamics
Fermentation technologist scarcity in Maharashtra and Gujarat compresses labor-cost differentials into pricing-tier spreads, with enzyme suppliers embedding technical service premiums into standard contracts while mid-tier processors absorb spot-market volatility.
Pricing Analysis
Margin tightening in economy-tier formulations reflects BIS certification delays extending working capital cycles for cash-constrained bakeries. Three-tier pricing structure across premium, standard, and economy levels separates FSSAI-compliant multinationals from domestic strain developers and unbranded regional distributors. Price differentiation hinges on certification grade and embedded application laboratory support. Spot-market purchasers in tier-2 cities exhibit acute price sensitivity, while integrated food manufacturers prioritize regulatory dossier completeness over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Maharashtra's dairy cooperatives and Gujarat's biscuit manufacturers mandate multi-supplier qualification for amylase and protease volumes. Supply concentrates in Denmark, the Netherlands, and India for microbial fermentation expertise, with raw material dependencies spanning corn starch substrates, specialized nutrient media, and recombinant strain starter cultures. Single-source vulnerability in novel strain engineering creates procurement risk. Distribution runs through technical service representatives embedding directly into western India's processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSSAI's clean-label enforcement hardens compliance costs into a barrier-to-entry moat, advantaging incumbents with captive regulatory affairs capabilities and documented strain provenance.
For Market Incumbents: Deepen backward integration into strain development to reduce dependency on imported starter cultures. Expand application laboratory presence in Karnataka's emerging beverage belt ahead of competitor technical service deployment. Capacity addition near Mumbai-Pune anchors defensive positioning against CDSCO-registered nutraceutical convergence plays. For New Entrants and Emerging Players: Begin with juice clarification enzymes in Karnataka's mango processing corridor, where FSSAI labeling enforcement has outpaced supplier technical service coverage. White-space exists in pectinase formulations for low-calorie sweetener production. Digital B2B procurement platforms enable direct access to tier-2 biscuit manufacturers bypassing traditional distributor markups. For Investors and Strategic Acquirers: The window for entry favors domestic strain developers with captive manufacturing infrastructure and existing BIS certification portfolios. Acquisition targets should demonstrate dual food-pharma compliance capabilities under CDSCO oversight. Signal to monitor: enforcement intensity of FSSAI's granular enzyme source disclosure requirements accelerating consolidation among mid-tier processors.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Development Backward Integration | Captive microbial engineering reduces import dependency and compresses certification timelines for FSSAI compliance. |
| Application Laboratory Expansion | Embedded technical service in Karnataka beverage clusters captures reformulation cycles ahead of competitor deployment. |
| CDSCO Dual-Compliance Registration | Novel enzyme strains with food-pharma dossiers command premium positioning in nutraceutical-adjacent segments. |
| Digital B2B Platform Partnership | Direct procurement channels disintermediate traditional distributors serving Maharashtra and Gujarat mid-tier processors. |
| Cold-Chain Logistics Investment | Temperature-controlled distribution extends enzyme activity preservation into northern and central Indian hinterlands. |
Study Parameters
Trade databases, FSSAI regulatory filings, and BIS certification records formed the secondary backbone, cross-referenced against primary interviews with fermentation technologists, dairy cooperative procurement managers, biscuit manufacturer R&D directors, and enzyme distributor network heads. Bottom-up and top-down triangulation validated volume estimates across product type and application segments.
Bottom-up modeling built from individual facility capacity and utilization rates, while top-down analysis anchored in national food processing output statistics. Segmentation dimensions included enzyme class, source biology, application sector, and end-user procurement sophistication. CAGRs derived from trend extrapolation of PLI scheme uptake rates and FSSAI compliance timeline acceleration. Forecast inputs incorporated microbial fermentation yield improvements and cold-chain infrastructure rollout pace.
Regulatory enforcement timing, strain development breakthroughs, and cold-chain investment flows are the dominant revision risks to the outlook. Deviation in FSSAI labeling norm implementation speed would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Release Agent Market
Food Additives and Ingredients
Pet Food Emulsifier Market
Food Additives and Ingredients
Gelatin Films Market
Food Additives and Ingredients
South America Food Enzymes Market
Food Additives and Ingredients
Organic Food Additives Market
Food Additives and Ingredients
Monk Fruit Ingredient Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
Cake Enzyme Market
Food Additives and Ingredients
Gum Hydrocolloid Market
Food Additives and Ingredients
Global Natamycin Market
Food Additives and Ingredients
Wine Fining Agent Market
Food Additives and Ingredients
Japan Food Additives Market
Food Additives and Ingredients
Germany Feed Additives Market
Food Additives and Ingredients
Potassium Polymetaphosphate Food Additives Market
Food Additives and Ingredients
Leavening Agents Market
Food Additives and Ingredients
Calcium Butyrate Market