
 Household Care Wipes Market | 2026-2036
Household Care Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Household Care Wipes Market Foresight
Residential cleaning routines is broadening the addressable base for household care wipes as dual-income households prioritize time-saving hygiene solutions. Procter & Gamble leverages its manufacturing scale to dominate shelf space in mass retail channels across North America. Kimberly-Clark sustains R&D intensity in spunlace non-woven technologies that improve biodegradability without sacrificing tensile strength. SC Johnson anchors its position through brand strength in disinfectant formulations that carry EPA registration for pathogen-specific claims.
Household care wipes are non-woven fabric substrates impregnated with cleaning, disinfecting, or conditioning solutions, engineered for single-use or limited-reuse surface treatment in domestic and light commercial environments. Spunlace manufacturing dominates material production due to its superior liquid retention and soft hand-feel compared to thermal-bond alternatives. Antibacterial wipes command premium positioning as consumers prioritize pathogen elimination, while moist formats lead volume growth in everyday surface cleaning. Canister packaging occupies the highest margin pool through resealable convenience and countertop visibility, though soft packs compete aggressively on per-unit cost in bulk retail.
EPA disinfectant registration requirements in the United States mandate substantiated efficacy claims and restrict active ingredient concentrations, raising barriers for new entrants. REACH compliance in Europe limits certain quaternary ammonium compounds and drives reformulation toward plant-derived antimicrobials. BIS certification requirements in India govern fiber content labeling and chemical residue thresholds for imported wipe products. Stakeholders must monitor evolving chemical restriction lists across multiple jurisdictions while calibrating regional product portfolios to local regulatory timelines.
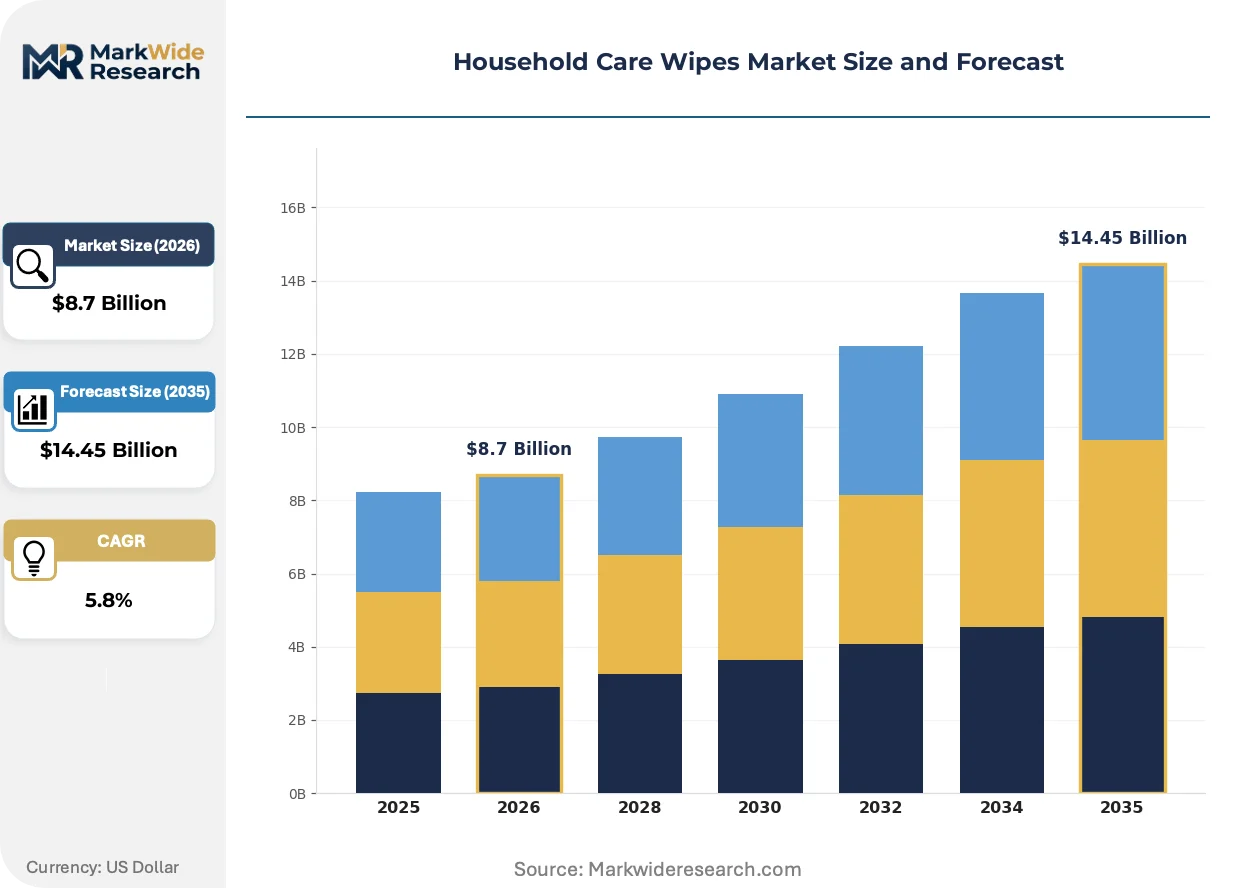
Market Dynamics
Spunlace non-woven manufacturing is consolidating supply chains as producers scale capacity to meet antibacterial wipe demand while navigating REACH chemical restrictions and EPA registration timelines.
Growth Catalysts
- REACH Chemical Reformulation:European manufacturers are accelerating plant-derived antimicrobial development to replace restricted quaternary ammonium compounds, opening premium positioning for compliant formulations.
- Dual-Income Household Time Compression:Residential buyers in the United States and Germany are prioritizing single-use convenience over traditional spray-and-cloth cleaning routines.
- Spunlace Capacity Expansion:Material suppliers are scaling liquid-retention engineered fabrics that improve biodegradability without sacrificing tensile performance in disinfecting applications.
Market Restraints
- Pulp Fiber Cost Volatility:Wood pulp input prices fluctuate with forestry harvest cycles and energy costs, compressing margins for moist wipe producers.
- EPA Registration Timelines:Pathogen-specific efficacy claims require 12-18 month substantiation periods that delay new product launches and freeze formulation innovation.
- Reusable Microfiber Substitution:Machine-washable cloth alternatives are capturing cost-conscious segments in Germany and Japan where environmental concern runs highest.
Strategic Opportunities
- India BIS Certification Gap:Domestic producers meeting fiber content labeling and chemical residue thresholds are capturing import substitution opportunities as foreign suppliers face compliance delays.
- EU Green Deal Biodegradability Mandates:Manufacturers developing certified compostable substrates ahead of 2030 packaging waste targets will secure preferential retail placement.
- Subscription Direct-to-Consumer Channels:Auto-replenishment models bypass mass retail slotting fees while capturing recurring revenue from hygiene-conscious households.
Industry Challenges
- Formulation Chemist Scarcity:Talent capable of balancing antimicrobial efficacy against plant-derived ingredient stability commands premium compensation and extended recruitment cycles.
- Cross-Border Regulatory Fragmentation:Divergent active ingredient approvals between EPA, ECHA, and Japan's PMDA force regional SKU proliferation that strains inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Care Wipes Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Antibacterial, Moist End User: Residential, Commercial, Institutional, Hospitality Packaging Type: Soft Pack, Resealable Pack, Canister, Bucket Material: Non-Woven Fabric, Spunlace, Polypropylene, Cotton |
| Companies Covered | Procter & Gamble, Kimberly-Clark, Clorox Company, Reckitt Benckiser, SC Johnson, Nice-Pak Products, Rockline Industries, Unilever, The Clorox Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Care Wipes Market Shifts & Advancements
Material science breakthroughs and regulatory chemistry shifts are restructuring competitive advantage around biodegradability certification and pathogen claim substantiation rather than base cleaning efficacy.
Bamboo-derived viscose fiber is consolidating position as the preferred sustainable substrate for premium household care wipes. German retailers are prioritizing shelf placement for products carrying FSC chain-of-custody certification. This material shift is consolidating supplier power toward pulp processors with integrated forestry assets.
EPA's emerging per- and polyfluoroalkyl substances restrictions are forcing reformulation of stain-resistant wipe coatings. Manufacturers must validate alternative barrier technologies before 2025 enforcement windows close. Disinfectant wipe producers with early PFAS-free submissions are securing first-mover positioning in United States mass retail.
After-sales service unbundling is fragmenting traditional brand loyalty as private-label suppliers offer equivalent spunlace substrates without marketing overhead. German and Japanese consumers are cross-shopping retailer-owned brands against established names based on ingredient transparency labels. This behavior shift concentrates volume in hard-discount channels where per-unit economics favor simplified formulations.
Household Care Wipes Market Segmentation
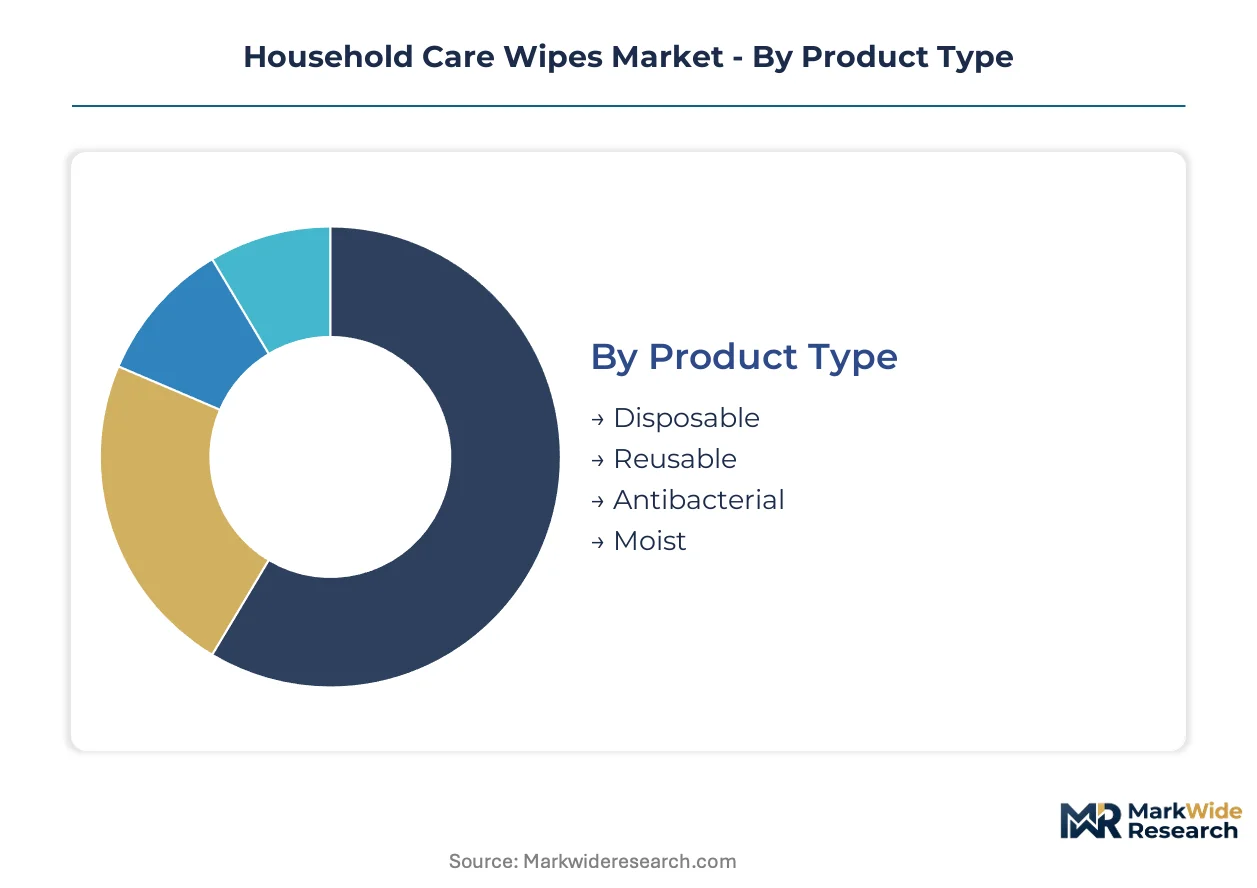
Household care wipes segmentation reflects divergent consumer priorities across convenience, sustainability, and pathogen elimination. Material chemistry and packaging engineering separate premium formulations from economy alternatives.
Product Type:
Customization spans single-use disposability through durable reusable formats, with antimicrobial claims commanding formulation complexity.
- Disposable:Single-use non-woven substrates dominate volume through spunlace manufacturing optimized for liquid retention and soft hand-feel. United States mass retail channels concentrate demand as dual-income households abandon spray-and-cloth routines for grab-and-go convenience.
- Antibacterial:Quaternary ammonium compound or plant-derived antimicrobial impregnation requires EPA registration in the United States and REACH compliance in Europe. Germany and Japan drive premium positioning as consumers prioritize verified pathogen elimination over basic surface cleaning.
- Reusable:Machine-washable microfiber or cotton substrates target cost-conscious segments in Germany where environmental concern accelerates substitution away from single-use formats.
- Moist:Pre-saturated formulations lead everyday surface cleaning volume through balanced surfactant chemistry that eliminates separate solution dispensing.
Leading the category by volume: Disposable. Growing fastest: Antibacterial.
End User:
Application intensity varies from daily residential touch-ups through institutional-grade disinfection protocols with divergent regulatory scrutiny.
- Residential:Individual household purchasers prioritize countertop visibility and resealable convenience over bulk economics. United States demand concentrates in suburban markets where time-compressed parents trade spray bottles for pre-moistened formats.
- Commercial:Office and retail maintenance contracts specify EPA-registered disinfectant claims with documented efficacy against norovirus and influenza. Procurement runs through facility management distributors with stringent chemical documentation requirements.
- Institutional:Healthcare-adjacent settings demand hospital-grade quaternary ammonium concentrations that exceed residential formulations. Japan's PMDA oversees antimicrobial claim substantiation for medical-adjacent applications.
- Hospitality:Hotel and restaurant operators balance guest-perceived hygiene theater against per-room cost targets. Soft pack formats compete aggressively on unit economics for back-of-house deployment.
Residential commands absolute volume. Commercial exhibits steepest expansion trajectory as return-to-office protocols institutionalize enhanced surface hygiene.
Packaging Type:
Margin structure stratifies across visibility-driven countertop presence versus cost-minimized bulk distribution.
- Canister:Rigid plastic containers with snap-lid resealability occupy premium shelf positioning through brand billboard effects. United States mass retail slotting fees favor established manufacturers with manufacturing scale to absorb placement costs.
- Soft Pack:Flexible film pouches with adhesive strip closures minimize per-unit material cost for bulk retail and hospitality procurement. German hard-discount channels concentrate volume as private-label suppliers eliminate marketing overhead.
- Resealable Pack:Zipper or tape-seal formats bridge convenience and economy for mid-tier residential purchasers. Moisture retention engineering determines repeat purchase rates.
- Bucket:High-capacity institutional formats with hinged lids serve commercial cleaning carts and healthcare supply closets. Refill economics drive purchasing decisions.
Canister leads margin capture. Soft pack gains share fastest through private-label expansion.
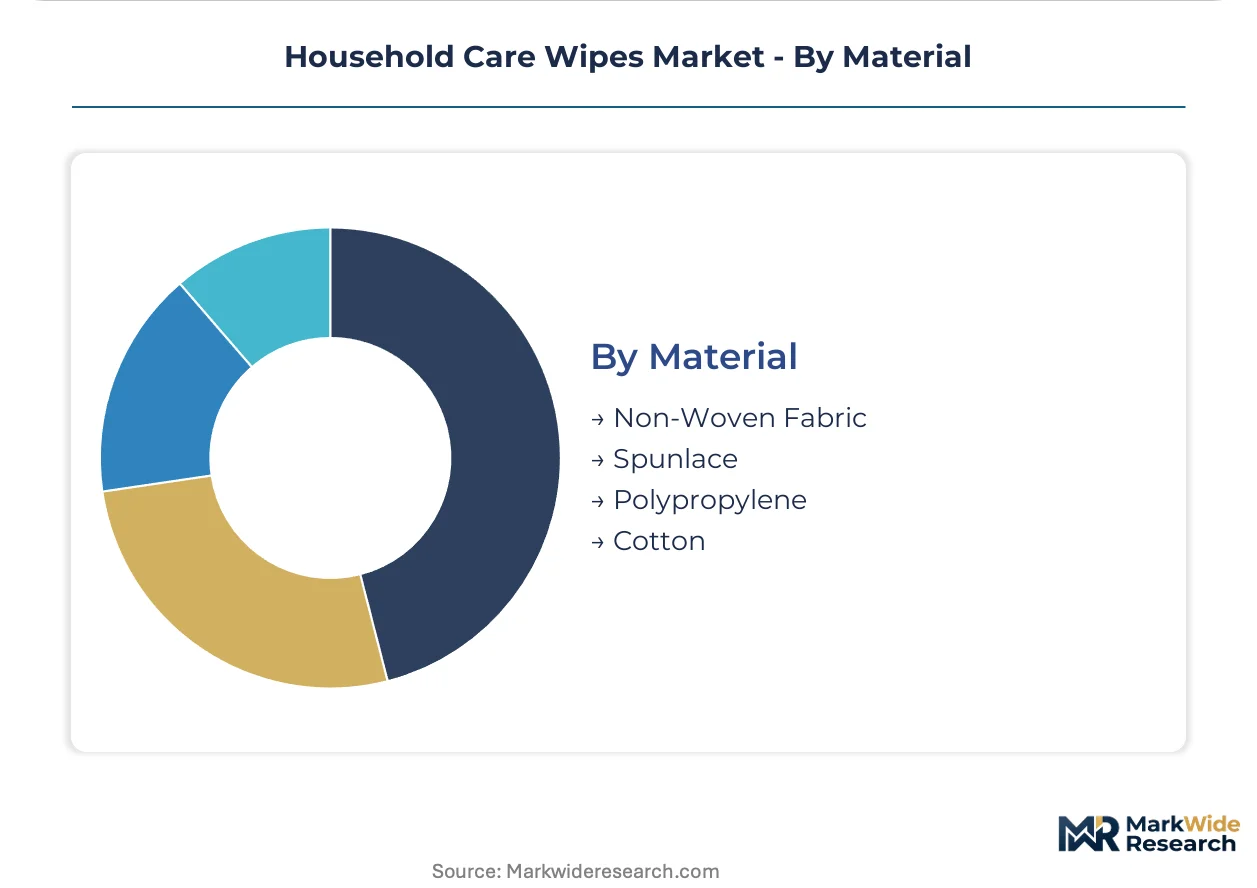
Material:
Substrate engineering balances liquid retention, tensile strength, and biodegradability certification against fiber cost volatility.
- Spunlace:Hydroentangled cellulose and synthetic blends dominate premium household care through superior drape and absorbency. German retailers prioritize FSC chain-of-custody certification for sustainable sourcing claims.
- Non-Woven Fabric:Thermal-bond or chemical-bond alternatives compete on cost for economy-tier disposables. India BIS certification governs fiber content labeling for imported substrates.
- Polypropylene:Synthetic thermoplastic fibers offer dimensional stability for wet-strength applications but face EU Green Deal biodegradability scrutiny. Reformulation toward certified compostable alternatives accelerates.
- Cotton:Natural fiber substrates command niche premium positioning for allergen-sensitive residential segments. Supply concentration among integrated textile processors limits new entrant access.
Spunlace dominates value. Cotton climbs fastest on sustainability positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Southeast Asia and special economic corridors in India concentrate wet-wipe manufacturing capacity as multinationals seek tariff-advantaged export platforms. Tax incentives in these zones reduce landed costs for North American and European markets while local regulators tighten chemical safety protocols.
United States
Dual-income suburban households in Texas and Florida drive canister-format volume through mass retail channels. EPA registration timelines for quaternary ammonium disinfectants extend 12-18 months, freezing formulation innovation cycles. Manufacturing clusters in North Carolina and Wisconsin specialize in spunlace non-woven substrates for private-label suppliers.
Germany
Hard-discount retail penetration in Bavaria and North Rhine-Westphalia accelerates soft-pack adoption among cost-conscious consumers. REACH restrictions on specific quaternary ammonium compounds force reformulation toward plant-derived antimicrobials. The ECHA chemical agency mandates updated safety data sheets for imported wipe substrates entering through Hamburg port facilities.
Japan
Tokyo and Osaka metropolitan areas concentrate demand for premium moist wipes with PMDA-registered antimicrobial claims. METI guidelines on plastic packaging waste drive development of certified compostable substrates. Regional distributors in Kansai prioritize products with JIS-standard biodegradability certification for hospitality procurement contracts.
India
Maharashtra and Gujarat textile belts scale spunlace capacity to serve domestic and export markets. BIS certification requirements for fiber content labeling and chemical residue thresholds delay foreign supplier entry. Domestic producers in Tamil Nadu capture import substitution opportunities through compliance-aligned manufacturing.
United Kingdom
London and Southeast England retail channels emphasize sustainability-labeled products ahead of EU Green Deal packaging waste targets. The Environment Agency enforces extended producer responsibility schemes for single-use wipes. Manchester-based converters develop FSC-certified bamboo viscose substrates for premium positioning.
Household Care Wipes Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with shelf-space dominance in mass retail favoring scale players while private-label suppliers capture hard-discount volume. The vendor base organizes around three archetypes: multinational consumer goods conglomerates with integrated manufacturing, regional spunlace substrate specialists, and private-label converters serving retailer-owned brands. Consolidation pressure intensifies as EPA registration costs and REACH compliance investments raise barriers for mid-tier entrants. Dominant competitive moves include backward integration into pulp processing and strategic partnerships with biodegradable material innovators.
Among North American consumer goods conglomerates, Procter & Gamble and Kimberly-Clark exemplify scale-driven archetypes that anchor mass retail positioning through manufacturing breadth and R&D intensity. SC Johnson occupies a position within the disinfectant-specialist tier, leveraging EPA-registered formulation expertise. These three entities represent the competitive concentration that smaller regional converters and private-label suppliers must navigate through cost positioning or sustainability differentiation.
| Leading Market Players |
|---|
| Procter & Gamble |
| Kimberly-Clark |
| Clorox Company |
| Reckitt Benckiser |
| SC Johnson |
| Nice-Pak Products |
| Rockline Industries |
| Unilever |
| The Clorox Company |
| Others |
Supply & Pricing Matrix
Mass retail procurement in the United States and Germany anchors pricing power toward suppliers with EPA-registered formulations and FSC-certified spunlace substrates, compressing margin capture for converters lacking manufacturing scale or regulatory documentation.
Pricing Analysis
Short lead-time premiums separate canister-format suppliers with domestic spunlace capacity from spot-market importers facing REACH compliance delays. Three-tier pricing structure across premium, standard, and economy levels reflects EPA registration tier, FSC chain-of-custody certification, and volume scale. Cost compression in soft-pack private-label tiers intensifies because pulp fiber volatility and discount retail slotting fees squeeze converter margins. Hospitality procurement in Japan exhibits highest price sensitivity, while institutional healthcare contracts in Germany show least sensitivity due to mandated disinfectant efficacy requirements.
Supply Chain Analysis
Single-source vulnerability sits with Indonesian and Malaysian pulp processors supplying bamboo-derived viscose fiber for premium biodegradable substrates. Raw material dependencies span wood pulp from Scandinavian forestry assets, quaternary ammonium compounds from Chinese chemical manufacturers, and polypropylene resin from South Korean petrochemical complexes. Tariff exposure on imported spunlace substrates into India strains inventory management for foreign suppliers awaiting BIS certification. Distribution runs through mass retail slotting-fee channels in the United States, hard-discount retail networks in Germany, and specialized medical distributors in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-derived antimicrobial chemistry is displacing legacy quaternary ammonium formulations as REACH restrictions and EPA emerging substance rules tighten active ingredient compliance windows.
For Market Incumbents: Anticipate reformulation cost spikes by securing captive supply of FSC-certified pulp assets and accelerating PFAS-free barrier technology validation ahead of enforcement windows. Backward integration into spunlace manufacturing in North Carolina or Wisconsin clusters defends margin position against private-label converters. EPA registration renewal timelines for existing quaternary ammonium claims represent the priority threat to monitor. For New Entrants and Emerging Players: The price-point gap between premium canister formats and economy soft-packs offers white-space targeting for mid-tier resealable packs with plant-derived antimicrobial claims. India domestic production meeting BIS fiber content and residue thresholds captures import substitution volume as foreign suppliers face compliance delays. Subscription direct-to-consumer auto-replenishment models bypass mass retail slotting fees while building recurring revenue from hygiene-conscious households. For Investors and Strategic Acquirers: The window for entry favors regional spunlace substrate specialists with integrated forestry assets and existing EPA or REACH formulation registrations. Five-to-ten year viability hinges on biodegradability certification positioning ahead of EU Green Deal packaging waste mandates. The signal to watch is accelerated private-label share capture in German hard-discount channels as ingredient transparency labels fragment traditional brand loyalty.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Processing | FSC-certified captive supply secures premium substrate access against Scandinavian forestry asset concentration. |
| PFAS-Free Barrier Technology Validation | Early EPA submission secures first-mover positioning in United States mass retail ahead of enforcement windows. |
| Subscription Direct-to-Consumer Launch | Auto-replenishment models bypass slotting fees while capturing recurring revenue from suburban dual-income households. |
| India BIS Certification Alignment | Domestic compliance captures import substitution opportunities as foreign suppliers face fiber labeling delays. |
| EU Green Deal Biodegradability Certification | Certified compostable substrates secure preferential retail placement ahead of packaging waste targets. |
Research Methodology
Independent corroboration across EPA registration databases, ECHA substance restriction lists, and BIS certification records underwrites the qualitative findings on regulatory compliance timelines. Primary interviews with spunlace manufacturing plant managers, mass retail category buyers, formulation chemists at disinfectant specialists, and hospitality procurement directors in Tokyo and Osaka combined with secondary validation from customs trade data, FSC chain-of-custody disclosures, and SEC filings from publicly traded consumer goods conglomerates. Bottom-up volume triangulation across product type, packaging format, and end-use segments cross-checks against top-down market sizing from pulp processor capacity announcements.
Rate-of-change decomposition across the analysis window segments growth drivers by material chemistry transition, regulatory reformulation requirements, and channel shift toward subscription models. Segmentation dimensions modeled include product type, packaging format, material substrate, and end-use intensity. CAGRs derive from elasticity-adjusted demand projections incorporating pulp fiber cost volatility and EPA registration timeline delays. Industry-specific forecast inputs incorporate spunlace capacity expansion announcements and REACH substance restriction amendment schedules.
Inputs from ECHA substance restriction consultations and EPA emerging contaminant monitoring were available through the study window; gaps in real-time private-label volume data from German hard-discount channels introduce uncertainty bands around share-shift projections. Forecasts reflect assumptions on regulatory enforcement timing and consumer willingness-to-pay premiums for biodegradability certification. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Australia Camping Equipment Market
Consumer Goods
Dosage Spoon Market
Consumer Goods
Air Care Market
Consumer Goods
Pre-Shave Products Market
Consumer Goods
Decorative Accessories Market
Consumer Goods
Middle East and Africa Hair Care Market
Consumer Goods
Children Digital Watch Market
Consumer Goods
Tattoo Accessories Market
Consumer Goods
Personal Care Shower and Bath Market
Consumer Goods
Asia-Pacific Gaming Keyboard Market
Consumer Goods
Saudi Arabia Perfume Market
Consumer Goods
Cookware Market
Consumer Goods
Shoe Shine Machine Market
Consumer Goods
Cat Hair Remover Market
Consumer Goods
Beauty Devices Market
Consumer Goods
Global Baby Swim Pants Diaper Market