
 Home and Laundry Care Market | 2026-2036
Home and Laundry Care Market Size, Share, and Industry Trends Forecast 2026-2036
Home and Laundry Care Market Intelligence
The European Union's REACH regulation, governing chemical substances, is recalibrating consumer expectations and product formulation strategies for cleaning agents. Unilever PLC leverages its extensive R&D to develop concentrated formulas that reduce water and packaging waste. The Procter and Gamble Co. dominates key segments through its massive manufacturing scale and global distribution network. Henkel AG and Co. KGaA differentiates with its material science expertise, influencing packaging and delivery systems.
Home and laundry care products are chemical formulations containing surfactants, enzymes, and builders designed to clean textiles and household surfaces. Their primary function is to remove soil, stains, and microorganisms through chemical and mechanical action. Liquid detergents continue to capture market share from powder detergents, driven by ease of use and cold-wash efficacy. In terms of end users, the commercial laundries segment provides more stable, high-volume contracts compared to the price-sensitive household sector.
Product safety and environmental claims are governed by bodies like the U.S. Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA). In China, national GB standards dictate permissible ingredients and labeling requirements, creating regional compliance hurdles for manufacturers. Navigating the divergent regulatory pressures on chemical composition and packaging sustainability will be critical for maintaining market access and brand trust.
Market Dynamics
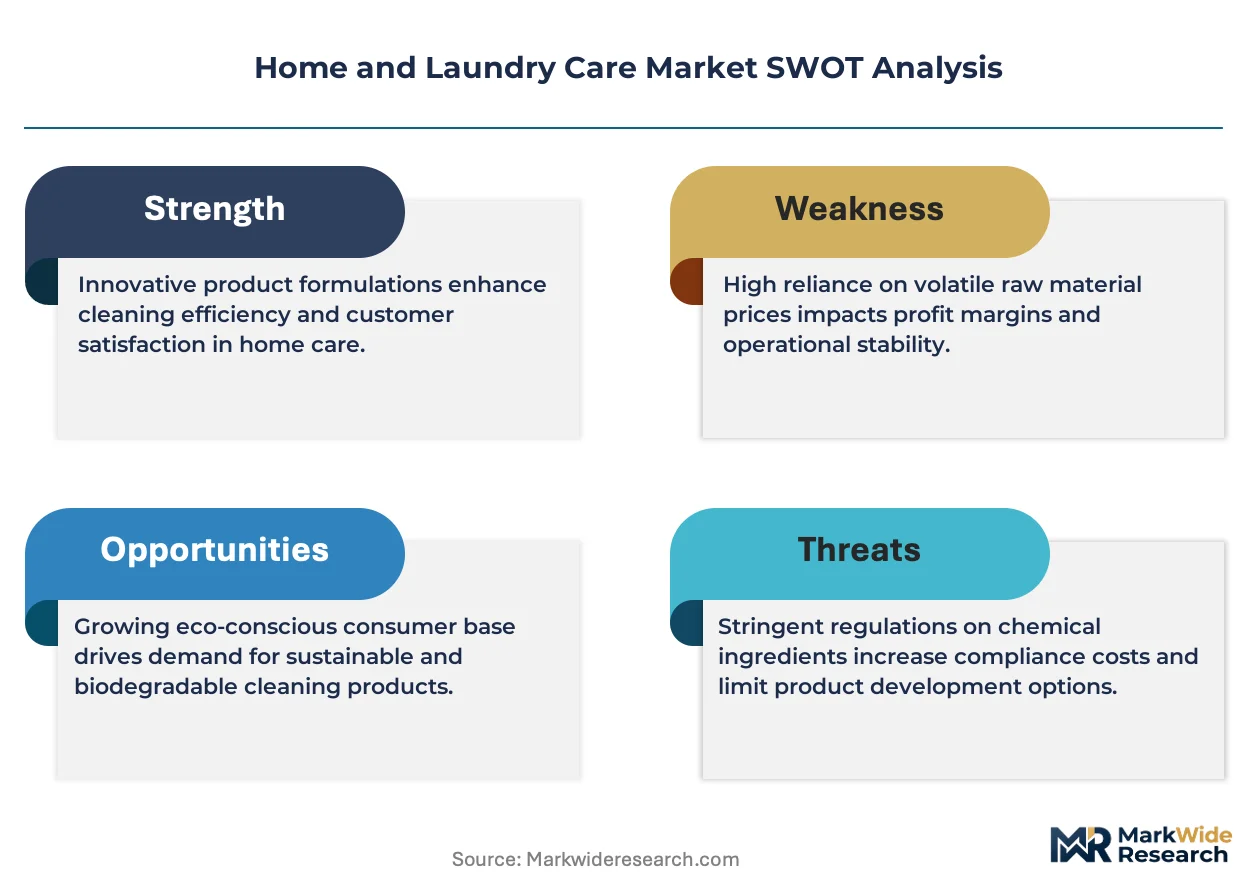
The central dynamic shaping the home and laundry care market is the regulatory pressure for sustainable chemistry, governed by frameworks like the EU Green Deal, which forces a fundamental re-evaluation of product formulations, packaging, and life-cycle impact.
Growth Catalysts
- Commercial Sector Expansion:Demand from commercial laundries in urban Indian centers is expanding, driven by higher hygiene standards in the hospitality and healthcare sectors, which require high-efficiency, bulk formulations.
- Sustainable Product Mandates:The EU Green Deal's focus on circular economy principles incentivizes development of biodegradable surfactants and enzymes, creating a premium market segment for certified eco-friendly products.
- Consumer Preference for Liquids:The ongoing shift from powder to liquid detergents, particularly in North America and Europe, is fueled by their superior performance in cold-water washes and ease of use with modern washing machines.
Market Restraints
- Input Cost Volatility:The price of surfactants, key active ingredients, is closely tied to volatile petrochemical feedstock prices, creating margin pressure and pricing instability for manufacturers.
- Regulatory Fragmentation:Divergent chemical safety standards, such as the European Chemicals Agency's REACH versus China's national GB standards, increase compliance costs and create barriers to global product harmonization.
- Price Sensitivity in Households:In the large but fragmented household segment, a significant portion of consumers prioritize price over brand loyalty or premium features, limiting uptake of innovative but costlier formulations.
Strategic Opportunities
- Concentrated and Solid Formats:Developing waterless or highly concentrated products, such as detergent sheets or pods, opens opportunities in e-commerce channels by reducing shipping weight and in water-scarce regions.
- Bio-Based Formulations:Investing in R&D for biosurfactants and novel enzymes allows brands to capture demand for high-performance products that also meet stringent environmental and health-conscious consumer expectations.
- Refill and Reuse Models:Launching subscription services for refillable packaging systems can build direct consumer relationships and brand loyalty, aligning with circular economy goals and reducing plastic waste.
Industry Challenges
- Supply Chain Reconfiguration:Transitioning from bulk, single-use packaging to support for refill stations and concentrated formats requires significant capital investment in new filling lines, logistics, and reverse logistics systems.
- Educating End Users:Overcoming consumer habits requires clear communication to ensure correct dosing of ultra-concentrated formulas, preventing product misuse, and demonstrating the value proposition beyond traditional formats.
- Substantiating Green Claims:Manufacturers face increasing scrutiny over environmental marketing claims, demanding rigorous life-cycle assessments to avoid "greenwashing" accusations and potential penalties from regulators like the U.S. EPA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home and Laundry Care Market |
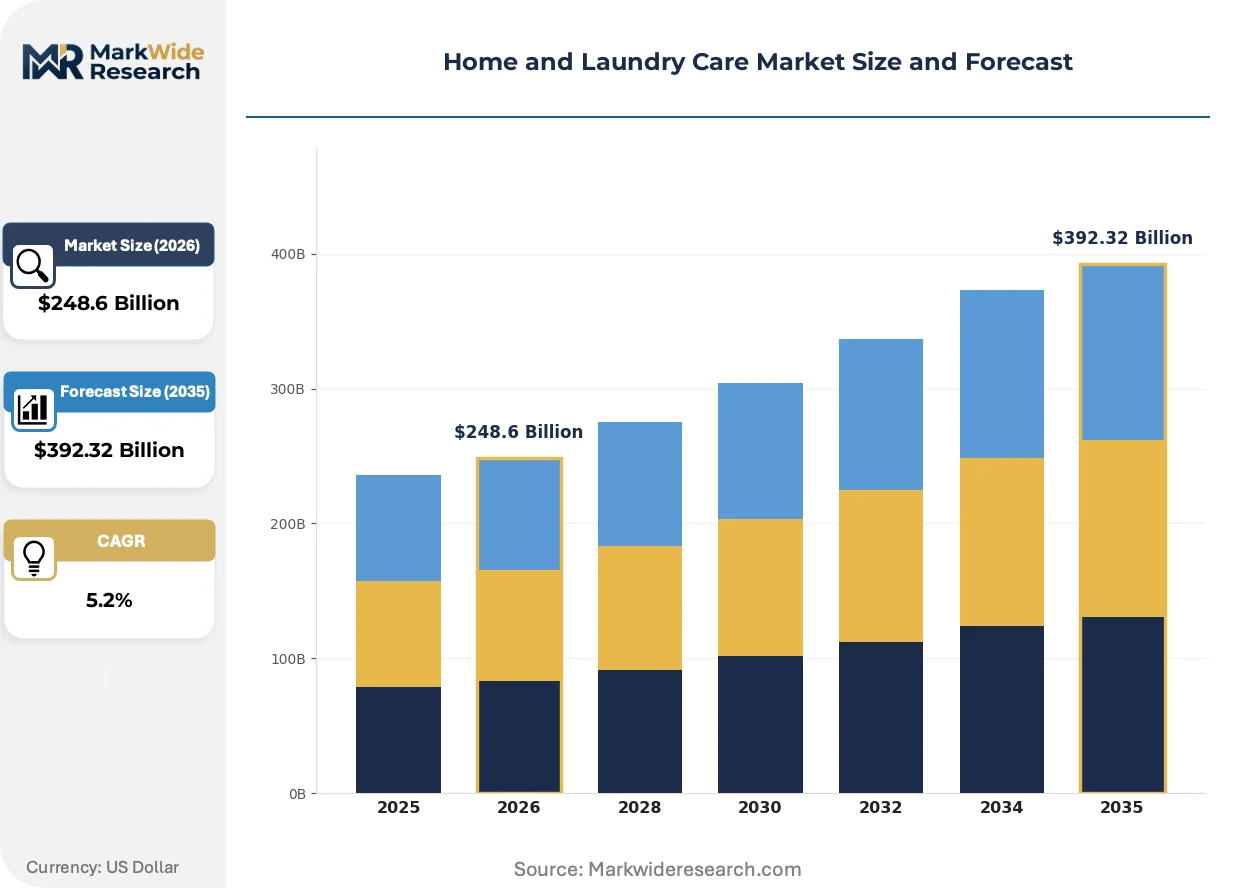
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $392.32 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Detergents, Powder Detergents, Fabric Softeners, Stain Removers End User: Households, Commercial Laundries, Hotels, Healthcare Facilities Distribution Channel: Online Retail, Supermarkets, Department Stores, Specialty Stores Packaging Type: Bottles, Sachets, Jars, Bulk Containers |
| Companies Covered | Reckitt Benckiser Group Plc, The Clorox Co., The Procter and Gamble Co., Church and Dwight Co. Inc., Colgate Palmolive Co., Unilever PLC, S.C. Johnson and Son Inc., Kao Corp., Henkel AG and Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home and Laundry Care Market Strategic Shifts & Innovations
Formulation science is being fundamentally re-engineered to meet the dual objectives of environmental sustainability and enhanced user convenience. This shift impacts everything from raw material sourcing to final product delivery systems, creating new competitive arenas for market participants.
Concentrated formulas, including pods, strips, and ultra-liquids, are designed to reduce water content, packaging materials, and transportation emissions. Adoption is highest among urban consumers and commercial laundries who value storage efficiency and precise dosing. This technology is consolidating market share around formats that offer superior logistical and environmental performance, displacing less efficient bulk powders and standard liquids.
The European Union's REACH regulation imposes stringent requirements for the registration, evaluation, and authorization of chemical substances. This forces manufacturers to provide extensive safety data for all ingredients, leading to the substitution of certain chemicals with safer, often more expensive, alternatives. The specialty chemical segment is most affected, as suppliers must now invest heavily in toxicological testing to maintain market access within the EU.
A notable behavioral shift is the adoption of subscription-based services that provide concentrated refills for durable, reusable containers. This model disrupts the traditional retail channel dominated by single-use packaging sold in physical stores, fostering a direct brand-to-consumer relationship. This trend is gaining the most traction in North American and Western European markets among environmentally-conscious households seeking to reduce their plastic footprint.
Home and Laundry Care Market Segmentation
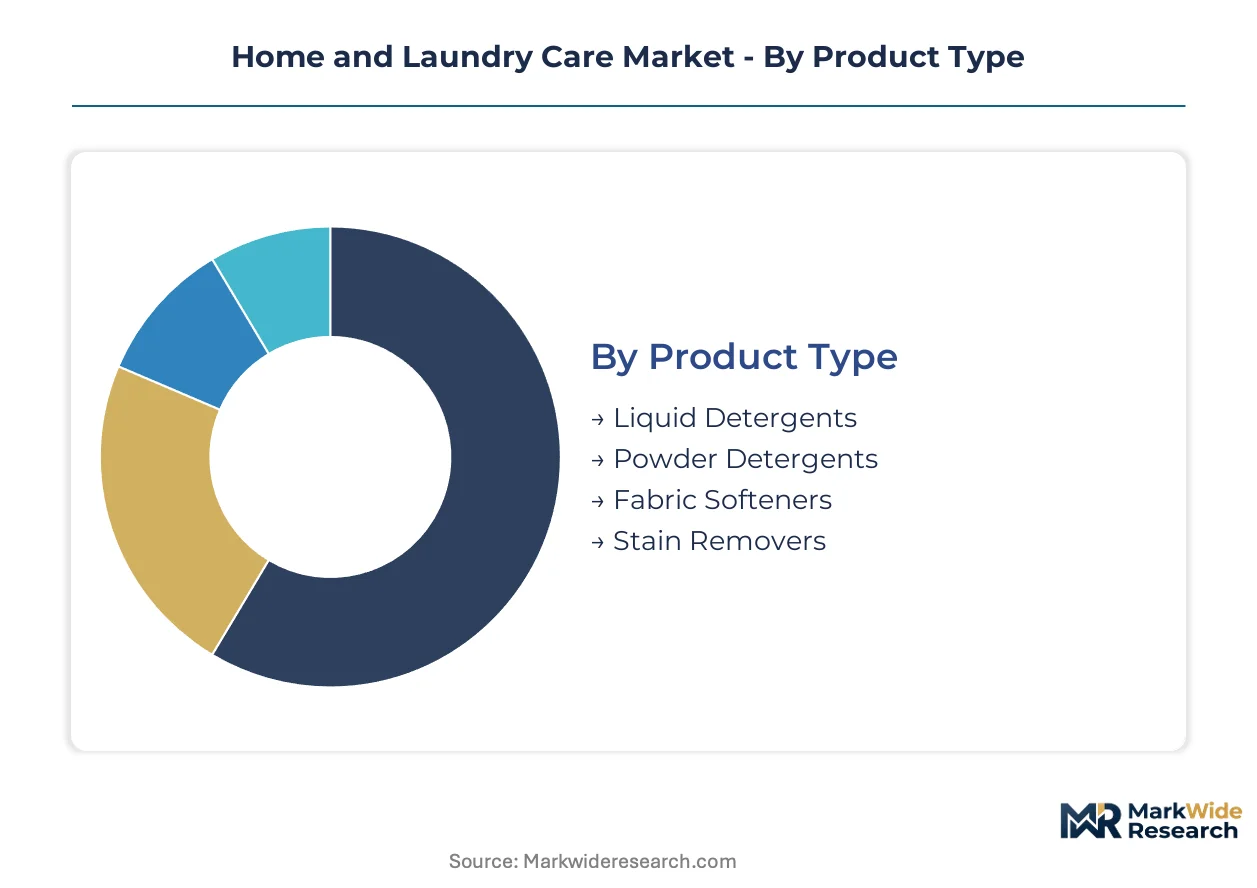
The home and laundry care market’s segmentation reveals how diverse product forms, end-user needs, and distribution strategies converge to meet evolving consumer and commercial demands. Understanding these distinctions is critical for manufacturers to tailor their offerings and market approaches effectively.
Product Type:
The home and laundry care market continually sees consumers evaluating product efficacy and convenience, driving shifts in their purchasing cycles for cleaning agents.
- Liquid Detergents:These concentrated formulations offer superior dissolution in cold water and precise dosing, appealing to consumers in North America and Europe using modern washing machines. Their ease of use contributes to their expanding market share.
- Powder Detergents:Typically more cost-effective and prevalent in emerging markets like India, powder detergents provide strong cleaning power for bulk laundry. Their traditional format still commands significant volume, particularly in price-sensitive household segments.
- Fabric Softeners:Designed to reduce static cling and enhance the tactile feel of fabrics, these products are often used as an additive to the primary wash cycle. Demand in Western Europe and Japan remains consistent for textile care.
- Stain Removers:Specialized chemical agents target specific types of stains, offering pre-treatment or in-wash solutions for challenging marks. These products serve a niche but essential function in maintaining garment longevity.
Volume placements concentrate in Powder Detergents; the faster expansion belongs to Liquid Detergents.
End User:
Different end-user segments exhibit varying price sensitivities and budget allocations, influencing the adoption rates of premium versus economy formulations.
- Commercial Laundries:This segment requires high-efficiency, bulk formulations for consistent, professional cleaning of large volumes of textiles. Demand from urban Indian centers is expanding due to stringent hygiene standards in hospitality and healthcare.
- Households:Comprising the largest but most price-sensitive segment, households seek convenience, efficacy, and value in their daily cleaning routines. Consumer preferences in the United States and Germany increasingly favor eco-friendly and concentrated options.
- Hotels:Hotels prioritize products that ensure guest satisfaction through clean linens and fresh amenities, often requiring specialized formulations for fabric care and stain removal. Procurement decisions are influenced by bulk pricing and consistent supply.
- Healthcare Facilities:Stringent sanitation protocols dictate the use of powerful disinfectants and hypoallergenic cleaning agents to prevent cross-contamination. Compliance with regulations from bodies like the U.S. EPA is paramount for these institutions.
The premium end of the market finds traction in Commercial Laundries, while Households drive overall market volume.
Distribution Channel:
The effectiveness of product delivery for home and laundry care items is heavily influenced by the specific purchasing habits and logistical requirements of diverse consumer applications.
- Online Retail:This channel facilitates the sale of concentrated and specialized formulations, benefiting from reduced shipping weight and direct-to-consumer models. Growth is pronounced in North America and China, driven by convenience and product variety.
- Supermarkets:Supermarkets remain the primary channel for mass-market home and laundry care products, offering broad accessibility and competitive pricing. Shoppers in France and Brazil frequently purchase their cleaning supplies during weekly grocery runs.
- Department Stores:These retailers often carry premium or niche brands, catering to consumers seeking higher-end or specialty cleaning solutions. Their curated selection targets a specific demographic willing to pay more for quality.
- Specialty Stores:Focusing on eco-friendly, organic, or unique formulations, these stores cater to health-conscious consumers or those with specific cleaning needs. Such outlets are common in urban centers across Germany and the United Kingdom.
Digital channels are increasingly critical for Online Retail, whereas Supermarkets maintain their broad consumer reach.
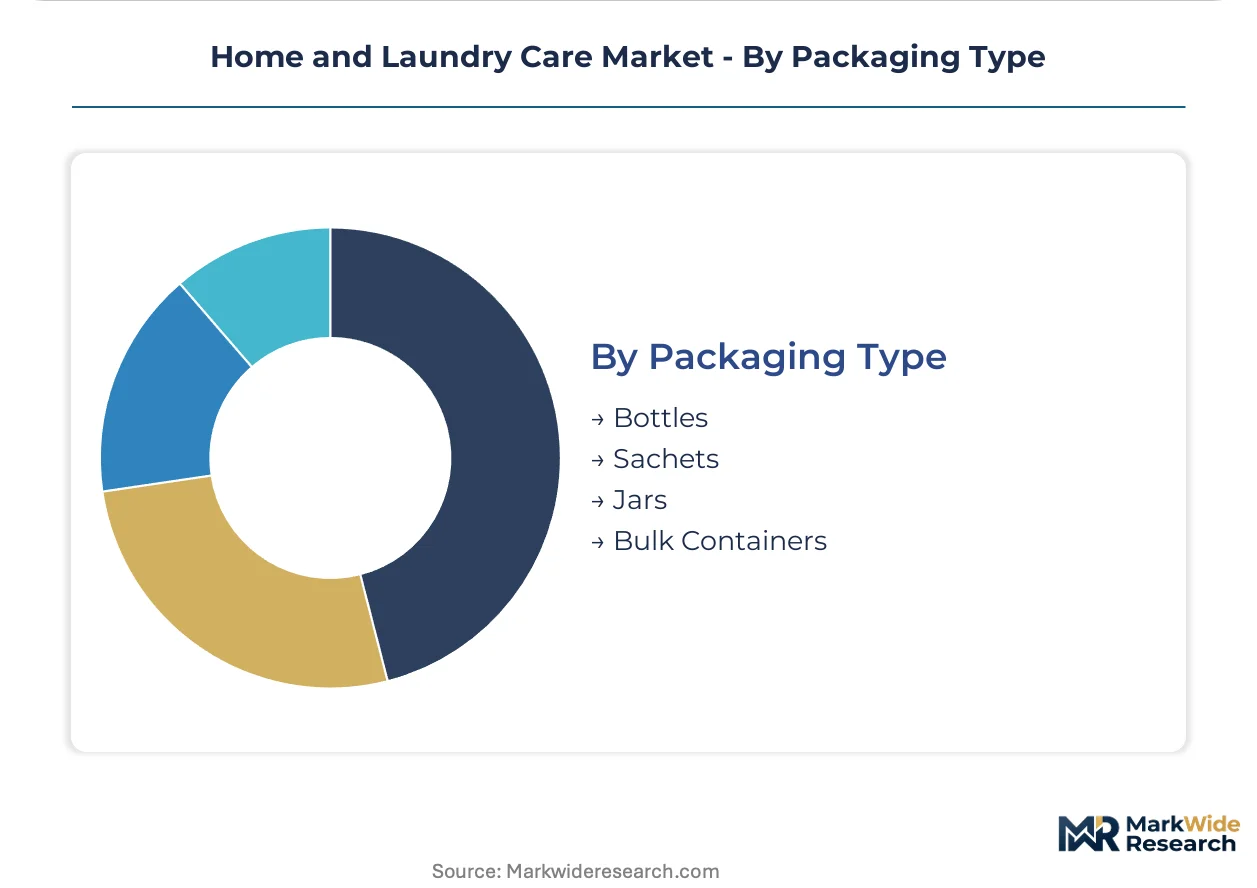
Packaging Type:
Packaging formats are often selected based on the volume requirements of the end-user and the efficiency desired for storage and transportation.
- Bulk Containers:Large-volume containers serve commercial laundries and institutional clients, offering cost efficiencies and reduced waste per use. These are essential for high-consumption environments in India and South Korea.
- Bottles:The most common packaging for liquid detergents and fabric softeners, bottles provide convenience for household use. Innovations in bottle design focus on recycled content and refill compatibility in markets like Germany.
- Sachets:Small, single-use sachets are popular in emerging markets and for travel-sized products, offering affordability and portability. Their widespread use is observed in Southeast Asia and parts of Africa.
- Jars:Typically used for powder detergents or specialized cleaning pastes, jars offer good product protection and are often resealable. This format is a staple in many traditional household cleaning product lines.
Bottles dominate in terms of unit volume, but Bulk Containers are gaining share due to sustainability initiatives and commercial demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban centers across India, particularly Mumbai and Delhi-NCR, drive significant demand for home and laundry care products. This concentration reflects rising disposable incomes and higher hygiene standards in major metropolitan areas. This dynamic influences product development and distribution strategies across the market.
India
Demand from commercial laundries in Indian cities is expanding, driven by stringent hygiene requirements in hospitality and healthcare. The Bureau of Indian Standards (BIS) influences product quality and safety norms for domestic manufacturers. Mumbai's rapidly expanding commercial sector requires high-efficiency, bulk formulations for consistent cleaning operations.
United States
Consumer preferences in the United States increasingly favor eco-friendly and concentrated options for household cleaning. The U.S. Environmental Protection Agency (EPA) governs product safety and environmental claims, impacting formulation choices. California's consumers, particularly in urban areas, show strong adoption of subscription-based refill services.
Germany
Households in Germany actively seek sustainable and concentrated cleaning solutions, aligning with broader environmental awareness. The EU Green Deal significantly influences product development, emphasizing circular economy principles for packaging and ingredients. Berlin and other major German cities exhibit a strong market for specialized eco-friendly cleaning agents.
China
Regulatory compliance with national GB standards dictates permissible ingredients and labeling requirements for cleaning agents in China. Online retail channels in China, especially in cities like Shanghai, facilitate the sale of concentrated and specialized formulations. This creates unique market entry challenges for international manufacturers adapting to local specifications.
France
Consumers in France frequently purchase their cleaning supplies during weekly grocery runs, making supermarkets a primary distribution channel. The EU Green Deal also shapes product innovation, encouraging biodegradable surfactants and enzymes. Paris and other French urban centers show consistent demand for fabric softeners and other textile care products.
Home and Laundry Care Market Key Industry Players
The competitive structure tilts toward established global conglomerates that leverage extensive R&D and massive manufacturing scale. These dominant players often compete with specialized innovators focusing on sustainable or niche formulations. The market also includes numerous regional brands catering to specific local preferences and price points. Strategic moves frequently involve significant investment in bio-based formulations and the expansion of global distribution networks.
Within the global conglomerate tier, The Procter and Gamble Co. and Unilever PLC represent entities with vast product portfolios and extensive international reach. These companies, characterized by their PLC and Co. structures, anchor significant market share across multiple product types and geographies. Their operational scale allows for broad market penetration and consistent product availability. Henkel AG and Co. KGaA, a German AG, exemplifies a major player differentiating through material science expertise and influencing packaging innovations. These firms operate with a broad strategic focus, spanning household and personal care categories.
| Leading Market Players |
|---|
| Reckitt Benckiser Group Plc |
| The Clorox Co. |
| The Procter and Gamble Co. |
| Church and Dwight Co. Inc. |
| Colgate Palmolive Co. |
| Unilever PLC |
| S.C. Johnson and Son Inc. |
| Kao Corp. |
| Henkel AG and Co. KGaA |
| Others |
Cost & Logistics Intelligence
Concentrated formulas and bio-based formulations reshape cost economics by reducing shipping weight and simultaneously influencing supply concentration towards specialized ingredient manufacturers. This transition allows for more efficient resource allocation across the value chain.
Pricing Analysis
Value-based pricing anchors the commercial laundries segment, where product efficacy and throughput directly correlate with contract value. Price differentiation stems from quality grade, brand premium, and eco-certification levels, particularly in European markets. Pricing pressure stems from volatile petrochemical feedstock prices, impacting surfactant costs across all segments. Households in emerging markets like India remain the most price-sensitive segment, while commercial laundries prioritize performance and consistent supply over marginal cost savings.
Supply Chain Analysis
China's national GB standards and the EU's REACH regulation impose local-content-rule pressures on ingredient sourcing, reshaping global supply chains. The home and laundry care market draws heavily from raw materials like petrochemical-derived surfactants and specialized enzymes, often sourced from global chemical producers. Commodity price volatility, especially for petrochemical feedstocks, represents a significant structural risk. Distribution runs through a hybrid model, combining mass-market supermarkets with direct-to-consumer online retail channels for specialized and concentrated products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story, with the EU Green Deal creating a significant barrier-to-entry moat for compliant players. Manufacturers must invest significantly in sustainable chemistry and circular economy principles to maintain market access.
For Market Incumbents: Deepen research and development into next-generation bio-based surfactants and enzyme technologies to align with evolving regulatory landscapes. Expand manufacturing capacity for concentrated formats in key urban centers, leveraging existing distribution networks. Invest in robust life-cycle assessment capabilities to substantiate green claims and proactively mitigate greenwashing accusations. Defend market share against niche eco-brands through strategic acquisitions of specialized formulation expertise.
For New Entrants and Emerging Players: Capture demand in the rapidly expanding online retail channels by offering highly concentrated or solid-format products. Target eco-conscious households in North America and Western Europe with subscription-based refill models. Focus on specific material science innovations, such as novel delivery systems or packaging solutions, to differentiate from established brands. A go-to-market strategy emphasizing transparency in ingredient sourcing and environmental impact will resonate with discerning consumers.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized ingredient manufacturers and technology providers enabling circular economy solutions. The long-term viability of this market hinges on sustainable innovation and regulatory compliance. Acquisition targets include firms with proprietary bio-based formulations or advanced packaging technologies that reduce plastic waste. The signal to watch for inflection is the widespread adoption of mandatory extended producer responsibility schemes across major economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint and ensures compliance with stringent regulations like the EU Green Deal. |
| Product Launch (Concentrated Formats) | Captures demand for efficient, eco-friendly products and reduces transportation costs for manufacturers. |
| Distribution Channel Expansion (Online/Refill) | Builds direct consumer relationships and supports circular economy goals by reducing single-use packaging. |
| Sustainability Repositioning | Enhances brand trust and market appeal among environmentally conscious consumers in developed markets. |
| R&D Investment (Bio-Based Formulations) | Develops high-performance, environmentally friendly alternatives to petrochemical-derived ingredients, meeting regulatory mandates. |
Research Approach
Independent corroboration across industry white papers, regulatory agency reports, and company annual filings underwrites the qualitative findings of this analysis. Combining primary interviews with R&D directors, procurement leads, brand managers, and regulatory affairs specialists provides granular insights. Secondary validation draws from trade data, academic research, and government publications, facilitating bottom-up and top-down triangulation.
The rate-of-change decomposition framing guides the quantitative forecast, dissecting market growth across the analysis window. Segmentation dimensions modeled include product type, end-user, distribution channel, packaging format, and regional regulatory frameworks. Compound annual growth rates were derived by factoring in historical market trends, projected economic indicators, and anticipated shifts in consumer behavior. Raw material price indices and regulatory compliance costs serve as key industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical stability, technological breakthroughs in green chemistry, and shifts in consumer preferences. The analytical framework reflects assumptions about market dynamics and regulatory evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Stationery Products Market
Consumer Goods
Gaming Computer Market
Consumer Goods
Asia Pacific Smartwatch Market
Consumer Goods
Global Residential Microwave Oven Market
Consumer Goods
Smart Television and Set-Top Box Market
Consumer Goods
Massage Pillow Market
Consumer Goods
Smart Kettle Market
Consumer Goods
Horsehair Clippers Market
Consumer Goods
Handmade Cigars Market
Consumer Goods
Fishing Tackle Box Market
Consumer Goods
Goggles Market
Consumer Goods
Facial Serum Market
Consumer Goods
South Korea Vegan Cosmetics Market
Consumer Goods
US Pet Food Market
Consumer Goods
South Africa Kitchen Appliances Market
Consumer Goods
Compound Bow and Crossbows Market