
 Highway, Street, and Bridge Construction Market | 2026-2036
Highway, Street, and Bridge Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Highway, Street, and Bridge Construction Market Insights
State transportation departments are reorganizing procurement priorities around climate-resilient designs, displacing traditional municipal buyers as the dominant contract source. China Communications Construction Company Limited leverages its integrated engineering-procurement-construction model across Belt and Road corridors. Kiewit Corporation anchors heavy civil project execution in North American megaprojects through self-performed concrete and steel capabilities. Skanska AB differentiates via its green construction certification depth and lifecycle carbon accounting for bridge assets.
Highway, street, and bridge construction encompasses the civil engineering, earthwork, paving, structural erection, and finishing operations required to build vehicular corridors and water crossings, typically involving asphalt or concrete surface courses over aggregate sub-bases with steel or prestressed concrete superstructures designed to withstand specified axle loads and environmental exposure. Its primary commercial purpose is creating durable transportation networks that enable freight logistics, commuter mobility, and regional economic connectivity. Rehabilitation projects now command the largest share of mature-market spending as aging infrastructure reaches design-life thresholds, while precast construction methods represent the fastest-expanding segment due to accelerated bridge replacement schedules and reduced traffic disruption. Composite materials remain a niche margin pool concentrated in corrosion-sensitive coastal and deicing-intensive environments.
The Federal Highway Administration mandates compliance with National Bridge Inspection Standards and Buy America provisions for federally funded projects, directly shaping material sourcing and contractor qualification requirements. EPA stormwater regulations under the Clean Water Act impose construction site runoff controls that elevate project engineering costs and timeline complexity. State departments of transportation enforce additional overload restrictions and seismic design criteria that vary by corridor classification. Stakeholders must monitor how infrastructure stimulus implementation timelines intersect with construction labor availability and domestic steel production capacity.
Market Dynamics
Federal surface transportation reauthorization in the United States is redirecting capital toward climate-resilient corridor designs, forcing contractors to retool engineering capabilities and procurement relationships around environmental performance mandates rather than lowest-bid award criteria.
Growth Catalysts
- India's national highway expansion corridors:The Ministry of Road Transport and Highways is accelerating greenfield corridor development through hybrid annuity and toll-operate-transfer models that de-risk private capital deployment.
- Smart infrastructure corridor mandates:Municipal governments across multiple continents are embedding sensor networks and intelligent traffic management into new-build specifications, creating bundled civil-digital procurement opportunities.
- Precast construction methods:Accelerated bridge replacement schedules are driving adoption of off-site manufactured superstructure components that compress project timelines and reduce traffic disruption penalties.
Market Restraints
- Domestic steel production capacity constraints:Buy America provisions under the Federal Highway Administration limit sourcing flexibility, exposing projects to mill capacity bottlenecks and price volatility during infrastructure stimulus waves.
- Specialized geotechnical labor scarcity:Foundation engineering expertise concentrates in a narrow contractor tier, creating bidding competition bottlenecks for complex water crossing projects.
- Composite materials cost premiums:Fiber-reinforced polymer decking remains economically uncompetitive against conventional prestressed concrete for standard-span applications outside corrosion-critical coastal zones.
Strategic Opportunities
- Lifecycle carbon accounting integration:Bridge asset owners are mandating embodied carbon disclosure through procurement scoring mechanisms, rewarding contractors with verified environmental product declarations.
- Rehabilitation project bundling:Aging infrastructure reaching design-life thresholds creates multi-year program opportunities for integrated design-build-maintain contracts.
- Modular expansion joint systems:Standardized component libraries are enabling rapid-deployment bridge maintenance that minimizes lane closure duration and user delay costs.
Industry Challenges
- Stormwater compliance engineering complexity:EPA construction site runoff controls under the Clean Water Act require specialized erosion control design and monitoring capabilities that extend pre-construction timelines.
- Seismic design criteria fragmentation:State departments of transportation enforce corridor-specific structural performance standards that complicate multi-jurisdictional contractor qualification and design standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Highway, Street, and Bridge Construction Market |
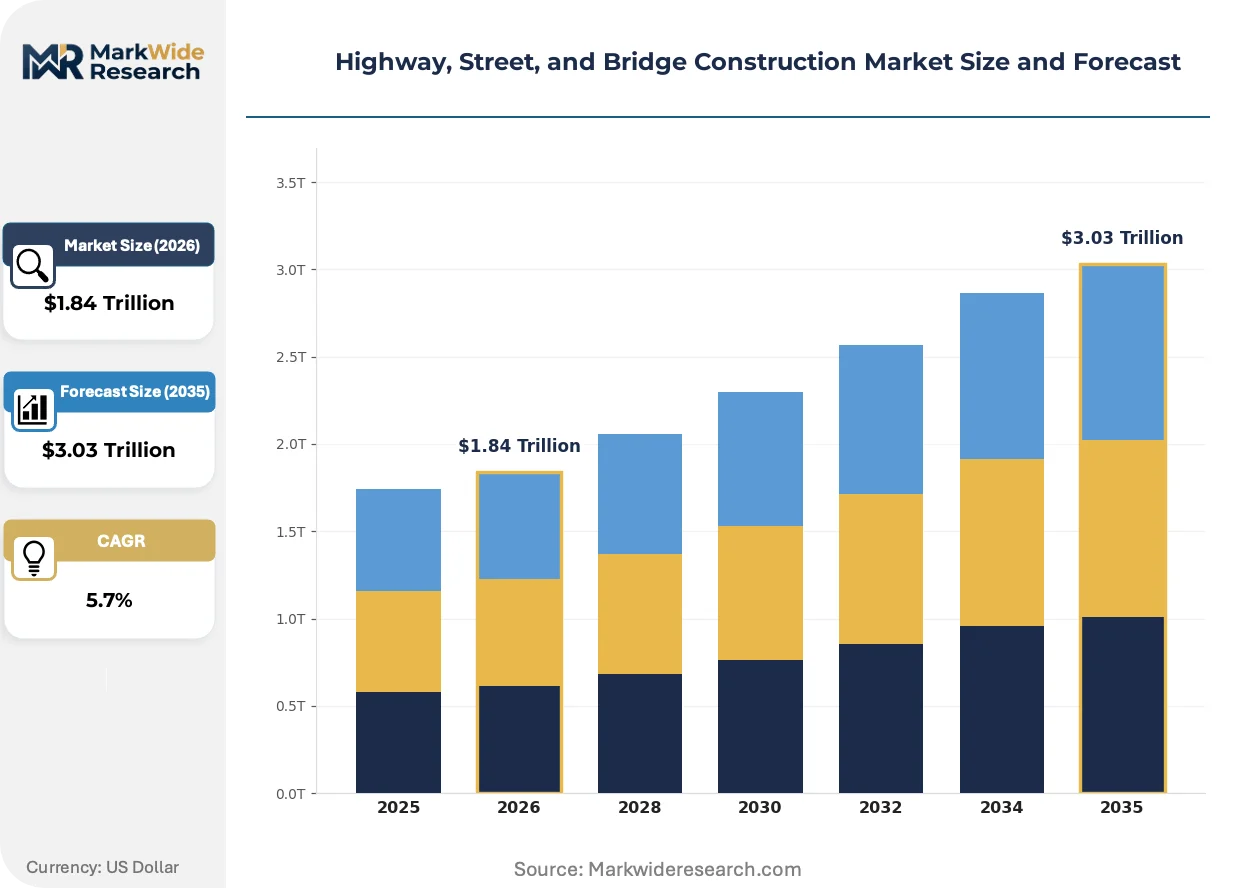
| Market Size in 2026 | $1.84 Trillion |
| Market Size in 2035 | $3.03 Trillion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: New Construction, Rehabilitation, Maintenance, Expansion Material Type: Asphalt, Concrete, Steel, Composite Construction Method: Traditional, Modular, Precast, Green Construction End User: Government, Private Sector, Contractors, Engineering Firms |
| Companies Covered | China Communications Construction Company Limited, China Railway Group Limited, Grupo ACS, Balfour Beatty, Kiewit Corporation, AECOM, Skanska AB, Bouygues Construction, Fluor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Highway, Street, and Bridge Construction Market Trends and Innovations
Digital fabrication and materials science advances are compressing traditional construction timelines while environmental compliance frameworks are embedding carbon performance into contract award mechanisms.
Ultra-high-performance concrete is displacing conventional reinforced concrete in bridge deck overlays and connection details. State transportation departments in corrosion-intensive regions are specifying UHPC for its superior durability and reduced maintenance liability. The material is displacing epoxy-coated rebar and latex-modified concrete as the default specification for aggressive environments.
The Federal Highway Administration's Buy America provisions are tightening domestic content requirements for federally assisted projects. Steel and iron sourcing documentation now consumes substantial pre-award administrative capacity. Contractors with captive supply relationships or backward integration into domestic fabrication are securing preferential qualification status.
Performance-based contractor selection is supplanting low-bid procurement for complex rehabilitation programs. Asset owners are weighting technical approach, past performance, and lifecycle cost methodology more heavily in scoring algorithms. This shift is most pronounced in California and New York, where seismic resilience and climate adaptation requirements demand specialized execution capabilities.
Highway, Street, and Bridge Construction Market Segmentation
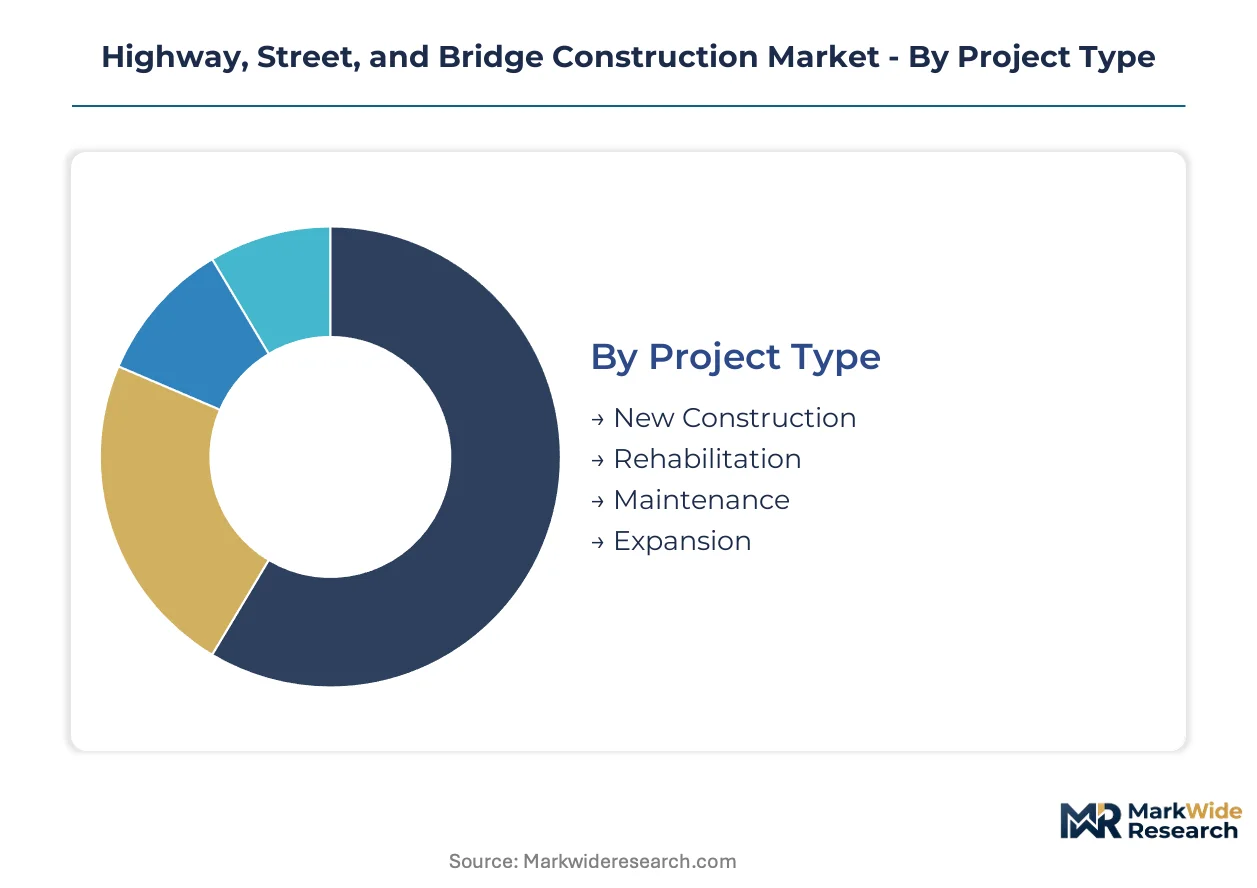
Segmentation in highway, street, and bridge construction reveals how capital allocation patterns diverge between mature infrastructure rehabilitation and emerging corridor development. Understanding these divides exposes where procurement volumes concentrate and which technical capabilities command premium positioning.
Project Type:
Rehabilitation work dominates domestic public spending while new construction concentrates in export-led infrastructure diplomacy corridors.
- New Construction:Greenfield corridor development requires integrated design-build capabilities for full lifecycle asset delivery. India's national highway expansion corridors and Belt and Road initiatives in Southeast Asia absorb the largest capital commitments, driven by last-mile connectivity gaps in freight logistics networks.
- Rehabilitation:Structural renewal of bridges reaching design-life thresholds involves superstructure replacement and substructure repair under traffic maintenance conditions. United States state transportation departments and European national road authorities command the deepest project pipelines, constrained by Buy America sourcing mandates and EU Green Deal carbon disclosure requirements.
- Maintenance:Routine pavement preservation and bridge inspection cycles sustain recurring revenue streams for regional contractors with established agency relationships.
- Expansion:Lane addition and capacity augmentation projects respond to congestion pricing corridors and port access demands in coastal logistics clusters.
Rehabilitation holds the largest share; momentum sits with new construction in South and Southeast Asian corridors.
Material Type:
Cost tier stratification separates premium durability specifications from commodity-grade applications, with corrosion resistance driving material selection in coastal and deicing-intensive environments.
- Concrete:Prestressed and ultra-high-performance formulations anchor superstructure and deck applications through superior compressive strength and reduced maintenance liability. State DOT specifications in corrosion-aggressive regions are displacing epoxy-coated rebar with UHPC overlays, tightening qualification requirements for ready-mix suppliers with certified environmental product declarations.
- Asphalt:Surface course and binder layer applications dominate pavement construction through lower initial capital outlay and rapid traffic restoration. Municipal street networks and secondary highway systems in North America and Europe maintain the deepest demand concentration, though thermal susceptibility limits specification in extreme climate zones.
- Steel:Structural shapes and reinforcement bars face sourcing constraints under domestic content mandates, exposing projects to mill capacity bottlenecks during stimulus waves.
- Composite:Fiber-reinforced polymer decking occupies niche positioning in marine environments and chemical exposure settings where corrosion immunity justifies cost premiums.
Concrete commands the largest installed base; composites climb the fastest in coastal resilience specifications.
Construction Method:
Volume concentration shifts toward off-site fabrication as accelerated bridge construction programs compress project timelines and reduce user delay penalties.
- Precast:Factory-manufactured superstructure components enable rapid-deployment replacement of deficient bridges with minimal traffic disruption. United States counties and state DOTs facing emergency replacement schedules are mandating precast pile caps and deck panels, rewarding contractors with captive casting yards and heavy-lift equipment fleets.
- Modular:Prefabricated bridge systems and tunnel segments support standardized component libraries for repetitive span configurations. Japan's metropolitan expressway authorities and Nordic infrastructure agencies specify modular expansion joint systems for rapid maintenance deployment.
- Traditional:Cast-in-place concrete and stick-built steel erection retain dominance in complex geometry applications and remote sites lacking precast logistics access.
- Green Construction:Embodied carbon reduction protocols and circular material sourcing are penetrating procurement scoring mechanisms in California and EU member states.
Traditional methods retain the largest share; precast gains share fastest in accelerated replacement programs.
End User:
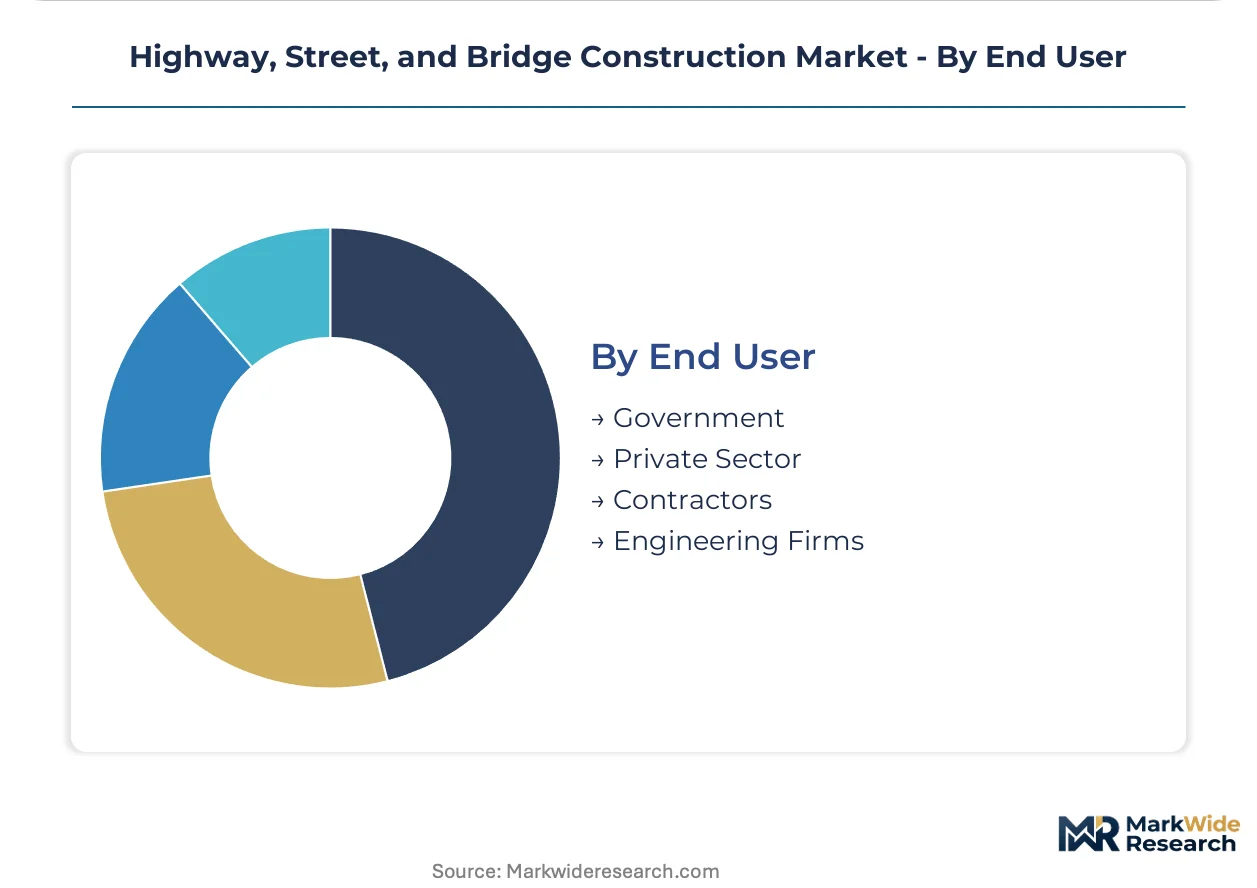
Customer type determines contract structure complexity, with government procurement dominating capital-intensive corridor development and private sector engagement concentrating in toll concession and logistics facility access.
- Government:Federal, state, and municipal transportation departments administer the deepest project pipelines through design-bid-build and design-build procurement. United States Federal Highway Administration funding cycles and India's Ministry of Road Transport and Highways hybrid annuity models shape contractor cash flow profiles and bonding capacity requirements.
- Private Sector:Toll road concessionaires and industrial facility developers demand integrated civil-digital delivery for smart corridor specifications. Logistics real estate investment trusts in North American inland port corridors and European freight villages are bundling access road construction with warehouse pad development.
- Contractors:Self-performing heavy civil specialists with in-house concrete and steel capabilities capture megaproject execution roles through technical qualification advantages.
- Engineering Firms:Design consultants and construction management advisors support owner agencies through independent assurance and project delivery oversight.
Government holds the largest share; private sector participation expands most quickly in availability-payment concession structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contractor capacity clusters in the United States, China, and India absorb the dominant share of capital deployment. Domestic content mandates and stimulus funding cycles reshape procurement flows across these markets. Regional specialization patterns reflect varying infrastructure maturity and funding mechanism design.
United States
Federal surface transportation reauthorization redirects capital toward climate-resilient corridor designs. The Federal Highway Administration enforces Buy America provisions that constrain steel sourcing flexibility. Texas and California transportation departments command the deepest state-level project pipelines through design-build procurement.
China
Belt and Road corridor development absorbs substantial engineering-procurement-construction capacity. The Ministry of Transport coordinates national highway network expansion through state-owned enterprise consortia. Yangtze River Delta and Pearl River Delta regions concentrate precast manufacturing and heavy-lift equipment fleets.
India
National highway expansion corridors drive greenfield development through hybrid annuity and toll-operate-transfer models. The Ministry of Road Transport and Highways accelerates private capital deployment via de-risked concession structures. Gujarat and Maharashtra anchor the deepest contractor concentration for western corridor execution.
Germany
Federal trunk road maintenance programs sustain rehabilitation demand as bridge assets reach design-life thresholds. The EU Green Deal carbon disclosure requirements reshape material specification and procurement scoring. Bavaria and North Rhine-Westphalia transportation authorities lead adoption of lifecycle carbon accounting for bridge assets.
United Arab Emirates
Logistics corridor and port access infrastructure absorbs capital through availability-payment concession structures. Federal transport regulations emphasize smart infrastructure embedding for freight optimization. Dubai and Abu Dhabi municipal authorities specify bundled civil-digital procurement for intelligent traffic management integration.
Highway, Street, and Bridge Construction Market Competitive Landscape
Concentration sits with integrated engineering-procurement-construction conglomerates and self-performing heavy civil specialists. The market structure divides between state-backed enterprises with diplomatic project access and privately held contractors with technical qualification depth. Strategic archetypes include full-lifecycle asset developers, regional rehabilitation specialists, and digital-integrated corridor builders. Competitive moves center on design-build-maintain contract capture and precast manufacturing capacity expansion.
Among state-backed conglomerates, China Communications Construction Company Limited and China Railway Group Limited occupy positions spanning Belt and Road corridor execution. Kiewit Corporation anchors the self-performing specialist tier with captive concrete and steel capabilities. Skanska AB exemplifies the sustainability-differentiated archetype through green construction certification depth and lifecycle carbon accounting integration.
| Leading Market Players |
|---|
| China Communications Construction Company Limited |
| China Railway Group Limited |
| Grupo ACS |
| Balfour Beatty |
| Kiewit Corporation |
| AECOM |
| Skanska AB |
| Bouygues Construction |
| Fluor Corporation |
| Others |
Pricing and Supply Chain Analysis
Ultra-high-performance concrete substitution for epoxy-coated rebar in corrosion-aggressive bridge specifications is simultaneously shifting supply geography toward certified ready-mix suppliers with environmental product declarations and compressing pricing economics for traditional reinforcement tiers.
Pricing Analysis
Buy America provisions dictate the pricing tier structure across federally assisted highway and bridge projects. Three-tier pricing structure across premium UHPC-certified, standard domestic-concrete, and economy imported-steel tiers separates contractors by qualification depth. Cost compression in standard concrete segments is intensifying because mill capacity bottlenecks during stimulus waves expose projects to steel price volatility. Municipal transportation departments exhibit the highest price sensitivity due to fixed budget appropriations, while federal megaproject buyers prioritize technical qualification over unit cost.
Supply Chain Analysis
Strategic stockpiling of precast components dominates contractor inventory strategy as accelerated bridge construction programs compress procurement lead times. Manufacturing concentrates in the United States, China, and India where captive casting yards and heavy-lift equipment fleets anchor regional execution capacity. The supply chain draws from domestic steel mills, certified ready-mix concrete plants, and specialized geotechnical engineering subcontractors. Single-source vulnerability in foundation engineering expertise creates bidding competition bottlenecks for complex water crossing projects. Distribution runs through state transportation department procurement portals and design-build consortium arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federal surface transportation reauthorization cycles position this market for cyclical recovery, with infrastructure stimulus implementation timelines intersecting with construction labor availability to create episodic demand surges.
For Market Incumbents: Compound technical qualification advantages by expanding captive precast manufacturing capacity in corridors with accelerated replacement schedules. Deepen backward integration into domestic steel fabrication to secure preferential qualification status under tightening Buy America enforcement. Counter specialized geotechnical labor scarcity through apprenticeship pipeline investments in foundation engineering capabilities. For New Entrants and Emerging Players: Lifecycle carbon accounting services represent a service-layer gap where incumbents under-serve asset owner procurement scoring requirements. Target state transportation departments in California and New York where seismic resilience mandates demand specialized execution capabilities. Penetrate through design-build-maintain contract bundling for aging bridge rehabilitation programs. For Investors and Strategic Acquirers: Capital is best deployed toward self-performing heavy civil specialists with in-house concrete and steel capabilities. Long-term viability hinges on contractor positioning within federal funding cycles and domestic content compliance infrastructure. Watch infrastructure stimulus appropriation velocity as the inflection indicator for capacity utilization and pricing power restoration.| Strategic Initiative | Industry Significance |
|---|---|
| Precast Manufacturing Capacity Expansion | Captive casting yards secure accelerated bridge construction procurement advantages under FHWA emergency replacement schedules. |
| Lifecycle Carbon Accounting Integration | Verified environmental product declarations satisfy EU Green Deal and California DOT procurement scoring mechanisms. |
| Backward Integration into Steel Fabrication | In-house production of structural components ensures Buy America compliance and insulates against mill capacity bottlenecks. |
| Design-Build-Maintain Contract Capture | Multi-year program structures align contractor cash flows with state transportation department rehabilitation pipelines. |
| Smart Infrastructure Partnership Development | Bundled civil-digital delivery capabilities meet municipal intelligent traffic management specification requirements. |
Research Methodology
Operator-level perspectives from state transportation department procurement officers, heavy civil project executives, precast manufacturing plant managers, and geotechnical engineering specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through Federal Highway Administration funding cycle disclosures, state DOT capital improvement program documents, EPA stormwater compliance filings, and industry association construction spending surveys. Bottom-up project pipeline enumeration triangulated against top-down infrastructure stimulus appropriation analysis.
Sensitivity analysis across material cost volatility scenarios, labor availability constraints, and regulatory implementation timelines shaped the analytical framework. Segmentation dimensions modeled include project type, material specification tier, construction method, and end-user procurement structure across the projection horizon. CAGRs derived from historical spending pattern regression and infrastructure investment elasticity coefficients, incorporating federal surface transportation reauthorization timing and domestic steel production capacity utilization as industry-specific forecast inputs.
Underlying assumptions cover infrastructure stimulus execution efficiency, construction labor market equilibrium, and domestic mill capacity expansion, with deviation risk concentrated in Buy America enforcement intensity and composite materials cost competitiveness. Revision becomes warranted when federal funding appropriation velocity crosses thresholds that strain contractor bonding capacity or precast manufacturing throughput.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Italy Architectural Coatings Market
Construction and Engineering
Weighbridge Market
Construction and Engineering
Foundry Sand Cleaning Machine Market
Construction and Engineering
Global Air Conditioner Market
Construction and Engineering
Asia-Pacific Building Automation System Market
Construction and Engineering
Commonwealth of Independent States (CIS) Underground Mining Equipment Market
Construction and Engineering
Japan Cross Laminated Timber (CLT) Market
Construction and Engineering
India Automated Material Handling (AMH) Market
Construction and Engineering
Reverse Circulation Drill Pipes Market
Construction and Engineering
Siding Market
Construction and Engineering
Piping Systems Market
Construction and Engineering
Qatar Residential Construction Market
Construction and Engineering
Ceramic Tile Printing Machine Market
Construction and Engineering
Painting Tools Market
Construction and Engineering
Europe Modular Construction Market
Construction and Engineering
Cherry Picker Crane Market