
 Global Veterinary CRO Market | 2026-2036
Global Veterinary CRO Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary CRO Market Foresight
Modular service bundling is expanding across the veterinary CRO landscape as sponsors seek integrated preclinical-to-regulatory pathways rather than fragmented vendor relationships. Charles River Laboratories leverages its captive vivarium network to anchor multi-species toxicology programs across North America and Europe. Labcorp Drug Development competes through diagnostic-to-CRO connectivity that sustains longitudinal study continuity. IDEXX Laboratories specializes in companion animal endpoints, dominating the clinical pathology segment that underpins FDA submission packages.
A veterinary contract research organization delivers outsourced scientific studies—toxicology, pharmacokinetics, safety pharmacology, and efficacy trials—conducted under GLP conditions to generate regulatory submission data for animal health products. Preclinical Research occupies the largest revenue pool due to mandatory toxicology requirements for new molecular entities, while Clinical Trials capture faster expansion as biologics and monoclonal antibodies for companion animals proliferate. Bioanalytical Services sit at the margin center because method validation for species-specific matrices commands premium pricing and repeat engagement cycles.
The FDA's Veterinary Innovation Program and the EMA's CVMP guidelines jointly shape study design standards, while ISO 10993 and OECD Test Guidelines harmonize cross-border data acceptability. The EU's Veterinary Medicines Regulation (Regulation 2019/6) accelerates demand for European-located CRO capacity as sponsors seek streamlined centralized marketing authorizations. Stakeholders must monitor regulatory divergence between FDA minor-use pathways and EMA environmental risk assessment requirements when configuring multi-jurisdictional development programs.
Market Dynamics
Modular service bundling is compressing vendor relationships across the veterinary CRO landscape as pharmaceutical sponsors abandon fragmented outsourcing for integrated preclinical-to-regulatory pathways. This structural shift favors organizations with captive vivarium networks and cross-border GLP certification.
Growth Catalysts
- FDA Veterinary Innovation Program:The streamlined approval pathway for minor species is accelerating novel therapeutic development and expanding addressable study volume for CROs with rodent and non-rodent capabilities.
- Monoclonal antibody pipelines:Biologics development for companion animals requires specialized toxicology and immunogenicity assessment, pulling sponsors toward CROs with biologic-specific method validation expertise.
- European regulatory harmonization:The EU's Veterinary Medicines Regulation (Regulation 2019/6) centralizes marketing authorizations, concentrating sponsor demand on CROs with EMA-aligned GLP certification.
Market Restraints
- Specialized vivarium scarcity:Purpose-built large animal housing for canine and feline toxicology studies concentrates in the United States and Germany, creating capacity bottlenecks during peak enrollment windows.
- Species-specific matrix validation:Bioanalytical method development for exotic companion species requires de novo validation cycles that extend study timelines beyond standard rodent programs.
- GLP inspectorate divergence:Misaligned OECD Test Guideline interpretations between FDA and EMA authorities force redundant study designs for multi-jurisdictional submissions.
Strategic Opportunities
- Japan's companion animal pharmaceutical market:PMDA's evolving guidance for pet therapeutics creates first-mover advantage for CROs establishing Tokyo-area GLP facilities with bilingual study reporting.
- Digital pathology integration:AI-enabled histopathology review is compressing toxicology report timelines and enabling real-time sponsor access to interim safety data.
- India's emerging sponsor base:Domestic animal health companies in Hyderabad and Bangalore are building internal development capabilities that require outsourced GLP execution partners.
Industry Challenges
- Veterinary pathologist recruitment:The specialized skill set combining diagnostic veterinary medicine with regulatory toxicology experience faces supply constraints across North America and Western Europe.
- Legacy data system integration:Sponsors operating on validated electronic data capture platforms encounter friction when interfacing with CROs using non-interoperable laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary CRO Market |
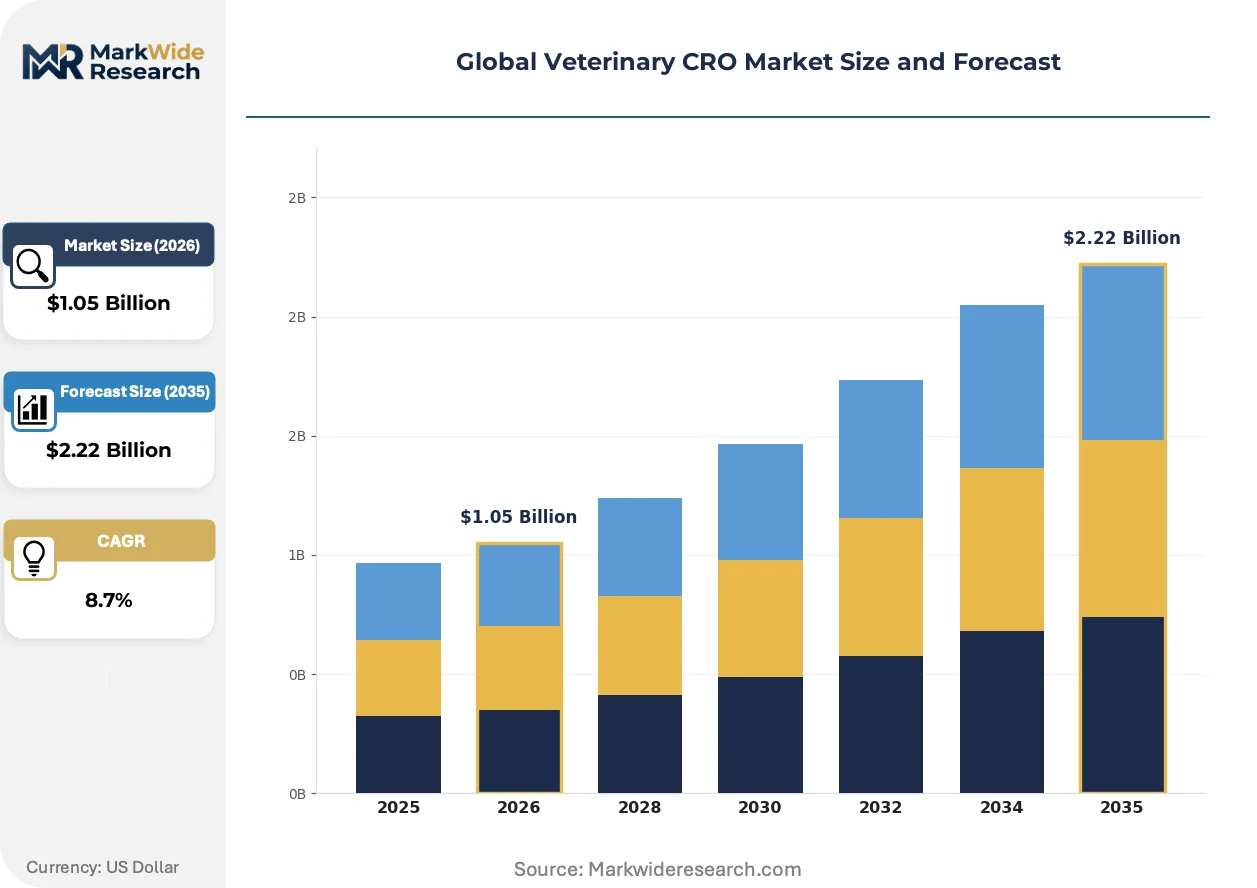
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.22 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Preclinical Research, Clinical Trials, Bioanalytical Services, Regulatory Consulting, Pharmacovigilance, Data Management Animal Species: Companion Animals, Livestock, Aquatic Animals, Equines, Laboratory Animals End User: Pharmaceutical Companies, Biotechnology Firms, Agricultural Producers, Contract Research Organizations, Academic Institutions Study Phase: Exploratory, Dose Optimization, Safety Assessment, Efficacy Evaluation, Post-Market Surveillance |
| Companies Covered | Charles River Laboratories, Labcorp Drug Development, Clinvet, KLIFOVET GmbH, IDEXX Laboratories, Envigo, Veterinary Research Management, VetPharm, Fortrea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary CRO Market Shifts & Advancements
Digital biomarker acquisition and real-time data streaming are reshaping how safety and efficacy endpoints are captured across veterinary development programs. These capabilities are compressing traditional study timelines while expanding the granularity of regulatory submission packages.
Implantable biosensors and wearable telemetry devices are electrifying physiological monitoring in canine and feline toxicology studies. Large pharmaceutical sponsors now specify continuous cardiovascular and activity telemetry as standard protocol elements. This technology is electrifying the competitive position of CROs with integrated device validation and data science capabilities.
The EU's Veterinary Medicines Regulation (Regulation 2019/6) mandates environmental risk assessment for all new veterinary medicinal products. This requirement is forcing sponsors to incorporate aquatic and terrestrial ecotoxicology modules earlier in development timelines. CROs with captive environmental toxicology divisions in the Netherlands and Germany are capturing disproportionate European sponsor volume.
Sponsor procurement teams are consolidating vendor panels and demanding outcome-based contracting with milestone-linked payment structures. This shift is displacing traditional time-and-materials arrangements in the clinical trials segment. The United States exhibits the fastest compression in vendor count, with top-ten animal health companies reducing active CRO relationships by half.
Global Veterinary CRO Market Segmentation
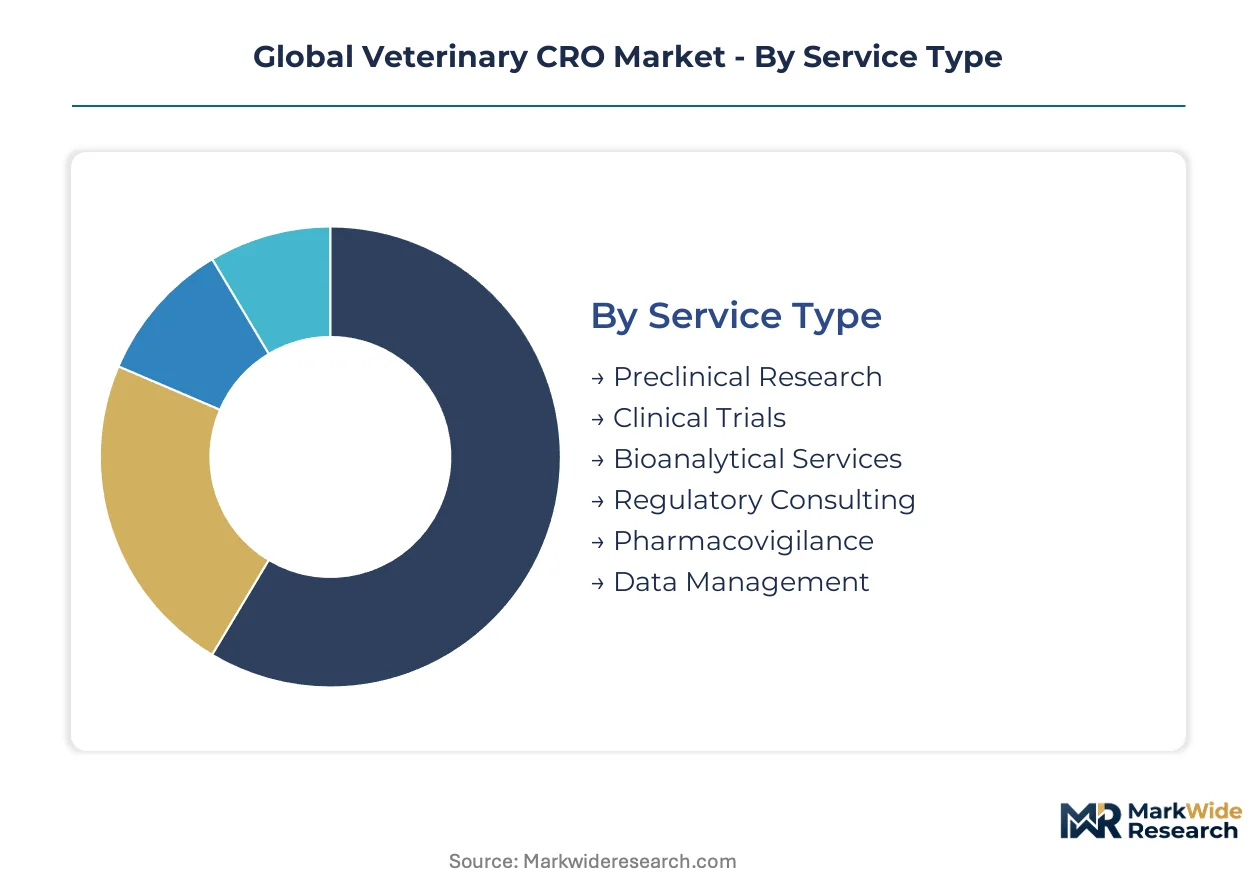
Veterinary CRO segmentation reveals how service specialization, species requirements, and study complexity create distinct procurement patterns. Sponsors configure vendor portfolios across these dimensions to match pipeline risk profiles and regulatory submission timelines.
Service Type:
Standardized protocols dominate toxicology and bioanalysis, while regulatory consulting demands bespoke engagement models shaped by jurisdiction-specific submission requirements.
- Preclinical Research:GLP-compliant toxicology, pharmacokinetics, and safety pharmacology studies generate the foundational data packages for FDA and EMA submissions. Demand concentrates in the United States where captive vivarium networks serve both domestic and European sponsor pipelines, driven by mandatory toxicology requirements for new molecular entities.
- Clinical Trials:Field efficacy and safety studies in target species under GCP conditions support label claims and dosing regimens. Sponsors in Germany and France are expanding companion animal biologics pipelines, pulling CRO investment toward European clinical operations capacity.
- Bioanalytical Services:Species-specific method validation and biomarker quantification underpin pharmacokinetic modeling.
- Regulatory Consulting:Strategic guidance on FDA Veterinary Innovation Program pathways and EMA centralized procedures.
- Pharmacovigilance:Post-authorization safety monitoring and adverse event reporting systems.
- Data Management:Electronic data capture, statistical analysis, and submission-ready documentation packages.
Leading the category by volume: Preclinical Research. Growing fastest: Clinical Trials.
Animal Species:
Companion animal studies command premium pricing due to specialized housing and endpoint expertise, while livestock programs emphasize throughput and agricultural field conditions.
- Companion Animals:Canine and feline toxicology and efficacy studies support the expanding small animal therapeutics sector. United States-based CROs with dedicated companion animal facilities capture disproportionate monoclonal antibody development programs from pharmaceutical sponsors.
- Livestock:Cattle, swine, and poultry studies address production animal health and food safety withdrawal periods. Demand from agricultural producers in Brazil and Argentina drives investment in Latin American field trial infrastructure.
- Aquatic Animals:Fish and shellfish studies for aquaculture therapeutics and environmental risk assessment.
- Equines:Performance and companion horse pharmaceutical development with specialized athletic monitoring protocols.
- Laboratory Animals:Rodent and non-rodent models for preliminary safety and pharmacology screening.
Companion Animals generates the highest revenue per study. Aquatic Animals is climbing the fastest on environmental risk assessment mandates.
End User:
Large pharmaceutical sponsors favor integrated CRO partnerships spanning multiple service categories, while biotechnology firms prioritize specialized capabilities in biologics development.
- Pharmaceutical Companies:Full-service outsourcing of development programs from IND-enabling through NADA submission. Top-tier animal health companies in the United States have reduced active CRO relationships by half, consolidating around vendors with cross-border GLP certification.
- Biotechnology Firms:Targeted engagement for novel modality validation and first-in-species studies. Emerging biotech clusters in the United Kingdom and Switzerland are driving demand for flexible, milestone-based contracting structures.
- Agricultural Producers:Field efficacy trials for generic and reformulated products.
- Contract Research Organizations:Subcontracting arrangements for capacity overflow and specialized expertise.
- Academic Institutions:Translational research and investigator-initiated studies with limited regulatory scope.
Pharmaceutical Companies anchor procurement volume. Biotechnology Firms are expanding most quickly as companion animal biologics pipelines mature.
Study Phase:
Early-phase studies emphasize speed and cost efficiency, while late-phase programs require rigorous documentation and regulatory interface capabilities.
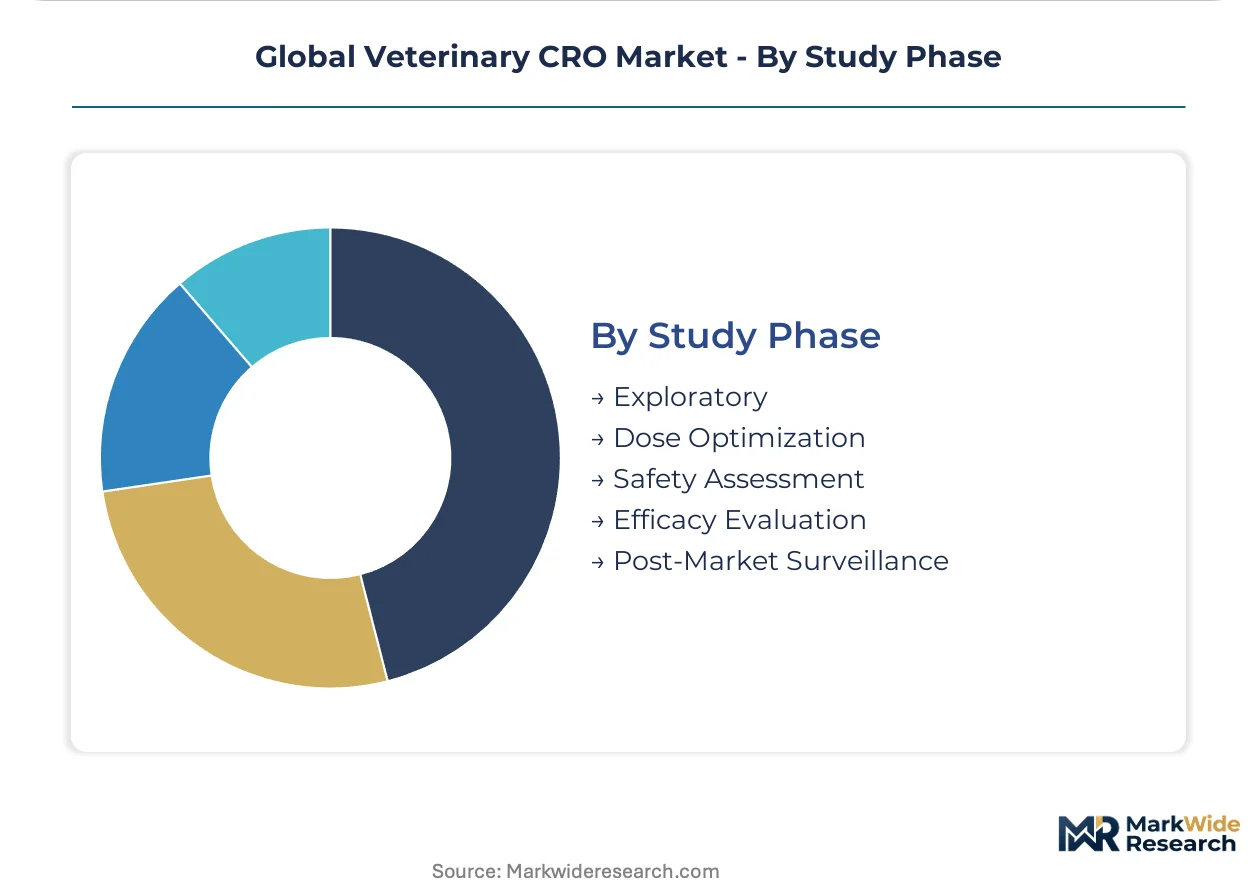
- Safety Assessment:Definitive toxicology and safety pharmacology studies under GLP conditions for regulatory submission. Sponsors conducting multi-jurisdictional filings face redundant study designs due to divergent OECD Test Guideline interpretations between FDA and EMA authorities.
- Efficacy Evaluation:Controlled clinical trials demonstrating therapeutic benefit in target species. Japanese pharmaceutical companies are expanding companion animal development, creating demand for Tokyo-area GLP facilities with bilingual reporting capabilities.
- Exploratory:Proof-of-concept and dose-ranging studies with reduced regulatory documentation requirements.
- Dose Optimization:Pharmacokinetic and pharmacodynamic modeling to establish dosing regimens.
- Post-Market Surveillance:Pharmacovigilance and field safety monitoring for authorized products.
Safety Assessment dominates study volume. Efficacy Evaluation shows the steepest expansion trajectory on biologics development growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates the dominant share of veterinary CRO demand, yet European sponsors increasingly route studies through German and British facilities to satisfy EMA centralized authorization requirements. This geographic split between consumption concentration and regulatory-aligned production capacity defines competitive positioning across the sector.
United States
Pharmaceutical sponsors concentrate monoclonal antibody development programs in Massachusetts and North Carolina research corridors. The FDA Veterinary Innovation Program accelerates minor species approvals, expanding addressable study volume for CROs with captive canine and feline vivarium networks. Boston-area facilities anchor multi-species toxicology execution for both domestic and European sponsor pipelines.
Germany
EMA-aligned GLP certification attracts sponsors seeking streamlined centralized marketing authorizations under Regulation 2019/6. The country's environmental risk assessment mandates for veterinary therapeutics pull aquatic ecotoxicology studies toward Lower Saxony and Bavaria. Munich-based CRO clusters specialize in companion animal biologics safety evaluation.
United Kingdom
Post-Brexit regulatory divergence forces sponsors to duplicate certain study elements for MHRA versus EMA submissions. Cambridge and Oxford biotech corridors drive demand for flexible, milestone-based contracting structures in early-phase development. British facilities retain strong positioning in equine and production animal field trial execution.
Japan
PMDA's evolving guidance for companion animal therapeutics creates first-mover opportunity for Tokyo-area GLP facilities. Domestic pharmaceutical companies expand pet therapeutics pipelines, requiring bilingual study reporting capabilities. Osaka-Kobe research clusters invest in biologic-specific immunogenicity assessment capacity.
India
Domestic animal health companies in Hyderabad and Bangalore build internal development capabilities requiring outsourced GLP execution partners. CDSCO's alignment with OECD Test Guidelines facilitates data acceptability for multi-jurisdictional submissions. Indian CROs compete on cost-efficient bioanalytical method validation for standard species matrices.
Global Veterinary CRO Market Competitive Landscape
The competitive structure tilts toward integrated service providers with cross-border GLP certification networks. Three tiers have crystallized: full-service organizations with captive vivarium infrastructure, specialized biologics boutiques with species-specific expertise, and regional execution partners competing on cost efficiency. Consolidation pressure intensifies as top-tier animal health sponsors reduce active vendor relationships by half, favoring partners with modular service bundling capabilities. Capacity expansion in companion animal housing and digital pathology integration represent the dominant competitive moves.
Within the integrated service tier, Charles River Laboratories and Labcorp Drug Development occupy anchor positions exemplifying captive infrastructure strategies. IDEXX Laboratories represents the specialized diagnostic-to-CRO connectivity archetype, particularly in clinical pathology segments that underpin FDA submission packages. These three organizations collectively illustrate how scale, species focus, and diagnostic integration define viable competitive positioning.
| Leading Market Players |
|---|
| Charles River Laboratories |
| Labcorp Drug Development |
| Clinvet |
| KLIFOVET GmbH |
| IDEXX Laboratories |
| Envigo |
| Veterinary Research Management |
| VetPharm |
| Fortrea |
| Others |
Supply & Pricing Matrix
Captive vivarium networks in the United States and Germany anchor both supply security and pricing power for veterinary CROs, as pharmaceutical sponsors consolidate vendor relationships around integrated preclinical-to-regulatory pathways rather than fragmented outsourcing arrangements. This vertical integration into specialized canine and feline housing infrastructure enables premium positioning for multi-species toxicology programs while compressing margins for regional execution partners lacking comparable asset bases.
Pricing Analysis
Margin tightening in clinical trials reflects sponsor procurement teams consolidating vendor panels and demanding milestone-linked payment structures that displace traditional time-and-materials arrangements. Three-tier pricing structure across premium, standard, and economy levels separates full-service integrated providers with cross-border GLP certification from specialized biologics boutiques and cost-competitive regional execution partners. Price differentiation rests on captive vivarium infrastructure and FDA Veterinary Innovation Program pathway expertise. Biotechnology firms exhibit highest price sensitivity due to limited development budgets, while top-ten animal health companies prioritize outcome-based contracting over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from top-tier pharmaceutical sponsors mandate CRO qualification across multiple geographies, concentrating supply relationships on organizations with parallel FDA and EMA-aligned GLP certification. Purpose-built large animal housing concentrates in the United States and Germany, with captive environmental toxicology divisions in the Netherlands serving EU environmental risk assessment mandates. Raw material dependencies span purpose-bred canine and feline colonies, GLP-grade reagents, and validated electronic data capture platforms. Single-source vulnerability in specialized veterinary pathologist talent pools across North America and Western Europe threatens study timeline execution. Distribution runs through direct sponsor-CRO contracting with limited intermediary involvement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital pathology integration and AI-enabled histopathology review are displacing legacy manual slide evaluation workflows, compressing toxicology report timelines while demanding new data science capabilities from CROs seeking competitive positioning.
For Market Incumbents: To counter sponsor vendor consolidation that has halved active CRO relationships among top-ten animal health companies, deepen captive vivarium networks in Massachusetts and North Carolina research corridors while accelerating digital pathology platform deployment. Capacity addition in Tokyo-area GLP facilities captures Japanese pharmaceutical expansion into companion animal therapeutics. Cross-border GLP certification investment sustains multi-jurisdictional submission competitiveness. For New Entrants and Emerging Players: Begin with India's emerging sponsor base in Hyderabad and Bangalore, where domestic animal health companies building internal development capabilities require outsourced GLP execution partners lacking established relationships. Biologic-specific immunogenicity assessment for monoclonal antibody pipelines represents the most penetrable service gap. Go-to-market positioning centers on flexible milestone-based contracting structures that accommodate biotechnology firm budget constraints. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated service providers seeking specialized biologics boutiques with species-specific expertise and regulatory consulting capabilities. Long-term viability favors CROs with demonstrated FDA Veterinary Innovation Program navigation and EMA centralized procedure alignment. Monitor PMDA guidance evolution for companion animal therapeutics as inflection indicator for Asia-Pacific capacity investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Pathology Platform Deployment | AI-enabled histopathology review compresses toxicology timelines for FDA submission packages. |
| Cross-Border GLP Certification Expansion | EMA-aligned certification captures sponsor demand under centralized Regulation 2019/6 authorization procedures. |
| Companion Animal Vivarium Capacity Addition | Canine and feline housing scarcity in peak enrollment windows commands premium pricing. |
| Biologic-Specific Method Validation Investment | Monoclonal antibody immunogenicity assessment expertise pulls pharmaceutical sponsor volume. |
| Environmental Toxicology Division Buildout | EU Veterinary Medicines Regulation mandates aquatic ecotoxicology for all new veterinary products. |
Research Methodology
Regulatory filings, trade association publications, and sponsor pipeline databases formed the secondary backbone, supplemented by primary interviews with veterinary drug development executives, regulatory affairs leads at animal health companies, CRO operations directors, and GLP facility managers. Bottom-up and top-down triangulation validated segment sizing across service type, animal species, and end user dimensions. Primary fieldwork captured procurement pattern shifts and vendor consolidation dynamics directly from sponsor decision-makers.
Bottom-up modeling aggregated individual CRO capacity and utilization rates across the United States, Germany, United Kingdom, Japan, and India, while top-down analysis cross-referenced pharmaceutical R&D expenditure allocation to veterinary therapeutics. Segmentation dimensions included service type, animal species, end user archetype, study phase, and regional regulatory cluster. CAGRs were derived from sponsor pipeline expansion rates and regulatory pathway acceleration effects. Forecast inputs incorporated FDA Veterinary Innovation Program enrollment trajectories and EMA centralized procedure application volumes.
Underlying measurement precision varies by segment; preclinical research and safety assessment carry tighter precision than exploratory study phases due to mandatory GLP documentation requirements. Forecasts reflect assumptions regarding regulatory pathway continuity and sponsor outsourcing propensity. Deviation in FDA-EMA OECD Test Guideline interpretation alignment would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare
Global Analytical Laboratory Services Market
Healthcare
Preimplantation Genetic Testing Market
Healthcare
Knee Arthrodesis Implant Market
Healthcare
Canada Aesthetic Devices Market
Healthcare
Global Pemphigus Vulgaris Market
Healthcare
Capnography Devices Market
Healthcare
Endoscopy Equipment and Software Market
Healthcare
Narcotic Analgesics Market
Healthcare
Implantable Port Devices Market
Healthcare
Anti-Rickettsial Treatment Market
Healthcare
Hearing Devices 3D Printing Market
Healthcare
Helicobacter Pylori Infections Treatment Market
Healthcare
Dental Implantology Software Market
Healthcare
Barbados Healthcare and Medical Tourism Market
Healthcare
Global Uveitis Treatment Market
Healthcare
Veterinary Biologics Market