
 Global Traditional Leather Market | 2026-2036
Global Traditional Leather Market Size, Share, and Industry Trends Forecast 2026-2036
Global Traditional Leather Market Foresight
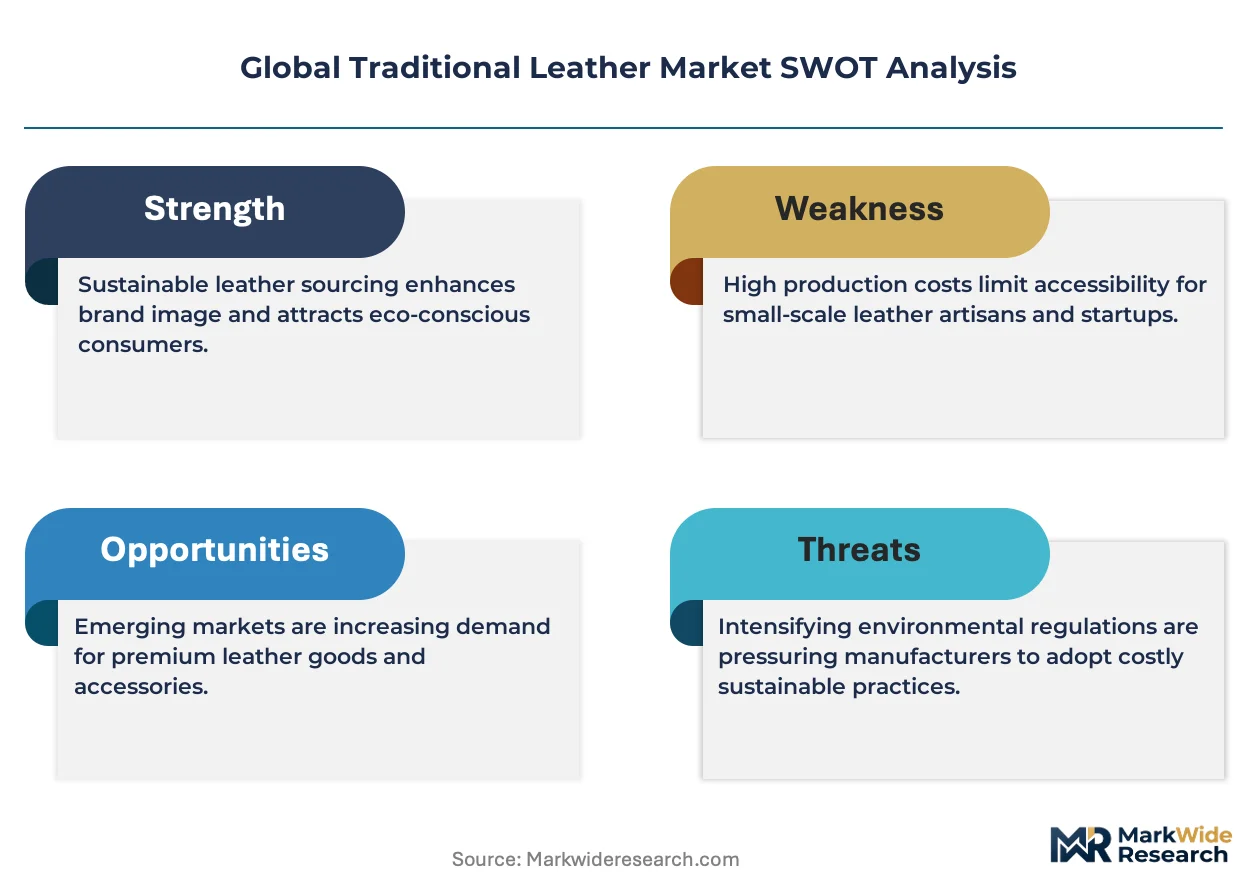
LWG (Leather Working Group) certification is rotating as the gatekeeper for supplier qualification among premium brands. Hermes International S.A. leverages vertical integration from tannery to finished goods, sustaining its position in full-grain leather goods. Kering S.A. anchors its sustainability narrative through certified sourcing protocols, while Nike Inc. competes by enforcing strict environmental standards across its leather supply chain.
Traditional leather comprises hides and skins processed through tanning to create durable, flexible material with tensile strength exceeding 20 MPa and natural breathability, serving primarily as a structural and aesthetic input for footwear, furniture, and automotive seating applications. Full-grain leather commands the highest margin pool due to its unaltered surface and durability premium, while chrome-tanned product dominates volume owing to faster processing cycles and lower unit costs. Vegetable-tanned leather is gaining share in fashion accessories where biodegradability and patina development justify longer lead times and higher price positioning.
REACH in Europe restricts hexavalent chromium discharge, ECHA monitors chemical inputs in tanning effluent, and India's CPCB enforces Common Effluent Treatment Plant mandates for tannery clusters in Kanpur and Kolkata. These frameworks elevate compliance costs for smaller operators while creating market access advantages for certified large-scale producers. Stakeholders must monitor regulatory divergence between jurisdictions where environmental standards tighten and regions where enforcement remains fragmented.
Market Dynamics
REACH compliance and chrome-tanning restrictions are compressing processing capacity in Europe while concentrating supply among certified large-scale tanneries. This regulatory pressure is decomposing the traditional fragmented supplier base and elevating vegetable-tanning alternatives.
Growth Catalysts
- Automotive seating demand:Premium vehicle manufacturers in Germany and Japan are expanding full-grain leather specifications for interior trim, pulling volume through Italian and French tanneries.
- REACH environmental mandates:ECHA monitoring of hexavalent chromium discharge is accelerating technology transfer toward cleaner tanning chemistry in European operations.
- Traceability protocols:LWG certification requirements from luxury footwear brands are filtering supplier qualification standards down through Tier-2 hide processors.
Market Restraints
- Raw hide cost volatility:Cattle supply fluctuations in Brazil and Argentina create input price instability for chromium-tanned bulk production.
- Processing concentration risk:Tamil Nadu and Uttar Pradesh clusters in India control disproportionate export volume, exposing buyers to single-region disruption.
- Biomaterial substitution:Mycelium-based leather alternatives from biotechnology suppliers are capturing share in fashion accessories where patina matters less than sustainability signaling.
Strategic Opportunities
- Underpenetrated Mexican supply:Hide processing infrastructure in León remains below capacity for North American automotive just-in-sequence delivery.
- Vegetable-tanning premiumization:Italian artisan tanneries are commanding price premiums for patina-developing leather in small-batch luxury goods.
- Digital hide traceability:Blockchain-enabled provenance tracking is opening direct-to-brand contracting for ranchers in Australia and New Zealand.
Industry Challenges
- Specialized tanning chemistry expertise:Vegetable-tanning mastery requires multi-year apprenticeship pipelines that collapsed during chrome-tanning dominance.
- Effluent treatment capex:Common Effluent Treatment Plant mandates from India's CPCB demand capital deployment that smaller Kanpur operators cannot finance.
- LWG certification timelines:Audit backlogs are extending supplier qualification cycles beyond brand launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Traditional Leather Market |
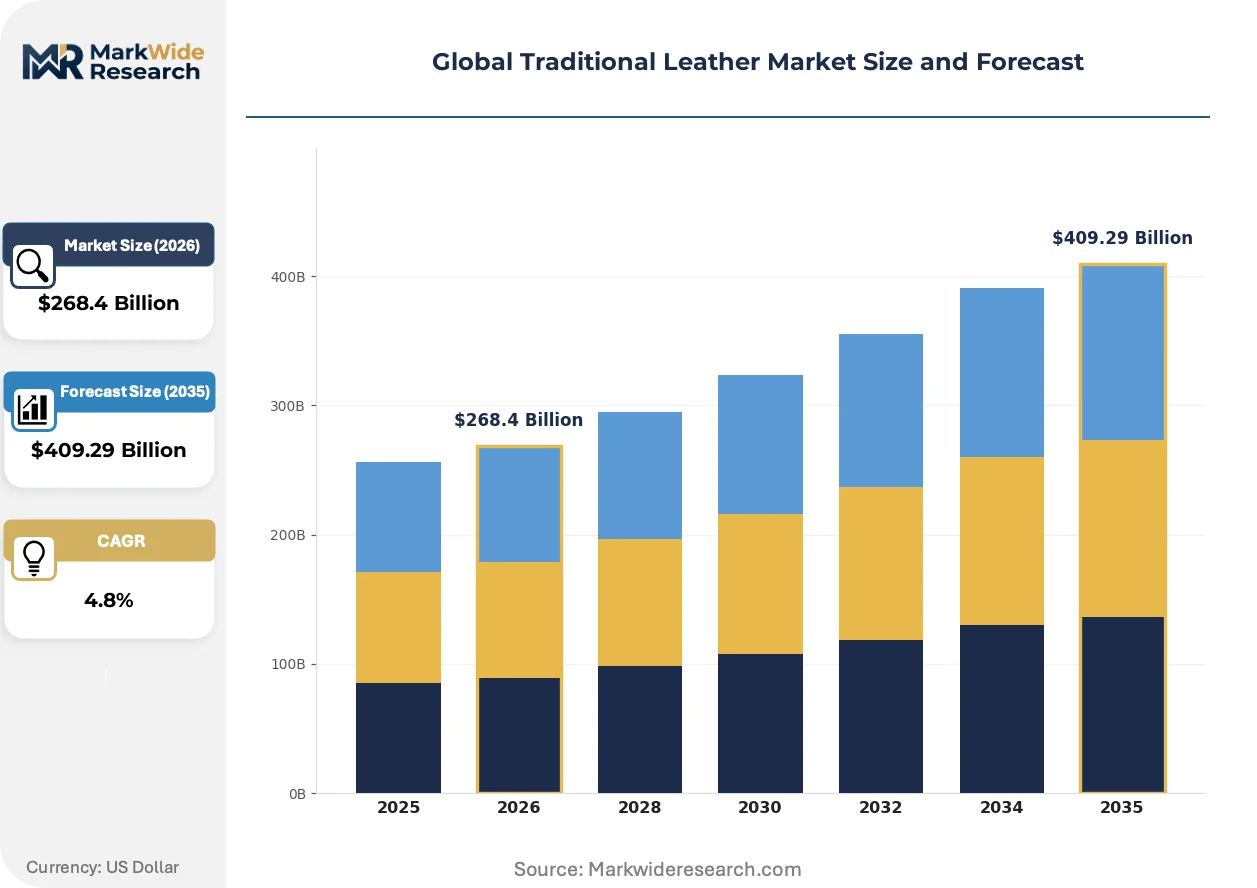
| Market Size in 2026 | $268.4 Billion |
| Market Size in 2035 | $409.29 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Leather Type: Full-Grain, Top-Grain, Corrected-Grain, Split, Nubuck End Use Industry: Footwear, Furniture, Fashion Accessories, Automotive Interiors, Sporting Goods Tanning Process: Chrome Tanning, Vegetable Tanning, Aldehyde Tanning, Brain Tanning, Alum Tanning Product Form: Rolls, Sheets, Cut Pieces, Blocks, Scrap |
| Companies Covered | LVMH Moet Hennessy Louis Vuitton SE, Kering S.A., Hermes International S.A., Capri Holdings Limited, Prada SpA, Samsonite International S.A., Adidas AG, Nike Inc., Burberry Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Traditional Leather Market Shifts & Advancements
Biotechnology and digital traceability are decomposing the traditional opacity of hide sourcing while regulatory chemistry restrictions force process reinvention. These forces are compressing the viable supplier base toward certified operators with capital for compliance.
Precision fermentation for collagen scaffolding is decomposing the conventional hide-to-leather production chain. Biotechnology firms in California and the Netherlands are cultivating cell-derived leather matrices that bypass tanning entirely. Luxury fashion houses are piloting these materials for accessories where grain consistency and batch reproducibility outweigh natural variation premiums.
ECHA's expanded REACH enforcement on chromium VI discharge limits is forcing tannery retrofit investments across Italy, Spain, and Portugal. Facilities without on-site effluent recovery face operational suspension. Vegetable-tanning specialists in Tuscany are absorbing displaced chrome-tanning volume by extending lead times and elevating pricing.
Brand-led procurement is consolidating toward direct ranch partnerships with DNA-verified hide traceability. Premium footwear manufacturers are bypassing commodity hide traders to contract specific cattle breeds from designated Australian stations. This disintermediation compresses margin extraction from traditional leather merchants while transferring quality risk to brand balance sheets.
Global Traditional Leather Market Segmentation
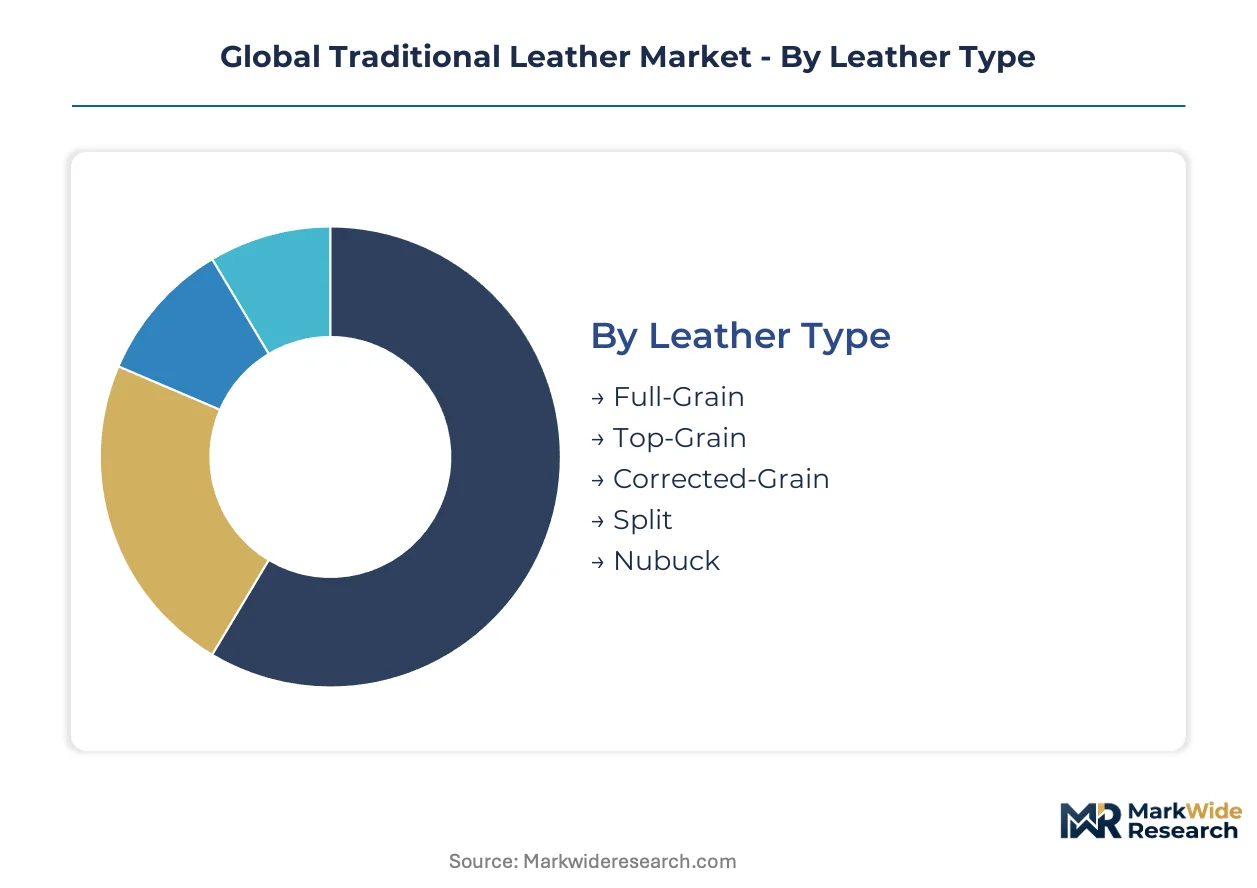
Segmentation in traditional leather reveals how processing chemistry, grain integrity, and end-use specifications channel value capture across disparate buyer ecosystems. Each dimension carries distinct margin profiles and regulatory exposure that reshape supplier qualification requirements.
Leather Type:
Distribution channels bifurcate sharply by leather type, with full-grain commanding direct-to-brand contracts while corrected-grain flows through wholesale merchants to mass-market manufacturers.
- Full-Grain:Unaltered surface retains complete fiber structure with tensile strength exceeding 20 MPa. Hermes and premium Italian footwear houses concentrate procurement here, paying durability premiums for heritage patina development. REACH compliance costs filter smaller tanneries from this tier.
- Top-Grain:Sanded surface removes imperfections while preserving structural integrity. Automotive seating specifications in Germany and Japan pull volume through certified Italian tanneries, with LWG certification now mandatory for supplier qualification.
- Corrected-Grain:Embossed surface patterns simulate uniform grain; Brazilian bulk processors dominate this price-sensitive segment.
- Split:Fibrous inner layer separated from top-grain; suede production in India and Bangladesh consumes this input.
- Nubuck:Sanded outer surface creates velvety nap; luxury sneaker brands in Italy specify this for limited-edition releases.
By volume, corrected-grain leads. By growth pace, full-grain is expanding most quickly.
End Use Industry:
Margin tiers separate dramatically by end use, with automotive and luxury fashion accessories capturing value multiples over commodity footwear and furniture applications.
- Footwear:Largest consumption segment spanning mass-market sneakers to bespoke dress shoes. Nike's environmental standards and LWG mandates filter supplier pools, while artisan producers in Italy's Marche region command 40-60 week lead times for hand-finished full-grain.
- Furniture:Upholstery demand concentrates in Italian design houses and North American contract manufacturers. Vegetable-tanned leather is gaining specification share where biodegradability aligns with corporate sustainability reporting.
- Fashion Accessories:Handbags and small leather goods generate highest per-square-meter margins; Kering's certified sourcing protocols dominate procurement here.
- Automotive Interiors:German and Japanese OEMs specify full-grain for flagship models, with just-in-sequence delivery requirements compressing supplier geography.
- Sporting Goods:Gloves and equipment use predominantly chrome-tanned splits; cost pressure from synthetic alternatives constrains pricing power.
Footwear absorbs the greatest raw hide volume. Fashion accessories deliver the steepest expansion trajectory.
Tanning Process:
Regulatory geography determines tanning process viability, with European REACH enforcement accelerating chemistry transitions that Asian clusters have not yet replicated.
- Chrome Tanning:Chromium sulfate processing dominates global volume with 24-48 hour cycles. ECHA's hexavalent chromium discharge limits are forcing retrofit investments across Italy, Spain, and Portugal; facilities lacking effluent recovery face suspension.
- Vegetable Tanning:Tannin extraction from tree bark requires 30-60 day processing. Tuscan artisan tanneries are absorbing displaced chrome volume, extending lead times and elevating pricing for patina-developing leather in small-batch luxury goods.
- Aldehyde Tanning:Formaldehyde-based chemistry produces washable leather for specific medical and infant applications.
- Brain Tanning:Traditional indigenous method using emulsified animal brains; negligible commercial scale, preserved for cultural heritage production.
- Alum Tanning:Aluminum salt processing creates lightweight, white leather for bookbinding and glove applications; limited modern commercial relevance.
Chrome tanning retains volume leadership. Vegetable tanning is climbing the fastest amid regulatory chemistry displacement.
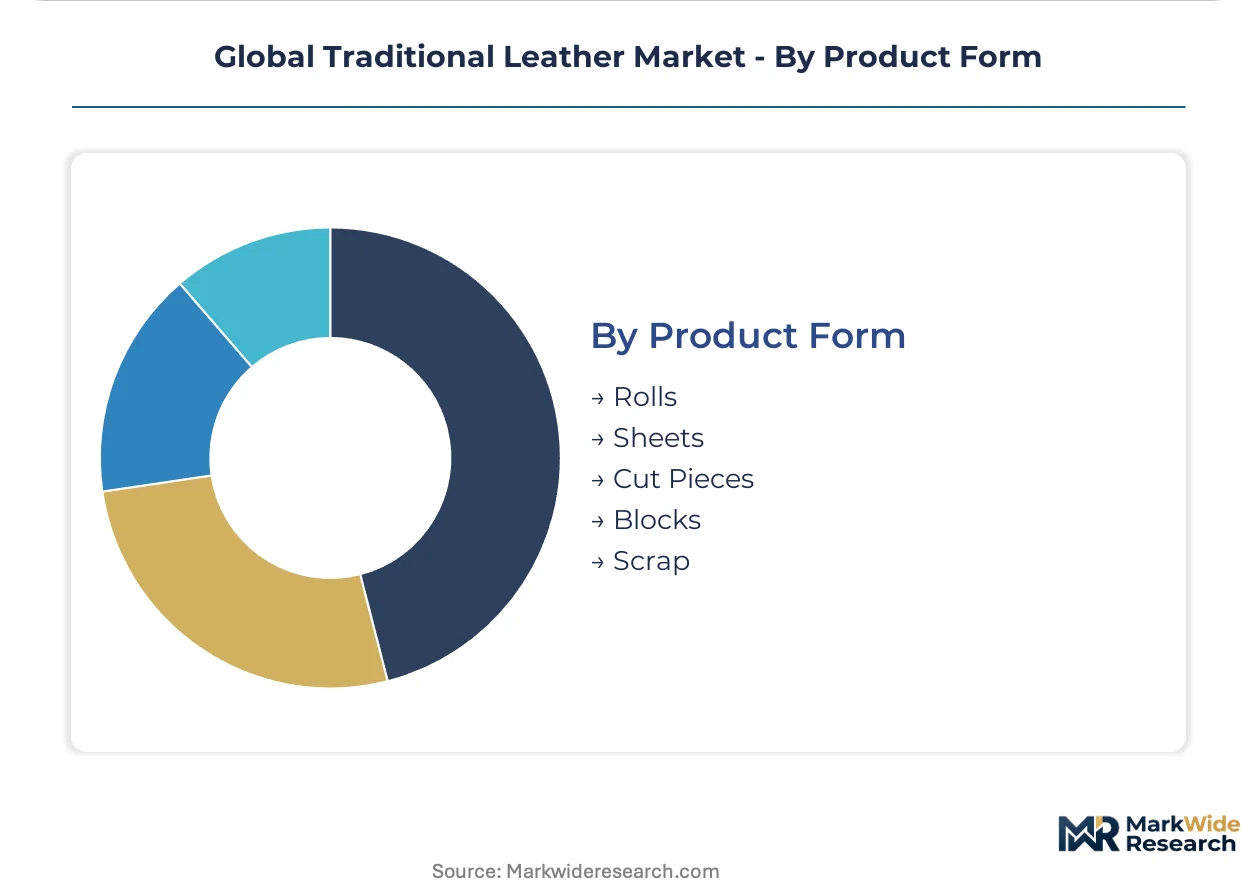
Product Form:
Supply chain configuration by product form reflects customer scale and cutting capability, with rolls serving industrial manufacturers and cut pieces enabling artisan production.
- Rolls:Continuous material for automated cutting systems in automotive and large footwear factories; Kanpur and Tamil Nadu clusters specialize in bulk roll export.
- Sheets:Standardized dimensions for furniture upholstery and mid-scale accessories production.
- Cut Pieces:Pre-dimensioned for specific patterns; Italian artisan workshops and small-batch manufacturers prefer this form to minimize waste.
- Blocks:Compressed material for industrial applications including polishing wheels and gaskets.
- Scrap:Remnant material for bonded leather production and composite applications; price-sensitive segment with minimal margin.
Rolls dominate volume throughput. Cut pieces are gaining share fastest among premium brands seeking waste reduction and artisan alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH enforcement across Europe and India's PLI scheme for manufacturing are redirecting capital toward compliant tanneries and export-oriented clusters. These policy frameworks are compressing regional supply bases while elevating certified operators.
Italy
Luxury footwear brands in Tuscany and Veneto are expanding full-grain leather specifications for heritage patina development. ECHA's hexavalent chromium discharge limits under REACH are forcing retrofit investments across tanneries in Santa Croce sull'Arno. Vegetable-tanning specialists in the Tuscan Leather District are absorbing displaced chrome-tanning volume and extending lead times.
India
Export-oriented automotive and furniture manufacturers are pulling volume through Tamil Nadu and Uttar Pradesh leather clusters. The CPCB enforces Common Effluent Treatment Plant mandates for tanneries in Kanpur and Kolkata, elevating compliance costs for smaller operators. Tamil Nadu's Ambur and Vaniyambadi clusters are consolidating supply for German and Japanese OEM seating programs.
France
Luxury fashion houses are contracting direct ranch partnerships for traceable hide sourcing. REACH compliance requirements filter supplier qualification toward LWG-certified tanneries. The Normandy and Limousin cattle regions are developing blockchain-enabled provenance tracking for premium brand procurement.
United States
Automotive seating demand from Detroit and Southern OEMs is pulling volume through North American hide processors. EPA effluent standards constrain chromium-tanning operations without on-site recovery systems. Texas and Kansas ranching operations are piloting DNA-verified hide traceability for direct-to-brand contracting.
Brazil
Raw hide supply fluctuations from São Paulo and Mato Grosso cattle operations create input price instability for bulk chromium-tanned production. The national environmental regulator monitors tanning effluent discharge from clusters in Franca and Jaú. São Paulo state tanneries are diversifying toward vegetable-tanning alternatives for European export compliance.
Global Traditional Leather Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, creating a bifurcated structure where scale-driven conglomerates anchor volume while artisan houses capture margin premiums. The vendor base separates into three archetypes: vertically integrated luxury houses controlling tannery-to-retail chains, brand-led manufacturers enforcing strict environmental standards across supplier networks, and regional bulk processors serving price-sensitive automotive and furniture contracts. Dominant competitive moves include backward integration into hide sourcing and geographic expansion into underpenetrated Mexican and Southeast Asian supply corridors.
Among French-listed luxury conglomerates, LVMH Moet Hennessy Louis Vuitton SE and Kering S.A. exemplify the vertically integrated archetype, anchoring premium-tier positioning through controlled tannery operations and certified sourcing protocols. Hermes International S.A. occupies a distinct position within this tier, representing the extreme case of captive supply chains from ranch partnerships through finished goods. These three entities sit within a competitive set where sustainability signaling and traceability infrastructure determine supplier qualification access.
| Leading Market Players |
|---|
| LVMH Moet Hennessy Louis Vuitton SE |
| Kering S.A. |
| Hermes International S.A. |
| Capri Holdings Limited |
| Prada SpA |
| Samsonite International S.A. |
| Adidas AG |
| Nike Inc. |
| Burberry Group plc |
| Others |
Supply & Pricing Matrix
Capacity utilization at Italian vegetable-tanning tanneries in Tuscany shapes both regional supply concentration and price floors for full-grain leather. These scale economies compress margin extraction from smaller operators while elevating certified producers into direct-to-brand contracting positions.
Pricing Analysis
LWG certification level creates the primary spread between premium full-grain and commodity corrected-grain leather. Three-tier pricing structure across certified artisan, standard commercial, and bulk economy levels dominates procurement contracts. Cost compression in chrome-tanned segments is intensifying because REACH retrofit investments are elevating fixed costs for non-compliant operators. Mass-market footwear manufacturers exhibit highest price sensitivity, while luxury fashion houses absorb premiums for traceable hide provenance.
Supply Chain Analysis
Italy and India anchor global leather processing, with Tuscan artisan tanneries supplying heritage patina leather and Tamil Nadu clusters feeding automotive seating programs. Raw material flows draw from Brazilian cattle ranches for chromium-tanned bulk production and Australian stations for DNA-verified full-grain hides. Single-region concentration in Uttar Pradesh exposes buyers to disruption from monsoon flooding or regulatory enforcement actions. Distribution runs through certified merchant houses for commodity grades and direct ranch partnerships for premium traceable supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase driven by automotive seating program restarts following supply chain normalization. Premium vehicle interior specifications are pulling volume through certified tanneries faster than replacement capacity can enter.
For Market Incumbents: Secure backward integration into Australian and New Zealand ranch partnerships to lock DNA-verified hide supply before competitors establish direct contracting. Expand vegetable-tanning capacity in Tuscany to absorb displaced chrome-tanning volume from REACH enforcement. Mycelium-based leather alternatives from biotechnology suppliers threaten fashion accessory margins.
For New Entrants and Emerging Players: Differentiate on blockchain-enabled hide traceability for mid-tier footwear brands seeking sustainability signaling without artisan pricing. Target underpenetrated Mexican processing infrastructure in León for North American automotive just-in-sequence delivery. Lead with LWG certification as a qualification wedge against established uncertified competitors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated luxury houses with captive tannery operations and multi-year brand contracts. Long-term viability over the next decade hinges on regulatory chemistry adaptation rather than commodity scale. Monitor ECHA enforcement intensity as the primary inflection signal for accelerated industry consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hide Sourcing | DNA-verified ranch partnerships in Australia transfer quality risk to brand balance sheets. |
| Vegetable-Tanning Capacity Expansion | Tuscan artisan tanneries absorb displaced chrome volume amid REACH chemistry restrictions. |
| LWG Certification Investment | Audit completion opens supplier qualification access for premium footwear brand contracts. |
| Blockchain Traceability Deployment | Digital provenance tracking enables direct-to-brand contracting for Normandy cattle stations. |
| Geographic Expansion into Mexico | León processing infrastructure addresses North American automotive just-in-sequence delivery gaps. |
Research Methodology
Cross-validation between primary interviews with tannery operations directors, luxury brand procurement heads, and automotive Tier 1 supplier quality managers anchors the qualitative findings. Secondary validation draws from ECHA REACH enforcement records, Italian tannery association production surveys, Indian CPCB effluent compliance filings, and customs trade data for hide and finished leather movements. Bottom-up capacity assessments at cluster level triangulate against top-down demand modeling from end-use industries.
Sensitivity analysis across chrome-tanning regulatory scenarios and raw hide price volatility bands stress-tests volume and value outputs over the projection horizon. Segmentation dimensions span leather type, tanning chemistry, end-use industry, and geographic production hub. CAGRs derive from installed capacity trajectories, regulatory-driven chemistry transition timelines, and brand-led procurement consolidation patterns. Forecast inputs include automotive seating specification shifts and biotechnology substitution rates in fashion accessories.
Material uncertainties — regulatory enforcement divergence between European REACH jurisdictions and emerging market clusters, cattle supply fluctuations from Brazilian ranching operations, and mycelium-based leather technology maturation — sit outside the modeled envelope. Forecasts reflect assumptions about certification adoption timelines and chemistry transition capex deployment. Recalibration cycles align with material shifts in ECHA enforcement intensity and automotive OEM seating program awards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Fishing Tackle Box Market
Consumer Goods
Sweden Cosmetics Products Market
Consumer Goods
Electric Hobs Market
Consumer Goods
Ankle Boots Market
Consumer Goods
Pet Travel Bags Market
Consumer Goods
Temporary Tattoo Market
Consumer Goods
Riding Multi-Purpose Lawn Mower Market
Consumer Goods
Household Vacuum Cleaners Market
Consumer Goods
Asia Pacific Water Heater Market
Consumer Goods
North America Refurbished and Used Mobile Phones Market
Consumer Goods
Cat Cage Market
Consumer Goods
Baby Bath and Shower Products Market
Consumer Goods
Asia-Pacific Washing Machine Market
Consumer Goods
Wet Shave Market
Consumer Goods
Pet Pee Pads Market
Consumer Goods
Bottle Openers Market