
 Global Property Restoration Software Market | 2026-2036
Global Property Restoration Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Property Restoration Software Market Foresight
Enterprise-grade API interoperability is bifurcating the competitive landscape between modular best-of-breed stacks and unified suites. Xactware Solutions leverages its decades-long dominance in insurance carrier integrations to anchor the estimation tier. Encircle differentiates through mobile-native field documentation that restoration contractors adopt for real-time moisture and damage capture.
Property restoration software encompasses cloud-deployed and on-premises platforms that automate project workflows, claims documentation, and moisture tracking for disaster recovery contractors. These systems typically integrate thermal imaging data, humidity sensor feeds, and third-party payment APIs to compress cycle times from initial loss notice to final invoice. Cloud-based deployment leads in new customer acquisition due to lower upfront capital requirements and automatic regulatory update delivery, while project management modules capture disproportionate attention as contractors seek to coordinate multi-trade crews across simultaneous jobs. Claims processing solutions are gaining share fastest among insurance adjusters who demand straight-through processing from field inspection to reserve setting.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements on European restoration platforms processing automated damage assessments. In the United States, state-level contractor licensing boards and the EPA's Lead Renovation, Repair and Painting Rule shape documentation standards that software vendors must embed. Stakeholders should monitor how evolving building codes and climate resilience mandates in flood-prone jurisdictions will redefine mandatory reporting fields and certification workflows.
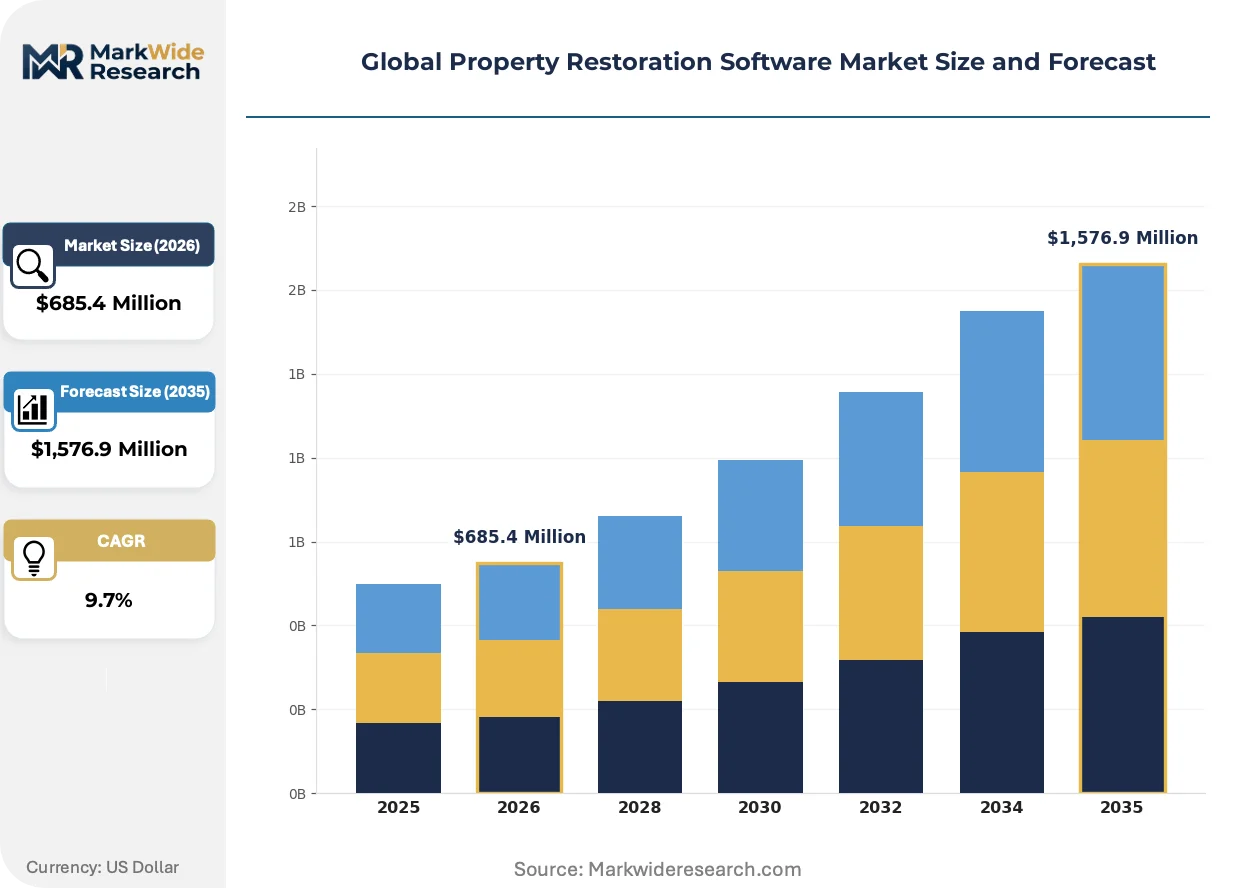
Market Dynamics
Insurance carriers are consolidating vendor relationships around platforms that deliver straight-through processing from field inspection to reserve setting, compressing procurement cycles and marginalizing point solutions lacking carrier-grade API certification.
Growth Catalysts
- EU Green Deal building retrofit mandates:Member states now require energy efficiency documentation for restoration work, forcing contractors to adopt platforms with embedded compliance workflows.
- Thermal imaging sensor cost curves:Hardware miniaturization has dropped entry-level thermal camera prices below $500, enabling field crews to capture moisture intrusion data without specialist dispatch.
- Hurricane corridor contractor density:Florida, Texas, and Louisiana restoration firms face simultaneous job volumes that demand crew coordination software for multi-trade scheduling.
Market Restraints
- Cloud data residency requirements:GDPR and EU AI Act provisions restrict where automated damage assessment algorithms can process imagery, fragmenting vendor infrastructure strategies.
- Legacy system integration debt:Established contractors operate on decade-old on-premises databases that resist API connections without expensive middleware layers.
- Specialized technician scarcity:Certified water damage restoration technicians command wage premiums that compress software budget allocations for mid-sized firms.
Strategic Opportunities
- India disaster resilience programs:The country's National Disaster Management Authority is digitizing building damage assessment protocols, creating first-mover openings for workflow automation vendors.
- IoT humidity sensor convergence:Real-time moisture monitoring hardware is integrating directly with job management dashboards, enabling predictive drying cycle optimization.
- Canada federal climate adaptation fund:Infrastructure grants for flood-prone municipalities include digitization requirements that subsidize contractor software procurement.
Industry Challenges
- Multi-jurisdiction licensing complexity:Contractors operating across state lines face divergent documentation standards that software must map without manual reconfiguration.
- Interoperability certification timelines:Carrier API accreditation processes extend 12-18 months, delaying revenue recognition for platform vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Property Restoration Software Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,576.9 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Solution: Project Management, Claims Processing, Estimation Tools, Customer Relationship Management, Reporting & Analytics Application: Water Damage, Fire Damage, Mold Remediation, Storm Damage, Disaster Recovery End User: Restoration Contractors, Insurance Adjusters, Facility Managers, Property Inspectors |
| Companies Covered | Xactware Solutions, Encircle, CoreLogic, Next Gear Solutions, Job-Dox, Jonas, LuxorCRM, Moisture Mapper, iRestore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Property Restoration Software Market Shifts & Advancements
Edge computing architectures are redistributing data processing from centralized clouds to job sites, enabling real-time moisture analysis without connectivity dependencies that plague disaster zones.
Portable thermal imaging hardware is miniaturizing to smartphone-attachable form factors, dropping unit costs below $400 and putting moisture detection capabilities in every field technician's pocket. Restoration contractors in hurricane-prone U.S. states are adopting these devices at 40% annual replacement rates for dedicated thermal cameras. The technology is miniaturizing damage documentation workflows from specialist-dependent procedures to standard crew capabilities.
EPA Lead Renovation, Repair and Painting Rule enforcement intensification is mandating dust containment documentation that legacy paper systems cannot satisfy. Software vendors are embedding EPA-compliant photo geotagging and timestamp verification into standard field capture modules. Contractors in pre-1978 housing stock corridors face the steepest compliance penalties, driving fastest adoption in New England and Midwest urban markets.
Carrier direct-bill arrangements are displacing traditional contractor-invoice workflows as adjusters demand real-time reserve visibility. Third-party administrators are consolidating payment authority, forcing restoration firms to adopt platforms with embedded claims status tracking. The shift is most visible in Texas and Florida, where hurricane volume has concentrated carrier procurement power among the largest property insurers.
Global Property Restoration Software Market Segmentation
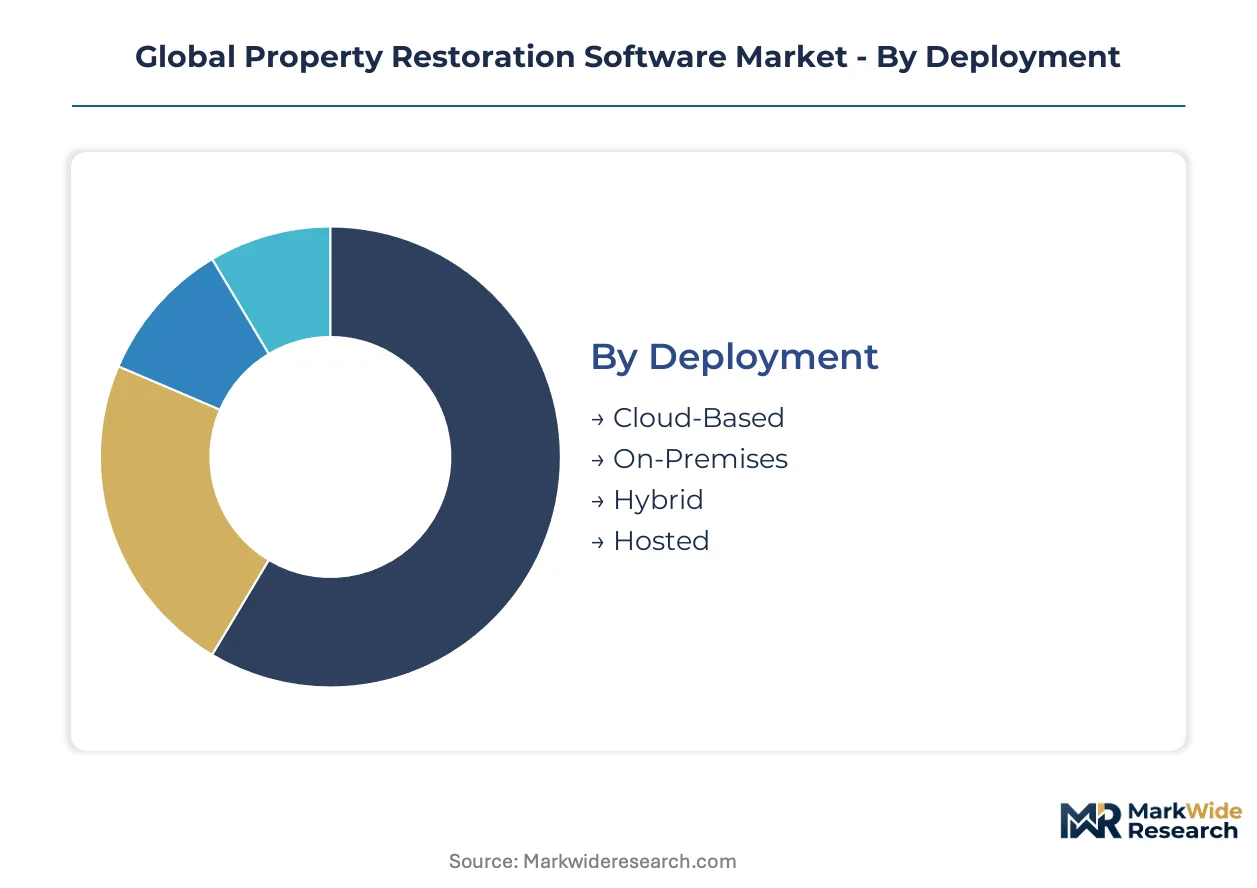
Segmentation in property restoration software determines how vendors allocate engineering resources and which channel partnerships yield recurring revenue. Contractors processing hurricane volume in Florida demand different feature bundles than European adjusters navigating GDPR documentation mandates.
Deployment:
Cloud-based platforms flow through insurance carrier procurement channels, while on-premises licenses anchor direct sales to security-conscious enterprise contractors.
- Cloud-Based:Multi-tenant architectures with automatic regulatory patch delivery dominate new customer acquisition. United States carriers in hurricane corridors prioritize these platforms for straight-through claims processing from field inspection to reserve setting.
- On-Premises:Single-tenant installations with local data sovereignty satisfy GDPR and EU AI Act residency requirements for European adjusters processing automated damage assessments. German and French contractors face the steepest compliance penalties for cloud data transfer violations.
- Hybrid:Split architectures keep sensitive customer data on-site while routing thermal imagery to cloud analytics engines. Mid-sized restoration firms in Canada leverage this configuration to qualify for federal climate adaptation digitization grants.
- Hosted:Vendor-managed private clouds with dedicated infrastructure appeal to contractors lacking internal IT capacity. India's National Disaster Management Authority procurement specifications favor this model for building damage assessment digitization.
By volume, Cloud-Based leads. By growth pace, Hybrid is climbing the fastest as jurisdictional data rules fragment.
Solution:
Cost tier differentiation separates enterprise-grade integrated suites from modular point solutions targeting specific workflow bottlenecks.
- Project Management:Crew scheduling and multi-trade coordination modules compress cycle times for simultaneous job volumes. Florida and Texas contractors facing hurricane season demand spikes adopt these tools at the highest replacement rates for legacy spreadsheets.
- Claims Processing:Straight-through automation from field documentation to carrier reserve setting marginalizes manual invoice workflows. Insurance adjusters in the United States consolidate procurement around platforms with real-time status visibility.
- Estimation Tools:Xactimate-compatible calculation engines with embedded pricing databases. Contractors in pre-1978 housing corridors use these for EPA Lead Renovation, Repair and Painting Rule compliance documentation.
- Customer Relationship Management:Policyholder communication portals with automated milestone updates. Mid-sized restoration firms deploy these to differentiate service levels in competitive Texas and Florida markets.
- Reporting & Analytics:Moisture trend dashboards and drying cycle optimization algorithms. European contractors under EU Green Deal retrofit mandates embed these for energy efficiency documentation workflows.
Project Management captures the largest installed base. Claims Processing is gaining share fastest among carrier-direct procurement channels.
Application:
Geography determines which damage types concentrate demand, with coastal and flood-prone jurisdictions driving disproportionate software spending.
- Water Damage:Moisture mapping and psychrometric calculation tools with thermal imaging integration. Louisiana and Florida contractors process the highest claim volumes, driving 40% annual replacement rates for smartphone-attachable detection hardware.
- Fire Damage:Smoke residue documentation and structural integrity assessment workflows. California contractors facing wildfire seasonality adopt these platforms for multi-jurisdiction licensing compliance across county lines.
- Mold Remediation:Spore count logging and containment verification with EPA-compliant photo geotagging. New England and Midwest urban markets with pre-1978 housing stock show steepest adoption curves.
- Storm Damage:Rapid deployment protocols for catastrophic event response coordination. Texas adjusters leverage these for real-time crew dispatch across hail and tornado corridors.
- Disaster Recovery:Federal emergency response integration and FEMA documentation compliance. Indian contractors participating in National Disaster Management Authority digitization programs represent emerging demand concentration.
Water Damage leads by revenue concentration. Disaster Recovery shows the steepest expansion trajectory as climate resilience programs scale in Asia-Pacific.
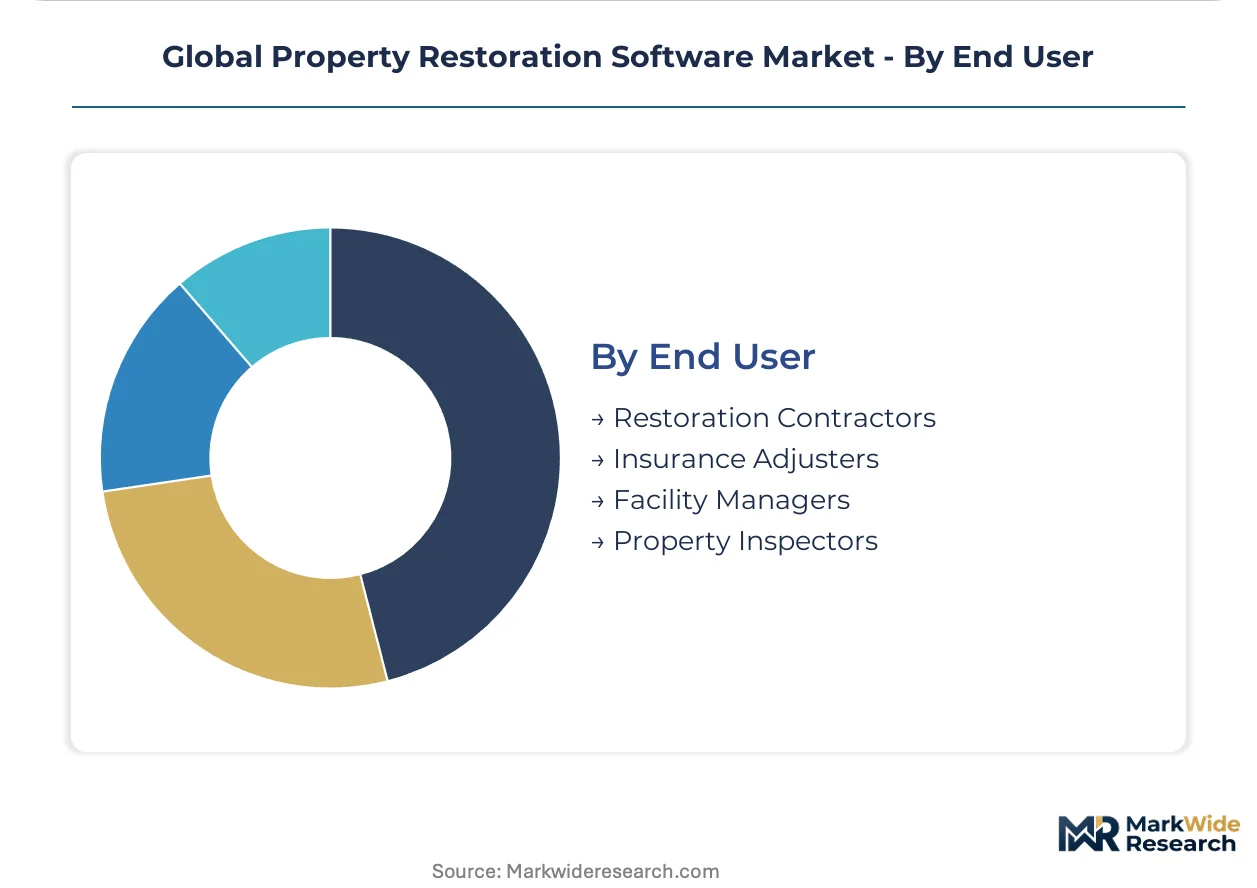
End User:
Customer type segmentation maps to divergent procurement authority and technical sophistication requirements.
- Restoration Contractors:Field-native mobile interfaces with offline capability for disaster zone connectivity gaps. Hurricane corridor firms in the United States prioritize crew coordination features for multi-trade scheduling.
- Insurance Adjusters:Carrier-certified API integrations with straight-through processing to reserve systems. Third-party administrators in Texas and Florida consolidate payment authority around these platforms.
- Facility Managers:Preventive maintenance modules with IoT humidity sensor convergence for predictive drying cycle optimization. Commercial property portfolios in flood-prone Canadian municipalities leverage federal adaptation grants for procurement.
- Property Inspectors:Lightweight documentation tools with timestamp verification and geotagging for litigation defense. Independent operators across multiple United States state licensing jurisdictions demand multi-standard template libraries.
Restoration Contractors represent the largest addressable base. Insurance Adjusters are expanding most quickly as carrier direct-bill arrangements displace traditional invoice workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software vendors export cloud-based claims platforms from the United States while importing compliance adaptations for EU data residency mandates. Trade in restoration technology flows asymmetrically: American carriers drive platform innovation, European regulators shape documentation standards, and Asian disaster programs create new demand corridors.
United States
Hurricane frequency in Florida and Texas sustains contractor software spending at levels unmatched elsewhere. The EPA's Lead Renovation, Repair and Painting Rule mandates dust containment documentation that paper systems cannot satisfy. Restoration firms in Miami-Dade and Houston deploy crew coordination platforms to manage simultaneous job volumes across multi-trade teams.
Germany
GDPR and EU AI Act provisions restrict where automated damage assessment algorithms process thermal imagery. German contractors face steep compliance penalties for cloud data transfer violations, driving demand for on-premises single-tenant installations. The Rhine-Ruhr metropolitan cluster hosts restoration firms adopting hybrid architectures to satisfy federal data sovereignty requirements.
Canada
Federal climate adaptation infrastructure grants for flood-prone municipalities subsidize contractor software procurement. Health Canada and PMRA documentation standards shape moisture tracking workflows for mold remediation projects. Restoration contractors in Ontario and British Columbia leverage these digitization subsidies to replace legacy spreadsheet systems.
India
The National Disaster Management Authority is digitizing building damage assessment protocols, creating first-mover openings for workflow automation vendors. BIS standards and central government digitization mandates accelerate platform adoption. Mumbai and Delhi restoration firms participate in federal programs requiring vendor-managed private cloud configurations.
United Kingdom
Post-Brexit regulatory divergence from EU data frameworks creates uncertainty for cloud platform vendors serving British adjusters. The UK's national building control system tightens energy efficiency documentation requirements for restoration work. London and Southeast England contractors navigate overlapping compliance obligations from retained EU directives and new domestic standards.
Global Property Restoration Software Market Competitive Landscape
Concentration sits with insurance-integrated platform vendors who have secured carrier-grade API certification. The vendor base spans three tiers: enterprise suites with decades-long carrier relationships, mobile-native field documentation specialists, and emerging workflow automation entrants. Strategic moves center on interoperability certification timelines and geographic expansion into climate resilience programs.
Within the estimation tier, Xactware Solutions anchors insurance carrier integrations through decades-long platform dominance. Encircle exemplifies mobile-native field documentation adoption among restoration contractors prioritizing real-time moisture capture. CoreLogic occupies a position bridging property data analytics with claims processing workflows. These three represent the archetypal competitive positions: carrier-anchored estimation, field-native mobility, and data-integrated analytics.
| Leading Market Players |
|---|
| Xactware Solutions |
| Encircle |
| CoreLogic |
| Next Gear Solutions |
| Job-Dox |
| Jonas |
| LuxorCRM |
| Moisture Mapper |
| iRestore |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts anchor cloud infrastructure procurement for property restoration software vendors, locking in compute access and subscription pricing visibility across multi-year carrier deployment cycles. These arrangements tether vendor margins to hyperscaler rate stability while insulating restoration firms from spot-price volatility in thermal imagery processing and automated damage assessment workloads.
Pricing Analysis
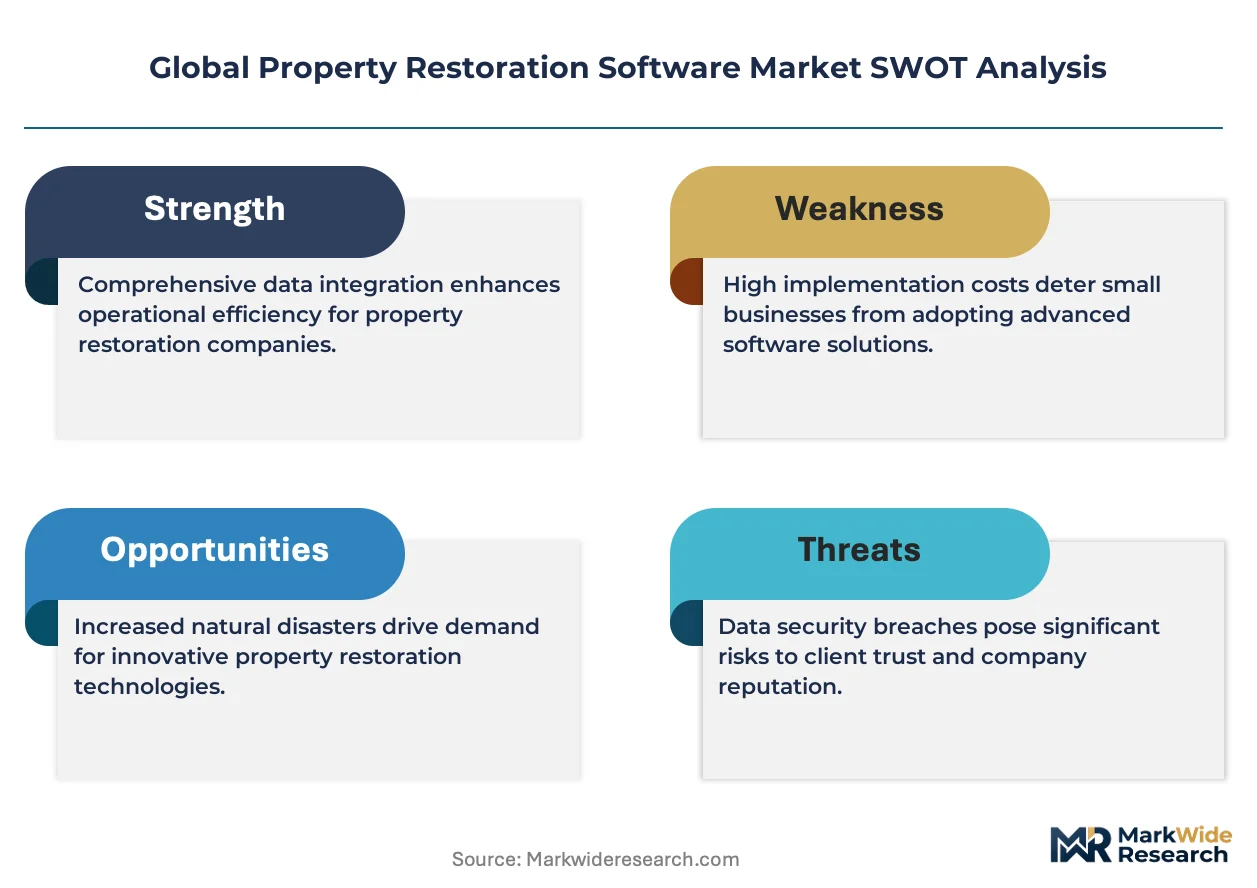
Insurance carrier procurement teams anchor SaaS-tiered subscription structures across enterprise, professional, and basic tiers differentiated by API call volume and carrier integration depth. Price differentiation rests on ISO 27001 certification grade and real-time reserve system connectivity rather than core feature parity. Cost compression in the mid-market tier is intensifying because regional restoration firms face technician wage premiums that squeeze software budgets. Independent contractors show highest price sensitivity, while national carriers with direct-bill arrangements demonstrate least sensitivity due to straight-through processing ROI.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes disrupts thermal imaging sensor shipments from Taiwan and South Korea to North American restoration hardware distributors. Cloud infrastructure provisioning draws from hyperscaler data centers in the United States, Ireland, and Singapore, with edge computing hardware sourcing concentrated in China and Vietnam. Single-source vulnerability sits with smartphone-attachable thermal camera modules where one Taiwanese OEM controls premium sensor supply. Distribution runs through insurance carrier procurement consortiums and direct vendor sales to enterprise restoration networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Property restoration software sits in early-cycle expansion as climate resilience mandates and carrier digitization programs drive first-time platform adoption among mid-sized contractors previously reliant on spreadsheets.
For Market Incumbents: Secure carrier-grade API certification timelines as a defensive moat against emerging workflow automation entrants threatening straight-through processing dominance. Deepen vertical integration into thermal imaging hardware distribution to capture margin pools currently flowing to third-party device vendors. Prioritize GDPR-compliant data residency infrastructure to defend European market position against regulatory fragmentation. For New Entrants and Emerging Players: Lead with mobile-native field documentation modules targeting independent restoration contractors in India's National Disaster Management Authority digitization programs as the most penetrable geography. Emphasize smartphone-attachable thermal camera bundling to bypass incumbent estimation software lock-in. Pursue channel partnerships with regional insurance adjusters rather than direct carrier certification battles. For Investors and Strategic Acquirers: Capital is best deployed toward platform vendors with existing carrier API accreditation and proven multi-jurisdiction compliance workflows. Long-term viability hinges on climate adaptation fund eligibility and IoT sensor convergence capabilities. Monitor carrier direct-bill arrangement penetration rates in Texas and Florida as the signal indicating inflection toward consolidated procurement authority.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier API Certification Investment | Accelerates straight-through claims processing adoption among Florida and Texas hurricane corridor insurers. |
| Edge Computing Infrastructure Deployment | Enables real-time moisture analysis in disaster zones with degraded connectivity. |
| IoT Humidity Sensor Integration | Feeds predictive drying cycle optimization algorithms for EU Green Deal compliance documentation. |
| GDPR-Compliant Data Residency Buildout | Captures German and French contractor demand facing steep cloud transfer violation penalties. |
| India Market Entry via Hosted Private Cloud | Aligns with National Disaster Management Authority procurement specifications for digitization programs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, carrier procurement disclosures, and climate adaptation fund documentation. Restoration contractor operations heads, insurance adjuster network managers, platform integration engineers, and thermal imaging hardware distributors contributed structured interviews. Secondary sources encompassed EPA enforcement records, EU AI Act implementation guidance, and federal infrastructure grant databases. Bottom-up estimates of contractor software spending triangulated against top-down carrier procurement budget allocations.
Segmentation dimensions modeled span deployment architecture, solution type, damage application, and end-user category across the projection horizon. CAGRs derived from adoption curve analysis by contractor firm size and carrier digitization maturity. Forecast inputs incorporated thermal imaging hardware cost curves, multi-jurisdiction licensing complexity indices, and climate event frequency projections for hurricane and flood corridors.
The analysis sits within stated boundaries; outcomes outside sustained carrier consolidation pressure and regulatory documentation tightening would require recalibration. Forecasts reflect assumptions on API interoperability timeline stability and hyperscaler infrastructure cost trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Africa Facility Management Market
Real Estate
Global Unified Facility Management Market
Real Estate
GCC Interior Design Services Market
Real Estate
Singapore Real Estate Market
Real Estate
Residential Property Management Market
Real Estate
Switzerland Facility Management Market
Real Estate
Europe Hard Facility Management Market
Real Estate
Canada Hospitality Real Estate Market
Real Estate
Real Estate Investment Trust (REIT) Market
Real Estate
Europe Smart Building Market
Real Estate
Asia Pacific Flexible Office Market
Real Estate
Qatar Commercial Real Estate Market
Real Estate
North America Affordable Housing Market
Real Estate
Europe REIT Market
Real Estate
New Zealand Facility Management Market
Real Estate
South Korea Self-Storage Market