
 Global Outdoor TV Market | 2026-2036
Global Outdoor TV Market Size, Share, and Industry Trends Forecast 2026-2036
Global Outdoor TV Market Outlook
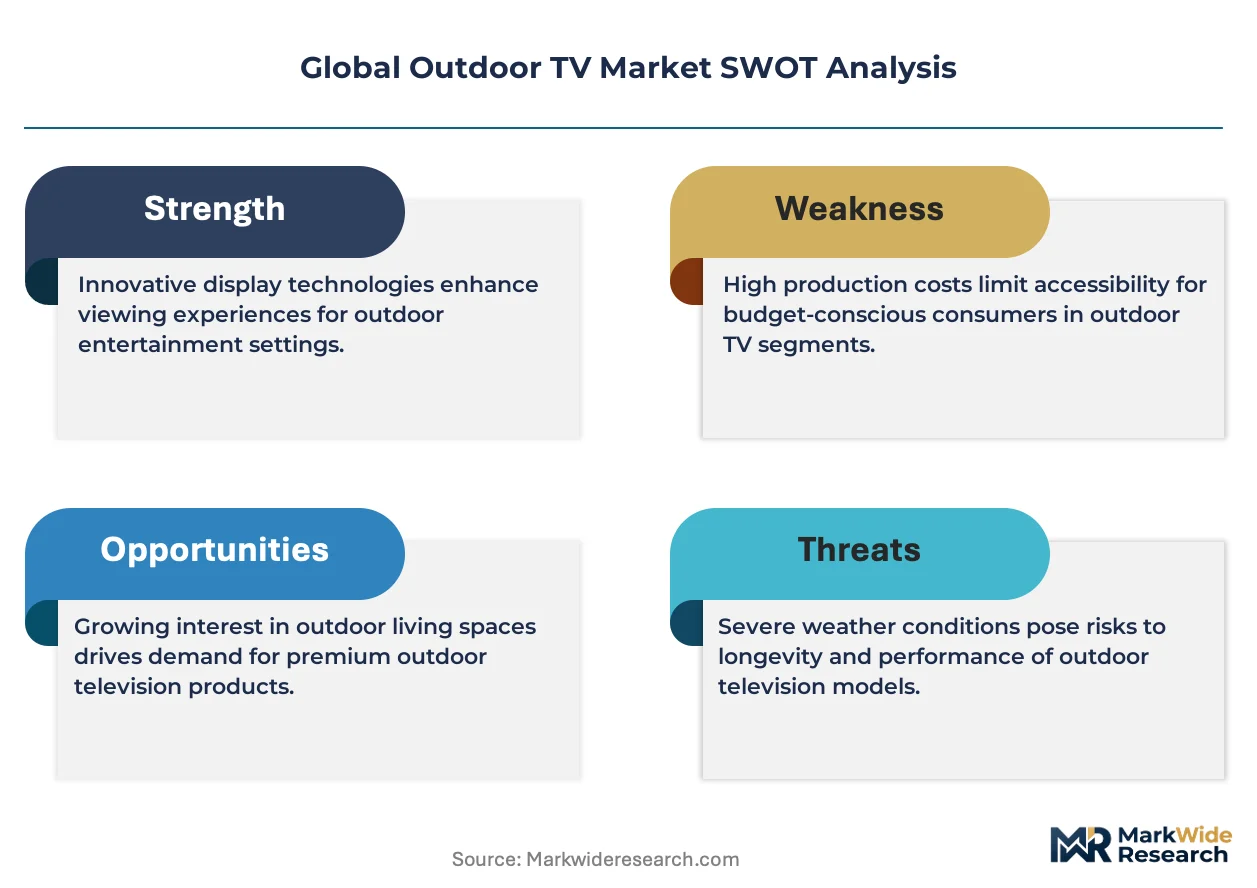
Display panel engineering talent scarcity is unwinding production timelines for weatherproofed units. SunBriteTV sustains its position through captive manufacturing of all-weather enclosures. Samsung Electronics leverages its semiconductor foundry scale to control QLED backlighting costs. LG Electronics anchors its outdoor lineup with OLED panels that deliver superior contrast in direct sunlight environments.
An outdoor television integrates sealed chassis architectures, thermal management systems, and anti-glare coatings to sustain operation across temperature extremes, humidity, and particulate exposure. LED displays currently dominate volume shipments due to cost efficiency and brightness performance in ambient light. Smart TV functionality is displacing basic connectivity as the default expectation across patio and commercial use cases. Wall-mounted installations lead demand but freestanding configurations are expanding fastest in hospitality retrofit projects.
The FCC regulates electromagnetic emissions and RF interference for connected outdoor displays sold in the United States. The EU Green Deal and Ecodesign Directive impose escalating efficiency requirements that reshape panel sourcing decisions for European-bound products. REACH compliance governs substance restrictions in weatherproofing materials across EU member states. Stakeholders must monitor how evolving IP rating standards and right-to-repair mandates reshape enclosure design priorities and warranty cost structures.
Market Dynamics
The EU Ecodesign Directive and REACH compliance mandates are forcing enclosure redesign cycles while display panel engineering talent scarcity stretches production timelines for weatherproofed units.
Growth Catalysts
- Hospitality retrofit wave:Luxury hotel chains across Florida, Arizona, and California are expanding outdoor entertainment deployments across pool decks and rooftop venues, driving volume demand for commercial-grade units.
- Smart TV functionality migration:Integrated streaming platforms and voice control are displacing basic connectivity as the default expectation across residential patio installations.
- Sun Belt residential culture:Year-round outdoor living patterns in Texas, Nevada, and Georgia sustain replacement cycles and premium-tier purchases for weatherproof displays.
Market Restraints
- Panel supply concentration:Korean and Taiwanese semiconductor foundries control QLED backlighting substrate supply, creating input cost volatility for manufacturers lacking captive sourcing.
- IP rating certification friction:Evolving IEC 60529 standards and right-to-repair mandates in Germany and France reshape warranty cost structures and enclosure engineering priorities.
- Direct-view LED substitution:Modular outdoor LED walls threaten freestanding outdoor TV configurations in hospitality and stadium applications above 85-inch equivalent scale.
Strategic Opportunities
- India commercial hospitality:Resort developments in Goa and Kerala represent underpenetrated demand for weatherproof displays as luxury tourism infrastructure expands.
- EU Green Deal alignment:Escalating efficiency benchmarks under the Ecodesign Directive create first-mover advantage for manufacturers with low-power thermal management architectures.
- Freestanding configuration growth:Portable, pedestal-mounted outdoor TVs are expanding fastest in European hospitality retrofit projects where wall mounting is structurally prohibitive.
Industry Challenges
- Sealed chassis engineering talent gap:Cross-functional expertise combining thermal management, materials science, and RF shielding remains scarce, unwinding OEM development timelines.
- Multi-jurisdiction certification complexity:Simultaneous FCC electromagnetic emissions compliance, CE marking, and emerging right-to-repair documentation requirements strain product launch bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Outdoor TV Market |
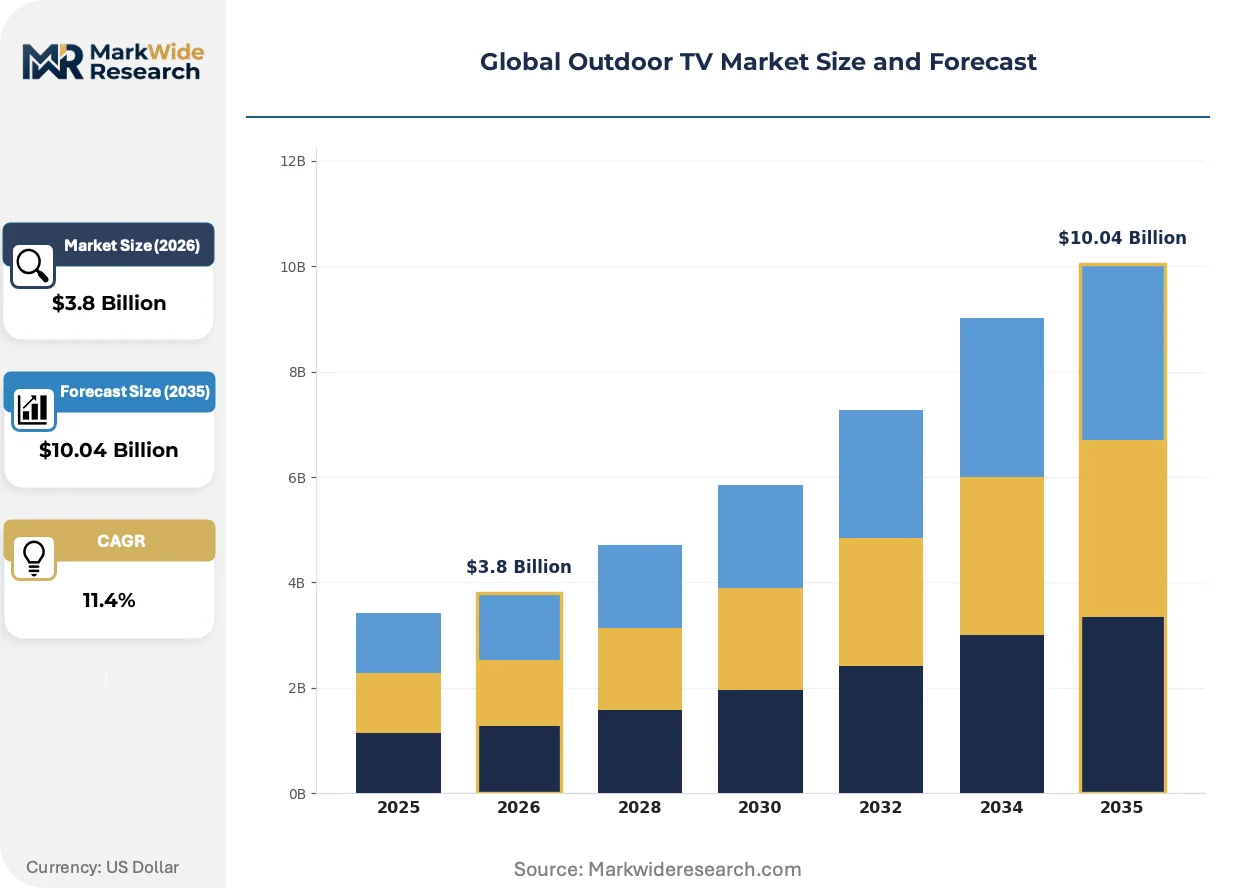
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, QLED, LCD Technology: Smart TV, 4K, 8K, HDR Use Case: Patio, Garden, Poolside, Commercial Spaces Installation: Wall-mounted, Freestanding, Permanent, Temporary |
| Companies Covered | SunBriteTV, Samsung Electronics, LG Electronics, Séura, Peerless-AV, SkyVue, Furrion, MirageVision, AquaLite TV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Outdoor TV Market Strategic Shifts
Anti-glare coating chemistry and thermal management architectures are decomposing traditional performance trade-offs between brightness, power consumption, and enclosure durability. Three shifts are restructuring competitive positioning.
Micro-LED backlighting is decomposing the brightness-versus-efficiency compromise that has constrained outdoor display development. Resort operators in Dubai and Miami are specifying micro-LED units for direct-sunlight poolside installations previously requiring shaded mounting. This technology is compressing the performance gap between premium OLED and cost-optimized LED configurations.
REACH substance restrictions are tightening weatherproofing material specifications across EU member states. ECHA enforcement of candidate list substances in gasket and coating chemistries is forcing reformulation of legacy enclosure sealing systems. German and Dutch manufacturers are accelerating fluoropolymer alternatives to maintain IP67 ratings under revised substance thresholds.
After-sales service unbundling is fragmenting traditional distribution economics. Commercial integrators in Australia and the United Arab Emirates are separating installation, extended warranty, and content management into discrete procurement decisions. This pattern is most visible in Saudi Arabia's giga-project hospitality developments, where owners negotiate display hardware, enclosure mounting, and outdoor-rated connectivity as independent contracts.
Global Outdoor TV Market Segmentation
Outdoor television procurement patterns diverge sharply between residential retrofit cycles and commercial hospitality rollouts. Panel technology choices and mounting configurations reshape total cost of ownership calculations across climate zones and regulatory environments.
Product Type:
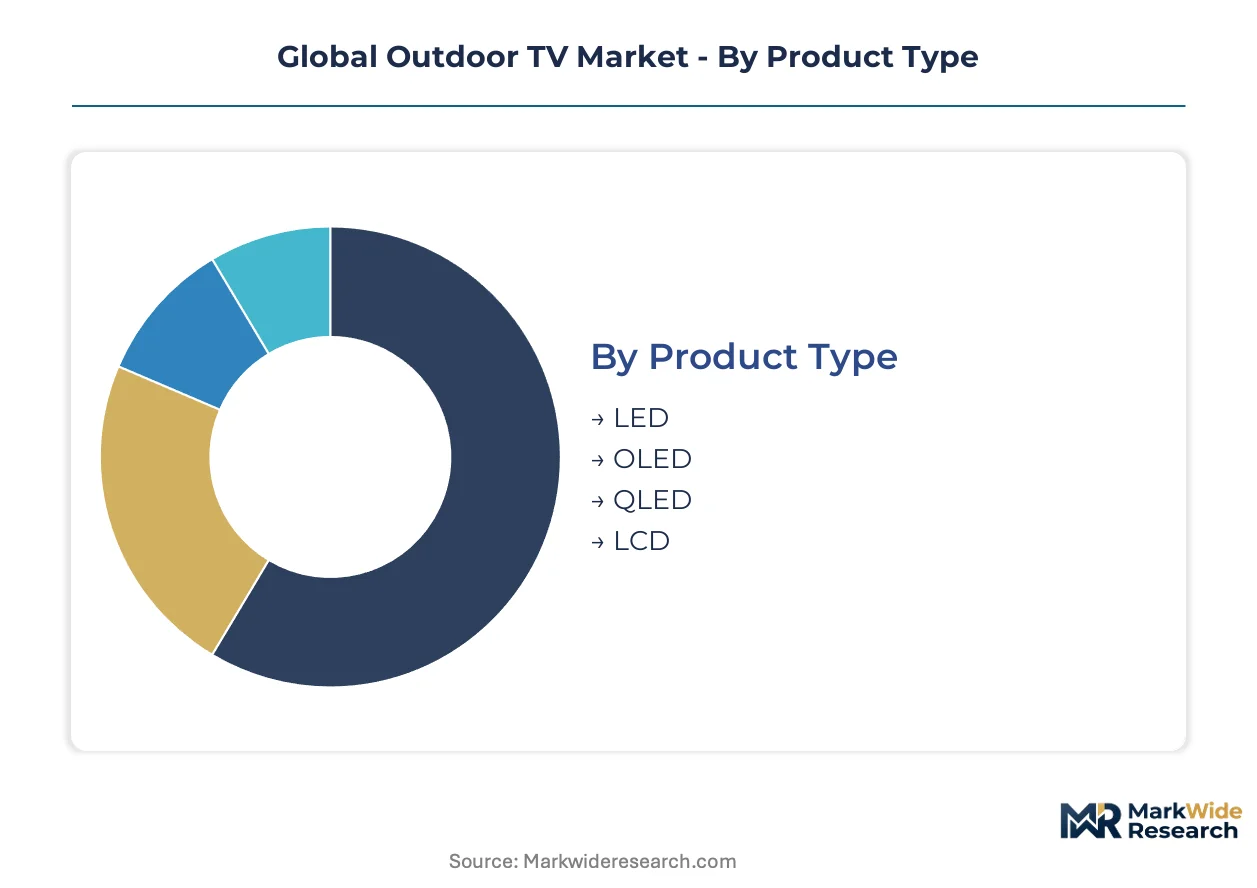
LED panels anchor domestic volume in Sun Belt states with cost-sensitive replacement cycles. OLED and QLED variants concentrate in export markets where premium positioning justifies efficiency investments.
- LED:Direct-lit and edge-lit architectures deliver the luminance density required for unshaded poolside operation. Demand concentrates in Texas and Arizona residential markets where thermal tolerance outweighs contrast performance. Korean semiconductor foundries control backlighting substrate supply, creating input cost volatility for assemblers lacking captive sourcing.
- OLED:Self-emissive pixel structures eliminate backlighting layers, enabling thinner sealed chassis designs with superior black levels in twilight viewing conditions. European hospitality operators in Portugal and Spain specify OLED for rooftop venues where ambient light control permits contrast advantages. LG Electronics anchors its outdoor lineup with these panels for direct-sunlight environments.
- QLED:Quantum dot enhancement layers boost color volume and brightness headroom for Florida and California luxury residential installations.
- LCD:Legacy fluorescent-backlit configurations persist in budget-tier commercial tenders across Indian resort developments.
LED commands the established base. The steepest expansion runs through OLED.
Technology:
Smart TV integration is displacing basic connectivity as the default expectation across patio installations. Resolution tiers separate premium hospitality specifications from residential economy purchases.
- Smart TV:Integrated streaming platforms and voice control architectures require RF shielding engineering that complicates sealed chassis design. Demand concentrates in United States residential retrofits where cord-cutting patterns accelerate hardware refresh cycles. FCC electromagnetic emissions compliance adds certification friction for connected outdoor displays.
- 4K:Ultra-high-definition resolution has become the procurement baseline for commercial spaces in Dubai and Miami where content detail visibility matters at extended viewing distances.
- 8K:Sixteen-megapixel density serves specialized stadium and arena applications above 85-inch equivalent scale where pixel structure must remain invisible.
- HDR:High dynamic range processing demands enhanced thermal management to sustain peak brightness without enclosure degradation.
Smart TV integration captures the volume center. 8K displays are climbing the fastest in specialized commercial deployments.
Use Case:
Residential applications dominate unit shipments while commercial spaces concentrate value through larger average display sizes and extended warranty procurement.
- Patio:Covered outdoor living spaces in Georgia and Nevada drive replacement cycles for weatherproofed units with moderate IP ratings. SunBriteTV sustains position through captive manufacturing of all-weather enclosures for this segment.
- Garden:Landscaped entertainment zones require freestanding configurations with pedestal mounting systems. European hospitality retrofit projects in Germany and France favor these where wall mounting is structurally prohibitive.
- Poolside:Chlorine and humidity exposure demand gasket reformulation under REACH substance restrictions. Resort operators in Goa and Kerala represent underpenetrated demand as luxury tourism infrastructure expands.
- Commercial Spaces:Rooftop venues and pool decks across Florida, Arizona, and California luxury hotel chains drive volume demand for commercial-grade units with extended service contracts.
Commercial spaces command the established base. The steepest expansion runs through garden installations.
Installation:
Mounting configuration selection determines structural engineering requirements and after-sales service unbundling patterns across procurement contracts.
- Wall-mounted:Fixed bracket installations lead demand through lower total installed cost and simplified cable management. Saudi Arabian giga-project hospitality developments negotiate display hardware and mounting as independent contracts.
- Freestanding:Portable pedestal configurations expand fastest where structural modification is restricted. Australian commercial integrators separate installation, extended warranty, and content management into discrete procurement decisions for these units.
- Permanent:Embedded structural installations with dedicated power and data infrastructure serve stadium and arena applications.
- Temporary:Rapid-deployment configurations with weatherproofed connectivity support event and seasonal hospitality operations.
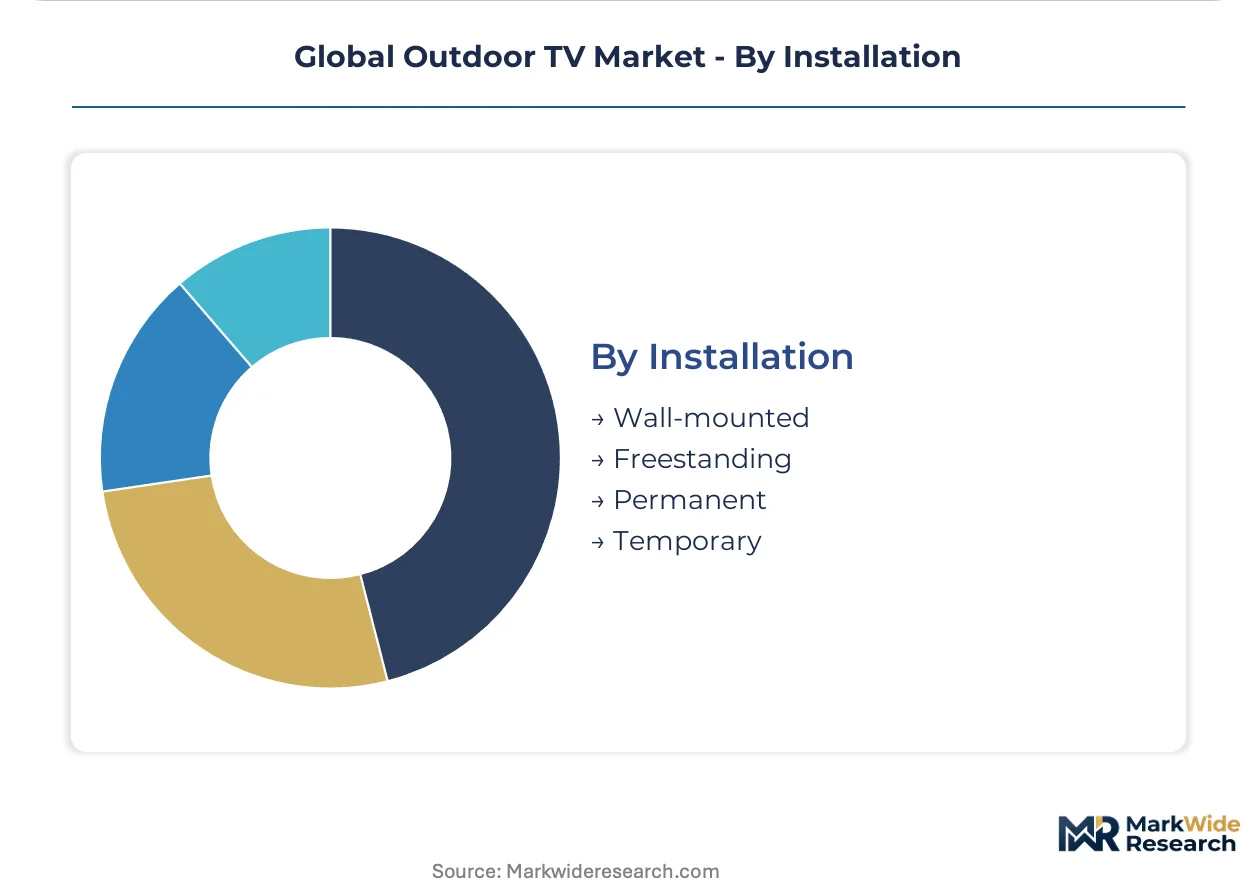
Wall-mounted configurations command the established base. Freestanding systems are gaining share fastest in European retrofit markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC electromagnetic emissions standards anchor North American procurement patterns, while EU Ecodesign Directives reshape sourcing decisions for European-bound products. Demand concentrates in Sun Belt states with year-round outdoor living cultures.
United States
Luxury hospitality chains across Florida, Arizona, and California are expanding pool deck and rooftop entertainment deployments. FCC regulations govern RF interference for connected outdoor displays sold domestically. Dallas-Fort Worth and Phoenix residential markets sustain replacement cycles for weatherproofed units with moderate IP ratings.
Germany
REACH compliance mandates are forcing gasket reformulation in weatherproofing materials across industrial manufacturing clusters. Right-to-repair documentation requirements strain product launch bandwidth for enclosure engineering teams. Stuttgart and Munich metropolitan areas concentrate precision engineering talent for sealed chassis thermal management systems.
India
Resort developments in Goa and Kerala represent underpenetrated demand as luxury tourism infrastructure expands. BIS certification requirements add friction for imported display hardware entering commercial tenders. Mumbai-Pune industrial corridor hosts assembly operations targeting hospitality retrofit specifications.
United Arab Emirates
Saudi Arabian giga-project hospitality developments negotiate display hardware, mounting, and connectivity as independent procurement contracts. MOHAP and related emirate-level regulators oversee product safety standards for outdoor-rated electronics. Dubai Design District clusters commercial integrators separating installation from extended warranty decisions.
Australia
Commercial integrators are unbundling after-sales service into discrete installation, warranty, and content management contracts. TGA and ACMA regulations govern electromagnetic compliance for connected outdoor displays. Sydney and Melbourne metropolitan markets drive freestanding configuration demand where structural wall mounting is restricted.
Global Outdoor TV Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the outdoor television value chain. The vendor base organizes around three strategic groupings: diversified electronics conglomerates with captive semiconductor sourcing, specialized weatherproofing fabricators with captive enclosure manufacturing, and commercial AV integrators with project-specific procurement relationships. Competitive moves concentrate on portfolio diversification into adjacent outdoor display formats and backward integration into thermal management component supply.
Among diversified electronics conglomerates, Samsung Electronics and LG Electronics exemplify scale-driven archetypes with in-house control over panel and backlighting substrate supply. SunBriteTV occupies a position within the specialized fabricator tier, representing captive manufacturing approaches to all-weather enclosure production. These three anchors illustrate how supply chain configuration separates premium positioning from cost-optimized volume strategies.
| Leading Market Players |
|---|
| SunBriteTV |
| Samsung Electronics |
| LG Electronics |
| Séura |
| Peerless-AV |
| SkyVue |
| Furrion |
| MirageVision |
| AquaLite TV |
| Others |
Value Chain & Pricing Dynamics
Sixteen-week lead times for QLED backlighting substrates from Korean foundries compress margin buffers for assemblers lacking captive sourcing, concentrating pricing power with vertically integrated conglomerates while forcing cost pass-through negotiations onto hospitality procurement teams. Inventory velocity constraints in weatherproofed enclosure manufacturing amplify working capital pressure across mid-tier fabricators competing for commercial retrofit contracts.
Pricing Analysis
United States residential markets command a 35-45% premium over Indian commercial tenders for equivalent panel specifications, reflecting divergent certification burdens and after-sales bundling expectations. Three-tier pricing structure across premium, standard, and economy levels separates OLED configurations with REACH-compliant gaskets from LED volumes with moderate IP ratings and legacy LCD tenders in budget resort developments. Cost compression in standard-tier LED assemblies is intensifying because Taiwanese substrate suppliers are prioritizing automotive display allocations. Hospitality chains in Florida and Arizona exhibit the least price sensitivity, prioritizing extended warranty procurement over unit acquisition cost.
Supply Chain Analysis
Strategic stockpiling of fluoropolymer gasket materials dominates European-bound production schedules, while just-in-time panel procurement persists for United States residential volumes with faster inventory turns. Manufacturing gravity centers on South Korea for QLED substrates, Taiwan for LED driver ICs, and Germany for precision thermal management components. Raw material dependencies span indium tin oxide for transparent electrodes, quantum dot enhancement films for color volume, and marine-grade aluminum alloys for corrosion-resistant chassis. Single-source vulnerability in micro-LED epitaxy equipment constrains capacity expansion for premium-tier manufacturers. Distribution runs through commercial AV integrators in Dubai and Miami who unbundle hardware, mounting, and connectivity into discrete procurement decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-functional engineering talent combining thermal management, materials science, and RF shielding remains scarcer than production capacity, creating durable advantage for incumbents with captive expertise development pipelines while raising entry barriers for specialized fabricators lacking university research partnerships.
For Market Incumbents: Consolidate position by deepening captive supply of QLED backlighting substrates through Korean foundry partnerships, insulating margin structures from input volatility. Accelerate fluoropolymer gasket formulation capabilities ahead of ECHA enforcement timelines to defend certification advantage against REACH-compliant European competitors. Prioritize thermal management R&D hiring in Stuttgart and Munich precision engineering clusters where talent concentration exceeds available headcount at specialized fabricators. For New Entrants and Emerging Players: Anchor in Indian resort developments across Goa and Kerala where BIS certification friction has delayed multinational penetration and local assembly partnerships unlock commercial tender access. Target freestanding pedestal configurations in Australian and European hospitality retrofits where structural wall-mounting restrictions fragment procurement decisions and after-sales unbundling creates service revenue attachment opportunities. Pursue direct relationships with commercial integrators separating installation from warranty procurement rather than competing through traditional distribution. For Investors and Strategic Acquirers: Long-term, this sits as a specialist-manufacturing consolidation play because enclosure engineering expertise and IP rating certification infrastructure compound defensively against modular LED wall substitution threats. Acquisition targets should demonstrate captive thermal management component supply or exclusive resort operator relationships with multi-year service contracts. The signal to watch is micro-LED backlighting cost curves crossing OLED premium thresholds, which would compress positioning windows for quantum dot-dependent configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Management Components | Captive heat-dissipation system production insulates margins from precision engineering talent scarcity in German industrial clusters. |
| REACH-Compliant Gasket Reformulation | Fluoropolymer alternatives to legacy sealing chemistries preserve IP67 ratings under ECHA substance threshold enforcement. |
| Freestanding Configuration Portfolio Expansion | Pedestal-mounted systems capture European hospitality retrofit demand where structural wall mounting is prohibited. |
| Smart TV RF Shielding Certification Investment | FCC electromagnetic emissions compliance creates procurement friction that filters out unqualified competitors in United States residential markets. |
| Commercial Integrator Partnership Structuring | Unbundled installation and warranty contracts in Australian and UAE markets fragment traditional distribution economics toward service revenue. |
Study Parameters
Cross-validation between primary interviews with display panel procurement directors, hospitality technology integrators, and sealed chassis engineering leads and secondary validation through SEC semiconductor foundry filings, ECHA substance restriction updates, and FCC equipment authorization databases anchors the qualitative findings. Bottom-up demand modeling triangulates against top-down value chain analysis across the projection horizon.
Sensitivity analysis on input cost volatility from Korean and Taiwanese substrate suppliers shapes the analytical framework, with segmentation dimensions spanning panel technology, mounting configuration, use case intensity, and regional regulatory cluster. CAGRs derive from installation base expansion rates, replacement cycle compression in Sun Belt states, and premium-tier mix shifts toward smart TV integration. Industry-specific forecast inputs include REACH substance list revisions and right-to-repair mandate implementation timelines in Germany and France.
Decision-makers should treat outputs as directional under assumptions of sustained Sun Belt residential replacement demand and stable Korean-Taiwanese semiconductor foundry allocation priorities; material deviation would warrant model refresh. Revision becomes warranted when micro-LED backlighting cost curves cross OLED premium positioning thresholds or when Ecodesign Directive efficiency benchmarks accelerate faster than thermal management architecture development cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Headset Market
Consumer Goods
Smart Audio Devices Market
Consumer Goods
Helmets Market
Consumer Goods
Electric Tooth Polisher Market
Consumer Goods
Baby Oil Market
Consumer Goods
Global Away-From-Home Tissue and Hygiene Market
Consumer Goods
Anti-Acne Cosmetics Market
Consumer Goods
Switzerland Home Appliances Market
Consumer Goods
Hair Removal Wax Market
Consumer Goods
OEM Shoe Manufacturer Service Market
Consumer Goods
Netherlands Pet Food Market
Consumer Goods
Europe Cookware Market
Consumer Goods
Asia-Pacific Hair Conditioner Market
Consumer Goods
Europe & UK Nonstick Cookware Market
Consumer Goods
Razor Blade Market
Consumer Goods
Cooker Hoods Market