
 Global Online Racing Games Market | 2026-2036
Global Online Racing Games Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online Racing Games Market Foresight
The capital-intensity divergence between blockbuster studios and mid-tier developers is collapsing as cloud infrastructure and cross-platform engines democratize production pipelines. Electronic Arts Inc. anchors its position through licensed motorsport IP and annualized release cycles that sustain recurring monetization. Codemasters Software Company Ltd. specializes in simulation physics and handling fidelity that differentiates its portfolio from arcade competitors. Microsoft Corporation leverages its Xbox Game Pass subscription to extend racing titles into bundled access models that compete on value rather than unit sales.
Global Online Racing Games constitute interactive software titles where players compete in vehicular time trials or head-to-head contests across networked servers, typically rendering at 60 frames per second with latency below 50 milliseconds to preserve input responsiveness. These products serve commercial entertainment purposes while generating revenue through engagement-driven monetization rather than one-time retail transactions. The Platform dimension shows mobile and cloud gaming segments capturing volume leadership due to lower hardware barriers, while PC and console installations retain premium monetization density through higher-spending competitive racers. Simulation titles within the Game Genre category concentrate development investment and margin pools, whereas Arcade and Kart Racing variants attract broader casual audiences that advertisers and freemium models target.
The US Federal Trade Commission scrutinizes loot box mechanics and in-game purchase disclosures, directly affecting how publishers structure Monetization Model transparency across freemium and pay-to-play offerings. China's National Press and Publication Administration enforces online game approval quotas and minor playtime restrictions that shape market access timelines and player base composition for titles seeking distribution there. Japan's Consumer Affairs Agency monitors gacha-style randomized rewards under its prize regulation framework, creating compliance complexity for cross-border live-service operations. Stakeholders must monitor how divergent regional approaches to player protection and content classification reshape development roadmaps and geographic prioritization decisions.
Market Dynamics
Cloud gaming infrastructure is collapsing the hardware barrier that historically gated premium racing simulation access, forcing publishers to rebuild monetization around engagement velocity rather than console cycle timing. This shift concentrates competitive advantage on network latency optimization and cross-platform save state synchronization.
Growth Catalysts
- China's MIIT licensing framework:The Ministry of Industry and Information Technology's streamlined approval process for online titles accelerates release timelines for compliant publishers, compressing time-to-revenue for live-service racing products targeting the domestic market.
- South Korea's PC bang infrastructure:Dense concentrations of high-performance gaming cafes sustain low-latency competitive environments that cultivate dedicated player bases and organic tournament ecosystems without consumer hardware investment.
- Ray-traced rendering pipelines:Real-time global illumination technology is elevating visual fidelity standards across simulation genres, driving hardware upgrade cycles and premium cosmetic monetization attachment rates.
Market Restraints
- GPU supply concentration:Taiwan Semiconductor Manufacturing's dominance in advanced node fabrication creates vulnerability to geopolitical disruption and pricing volatility for graphics-intensive titles.
- Input latency physics:The 50-millisecond threshold for competitive responsiveness requires edge server deployment that inflates operational expenditure in markets lacking cloud infrastructure density.
- Japan's Consumer Affairs Agency gacha enforcement:Prize regulation frameworks impose compliance complexity on randomized reward mechanics, constraining monetization design flexibility for cross-border live-service operations.
Strategic Opportunities
- India's broadband expansion:Reliance Jio's fiber rollout and affordable data pricing are unlocking addressable audiences previously excluded by connectivity costs and hardware scarcity.
- Subscription bundling models:Platform holders are integrating racing titles into all-access catalogs that compete on value rather than unit sales, reducing customer acquisition friction for mid-tier developers.
- Vehicle-to-cloud telemetry convergence:OEM data partnerships enable authentic handling models derived from real-world sensor feeds, differentiating simulation authenticity from arcade competitors.
Industry Challenges
- Netcode engineering scarcity:Specialized talent for deterministic lockstep synchronization commands premium compensation that strains mid-studio payroll structures.
- Cross-platform certification complexity:Sony, Microsoft, and Nintendo impose divergent technical standards that prolong release timelines and inflate quality assurance expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online Racing Games Market |
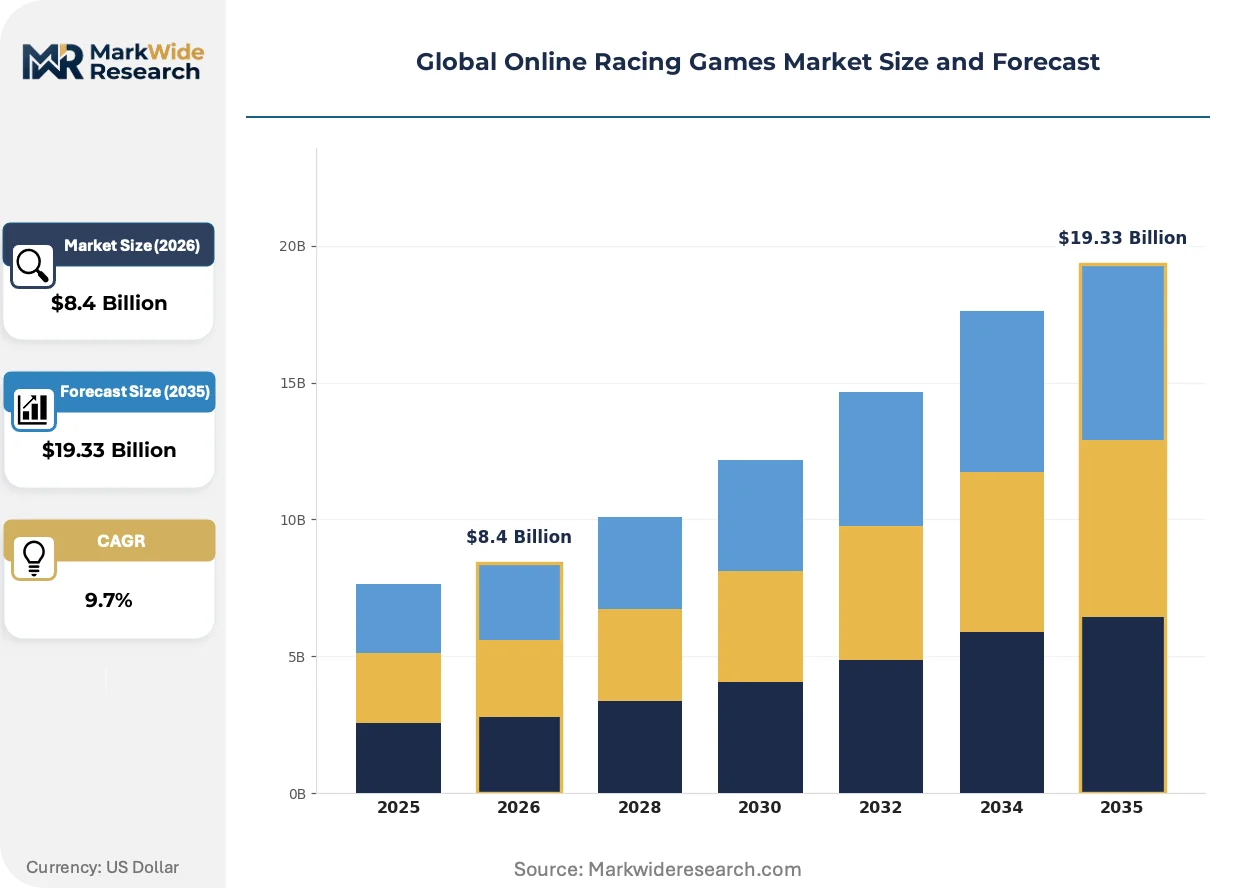
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Genre: Simulation, Arcade, Kart Racing, Time Trial, Drag Racing, Off-Road Platform: PC, Console, Mobile, Cloud Gaming, VR Headsets, Hybrid Monetization Model: Freemium, Subscription, In-App Purchases, Advertisements, Pay-to-Play Player Type: Casual Gamers, Competitive Racers, Social Players, eSports Participants, Streamers |
| Companies Covered | Electronic Arts Inc., Microsoft Corporation, Gameloft SE, Aquiris Game Studio SA, THQ Nordic GmbH, Codemasters Software Company Ltd., Ubisoft Entertainment SA, Take-Two Interactive Software Inc., Nexon Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online Racing Games Market Shifts & Advancements
Real-time physics computation and spectator-facing broadcast tools are converging to transform racing games into viewership-first entertainment properties. Publishers now architect titles for dual consumption modes simultaneously.
Neural network-based anti-cheat systems are miniaturizing detection footprints while expanding behavioral analysis scope. Competitive leagues deploy these tools to preserve integrity in prize-funded tournaments. The compression of cheat development cycles is forcing continuous model retraining that elevates operational security expenditure across live-service portfolios.
The EU's Digital Services Act imposes transparency mandates on algorithmic content recommendation and in-game purchase disclosure. Publishers serving European audiences must restructure storefront interfaces and probability displays. Simulation titles with complex DLC ecosystems face particular compliance burden in Germany and France where consumer protection enforcement is most active.
Viewership monetization is displacing player monetization as the primary revenue architecture for top-tier releases. Streaming platform revenue-share agreements and sponsored tournament broadcasts now exceed direct consumer spending in certain title lifecycles. This pattern concentrates most visibly in South Korea and Brazil where live-streaming penetration outpaces hardware ownership.
Global Online Racing Games Market Segmentation
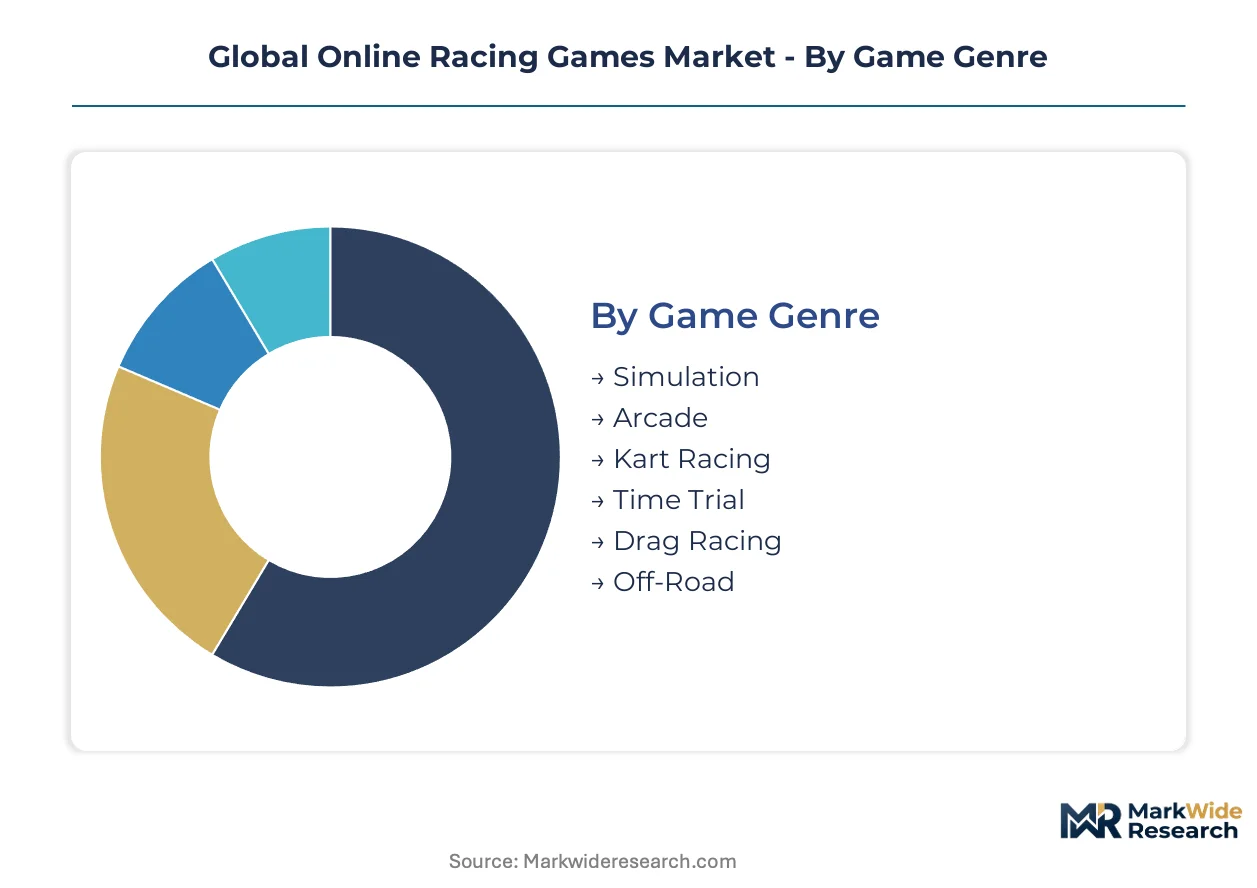
Segmentation in online racing games determines how publishers allocate engineering resources and pricing architecture. Each dimension carries distinct margin profiles and regulatory exposure that shape go-to-market strategy.
Game Genre:
Margin pools concentrate where physics fidelity commands premium pricing and recurring DLC attachment.
- Simulation:Real-time vehicle dynamics and tire modeling demand substantial development investment. South Korea's PC bang culture sustains competitive leagues that monetize through seasonal battle passes and vehicle licensing fees.
- Arcade:Accessible handling models prioritize spectacle over authenticity. Mobile-first markets in India and Brazil drive volume through advertising-supported models that sacrifice per-user revenue for scale.
- Kart Racing:Power-up mechanics and character licensing dominate this family-oriented segment. Nintendo's IP control constrains independent publisher entry.
- Time Trial:Leaderboard-centric competition minimizes server infrastructure costs. Ghost data synchronization enables asynchronous multiplayer without real-time netcode expenditure.
- Drag Racing:Straight-line acceleration mechanics simplify physics computation. Aftermarket parts licensing generates incremental revenue through cosmetic customization.
- Off-Road:Terrain deformation systems elevate storage and memory requirements. Rally championship partnerships provide differentiated content pipelines.
The dominant share belongs to Simulation, while Arcade is closing the gap fastest through emerging market smartphone penetration.
Platform:
Hardware barriers dictate customer acquisition economics and monetization ceiling.
- PC:Open hardware ecosystems enable modding communities that extend title longevity. Steam Workshop integration reduces publisher content production burden.
- Console:Sony, Microsoft, and Nintendo certification processes impose quality gates that inflate launch timelines. First-party controller standardization ensures consistent input latency.
- Mobile:Touchscreen interfaces constrain control precision, favoring simplified physics models. China's MIIT licensing framework shapes release sequencing for domestic distribution.
- Cloud Gaming:Edge server deployment eliminates consumer hardware requirements. Network infrastructure density in South Korea and Japan enables competitive responsiveness thresholds.
- VR Headsets:Motion sickness mitigation limits session duration and monetization depth. Meta's hardware subsidies accelerate addressable base expansion.
- Hybrid:Cross-progression systems synchronize save states across device categories. Operational complexity elevates ongoing service costs.
Mobile captures the largest player base, though Cloud Gaming is expanding most quickly through 5G rollout acceleration.
Monetization Model:
Regulatory scrutiny intensity varies dramatically across pricing architectures.
- Freemium:Gated progression systems convert engagement into cosmetic and convenience purchases. Japan's Consumer Affairs Agency monitors probability disclosures for randomized rewards.
- Subscription:Xbox Game Pass and PlayStation Plus bundle access that competes on value rather than unit sales. Recurring revenue predictability attracts mid-tier developer participation.
- In-App Purchases:Direct storefront transactions face platform holder revenue share extraction. Apple's 30% fee structure compresses net margins for iOS-distributed titles.
- Advertisements:Rewarded video placement monetizes non-paying audiences without gameplay interruption. Brand safety concerns constrain motorsport adjacency for family-oriented advertisers.
- Pay-to-Play:Upfront purchase models avoid ongoing regulatory compliance burden. Premium pricing limits addressable market to dedicated enthusiasts.
Freemium holds the dominant revenue position, while Subscription is gaining share fastest through platform holder bundling incentives.
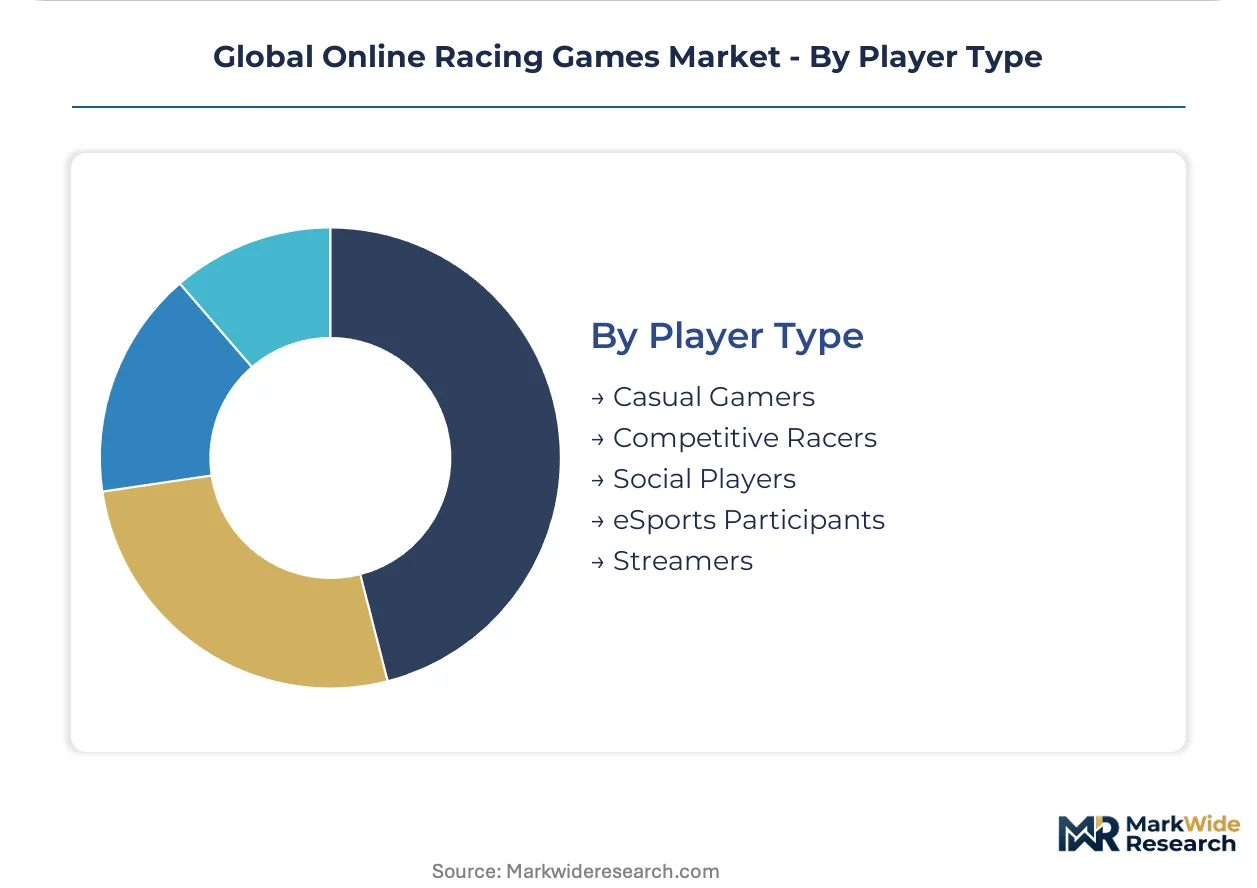
Player Type:
Engagement depth determines lifetime value and content production requirements.
- Casual Gamers:Short session patterns favor pick-up-and-play mechanics. Advertising and freemium models monetize this volume segment.
- Competitive Racers:Ranked ladder systems and tournament infrastructure demand anti-cheat investment. Prize pools in South Korea and Brazil exceed direct consumer spending in certain title lifecycles.
- Social Players:Party systems and voice chat prioritize connection stability over visual fidelity. Cross-platform friend lists reduce fragmentation friction.
- eSports Participants:Broadcast tool integration and spectator modes architect titles for dual consumption. Streaming platform revenue-share agreements now constitute primary revenue for top-tier releases.
- Streamers:Content creator programs subsidize acquisition through organic reach. DMCA compliance for licensed music constrains background audio design.
Casual Gamers comprise the largest addressable population, though eSports Participants are climbing the fastest as viewership monetization displaces player spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The export-import balance in online racing games tilts toward service exports from developed markets into emerging consumption zones. The United States and Japan generate surplus through IP licensing and engine technology sales. China and South Korea import premium simulation physics while exporting mobile monetization expertise.
United States
Licensed motorsport IP and annualized release cycles sustain publisher revenue through recurring monetization. The FTC scrutinizes loot box mechanics and in-game purchase disclosures, forcing transparency restructuring across freemium models. Los Angeles and Austin host development clusters where Electronic Arts and Microsoft anchor competitive positioning through subscription bundling and first-party platform control.
China
Mobile-first audiences and PC bang culture drive volume leadership in freemium adoption. The MIIT licensing framework accelerates release timelines for compliant publishers while enforcing minor playtime restrictions. Shenzhen and Shanghai concentrate cloud gaming infrastructure investment as Tencent and NetEase deploy edge servers for latency-sensitive competitive racing.
South Korea
PC bang infrastructure sustains low-latency competitive environments without consumer hardware investment. The Game Rating and Administration Committee monitors content classification and playtime limits for minors. Seoul's dense gaming cafe networks cultivate organic tournament ecosystems where Nexon monetizes through seasonal battle passes and vehicle licensing fees.
Japan
Console heritage and character licensing dominance anchor premium pricing in kart racing segments. The Consumer Affairs Agency enforces gacha-style randomized reward regulations under prize frameworks, constraining monetization design flexibility. Tokyo's development studios specialize in broadcast tool integration for viewership-first entertainment properties targeting dual consumption modes.
Germany
Simulation physics fidelity commands enthusiast pricing from dedicated PC racing communities. The EU Digital Services Act imposes algorithmic transparency mandates on storefront interfaces and probability displays. Munich and Hamburg host mid-tier developers leveraging Steam Workshop integration to reduce content production burden through modding communities.
Global Online Racing Games Market Competitive Landscape
Concentration sits with platform-integrated publishers and licensed motorsport specialists. The market structure shows tiered consolidation where first-party platform holders and blockbuster studios capture premium monetization density. Three archetypes dominate: platform-integrated conglomerates with subscription bundling leverage, licensed motorsport specialists with annualized release discipline, and mobile-first publishers with freemium optimization expertise. Competitive moves center on cloud infrastructure partnerships and cross-platform save state synchronization to collapse hardware barriers.
Within the licensed motorsport tier, Electronic Arts Inc. and Codemasters Software Company Ltd. exemplify divergent physics fidelity strategies, with the former emphasizing annualized portfolio breadth and the latter concentrating on simulation authenticity. Microsoft Corporation anchors platform-integrated positioning through subscription access models that compete on value rather than unit sales. These three entities represent the dominant competitive archetypes structuring margin capture across PC, console, and emerging cloud segments.
| Leading Market Players |
|---|
| Electronic Arts Inc. |
| Microsoft Corporation |
| Gameloft SE |
| Aquiris Game Studio SA |
| THQ Nordic GmbH |
| Codemasters Software Company Ltd. |
| Ubisoft Entertainment SA |
| Take-Two Interactive Software Inc. |
| Nexon Co. Ltd. |
| Others |
Supply & Pricing Matrix
Cloud infrastructure substitution for dedicated console hardware is redistributing development cost structures while collapsing geographic barriers to premium simulation access. This shift simultaneously compresses upfront retail pricing power in developed markets and unlocks subscription-based monetization elasticity where network density permits competitive latency thresholds.
Pricing Analysis
Industrial OEM buyers anchor pricing structures through vehicle telemetry licensing agreements that command premium fees for authentic handling models. Pricing stratifies across simulation authenticity tiers, with physics fidelity and motorsport IP certification driving differentiation. Pricing pressure stems from platform holder subscription bundling that commoditizes unit sales. Casual mobile segments exhibit highest price sensitivity, while competitive PC racers demonstrate lowest elasticity for premium DLC.
Supply Chain Analysis
Inventory cycles for GPU and edge server hardware extend lead times for cloud deployment in emerging markets. Supply concentrates in Taiwan, South Korea, and China for advanced semiconductor fabrication. Development pipelines draw from Unity and Unreal engine licensing, motion capture services, and vehicle OEM data partnerships. Single-source vulnerability in TSMC's advanced node production creates disruption risk. Distribution runs through platform holder digital storefronts and direct-to-consumer live-service operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where cross-platform save state synchronization and cloud-native architecture are displacing hardware-tied monetization. The interoperability shift toward subscription bundling and engagement-velocity pricing restructures competitive advantage around network infrastructure rather than retail distribution.
For Market Incumbents: Secure exclusive vehicle licensing partnerships with premium OEMs to differentiate simulation portfolios from subscription-catalog commoditization. Invest in edge server deployment across South Korea and Japan where PC bang density sustains low-latency competitive environments. Backward integration into cloud infrastructure reduces platform holder revenue share extraction. For New Entrants and Emerging Players: Differentiate on broadcast tool integration and spectator-mode architecture to capture viewership monetization displacing player spending in Brazil and South Korea. Target India's broadband expansion zones where Reliance Jio infrastructure unlocks previously excluded audiences. Pursue white-label netcode licensing to mid-tier studios facing engineering talent scarcity. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform-integrated publishers with subscription bundling leverage and licensed motorsport specialists with annualized release discipline. Long-term viability hinges on cloud infrastructure partnerships and cross-platform certification efficiency. Watch for MIIT licensing quota adjustments in China as inflection signals for geographic revenue timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Infrastructure Partnership | Edge server deployment with Tencent or NetEase collapses hardware barriers in China. |
| Vehicle Telemetry Licensing Agreement | OEM data partnerships with Porsche or Ferrari differentiate simulation authenticity. |
| Cross-Platform Certification Investment | Unified technical standards reduce Sony, Microsoft, Nintendo QA expenditure. |
| Broadcast Tool Integration | Spectator-facing architecture captures streaming revenue-share in South Korea. |
| Neural Network Anti-Cheat Deployment | Behavioral analysis preserves tournament integrity for prize-funded competitive leagues. |
Research Methodology
A standing panel of live-service product directors, netcode engineering leads, platform partnership managers, and esports tournament operators provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with secondary validation against SEC filings, platform holder earnings disclosures, and regional regulatory filings from China's MIIT and Japan's Consumer Affairs Agency. Bottom-up segment sizing triangulated against top-down market boundary checks.
Consistency checks validated volume and value outputs against hyperscaler capex disclosures, Steam concurrent player data, and mobile platform revenue estimates. The analytical framework modeled platform, game genre, and monetization model dimensions across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic gaming expenditure trends. Forecast inputs incorporated cloud infrastructure rollout schedules, licensing approval timelines, and 5G penetration curves.
Forecasts assume regulatory continuity in China's MIIT framework and Japan's gacha enforcement regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness
Exercise Bike Market
Sports & Fitness
Global Player Tracking Market
Sports & Fitness
Europe Sports Analytics Market
Sports & Fitness
Speed Hurdle Market
Sports & Fitness
Turbo Trainer Market
Sports & Fitness
Hydration Belt Market
Sports & Fitness
Home Fitness Equipment Market
Sports & Fitness
Bicycle Drivetrain Cassette Market
Sports & Fitness
Fitness Tracker for Heart Rate Market
Sports & Fitness
Synthetic Ice Skating Rink Market
Sports & Fitness
Ankle Roll Guard Market
Sports & Fitness
Smart Breathing Trainer Market
Sports & Fitness
Breathing Wear Market
Sports & Fitness
Global Shooting Games Market
Sports & Fitness
B2B Sports Nutrition Market
Sports & Fitness
GPS Watches for Kids Market