
 Global Healthcare Education Solution Market | 2026-2036
Global Healthcare Education Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Education Solution Market Foresight
Nursing faculty shortages across developed markets is collapsing the traditional apprenticeship model for clinical training. Siemens Healthineers leverages its simulation hardware portfolio to anchor hospital-based education contracts in Germany and Japan. SAP competes through enterprise learning platforms that integrate workforce credentialing with hospital HR systems.
Healthcare education solutions encompass integrated software, hardware, and content platforms designed to deliver standardized clinical training, competency assessment, and continuing professional development across distributed learner populations. Simulation platforms incorporate haptic feedback devices, virtual reality headsets, and physiological modeling engines to replicate surgical procedures, emergency response protocols, and diagnostic workflows without patient risk. Learning Management Systems dominate procurement budgets among medical schools due to their scalability across thousands of concurrent users, while simulation platforms capture the fastest growth trajectory as hardware costs decline and fidelity improves. Cloud-based deployment occupies the largest addressable base among nursing colleges seeking to minimize IT infrastructure capital expenditure.
The FDA's quality system regulation mandates device-specific training documentation for clinical operators, creating recurring revenue streams for content management vendors serving manufacturers. EMA's Medical Device Regulation and ISO 13485 training requirements compel European healthcare organizations to maintain auditable competency records, reinforcing demand for assessment tools with built-in compliance reporting. India's CDSCO and the country's central drug standards authority are tightening qualification norms for medical device sales representatives, expanding the addressable market for professional certification platforms. Stakeholders must evaluate whether their platform architectures can absorb emerging interoperability standards linking education records directly to provider credentialing databases and payer networks.
Market Dynamics
The nursing faculty shortage across developed markets is collapsing the traditional apprenticeship model for clinical training, forcing institutions toward simulation-based and digital delivery platforms that reduce instructor dependency while maintaining competency standards.
Growth Catalysts
- EU Medical Device Regulation (MDR):Tightened training documentation requirements for device manufacturers create recurring demand for auditable competency management platforms across European healthcare organizations.
- Simulation hardware cost compression:Declining prices for haptic feedback devices and VR headsets enable medical schools to scale standardized procedural training without patient risk exposure.
- India's CDSCO qualification norms:Stricter credentialing requirements for medical device sales representatives expand the addressable market for professional certification platforms in southern states.
Market Restraints
- Cloud infrastructure dependency:Nursing colleges minimizing capital expenditure become locked into recurring SaaS fees that escalate with user scaling, compressing long-term budget flexibility.
- Faculty credentialing bottlenecks:Simulation platform deployment requires instructors to obtain specialized technical certifications, creating deployment delays in markets with limited trainer availability.
- Interoperability fragmentation:Education record systems lack standardized APIs linking to provider credentialing databases, forcing costly custom integration work for hospital networks.
Strategic Opportunities
- FDA quality system regulation expansion:Device-specific training mandates for clinical operators open recurring revenue streams for content management vendors serving US manufacturers.
- VR-physiological modeling convergence:Integration of immersive headsets with real-time biometric engines enables emergency response training scenarios previously requiring physical simulation centers.
- Japan's hospital HR system integration:Enterprise learning platforms that embed workforce credentialing directly into existing personnel management infrastructure capture procurement preference.
Industry Challenges
- Legacy LMS migration complexity:Medical schools with decades of course content in proprietary formats face multi-year conversion timelines to cloud-native architectures.
- Competency assessment standardization delays:Absence of universal benchmarks for simulation-based skills evaluation forces institutions to maintain parallel validation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Education Solution Market |
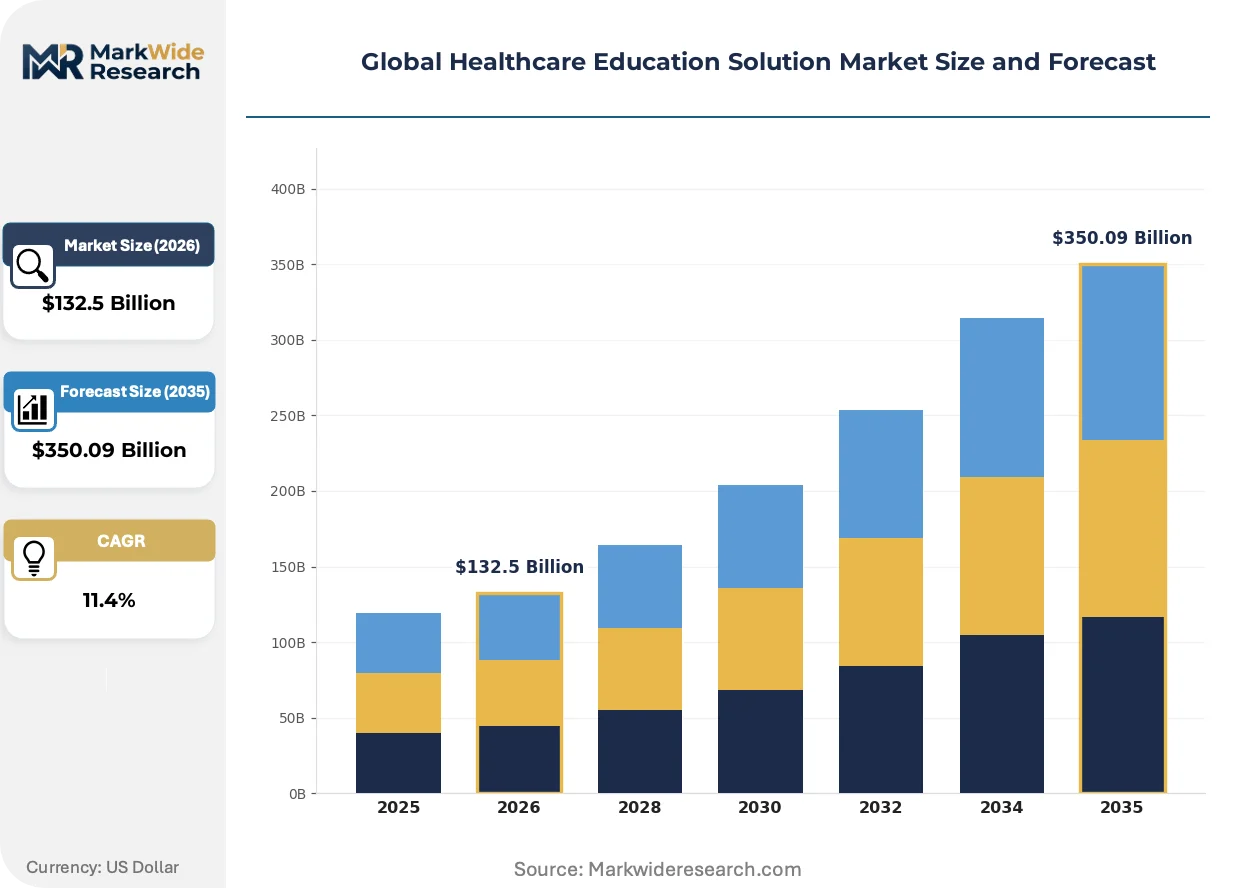
| Market Size in 2026 | $132.5 Billion |
| Market Size in 2035 | $350.09 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Learning Management Systems, Simulation Platforms, Virtual Classrooms, Assessment Tools, Content Management Systems Application: Medical Training, Continuing Education, Patient Education, Professional Certification, Skill Development End User: Medical Schools, Nursing Colleges, Research Institutes, Hospitals, Healthcare Organizations Deployment: Cloud-Based, On-Premise, Hybrid, Mobile-Based, Web-Based |
| Companies Covered | GE Healthcare, Stryker, Siemens Healthineers, Medtronic, SAP, Adobe, Oracle, Elsevier, FUJIFILM Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Education Solution Market Shifts & Advancements
Healthcare education is pivoting from classroom-centered delivery toward immersive, competency-verified platforms that integrate directly with workforce credentialing systems and regulatory compliance frameworks.
Virtual reality surgical training systems is miniaturizing from room-scale installations to portable headset configurations. Community hospitals and ambulatory surgery centers in Germany and Japan are adopting these platforms at accelerated pace to meet procedural volume requirements without resident staffing. The technology is compressing the capital barrier between academic medical centers and smaller facilities, redistributing advanced training capability across facility tiers.
EMA's Medical Device Regulation and ISO 13485 training requirements are compelling European healthcare organizations to maintain auditable competency records with built-in compliance reporting. Manufacturers serving EU markets must document operator training for each device class, creating procurement pull for assessment platforms with automated audit trails. Hospital networks in France and Germany are prioritizing vendors with pre-validated MDR reporting modules.
Subscription-based licensing for simulation content is displacing perpetual hardware purchases in nursing college procurement. Institutions in India's Karnataka and Tamil Nadu states are favoring vendors offering content libraries with usage-based renewal over capital-intensive equipment ownership. This preference shift concentrates vendor relationships around content refresh velocity and cloud reliability rather than device durability.
Global Healthcare Education Solution Market Segmentation
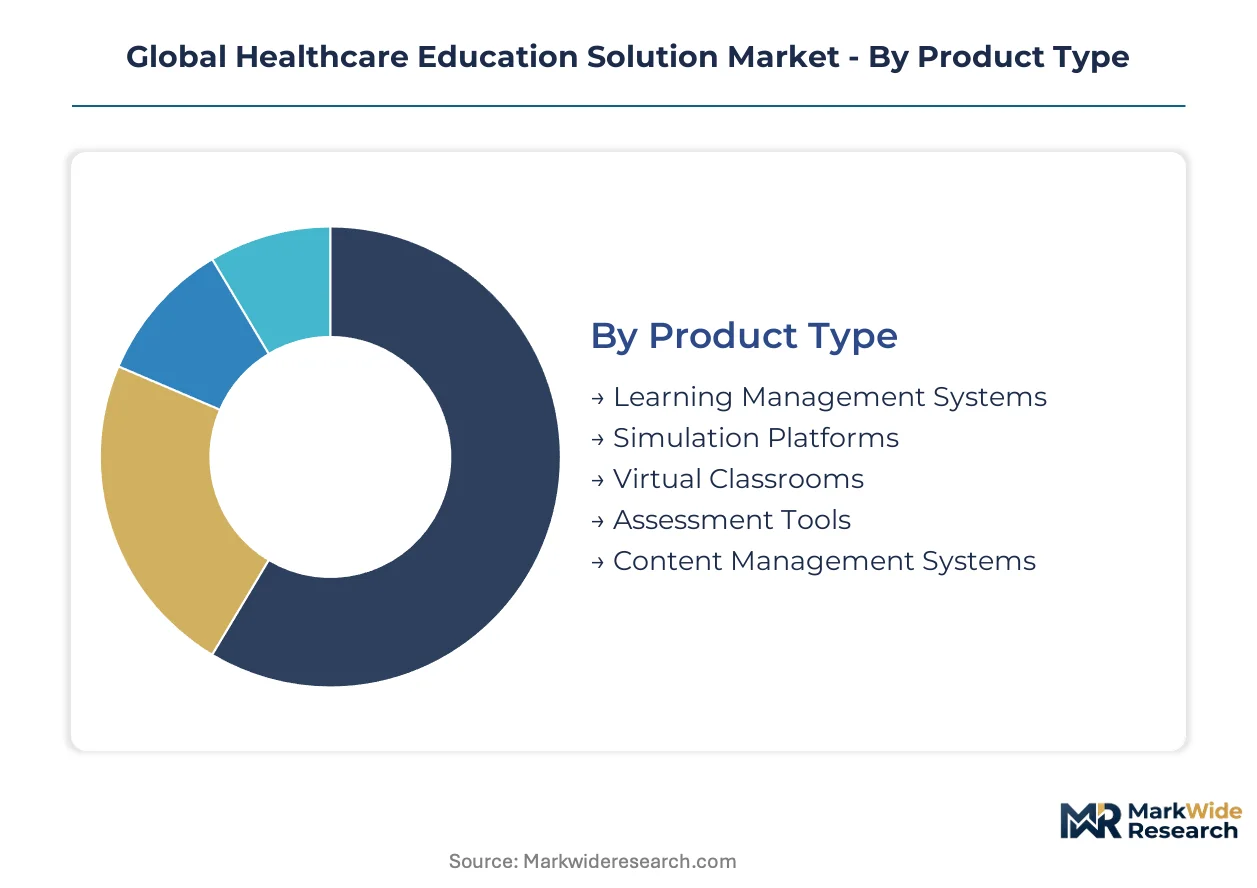
Healthcare education solutions fragment across product architectures that serve distinct compliance mandates and capital constraints. Procurement patterns diverge sharply between institutions seeking scalable software subscriptions and those investing in immersive hardware infrastructure.
Product Type:
FDA quality system regulation and EMA MDR documentation requirements create divergent demand profiles across platform categories, with compliance-heavy segments commanding premium pricing against utility-focused alternatives.
- Learning Management Systems:Cloud-native architectures support thousands of concurrent users across distributed medical school campuses. Procurement concentrates in US and EU institutions scaling standardized curricula while maintaining HIPAA and GDPR audit trails for student records.
- Simulation Platforms:Haptic feedback devices, VR headsets, and physiological modeling engines replicate surgical procedures without patient risk. Demand clusters in Germany and Japan where hospital networks deploy portable configurations to meet procedural volume requirements.
- Virtual Classrooms:Synchronous video infrastructure with integrated assessment polling.
- Assessment Tools:Automated competency validation with built-in compliance reporting modules.
- Content Management Systems:Centralized repositories for device-specific training documentation serving manufacturers.
Established volume favors Learning Management Systems; emerging adoption favors Simulation Platforms.
Application:
Customer maturity determines deployment depth, with academic institutions prioritizing foundational training while healthcare organizations emphasize workforce credentialing integration.
- Medical Training:Pre-licensure curricula spanning basic sciences through clinical rotations. US medical schools dominate procurement budgets here, driven by LCME accreditation requirements and student volume scaling.
- Continuing Education:Mandatory credit accumulation for license renewal across nursing and physician populations. EU markets show concentrated demand as MDR and ISO 13485 compel auditable competency maintenance.
- Patient Education:Condition-specific content delivery for chronic disease management.
- Professional Certification:Standardized examination preparation and credential verification.
- Skill Development:Targeted procedural training for emerging clinical techniques.
Regulatory compulsion anchors Continuing Education; technology innovation drives Medical Training.
End User:
Capital availability and technical staffing levels create distinct purchasing modalities across institutional categories.
- Medical Schools:Comprehensive platform deployments integrating LMS, simulation, and assessment across preclinical and clinical years. Procurement emphasizes scalability and accreditation alignment in the US and UK markets.
- Nursing Colleges:Cloud-first strategies minimizing IT infrastructure expenditure, particularly across India's Karnataka and Tamil Nadu states where private institutions scale digital infrastructure rapidly.
- Research Institutes:Specialized platforms supporting protocol training and regulatory submission preparation.
- Hospitals:Workforce credentialing systems embedded within HR infrastructure, with preference in Japan for enterprise learning platforms integrating directly with personnel management systems.
- Healthcare Organizations:Multi-facility deployments standardizing training across distributed clinical sites.
Budget concentration sits with Medical Schools; growth velocity clusters with Nursing Colleges.
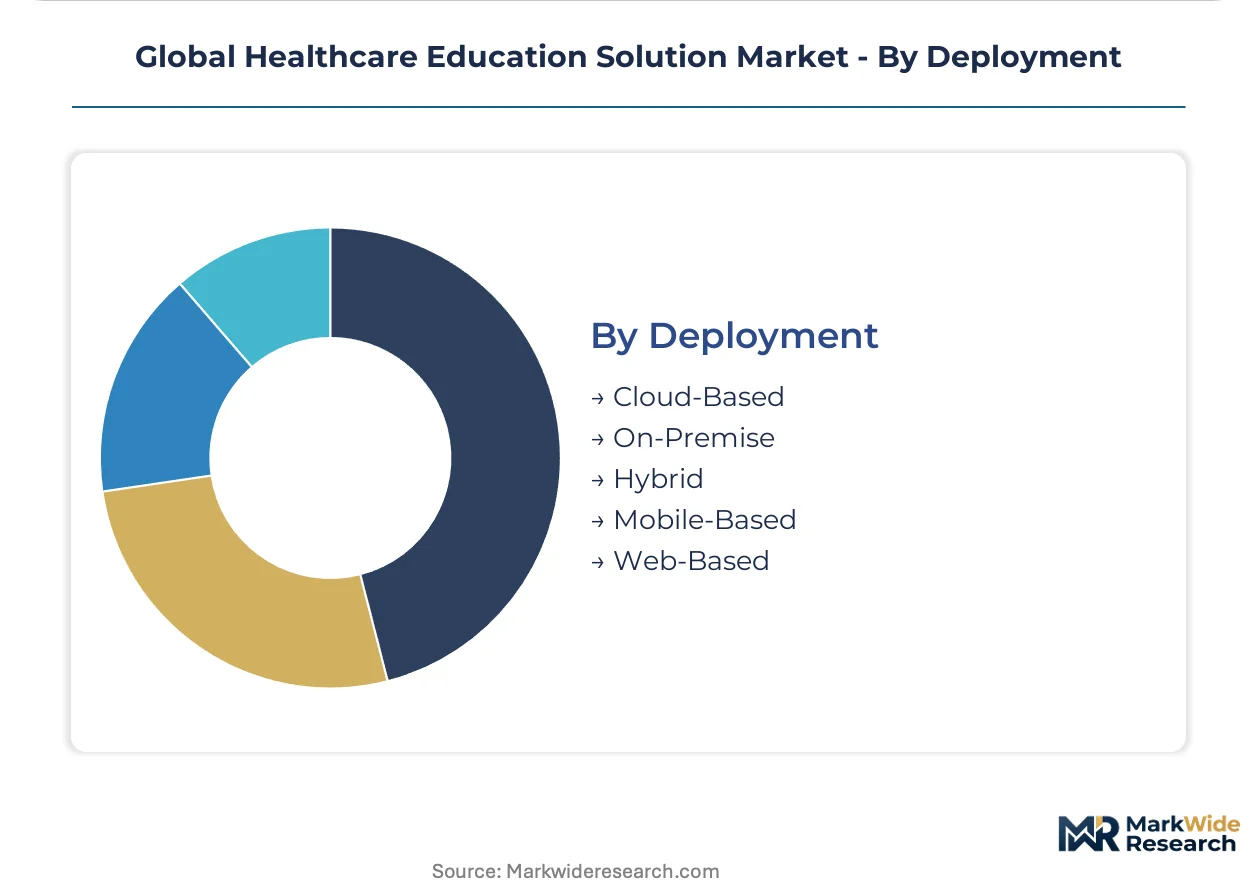
Deployment:
Infrastructure ownership preferences split between capital conservation and data sovereignty requirements.
- Cloud-Based:Subscription models eliminating hardware procurement cycles. India's nursing colleges favor this modality to bypass IT capital expenditure, while EU institutions navigate GDPR data residency constraints.
- On-Premise:Local server installations serving high-fidelity simulation hardware requiring minimal latency. German hospital networks maintain this architecture for surgical training centers with sensitive patient data integration.
- Hybrid:Split architectures preserving sensitive records on-premise while leveraging cloud scalability for general content.
- Mobile-Based:Smartphone-optimized interfaces for point-of-care reference and microlearning.
- Web-Based:Browser-accessible platforms requiring no local installation.
Procurement momentum favors Cloud-Based; specialized use cases sustain On-Premise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA quality system regulation anchors procurement volume in the United States, while EMA MDR compliance requirements and India's CDSCO qualification norms reshape investment patterns across their respective jurisdictions.
United States
Medical schools in Massachusetts and California are scaling simulation-based curricula to address LCME-mandated clinical competency requirements. FDA's device-specific training documentation mandates create recurring revenue streams for content management vendors serving domestic manufacturers. The Greater Boston cluster concentrates academic medical center procurement budgets for integrated LMS and assessment platforms.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia deploy portable VR surgical training configurations to meet procedural volume requirements without resident staffing expansion. EMA MDR and ISO 13485 training requirements compel healthcare organizations to maintain auditable competency records with automated audit trails. Siemens Healthineers anchors hospital-based education contracts through its simulation hardware portfolio.
Japan
Enterprise learning platforms embedding workforce credentialing directly into hospital HR systems capture procurement preference in Tokyo and Osaka metropolitan areas. METI standards for medical device operator qualification drive demand for assessment tools with built-in compliance reporting. The Kanto region concentrates deployment of cloud-native architectures supporting thousands of concurrent users.
India
Private nursing colleges in Karnataka and Tamil Nadu states scale digital infrastructure through cloud-first strategies minimizing IT capital expenditure. CDSCO tightening of qualification norms for medical device sales representatives expands the addressable market for professional certification platforms. Bangalore and Chennai clusters favor subscription-based licensing for simulation content over capital-intensive equipment ownership.
United Kingdom
Medical schools in London and the Southeast integrate GDPR-compliant student record systems with accreditation-aligned assessment platforms. NHS workforce credentialing requirements drive procurement of learning management systems with built-in compliance reporting for continuing professional development. The Oxford-Cambridge corridor concentrates research institute investment in specialized protocol training platforms.
Global Healthcare Education Solution Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the healthcare education solution market. Medical device manufacturers with simulation hardware portfolios anchor premium-tier hospital contracts, while enterprise software vendors capture scalable LMS procurement through HR system integration. The market structure fragments across three strategic archetypes: integrated device-education conglomerates, pure-play simulation specialists, and enterprise learning platform providers. Dominant competitive moves include strategic partnerships between hardware manufacturers and content libraries, plus geographic expansion through cloud-native deployment models that bypass local infrastructure requirements.
Within the integrated device-education tier, GE Healthcare and Siemens Healthineers represent archetypes leveraging existing hospital relationships to anchor education contracts. Stryker occupies a position exemplifying the simulation hardware specialist model, while SAP anchors the enterprise software vector integrating workforce credentialing with personnel management infrastructure. These three companies collectively illustrate how vendor origin—medical technology versus enterprise software—determines procurement channel access and contract structure.
| Leading Market Players |
|---|
| GE Healthcare |
| Stryker |
| Siemens Healthineers |
| Medtronic |
| SAP |
| Adobe |
| Oracle |
| Elsevier |
| FUJIFILM Holdings |
| Others |
Supply & Pricing Matrix
FDA quality system regulation gates both vendor qualification and price differentiation in the healthcare education solution market, compelling manufacturers to maintain auditable training documentation that separates premium-tier compliance platforms from utility-focused alternatives. This regulatory threshold simultaneously constrains supply-side entry and enables certified vendors to command sustained pricing power across hospital networks and medical device manufacturers.
Pricing Analysis
Geographic price spreads between Germany and India's nursing colleges exceed threefold for equivalent simulation content libraries, reflecting divergent purchasing power and regulatory stringency. Subscription-based SaaS tiers dominate procurement, with pricing stratifying across enterprise, institutional, and individual licensing levels based on user volume scale and ISO 13485 certification integration. Cost compression in hardware components intensifies pricing pressure on perpetual-license simulation platforms, while cloud-native assessment tools with built-in MDR compliance reporting face limited price sensitivity among European hospital networks.
Supply Chain Analysis
Inventory lead times for haptic feedback devices and VR headsets from Taiwan and South Korea extend delivery windows for simulation platform deployments, particularly affecting German hospital networks scaling emergency response training infrastructure. Component sourcing draws from specialized semiconductor foundries in Taiwan, optical sensor manufacturers in Japan, and precision actuator suppliers in Germany. Single-source vulnerability concentrates in advanced haptic engine production, while distribution runs through authorized medical device channels requiring FDA or CE marking validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
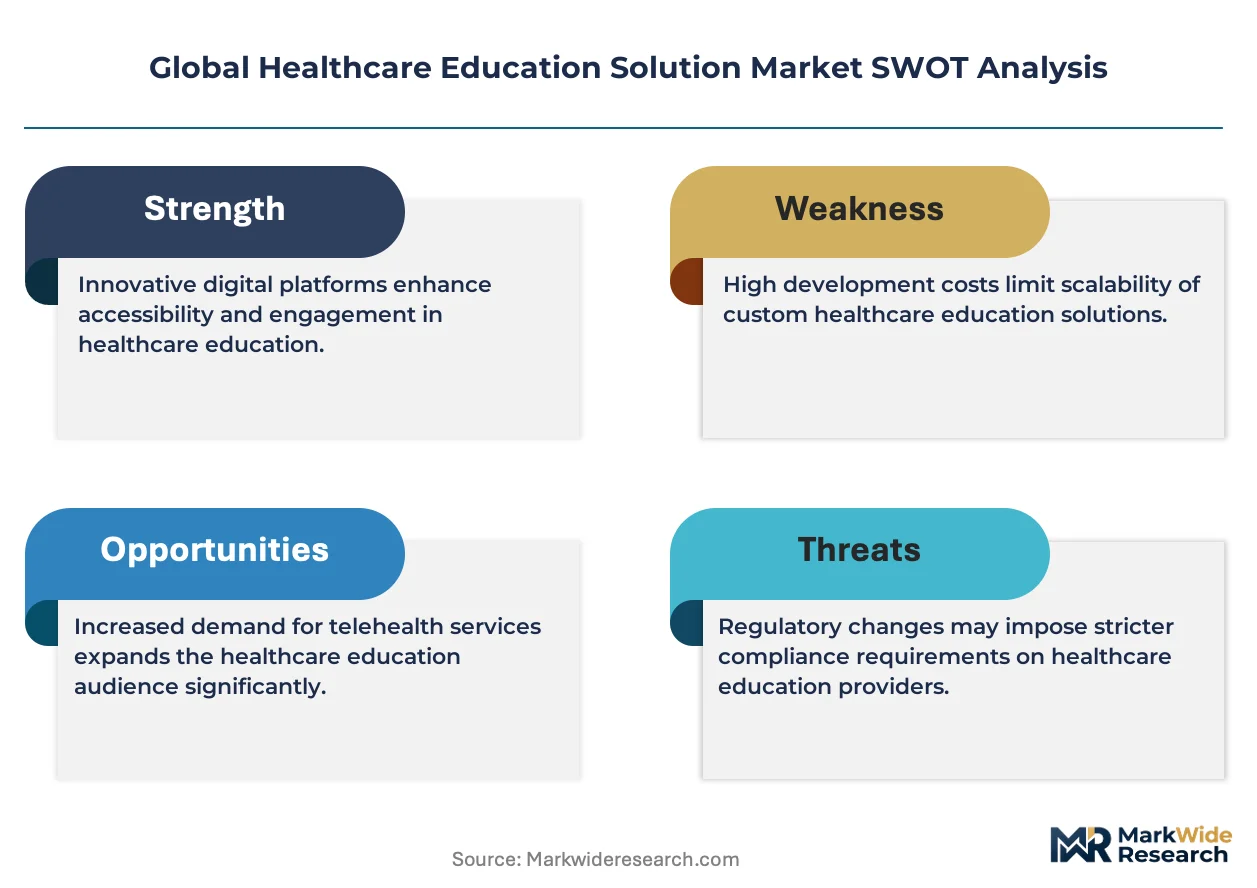
The healthcare education solution market rewards vendors possessing rare combinations of regulatory certification expertise and immersive hardware engineering capability, creating acquisition premiums for firms bridging these skill domains.
For Market Incumbents: Fortify market position through backward integration into physiological modeling engine development, reducing dependency on third-party biometric software licensors. Siemens Healthineers and GE Healthcare should accelerate cloud-native architecture migration to defend against SaaS-native entrants targeting India's nursing college expansion, while embedding MDR-compliant audit trails deeper into hospital HR system integrations. For New Entrants and Emerging Players: Content refresh velocity gaps in India's southern states present immediate white-space opportunity, where private nursing colleges prioritize subscription libraries over capital-intensive equipment ownership. Target Karnataka and Tamil Nadu with usage-based simulation content licensing, leveraging cloud deployment to bypass local infrastructure requirements and establish recurring revenue relationships before hardware incumbents adapt pricing models. For Investors and Strategic Acquirers: EMA MDR enforcement reshapes the acquisition landscape toward assessment platforms with pre-validated compliance reporting modules. Long-term viability centers on vendors capturing hospital network standardization decisions across the projection horizon. Prioritize targets combining VR-physiological modeling convergence with established FDA 510(k) documentation pathways, watching for CDSCO qualification norm tightening as India's inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Architecture Migration | Enables SaaS pricing capture among India's capital-constrained nursing colleges scaling digital infrastructure. |
| MDR Compliance Module Development | Secures procurement preference from German hospital networks requiring automated audit trail capabilities. |
| Hospital HR System Integration | Captures recurring enterprise contracts in Japan's Tokyo-Osaka metropolitan corridor through METI-aligned credentialing. |
| VR-Physiological Modeling Convergence | Compresses emergency response training costs for German community hospitals without resident staffing expansion. |
| Subscription Content Licensing Pivot | Aligns vendor relationships with Karnataka and Tamil Nadu procurement preferences minimizing IT capital expenditure. |
Research Methodology
A spread of perspectives from medical school curriculum directors, hospital biomedical engineering leads, nursing college procurement officers, and medical device regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary field engagement combined structured interviews with secondary validation against FDA 510(k) filings, EMA MDR technical documentation, CDSCO qualification guidelines, and hospital GPO contract databases. Bottom-up demand modeling across deployment modes triangulated with top-down market sizing from regulatory filing revenue disclosures.
Segmentation dimensions modeled encompass product architecture, application category, end-user institution type, and deployment modality, with additional granularity on regional regulatory cluster variations. CAGRs derive from installed base expansion rates, replacement cycle compression, and pricing trajectory assumptions across the projection horizon. Industry-specific forecast inputs include simulation hardware cost decline curves and nursing faculty shortage severity indices by geography.
Forecasts assume regulatory continuity in FDA quality system enforcement, EMA MDR implementation timelines, and India's CDSCO qualification expansion; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare
Global Vagus Nerve Stimulation Market
Healthcare
Oncology Adjuvants Market
Healthcare
US Interventional Radiology Market
Healthcare
Desmoid Tumor Market
Healthcare
Endoscopy Device Market
Healthcare
Wearable Cardioverter Defibrillators Market
Healthcare
Ischemic Cerebral Stroke Market
Healthcare
Zellweger Spectrum Disorders Market
Healthcare
Neurocutaneous Disorders Market
Healthcare
Healthcare Contract Sales Organizations Market
Healthcare
Depression Drugs Market
Healthcare
Venous Device Market
Healthcare
Absorbable PGLA Surgical Sutures Market
Healthcare
Medical Device Regulatory Affairs Market
Healthcare
Mental Retardation Treatment Market
Healthcare
Surgical Glue Market