
 Global Document Outsourcing Market | 2026-2036
Global Document Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Document Outsourcing Market Foresight
The shift from captive document operations toward third-party managed print services is broadening addressable scope for specialized providers. Ricoh Co. Ltd. leverages its integrated hardware-software portfolio to anchor managed document services across enterprise accounts. Xerox Corporation competes through channel density and workplace solutions that sustain recurring revenue streams. Iron Mountain Incorporated dominates physical and digital archiving with compliance-grade infrastructure that controls regulatory risk for clients.
Document outsourcing encompasses the delegation of document lifecycle management — including printing, scanning, conversion, archival, and data extraction — to external specialists operating under service-level agreements with defined turnaround times and security protocols. Its primary commercial purpose is to reduce fixed capital in print infrastructure while ensuring information governance standards. Printing services and archiving solutions command the largest share of service-type revenue, reflecting entrenched enterprise reliance on hybrid physical-digital workflows. Cloud-based platforms represent the fastest-expanding delivery model as organizations prioritize scalable consumption over on-premises equipment ownership.
FDA record-keeping requirements for pharmaceutical trials, HIPAA privacy safeguards for healthcare records, and GDPR data processing rules in Europe collectively elevate compliance complexity and drive demand for certified outsourcing partners. ISO 27001 and SOC 2 Type II attestations increasingly function as baseline qualifiers in vendor selection processes. Stakeholders must weigh geographic data residency requirements against cloud-platform agility when structuring multi-year outsourcing contracts.
Market Dynamics
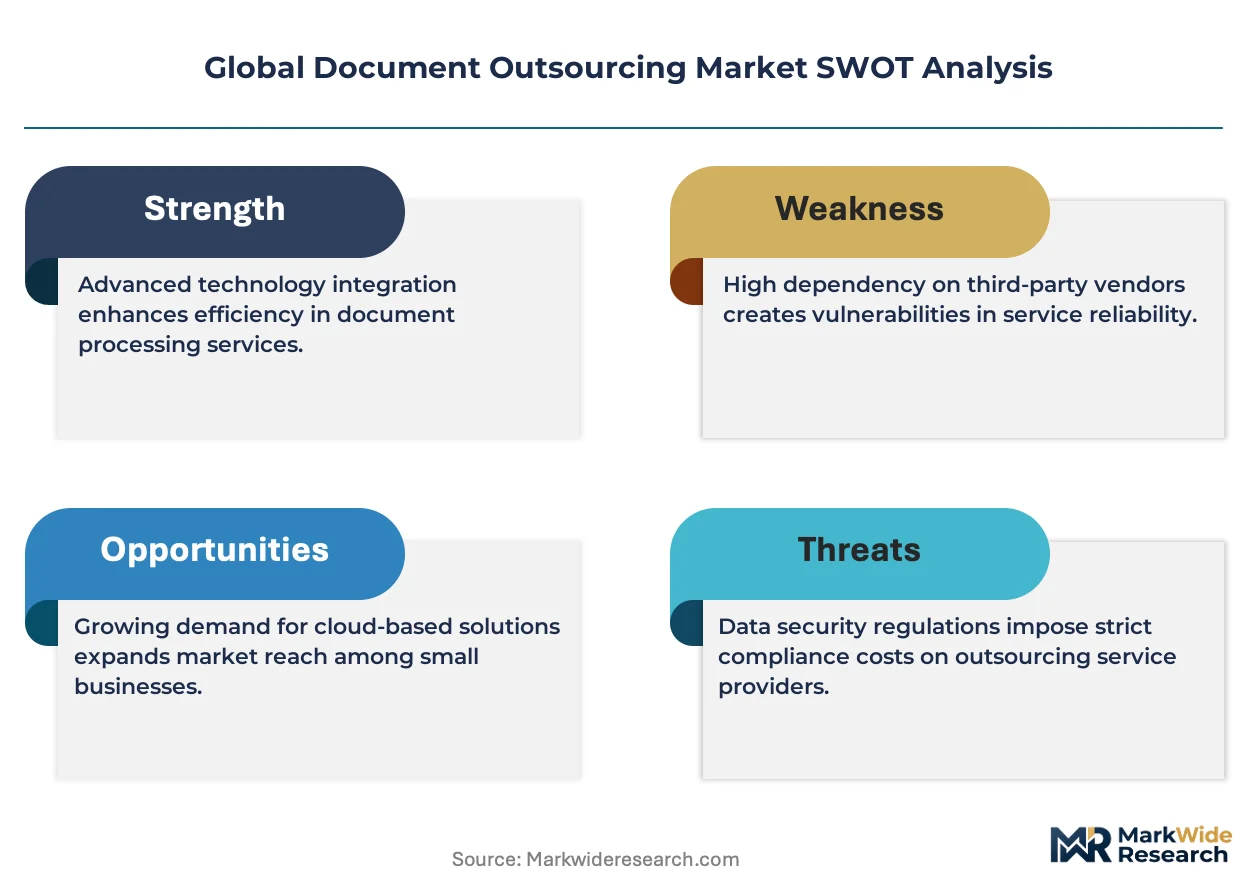
Healthcare providers are accelerating delegation of medical records management to external specialists as HIPAA compliance pressures intensify and cloud infrastructure matures. This structural shift from captive print operations toward third-party service models is compressing capital deployment cycles across enterprise accounts.
Growth Catalysts
- HIPAA Privacy Rule Enforcement:Healthcare systems face escalating audit frequency and penalty exposure, driving demand for certified outsourcing partners with SOC 2 Type II attestations and dedicated compliance infrastructure.
- Hybrid Workflow Persistence:Enterprise reliance on simultaneous physical and digital document processing sustains demand for integrated managed print services that bridge legacy paper systems with cloud repositories.
- India:The country's national IT regulator and data protection framework evolution is prompting multinational enterprises to establish compliant document processing centers in Bangalore and Hyderabad.
Market Restraints
- Data Residency Friction:GDPR Article 44 cross-border transfer restrictions and emerging localization mandates in Germany and France fragment service delivery architectures and inflate compliance overhead.
- Input Cost Volatility:Specialized secure courier networks and bonded archival facilities command premium pricing that compresses margins for multi-site contract structures.
- Substitution Pressure:Native digital workflows and born-digital document systems in software and fintech verticals bypass traditional scanning and conversion service demand entirely.
Strategic Opportunities
- Brazil:ANVISA pharmaceutical documentation requirements and underdeveloped domestic archiving infrastructure create white space for compliance-grade outsourcing entrants.
- AI-Document Convergence:Machine learning extraction layered atop scanning services enables value-added analytics contracts that extend customer lifetime value beyond commodity processing.
- Japan METI Digitalization Push:Government incentives for SME administrative efficiency are accelerating cloud-based document platform adoption among manufacturing supply chain participants.
Industry Challenges
- ISO 27001 Certification Burden:Extended audit timelines and recurring surveillance costs strain mid-tier providers attempting to compete for enterprise and government contracts.
- Legacy ERP Integration Complexity:Custom API development for SAP and Oracle document management modules inflates implementation costs and extends sales cycles for hybrid cloud deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Document Outsourcing Market |
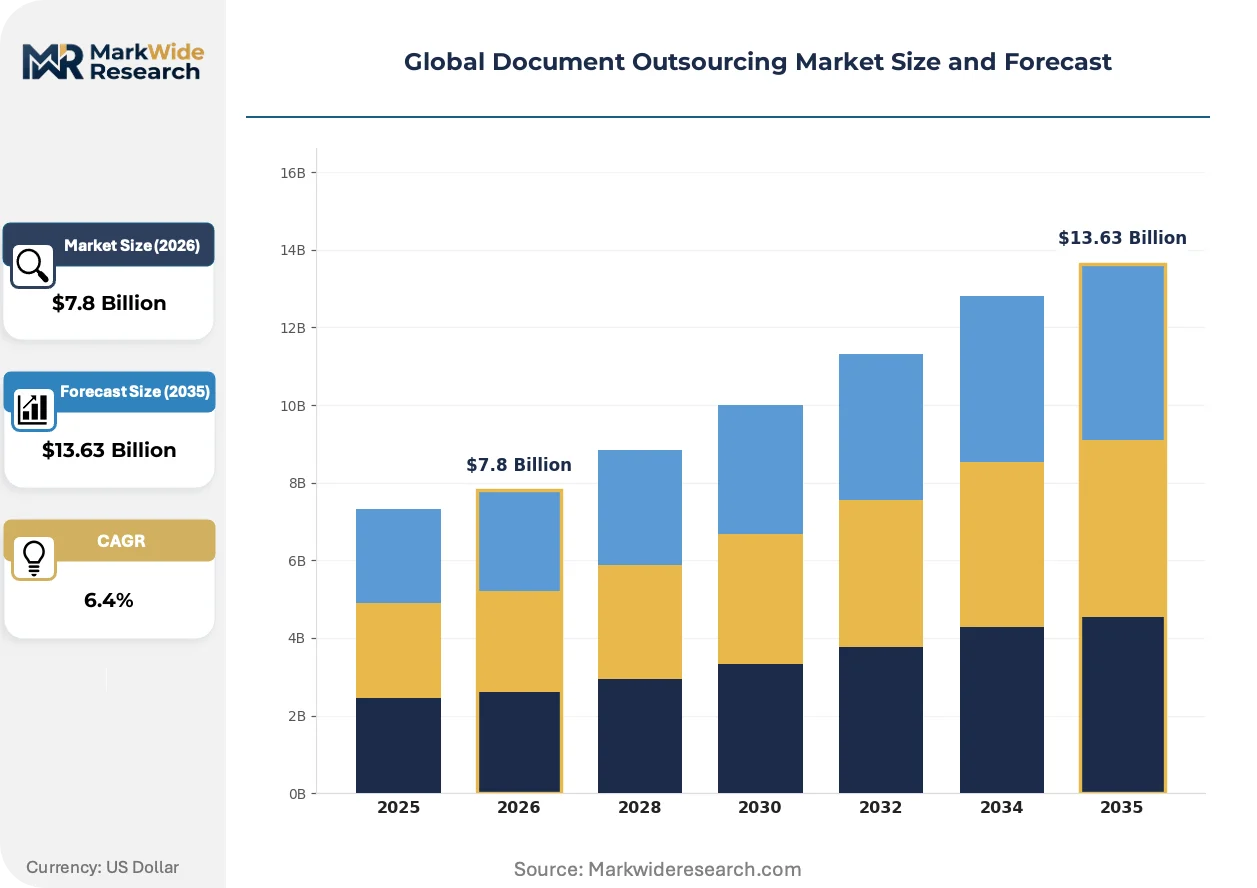
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Printing Services, Scanning Services, Document Conversion, Data Entry, Archiving Solutions Application: Legal Documentation, Financial Records, Educational Materials, Healthcare Records, Government Files Client Type: Small & Medium Businesses, Large Corporations, Non-governmental Organizations, Educational Institutions, Public Sector Units Delivery Model: Onshore Outsourcing, Nearshore Outsourcing, Offshore Outsourcing, Hybrid Solutions, Cloud-based Platforms |
| Companies Covered | Ricoh Co. Ltd., Iron Mountain Incorporated, HP Inc., Xerox Corporation, Canon Inc., Lexmark International Inc., Fujifilm Business Innovation Co. Ltd., Konica Minolta Inc., Accenture Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Document Outsourcing Market Shifts & Advancements
Intelligent document processing platforms are absorbing optical character recognition workloads while embedding compliance automation directly into workflow engines. This technological infusion is compressing the boundary between raw scanning services and analytics-enabled information governance.
Intelligent character recognition with handwriting parsing is absorbing manual data entry functions previously performed by offshore keying operations. Pharmaceutical trial sponsors and insurance claims processors in the United States are deploying these tools at scale. The technology is absorbing labor-intensive verification steps and reallocating human capital toward exception handling and quality assurance functions.
GDPR Article 17 right-to-erasure mandates are forcing document archiving providers to implement granular indexing and automated deletion workflows across multi-tenant storage environments. European healthcare networks and financial institutions face the steepest compliance retrofit costs. German hospital systems are responding by consolidating vendor relationships with partners offering certified data lineage tracking.
Subscription consumption models are displacing per-page pricing structures in enterprise managed print contracts. Channel partners and direct sales teams face compressed commission structures and extended customer success obligations. This transition is most visible in United States legal services and accounting verticals where firms prioritize predictable operational expenditure over capital equipment ownership.
Global Document Outsourcing Market Segmentation
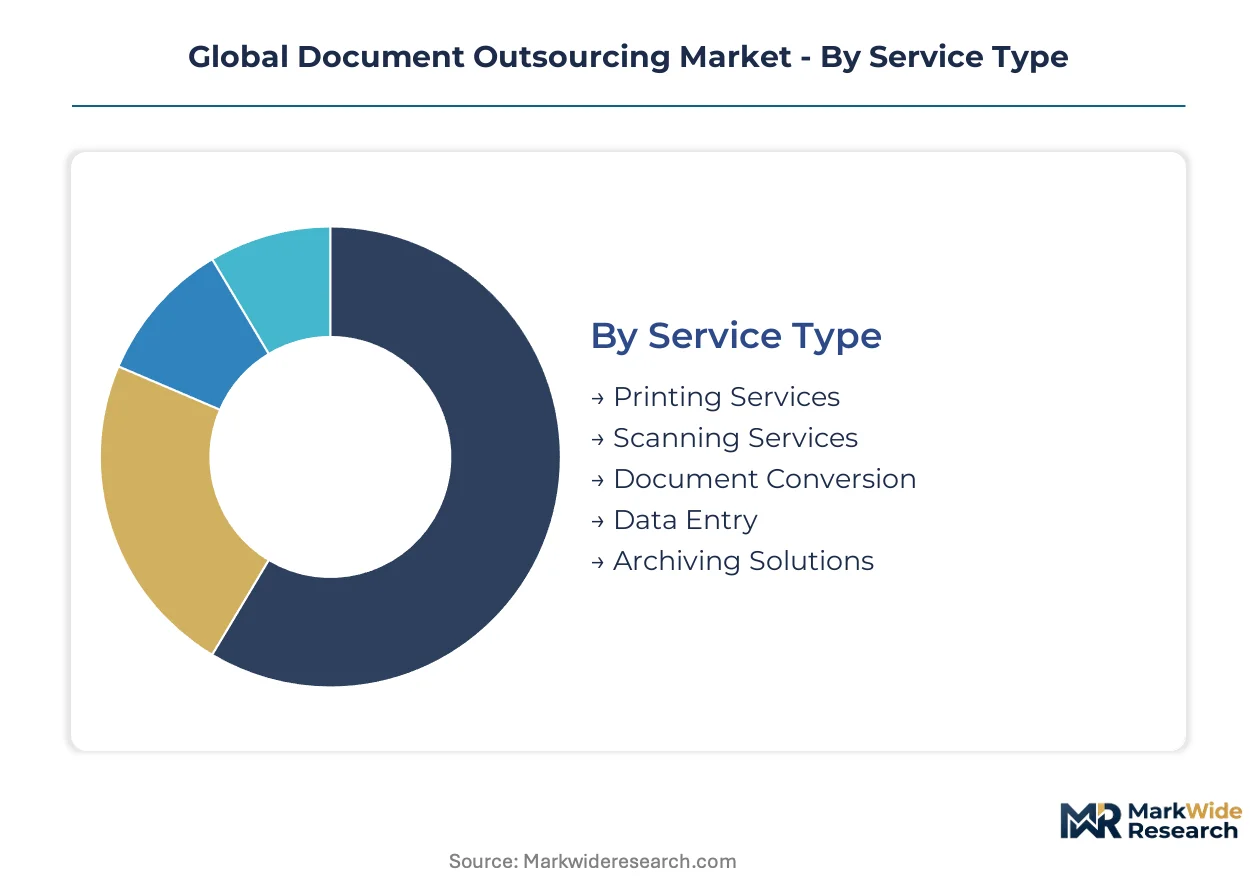
Document outsourcing providers structure service portfolios around capital intensity gradients and compliance-grade infrastructure requirements. Segmentation reveals where fixed asset deployment concentrates and which delivery architectures command premium pricing.
Service Type:
Capital intensity varies sharply across document lifecycle services, with physical infrastructure requirements dictating margin structures and competitive moats.
- Printing Services:High-volume production facilities with secure print management systems dominate enterprise contracts. Financial institutions in the United States and Germany sustain demand for compliance-grade output with audit trails and chain-of-custody documentation.
- Archiving Solutions:Climate-controlled vaults and digitization pipelines require substantial real estate and bonded security infrastructure. Healthcare networks facing HIPAA audit pressures are consolidating vendor relationships with providers offering SOC 2 Type II certified facilities.
- Scanning Services:Production-grade capture centers with OCR and ICR capabilities.
- Document Conversion:Format migration and legacy system integration services.
- Data Entry:Offshore keying operations facing automation displacement from intelligent character recognition platforms.
Archiving Solutions absorbs the bulk of installed capacity; Cloud-integrated scanning workflows are expanding most quickly.
Application:
Regulatory density determines outsourcing penetration rates, with sectors facing mandatory retention periods and audit scrutiny showing highest third-party adoption.
- Healthcare Records:HIPAA Privacy Rule enforcement and FDA 21 CFR Part 11 compliance requirements drive demand for certified partners with dedicated compliance officers and encrypted transmission protocols. Hospital systems in the United States are accelerating cloud migration for patient files.
- Legal Documentation:Court filing deadlines and discovery obligations impose strict turnaround requirements. Law firms prioritize vendors offering litigation support services with native integration into e-discovery platforms.
- Financial Records:SEC retention mandates and SOX audit trail requirements.
- Government Files:Classification handling and FOIA response workflows.
- Educational Materials:Transcript processing and credential verification services.
Healthcare Records commands the steepest compliance premiums; Legal Documentation shows the sharpest uptake in subscription pricing models.
Client Type:
Contract scale and procurement sophistication separate segments, with enterprise accounts driving standardization of service-level agreements.
- Large Corporations:Multi-site managed print service contracts with global master agreements and centralized billing. Manufacturing supply chains in Japan and Germany are consolidating vendor panels under METI and KBA efficiency directives.
- Small & Medium Businesses:Cost-sensitive buyers favoring per-page pricing and minimal capital commitment. Cloud-based platforms are displacing on-premises equipment ownership in this tier.
- Public Sector Units:RFP-driven procurement with domestic content requirements.
- Educational Institutions:Seasonal volume spikes around enrollment periods.
- Non-governmental Organizations:Grant-funded documentation with restricted overhead ratios.
Large Corporations anchor vendor revenue stability; Small & Medium Businesses are climbing the fastest toward cloud-native delivery.
Delivery Model:
Geographic arbitrage opportunities are narrowing as data residency mandates reshape location strategy.
- Cloud-based Platforms:Scalable consumption models with API-first architecture enabling ERP integration. GDPR Article 44 transfer restrictions are forcing European enterprises toward EU-sovereign cloud instances.
- Onshore Outsourcing:Domestic processing for classified or sensitive materials with no cross-border exposure. Defense contractors and government agencies mandate this model exclusively.
- Nearshore Outsourcing:Time-zone alignment with moderate labor cost advantages.
- Offshore Outsourcing:India-based processing centers facing data localization headwinds.
- Hybrid Solutions:Mixed architectures combining on-premises capture with cloud repositories.
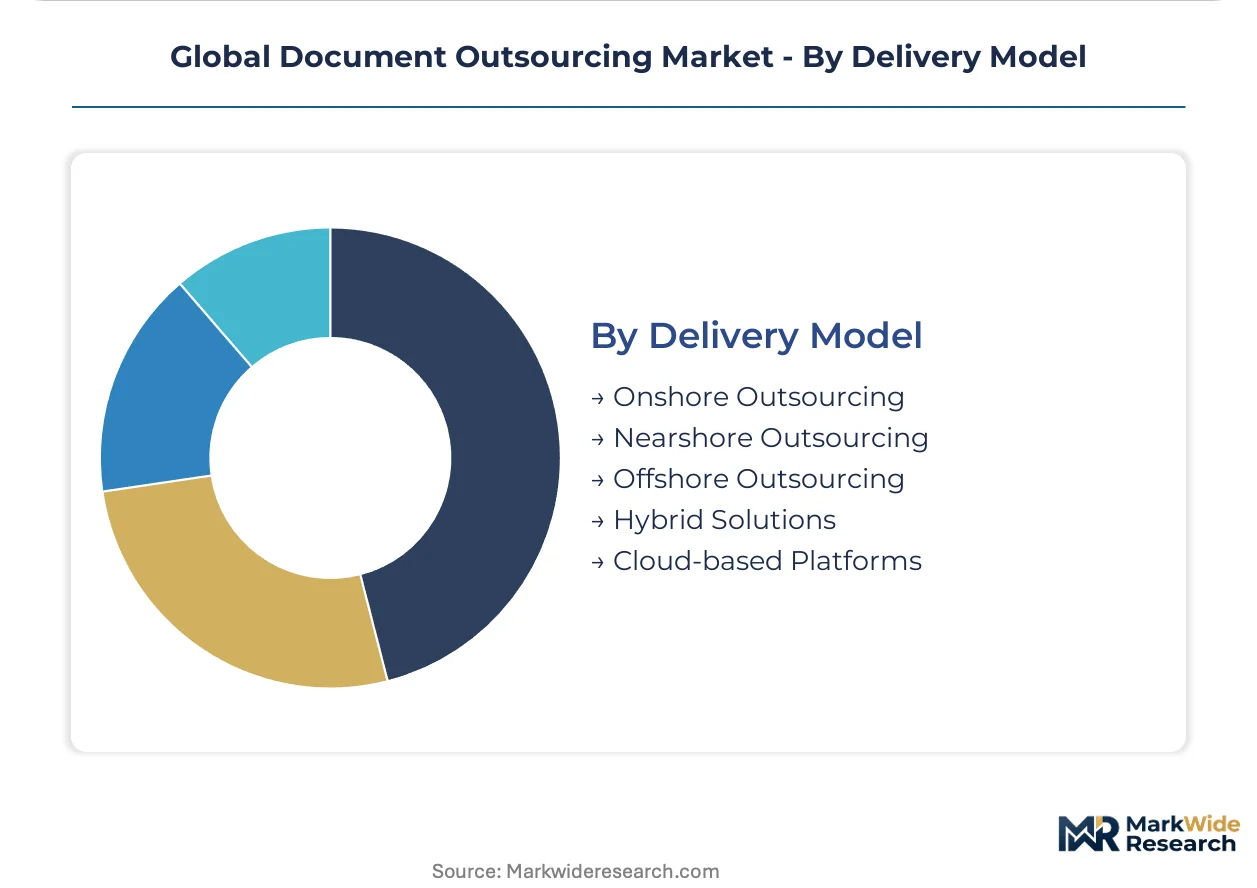
Onshore Outsourcing retains the highest security premiums; Cloud-based Platforms are gaining share fastest among digitally mature enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pulp and paper feedstock availability in the Nordic region anchors document outsourcing infrastructure investments. Data residency mandates and compliance-grade facility requirements reshape geographic deployment strategies across major economies.
United States
HIPAA Privacy Rule enforcement drives healthcare systems toward certified outsourcing partners with SOC 2 Type II infrastructure. FDA 21 CFR Part 11 requirements for pharmaceutical documentation sustain demand for compliant archiving solutions. Hospital networks in Boston and Minneapolis accelerate cloud migration for patient record management.
Germany
GDPR Article 44 cross-border transfer restrictions fragment service delivery architectures for multinational enterprises. KBA efficiency directives push manufacturing supply chains toward consolidated vendor panels with certified data lineage tracking. Industrial clusters in Bavaria and Baden-Württemberg prioritize EU-sovereign cloud instances for document processing.
Japan
METI digitalization incentives accelerate SME adoption of cloud-based document platforms across manufacturing supply chains. JIS standards compliance requirements elevate certification burdens for domestic and foreign service providers. Document processing demand concentrates in Kanto and Kansai metropolitan corridors.
India
Data localization mandates from the national IT regulator prompt multinational enterprises to establish compliant processing centers in Bangalore and Hyderabad. Offshore document processing faces evolving data protection framework constraints. Domestic BPO infrastructure expands to serve both export and captive enterprise requirements.
Brazil
ANVISA pharmaceutical documentation requirements create white space for compliance-grade outsourcing entrants. Underdeveloped domestic archiving infrastructure elevates capital deployment requirements for certified facility construction. São Paulo anchors demand for secure document lifecycle management services.
Global Document Outsourcing Market Competitive Landscape
Global majors compete with regional champions across compliance certification and infrastructure density dimensions. The vendor base separates into hardware-integrated platforms, pure-play archiving specialists, and IT services conglomerates with document capabilities. Three archetypes dominate: integrated hardware-software providers, compliance-grade physical infrastructure operators, and cloud-native workflow platforms. Competitive moves concentrate on M&A for geographic coverage and strategic partnerships for ERP integration.
Within the integrated hardware-software tier, Ricoh Co. Ltd. and Xerox Corporation exemplify providers anchoring managed document services through captive equipment portfolios. Iron Mountain Incorporated occupies a distinct position as a compliance-grade archiving specialist with physical and digital infrastructure. These three companies represent the dominant competitive anchors across enterprise contract structures.
| Leading Market Players |
|---|
| Ricoh Co. Ltd. |
| Iron Mountain Incorporated |
| HP Inc. |
| Xerox Corporation |
| Canon Inc. |
| Lexmark International Inc. |
| Fujifilm Business Innovation Co. Ltd. |
| Konica Minolta Inc. |
| Accenture Plc |
| Others |
Supply & Pricing Matrix
Intelligent document processing platforms are compressing cost economics for scanning and data extraction while simultaneously concentrating supply among providers with AI development capabilities. This technological shift rewards vendors with captive machine learning infrastructure and squeezes margins for labor-dependent offshore operators.
Pricing Analysis
Service bundling separates compliance-grade archiving with SOC 2 Type II certification from unbundled commodity scanning. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and geographic delivery cost. Pricing pressure stems from intelligent character recognition displacing manual data entry in United States insurance and pharmaceutical verticals. Small and medium businesses exhibit highest price sensitivity, while healthcare networks facing HIPAA audit exposure accept premium pricing for certified infrastructure.
Supply Chain Analysis
Direct-to-enterprise sales teams handle large corporation contracts with global master agreements, while channel partners serve cost-sensitive SMB tiers. Production-grade scanning hardware concentrates in Japan and Germany, with optical character recognition software development anchored in the United States and India. Secure courier networks and bonded archival facilities draw from specialized logistics providers with regulatory clearances. Single-source vulnerability runs through ISO 27001 certification bodies with extended audit timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native document platforms are displacing on-premises equipment ownership, compressing the window for legacy hardware providers to transition toward subscription revenue models.
For Market Incumbents: Deploy compliance certification as a defensive moat by accelerating SOC 2 Type II and ISO 27001 investments ahead of mid-tier competitors. Consolidate vendor relationships with healthcare networks facing intensifying HIPAA audit frequency. Native digital workflow substitution in software and fintech verticals threatens traditional scanning demand. For New Entrants and Emerging Players: The gap between premium certified archiving and economy-tier scanning services creates entry space for AI-enabled analytics providers. Brazil's underdeveloped domestic archiving infrastructure and ANVISA pharmaceutical documentation requirements offer white-space expansion. Target cloud-native workflow platforms with API-first architecture for rapid ERP integration. For Investors and Strategic Acquirers: Re-rating potential sits with compliance-grade physical infrastructure operators given data residency mandate expansion across Europe and Asia. Acquisition targets should demonstrate EU-sovereign cloud capabilities or certified data lineage tracking. Watch for GDPR Article 44 enforcement patterns as inflection signal for geographic arbitrage compression.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Certification Investment | SOC 2 Type II and ISO 27001 credentials unlock healthcare and government contract access. |
| AI-Enabled Document Extraction | Machine learning layers atop scanning services extend customer lifetime value beyond commodity processing. |
| Geographic Expansion | EU-sovereign cloud instances address GDPR Article 44 cross-border transfer restrictions. |
| Strategic Partnership | ERP integration agreements with SAP and Oracle reduce implementation friction for enterprise accounts. |
| Platform Integration | API-first architecture enables seamless connection between legacy capture systems and cloud repositories. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with document outsourcing executives, compliance officers at healthcare systems, procurement leads at financial institutions, and channel sales heads validated demand patterns. FDA 21 CFR Part 11 submissions, HIPAA audit reports, and GDPR enforcement actions supplemented quantitative sizing. Bottom-up service-type modeling and top-down macroeconomic triangulation reconciled volume estimates.
Data-stream reconciliation across cloud platform adoption metrics, managed print service contract values, and archiving facility capacity utilization informed projection mechanics. Segmentation dimensions spanned service type, application vertical, client scale tier, and delivery model architecture. CAGRs were derived from fitted trend analysis against historical penetration rates. HIPAA enforcement intensity and METI digitalization incentive uptake served as industry-specific demand inputs across the analysis window.
Inputs from regulatory databases and trade association surveys were available through the study window; gaps in real-time contract renewal data introduce uncertainty bands around near-term share shifts. Forecasts reflect documented assumptions regarding compliance cost trajectories and substitution rates from native digital workflows. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Global Software Outsourcing Market
Business Process Outsourcing (BPO)
Global Cloud Bpo Market
Business Process Outsourcing (BPO)
Public Cloud Business Process Services Market
Business Process Outsourcing (BPO)
UAE Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Business Process Automation (BPA) Market
Business Process Outsourcing (BPO)
Global Insurance Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Payroll Outsourcing Services Market
Business Process Outsourcing (BPO)
Indonesia Business Process Outsourcing Services Market
Business Process Outsourcing (BPO)
Healthcare BPO Market
Business Process Outsourcing (BPO)
Recruitment Process Outsourcing (RPO) Services Market
Business Process Outsourcing (BPO)
Business Processing Outsourcing Market
Business Process Outsourcing (BPO)
Business Process Management (BPM) Market
Business Process Outsourcing (BPO)
Global Outsourced Sales Service Market
Business Process Outsourcing (BPO)
Digitalization in Bpo Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Front Office BPO Services Market