
 Global Cloud Music Service Market | 2026-2036
Global Cloud Music Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Music Service Market Foresight
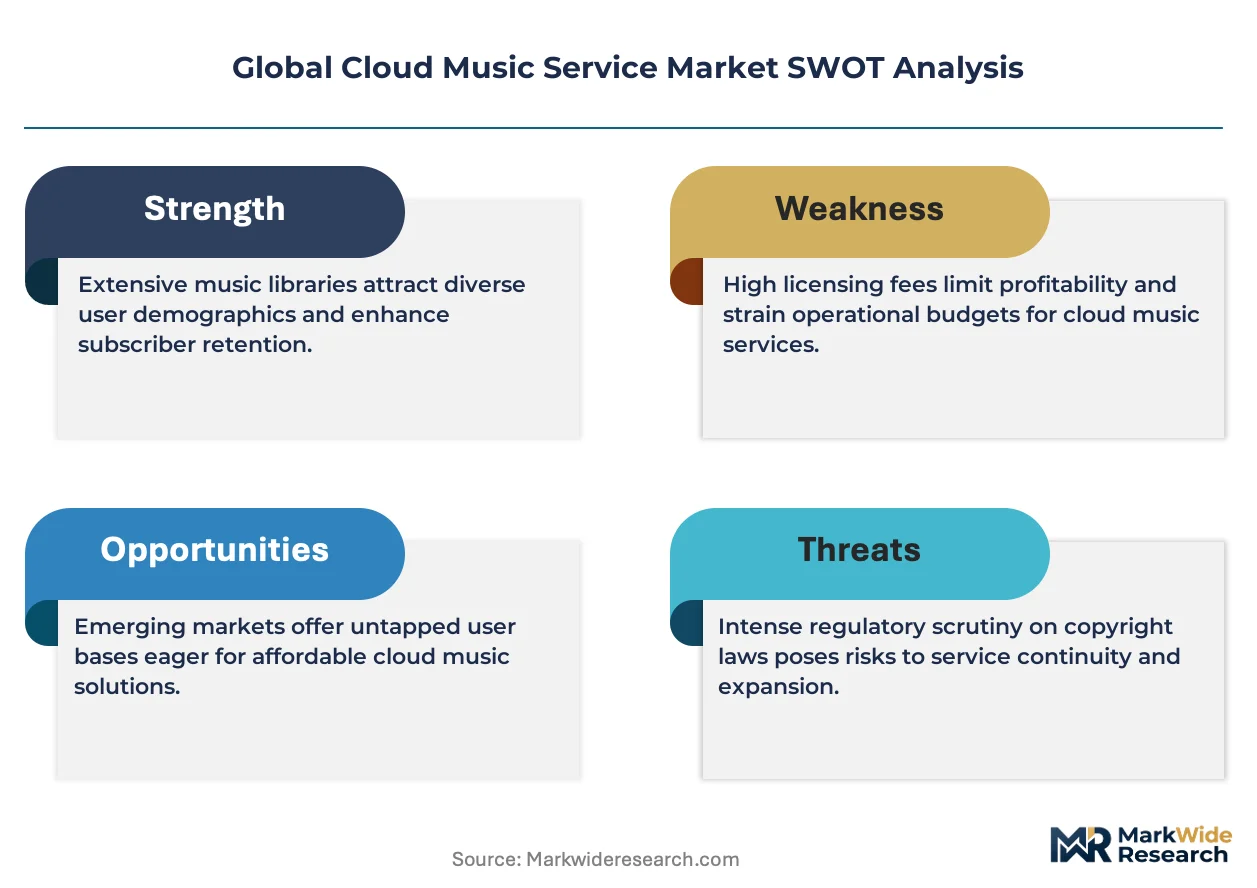
Subscription-based licensing is pivoting from static monthly fees toward dynamic, usage-calibrated tiers that bundle hi-resolution audio, offline sync, and family sharing. Spotify Technology leverages its podcast infrastructure to anchor listener retention beyond music catalogs. Apple Music differentiates through spatial audio integration and hardware-software cohesion across its ecosystem. Amazon Music competes on value bundling with Prime membership, extending reach into household purchasing workflows.
A cloud music service delivers audio content via internet-hosted streaming infrastructure, encoding files through lossy and lossless compression protocols for real-time playback across variable bandwidth conditions. The primary commercial purpose centers on replacing physical and owned-digital music ownership with continuous access to licensed catalogs. Ad-supported streaming captures volume-heavy user bases with lower per-account yield, while subscription-based tiers concentrate margin pools among committed listeners willing to pay for uninterrupted, high-fidelity experiences. Smart speakers represent a device compatibility segment where voice-activated discovery is accelerating household penetration and platform habit formation.
FCC net neutrality rulings in the US shape how internet service providers throttle or prioritize music streaming traffic, directly affecting playback quality and consumer satisfaction. GDPR and the EU AI Act impose strict boundaries on automated recommendation transparency and cross-border data residency for European subscribers. Stakeholders must monitor how Brazil's national data protection authority and China's SAMR licensing requirements evolve, as these jurisdictions increasingly dictate terms for algorithmic content curation and foreign platform market access.
Market Dynamics
Automotive OEMs embedding streaming into connected dashboards are redistributing platform power toward vehicle-native interfaces, compressing mobile app dependency while creating new data-sharing negotiations between carmakers and audio providers.
Growth Catalysts
- EU AI Act transparency mandates:Platforms redesigning recommendation engines for explainability are capturing premium subscriber trust in European markets where algorithmic accountability drives switching behavior.
- Smart speaker voice activation:Household penetration of voice-controlled discovery is habituating non-technical users to streaming platforms, expanding addressable bases beyond smartphone-native demographics.
- Brazil mobile infrastructure:Expanding 4G coverage in secondary cities is converting piracy-era listeners into paying subscribers through carrier-billed plans.
Market Restraints
- Content licensing cost inflation:Major label renegotiations every 2-3 years compress platform margins regardless of subscriber growth trajectories.
- US net neutrality uncertainty:FCC rulings permitting ISP throttling of streaming traffic degrade playback quality for price-sensitive tiers without recourse.
- GDPR data residency requirements:European subscriber data localization mandates fragment cloud infrastructure economics, raising compliance overhead.
Strategic Opportunities
- India price-sensitive tiers:Daily and weekly micro-subscription models adapted to prepaid mobile cultures can unlock volume in underpenetrated urban and semi-urban markets.
- Spatial audio hardware convergence:Integration with augmented reality headsets and spatial computing devices creates premium experiences beyond traditional stereo consumption.
- SAMR licensing clarity in China:Foreign platform market access rules stabilizing under China's State Administration for Market Regulation enable compliant entrants to serve Mandarin-language demand.
Industry Challenges
- Algorithmic fairness auditing:Platform engineering teams lack standardized methodologies to detect recommendation bias across multilingual catalogs and diverse listener demographics.
- Legacy automotive integration:Proprietary infotainment systems in older vehicle fleets resist API standardization, fragmenting development resources across OEM-specific protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Music Service Market |
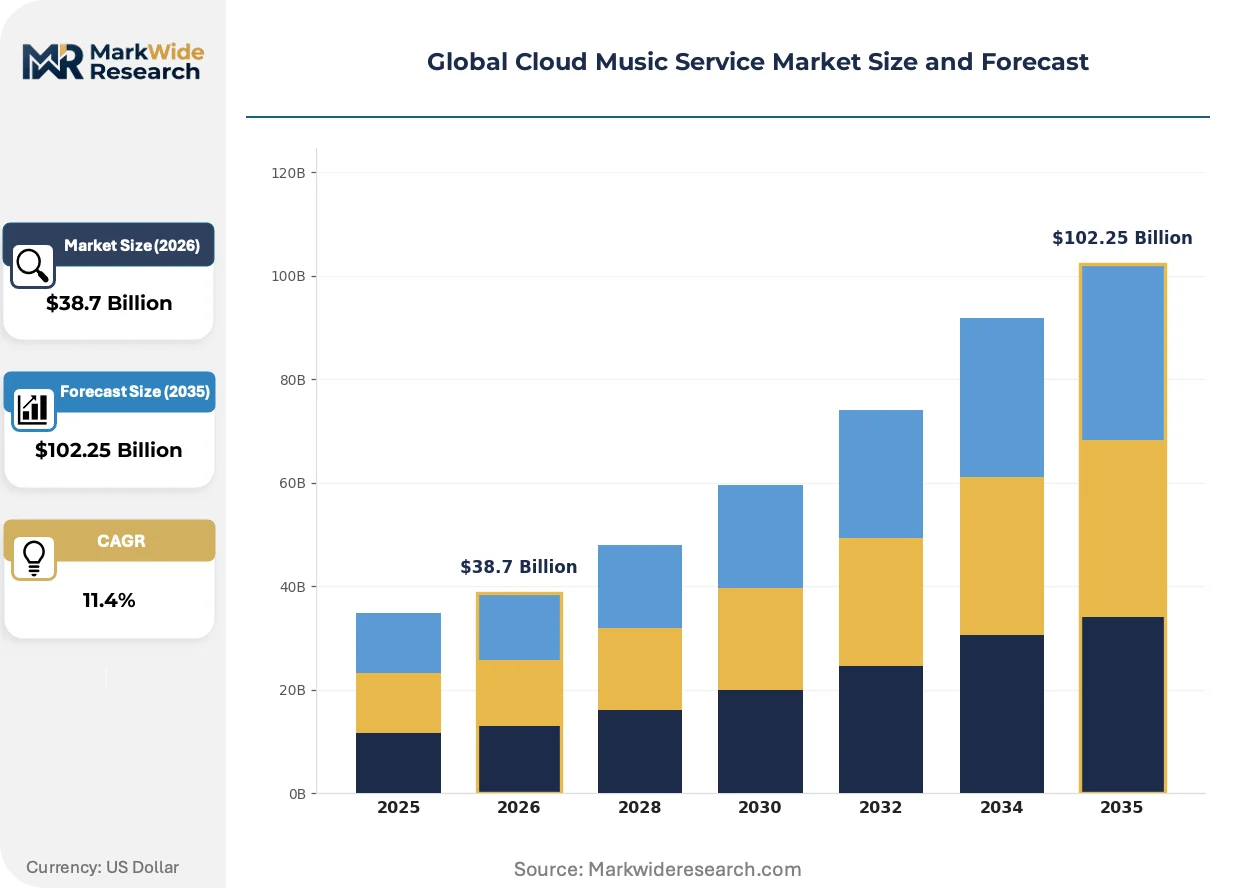
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription-Based, Ad-Supported, Freemium, Paid Downloads Device Compatibility: Smartphones, Tablets, Smart Speakers, Desktop Computers, Wearables User Demographic: Young Adults, Professionals, Students, Seniors, Music Enthusiasts Content Offering: On-Demand Streaming, Radio Stations, Playlists, Podcasts, Live Concerts |
| Companies Covered | Spotify Technology, Apple Music, Amazon Music, Tencent Music Entertainment Group, YouTube Music, NetEase, Deezer, SoundCloud, Pandora, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Music Service Market Shifts & Advancements
Audio delivery infrastructure is fragmenting into specialized components as platforms compete on latency, fidelity, and personalization depth rather than catalog size alone.
Edge computing nodes for audio streaming is modularizing how platforms distribute content, reducing round-trip latency for real-time lyrics synchronization and collaborative playlist editing. Live concert broadcasters and fitness application integrators are adopting these distributed architectures fastest. This modularization is compressing the advantage of centralized hyperscale data centers for latency-sensitive interactive features.
GDPR and the EU AI Act together mandate algorithmic explainability for automated playlist generation, forcing platforms to document recommendation logic for regulatory inspection. The industrial consequence is engineering resource reallocation toward transparency tooling rather than pure accuracy optimization. European subscriber segments are responding with elevated trust metrics, though implementation costs disadvantage smaller platforms.
Household listening behavior is consolidating around voice-first discovery, displacing typed search and browse-based exploration in domestic contexts. Smart speaker channels are capturing disproportionate session volume, with automotive voice interfaces following similar patterns. Brazil and India exhibit the fastest behavioral rotation toward voice, where text input friction remains higher across diverse language scripts.
Global Cloud Music Service Market Segmentation
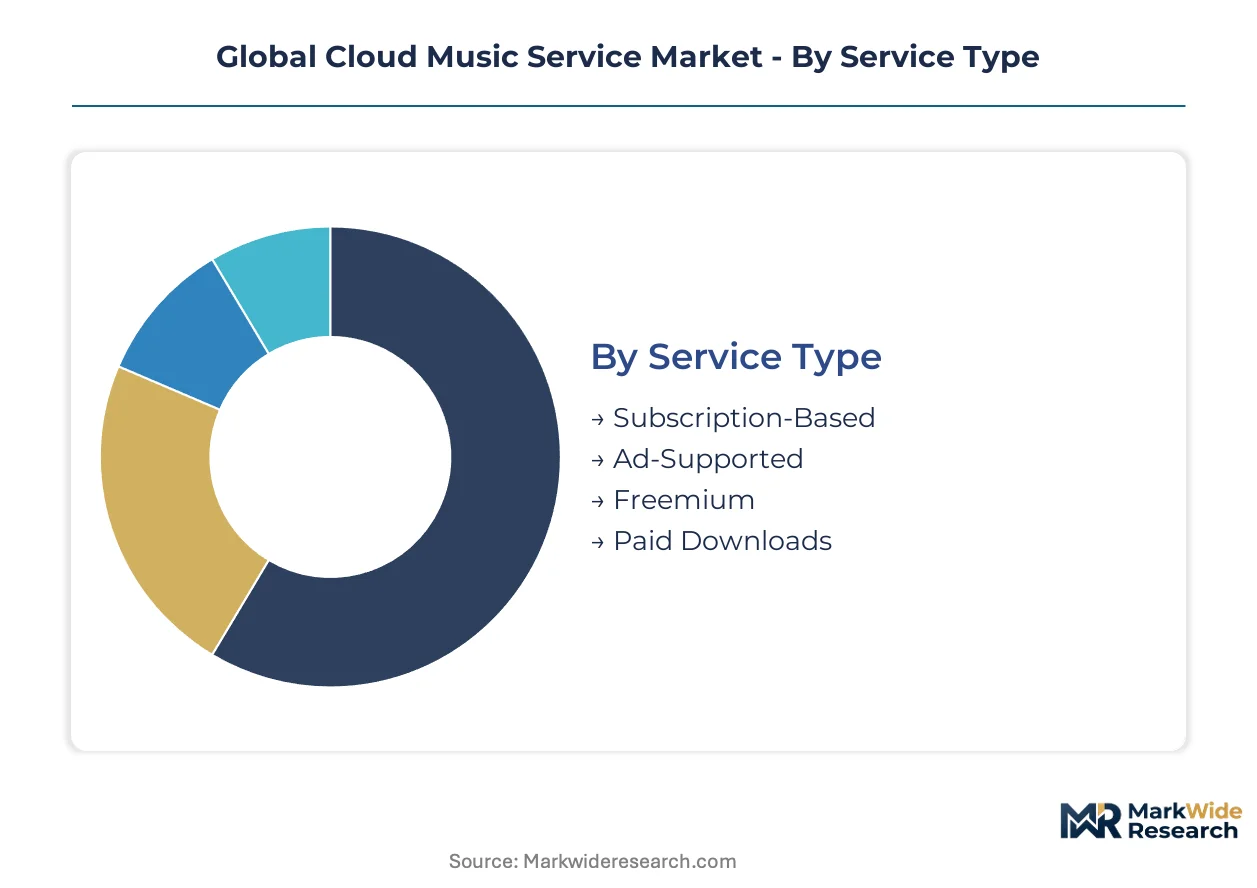
Cloud music platforms calibrate pricing, codec quality, and feature depth across distinct user profiles and hardware contexts. Segmentation reveals where subscriber lifetime value concentrates versus where volume acquisition costs dominate platform economics.
Service Type:
Upgrade cycles differ sharply across payment models, with annual plan renewals and tier migrations driving revenue predictability more than new user acquisition.
- Subscription-Based:Monthly and annual plans deliver lossless audio, offline downloads, and family sharing to committed listeners. Revenue concentrates among North American and Western European households where credit-card billing infrastructure supports recurring payments.
- Ad-Supported:Free tiers monetize attention through audio and display advertising, capturing price-sensitive users who resist paywalls. Brazil and India exhibit the heaviest ad-supported consumption as carrier-billed upgrades penetrate prepaid mobile markets more slowly.
- Freemium:Hybrid models gate premium features behind subscription prompts, using playback limits and audio quality caps as conversion levers.
- Paid Downloads:Permanent ownership of digital files persists among audiophile collectors and archival users in Japan and Germany.
Volume placements concentrate in Ad-Supported tiers; the faster expansion belongs to Subscription-Based models as family plans and student discounts deepen household penetration.
Device Compatibility:
Hardware replacement cycles—smartphone upgrades every 2-3 years, automotive infotainment refreshes every 5-7 years—determine where platform engineering resources concentrate for SDK maintenance and codec optimization.
- Smartphones:iOS and Android applications dominate session volume, with mobile data compression algorithms determining playback quality across variable network conditions. India and Indonesia drive smartphone-native subscriber growth as first-time users bypass desktop entirely.
- Smart Speakers:Voice-activated discovery through Amazon Echo and Google Nest devices habituates household listening without screen interaction. Brazil shows the steepest behavioral rotation toward voice commands where Portuguese-language natural language processing has matured.
- Tablets:Larger screens support lyric visualization and playlist curation, appealing to secondary-device users in North American and European households.
- Desktop Computers:Browser-based and native applications serve professional DJs, music journalists, and office workers requiring multitasking workflows.
- Wearables:Cellular-enabled watches enable untethered listening during fitness activities, with Garmin and Apple Watch integrations expanding fastest among marathon runners and triathletes.
Smartphones capture the dominant share of listening hours; Smart Speakers are climbing the fastest as voice interfaces displace typed search in domestic contexts.
User Demographic:
Customer lifetime value spreads unevenly across age and occupation cohorts, with student discounts and family plans creating distinct acquisition cost profiles.
- Young Adults:Ages 18-25 exhibit the highest playlist creation rates and social sharing velocity, driving organic platform growth through network effects. Mexico City and São Paulo anchor this demographic's concentration in Latin America.
- Professionals:Commute and focus-work listening sustains premium subscription rates among office workers in London, New York, and Singapore who prioritize uninterrupted, high-fidelity playback.
- Students:Verified academic discounts convert price-sensitive users before income growth, with .edu email verification gating reduced-rate access in the US, UK, and Australia.
- Seniors:Simplified interfaces and curated nostalgia playlists retain aging subscribers who value ease over discovery algorithms.
- Music Enthusiasts:Super-users with 100,000-plus track libraries demand advanced metadata tools, third-party app integrations, and hi-resolution audio tiers.
Young Adults generate the heaviest streaming volume; Professionals deliver the highest per-account margins through uninterrupted premium subscriptions.
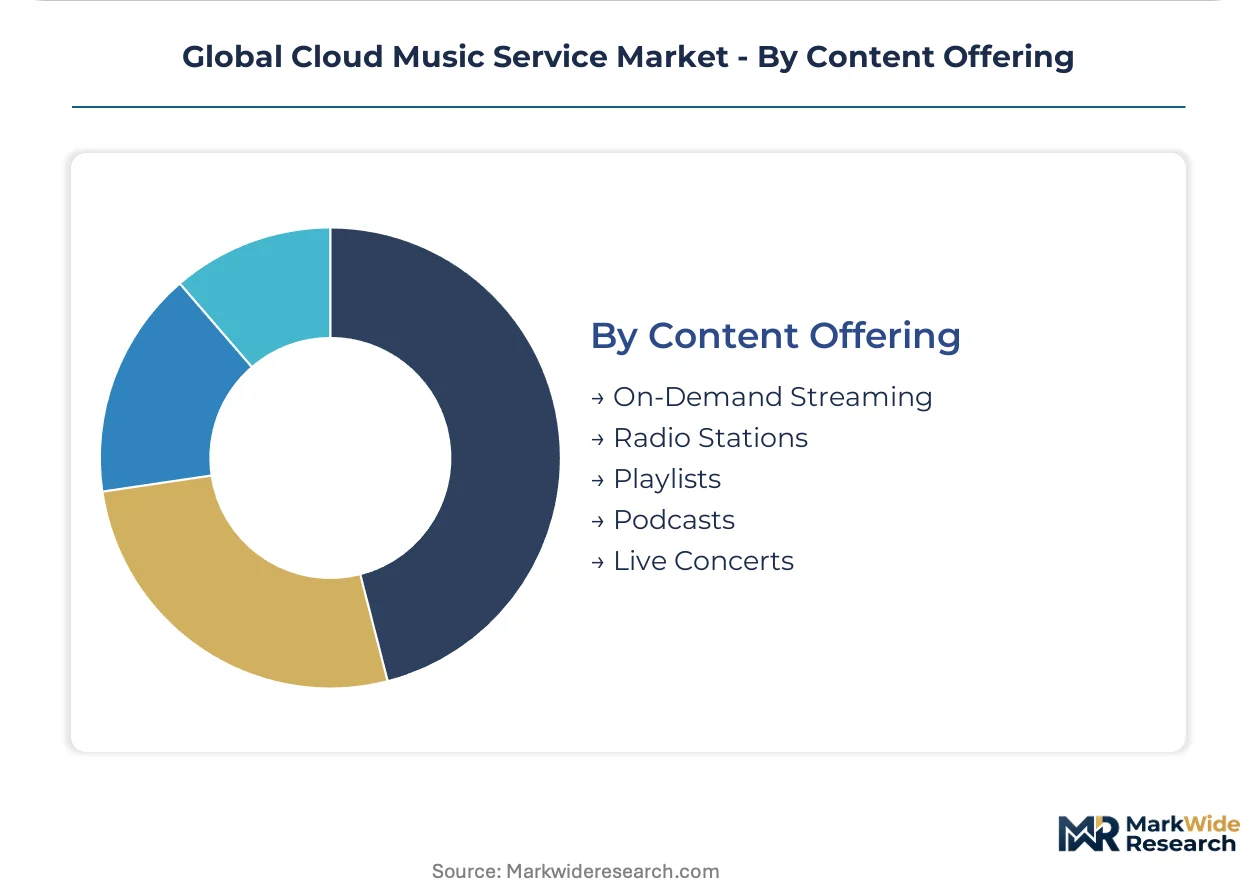
Content Offering:
Content format diversification reshapes royalty allocation and engagement metrics, with video-audio hybrids and real-time broadcasts demanding distinct infrastructure investments.
- On-Demand Streaming:Catalog access with search, browse, and algorithmic recommendation constitutes the core platform value proposition. Germany and South Korea exhibit the deepest per-user engagement with on-demand libraries.
- Podcasts:Spoken-word content extends session duration beyond music consumption, with exclusive licensing deals concentrating talent in the US and UK markets.
- Radio Stations:Curated genre and mood channels reduce decision fatigue for passive listeners, retaining users who resist algorithmic personalization.
- Playlists:Editorial and algorithmic collections drive discovery, with collaborative editing features increasing stickiness among friend networks.
- Live Concerts:Real-time and on-demand performance broadcasts require low-latency edge infrastructure, with virtual ticketed events expanding fastest in Japan and Australia where physical venue capacity constraints persist.
On-Demand Streaming anchors platform economics; Live Concerts are gaining share fastest as hybrid physical-virtual event formats mature post-pandemic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors Latin America's streaming expansion, with its dense metropolitan subscriber base and carrier-billing partnerships converting mobile-first listeners into paying accounts faster than any other emerging market cluster.
United States
FCC net neutrality rulings directly shape how internet service providers throttle streaming traffic, forcing platforms to negotiate quality-of-service guarantees. The regulatory uncertainty compresses margins for ad-supported tiers dependent on consistent playback quality. Los Angeles and Nashville concentrate music industry licensing negotiations, with label headquarters proximity enabling faster rights clearance for new releases.
Germany
GEMA collective licensing and GDPR data residency requirements fragment infrastructure economics for foreign platforms serving German subscribers. The country's national data protection authority enforces strict algorithmic transparency mandates under the EU AI Act. Berlin's startup ecosystem produces specialized audio compression and metadata management tools that platforms integrate to meet European compliance standards.
Brazil
Expanding 4G coverage in secondary cities like Curitiba and Recife converts piracy-era listeners through carrier-billed micro-subscriptions. ANVISA and the national data protection authority impose evolving requirements on health-related audio content and cross-border data flows. São Paulo's advertising technology cluster supplies programmatic audio ad infrastructure that monetizes the region's heavy ad-supported consumption base.
China
SAMR licensing requirements and content censorship protocols create compliance barriers that favor domestic platforms with established regulatory relationships. The dual carbon goals pressure data center operators to source renewable energy for streaming infrastructure. Beijing and Shanghai host the engineering talent pools developing proprietary recommendation algorithms optimized for Mandarin-language catalogs and local listening patterns.
India
TRAI mobile data pricing regulations and prepaid mobile cultures drive demand for daily and weekly subscription tiers adapted to irregular income cycles. The PLI scheme for electronics manufacturing accelerates domestic smart speaker production, reducing hardware costs for voice-activated streaming. Mumbai's Bollywood production ecosystem supplies exclusive regional content that platforms license to differentiate against international catalogs.
Global Cloud Music Service Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the cloud music service landscape, with infrastructure-owning platforms bearing data center costs while pure-play streamers rent compute capacity. The market structures around three tiers: global hyperscalers with bundled ecosystem advantages, regional specialists with localized content depth, and audio-first independents competing on discovery algorithms. Consolidation pressure concentrates among mid-tier players lacking exclusive catalog rights or hardware distribution channels. Dominant competitive moves include exclusive podcast licensing to extend session duration and automotive OEM partnerships to embed streaming into vehicle-native interfaces.
Among US-based technology conglomerates, Spotify Technology and Apple exemplify divergent ecosystem strategies—one operating as an audio-first independent with podcast infrastructure investments, the other leveraging hardware-software cohesion across device families. Tencent Music Entertainment Group anchors the Chinese market through regulatory-compliant operations and domestic catalog depth. These three occupy positions that illustrate how geographic regulatory fluency and capital structure shape competitive viability across divergent national frameworks.
| Leading Market Players |
|---|
| Spotify Technology |
| Apple Music |
| Amazon Music |
| Tencent Music Entertainment Group |
| YouTube Music |
| NetEase |
| Deezer |
| SoundCloud |
| Pandora |
| Others |
Supply & Pricing Matrix
Bandwidth and data center energy cost indices cascade through cloud music infrastructure economics, compressing margins on ad-supported tiers while enabling premium subscription pricing power for platforms with captive server capacity.
Pricing Analysis
Margin tightening in ad-supported tiers reflects content licensing renegotiation cycles with major labels, which reset every 24-36 months regardless of subscriber growth trajectories. Three-tier pricing structure across premium, standard, and economy levels separates hi-resolution audio subscribers from compressed-stream users and free-tier listeners. Price differentiation rests on codec quality certification and family-sharing scale, with Brazilian and Indian prepaid mobile markets exhibiting the highest buyer price sensitivity. Premium subscribers in North American and Western European markets show the lowest price elasticity, sustaining uninterrupted billing through economic cycles.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud infrastructure concentrated in the United States, Ireland, and Singapore, where AWS, Azure, and Google Cloud anchor streaming delivery. Raw material dependencies span server-grade silicon from Taiwan, submarine cable bandwidth from Japan, and renewable energy credits for carbon-neutral data center operations. Supply chain risk centers on GDPR data residency mandates fragmenting European subscriber data localization away from centralized hubs. Distribution runs through carrier-billed partnerships in emerging markets and direct-to-consumer app store billing in mature economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Content licensing cost inflation is compressing mid-tier platforms without exclusive catalog depth or hardware ecosystem lock-in, forcing consolidation toward capital-heavy incumbents with negotiating leverage against major labels.
For Market Incumbents: Extend podcast infrastructure investments to anchor session duration beyond music catalogs, defending against pure-play audio competitors. Deepen automotive OEM integration partnerships to embed streaming into vehicle-native interfaces before proprietary infotainment systems fragment API standardization. Vertical integration into edge computing nodes reduces latency for real-time collaborative features, creating technical moats that rented-cloud competitors cannot replicate. For New Entrants and Emerging Players: Daily and weekly micro-subscription buyers in Indian prepaid mobile markets represent the most penetrable white-space opportunity, with TRAI data pricing regulations enabling carrier-billed models adapted to irregular income cycles. Spatial audio hardware convergence with augmented reality headsets offers a second entry vector where incumbent platform engineering resources remain concentrated on stereo optimization. A go-to-market angle targeting fitness application integrators with untethered wearable streaming APIs bypasses saturated smartphone-native discovery channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional specialists with localized content depth in Brazil and India, where expanding 4G coverage converts piracy-era listeners faster than global platforms adapt pricing models. Long-term viability over a multi-year horizon hinges on regulatory fluency with SAMR licensing in China and ANVISA content protocols in Brazil. The signal to watch is automotive infotainment system standardization momentum, which will determine whether vehicle-native interfaces concentrate power among embedded platforms or fragment across OEM-specific protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Podcast Licensing | Spoken-word content extends session duration beyond music catalogs, concentrating talent in US and UK markets. |
| Automotive OEM Partnership | Vehicle-native embedding reduces mobile app dependency while creating new data-sharing negotiations with carmakers. |
| Edge Computing Deployment | Distributed audio nodes reduce latency for real-time lyrics synchronization and collaborative playlist editing features. |
| Spatial Audio Hardware Integration | Augmented reality headset convergence creates premium experiences beyond traditional stereo consumption formats. |
| Carrier-Billed Micro-Subscription | Daily and weekly tiers adapted to prepaid mobile cultures unlock volume in Indian and Brazilian price-sensitive markets. |
Research Methodology
Multi-period observation of subscriber churn rates, content licensing renewal terms, and smart speaker household penetration anchored the trend analysis, supplemented by interviews with platform engineering directors, major label licensing executives, automotive infotainment product managers, and telecom carrier partnership leads. Secondary validation drew from SEC filings of listed audio platforms, App Annie streaming session data, FCC net neutrality docket records, and EU AI Act implementation guidance documents. Bottom-up subscriber cohort modeling triangulated against top-down market sizing from infrastructure capacity disclosures.
Segment-weighting across service type, device compatibility, and user demographic dimensions informed value and volume projections across the analysis window. CAGRs were derived from subscriber growth trajectories calibrated against content cost inflation and hardware replacement cycles. Industry-specific forecast inputs included 4G coverage expansion timelines in Brazilian secondary cities and TRAI mobile data pricing regulatory filings in India.
Revisions become necessary when content licensing renegotiations reset major label terms, FCC rulings alter ISP throttling permissions, or SAMR licensing requirements shift foreign platform market access rules in China. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Media and Entertainment
Japan Webtoons Market
Media and Entertainment
Digital Audio Market
Media and Entertainment
Online Movie Market
Media and Entertainment
Digital Avatar Market
Media and Entertainment
India Smart TV and OTT Market
Media and Entertainment
Europe Social Media Analytics Market
Media and Entertainment
Print Newspapers and Magazines Market
Media and Entertainment
VR Melee Games Market
Media and Entertainment
Live Streaming Pay-Per-View Market
Media and Entertainment
Adult Entertainment Market
Media and Entertainment
Voice Over New Radio Market
Media and Entertainment
Europe Gaming Peripherals Market
Media and Entertainment
Nigeria OOH and DOOH Market
Media and Entertainment
North America OOH and DOOH Market
Media and Entertainment
Asia Pacific Photography Service Market
Media and Entertainment
Global Music Streaming Service Market