
 Global Baby Clothing Market | 2026-2036
Global Baby Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Baby Clothing Market Analysis
Direct-to-consumer subscription models is reshaping margin distribution in baby clothing, shifting profit pools from wholesale markups toward recurring revenue and first-party data ownership. Carter's, Inc anchors its competitive position through vertical control over cotton sourcing and private-label manufacturing. Inditex leverages rapid-response supply chains to compress design-to-shelf timelines for infant collections. H&M Group competes on sustainability credentials, integrating organic cotton certification across its newborn lines.
Baby clothing encompasses garments engineered for children from birth through approximately four years of age, constructed with flame-resistant finishes, hypoallergenic dyes, and snap-fastener closures to accommodate rapid growth and limited motor coordination. The category serves both protective and developmental functions, regulating body temperature while enabling caregiver access for feeding and diaper changes. Bodysuits and pants together constitute the core volume base, while jackets command higher unit margins due to seasonal replacement cycles and technical insulation requirements. Online channels are capturing the fastest expansion as mobile-native parents prioritize convenience and subscription replenishment over physical store visits.
REACH restrictions on azo dyes and formaldehyde-based finishes in Europe, alongside the US Consumer Product Safety Commission's flammability standards for children's sleepwear, are elevating compliance costs and favoring suppliers with certified testing infrastructure. OEKO-TEX Standard 100 certification has become a de facto market-access requirement for premium positioning in North American and European retail. Stakeholders must monitor regulatory divergence between jurisdictions, as chemical safety thresholds and labeling mandates continue to tighten without harmonization across major consumption markets.
Market Dynamics
Digital-native millennial parents are consolidating purchasing power through subscription channels, forcing incumbent brands to rebuild distribution architecture around recurring revenue models and first-party data capture rather than wholesale dependency.
Growth Catalysts
- REACH chemical safety standards:ECHA's tightening azo dye and formaldehyde restrictions are accelerating certified supplier consolidation in Europe, rewarding testing infrastructure investments with preferential retail access.
- Organic cotton certification:OEKO-TEX Standard 100 has become a de facto premium positioning requirement in North America, creating compliance-based segmentation that locks out uncertified competitors.
- China-India-US demand concentration:Divergent birth rate trajectories and disposable income expansion across these three markets are concentrating volume growth in digitally integrated supply chains.
Market Restraints
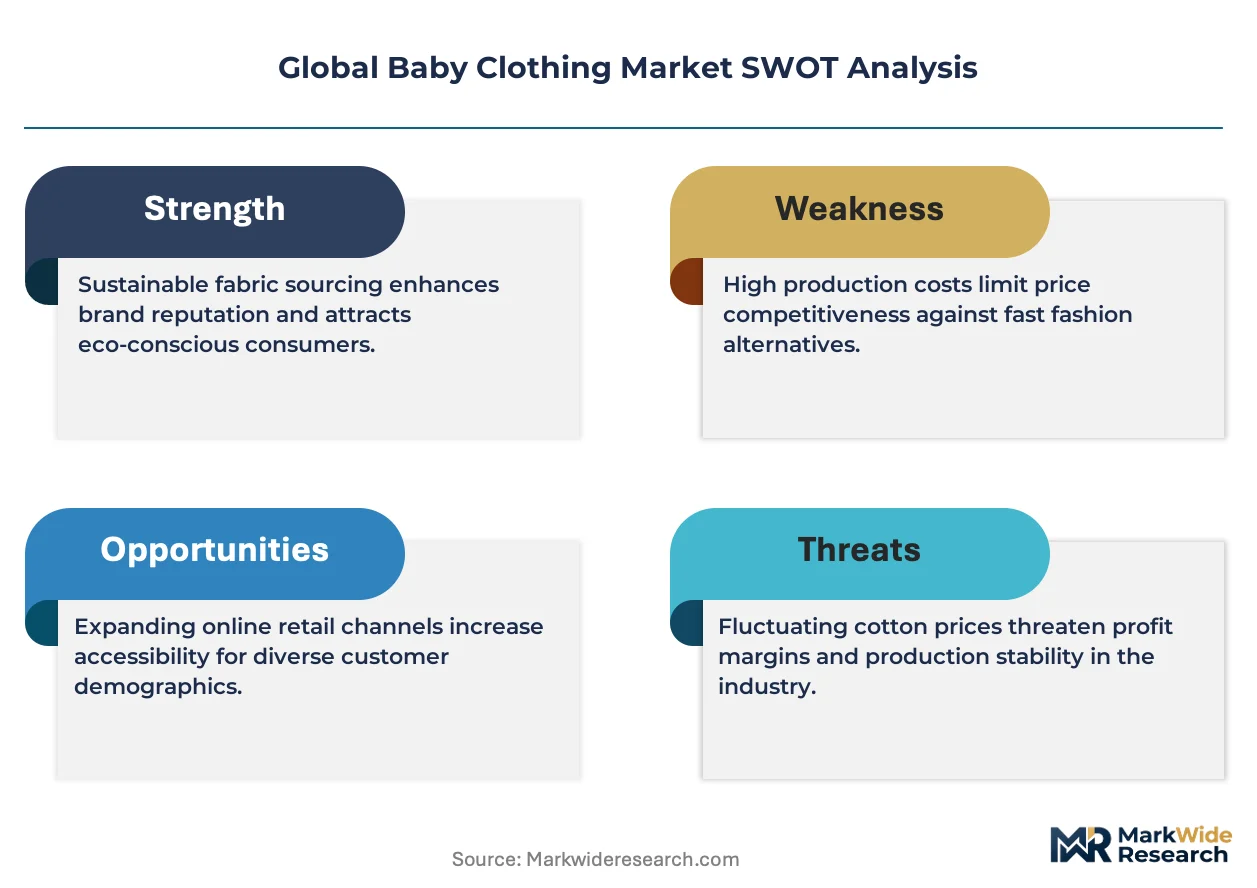
- Cotton price volatility:Climate-driven yield uncertainty and water scarcity in Punjab and Texas are compressing margin predictability for brands without backward integration into sourcing.
- Supplier concentration in Bangladesh and Vietnam:Geographic clustering of cut-and-sew capacity creates disruption exposure from single-point logistics failures and labor compliance shocks.
- Technical limitation in biodegradable finishes:Current bio-based flame retardants fail to meet US Consumer Product Safety Commission sleepwear standards, blocking sustainable positioning in regulated categories.
Strategic Opportunities
- Underpenetrated India tier-2 cities:Rising middle-class formation in Jaipur, Lucknow, and Indore remains underserved by branded baby clothing relative to metro saturation.
- Regulatory tailwind from EU Green Deal:Circular textile mandates and extended producer responsibility schemes will advantage brands with take-back infrastructure and resale platform integration.
- AI-driven size prediction:Machine learning integration with subscription replenishment is reducing return rates and enabling predictive inventory positioning ahead of growth spurts.
Industry Challenges
- Certification timeline compression:OEKO-TEX and GOTS testing backlogs are extending product launch cycles by 8-14 weeks, forcing brands to front-load development calendars.
- Legacy ERP integration with DTC platforms:Wholesale-oriented inventory systems require expensive middleware rebuilds to support real-time subscription fulfillment and personalization engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Baby Clothing Market |
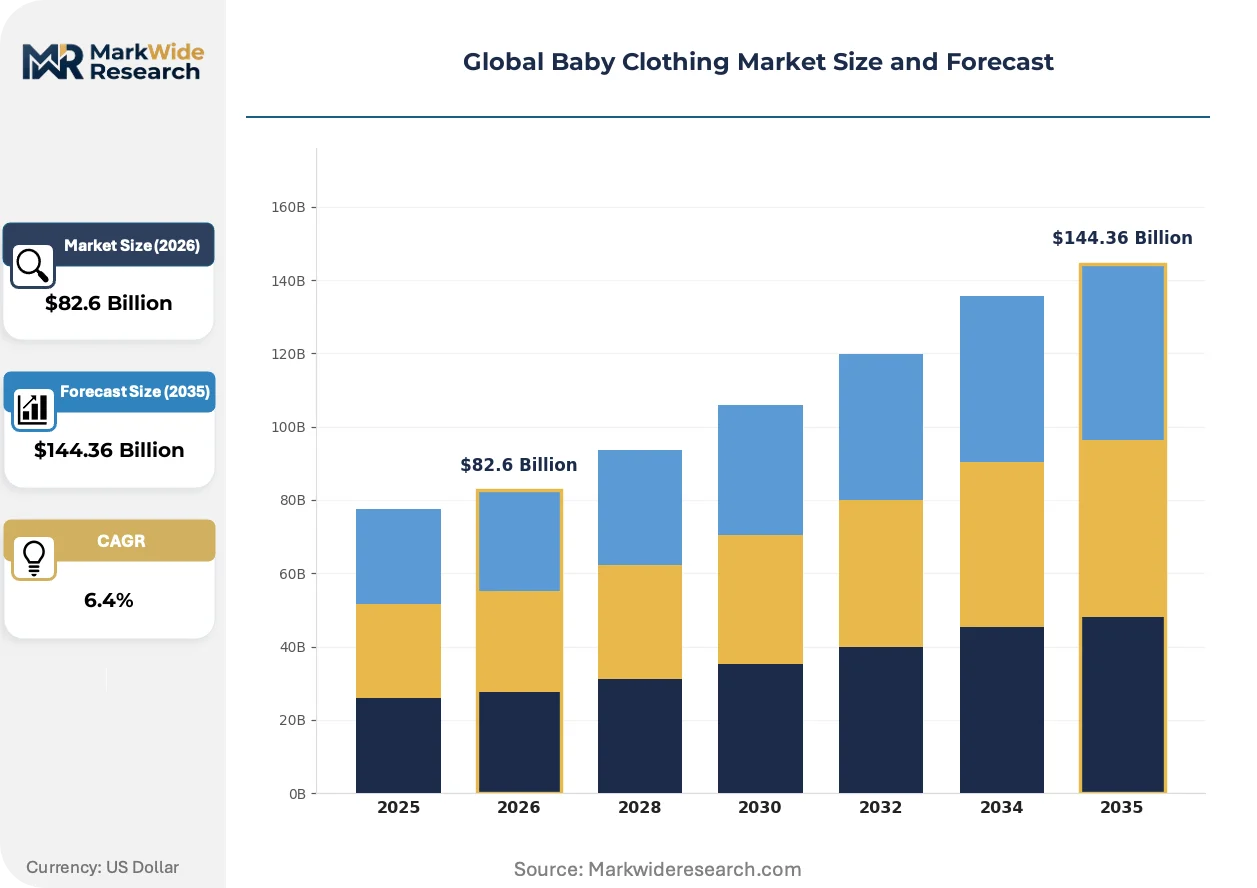
| Market Size in 2026 | $82.6 Billion |
| Market Size in 2035 | $144.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bodysuits, Dresses, Pants, Jackets Material: Cotton, Polyester, Wool, Linen Age Group: Newborn, Infant, Toddler, Preschool Distribution Channel: Online, Department Stores, Specialty Retailers, Supermarkets |
| Companies Covered | Carter's, Inc, H&M Group, Nike, Inc, The Children's Place, Inc, Gerber Childrenswear, Inditex, Hanesbrands Inc, Ralph Lauren, Cotton On Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Baby Clothing Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry restrictions are converging to redefine performance standards in infant apparel, while channel architecture undergoes parallel restructuring around convenience-driven replenishment models.
Smart temperature-regulating fabrics incorporating phase-change materials are migrating from medical and outdoor applications into premium baby clothing lines. Early adopters in Nordic markets and high-altitude US mountain states are driving initial volume. This migration is compressing the traditional seasonal purchasing calendar as parents invest in year-round thermal management rather than discrete winter layering.
REACH restrictions on formaldehyde-based finishes and azo dyes are forcing reformulation of conventional textile treatments across European supply chains. Industrial consequence includes elevated R&D expenditure and accelerated supplier qualification timelines. Premium private-label programs at major retailers are most affected, responding with dedicated compliance teams and pre-certified yarn sourcing from Turkey and Portugal.
Subscription-based replenishment is displacing episodic purchasing among mobile-native parent cohorts. Direct-to-consumer platforms and integrated retail apps are capturing diaper-bag essentials and size-transition moments previously served by physical registry visits. This behavioral shift is most visible in US coastal metropolitan areas and UK commuter belts, where delivery density supports economically viable replenishment logistics.
Global Baby Clothing Market Segmentation
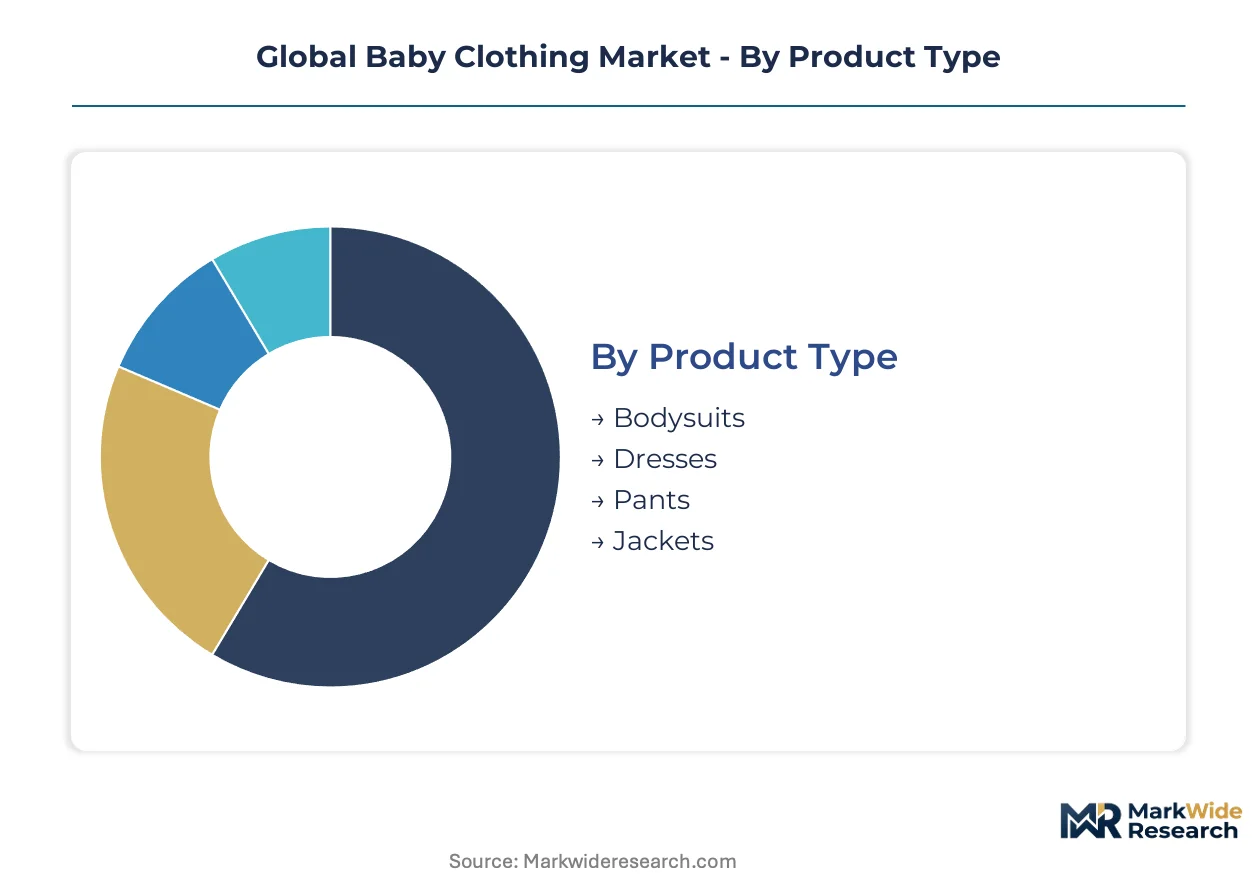
Baby clothing segmentation reflects divergent purchasing behaviors across product lifecycles and material preferences. Understanding these divides enables targeted positioning against regulatory requirements and channel-specific margin structures.
Product Type:
Mature staples anchor volume while technical outerwear commands premium positioning through seasonal replacement cycles.
- Bodysuits:Snap-closure one-piece garments constructed from interlock knit cotton with envelope necklines for gentle over-head removal. Demand concentrates in US and Chinese mass-market channels where bulk purchasing for diaper-bag rotation drives replenishment frequency.
- Jackets:Insulated outerwear with technical flame-resistant finishes meeting US Consumer Product Safety Commission sleepwear standards. Nordic markets and high-altitude US states drive premium thermal management adoption, compressing traditional seasonal purchasing calendars.
- Dresses:Occasion-wear segments with smocking and embroidery detailing for ceremonial purchase occasions.
- Pants:Elastic-waist separates coordinating with bodysuit tops for everyday rotation sets.
Bodysuits handle the majority of throughput; jackets are expanding most quickly on share through technical insulation requirements.
Material:
Natural fiber dominance is fragmenting as certified organic supply chains struggle to match conventional cotton price points.
- Cotton:GOTS-certified organic varieties command 15-30% price premiums in European and North American premium retail. REACH-compliant dyeing infrastructure in Turkey and Portugal is locking in preferred supplier status for OEKO-TEX Standard 100 certification.
- Polyester:Recycled PET microfiber blends enable moisture-wicking performance in athletic-inspired infant lines. Chinese manufacturing clusters leverage scale economies for cost-competitive synthetic base layers.
- Wool:Merino varieties from Australian and New Zealand sourcing for temperature-regulating base layers in cold climate markets.
- Linen:Breathable summer-weight construction for Mediterranean and Gulf Coast seasonal demand pockets.
Cotton retains the dominant share position; polyester is climbing the fastest through performance positioning and cost accessibility.
Age Group:
Rapid growth velocity in early months creates sizing complexity that subscription models are engineered to solve.
- Newborn:Preemie to three-month sizing with kimono-style side-snap construction for umbilical cord protection. US hospital gift shop channels and Chinese confinement care packages concentrate initial purchase moments.
- Infant:Three to twelve months with reinforced knee panels for crawling-phase durability. Indian tier-2 city expansion is driving branded penetration previously served by unorganized tailoring.
- Toddler:One to three years with potty-training friendly elastic waistbands and tagless labeling for sensory sensitivity.
- Preschool:Three to four years mirroring children's fashion trends with licensed character applications.
Newborn captures highest per-unit gifting expenditure; toddler is gaining share fastest through extended sizing ranges and transition-moment subscription capture.
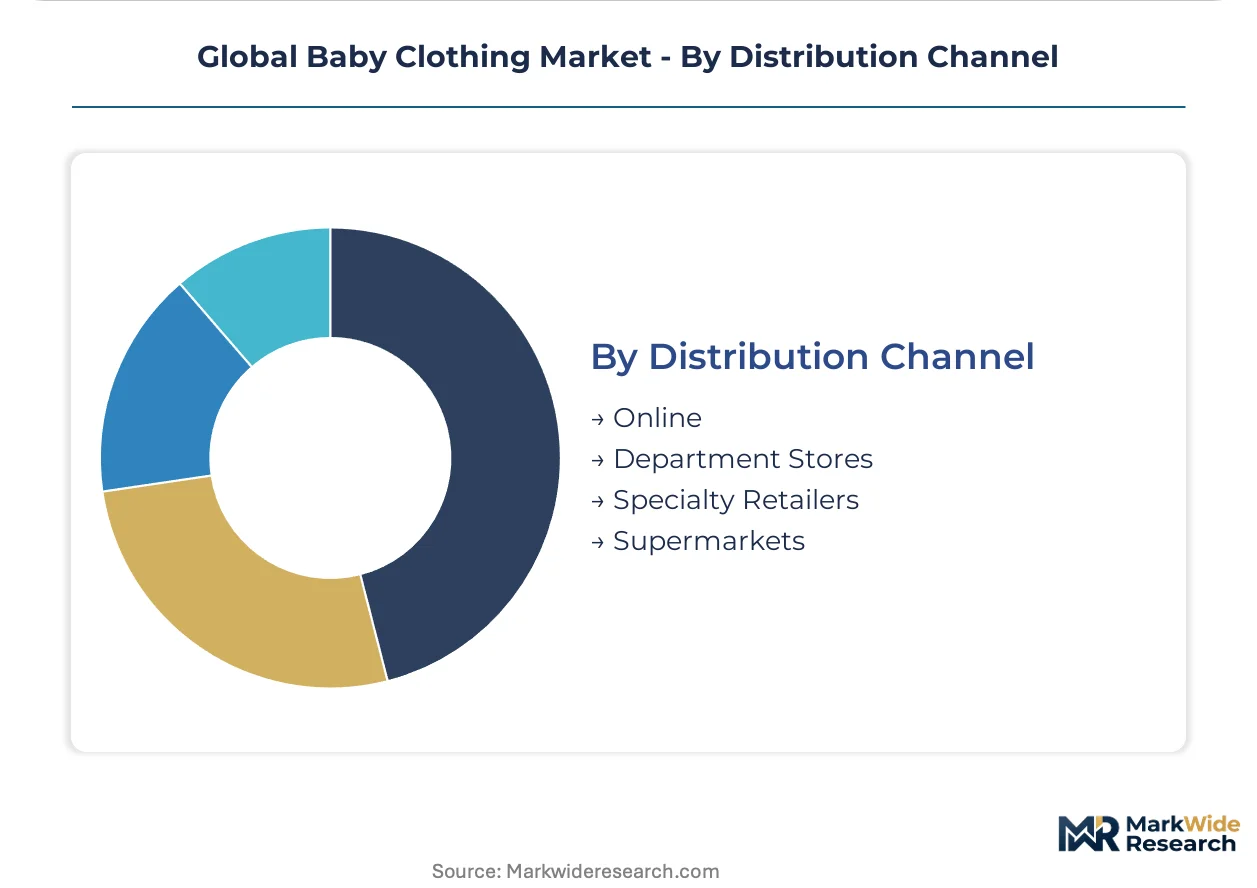
Distribution Channel:
Channel economics are inverting as first-party data ownership outweighs wholesale volume scale.
- Online:Direct-to-consumer platforms with AI-driven size prediction and replenishment algorithms. UK commuter belts and US coastal metropolitan areas support economically viable delivery density for diaper-bag essentials.
- Specialty Retailers:Curated boutique assortments with certified organic positioning and registry services. German and French independent retailers leverage OEKO-TEX certification for differentiation against mass-market competition.
- Department Stores:Legacy registry infrastructure with private-label consolidation pressuring branded space allocation.
- Supermarkets:Value-tier emergency replenishment for sizing transitions and stain replacement.
Online channels command the steepest expansion trajectory; specialty retailers retain margin leadership through certification-based curation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: US parents favor subscription replenishment for everyday basics, while Chinese buyers concentrate spending on ceremonial gifting occasions, and European purchasers prioritize certified organic credentials in boutique channels.
United States
Millennial parents in coastal metropolitan areas drive direct-to-consumer subscription adoption for diaper-bag essentials. The US Consumer Product Safety Commission enforces flammability standards for children's sleepwear that elevate testing costs. Los Angeles and New York City anchor premium brand headquarters and influencer marketing infrastructure.
China
Confinement care packages and hospital gift channels concentrate newborn apparel expenditure in tier-1 cities. The country's national quality regulator enforces GB standards for textile safety in infant products. Guangzhou and Shenzhen manufacturing clusters supply synthetic base layers leveraging recycled PET scale economies.
Germany
Independent retailers in Berlin and Munich leverage OEKO-TEX certification for differentiation against mass-market competition. ECHA's REACH restrictions on azo dyes and formaldehyde-based finishes accelerate certified supplier consolidation. The Rhine-Ruhr industrial corridor hosts specialized dyeing infrastructure compliant with EU chemical safety thresholds.
India
Rising middle-class formation in Jaipur, Lucknow, and Indore drives branded penetration previously served by unorganized tailoring. BIS textile labeling mandates tighten compliance requirements for imported infant apparel. Tiruppur's knitwear cluster adapts GOTS-certified organic cotton processing for export markets.
United Kingdom
Commuter belts around London support economically viable delivery density for online replenishment of everyday rotation sets. The country's national consumer protection framework aligns with EU-derived chemical safety standards post-Brexit. Manchester retains legacy textile testing laboratories serving premium private-label programs.
Global Baby Clothing Market Vendor Landscape
Capability concentration sits with vertically integrated specialists who control cotton sourcing and certified manufacturing; scale advantage sits with fast-fashion conglomerates leveraging rapid-response supply chains. The market structures around three archetypes: private-label manufacturers with backward integration into yarn sourcing, multi-brand retailers curating certified organic assortments, and sportswear houses extending performance technology into infant lines. Competitive moves center on supplier certification pre-qualification and subscription platform infrastructure buildout.
Within the vertically integrated tier, Carter's, Inc and Gerber Childrenswear exemplify archetypes combining captive cotton sourcing with private-label manufacturing control. H&M Group and Inditex occupy positions on the fast-fashion vector, competing through sustainability credentialing and compressed design-to-shelf timelines respectively. These four anchors illustrate the strategic divergence between margin defense through supply chain ownership and market share capture through rapid assortment rotation.
| Leading Market Players |
|---|
| Carter's, Inc |
| H&M Group |
| Nike, Inc |
| The Children's Place, Inc |
| Gerber Childrenswear |
| Inditex |
| Hanesbrands Inc |
| Ralph Lauren |
| Cotton On Group |
| Others |
Supply Flow & Price Mechanics
Undercapacity in certified organic cotton ginning across Turkey and Portugal is tightening supplier leverage and compressing margin negotiation windows for brands without pre-qualified yarn commitments. This utilization squeeze simultaneously elevates compliance premiums for REACH-certified dyeing and accelerates spot-market sourcing for conventional grades.
Pricing Analysis
Long-term offtake agreements with GOTS-certified Turkish spinners anchor pricing stability for premium private-label programs, while spot-market purchasing dominates conventional cotton tiers. Price differentiation hinges on OEKO-TEX Standard 100 certification tier and volume-scale commitments from subscription platforms. Pricing pressure intensifies in the bodysuit mass-market tier as Bangladeshi cut-and-sew capacity floods undifferentiated volume. Direct-to-consumer subscription buyers exhibit lowest price sensitivity; supermarket emergency-replenishment shoppers are most elastic.
Supply Chain Analysis
Export-control regimes on formaldehyde-based textile finishes under REACH limit conventional treatment flows into European retail channels. Manufacturing concentrates in Bangladesh, Vietnam, and China, with Tiruppur's knitwear cluster supplying certified organic processing for North American premium lines. Raw material flows draw from Punjab cotton, Australian merino wool, and recycled PET feedstocks from Guangzhou chemical plants. Single-source vulnerability concentrates in Bangladeshi cut-and-sew for mass-market bodysuits. Distribution runs through direct-to-consumer platforms, specialty boutique networks, and consolidated department-store registries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global baby clothing sits in early-cycle expansion as subscription replenishment penetration among millennial parents remains below saturation thresholds in tier-2 Indian cities and European commuter belts.
For Market Incumbents: Build subscription-data moats by integrating AI-driven size prediction with replenishment algorithms. Defend against fast-fashion compressors by locking multi-year GOTS-certified cotton offtake from Turkish spinners. Prioritize middleware rebuilds connecting legacy ERP systems to real-time subscription fulfillment engines.
For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 cities where branded penetration lags behind Jaipur, Lucknow, and Indore middle-class formation. Target ceremonial gifting occasions in Chinese confinement care packages with OEKO-TEX-certified newborn kimono sets. Launch through hospital gift-shop channels and integrated retail apps rather than wholesale distribution.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer platforms with captive size-prediction algorithms and certified supply chain integration. Over a five-to-ten-year horizon, vertically integrated specialists with backward cotton sourcing control offer superior cash-flow durability. Monitor OEKO-TEX testing backlog compression as an inflection signal for launch-cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Platform Integration | Captures recurring revenue and first-party data from mobile-native millennial parents. |
| Certified Supply Chain Lock-In | Secures preferential access to GOTS-certified Turkish cotton amid testing backlog constraints. |
| AI-Driven Size Prediction | Reduces return rates by anticipating growth spurts in infant and toddler segments. |
| Tier-2 Geographic Expansion | Accesses underserved middle-class formation in Indian cities beyond metro saturation. |
| Circular Infrastructure Buildout | Positions for EU Green Deal extended producer responsibility mandates in textile recovery. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with brand managers, category buyers at specialty retailers, subscription platform engineers, and certified dyeing facility managers in Turkey and Portugal. Secondary validation drew from customs records, OEKO-TEX certification databases, Nielsen retail audit data, and SEC filings of publicly traded apparel conglomerates. Bottom-up volume modeling triangulated against top-down macro consumption indicators.
Calibration anchored segment-level projections to historical elasticity patterns across product type, material certification tier, and channel architecture. Modeled dimensions spanned bodysuit-jacket-dress-pants categories, cotton-polyester-wool-linen material splits, and online-specialty-department-supermarket channel shares. CAGRs derived from regression against birth rate trajectories, disposable income indices, and digital adoption curves. Forecast inputs incorporated REACH compliance cost pass-through rates and subscription penetration velocity in coastal US metropolitan areas.
Macroeconomic conditions sit as an overlay; deviation in birth rate trajectories, cotton commodity volatility, or logistics cost indices would shift the trajectory. Forecasts reflect documented assumptions on regulatory stability and certification timeline normalization. Material shifts in EU Green Deal implementation pace or biodegradable flame-retardant technical breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO