
 Global Asset Integrity Management Market | 2026-2036
Global Asset Integrity Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Asset Integrity Management Market Foresight
Midstream pipeline operators is redrawing procurement priorities across the asset integrity landscape. DNV AS leverages its offshore classification heritage to dominate subsea inspection protocols. Bureau Veritas sustains a competitive edge through its integrated testing and certification network spanning multiple continents. SGS Société Générale de Surveillance SA anchors its position with specialized corrosion monitoring services for downstream refineries.
Asset integrity management encompasses the systematic processes, technologies, and services deployed to ensure industrial assets operate safely, reliably, and efficiently throughout their operational lifecycle, incorporating non-destructive testing protocols, risk-based inspection methodologies, and predictive maintenance algorithms that process vibration, thermal, and ultrasonic sensor data. Its primary commercial purpose centers on preventing catastrophic failures, extending asset service life, and minimizing unplanned downtime in capital-intensive infrastructure. Software platforms command disproportionate margin pools as operators digitize legacy inspection records and integrate real-time sensor feeds into centralized dashboards. Robotics represents the fastest-growing technology segment as autonomous crawlers and drones replace human entry into confined spaces and elevated structures. Pipeline management remains the largest application category due to the sheer linear kilometerage of hydrocarbon and water transmission networks requiring continuous surveillance.
The US Pipeline and Hazardous Materials Safety Administration mandates integrity management programs for high-consequence areas under 49 CFR Part 195, while the EU F-Gas Regulation imposes leak detection requirements on fluorinated gas infrastructure that drive sensor deployment across European chemical plants. ISO 55000 asset management standards provide a voluntary framework that large operators increasingly adopt to satisfy insurer and investor due diligence requirements. Stakeholders must monitor how API, ASME, and national regulator harmonization efforts reshape compliance costs and technology specifications across jurisdictional boundaries.
Market Dynamics
Robotics penetration into confined-space inspection is compressing inspection timelines and redrawing labor economics across pipeline, refinery, and offshore asset portfolios. Autonomous crawlers and magnetic drones now execute wall-thickness surveys in fractions of human-entry durations, forcing service providers to restructure field crew deployment and equipment amortization models.
Growth Catalysts
- API 1163 in-line inspection mandates:North American pipeline operators face compressed reassessment intervals for high-consequence areas, driving continuous tool deployment and data analytics contracts.
- Offshore wind foundation monitoring:European North Sea leaseholders require structural integrity programs for monopile and jacket installations, extending asset integrity service demand beyond hydrocarbons.
- Digital twin integration:Downstream refineries in the US Gulf Coast corridor deploy physics-based corrosion models fed by real-time sensor streams to optimize turnaround scheduling.
Market Restraints
- Specialized inspector scarcity:Certified API 510/570/653 pressure vessel and piping inspectors command premium compensation, constraining service provider scaling.
- Sensor hardware import concentration:Ultrasonic transducer and electromagnetic acoustic transducer supply chains concentrate in East Asian manufacturing hubs, exposing procurement to logistics volatility.
- Legacy system integration friction:Decades-old inspection databases in PDF and paper formats resist automated ingestion into cloud-native analytics platforms.
Strategic Opportunities
- Brazil pre-salt expansion:Deepwater floating production unit deployments off Rio de Janeiro and Espírito Santo create demand for subsea riser and mooring integrity programs.
- Hydrogen infrastructure certification:EU F-Gas Regulation extensions and national hydrogen strategies require adapted leak detection protocols for embrittlement-sensitive steel assets.
- Drone-swarm coordination software:Convergence of autonomous navigation algorithms with edge-computing hardware enables simultaneous multi-asset surveys at downstream complexes.
Industry Challenges
- Data interoperability standards:Operator-specific formats for inspection reports, risk matrices, and anomaly classifications impede vendor switching and multi-contractor coordination.
- Cybersecurity certification timelines:IEC 62443 compliance for connected inspection hardware and cloud platforms extends product development cycles and field deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Asset Integrity Management Market |
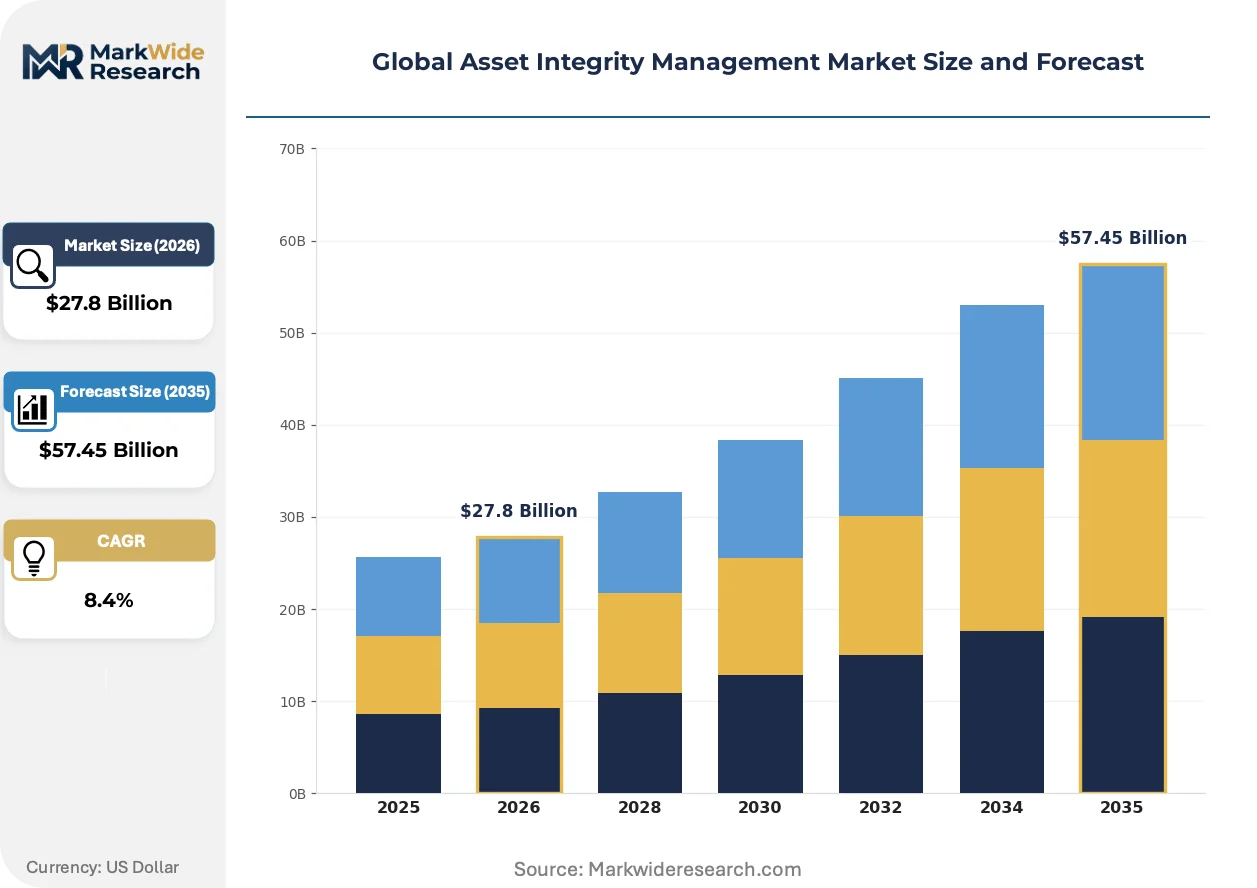
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $57.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection, Maintenance, Consulting, Risk Management End User: Oil & Gas, Chemical, Power Generation, Aerospace Technology: IoT Solutions, Robotics, Data Analytics, Software Platforms Application: Pipeline Management, Structural Integrity, Equipment Monitoring, Asset Management |
| Companies Covered | SGS Société Générale de Surveillance SA, Bureau Veritas, Intertek Group plc, TechnipFMC plc, Aker Solutions, DNV AS, Applus+, Oceaneering International, Inc., TÜV SÜD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Asset Integrity Management Market Shifts & Advancements
Computational inspection methods are displacing deterministic assessment protocols across pressure equipment and structural systems. Machine learning classifiers now process radiographic and ultrasonic signals to flag indications with reduced human interpreter dependency.
Guided wave ultrasonic testing is bifurcating pipeline inspection economics. Long-range screening tools detect corrosion and cracking in coated and buried segments without excavation or coating removal. Midstream operators in the Permian Basin and Western Canadian Sedimentary Basin deploy these systems for rapid corridor prioritization. The technology is compressing preliminary survey costs while concentrating detailed excavation budgets on validated anomaly locations.
The EU F-Gas Regulation imposes mandatory leak detection and repair programs on fluorinated gas infrastructure above specified charge thresholds. Chemical plant operators in Germany's Rhine-Ruhr industrial cluster and France's Lyon corridor must install fixed sensor networks and execute periodic manual surveys. This mandate is accelerating infrared camera and photoacoustic spectroscopy deployments across European refrigeration and process cooling assets.
Performance-based service contracting is displacing time-and-material inspection arrangements. Major integrated operators now negotiate availability guarantees and risk-sharing mechanisms with integrity service providers. This model concentrates in the US Gulf Coast petrochemical corridor where unplanned outage costs dwarf inspection program expenditures. Providers absorb equipment and labor risk in exchange for outcome-linked compensation structures.
Global Asset Integrity Management Market Segmentation
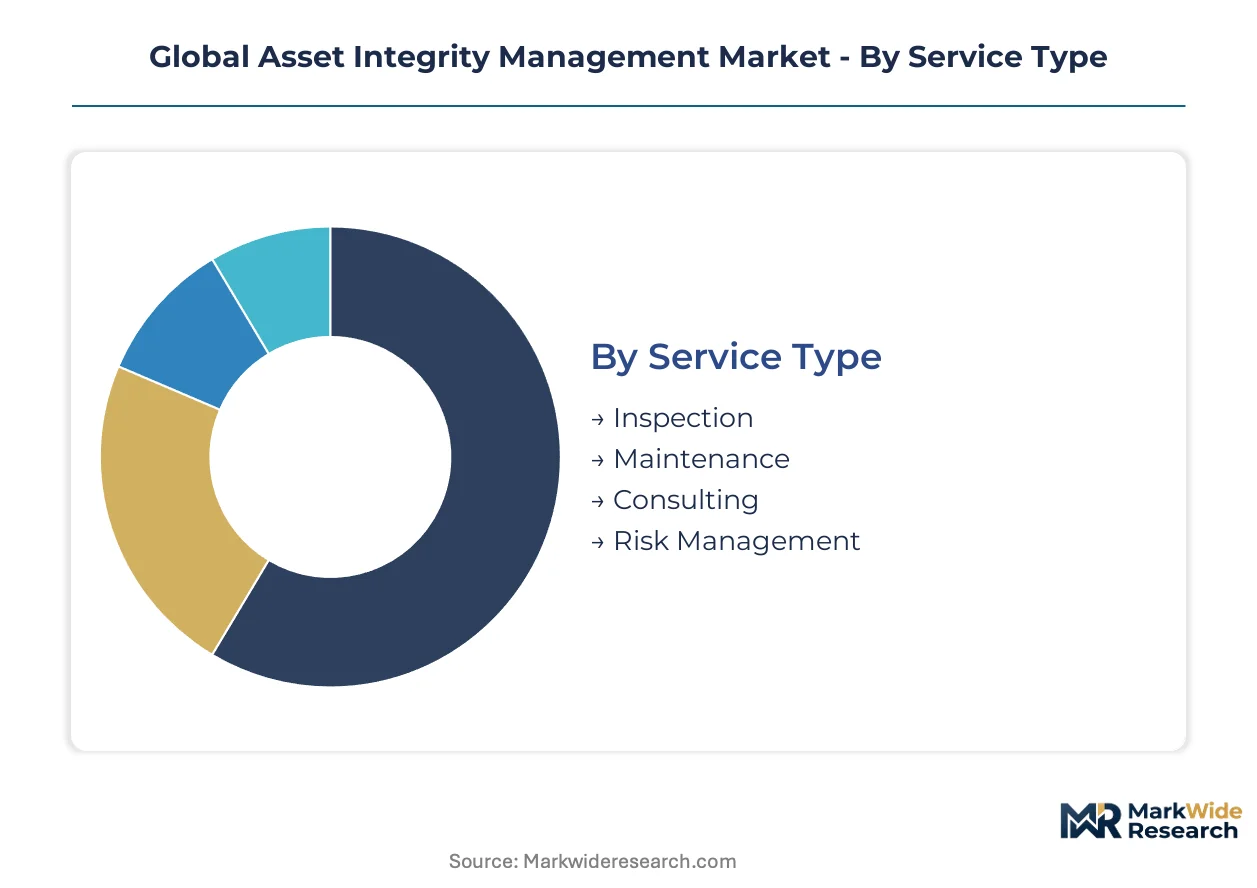
Segmentation in asset integrity management reveals how value pools concentrate across service delivery models and technology stacks. Operators allocate budgets differently across inspection routines, predictive platforms, and risk advisory depending on asset criticality and regulatory exposure.
Service Type:
Margin pools sit heaviest in specialized inspection services where certified technician scarcity creates pricing power. Maintenance contracts generate recurring revenue but compress under competitive tendering.
- Inspection:Non-destructive testing protocols using ultrasonic, radiographic, and electromagnetic methods dominate capital allocation. US Gulf Coast refineries and Permian Basin pipeline operators drive demand for API-certified pressure vessel and piping assessments under compressed reassessment intervals mandated by PHMSA.
- Maintenance:Scheduled turnaround planning and corrective repair execution anchor long-term service agreements. European chemical clusters in Germany's Rhine-Ruhr and France's Lyon corridor require continuous mechanical integrity programs under EU F-Gas Regulation leak detection mandates.
- Consulting:Risk-based inspection strategy and regulatory compliance advisory support operator capital planning.
- Risk Management:Quantitative failure probability modeling and consequence analysis for insurance and investor due diligence.
Inspection holds installed capacity. Risk Management is rotating up the share rankings.
End User:
Volume concentration follows hydrocarbon infrastructure density and process safety regulatory intensity.
- Oil & Gas:Upstream offshore platforms, midstream transmission networks, and downstream refining complexes generate the largest absolute spend. Brazilian pre-salt floating production units and US deepwater Gulf installations require subsea riser integrity programs and corrosion monitoring under ABS and DNV classification rules.
- Chemical:Process plant operators face fluorinated gas containment obligations under EU F-Gas Regulation extensions. German and French chemical manufacturers deploy fixed sensor networks and infrared detection systems for refrigeration and cooling assets above regulatory charge thresholds.
- Power Generation:Thermal plant boiler and turbine monitoring, plus nuclear containment integrity programs.
- Aerospace:Airframe structural health monitoring and engine component life prediction for fleet maintenance.
Oil & Gas commands the dominant revenue share. Chemical is climbing fastest on regulatory compliance spending.
Technology:
Software and analytics layers capture disproportionate margin expansion as operators digitize legacy inspection records.
- Software Platforms:Cloud-native asset information management systems integrate inspection data, risk matrices, and work order execution. US Gulf Coast petrochemical operators deploy physics-based corrosion models fed by real-time sensor streams to optimize turnaround scheduling and minimize unplanned outage costs.
- Robotics:Autonomous crawlers and magnetic drones execute wall-thickness surveys in confined spaces and elevated structures without human entry. Midstream operators in the Permian Basin and Western Canadian Sedimentary Basin deploy long-range guided wave screening tools for rapid pipeline corridor prioritization.
- IoT Solutions:Wireless vibration, thermal, and ultrasonic sensor networks for continuous condition monitoring.
- Data Analytics:Machine learning classifiers processing radiographic and ultrasonic signals to flag anomalies with reduced interpreter dependency.
Software Platforms anchor current profitability. Robotics is expanding most quickly as labor substitution economics improve.
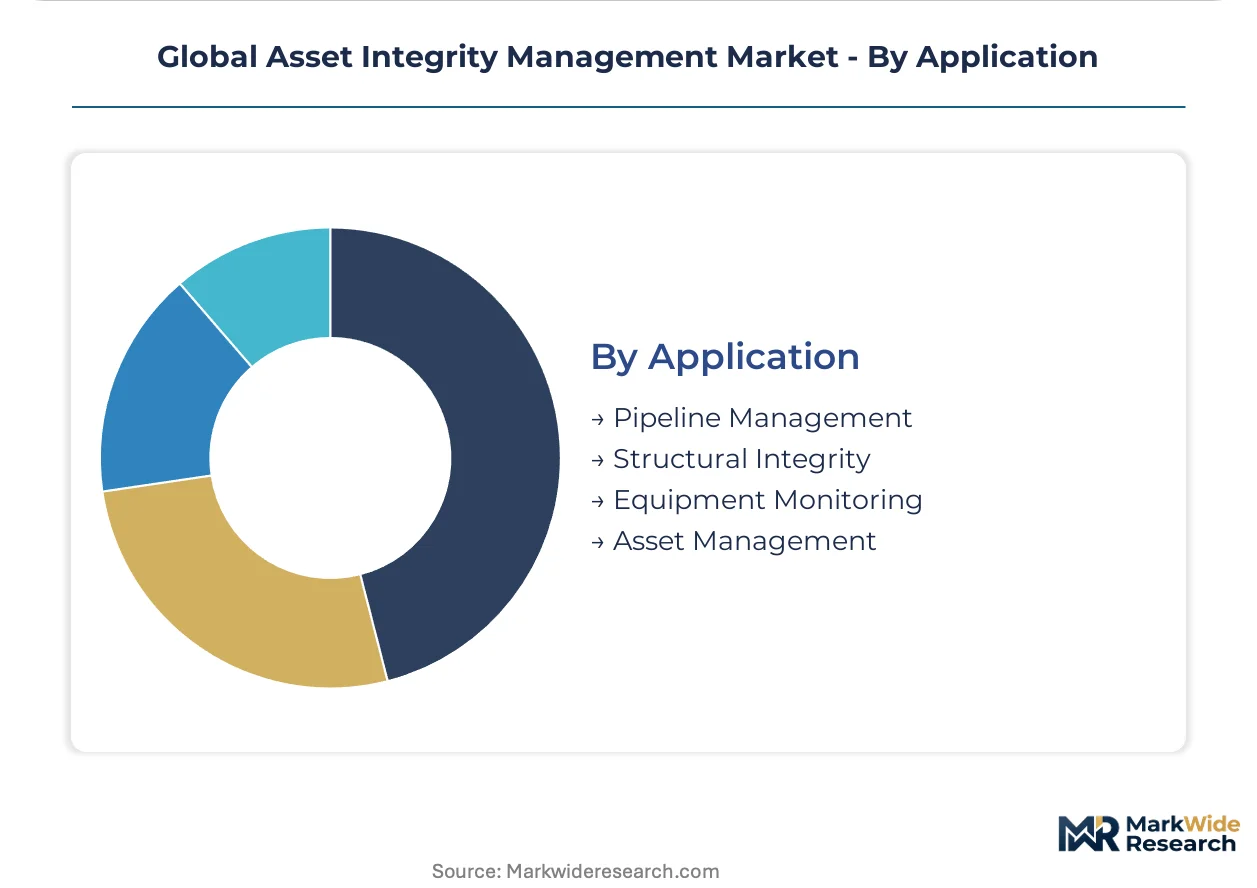
Application:
Pipeline linear kilometerage creates the largest addressable surface area for inspection service deployment.
- Pipeline Management:High-consequence area integrity programs for hydrocarbon and water transmission networks. North American operators face compressed reassessment intervals under API 1163 in-line inspection mandates, driving continuous tool deployment and data analytics contracts across the US Gulf Coast corridor.
- Structural Integrity:Offshore wind foundation monitoring for European North Sea monopile and jacket installations extends service demand beyond hydrocarbons. Leaseholders in UK, German, and Danish waters require structural health programs for fatigue and corrosion assessment.
- Equipment Monitoring:Rotating machinery, pressure vessels, and heat exchanger condition tracking.
- Asset Management:Enterprise-wide ISO 55000 framework implementation for lifecycle cost optimization.
Pipeline Management retains the largest installed base. Structural Integrity is gaining share fastest on offshore wind expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin pipeline network anchors North American spending, while North Sea offshore wind foundations and Brazil's pre-salt floating production units concentrate integrity program deployment across three continents.
United States
PHMSA mandates under 49 CFR Part 195 compress reassessment intervals for high-consequence area pipelines. API 1163 in-line inspection protocols drive continuous tool deployment across Texas and Louisiana corridors. The US Gulf Coast petrochemical cluster deploys digital twin corrosion models fed by real-time sensor streams to optimize turnaround scheduling.
Brazil
Deepwater floating production unit deployments off Rio de Janeiro and Espírito Santo create subsea riser and mooring integrity demand. ANVISA and environmental licensing requirements impose structural health monitoring obligations on offshore assets. The Santos Basin pre-salt cluster requires continuous corrosion surveillance for salt-laden production environments.
Germany
EU F-Gas Regulation leak detection mandates accelerate fixed sensor network deployment across chemical refrigeration assets. The Rhine-Ruhr industrial cluster installs infrared camera and photoacoustic spectroscopy systems for fluorinated gas containment. Offshore wind leaseholders in the North Sea execute monopile fatigue assessment programs under BSH certification rules.
China
GB standards and MIIT directives tighten pressure equipment inspection intervals across refining and chemical complexes. The Yangtze River Delta petrochemical corridor deploys automated ultrasonic testing for storage tank floor integrity. Dual carbon goals accelerate sensor deployment for fugitive emission monitoring at Shanghai and Ningbo processing facilities.
United Kingdom
North Sea decommissioning timelines and offshore wind expansion drive structural integrity spending. The HSE enforces safety case requirements for aging platform infrastructure while Crown Estate leaseholders monitor jacket foundation fatigue. Aberdeen service providers coordinate drone-based flare stack inspection across UK continental shelf assets.
Global Asset Integrity Management Market Competitive Landscape
Concentration sits with diversified inspection conglomerates and specialized offshore engineering houses. Three archetypes dominate: classification society-derived technical advisors, integrated testing and certification networks, and subsea robotics specialists. Competitive moves center on performance-based contracting restructuring and autonomous inspection hardware co-development with operator consortiums.
Within the classification-derived tier, DNV AS and Bureau Veritas exemplify technical authority positioning built on offshore heritage and multi-continent accreditation networks. SGS Société Générale de Surveillance SA anchors the specialized monitoring segment with corrosion-focused service lines for downstream refineries. These three entities represent distinct strategic postures—subsea protocol dominance, integrated certification scale, and application-specific depth—rather than overlapping capability matrices.
| Leading Market Players |
|---|
| SGS Société Générale de Surveillance SA |
| Bureau Veritas |
| Intertek Group plc |
| TechnipFMC plc |
| Aker Solutions |
| DNV AS |
| Applus+ |
| Oceaneering International, Inc. |
| TÜV SÜD |
| Others |
Supply & Pricing Matrix
Ninety-day sensor hardware lead times from East Asian manufacturing hubs compress procurement flexibility and amplify pricing power for ultrasonic transducer suppliers serving North American pipeline operators under API 1163 mandates. Inventory buffers at US Gulf Coast petrochemical clusters rarely exceed thirty days, tethering inspection service pricing to semiconductor foundry output cycles and freight rate volatility across Pacific routes.
Pricing Analysis
Volume-discount tiering structures separate enterprise-scale operators negotiating multi-year predictive maintenance subscriptions from midstream specialists purchasing per-survey robotic inspection services. Price differentiation hinges on API 510/570/653 inspector certification levels and real-time data analytics bundling. Cost compression in standard ultrasonic testing is intensifying because automated signal processing reduces interpreter hours. Mid-tier pipeline operators exhibit highest price sensitivity; integrated supermajors prioritize outcome guarantees over unit economics.
Supply Chain Analysis
Japan and Germany anchor precision electromagnetic acoustic transducer fabrication, while China dominates commodity-grade ultrasonic sensor assembly and drone hardware manufacturing. Raw material flows draw from rare earth processing in Inner Mongolia, specialty steel from ThyssenKrupp for crawler chassis, and FPGA chips from Xilinx distributors. Single-source vulnerability concentrates in phased-array probe ceramics sourced from two Japanese ceramics houses. Distribution runs through authorized service dealer networks with direct-to-operator digital platforms gaining share for software subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
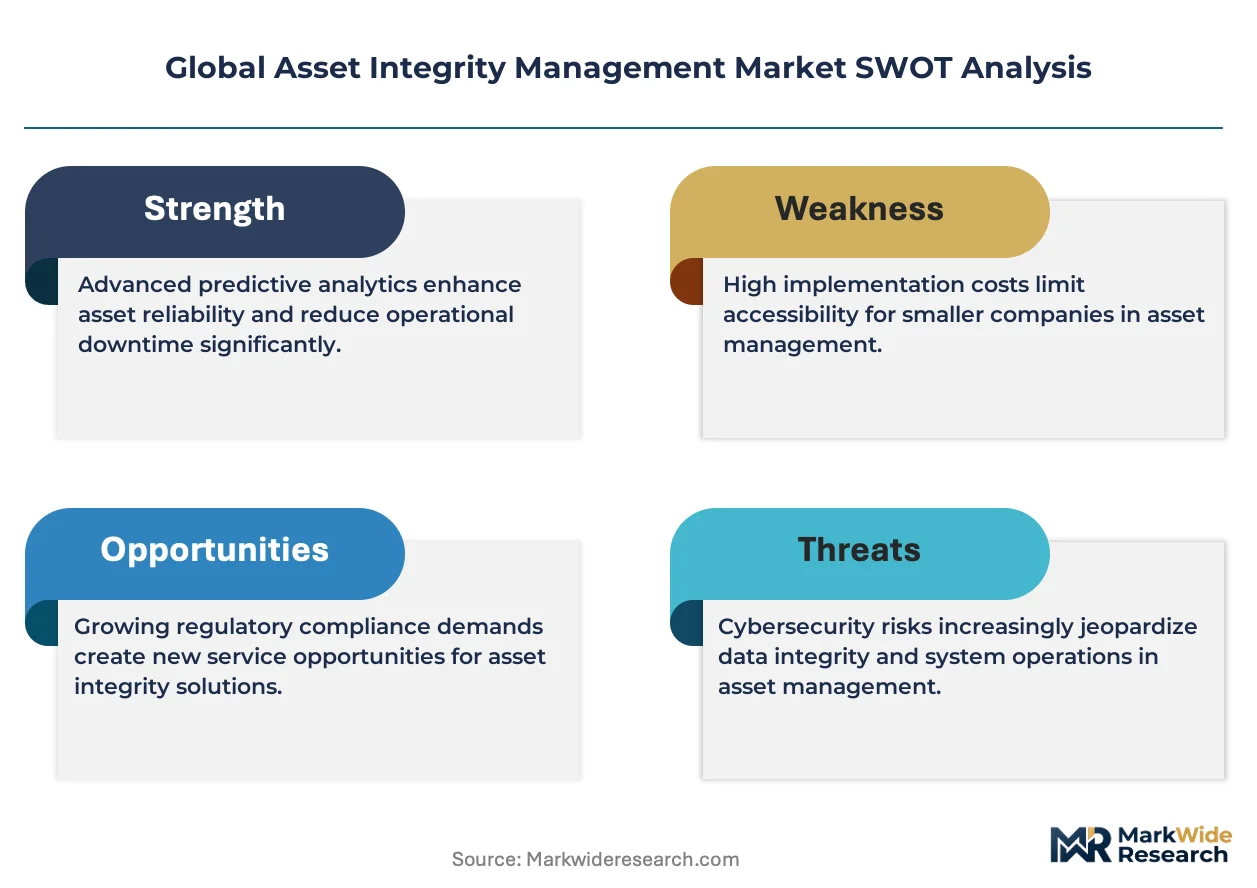
Incumbents face substitution pressure from AI-native inspection platforms that bypass traditional certification hierarchies through machine-learning anomaly detection, threatening the credential-based moat that established service providers have constructed.
For Market Incumbents: Fortify proprietary data lake advantages by integrating decades of inspection records into cloud-native platforms that resist vendor displacement. Pursue backward integration into drone hardware through partnerships with Chinese OEMs to capture equipment margin pools and lock in sensor supply. The threat of vertically integrated oil majors building captive inspection capabilities demands preemptive performance-based contracting with availability guarantees.
For New Entrants and Emerging Players: API 1163 certification fast-tracks for robotic in-line inspection tools offer the lowest barrier to revenue in Permian Basin midstream corridors where operator demand outpaces certified provider supply. White-space targets include hydrogen infrastructure leak detection protocols for EU F-Gas Regulation extensions and drone-swarm coordination software for downstream refinery complexes. A go-to-market angle anchored in computational NDT—machine-learning radiographic interpretation without human-in-the-loop—bypasses inspector scarcity constraints.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because tightening PHMSA reassessment intervals and EU F-Gas extensions create inelastic demand for compliance-linked services regardless of hydrocarbon price cycles. Acquisition targets should emphasize software-platform revenue mix over labor-heavy inspection contracting. The signal to watch is operator consolidation in the US Gulf Coast petrochemical corridor, which concentrates procurement power and favors scaled providers with integrated digital twin capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Robotics Hardware Co-Development | Autonomous crawler partnerships with Permian Basin operator consortiums compress field crew deployment costs. |
| Digital Twin Platform Integration | Physics-based corrosion models fed by real-time sensor streams optimize turnaround scheduling for US Gulf Coast refineries. |
| Certification Fast-Track Investment | API 1163 in-line inspection tool qualification accelerates market entry in high-consequence area corridors. |
| Hydrogen Adaptation Program | Embrittlement-sensitive steel protocols for EU F-Gas Regulation extensions capture emerging infrastructure spend. |
| Outcome-Based Contracting Restructure | Availability guarantees with risk-sharing mechanisms align provider compensation with operator uptime metrics. |
Research Methodology
A standing panel of integrity program directors at midstream operators, API certification board members, PHMSA compliance officers, and robotics hardware procurement leads provided ongoing calibration across eighteen months of field engagement. Primary interview streams combined with secondary validation against PHMSA incident databases, API standards revision dockets, DNV offshore classification records, and EU F-Gas Regulation implementation reports. Bottom-up service provider revenue builds triangulated against top-down operator capital expenditure surveys across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including ABS and DNV classification society filings, Bureau Veritas annual disclosures, and midstream operator 10-K integrity spending footnotes. The analytical framework modeled segmentation across service type, end user, technology stack, and application vertical throughout the forecast period. CAGRs derived from weighted regression of historical integrity spend against pipeline mileage expansion, regulatory reassessment interval compression, and offshore wind installation forecasts.
Decision-makers should treat outputs as directional under base assumptions of sustained PHMSA enforcement intensity and EU F-Gas regulatory extension; material deviation in hydrocarbon demand trajectories or inspector certification reform would warrant model refresh. Recalibration cycles align with material shifts in API standards harmonization, offshore wind lease award timelines, and autonomous inspection hardware field deployment milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Oil and Gas Risk Management Market
Risk Management and Compliance
Southeast Asia Credit and Risk Management Market
Risk Management and Compliance
China Enterprise Risk Management Market
Risk Management and Compliance
Global Compliance Management Software Market
Risk Management and Compliance
Asia-Pacific BFSI Biometrics Market
Risk Management and Compliance
United States Strategic Consulting Services Market
Risk Management and Compliance
BFSI Security Market
Risk Management and Compliance
Global Risk and Compliance Consulting Services Market
Risk Management and Compliance
Quality Warranty Management Market
Risk Management and Compliance
Global Risk Management Software Market
Risk Management and Compliance
Crypto Compliance Software Market
Risk Management and Compliance
Surety Market
Risk Management and Compliance
Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
United States Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Medical Device Cyber Risk Quantification Market
Risk Management and Compliance
Global Energy Trading and Risk Management (ETRM) Market