
 Global Admissions Software Market | 2026-2036
Global Admissions Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Admissions Software Market Foresight
The transition from on-premise licensing to subscription-based cloud delivery is shifting procurement patterns across higher education technology budgets. Ellucian leverages its installed base across North American universities to sustain renewal rates. Salesforce competes through its Education Cloud ecosystem, while Technolutions anchors its position with Slate's dominance in graduate admissions workflows.
Admissions software encompasses cloud-deployed platforms that automate student enrollment, document verification, and fee collection through API-connected workflows with student information systems. These systems process application data against configurable business rules engines that route candidates through review stages. Cloud-based deployment leads the market as universities retire aging client-server installations, while subscription pricing models capture recurring revenue from institutions seeking predictable annual expenditures. Document management and reporting analytics represent the fastest-growing application segments as admissions offices confront rising application volumes.
FDA oversight does not extend to admissions software, yet FERPA compliance audits by the US Department of Education shape product architecture decisions for American vendors. GDPR enforcement by European data protection authorities and ISO 27001 certification requirements influence procurement specifications across OECD markets. Stakeholders must monitor how emerging AI-driven application review tools attract scrutiny from education regulators and civil rights enforcement bodies.
Market Dynamics
The migration from perpetual license models to recurring subscription structures is compressing vendor cash conversion cycles and forcing admissions technology providers to prioritize retention engineering over new-logo acquisition.
Growth Catalysts
- FERPA Compliance Mandates:US Department of Education audit protocols are compelling American universities to replace non-compliant legacy systems with auditable cloud platforms featuring granular access logging.
- API-First Architecture:Modern student information system integrations enable real-time data synchronization between admissions, financial aid, and registrar offices, eliminating manual transcript re-entry.
- Research-Intensive University Concentration:Doctoral-granting institutions in the United States, United Kingdom, and Australia generate disproportionate platform demand due to complex multi-stage graduate admissions workflows.
Market Restraints
- GDPR Data Residency Costs:European institutions face 15-25% infrastructure premiums to maintain student records within EU jurisdictional boundaries, constraining cloud vendor margins.
- Legacy System Entrenchment:Decades-old COBOL-based enrollment databases at mid-tier state universities create technical debt that resists API-layer abstraction.
- Substitute Process Automation:Low-code workflow tools from generalist enterprise software vendors capture simple application-routing use cases at one-third the specialized platform cost.
Strategic Opportunities
- India Higher Education Expansion:National Education Policy implementation is digitizing admissions at 1,000+ new autonomous colleges lacking legacy infrastructure.
- AI-Driven Document Verification:Machine learning models trained on transcript authentication are reducing manual review hours for international credential evaluation.
- Outcome-Based Pricing Models:Vendors pilot enrollment-yield guarantees where institutions pay proportional to matriculation rates rather than application volume processed.
Industry Challenges
- Interoperability Skill Scarcity:Admissions offices lack staff capable of configuring SIS-to-CRM data mappings, creating implementation bottlenecks.
- FERPA-GDPR Dual Certification:Vendors serving transatlantic university consortia must maintain parallel compliance frameworks with divergent breach notification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Admissions Software Market |
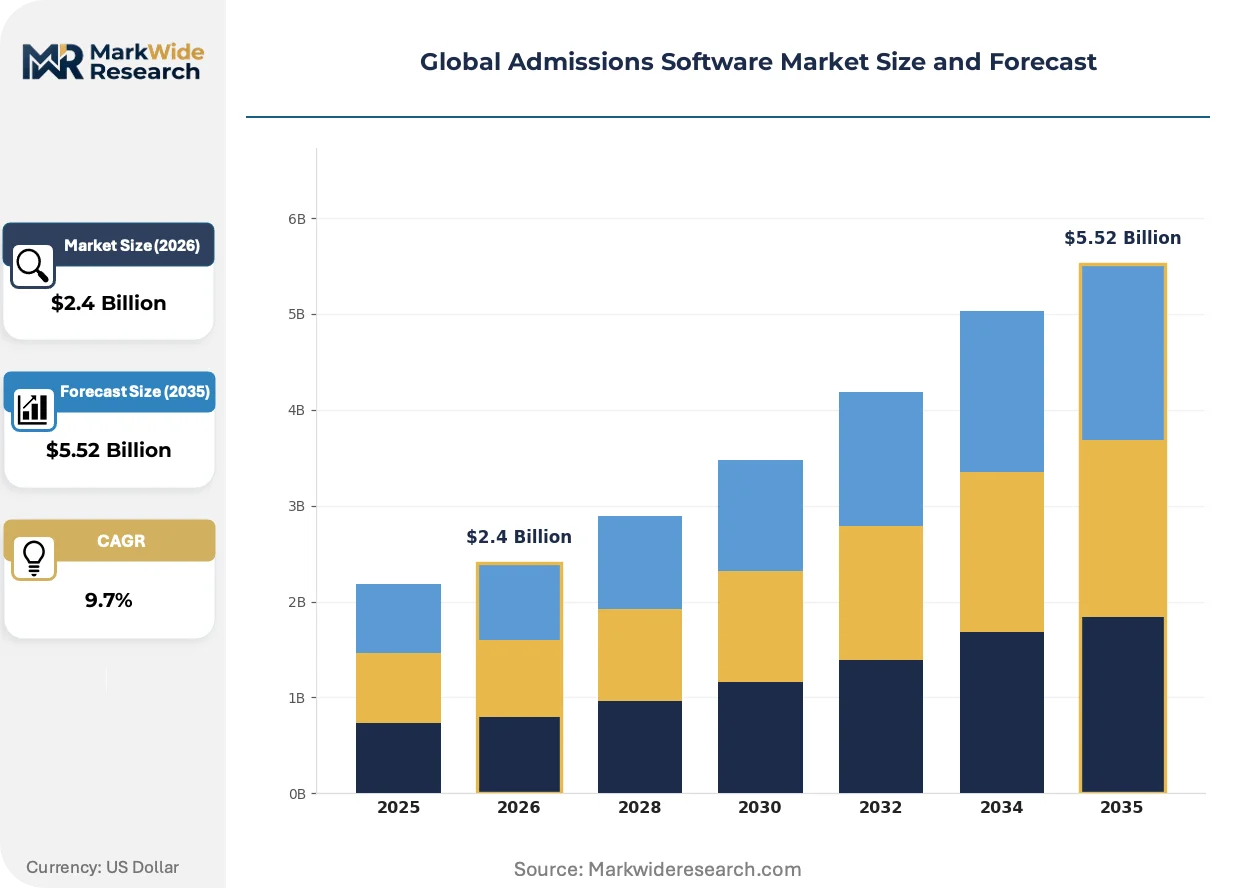
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Application: Student Enrollment, Document Management, Fee Processing, Interview Scheduling, Reporting & Analytics End User: Universities, Secondary Schools, Training Institutes, Language Centers, Vocational Schools Pricing Model: Subscription, One-Time License, Freemium, Pay-As-You-Go, Enterprise Licensing |
| Companies Covered | Ellucian, Blackbaud, Oracle, Technolutions (Slate), Jenzabar, Salesforce, Campus Management, SchoolMint, Hyland Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Admissions Software Market Shifts & Advancements
Admissions technology is converging around predictive analytics and automated decision support, compressing the traditional seasonal hiring cycle for temporary application readers.
Machine learning algorithms for holistic application review are absorbing pattern-recognition tasks previously assigned to admissions committees. Early-adopter institutions in the United States and Australia deploy these tools for initial candidate scoring, reducing median review time per file from 12 minutes to 4 minutes. The technology is absorbing routine screening functions while elevating human reviewers toward discretionary judgment calls.
GDPR Article 22 restrictions on automated decision-making are forcing European vendors to engineer human-in-the-loop checkpoints for any algorithmic admissions recommendation. French CNIL enforcement actions against three universities in 2023 established precedent that purely automated rejections violate data subject rights. Continental European institutions now mandate explainability dashboards showing which application elements triggered specific scoring outcomes.
Consolidated purchasing through shared services organizations is displacing individual campus procurement autonomy. Multi-campus systems in Texas, California, and England negotiate enterprise licenses covering 10-40 affiliated institutions simultaneously. This concentration is visible most acutely among public university systems seeking procurement efficiency targets mandated by state legislatures.
Global Admissions Software Market Segmentation
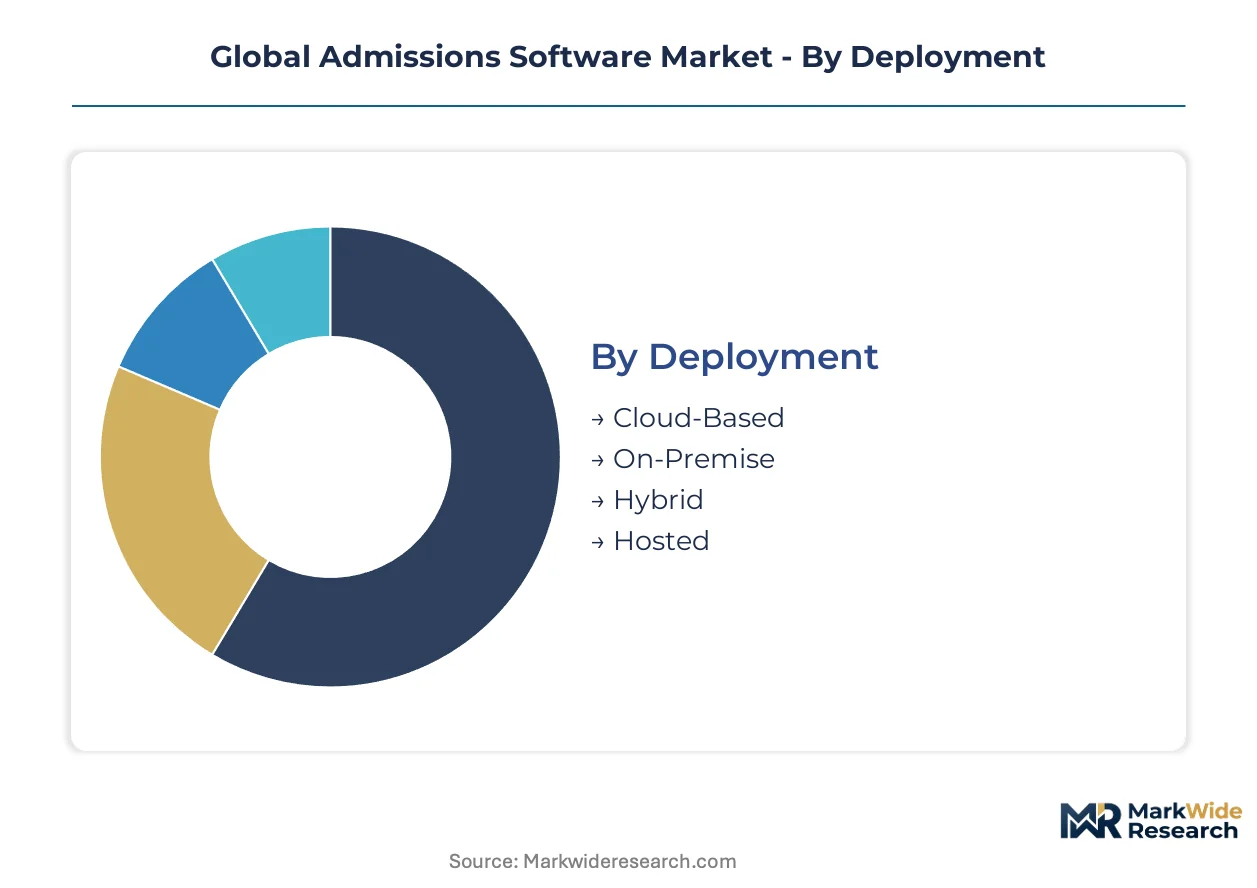
Admissions software segmentation reveals how deployment economics, application workflows, and procurement authority fragment across institution types. Each dimension carries distinct margin profiles and integration requirements that shape vendor product strategy.
Deployment:
Cloud-based platforms capture volume through predictable annual subscriptions, while on-premise installations retain premium pricing for institutions with stringent data control mandates.
- Cloud-Based:Multi-tenant SaaS architectures deliver automatic updates and elastic scaling during application surges. Research-intensive universities in the United States, the United Kingdom, and Australia favor these platforms for distributed admissions committee access across campuses. FERPA audit trails and GDPR data residency controls differentiate vendor offerings at the contract negotiation stage.
- On-Premise:Client-server installations running within institutional data centers provide complete physical control over student records. Demand concentrates among European universities facing CNIL scrutiny and Middle Eastern institutions with sovereign data requirements. These deployments carry 40-60% higher total cost of ownership over a seven-year lifecycle.
- Hybrid:Split architectures keep sensitive biometric data on-premise while routing routine workflows through cloud interfaces.
- Hosted:Single-tenant cloud deployments offer dedicated infrastructure without operational burden on university IT departments.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
Application:
Workflow automation intensity varies sharply across admissions functions, with document-heavy processes commanding premium module pricing.
- Document Management:OCR-enabled transcript parsing and credential verification engines process international academic records against standardized databases. Indian autonomous colleges and Australian Group of Eight universities deploy these tools to compress evaluation timelines for postgraduate applicants. Machine learning models trained on institutional historical data reduce manual review hours.
- Reporting & Analytics:Real-time dashboards tracking application funnel conversion, yield projections, and demographic diversity metrics inform enrollment strategy. United States doctoral-granting institutions use these capabilities to optimize financial aid packaging before National College Decision Day. GDPR Article 22 compliance requires explainability overlays for any algorithmic candidate scoring.
- Student Enrollment:Core application intake portals with configurable business rules routing candidates to appropriate review queues.
- Fee Processing:PCI-DSS compliant payment gateways handling application fee collection across multiple currencies.
- Interview Scheduling:Calendar synchronization tools coordinating multi-timezone availability for admissions committees and candidates.
Document Management commands the steepest expansion trajectory as application volumes rise across English-medium programs globally.
End User:
Procurement sophistication and integration complexity diverge dramatically between degree-granting institutions and non-degree training providers.
- Universities:Multi-departmental deployments spanning undergraduate, graduate, and professional schools with distinct workflow requirements. Public university systems in Texas and California negotiate enterprise licenses covering 10-40 campuses simultaneously. SIS integration depth determines vendor selection more than feature breadth.
- Secondary Schools:Simpler application routing with lighter compliance burdens and standardized export formats for university destination tracking.
- Training Institutes:Rapid-deployment needs without legacy system entanglement favor cloud-native platforms with minimal configuration.
- Language Centers:Seasonal enrollment spikes require elastic infrastructure for intensive application windows.
- Vocational Schools:Competency-based admissions criteria demand flexible scoring rubrics outside traditional GPA frameworks.
Universities generate the dominant revenue share. Training Institutes represent the most accessible new-logo opportunity.
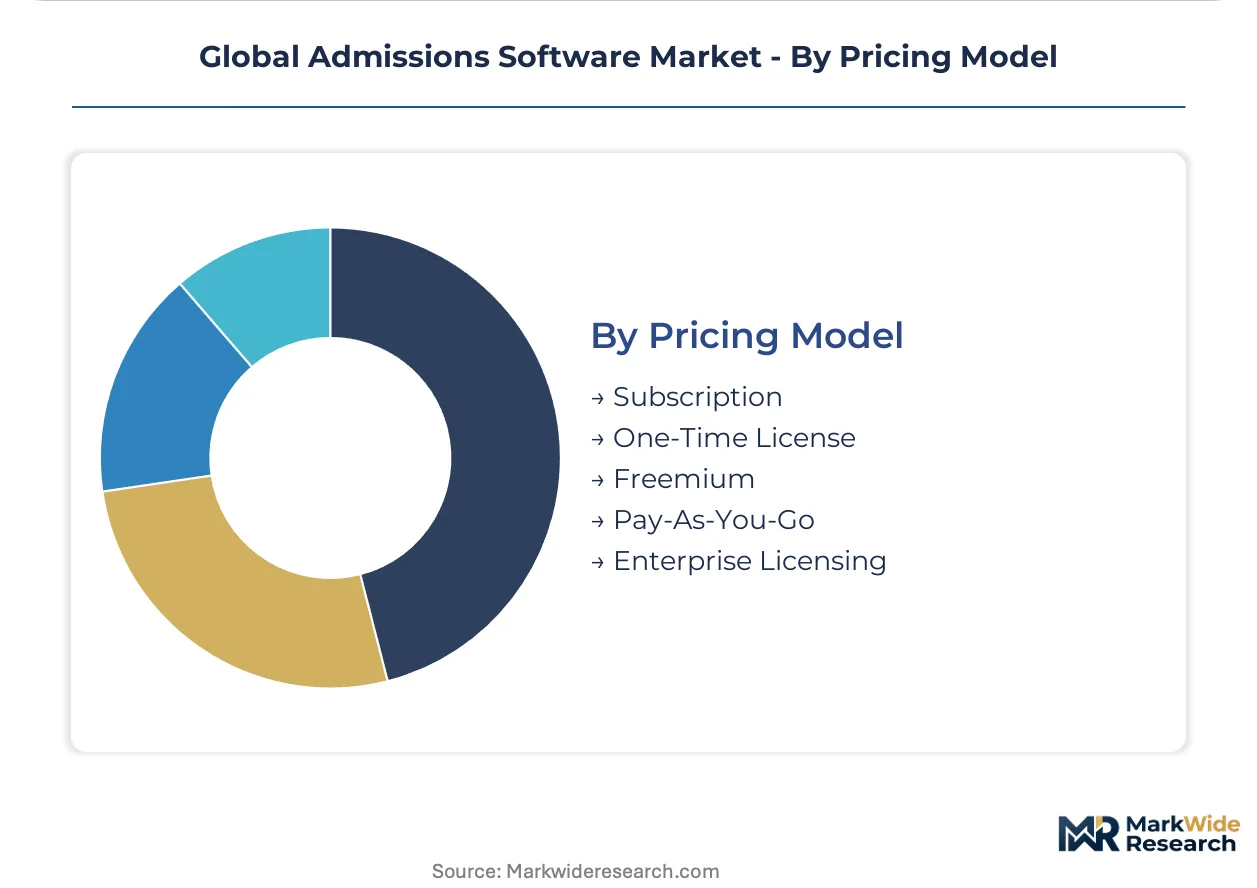
Pricing Model:
Revenue predictability versus customer acquisition friction defines the trade-off across commercial structures.
- Subscription:Annual recurring revenue models with tiered pricing based on application volume bands or active user counts. North American higher education technology budgets increasingly favor this expenditure predictability. Vendors prioritize retention engineering and expansion revenue over new-logo acquisition.
- Enterprise Licensing:Multi-year agreements with unlimited usage rights across consolidated university systems. Public sector procurement frameworks in England and Australia mandate these structures for transparency compliance.
- One-Time License:Perpetual software ownership with separate maintenance contracts common in legacy on-premise deployments.
- Freemium:Limited-feature entry tiers capturing small private colleges before expansion selling.
- Pay-As-You-Go:Transactional pricing tied to actual application volume processed, piloted by vendors testing outcome-based commercial models.
Subscription pricing dominates current bookings. Pay-As-You-Go experiments signal potential structural evolution toward enrollment-yield guarantees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor deployment strategies as cloud infrastructure costs diverge sharply between jurisdictions with stringent data residency mandates and those without. FERPA audit requirements in the United States impose compliance burdens that European GDPR frameworks amplify further, pushing some institutions toward hybrid architectures that segment sensitive records across geographies.
United States
Doctoral-granting universities in Massachusetts, California, and Texas generate concentrated platform demand for multi-stage graduate admissions workflows. The US Department of Education's FERPA audit protocols compel institutions to replace legacy client-server systems with cloud platforms featuring granular access logging. Boston's higher education technology cluster anchors significant procurement decision-making for research-intensive institutions nationwide.
United Kingdom
Russell Group universities drive sophisticated integration requirements between admissions, financial aid, and alumni advancement systems. The Information Commissioner's Office enforces GDPR Article 22 restrictions on automated admissions decisions, mandating human-in-the-loop checkpoints for algorithmic candidate scoring. London's EdTech procurement networks influence adoption patterns across English-medium programs globally.
Australia
Group of Eight universities deploy document verification engines to compress evaluation timelines for international postgraduate applicants. The Office of the Australian Information Commissioner enforces the Privacy Act's Australian Privacy Principles with breach notification timelines diverging from European frameworks. Melbourne and Sydney host concentrated vendor implementation teams serving Asia-Pacific expansion strategies.
Germany
Technical universities and research institutes prioritize on-premise deployments to satisfy sovereign data requirements under Federal Data Protection Act enforcement. The Conference of Independent Data Protection Authorities coordinates state-level scrutiny of cloud-based student record processing. Munich and Berlin clusters concentrate procurement authority for multi-campus technical university systems.
India
National Education Policy implementation is digitizing admissions at autonomous colleges lacking legacy infrastructure across Maharashtra, Karnataka, and Tamil Nadu. The Ministry of Education's Academic Bank of Credits mandates interoperable data standards that favor API-first platform architectures. Bangalore's higher education technology ecosystem is emerging as a regional hub for cloud-native deployment expertise.
Global Admissions Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue outcome-based commercial models and AI-augmented document verification. The vendor landscape fragments across three maturity tiers: legacy installed-base incumbents with renewal-focused strategies, cloud-native challengers with API-first architectures, and vertical specialists dominating graduate admissions workflows. Competitive positioning hinges on SIS integration depth rather than feature breadth. Consolidation pressures intensify as multi-campus systems negotiate enterprise licenses covering dozens of affiliated institutions simultaneously.
Within the legacy installed-base tier, Ellucian leverages its North American university footprint to sustain renewal engineering investments. Salesforce and Technolutions occupy distinct strategic positions: the former competes through Education Cloud ecosystem breadth, while the latter anchors graduate admissions specialization with Slate's workflow dominance. These three exemplify how vendor archetypes map to institutional procurement sophistication levels, with cloud-native platforms capturing new-logo opportunities at training institutes and vocational schools lacking technical debt entanglement.
| Leading Market Players |
|---|
| Ellucian |
| Blackbaud |
| Oracle |
| Technolutions (Slate) |
| Jenzabar |
| Salesforce |
| Campus Management |
| SchoolMint |
| Hyland Software |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists in admissions technology supply chains concentrate implementation expertise across Boston, London, and Melbourne clusters, tightening pricing discipline as vendor consolidation reduces competitive bidding room for university procurement offices.
Pricing Analysis
Direct-to-institution subscription contracts bypass distributor margins entirely, compressing channel economics for legacy on-premise resellers. Pricing stratifies across enterprise, mid-tier, and entry-level SaaS tiers with differentiation driven by API integration depth and FERPA audit certification status. Cost compression in entry-level tiers is intensifying because low-code workflow substitutes capture simple routing use cases. Training institutes and vocational schools exhibit highest price sensitivity; research-intensive universities with complex graduate workflows demonstrate lowest.
Supply Chain Analysis
Returns and data migration flows from legacy on-premise retirements create refurbishment revenue streams for implementation specialists serving European universities with GDPR Article 22 compliance requirements. Software development concentrates in the United States, the United Kingdom, and India with cloud infrastructure provisioning resting on hyperscaler data centers in Frankfurt, Dublin, and Singapore. Single-source vulnerability sits with API-gateway providers connecting admissions platforms to student information systems. Distribution runs through direct enterprise sales teams with limited channel partner penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
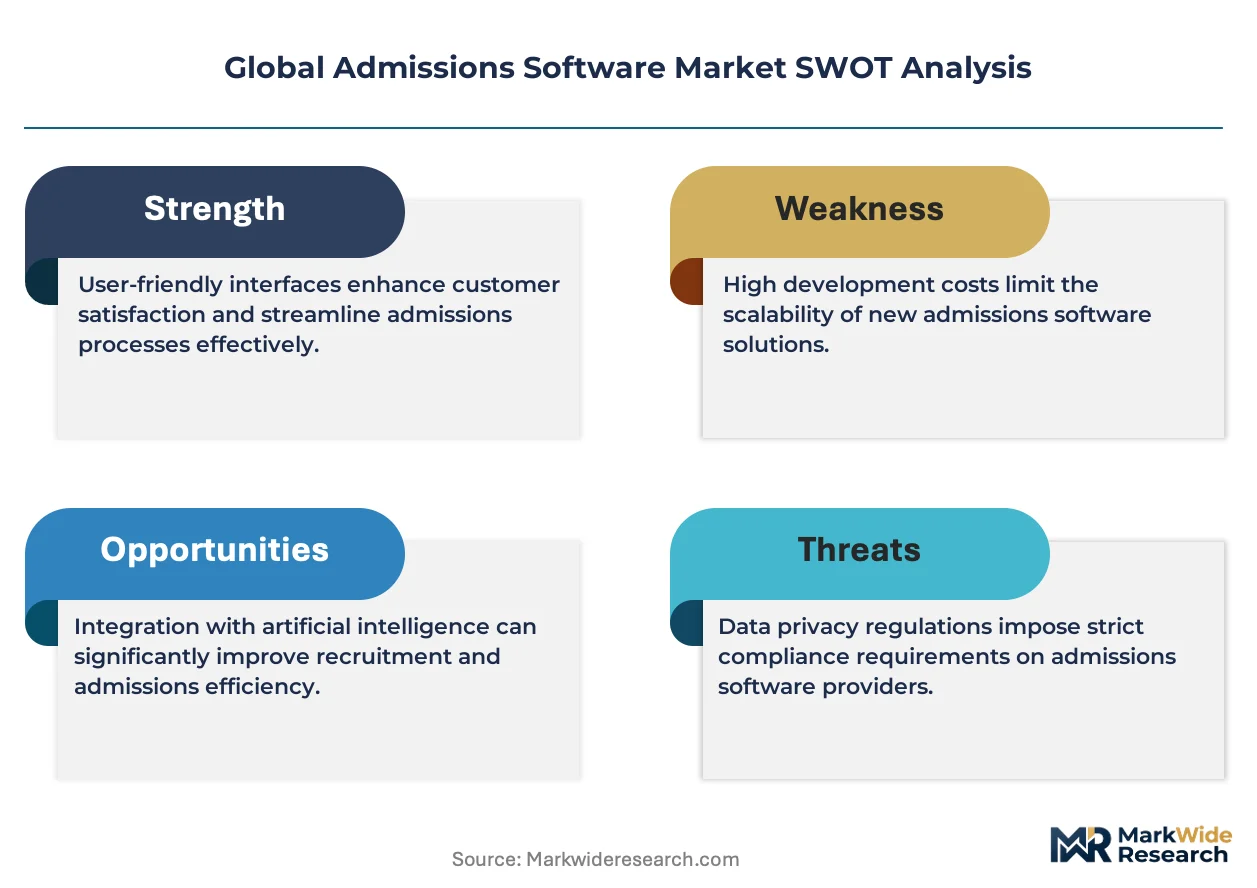
Analyst Recommendations
Global admissions software has entered late-cycle quality phase as procurement committees prioritize FERPA-compliant audit trails and GDPR Article 22 explainability dashboards over feature breadth in vendor selection.
For Market Incumbents: Acquire machine learning document verification capabilities to neutralize specialist challengers. Consolidate implementation partner networks in India and Australia to capture National Education Policy digitization waves. Deepen API-layer abstraction investments to displace COBOL-based legacy entrenchment at mid-tier state universities. For New Entrants and Emerging Players: Enter via AI-augmented transcript authentication modules targeting international credential evaluation bottlenecks at Australian Group of Eight universities. White-space concentrates in Indian autonomous colleges lacking legacy infrastructure across Maharashtra and Karnataka. Pursue outcome-based pricing pilots with enrollment-yield guarantees to differentiate from volume-based subscription incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid-deployment specialists with GDPR-FERPA dual certification capabilities and established SIS integration libraries. Long-term viability hinges on retention engineering economics as cloud-native platforms mature. Monitor CNIL enforcement patterns in France and ICO audit intensity in the United Kingdom for regulatory inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Document Verification | Machine learning models trained on international credential databases compress manual review hours at Australian universities. |
| API-First Architecture Investment | Real-time SIS synchronization eliminates transcript re-entry errors across Texas and California multi-campus systems. |
| Outcome-Based Pricing Pilot | Enrollment-yield guarantees align vendor revenue with institutional matriculation rates rather than application volume. |
| GDPR-FERPA Dual Certification | Parallel compliance frameworks capture transatlantic university consortia procurement with divergent breach notification timelines. |
| India Market Expansion | National Education Policy digitization creates 1,000+ autonomous college opportunities without legacy technical debt. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with university CIOs, admissions directors, SIS integration specialists, and procurement officers at shared services organizations with secondary validation against Department of Education FERPA audit protocols, ICO GDPR guidance documents, and hyperscaler education vertical disclosures. Bottom-up institutional spend estimates triangulated against top-down vendor revenue segmentation.
Historical reference periods anchored the projection horizon to pre-pandemic enrollment cycles and post-digital-acceleration baselines. The analytical framework modeled deployment architecture, application workflow intensity, end-user procurement sophistication, and regional regulatory cluster across the forecast period. CAGRs derived from institution-count growth, application-volume elasticity, and subscription pricing trajectory with inputs from cloud infrastructure cost curves and compliance audit frequency trends.
Inputs from vendor financial disclosures and university procurement databases were available through the study window; gaps in private institution spend transparency introduce uncertainty bands around mid-tier college penetration estimates. Forecasts reflect assumptions about FERPA audit enforcement intensity and GDPR Article 22 interpretation stability. Practitioners should monitor CNIL algorithmic decision rulings and US Department of Education audit protocol updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
Global Edutainment Centers Market
Education & Training
E Learning Virtual Reality Market
Education & Training
Flipped Classroom Market
Education & Training
Global Learning Management Systems (LMS) Market
Education & Training
Europe Leadership Development Program Market
Education & Training
Online Examination Service Market
Education & Training
Asia Pacific Strategic Consulting Services Market
Education & Training
Global Social Learning Platforms Market
Education & Training
North America IT Training Market
Education & Training
Corporate Learning Management System Market
Education & Training
Global Virtual Classroom Market
Education & Training
Digital English Learning Market
Education & Training
Europe K12 Education Market
Education & Training
Vocational English Course Counselling Solution Market
Education & Training
Europe Management Consulting Services Market
Education & Training
Frontline Workers Training Market