
 Glioblastoma Multiforme Treatment (GBM) Market | 2026-2036
Glioblastoma Multiforme Treatment (GBM) Market Size, Share, and Industry Trends Forecast 2026-2036
Glioblastoma Multiforme Treatment (GBM) Market Foresight
Adjuvant immunotherapy revenue is rewriting margin economics across the GBM treatment landscape. F. Hoffmann-La Roche Ltd anchors European oncology infrastructure through its established neuro-oncology portfolio. Merck & Co., Inc. dominates checkpoint inhibitor R&D with programs targeting glioblastoma's immunosuppressive microenvironment. Amgen, Inc. differentiates through bispecific antibody platforms engineered for blood-brain barrier penetration.
Glioblastoma Multiforme Treatment encompasses multimodal interventions for grade IV astrocytomas characterized by necrotic cores, microvascular proliferation, and IDH-wildtype molecular profiles, with temozolomide-based chemoradiation remaining the standard-of-care backbone following maximal safe surgical resection. The primary purpose spans cytoreduction, local disease control, and systemic life extension in a patient population with median survival historically measured in months. Immunotherapy represents the fastest-expanding treatment type as CAR-T and vaccine platforms target tumor-specific neoantigens. Monoclonal antibodies command concentrated R&D investment within drug class segmentation due to their validated engineering pathways and blood-brain barrier delivery innovations. Convection-enhanced delivery is gaining structural importance among delivery methods by enabling suprathreshold drug concentrations in tumor margins that systemic administration cannot achieve.
The FDA's Breakthrough Therapy designation and Orphan Drug Act incentives compress development timelines for glioblastoma therapies, while the EMA's PRIME scheme accelerates European access pathways for addressing this unmet medical need. ISO 14155 governs clinical investigation standards that shape trial conduct across jurisdictions, directly influencing which delivery innovations reach registrational studies. Stakeholders must monitor which blood-brain barrier platform achieves reproducible commercial scalability before committing manufacturing investment.
Market Dynamics
Convection-enhanced delivery systems are restructuring competitive positioning across the GBM treatment landscape by enabling suprathreshold drug concentrations at tumor margins that systemic administration cannot achieve.
Growth Catalysts
- FDA Accelerated Approval:The FDA's Breakthrough Therapy designation compresses development timelines for orphan oncology indications, pulling novel immunotherapies into earlier-phase commercialization.
- CAR-T Platform Maturation:Autologous cell therapy manufacturing is achieving reproducible scalability for glioblastoma neoantigen targeting, expanding addressable patient populations.
- German Hospital Consolidation:Specialized cancer hospitals in Germany are anchoring European treatment volume and cross-border research collaboration, concentrating demand for advanced neurosurgical interventions.
Market Restraints
- Blood-Brain Barrier Delivery Costs:Engineering bispecific antibodies and nanoparticle carriers for CNS penetration requires specialized manufacturing infrastructure that constrains margin economics.
- EMA Regulatory Friction:Divergent evidentiary requirements between FDA and EMA PRIME schemes create duplicative clinical investment for developers seeking transatlantic approval.
- Temozolomide Generic Substitution:Patent expiration of the chemoradiation backbone is compressing pricing power for standard-of-care regimens across mature markets.
Strategic Opportunities
- Japan's PMDA Sakigake Pathway:Japan's regenerative medicine framework offers conditional approval mechanisms for glioblastoma cell therapies ahead of full registrational data.
- Neuro-oncology Center Expansion:Academic medical centers in the United States are consolidating surgical, radiation, and immuno-oncology capabilities under single-site governance.
- Vaccine-Therapeutic Convergence:Combination of personalized neoantigen vaccines with checkpoint modulation represents unclaimed white space in adjuvant treatment sequencing.
Industry Challenges
- Neuro-oncology Specialist Scarcity:Fellowship-trained surgical neuro-oncologists and neuro-radiation oncologists remain concentrated at tertiary referral centers, limiting trial site activation.
- ISO 14155 Compliance Burden:Clinical investigation standards for device-drug combination delivery systems impose documentation requirements that extend study startup timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glioblastoma Multiforme Treatment (GBM) Market |
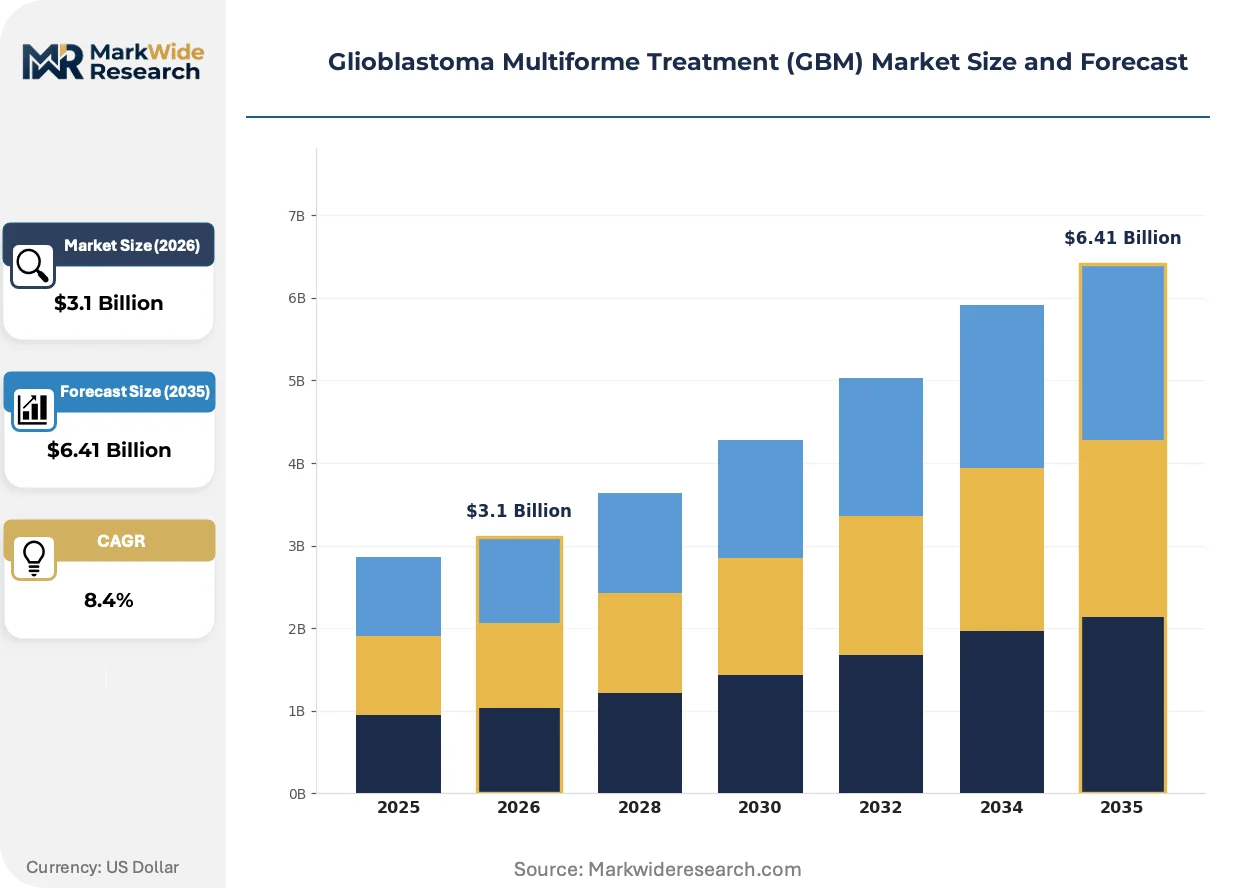
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.41 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Surgical Resection, Radiation Therapy, Chemotherapy, Targeted Therapy, Immunotherapy Drug Class: Alkylating Agents, Monoclonal Antibodies, Checkpoint Inhibitors, VEGF Inhibitors, Tyrosine Kinase Inhibitors Delivery Method: Oral Administration, Intravenous Injection, Intracranial Infusion, Convection-Enhanced Delivery, Implantable Wafers End User: Neurosurgical Centers, Oncology Clinics, Research Institutes, Specialized Cancer Hospitals |
| Companies Covered | Merck & Co., Inc., F. Hoffmann-La Roche Ltd, Amgen, Inc., Pfizer Inc., Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., Arbor Pharmaceuticals, LLC, Amneal Pharmaceuticals, Karyopharm Therapeutics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glioblastoma Multiforme Treatment (GBM) Market Shifts & Advancements
Digital biomarker platforms and real-world evidence infrastructure are compressing traditional clinical development cycles while reshaping how treatment response gets measured outside controlled trial settings.
Intratumoral microdosing protocols using implantable infusion catheters are virtualizing the traditional systemic chemotherapy paradigm. Neurosurgical centers at Duke University and MD Anderson are piloting programmable pump systems that enable chronic intermittent dosing directly into resection cavities. This architecture is virtualizing the pharmacokinetic assumptions that have governed glioblastoma drug development for two decades.
The FDA's Orphan Drug Act tax credit provisions and seven-year market exclusivity incentives are redirecting portfolio prioritization toward glioblastoma indications. Biotechnology developers are restructuring trial designs to capture accelerated approval pathways earlier in development. Small-cap oncology specialists are responding by front-loading CMC investment to meet manufacturing readiness requirements for breakthrough-designated programs.
Academic medical center procurement is consolidating supplier relationships around integrated delivery-device-drug bundles rather than discrete component purchasing. Hospital value analysis committees are displacing traditional physician preference item selection with total cost-of-care contracts that span surgical resection through adjuvant therapy. This behavioral shift is most visible in the United States, where integrated delivery networks are capturing neuro-oncology service lines under single vendor agreements.
Glioblastoma Multiforme Treatment (GBM) Market Segmentation
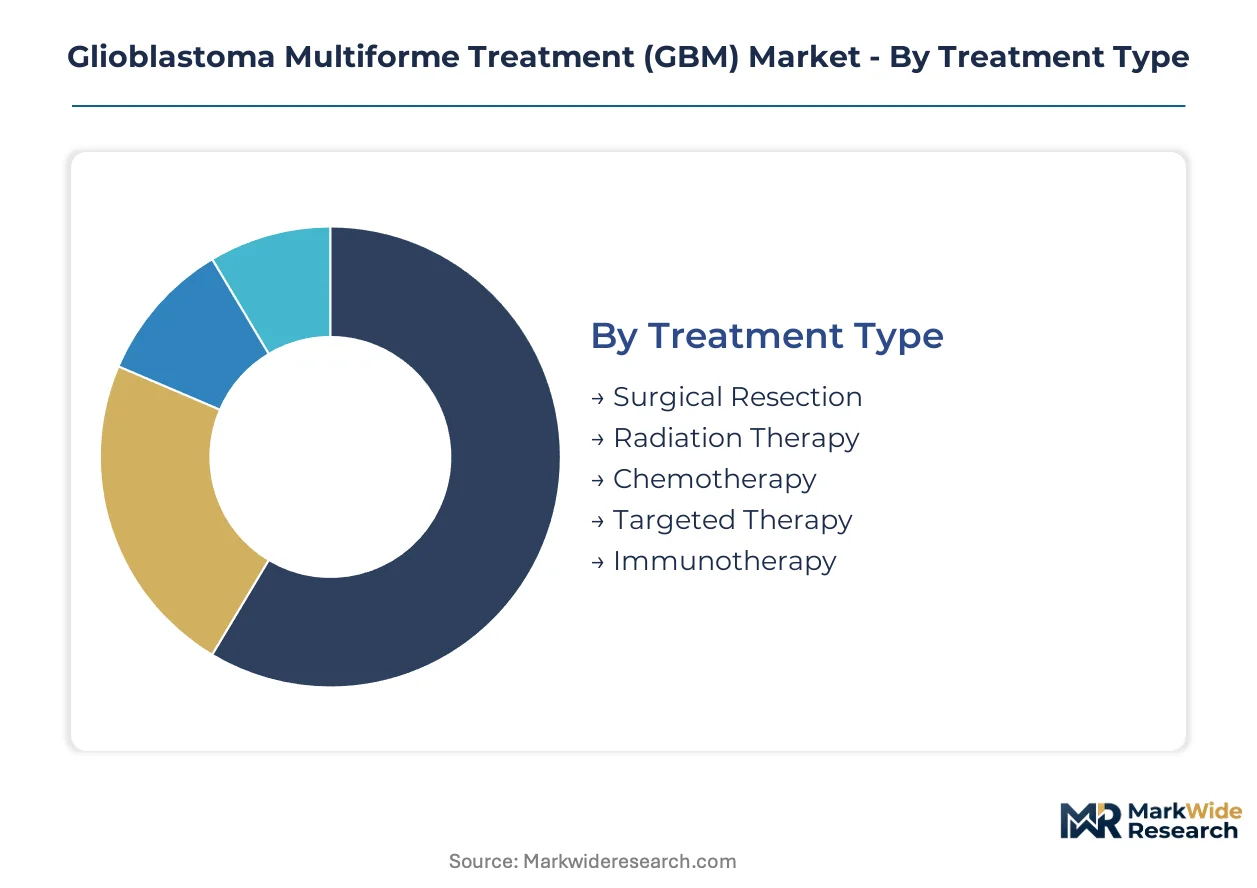
Glioblastoma treatment pathways fragment across intervention intensity, molecular targeting sophistication, and institutional capability requirements. Each segmentation dimension carries distinct reimbursement logic and capital deployment patterns that reshape competitive positioning.
Treatment Type:
The use-case spectrum spans cytoreductive surgery through systemic immunomodulation, with selection driven by resectability, molecular profile, and performance status.
- Surgical Resection:Maximal safe cytoreduction remains the foundational intervention, with extent of resection correlating directly to survival outcomes. Neurosurgical centers at Duke University and MD Anderson anchor demand concentration, driven by intraoperative MRI and fluorescence-guided resection technology adoption.
- Immunotherapy:CAR-T platforms and personalized neoantigen vaccines target tumor-specific antigens with engineered precision. German specialized cancer hospitals and US academic medical centers concentrate early adoption, propelled by FDA Breakthrough Therapy designation pathways that compress development-to-commercialization timelines.
- Radiation Therapy:Fractionated external beam protocols with temozolomide synchronization constitute standard-of-care adjuvant management. Oncology clinics in metropolitan hospital systems dominate volume.
- Chemotherapy:Temozolomide-based regimens anchor systemic treatment despite generic substitution pressures. Community oncology networks sustain prescription volume.
- Targeted Therapy:Molecularly directed agents address IDH-mutant and MGMT-methylated subpopulations with biomarker-selected precision. Research institutes coordinate companion diagnostic validation.
Established volume favors surgical resection; emerging adoption favors immunotherapy.
Drug Class:
Margin economics stratify across generic alkylating commoditization and engineered biologic premium capture.
- Monoclonal Antibodies:Bispecific platforms engineered for blood-brain barrier penetration command concentrated R&D investment. Amgen's neuro-oncology programs exemplify engineering pathways that validate manufacturing scalability.
- Checkpoint Inhibitors:PD-1/PD-L1 modulation targets glioblastoma's immunosuppressive microenvironment with combination trial expansion. Merck dominates clinical program breadth.
- Alkylating Agents:Temozolomide and nitrosoureas constitute the chemoradiation backbone with compressed pricing power post-patent expiration. Generic manufacturers capture volume.
- VEGF Inhibitors:Bevacizumab addresses tumor-associated edema and progression with antiangiogenic mechanism. Hospital outpatient infusion centers concentrate administration.
- Tyrosine Kinase Inhibitors:EGFR and other kinase targeting addresses molecularly defined subpopulations with oral bioavailability. Specialty pharmacy distribution channels dominate access.
Generic substitution erodes alkylating agent margins; biologic engineering premiums sustain monoclonal antibody investment.
Delivery Method:
Pharmacokinetic architecture determines CNS exposure thresholds and manufacturing infrastructure requirements.
- Convection-Enhanced Delivery:Implantable catheter systems enable suprathreshold drug concentrations in tumor margins that systemic administration cannot achieve. US neurosurgical centers pilot programmable pump architectures that virtualize traditional dosing paradigms.
- Oral Administration:Temozolomide and small-molecule kinase inhibitors leverage patient-administered convenience with established bioavailability profiles. Community oncology clinics sustain prescription volume.
- Intravenous Injection:Checkpoint inhibitors and monoclonal antibodies require infusion center infrastructure with cold-chain logistics. Hospital outpatient departments concentrate administration.
- Intracranial Infusion:Direct catheter-based delivery into resection cavities enables localized high-dose exposure. Academic medical centers coordinate surgical and medical oncology integration.
- Implantable Wafers:Biodegradable polymer matrices release chemotherapeutic agents directly into surgical beds. Neurosurgical centers with integrated device procurement govern adoption.
Systemic convenience anchors oral administration volume; locoregional efficacy gains favor convection-enhanced delivery expansion.
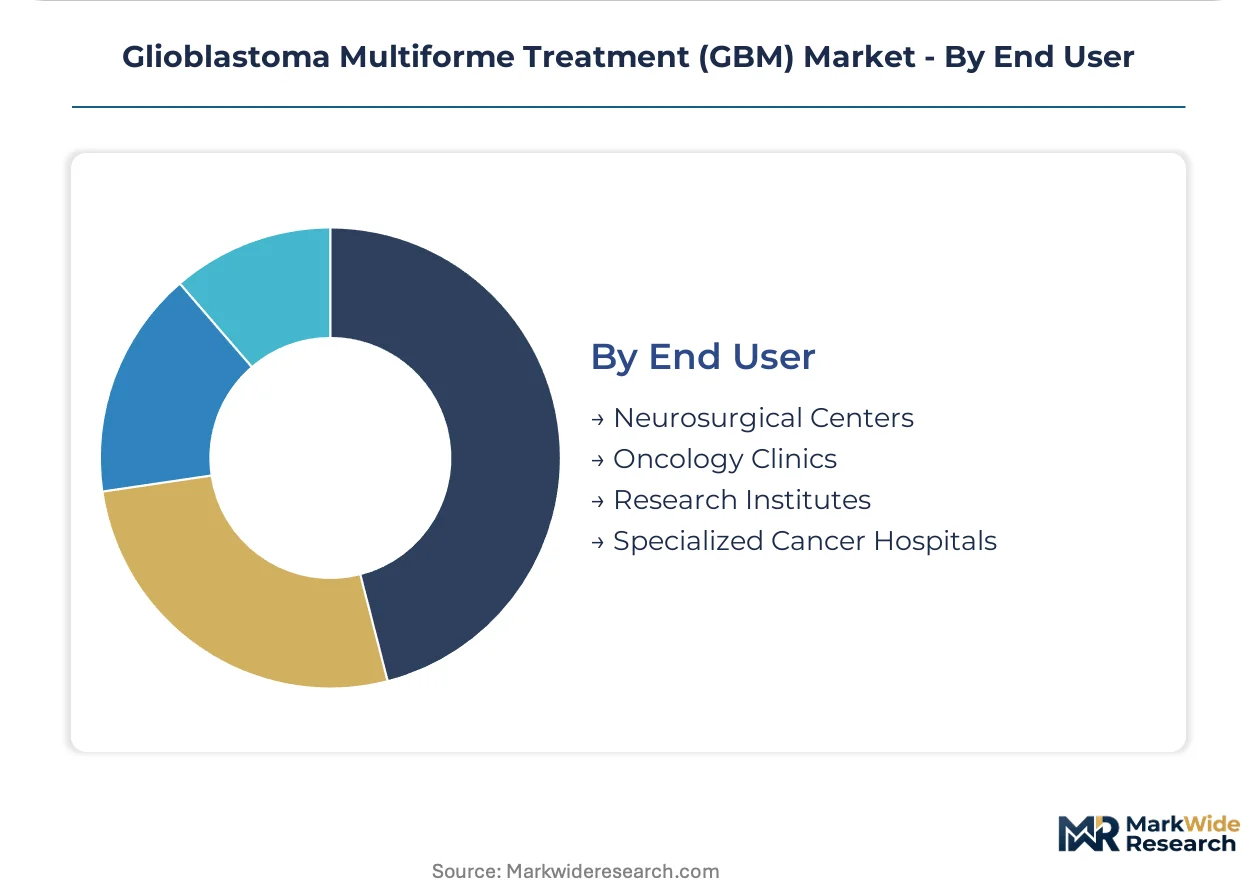
End User:
Institutional capability tiers determine access to surgical innovation, clinical trial infrastructure, and integrated care coordination.
- Neurosurgical Centers:Tertiary referral hubs with fellowship-trained surgical neuro-oncologists anchor resection volume and device-drug combination adoption. US academic medical centers consolidate radiation and immuno-oncology capabilities under single-site governance.
- Specialized Cancer Hospitals:German institutions anchor European treatment volume and cross-border research collaboration with centralized high-complexity case management.
- Oncology Clinics:Community and hospital-affiliated practices manage adjuvant chemotherapy and radiation with standardized protocols. Value analysis committees displace physician preference item selection.
- Research Institutes:Academic medical centers with NCI designation coordinate phase I/II trial activation and biomarker-driven patient selection. ISO 14155 compliance requirements shape site activation timelines.
Clinical trial concentration favors research institutes; commercial volume consolidation favors specialized cancer hospitals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies: German and Swiss buyers absorb premium pricing for blood-brain barrier platforms, while Indian and Brazilian markets remain anchored to generic temozolomide substitution. Price sensitivity concentrates where reimbursement infrastructure fragments.
United States
Duke University and MD Anderson anchor neurosurgical innovation through intraoperative MRI and fluorescence-guided resection technology adoption. FDA Breakthrough Therapy designation compresses commercialization timelines for orphan oncology indications. Academic medical centers in Greater Boston and the Pacific Northwest consolidate radiation and immuno-oncology capabilities under single-site governance.
Germany
Specialized cancer hospitals anchor European treatment volume and cross-border research collaboration with centralized high-complexity case management. EMA PRIME scheme accelerates access pathways for addressing unmet medical needs in glioblastoma. The Heidelberg and Munich metropolitan clusters concentrate fellowship-trained surgical neuro-oncologists and device procurement integration.
Japan
PMDA Sakigake pathway offers conditional approval mechanisms for glioblastoma cell therapies ahead of full registrational data. METI regenerative medicine framework redirects domestic biotechnology investment toward neuro-oncology indications. The Kanto region around Tokyo anchors clinical trial activation and biomarker-driven patient selection infrastructure.
India
CDSCO accelerated approval pathways for orphan drugs remain underdeveloped relative to Western regulators, constraining premium therapy access. Sun Pharmaceutical Industries Ltd. and domestic generic manufacturers capture volume through temozolomide commoditization. Maharashtra and Gujarat host concentrated oncology clinic networks managing adjuvant chemotherapy with standardized protocols.
Switzerland
Swissmedic alignment with EMA centralized procedures enables rapid market authorization for blood-brain barrier delivery innovations. Basel and Zurich anchor biotechnology R&D investment and manufacturing readiness for breakthrough-designated programs. The country's reimbursement infrastructure sustains premium pricing for engineered biologic platforms.
Glioblastoma Multiforme Treatment (GBM) Market Competitive Landscape
Capability concentration sits with biotechnology specialists engineering bispecific platforms for CNS penetration; scale advantage sits with diversified pharmaceutical conglomerates commanding checkpoint inhibitor portfolios. The market structures around three tiers: integrated oncology majors with neuro-oncology infrastructure, mid-cap immuno-oncology developers, and generic manufacturers capturing commoditized chemoradiation backbones. Dominant competitive moves include strategic partnerships for blood-brain barrier delivery technology and portfolio diversification into adjuvant immunotherapy sequencing.
Within the integrated oncology tier, Merck & Co., Inc. and F. Hoffmann-La Roche Ltd occupy positions exemplifying scale-driven R&D breadth and established European neuro-oncology infrastructure respectively. Amgen, Inc. represents the biotechnology specialist archetype focused on engineered biologic platforms. These three companies collectively illustrate the capability-scale spectrum reshaping competitive positioning across the GBM treatment landscape.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd |
| Amgen, Inc. |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Arbor Pharmaceuticals, LLC |
| Amneal Pharmaceuticals |
| Karyopharm Therapeutics, Inc. |
| Others |
Supply & Pricing Matrix
Undercapacity in CAR-T autologous cell manufacturing across US coastal hubs compresses pricing power for immunotherapy developers while inflating contract-manufacturing premiums. This utilization squeeze forces developers toward dual-sourcing strategies that fragment supply relationships and elevate total cost-of-care negotiations with integrated delivery networks.
Pricing Analysis
Project-based contracting dominates immunotherapy pricing, with milestone payments tied to FDA designation achievements and manufacturing readiness gates. Price differentiation hinges on blood-brain barrier penetration certification and companion diagnostic bundling. Cost compression in alkylating agent tiers intensifies because temozolomide generic substitution erodes branded pricing. Community oncology clinics exhibit highest price sensitivity, while academic medical centers absorb premium positioning for breakthrough-designated platforms.
Supply Chain Analysis
Lonza and Catalent concentration in mammalian cell culture capacity anchors biologic manufacturing for bispecific antibody programs. Active pharmaceutical ingredient sourcing draws from Switzerland, Singapore, and Ireland for high-potency oncology compounds. Supply chain risk centers on single-source vulnerability for implantable convection-enhanced delivery catheters. Distribution runs through hospital value analysis committees that consolidate procurement around integrated device-drug bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation in the United States, where single-vendor agreements for neuro-oncology service lines disaggregate traditional physician preference autonomy.
For Market Incumbents: Pre-empt emerging CAR-T platform developers by securing exclusive convection-enhanced delivery partnerships with Duke University and MD Anderson surgical hubs. Lock in backward integration into implantable pump manufacturing to defend margin position against device commoditization. Prioritize ISO 14155 certification investment to accelerate trial site activation timelines ahead of competitor submissions.
For New Entrants and Emerging Players: India's CDSCO regulatory gap for orphan oncology indications presents the most penetrable geographic entry point for biosimilar temozolomide formulations. White space concentrates in personalized neoantigen vaccine manufacturing for adjuvant sequencing. Pursue licensing arrangements with German specialized cancer hospitals to establish European clinical validation anchors before FDA submission.
For Investors and Strategic Acquirers: Long-term, this sits as a platform-technology play because blood-brain barrier delivery scalability determines which immunotherapy assets achieve commercial viability. Target acquisition candidates with validated convection-enhanced delivery catheter designs and programmable pump architectures. Watch for FDA Breakthrough Therapy designation density as the inflection signal for portfolio prioritization shifts among major oncology developers.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Breakthrough Therapy designation compresses development timelines for glioblastoma immunotherapies through FDA accelerated pathways. |
| Manufacturing Scale-Up | Autologous CAR-T production expansion at Lonza and Catalent facilities addresses capacity constraints for neoantigen-targeting platforms. |
| Regulatory Approval Pathway | EMA PRIME scheme alignment with FDA Breakthrough Therapy designations reduces duplicative clinical investment for transatlantic submissions. |
| Licensing Agreement | Blood-brain barrier platform partnerships with Amgen validate bispecific antibody engineering pathways for CNS penetration. |
| Pipeline Diversification | Checkpoint inhibitor combination trials with Merck expand addressable patient populations beyond monotherapy responders. |
Research Methodology
Desk research of FDA Breakthrough Therapy designation records, ClinicalTrials.gov protocol registries, and EMA PRIME eligibility assessments preceded structured interviews with neuro-oncology drug development executives, regulatory affairs leads at biotechnology firms, hospital formulary directors, and payer access specialists. Secondary validation drew from SEC oncology pipeline disclosures, CMS Medicare reimbursement data, and German hospital procurement databases. Bottom-up patient-flow modeling triangulated against top-down pharmaceutical revenue estimates across treatment type and drug class segmentations.
Assumptions held FDA and EMA regulatory pathway convergence stable while varying blood-brain barrier platform commercialization timelines across the projection horizon. Segmentation dimensions modeled encompassed treatment line intensity, molecular targeting sophistication, delivery method pharmacokinetic architecture, and regional regulatory cluster differentiation. CAGRs derived from log-linear trend fitting to historical approval velocity and manufacturing capacity expansion rates. Forecast inputs incorporated neurosurgical center adoption curves for convection-enhanced delivery and generic substitution elasticity for temozolomide commoditization.
Practitioners should monitor FDA Breakthrough Therapy designation grant rates and EMA PRIME scheme admission velocity for early signals of regulatory pathway efficiency shifts. Forecasts reflect assumptions regarding immunotherapy manufacturing scalability and blood-brain barrier platform validation trajectories. Quarterly review of neurosurgical center procurement consolidation indicators and CAR-T manufacturing capacity utilization reports is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Glucagon Therapy Market
Specialty Medicine
Benign Positional Vertigo Market
Specialty Medicine
Global Bladder Disorders Market
Specialty Medicine
Progressive Supranuclear Palsy (PSP) Market
Specialty Medicine
Ulcerative Colitis Market
Specialty Medicine
Vesicoureteral Reflux Market
Specialty Medicine
Botulism Treatment Market
Specialty Medicine
Global Female Sexual Dysfunction Treatment Market
Specialty Medicine
Global Gastrointestinal Stromal Tumors Market
Specialty Medicine
Whim Syndrome Management Market
Specialty Medicine
Global Cough Hypersensitivity Syndrome Treatment Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
Global Pigmentation Disorders Treatment Market
Specialty Medicine
Hypothyroidism Market
Specialty Medicine
Ischemic Hepatitis Treatment Market
Specialty Medicine
Lamellar Ichthyosis Treatment Market