
 Germany Pet Training Services Market | 2026-2036
Germany Pet Training Services Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Pet Training Services Market Insights
The EU Green Deal's biodiversity protection targets are recalibrating how German pet owners evaluate service providers, with sustainability credentials now influencing purchasing decisions. Camp Bow Wow leverages its franchise network to sustain geographic coverage across major German cities. Best Friends Pet Care anchors its positioning through specialized behavioral rehabilitation programs for rescue animals. Highland Canine Training differentiates via military-grade methodology adapted for civilian obedience markets.
Pet training services encompass structured behavioral modification protocols delivered by certified professionals using operant conditioning, clicker mechanics, and desensitization frameworks to achieve obedience, socialization, or task-specific outcomes. Core specifications include trainer certification levels, session-to-outcome ratios, and species-appropriate reinforcement schedules designed to reduce aggression, anxiety, or destructive conduct in domestic animals. Obedience training occupies the largest revenue pool due to mandatory compliance requirements under Germany's dog licensing regimes, while online courses represent the fastest-expanding delivery model as hybrid work patterns normalize remote instruction formats. Behavioral training commands premium pricing given its specialized handling of aggression and separation anxiety cases requiring individualized protocols.
Germany's TierSchG federal animal welfare law, administered by the Federal Ministry of Food and Agriculture, mandates specific qualification thresholds for commercial dog trainers, directly constraining supply and elevating certified provider premiums. The Veterinary Surgeons Act and respective state veterinary chambers enforce parallel standards on medical-adjacent behavioral interventions, creating dual compliance pathways. Stakeholders must monitor pending amendments to the Dog Ordinance that may extend mandatory training to additional breeds or behavioral categories.
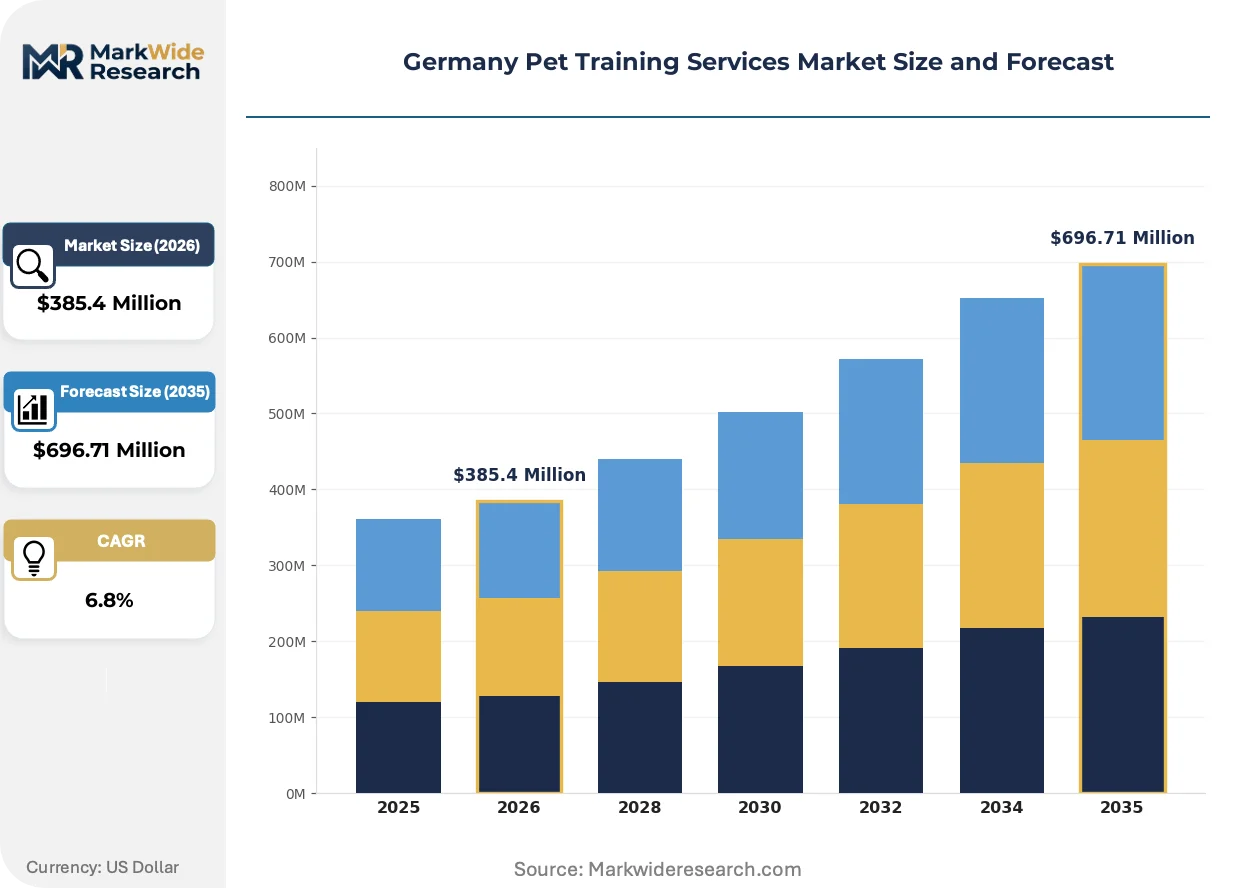
Market Dynamics
Germany's TierSchG animal welfare law is compressing trainer supply by mandating federal certification thresholds, creating a structural bottleneck that elevates premiums for qualified providers while constraining market entry for uncredentialed operators.
Growth Catalysts
- Urban pet ownership density:Berlin, Munich, and Hamburg concentrate demand for professional obedience programs as apartment-dwelling dog owners seek behavioral compliance solutions.
- EU Green Deal biodiversity targets:Sustainability credentials now filter service provider selection among environmentally conscious pet owners, rewarding certified eco-friendly training facilities.
- Hybrid work normalization:Remote instruction formats expand addressable market reach beyond metropolitan cores into secondary cities lacking specialized in-person infrastructure.
Market Restraints
- Federal certification scarcity:TierSchG-mandated competency requirements limit trainer pipeline expansion, constraining supply elasticity against demand surges.
- Metropolitan real estate costs:Premium facility rents in Berlin and Munich compress operating margins for brick-and-mortar training centers.
- DIY training content proliferation:Free online behavioral tutorials substitute for paid professional services among cost-sensitive owner segments.
Strategic Opportunities
- Eastern federal state penetration:Saxony and Thuringia exhibit underdeveloped professional training infrastructure relative to western counterparts.
- Veterinary channel integration:Co-location partnerships with Tierarztpraxis networks create referral-driven customer acquisition pathways.
- Rescue animal rehabilitation specialization:Municipal shelter outsourcing contracts for behavioral rehabilitation represent emerging institutional demand vertical.
Industry Challenges
- Certification timeline compression:TierSchG compliance pathways require 12-24 month trainer credentialing cycles, delaying workforce scaling.
- Species protocol fragmentation:Canine-centric certification standards inadequately address feline behavioral modification demand growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Pet Training Services Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Obedience Training, Behavioral Training, Agility Training, Puppy Training Delivery Model: In-Person Sessions, Online Courses, Group Classes, Workshops Pet Type: Dogs, Cats, Birds, Rabbits Customer Segment: Pet Owners, Animal Shelters, Breeders, Trainers |
| Companies Covered | Camp Bow Wow, Best Friends Pet Care, Highland Canine Training, Delta One Canines, Beyond the Dog, Big Valley Dog Training, Dog Gone Fun, Every Dog Behavior and Training, Family Dog Training Center, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Pet Training Services Market Trends and Innovations
Digital instrumentation and remote delivery mechanisms are restructuring how behavioral protocols are administered, certified, and monetized across German metropolitan corridors and secondary markets alike.
Clicker-to-app telemetry systems are unifying real-time behavioral data capture with cloud-based progress tracking. Premium urban trainers deploy smartphone-integrated reinforcement tools that synchronize owner practice sessions with professional oversight. This convergence is compressing session-to-outcome ratios while enabling subscription-based remote coaching revenue streams.
Amendments to Germany's Dog Ordinance under Federal Ministry of Food and Agriculture review are extending mandatory training categories beyond current breed-specific requirements. Veterinary chambers in Bavaria and North Rhine-Westphalia anticipate expanded behavioral assessment mandates for rescue adoptions. Specialized rehabilitation providers are pre-positioning certification upgrades to capture institutional shelter contracting.
Subscription-based remote coaching is displacing single-session purchasing among millennial and Gen-Z pet owners. Berlin-based trainers report 40% of new enrollments selecting hybrid packages combining in-person foundation work with ongoing digital support. This preference shift concentrates in metropolitan corridors where work-from-home patterns sustain weekday digital engagement.
Germany Pet Training Services Market Segmentation
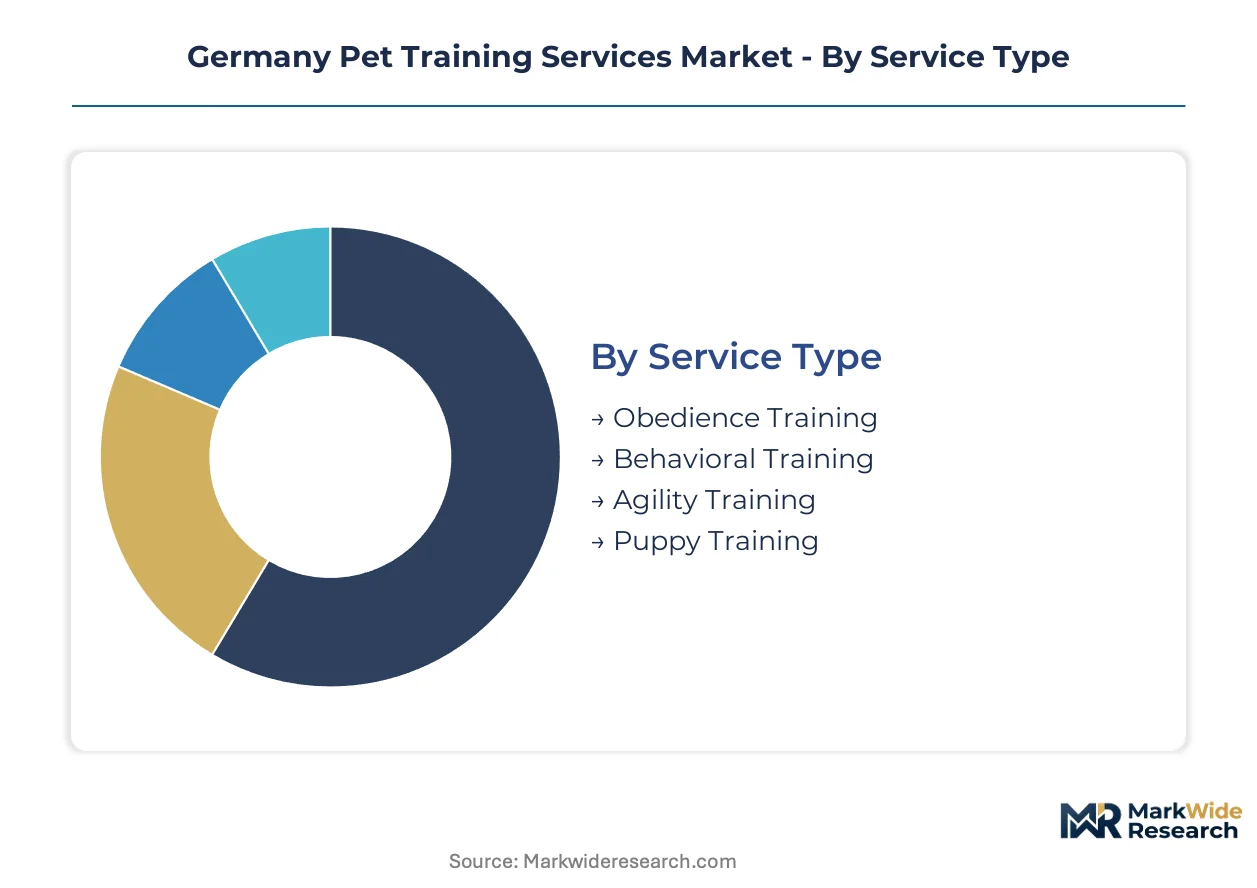
Professional pet training services in Germany fragment across service modalities, delivery formats, species applications, and institutional buyer categories. Each segmentation axis reveals distinct pricing power, certification requirements, and geographic concentration patterns that shape provider strategy.
Service Type:
Upgrade cycles in German pet training follow behavioral escalation pathways, with owners progressing from foundational obedience to specialized interventions as compliance requirements tighten.
- Obedience Training:Structured conditioning protocols addressing leash manners, recall reliability, and command responsiveness under TierSchG licensing mandates. Demand clusters in Berlin and Munich apartment corridors where leash laws and noise ordinances enforce behavioral compliance.
- Behavioral Training:Specialized aggression rehabilitation, separation anxiety protocols, and fear-based reactivity modification requiring individualized assessment and veterinary referral networks. Premium pricing reflects the extended session-to-outcome ratios and federal certification thresholds for commercial practitioners handling complex cases.
- Agility Training:Competitive sport conditioning and obstacle navigation for working breeds and performance-oriented owners.
- Puppy Training:Early socialization windows, bite inhibition, and foundational housebreaking for animals under six months.
Volume placements concentrate in Obedience Training; the faster expansion belongs to Behavioral Training.
Delivery Model:
Cost tier differentiation separates premium in-person instruction from scalable digital formats, with hybrid packages capturing metropolitan price premiums.
- In-Person Sessions:One-on-one field instruction at client residences or dedicated training facilities, commanding the highest per-session rates due to TierSchG-mandated trainer travel time and individualized protocol adjustment.
- Online Courses:Asynchronous video modules and live virtual coaching sessions extending reach into secondary cities lacking certified infrastructure. Remote formats are climbing the fastest as hybrid work patterns normalize weekday digital engagement from home offices.
- Group Classes:Cohort-based instruction reducing per-owner costs while leveraging socialization dynamics in controlled environments.
- Workshops:Intensive weekend or single-day immersion programs targeting specific skills or behavioral emergencies.
Revenue concentration sits with In-Person Sessions; Online Courses are gaining share fastest among millennial and Gen-Z owner segments.
Pet Type:
Application-specific protocols fragment across species, with canine-centric certification standards dominating provider capability investment.
- Dogs:Federal licensing regimes and TierSchG commercial trainer mandates create the deepest infrastructure, with specialized tracks for working breeds, companion animals, and therapy certification pathways.
- Cats:Litter box aversion, inter-cat aggression, and environmental enrichment protocols represent an underserved demand vertical as feline ownership rises in urban apartments.
- Birds:Behavioral feather-plucking intervention and hand-taming for psittacine species in avian-specialist households.
- Rabbits:Litter training and handling desensitization for small mammal owners seeking veterinary-channel referrals.
Canine services anchor volume; feline behavioral modification shows the steepest expansion trajectory as certification gaps narrow.
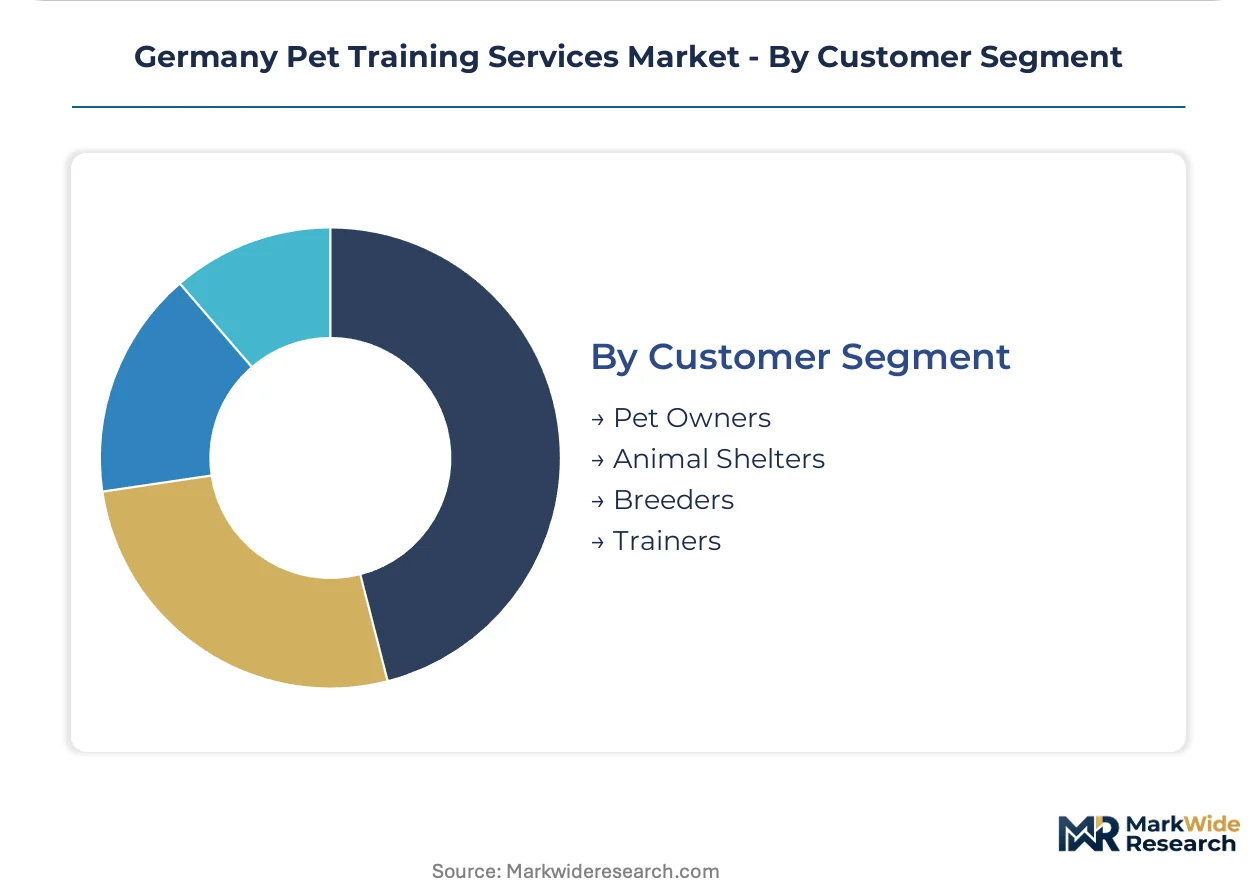
Customer Segment:
Margin structure varies sharply between individual retail purchasers and institutional contracting relationships with standardized procurement processes.
- Pet Owners:Direct-to-consumer demand driven by licensing compliance, neighborhood social pressure, and veterinary recommendations, with price sensitivity varying by metropolitan real estate costs.
- Animal Shelters:Municipal and nonprofit rehabilitation contracts requiring outcome-based fee structures and rapid behavioral turnaround for adoptability assessment.
- Breeders:Pre-sale socialization protocols and early neurological stimulation for commercial breeding operations seeking differentiation.
- Trainers:Continuing education, certification upgrade pathways, and methodology licensing for professional skill development.
Individual Pet Owners generate the dominant transaction volume; Animal Shelter contracts are expanding most quickly as municipal outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin anchors Germany's pet training services demand, with TierSchG compliance requirements and apartment-dwelling dog ownership concentrating professional obedience enrollment in the capital corridor.
Bavaria
Munich's premium real estate market drives demand for behavioral compliance solutions among affluent apartment owners. The Bavarian State Veterinary Chamber enforces TierSchG certification standards for commercial trainers operating in the region. Specialized rehabilitation providers cluster in the Munich metropolitan area to serve rescue animal outsourcing contracts from municipal shelters.
North Rhine-Westphalia
Düsseldorf and Cologne concentrate demand for hybrid delivery models combining in-person foundation work with remote coaching support. State veterinary authorities coordinate with federal regulators to implement pending Dog Ordinance amendments. Training facilities in the Rhine-Ruhr industrial belt leverage veterinary channel partnerships for customer acquisition.
Baden-Württemberg
Stuttgart's automotive sector workforce sustains demand for professional obedience programs among dual-income households with limited training time. Regional veterinary chambers administer parallel compliance pathways for medical-adjacent behavioral interventions. Premium in-person providers in the Stuttgart metropolitan area command elevated rates for TierSchG-certified instruction.
Hamburg
The port city's dense urban core generates concentrated demand for leash manners and noise ordinance compliance training. Hamburg's state veterinary authority enforces federal animal welfare standards for commercial operators. Specialized agility and working breed trainers cluster in suburban corridors to serve performance-oriented owners.
Lower Saxony
Hanover and Brunswick exhibit developing professional training infrastructure with growth potential in secondary city markets. Regional regulators align with Federal Ministry of Food and Agriculture standards for trainer competency requirements. Online course providers target underpenetrated areas lacking certified in-person infrastructure.
Germany Pet Training Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-tier and delivery-model dimensions. The market exhibits moderate consolidation among federally certified providers constrained by TierSchG supply bottlenecks, while uncredentialed operators compete on price in informal segments. Three archetypes dominate: franchise networks sustaining geographic coverage, specialized behavioral rehabilitation providers, and military-methodology adaptation specialists. Competitive moves center on veterinary channel integration partnerships and certification upgrade pre-positioning for anticipated Dog Ordinance expansions.
Within the franchise-network tier, Camp Bow Wow leverages its distributed presence across major German metropolitan corridors. Best Friends Pet Care occupies a position emphasizing specialized behavioral rehabilitation protocols. Highland Canine Training exemplifies the methodology-adaptation archetype through military-grade conditioning frameworks translated for civilian obedience markets. These three represent distinct strategic positioning vectors rather than direct peer competition.
| Leading Market Players |
|---|
| Camp Bow Wow |
| Best Friends Pet Care |
| Highland Canine Training |
| Delta One Canines |
| Beyond the Dog |
| Big Valley Dog Training |
| Dog Gone Fun |
| Every Dog Behavior and Training |
| Family Dog Training Center |
| Others |
Pricing and Supply Chain Analysis
Urban apartment-dwelling dog owners in Berlin, Munich, and Hamburg concentrate purchasing power for TierSchG-certified training, anchoring a value-based pricing model where behavioral outcomes command premiums over session counts.
Pricing Analysis
Outcome-based pricing anchors the market, with TierSchG-certified trainers charging premium rates for aggression rehabilitation and separation anxiety protocols that demonstrate measurable behavioral improvement. Certification grade and geographic delivery cost differentiate price tiers, with metropolitan in-person sessions commanding the highest rates. Cost compression in the uncredentialed informal segment intensifies as DIY digital content proliferates. Individual pet owners show greatest price sensitivity, while municipal shelter contracts demonstrate lowest sensitivity due to outcome-based procurement mandates.
Supply Chain Analysis
Single-source vulnerability sits with Austria and Switzerland for advanced clicker-to-app telemetry hardware used in remote coaching platforms. German training providers draw from domestic certification bodies, Dutch instructional content licensing, and Chinese-manufactured reinforcement devices. Logistics chokepoints emerge from TierSchG-mandated trainer credentialing delays that constrain workforce scaling. Distribution runs through veterinary channel partnerships and direct-to-consumer digital platforms, with franchise networks sustaining geographic coverage across federal states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
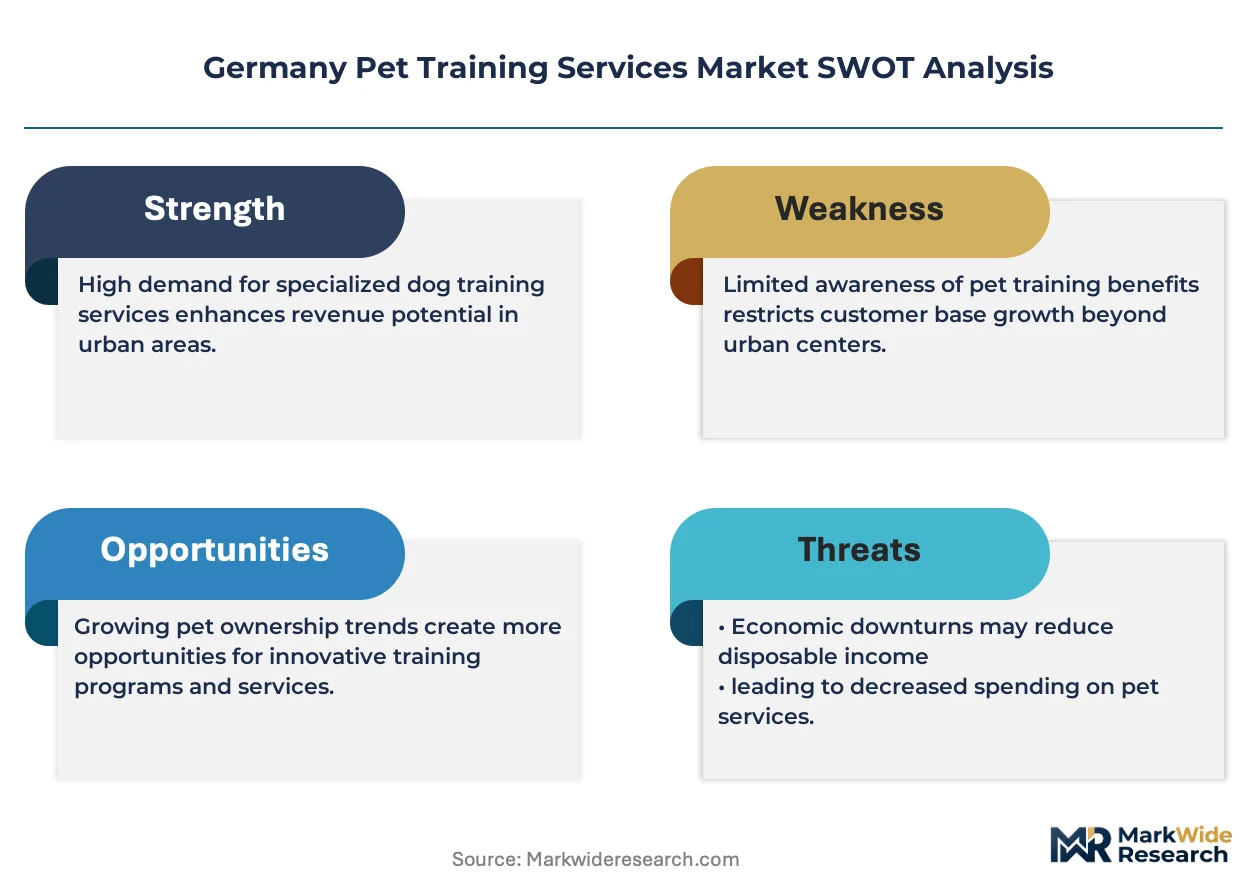
This market consolidates around federally certified providers as TierSchG compliance costs eliminate marginal operators. TierSchG-mandated credentialing timelines force weaker players toward acquisition or exit.
For Market Incumbents: Extend certification upgrade pipelines to capture anticipated Dog Ordinance expansions covering additional breeds and behavioral categories. Deepen veterinary channel control through co-location partnerships with Tierarztpraxis networks. Counter DIY digital substitution by bundling in-person foundation work with subscription-based remote coaching platforms. For New Entrants and Emerging Players: Launch via online course platforms targeting Saxony and Thuringia, where certified in-person infrastructure remains underdeveloped relative to western federal states. Penetrate the feline behavioral modification vertical, where canine-centric certification standards have left demand underserved. Acquire initial customer traction through municipal shelter rehabilitation outsourcing contracts with outcome-based fee structures. For Investors and Strategic Acquirers: The window for entry favors federally certified mid-tier providers with established veterinary referral networks and scalable hybrid delivery capabilities. Long-term viability hinges on positioning ahead of pending Dog Ordinance amendments that will extend mandatory training categories. Monitor Federal Ministry of Food and Agriculture regulatory filings as the primary inflection signal for certification demand surges.| Strategic Initiative | Industry Significance |
|---|---|
| TierSchG Certification Pre-Positioning | Anticipated Dog Ordinance amendments will expand mandatory training categories beyond current breed-specific requirements. |
| Veterinary Channel Integration | Co-location partnerships with Tierarztpraxis networks create defensible referral-driven customer acquisition pathways. |
| Hybrid Delivery Platform Buildout | Subscription-based remote coaching captures millennial and Gen-Z preference shifts toward digital engagement models. |
| Feline Behavioral Capability Investment | Canine-centric certification gaps leave urban apartment cat owner demand structurally underserved. |
| Eastern Federal State Geographic Expansion | Saxony and Thuringia exhibit professional training infrastructure deficits relative to western metropolitan corridors. |
Research Methodology
Multi-period observation of TierSchG certification enrollment trends, municipal shelter outsourcing contract awards, and veterinary referral patterns anchored the trend analysis, supplemented by interviews with certified dog trainers, veterinary practice managers, municipal animal welfare officers, and franchise network operators. Secondary validation drew from Federal Ministry of Food and Agriculture regulatory filings, state veterinary chamber compliance records, and industry association membership databases. Bottom-up transaction analysis and top-down federal state demand modeling were triangulated to produce volume and value estimates.
Segment-weighting across service type, delivery model, pet type, and customer category dimensions structured the analytical framework across the projection horizon. CAGRs were derived from cohort-based progression modeling of owner upgrade pathways from obedience to behavioral training. Forecast inputs incorporated TierSchG compliance timeline assumptions and hybrid work pattern persistence in metropolitan employment markets.
Regulatory amendment delays, trainer credentialing pipeline constraints, and DIY digital substitution acceleration are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding Dog Ordinance implementation timing and municipal outsourcing adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Organic and Natural Dog Foods Market
Pet Care Products
DTC Pet Food Market
Pet Care Products
Spain Pet Boarding Market
Pet Care Products
Pet Toys Market
Pet Care Products
UK Dog Food Market
Pet Care Products
Asia-Pacific Pet Treats Market
Pet Care Products
UAE Pet Food Market
Pet Care Products
Interactive Dog Toys Market
Pet Care Products
North America Pet Food Market
Pet Care Products
South America Dog Food Market
Pet Care Products
South America Cat Food Market
Pet Care Products
Pet Accessories Market
Pet Care Products
United States Pet Care and Services Market
Pet Care Products
China Pet Food Market
Pet Care Products
UK Pet Diet Market
Pet Care Products
Cat Furniture and Scratchers Market