
 Germany Pet Insurance Market | 2026-2036
Germany Pet Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Pet Insurance Market Intelligence
The EU Green Deal's extension into animal welfare reporting obligations is recalibrating how German insurers structure product liability and coverage transparency. Uelzener Allgemeine Versicherungs-Gesellschaft leverages its century-long veterinary focus to dominate traditional broker channels. Getsafe Digital GmbH competes through app-first policy management targeting urban millennials. Allianz Versicherungs-AG anchors the market with bundled household and pet offerings through its established agency network.
Pet insurance constitutes a risk-transfer mechanism covering veterinary treatment costs, mortality, and third-party liability through indemnity or reimbursement contracts, typically capped at annual benefit limits between EUR 5,000 and EUR 50,000 depending on species and tier. Its primary commercial purpose is to shield households from catastrophic veterinary expenditure while enabling clinics to recommend advanced diagnostics without cost-driven euthanasia decisions. Comprehensive policies now lead premium generation as owners seek coverage bridging accident, illness, and preventive care. Online distribution channels represent the fastest-growing acquisition path, though broker relationships still capture older demographics and complex multi-pet portfolios. Basic coverage tiers remain mature with thin margins, while premium and custom levels concentrate profitability through wellness add-ons and dental modules.
BaFin's insurance supervision framework and Germany's Tierarzneimittelgesetz (veterinary medicines law) jointly shape product design, mandating clear benefit schedules and restricting misleading wellness marketing. The EU's CSRD disclosure requirements are beginning to force insurers to document embedded animal welfare risks in underwriting portfolios. Stakeholders must monitor how digitized claims platforms interact with BaFin's conduct standards and whether veterinary price transparency laws alter loss-ratio dynamics.
Market Dynamics
BaFin's conduct standards and the EU Green Deal's animal welfare reporting obligations are forcing German insurers to restructure product transparency and liability frameworks.
Growth Catalysts
- Hundesteuer Enforcement:Municipal tax collection in Berlin and Munich pushes dog owners toward formal insurance documentation. Compliance requirements expand the addressable base.
- Veterinary Cost Inflation:Advanced diagnostic imaging and orthopedic surgery pricing at Tierärztliche Hochschulen drives household demand for catastrophic coverage.
- Urban Millennial Pet Ownership:Dense apartment living in Bavaria and North Rhine-Westphalia concentrates risk exposure and policy uptake among younger demographics.
Market Restraints
- Veterinary Price Opacity:The Tierarzneimittelgesetz does not mandate procedure cost disclosure, complicating actuarial loss-ratio forecasting.
- Broker Channel Concentration:Traditional intermediaries in rural eastern Germany control access to older, higher-premium customer segments.
- Wellness Marketing Restrictions:BaFin limits preventive care benefit promotion, constraining product differentiation.
Strategic Opportunities
- CSRD-Aligned Animal Welfare Reporting:The EU's Corporate Sustainability Reporting Directive creates first-mover advantage for insurers documenting embedded welfare risks.
- App-First Policy Management:Mobile-native distribution bypasses broker intermediation costs in metropolitan clusters.
- Dental and Wellness Modules:Add-on coverage for periodontal disease and vaccination schedules captures margin in premium tiers.
Industry Challenges
- Claims Platform Compliance:Automated reimbursement systems must align with BaFin's conduct standards for dispute resolution timelines.
- Legacy System Integration:Incumbent insurers face technical debt when connecting digital front-ends to decades-old policy administration cores.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Pet Insurance Market |
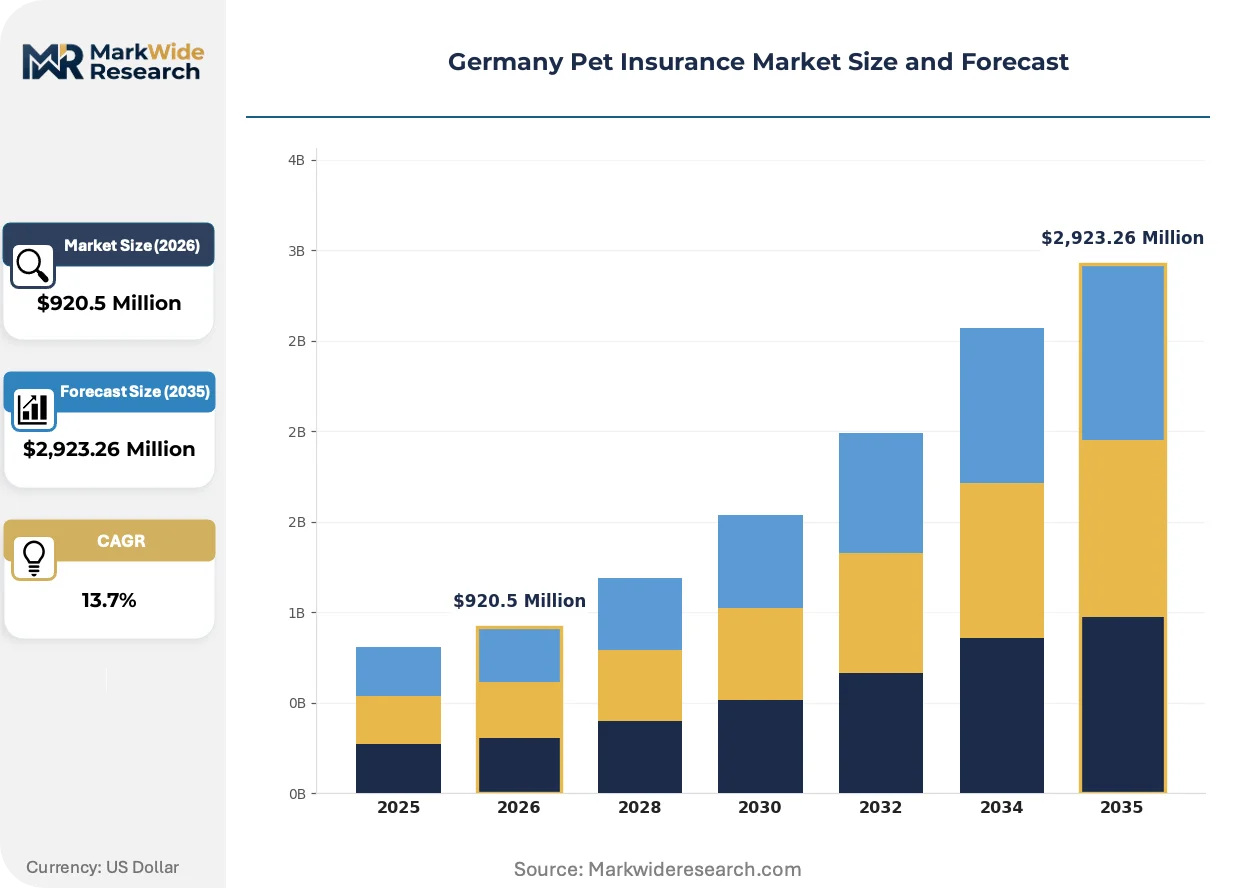
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $2,923.26 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Accident, Illness, Comprehensive, Third-Party Liability Animal Type: Dog, Cat, Bird, Exotic Coverage Level: Basic, Standard, Premium, Custom Distribution Channel: Online, Broker, Direct Sales, Pet Shops |
| Companies Covered | Uelzener Allgemeine Versicherungs-Gesellschaft, Getsafe Digital GmbH, Allianz Versicherungs-AG, Petplan (Allianz), Trupanion, Inc., AGILA Haustierversicherung AG, HanseMerkur Krankenversicherung AG, Figo Pet Insurance, LLC, Deutsche Familienversicherung AG (DFV), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Pet Insurance Market Strategic Shifts & Innovations
Digital claims processing and embedded welfare risk modeling are compressing underwriting cycles while expanding coverage scope beyond traditional veterinary reimbursement.
Telematics-enabled pet health monitoring is integrating biometric collar data into dynamic premium pricing models. Munich-based insurtechs deploy these sensors for early illness detection. The technology is integrating real-time behavioral analytics with annual policy adjustments.
The EU Green Deal's extension into animal welfare reporting obligations is mandating documented supply chain risk in underwriting portfolios. German insurers must now disclose embedded welfare exposure in corporate filings. Small mutuals in Baden-Württemberg lack compliance infrastructure and face consolidation pressure.
Subscription-based preventive care bundles are displacing traditional indemnity structures among urban millennials. Digital-native carriers offer monthly wellness credits redeemable at partner clinics. This shift concentrates in Berlin and Hamburg where clinic density supports network effects.
Germany Pet Insurance Market Segmentation
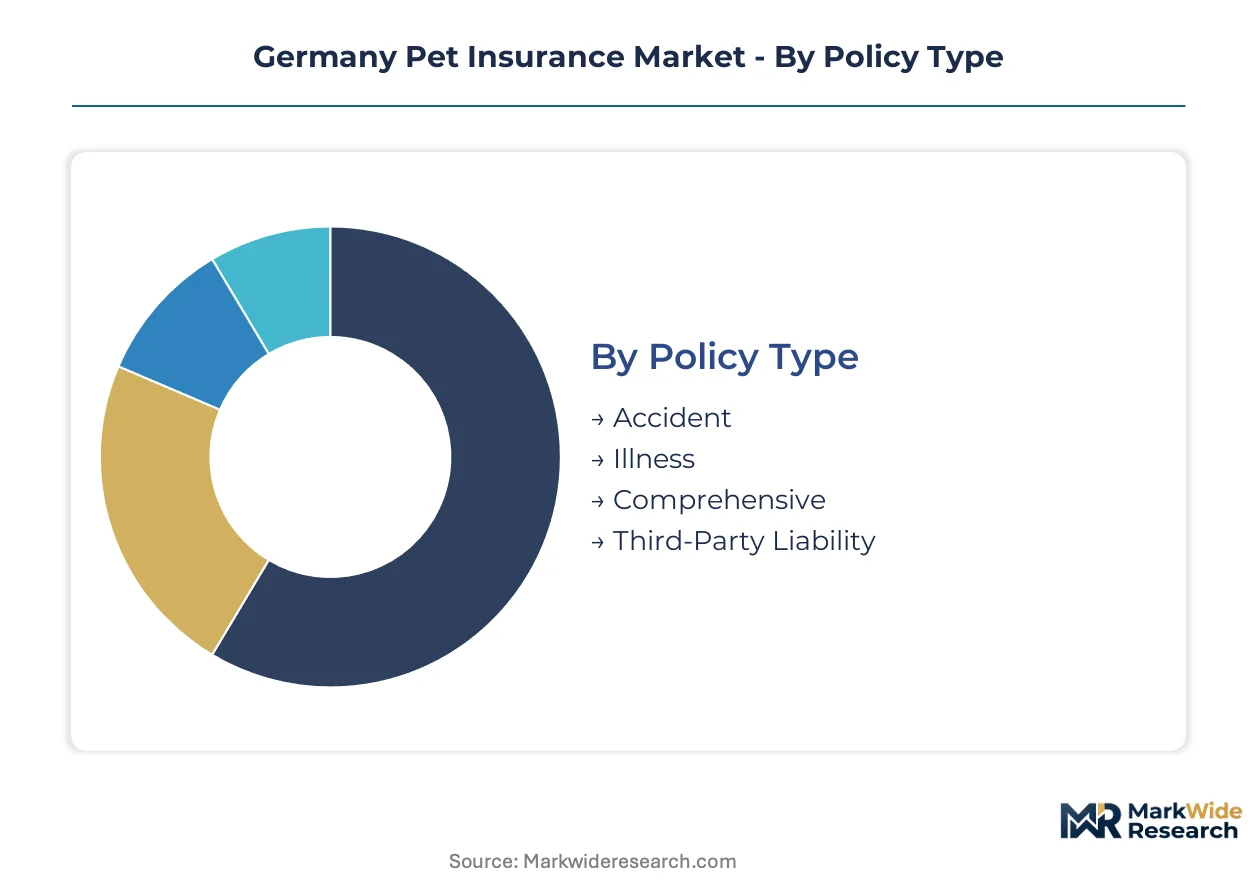
German pet insurance segmentation reveals how policy architecture, species risk profiles, and channel economics fragment the addressable market. Each dimension carries distinct margin structures and regulatory exposure that shape carrier strategy.
Policy Type:
Comprehensive and accident-only products split volume from opposite ends of the premium spectrum, with illness coverage anchoring the middle tier.
- Accident:Covers traumatic injury from vehicle collisions, falls, and bites with fixed benefit schedules. Demand concentrates among rural dog owners in Lower Saxony where hunting and agricultural exposure elevate injury frequency.
- Illness:Reimburses diagnostic and treatment costs for disease conditions excluding pre-existing chronic states. Veterinary oncology and orthopedic surgery at Munich's Tierärztliche Hochschule drive household uptake among cat owners seeking catastrophic protection.
- Comprehensive:Bundles accident, illness, and preventive care modules under unified annual limits. Bavarian multi-pet households favor this tier for administrative simplicity.
- Third-Party Liability:Covers legal damages from pet-inflicted injury or property destruction. Berlin's Hundesteuer enforcement mandates documentation that channels owners toward formal liability coverage.
Today's leader: Comprehensive. Tomorrow's challenger: Third-Party Liability.
Animal Type:
Species-specific mortality tables and veterinary cost baselines create divergent risk pools that carriers price through separate underwriting manuals.
- Dog:Largest premium pool driven by Hundesteuer compliance, orthopedic surgery costs, and liability exposure. North Rhine-Westphalia's dense urban ownership concentrates policy density in metropolitan corridors.
- Cat:Lower per-policy premium but expanding share through indoor-only wellness modules. Munich and Hamburg clinics report climbing renal disease claim frequency among aging feline populations.
- Bird:Avian mortality and theft coverage with capped benefit structures. Avicultural societies in Baden-Württemberg sustain niche demand through breeder network referrals.
- Exotic:Reptile, small mammal, and aquarium species coverage requiring specialized veterinary panels. Berlin's urban exotic ownership outpaces veterinary capacity, constraining product rollout.
Canine policies generate current margin concentration. Feline coverage is climbing the fastest trajectory among urban millennials.
Coverage Level:
Benefit ceilings and service inclusions stratify customers across price-sensitive entry tiers and wellness-integrated premium structures.
- Basic:Accident-only coverage with EUR 2,500 annual limits and no preventive care. Thin margins restrict carrier interest to customer acquisition funnels.
- Standard:Accident-plus-illness with EUR 5,000-10,000 limits and limited dental. Broker channels in eastern Germany dominate distribution to older demographic cohorts.
- Premium:Comprehensive coverage with EUR 25,000+ limits, dental modules, and telemedicine access. Getsafe Digital GmbH targets this tier through app-native policy management.
- Custom:Bespoke limits and exotic species riders for high-value animals and commercial breeders. Uelzener Allgemeine Versicherungs-Gesellschaft anchors this segment through veterinary specialist relationships.
Premium tiers capture profitability concentration. Custom levels are expanding most quickly among commercial breeding operations.
Distribution Channel:
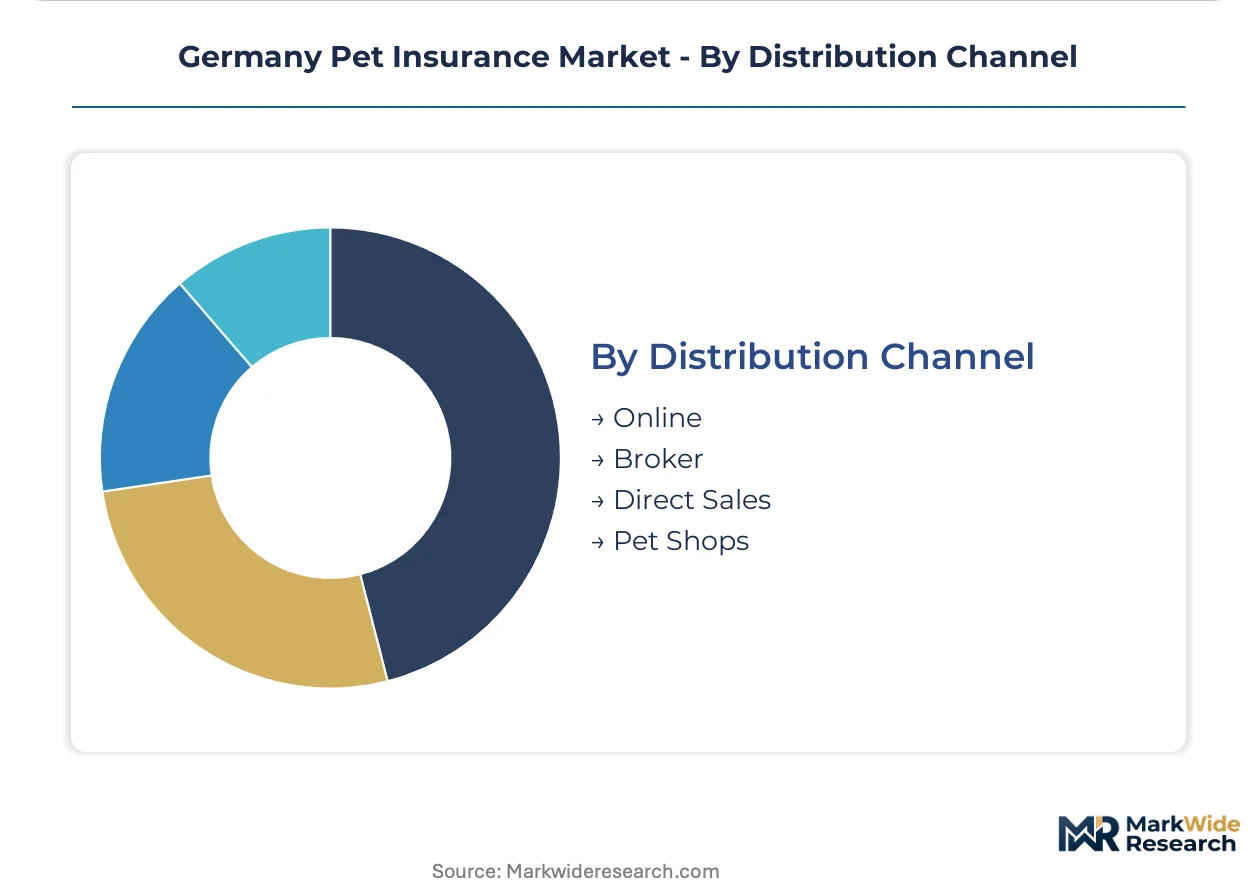
Channel economics fragment acquisition costs from sub-5% digital expense ratios to 15-20% broker commissions that persist in legacy customer segments.
- Online:Direct-to-consumer platforms with automated underwriting and claims submission. Allianz Versicherungs-AG and digital-native competitors compete for Berlin and Hamburg millennial cohorts.
- Broker:Intermediated sales with advisory services for complex multi-pet portfolios. Rural eastern Germany retains broker dependency among older owners.
- Direct Sales:Carrier-owned agency networks and call center operations. Allianz leverages household bundling through established property-casualty relationships.
- Pet Shops:Point-of-sale enrollment at veterinary clinics and retail chains. Munich and Frankfurt clinic partnerships concentrate this channel in metropolitan clusters.
Broker relationships defend mature premium pools. Online platforms are gaining share fastest among first-time pet owners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pet insurance originated from agricultural mutuals in Lower Saxony during the early twentieth century, expanding through veterinary cooperative networks before migrating into urban centers. The sector now clusters around metropolitan ownership densities and regional regulatory enforcement patterns.
Bavaria
Munich's Tierärztliche Hochschule drives orthopedic surgery demand among large-breed dog owners. The state's Hundesteuer administration requires formal liability documentation for all registered canines. Multi-pet households in Munich and Nuremberg concentrate comprehensive policy uptake through broker relationships.
North Rhine-Westphalia
Dense urban corridors around Cologne and Düsseldorf elevate third-party liability exposure for apartment-dwelling dog owners. Municipal tax offices enforce Hundesteuer compliance through insurance verification. Digital-native carriers target millennial cohorts in these metropolitan clusters with app-first enrollment.
Baden-Württemberg
Stuttgart's veterinary specialist density supports custom coverage for commercial breeding operations. Small mutuals in this region face consolidation pressure from EU Green Deal reporting obligations. Avicultural societies sustain niche bird mortality coverage through breeder network referrals.
Berlin-Brandenburg
Capital-region millennial pet ownership concentrates subscription-based preventive care demand. Getsafe Digital GmbH anchors app-native distribution in this metropolitan area. Tierarzneimittelgesetz compliance requirements shape product transparency standards for digital claims platforms.
Lower Saxony
Rural hunting and agricultural exposure elevates accident-only coverage demand among working dog owners. Traditional broker channels dominate policy distribution to older demographic cohorts. Hanover's veterinary medicine faculty supplies actuarial research partnerships for regional carriers.
Germany Pet Insurance Market Key Industry Players
Capital-heavy incumbents with established agency networks compete with asset-light digital natives for customer acquisition. The market structure fragments across three tiers: century-old veterinary specialists, household-name conglomerates with bundling capabilities, and insurtech challengers with mobile-first distribution. Strategic archetypes include broker-dependent traditionalists, direct-to-consumer digital platforms, and diversified financial services groups leveraging cross-sell infrastructure. Competitive intensity centers on channel migration and wellness module differentiation.
Among veterinary-focused traditionalists, Uelzener Allgemeine Versicherungs-Gesellschaft occupies a position representing broker-channel dominance. Getsafe Digital GmbH exemplifies the app-native archetype targeting metropolitan millennials. Allianz Versicherungs-AG anchors the diversified conglomerate tier through household bundling and established agency networks. These three patterns illustrate how carrier strategy fragments across distribution philosophy and customer demographic targeting.
| Leading Market Players |
|---|
| Uelzener Allgemeine Versicherungs-Gesellschaft |
| Getsafe Digital GmbH |
| Allianz Versicherungs-AG |
| Petplan (Allianz) |
| Trupanion, Inc. |
| AGILA Haustierversicherung AG |
| HanseMerkur Krankenversicherung AG |
| Figo Pet Insurance, LLC |
| Deutsche Familienversicherung AG (DFV) |
| Others |
Cost & Logistics Intelligence
Digital claims automation and embedded wellness modules are compressing underwriting costs while redistributing pricing power toward carriers with direct veterinary clinic partnerships. This technology shift simultaneously lowers administrative expense ratios and concentrates margin capture among platform-native insurers in Berlin and Munich metropolitan clusters.
Pricing Analysis
Subscription-based tiered pricing across premium, standard, and economy levels anchors the German market, with premium tiers capturing profitability through dental modules and telemedicine access while basic tiers face thinning margins. Price differentiation hinges on coverage ceiling magnitude and preventive care inclusion depth. Cost compression in basic tiers is intensifying because digital-native entrants automate claims processing at sub-5% expense ratios. Rural broker-dependent segments show highest price sensitivity; metropolitan millennials accepting app-native distribution exhibit lowest sensitivity to premium tier pricing.
Supply Chain Analysis
Single-source vulnerability sits with Munich's Tierärztliche Hochschule for specialized orthopedic surgery pricing benchmarks that feed into actuarial models. Supply concentration centers on Germany for veterinary service delivery, with diagnostic imaging equipment sourced from Japan and pharmaceutical inputs drawn from Switzerland and the Netherlands. Regulatory restriction risk emanates from BaFin's evolving conduct standards for automated claims platforms. Distribution runs through broker intermediaries in rural eastern Germany and direct-to-consumer digital channels in metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany Pet Insurance Market functions as a stable compounder, with Hundesteuer enforcement and veterinary cost inflation generating predictable policy expansion across urban ownership cohorts.
For Market Incumbents: Extend broker channel control in Bavaria and North Rhine-Westphalia through exclusive veterinary clinic partnerships that lock in referral flows. Consolidate legacy policy administration systems with digital front-ends to defend against insurtech customer acquisition in Berlin and Hamburg. Vertical integration into telematics-enabled pet health monitoring creates defensive moats against platform-native competitors.
For New Entrants and Emerging Players: The gap between premium-tier comprehensive coverage and economy accident-only policies creates white-space opportunity in mid-market illness-plus-accident bundles. Target cat-owning urban millennials in Berlin-Brandenburg where indoor-only wellness modules remain underpenetrated. Deploy app-first enrollment with monthly subscription flexibility to bypass established broker relationships.
For Investors and Strategic Acquirers: Roll-up economics work for small mutuals in Baden-Württemberg because EU Green Deal reporting obligations force compliance infrastructure investments that exceed standalone carrier capabilities. Five-to-ten year viability favors diversified conglomerates with household bundling infrastructure over single-line specialists. Monitor BaFin's digitized claims platform conduct standards as the inflection signal for regulatory compliance cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Clinic Network Partnership | Locks in referral flows through exclusive diagnostic and claims processing integration with Munich's Tierärztliche Hochschule. |
| Telematics-Enabled Pet Health Monitoring | Deploys biometric collar data from Munich-based insurtechs into dynamic premium pricing and early illness detection. |
| Digital Claims Platform Development | Automates reimbursement timelines while aligning with BaFin conduct standards for dispute resolution in Berlin-Brandenburg. |
| CSRD-Aligned Animal Welfare Reporting | Documents embedded welfare risks in underwriting portfolios ahead of EU Green Deal disclosure mandates. |
| Subscription-Based Preventive Care Bundles | Displaces traditional indemnity structures through monthly wellness credits redeemable at partner clinics in Hamburg. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with veterinary clinic operators, insurance product managers at carrier headquarters, BaFin regulatory specialists, and broker network principals with secondary validation. BaFilings, Tierarzneimittelgesetz regulatory updates, veterinary medicine faculty research publications, and municipal Hundesteuer enforcement records supplied foundational data. Bottom-up policy volume estimates triangulated against top-down premium pool calculations.
Historical reference periods anchored the projection horizon to observed enrollment velocity and premium growth trajectories across the analysis window. The analytical framework modeled segmentation dimensions spanning policy type, animal species, coverage level tier, and distribution channel geography. CAGRs derived from regression analysis of insured population expansion against veterinary cost inflation indices. Forecast inputs incorporated Hundesteuer compliance rate assumptions and metropolitan millennial pet ownership density projections.
Caveats apply where BaFin conduct standard revisions or veterinary price transparency legislation could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement continuity and digital channel adoption velocity among older demographic cohorts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Investment Analysis and Financial Strategies
Cryptocurrency Exchanges Market
Investment Analysis and Financial Strategies
India Asset Management Market
Investment Analysis and Financial Strategies
Global Executive Search (Headhunting) Market
Investment Analysis and Financial Strategies
Portugal Mobile Payments Market
Investment Analysis and Financial Strategies
Financial Calculators Market
Investment Analysis and Financial Strategies
Bank Management Software Market
Investment Analysis and Financial Strategies
Asia-Pacific Crypto Payment Gateway Market
Investment Analysis and Financial Strategies
Automotive Insurance Market
Investment Analysis and Financial Strategies
Debt Settlement Market
Investment Analysis and Financial Strategies
Aviation Insurance Market
Investment Analysis and Financial Strategies
Risk-Based Monitoring Software Market
Investment Analysis and Financial Strategies
Mobile Payment Data Protection Market
Investment Analysis and Financial Strategies
Asia-Pacific Sustainable Finance Market
Investment Analysis and Financial Strategies
Germany Forensic Accounting Market
Investment Analysis and Financial Strategies
Brazil Car Loan Market
Investment Analysis and Financial Strategies
Digital Payment in Healthcare Market