
 Flat Bottom Bags Market | 2026-2036
Flat Bottom Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Flat Bottom Bags Market Foresight
Germany is tilting toward expanded flat bottom bag conversion capacity as European brands demand higher-performance packaging. Smurfit Kappa leverages its integrated paperboard supply chain to dominate kraft-based formats across the continent. Mondi Group anchors its position through specialty coating technologies that extend barrier performance without full lamination. Amcor competes via global scale in flexible packaging, though its European operations focus increasingly on recyclable mono-material structures.
Flat bottom bags are self-standing flexible containers with gusseted side panels and a sealed rectangular base, typically constructed from multi-ply kraft paper, polyethylene, or laminated films with oxygen transmission rates below 1 cc/m²/day for sensitive contents. These structures serve primarily to maximize retail shelf presence while protecting dry goods from moisture, oxidation, and mechanical damage. Kraft paper material leads in European food packaging applications where fiber-based recyclability aligns with retailer sustainability mandates, while laminated film dominates cosmetic and chemical segments where barrier performance commands premium positioning. Food processing companies represent the deepest customer pool, though boutique retailers are shifting fastest toward zip-lock and tin-tie closures for premium positioning.
FDA food-contact regulations govern material migration limits for US-bound products, while REACH and the EU Packaging and Packaging Waste Directive constrain substance use and end-of-life obligations across European supply chains. EFSA evaluations of novel biodegradable polymers are reshaping formulation choices as converters anticipate stricter single-use plastic thresholds. Stakeholders must monitor how evolving extended producer responsibility frameworks alter material economics and which certification pathways unlock preferential retail placement.
Market Dynamics
European REACH compliance deadlines and FDA migration limit updates are forcing converters to reformulate multi-layer structures, collapsing legacy supply chains that relied on non-compliant adhesive chemistries and barrier coatings.
Growth Catalysts
- Specialty Coffee Roasting:Third-wave roasters in Germany and Italy are specifying flat bottom bags with one-way degassing valves and resealable tin-ties. This format commands shelf space in premium retail channels.
- EU Packaging and Packaging Waste Directive:Mandatory recycled content thresholds are accelerating fiber-based substrate adoption. Kraft paper flat bottom bags qualify for extended producer responsibility credits in multiple member states.
- Oxygen Scavenger Integration:Embedded iron-based scavenger layers are extending shelf life for nut and dried fruit applications without full aluminum lamination. Food processors are retrofitting filling lines to accommodate these structures.
Market Restraints
- Ethylene-Vinyl Alcohol Supply Concentration:EVOH barrier resin production clusters in Japan and Belgium. Any disruption to these supply nodes propagates through European converter networks within weeks.
- Adhesive Migration Testing Costs:FDA food-contact notification pathways for novel laminating adhesives require 18-24 month evaluation timelines. This friction delays product launches for US-bound shipments.
- Rigid Container Substitution:Glass jars and metal tins retain preference in gift-oriented confectionery segments where perceived value depends on container heft and transparency.
Strategic Opportunities
- Poland and Czech Republic:Central European contract manufacturing is expanding for German private-label brands seeking cost-advantaged conversion without sacrificing REACH compliance.
- Compostable Certification Pathways:OK Compost HOME and EN 13432 certifications unlock placement in French and Belgian retailer sustainability programs. Converters are investing in pilot lines for PLA-PBAT blends.
- Direct-to-Consumer Subscription:Coffee subscription services are specifying smaller batch sizes with zip-lock closures. This channel bypasses traditional wholesale distribution markups.
Industry Challenges
- Barrier Coating Formulation Expertise:Water-based coatings that match solvent-based oxygen transmission rates require polymer scientists with thin-film deposition experience. This talent pool concentrates in German and Swiss research institutes.
- Legacy Filling Line Integration:Vertical form-fill-seal equipment from the 1990s lacks the jaw precision for gusseted bottom seals. Retrofit costs often exceed new equipment purchase price.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flat Bottom Bags Market |
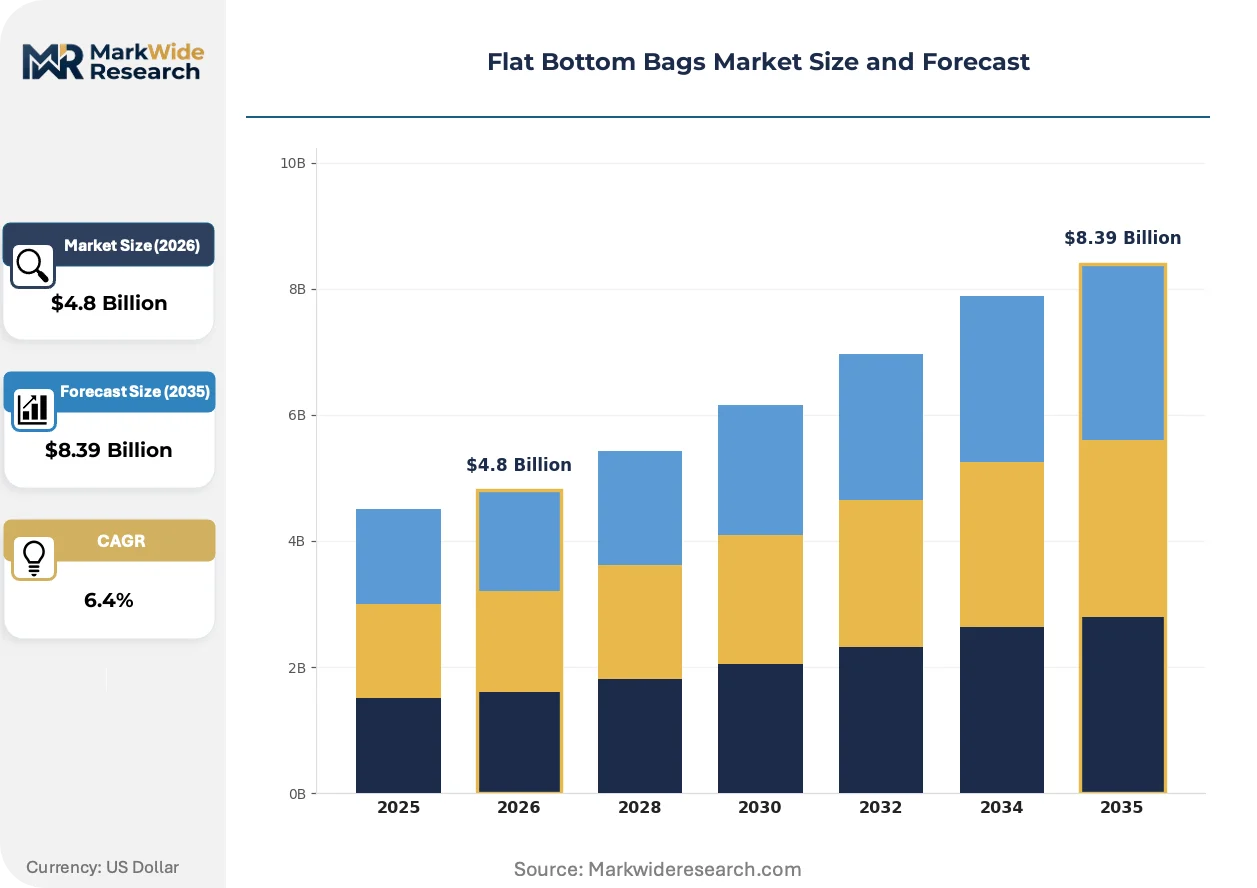
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Kraft Paper, Polyethylene, Foil, Laminated Film, Biodegradable Polymers Application: Food Packaging, Beverage Packaging, Pet Food Packaging, Chemical Packaging, Cosmetic Packaging Closure Type: Zip Lock, Tin Tie, Valve, Heat Seal, Doypack Closure Customer Type: Food Processing Companies, Chemical Manufacturers, Cosmetic Brands, Pet Product Makers, Boutique Retailers |
| Companies Covered | Smurfit Kappa, Berry Global, Mondi Group, Sealed Air, WestRock, International Paper, Novolex, Scholle IPN, Amcor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flat Bottom Bags Market Shifts & Advancements
Barrier technology convergence and regulatory substance bans are compressing formulation cycles. Converters must now validate alternatives before incumbent chemistries face restriction.
Mono-material polyethylene structures with plasma-enhanced barrier deposition are collapsing the multi-layer lamination model. Specialty nut processors in California and Oregon are qualifying these formats for 12-month shelf life claims. The elimination of adhesive layers simplifies mechanical recycling streams and reduces converter inventory complexity.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating oil-and-grease-resistant coatings from food-contact applications. ECHA evaluations of fluoropolymer alternatives are redirecting R&D spending toward silicon oxide and clay-based barrier technologies. German confectionery brands are accelerating qualification timelines to avoid supply disruption.
Brand procurement teams are consolidating supplier panels to three approved converters per geography. This concentration transfers specification authority from purchasing to technical packaging departments. Italian pasta and rice brands are driving this shift, demanding audited compliance documentation upfront rather than post-delivery verification.
Flat Bottom Bags Market Segmentation
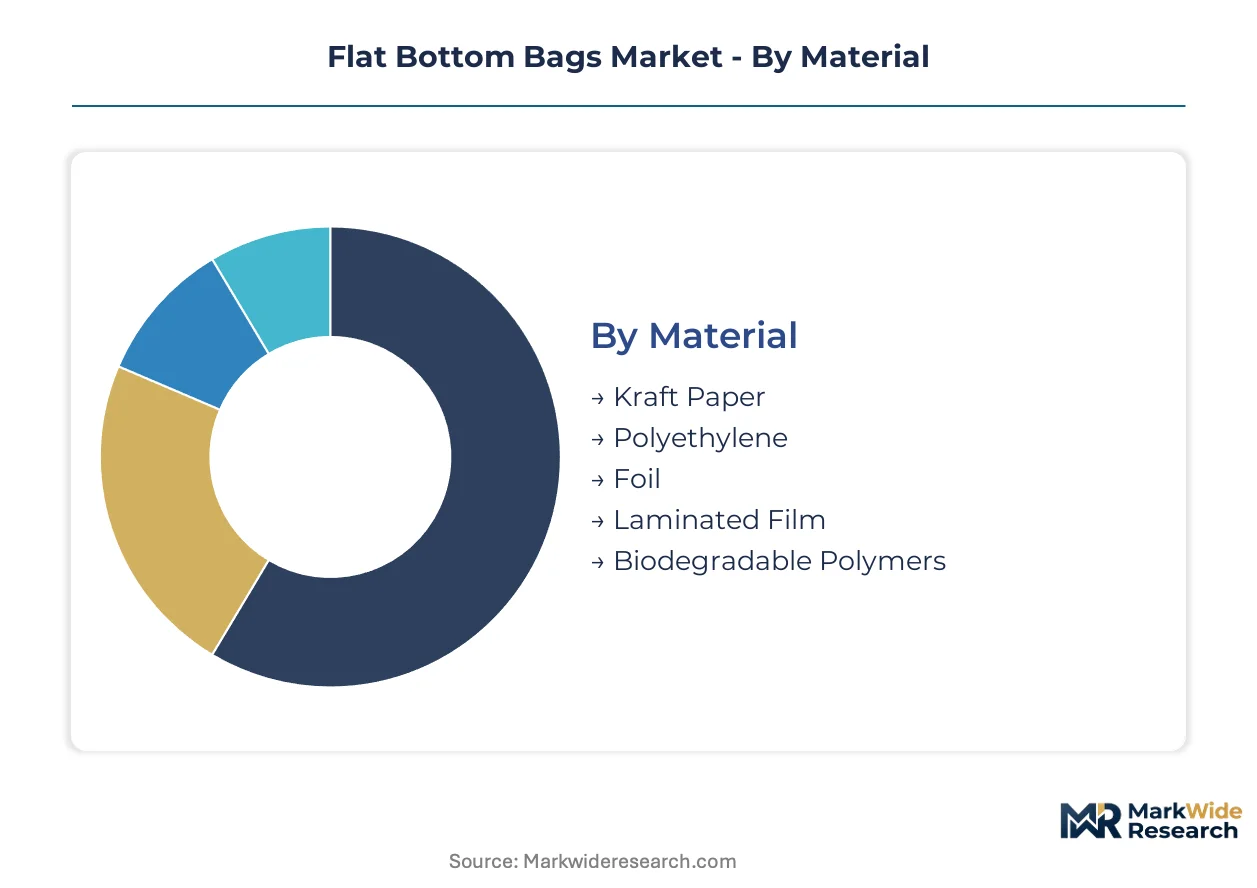
Flat bottom bag specifications diverge sharply across material grades and end-use requirements. Converters must align substrate selection, barrier performance, and closure mechanics with precise customer workflows and regulatory exposure.
Material:
Cost tier separates commodity substrates from engineered barrier structures. Raw material economics and end-of-life obligations drive specification authority toward procurement teams.
- Kraft Paper:Multi-ply fiber construction with PE extrusion or water-based barrier coatings. German and Italian food brands specify this format for EPR credit eligibility under EU Packaging and Packaging Waste Directive mandates.
- Laminated Film:Multi-layer PET/PE/EVOH structures delivering oxygen transmission below 1 cc/m²/day. Specialty coffee roasters in Germany and nut processors in California demand this grade for 12-month shelf life claims without refrigeration infrastructure.
- Polyethylene:Mono-material structures with plasma-enhanced barrier deposition. Emerging qualification for mechanical recycling streams.
- Foil:Aluminum lamination for absolute moisture and light exclusion. Retained in pharmaceutical-adjacent food segments.
- Biodegradable Polymers:PLA-PBAT blends pursuing OK Compost HOME certification. Pilot line investments concentrate in France and Belgium.
Kraft paper commands the established base. The steepest expansion runs through mono-material polyethylene as recyclability mandates tighten.
Application:
End-use exposure to moisture, oxidation, and mechanical stress determines barrier investment levels. Customer procurement cycles and shelf-life claims set specification boundaries.
- Food Packaging:Dry goods protection with oxygen scavenger integration for nuts and dried fruits. German private-label brands drive volume through Central European contract manufacturing.
- Pet Food Packaging:High-fat content formulations requiring oil-and-grease-resistant coatings. REACH Annex XVII fluoropolymer restrictions are forcing coating reformulation toward silicon oxide alternatives.
- Beverage Packaging:Coffee and tea formats with one-way degassing valves. Third-wave roasters specify tin-tie and zip-lock closures for premium retail channel placement.
- Cosmetic Packaging:Laminated film dominance for moisture-sensitive powders and granules. Boutique brands prioritize shelf differentiation over unit cost.
- Chemical Packaging:Industrial-grade barrier specifications for agrochemical and detergent applications. FDA food-contact compliance not required, simplifying material selection.
Food packaging anchors volume demand. Pet food packaging is gaining share fastest as premiumization extends to companion animal nutrition.
Closure Type:
Customer type dictates resealability requirements and equipment compatibility. Filling line retrofit costs constrain format migration for legacy processors.
- Tin Tie:Metal wire and paper band combination for manual reseal. Specialty coffee subscription services specify this format for batch-size flexibility and premium unboxing experience.
- Zip Lock:Interlocking plastic track for repeated access. Direct-to-consumer channels bypass wholesale markups with smaller pack sizes.
- Valve:One-way degassing for freshly roasted coffee. German and Italian roasters mandate this for retail shelf presence.
- Heat Seal:Permanent closure for single-use industrial applications. Lowest unit cost position.
- Doypack Closure:Spout integration for liquid and semi-liquid contents. Limited penetration in traditional flat bottom formats.
Heat seal dominates industrial procurement. Zip lock formats are expanding most quickly through subscription commerce channels.
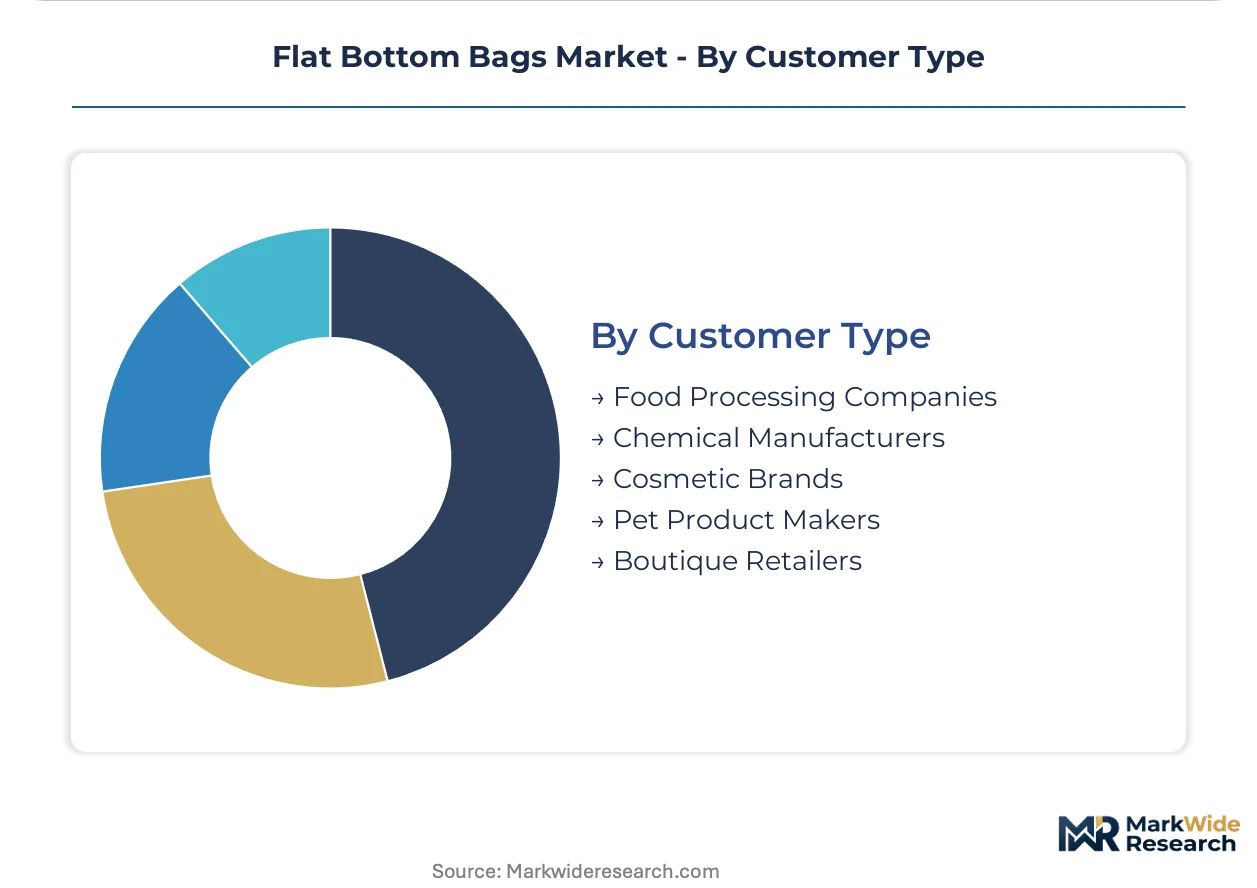
Customer Type:
Volume concentration and technical specification authority vary across buyer categories. Consolidated supplier panels are transferring negotiation leverage from purchasing to packaging engineering departments.
- Food Processing Companies:High-volume procurement with audited compliance documentation requirements. Italian pasta and rice brands drive upfront certification rather than post-delivery verification.
- Boutique Retailers:Small-batch flexibility with zip-lock and tin-tie premium positioning. Fastest format innovation adoption.
- Cosmetic Brands:Laminated film specifications for moisture barrier performance. Sustainability claims increasingly influence substrate selection.
- Pet Product Makers:High-fat formulation packaging with coating reformulation pressure from REACH restrictions.
- Chemical Manufacturers:Non-food-contact applications with simplified regulatory exposure. Price-sensitive procurement.
Food processing companies represent the deepest volume base. Boutique retailers are climbing the fastest as channel fragmentation multiplies SKU requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German roasters specify flat bottom bags with degassing valves and tin-tie closures at triple the rate of Italian processors, who favor heat-sealed formats for commodity pasta and rice. This consumption-mix differential reflects how premium retail channel density shapes packaging specification authority across European markets.
Germany
Third-wave coffee roasters in Berlin and Hamburg drive specification for oxygen scavenger-integrated kraft paper formats with one-way valves. REACH Annex XVII restrictions on fluoropolymer coatings are forcing reformulation of oil-resistant barriers toward silicon oxide alternatives. The Baden-Württemberg converter cluster around Stuttgart is expanding pilot capacity for mono-material polyethylene structures with plasma-enhanced deposition.
Italy
Pasta and rice brands in Emilia-Romagna specify multi-ply kraft flat bottom bags for EPR credit eligibility under EU Packaging and Packaging Waste Directive mandates. EFSA evaluations of novel biodegradable polymers are reshaping formulation choices for compostable certification pathways. Bologna-based technical packaging departments are consolidating supplier panels to three approved converters per geography.
United States
Specialty nut processors in California and Oregon qualify mono-material polyethylene formats for 12-month shelf life claims without refrigeration infrastructure. FDA food-contact notification pathways for novel laminating adhesives impose 18-24 month evaluation timelines that delay product launches. The Pacific Northwest contract manufacturing base is retrofitting vertical form-fill-seal equipment for gusseted bottom seal precision.
Poland
Central European contract manufacturing capacity is expanding for German private-label brands seeking cost-advantaged conversion without sacrificing REACH compliance. The country's national packaging regulator enforces EU extended producer responsibility frameworks that alter material economics for imported substrates. Warsaw-area converter investments concentrate on zip-lock closure integration for direct-to-consumer subscription channels.
France
OK Compost HOME and EN 13432 certifications unlock preferential retailer placement in sustainability programs across Paris and Lyon metropolitan markets. ECHA evaluations of fluoropolymer alternatives are redirecting R&D spending toward clay-based barrier technologies. The Île-de-France pilot line corridor is testing PLA-PBAT blend formulations for biodegradable polymer adoption.
Flat Bottom Bags Market Competitive Landscape
Capability concentration sits with specialty coating and barrier technology developers; scale advantage sits with integrated paperboard and flexible packaging conglomerates. The market structure tiers between multinational converters with captive raw material supply and regional specialists with formulation expertise. Two strategic archetypes dominate: integrated fiber-based substrate suppliers leveraging kraft paper recyclability credentials, and flexible packaging specialists pivoting toward mono-material recyclable structures. Competitive moves center on backward integration into barrier resin supply and strategic partnerships with coffee roasting equipment manufacturers for co-developed filling line specifications.
Within the integrated paperboard tier, Smurfit Kappa and WestRock exemplify geographic anchoring strategies that pair kraft pulp access with European EPR credit eligibility. Mondi Group occupies a position among specialty coating technology developers, its name signaling central European research institute proximity. Amcor sits within the global flexible packaging scale tier, its market presence reflecting multi-continent manufacturing footprints. These three names represent how substrate control, barrier innovation, and geographic coverage define competitive positioning without requiring specific product or financial claims.
| Leading Market Players |
|---|
| Smurfit Kappa |
| Berry Global |
| Mondi Group |
| Sealed Air |
| WestRock |
| International Paper |
| Novolex |
| Scholle IPN |
| Amcor |
| Others |
Supply & Pricing Matrix
Converter undercapacity in Central Europe is compressing lead times and tilting negotiation leverage toward kraft paper suppliers with captive pulp supply. German brands now accept longer contract durations to lock in EPR-compliant substrate access, while spot-market polyethylene buyers face volatile resin pass-throughs from Belgian EVOH disruptions.
Pricing Analysis
Long-term offtake agreements dominate procurement between German food brands and Baden-Württemberg converters, insulating volume commitments from spot resin volatility. Pricing stratifies across premium oxygen-scavenger grades, standard kraft-PE laminations, and economy heat-seal formats without barrier coatings. Cost compression in standard tiers is intensifying because Polish contract manufacturers are undercutting legacy German suppliers on REACH-audited production. Boutique coffee roasters show least price sensitivity, while private-label pasta brands drive hardest unit-cost negotiations.
Supply Chain Analysis
Contract manufacturing capacity concentrates in Poland, the Czech Republic, and Germany's Baden-Württemberg cluster, with Warsaw-area facilities expanding zip-lock integration lines fastest. Raw material supply draws from Swedish kraft pulp mills, Belgian EVOH resin plants, and Chinese PE film extrusion. Single-source vulnerability sits with Japanese EVOH producers, where any disruption propagates through European barrier film networks within weeks. Distribution runs through regional converter hubs that pre-position finished inventory near Emilia-Romagna pasta processors and Berlin coffee roasters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among Italian pasta and rice brands is shifting specification authority from purchasing departments to technical packaging engineering, compressing supplier panels to three approved converters per geography.
For Market Incumbents: Insulate margin position by backward integration into kraft pulp supply or captive barrier coating R&D, as REACH Annex XVII fluoropolymer bans threaten incumbent oil-resistant formulations. Anchor capacity expansion in Poland to serve German private-label demand without surrendering REACH compliance premiums. Prioritize OK Compost HOME certification investments to unlock French retailer sustainability program placement. For New Entrants and Emerging Players: Build out pilot-line capacity for PLA-PBAT biodegradable blends in France or Belgium, where compostable certification unlocks preferential shelf access ahead of mainstream converter adoption. Target direct-to-consumer coffee subscription channels with smaller batch zip-lock formats that bypass wholesale distribution markups. Lead with rapid FDA food-contact notification capabilities to differentiate against legacy players facing adhesive migration testing delays. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across mono-material polyethylene conversion as plasma-enhanced barrier deposition eliminates multi-layer lamination complexity. Five-to-ten-year viability favors acquiring German or Swiss specialty coating technology developers with thin-film polymer science talent pools. Monitor EFSA evaluation timelines for novel biodegradable polymers as the signal for compostable substrate inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulp Supply | Secures EPR credit eligibility under EU Packaging and Packaging Waste Directive mandates for German brands. |
| Plasma-Enhanced Barrier Deposition Investment | Enables mono-material PE structures that qualify for mechanical recycling streams in California and Oregon. |
| OK Compost HOME Certification Pathway | Unlocks preferential retailer placement in French and Belgian sustainability programs ahead of competitors. |
| Central European Contract Manufacturing Expansion | Captures German private-label volume with REACH-compliant cost advantages over domestic conversion. |
| Direct-to-Consumer Subscription Channel Development | Bypasses wholesale markups with zip-lock formats specified by third-wave coffee roasters in Berlin and Hamburg. |
Research Methodology
A standing panel of converter operations managers, brand packaging engineers, resin procurement leads, and EPR compliance officers provided ongoing calibration against secondary validation from FDA food-contact notification databases, ECHA REACH restriction proposals, EU Packaging and Packaging Waste Directive implementation reports, and trade customs data on kraft paper and PE film flows. Bottom-up volume estimates from named converter capacity triangulated with top-down demand modeling across food processing, pet food, and beverage end-uses.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning material substrate tier, closure mechanism complexity, customer type procurement authority, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating coffee roasting equipment installation rates, EPR credit valuation trajectories, and filling line retrofit cost amortization schedules. Forecast inputs included EVOH resin supply node reliability indices and biodegradable polymer certification pipeline status.
Practitioners should monitor EFSA novel polymer evaluations, REACH Annex XVII restriction timelines, and Central European converter capacity utilization for early signals of substrate substitution or supply relocation. Quarterly review of EPR credit pricing, adhesive migration testing backlogs, and plasma deposition equipment order books is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bag Clips Market
Bags and Containers
Cooler Bags Market
Bags and Containers
Scented Trash Bags Market
Bags and Containers
Aluminum Beverage Bags Market
Bags and Containers
Side Weld Bags Market
Bags and Containers
Ventilated Bulk Bags Market
Bags and Containers
Child Resistant Bags Market
Bags and Containers
4-Loop FIBC Market
Bags and Containers
Ziplock Food Bags Market
Bags and Containers
Disposable Garbage Bags Market
Bags and Containers
Bag & Bag Aerosol Can Market
Bags and Containers
Isothermal Bags Market
Bags and Containers
Lunch Boxes and Lunch Bags Market
Bags and Containers
Portion Bags Market
Bags and Containers
Conductive Bags Market
Bags and Containers
Clay Desiccant Bag Market