
 First-Class Sofa Market | 2026-2036
First-Class Sofa Market Size, Share, and Industry Trends Forecast 2026-2036
First-Class Sofa Market Insights
White-glove delivery and in-home assembly subscription tiers is consolidating revenue streams for premium seating manufacturers. Restoration Hardware leverages its proprietary RH Members Program to sustain repeat residential purchases. Ethan Allen Global anchors its North American production network through vertically owned woodworking facilities. Wayfair competes on digital catalog breadth while navigating logistics complexity across dispersed supplier bases.
A first-class sofa denotes upholstered seating engineered with kiln-dried hardwood frames, eight-way hand-tied spring suspension, and high-resilience foam cores exceeding density ratings for residential-grade alternatives, serving both residential living environments and commercial hospitality settings where durability and aesthetic refinement carry equal weight. Leather upholstery commands the widest margin pools among material segments due to raw hide sourcing constraints and artisan finishing requirements. Sectional configurations represent the fastest-growing product type as open-plan residential layouts and hotel lobby configurations displace traditional fixed seating arrangements.
EPA formaldehyde emission standards under the Toxic Substances Control Act govern composite wood components in domestically sold seating, while California Air Resources Board Phase 2 criteria extend binding limits on adhesive off-gassing for products entering the West Coast distribution corridor. EU REACH Annex XVII restrictions on chromium VI in leather tanning reshape European supply base compliance costs. Stakeholders must monitor evolving state-level extended producer responsibility frameworks for furniture disposal that threaten to add reverse-logistics cost layers without corresponding price recovery mechanisms.
Market Dynamics
REACH Annex XVII restrictions on chromium VI in leather tanning are forcing European tanneries to retool finishing lines, while kiln-dried hardwood frame shortages concentrate purchasing power among vertically integrated manufacturers with captive lumber yards.
Growth Catalysts
- Chrome-free leather processing:EU REACH compliance mandates are accelerating adoption of vegetable-tanned and synthetic-alternative upholstery across hospitality procurement specifications in Germany and Italy.
- Open-plan residential layouts:Sectional configurations are displacing traditional fixed seating in suburban developments across the United States and Australia, driving modular frame engineering investments.
- White-glove delivery tiers:Subscription-based in-home assembly services are consolidating repeat residential revenue streams for manufacturers with captive logistics networks.
Market Restraints
- Raw hide sourcing constraints:Artisan finishing requirements and livestock supply volatility compress margin pools for leather upholstery segments dependent on full-grain hides.
- Composite wood emission standards:EPA formaldehyde limits under the Toxic Substances Control Act and California Air Resources Board Phase 2 criteria add compliance testing layers for domestic frame producers.
- Extended producer responsibility frameworks:State-level furniture disposal mandates in multiple US jurisdictions threaten reverse-logistics cost accumulation without price recovery mechanisms.
Strategic Opportunities
- Hospitality suite upgrades:Luxury developments in Dubai and Singapore are driving specification upgrades for high-resilience foam cores and eight-way hand-tied suspension systems.
- Digital catalog breadth:Platform-based retailers are capturing share through logistics partnerships that offset dispersed supplier base complexity.
- Vertically owned woodworking:Captive production of kiln-dried hardwood frames insulates margin pressure from lumber commodity cycles.
Industry Challenges
- Eight-way hand-tied craftsmanship:The skilled labor pool for traditional spring suspension installation is contracting, extending production lead times for premium residential orders.
- Multi-jurisdiction compliance:Simultaneous adherence to EPA, CARB, and evolving EU chemical restrictions fragments quality assurance protocols for exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | First-Class Sofa Market |
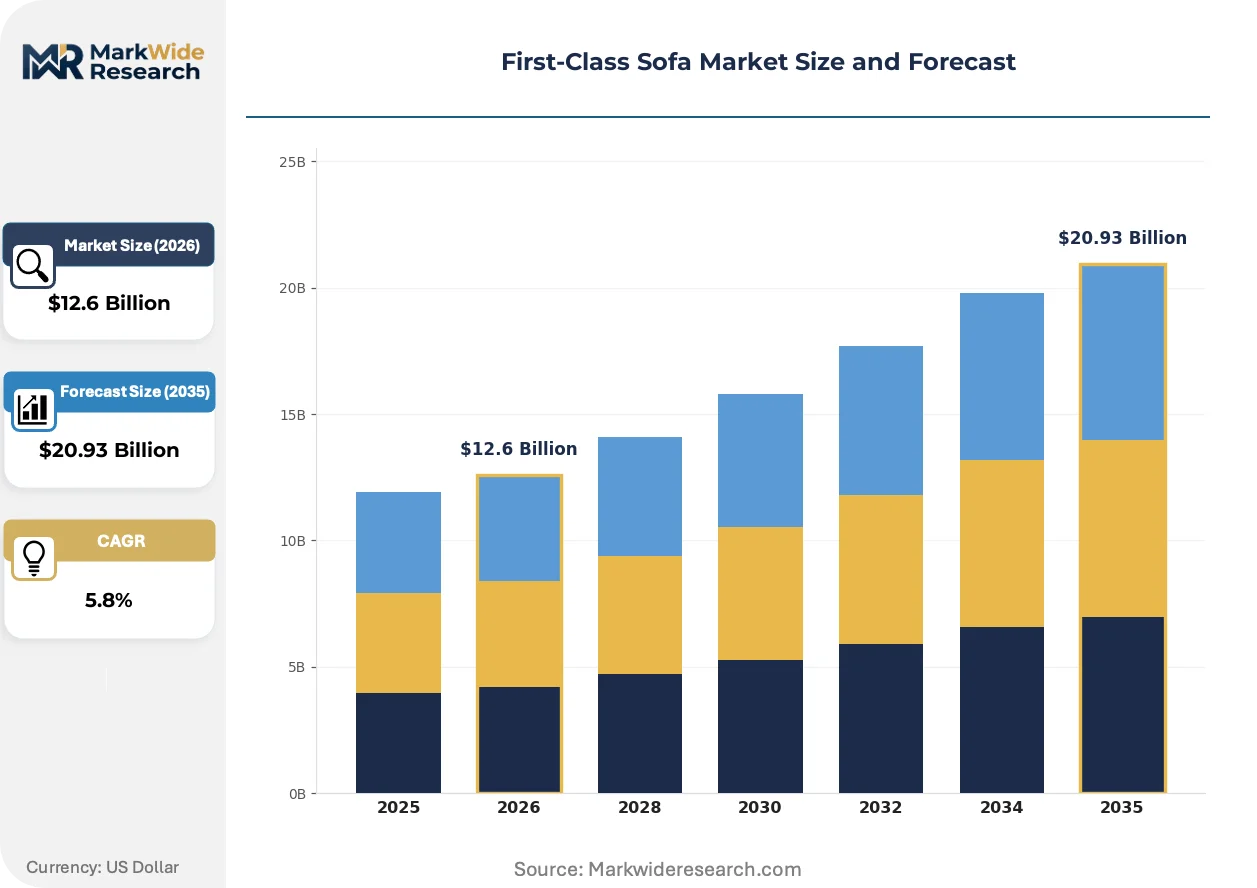
| Market Size in 2026 | $12.6 Billion |
| Market Size in 2035 | $20.93 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sectional, Recliner, Loveseat, Sofa Bed Material: Leather, Fabric, Velvet, Microfiber Style: Contemporary, Traditional, Mid-Century Modern, Rustic End User: Residential, Commercial, Hospitality, Retail |
| Companies Covered | Ashley Furniture Industries, La-Z-Boy Incorporated, Williams-Sonoma Inc., Ethan Allen Global Inc., Restoration Hardware, Herman Miller Inc., Steelcase Inc., Inter IKEA Systems B.V., Wayfair, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
First-Class Sofa Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are rewriting upholstery specification protocols, while logistics innovation and digital procurement platforms compress traditional channel structures.
High-resilience foam core formulations with density ratings exceeding residential-grade alternatives are rewriting durability benchmarks for commercial hospitality seating. Hotel operators in Singapore and Dubai are specifying these cores for lobby configurations with intensive daily use cycles. The technology is compressing replacement intervals and shifting total-cost-of-ownership calculations in procurement evaluations.
REACH Annex XVII chromium VI restrictions are reshaping European leather supply bases, compelling tanneries in Italy and Spain to invest in vegetable-tanning infrastructure or synthetic polymer alternatives. The industrial consequence is a bifurcation between heritage artisan producers and scaled manufacturers with chemistry-agnostic finishing lines. Hospitality procurement teams are responding with dual-source strategies that segregate EU-compliant and legacy-tanned upholstery streams.
Subscription-tier white-glove delivery and in-home assembly is displacing traditional freight-only logistics for premium residential purchases. Restoration Hardware's proprietary membership program exemplifies the bundling of product and service into recurring revenue structures. This pattern is most visible in suburban United States markets where consumer willingness to pay for convenience sustains margin premiums over standard freight alternatives.
First-Class Sofa Market Segmentation
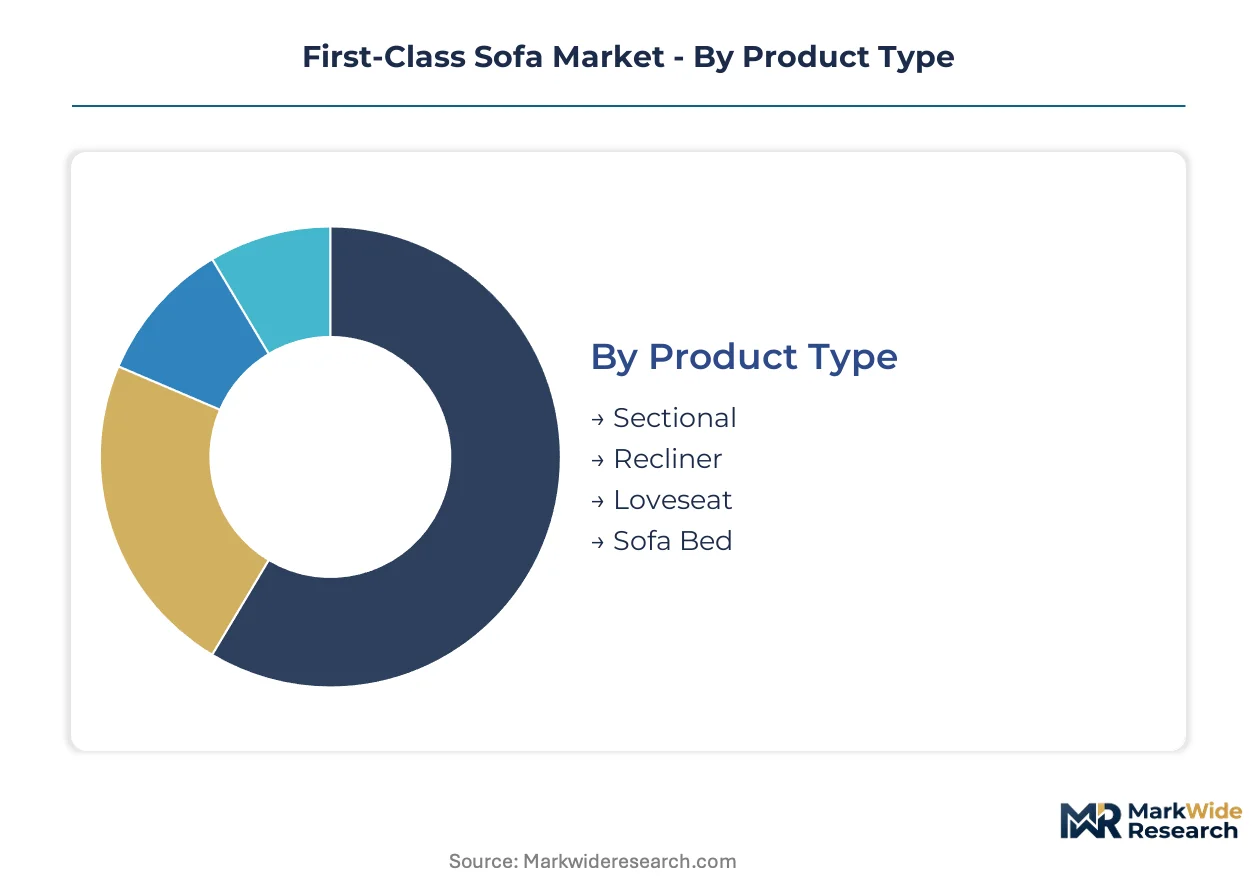
First-class sofa procurement decisions split across four distinct category axes, each commanding separate supply chain configurations and margin structures. Manufacturers optimize production networks differently depending on whether they chase hospitality volume or residential premium pricing.
Product Type:
Frame engineering and suspension system investments concentrate most heavily in two configuration categories that anchor both commercial and residential procurement.
- Sectional:Modular frame systems with configurable components dominate open-plan residential layouts in suburban United States and Australian developments. Hotel lobby reconfigurations in Dubai and Singapore are accelerating specification of sectional units with eight-way hand-tied suspension and high-resilience foam cores exceeding standard density ratings.
- Recliner:Mechanized frame assemblies integrate motorized tilt systems with kiln-dried hardwood foundations. Demand clusters in North American residential markets where aging demographics prioritize ergonomic adjustability over fixed-position seating.
- Loveseat:Compact two-seat configurations serve boutique hospitality suites and urban residential footprints with space constraints.
- Sofa Bed:Dual-function mechanisms with fold-out mattress systems target secondary residential spaces and extended-stay hospitality properties.
Today's leader: Sectional. Tomorrow's challenger: Recliner.
Material:
Raw input sourcing geography and finishing chemistry compliance costs create tiered margin pools across upholstery categories.
- Leather:Full-grain hides with artisan finishing command the widest margin spreads due to livestock supply volatility and tannery capacity constraints. EU REACH Annex XVII chromium VI restrictions are forcing Italian and Spanish tanneries toward vegetable-tanning retooling, bifurcating supply between heritage producers and chemistry-agnostic scaled manufacturers.
- Fabric:Woven synthetic and natural fiber blends offer specification flexibility at compressed price points. Hospitality procurement in Germany and Italy is accelerating adoption of performance-grade fabric alternatives as chrome-free leather transitions create temporary supply gaps.
- Velvet:Dense pile constructions with cotton or synthetic bases target aesthetic-driven residential segments in high-end urban developments.
- Microfiber:Ultra-fine synthetic filament constructions emphasize stain resistance and durability for family-oriented residential applications.
Leather maintains pricing power through supply scarcity. Fabric is gaining share fastest through regulatory-driven substitution.
Style:
Design lineage determines both manufacturing labor intensity and distribution channel placement for premium seating.
- Contemporary:Clean-line silhouettes with minimal ornamentation align with modern hospitality specifications in Singapore and Dubai luxury developments. Production concentrates with manufacturers possessing CNC woodworking capability for precision frame fabrication.
- Traditional:Ornate carving and rolled-arm constructions require skilled hand-finishing that extends lead times. Demand persists in established United States suburban markets where heritage aesthetics sustain premium positioning.
- Mid-Century Modern:Tapered leg and tight-back configurations target design-conscious urban residential buyers.
- Rustic:Distressed leather and exposed wood grain finishes serve lodge-style hospitality properties and rural residential markets.
Contemporary styling anchors commercial volume. Traditional styling defends margin in legacy residential segments.
End User:
Procurement sophistication and total-cost-of-ownership calculation methods diverge sharply across buyer categories.
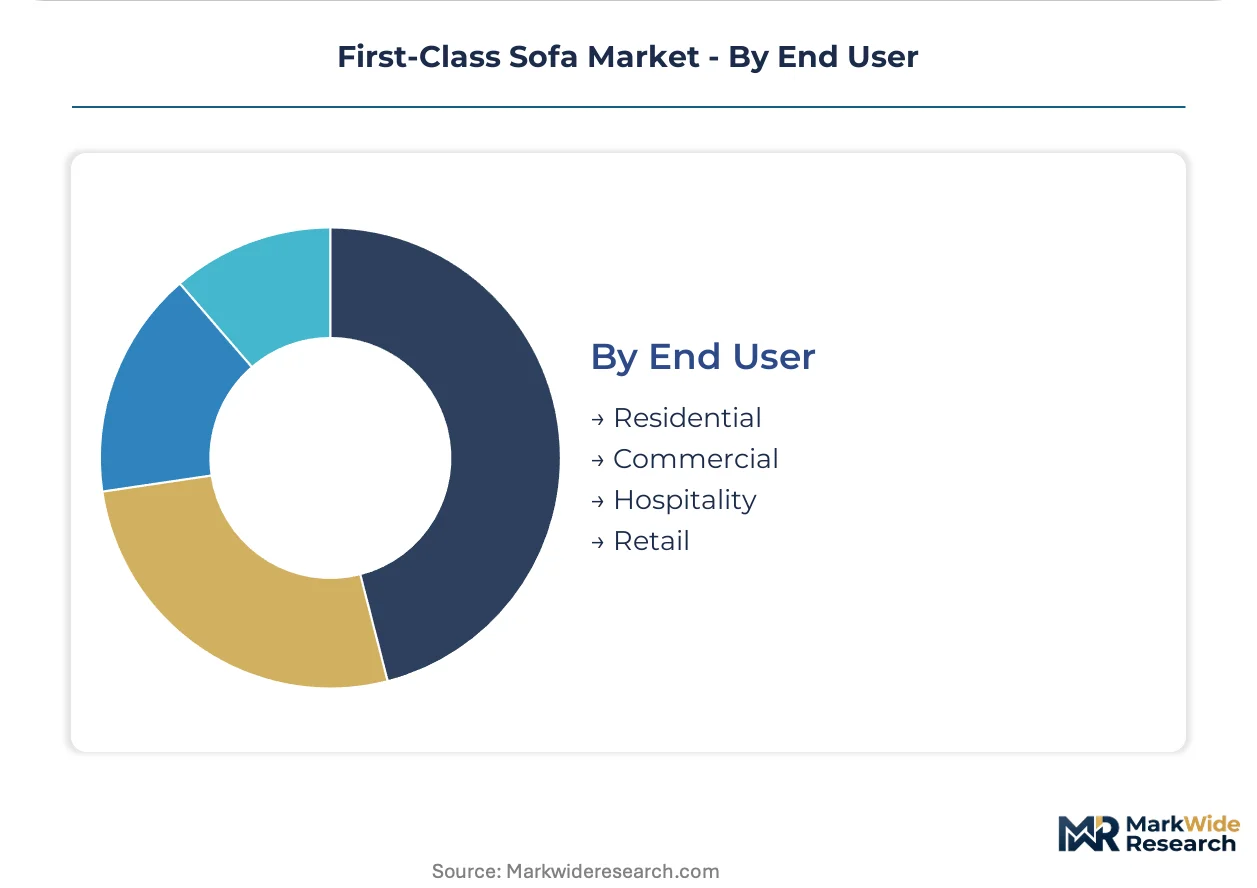
- Residential:Individual purchasers prioritize aesthetic coordination and white-glove delivery convenience. Subscription-tier assembly services in United States suburban markets are consolidating repeat purchase revenue for manufacturers with captive logistics networks.
- Hospitality:Procurement teams in Dubai and Singapore luxury developments specify eight-way hand-tied suspension and high-resilience foam cores based on intensive daily use cycle calculations. Replacement interval compression justifies upfront premium positioning.
- Commercial:Corporate lounge and executive seating buyers emphasize durability certification and bulk procurement efficiency.
- Retail:Furniture showroom and design center purchasers curate inventory for resale to downstream residential and commercial clients.
Hospitality drives specification innovation. Residential sustains volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's REACH-driven upholstery compliance costs diverge sharply from the United States' state-by-state disposal mandates, creating divergent cost structures for manufacturers serving both markets. Luxury hospitality procurement in Singapore and Dubai operates on replacement-interval calculations that justify premium foam specifications unavailable in most residential channels. Suburban developments across Australia and the United States are normalizing sectional configurations that strain traditional frame engineering capacity.
United States
Suburban residential developments in Texas and Florida are driving sectional sofa specifications with modular frame systems. EPA formaldehyde emission standards under the Toxic Substances Control Act govern composite wood components entering domestic distribution. North Carolina's furniture manufacturing corridor concentrates kiln-dried hardwood frame production among vertically integrated producers with captive lumber yards.
Germany
Hospitality procurement teams in Berlin and Munich are accelerating chrome-free leather adoption as REACH Annex XVII chromium VI restrictions reshape tannery compliance. ECHA enforcement of vegetable-tanning transitions is bifurcating supply between heritage artisan producers and chemistry-agnostic scaled manufacturers. Baden-Württemberg's industrial upholstery cluster is retooling finishing lines to serve dual-source specification strategies.
Singapore
Luxury hotel lobby reconfigurations are specifying high-resilience foam cores with density ratings exceeding residential-grade alternatives for intensive daily use cycles. The Building and Construction Authority's fire safety regulations govern upholstery flammability standards for commercial installations. Marina Bay hospitality developments are compressing replacement intervals through premium suspension system investments.
Dubai
Luxury hospitality suite upgrades are driving eight-way hand-tied spring suspension specifications for durability benchmarking. Dubai Municipality's product safety standards align with EU REACH chemical restrictions for imported upholstery materials. Jumeirah Beach hospitality clusters are consolidating procurement power for high-specification foam core volumes.
Australia
Open-plan residential layouts in Melbourne and Sydney suburbs are displacing traditional fixed seating with configurable sectional systems. The Australian Competition and Consumer Commission's product safety standards govern frame stability and upholstery flammability for domestic sales. Victoria's manufacturing base is adapting modular engineering investments to capture suburban development demand.
First-Class Sofa Market Competitive Landscape
Top-tier vendors anchor premium hospitality and residential segments, while mid-scale fabricators compete on digital catalog breadth and logistics partnerships. The vendor base spans heritage furniture houses with captive production networks, platform-based retailers navigating dispersed supplier complexity, and contract specialists serving commercial procurement channels. Strategic archetypes include vertically integrated manufacturers with in-house woodworking, membership-program retailers bundling product and white-glove service, and platform operators leveraging logistics partnerships. Dominant competitive moves encompass captive lumber yard acquisitions and subscription-tier delivery service launches.
Among North American heritage houses, Ethan Allen Global and La-Z-Boy Incorporated exemplify vertically integrated production archetypes with owned woodworking facilities, while Restoration Hardware occupies a position representing membership-program bundling of premium seating and white-glove services. Wayfair sits within the platform-retailer archetype, competing through digital catalog scale and third-party logistics orchestration rather than captive manufacturing.
| Leading Market Players |
|---|
| Ashley Furniture Industries |
| La-Z-Boy Incorporated |
| Williams-Sonoma Inc. |
| Ethan Allen Global Inc. |
| Restoration Hardware |
| Herman Miller Inc. |
| Steelcase Inc. |
| Inter IKEA Systems B.V. |
| Wayfair |
| Others |
Pricing and Supply Chain Analysis
EU REACH Annex XVII chromium VI restrictions gate qualified leather supply and premium-tier pricing access for European hospitality procurement, forcing tanneries toward vegetable-tanning retooling that bifurcates cost structures between heritage artisan producers and chemistry-agnostic scaled manufacturers.
Pricing Analysis
Capacity additions in Spain and Italy are reshaping price floors for chrome-free leather upholstery as tanneries retool finishing lines to serve dual-source specification strategies. Three-tier pricing structure across premium, standard, and economy levels separates full-grain artisan hides from vegetable-tanned alternatives and performance-grade fabric substitutes. Price differentiation hinges on certification grade for EU chemical compliance and brand premium for white-glove delivery bundling. Cost compression in standard-tier fabric upholstery is intensifying because hospitality procurement teams in Germany are accelerating regulatory-driven substitution. Budget-conscious residential buyers in Australian suburbs exhibit highest price sensitivity, while Dubai luxury hotel operators demonstrate lowest sensitivity due to replacement-interval calculations.
Supply Chain Analysis
Kiln-dried hardwood frame supply rests on North Carolina's furniture manufacturing corridor, Italian tannery clusters, and Australian modular engineering facilities. Raw material dependencies include full-grain livestock hides, high-density polyurethane foam cores, and eight-way hand-tied spring suspension components. Single-source vulnerability concentrates in skilled craftsmanship pools for traditional suspension installation, extending production lead times. Distribution runs through vertically integrated manufacturers with captive lumber yards, platform retailers orchestrating third-party logistics, and contract specialists serving commercial procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in premium-tier upholstery segments where regulatory compliance investments and white-glove service bundling sustain pricing power against commodity-grade alternatives.
For Market Incumbents: Anchor market position through captive acquisition of kiln-dried hardwood lumber yards and proprietary membership program structures that consolidate repeat residential revenue. Defend against platform-based retailers by deepening control over in-home assembly logistics networks. Prioritize certification investment for EU REACH Annex XVII compliance to maintain hospitality specification access. For New Entrants and Emerging Players: The price-point gap between premium leather and economy fabric tiers creates entry opportunity for mid-market chrome-free alternatives with performance-grade specifications. Target hospitality procurement teams in Singapore and Dubai seeking durability benchmarks without full-grain artisan pricing. Pursue white-label manufacturing partnerships with established tanneries transitioning vegetable-tanning capacity. For Investors and Strategic Acquirers: Roll-up economics work for regional upholstery fabricators with modular engineering capabilities because suburban residential developments across the United States and Australia are normalizing sectional configurations that strain traditional frame capacity. Five-to-ten year viability favors targets with established logistics partnerships and hospitality certification credentials. Watch for inflection where state-level extended producer responsibility frameworks trigger consolidation pressure among dispersed supplier bases.| Strategic Initiative | Industry Significance |
|---|---|
| Chrome-Free Tanning Transition | EU REACH compliance investments by Italian tanneries unlock hospitality specification access in Germany. |
| Captive Lumber Yard Acquisition | Vertically integrated hardwood frame production insulates margin pressure from commodity lumber cycles. |
| White-Glove Service Tier Launch | Subscription-based in-home assembly consolidates repeat residential revenue for manufacturers with logistics networks. |
| Modular Frame Engineering Scale-Up | Configurable sectional systems capture open-plan residential demand in Texas and Florida suburban developments. |
| Hospitality Certification Investment | Eight-way hand-tied suspension credentials secure Dubai and Singapore luxury suite upgrade specifications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with furniture manufacturing executives, hospitality procurement directors, tannery operations managers, and residential retail channel heads with secondary validation through customs trade data, EPA formaldehyde emission filings, ECHA REACH enforcement records, and hospitality development specification databases. Bottom-up segment sizing and top-down market triangulation cross-validated volume and value estimates.
Segment-weighting approaches modeled product type, material chemistry compliance tier, end-use procurement sophistication, and regional regulatory framework clusters across the projection horizon. CAGRs derived from historical trajectory analysis and forward-looking replacement cycle assumptions incorporated kiln-dried hardwood lumber price indices and hospitality construction pipeline tracking.
Caveats apply where REACH Annex XVII enforcement intensity, state-level furniture disposal mandate adoption, or livestock supply volatility could materially shift the outlook. A small set of named triggers—ECHA inspection frequency, extended producer responsibility legislative momentum, and skilled craftsmanship labor pool contraction—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture & Home Decor
US Home Remodeling Market
Furniture & Home Decor
Wardrobe Boxes Market
Furniture & Home Decor
Study Carrels Market
Furniture & Home Decor
US Contract Furniture and Furnishing Market
Furniture & Home Decor
United States Home Decor Market
Furniture & Home Decor
North America Sustainable Home Decor Market
Furniture & Home Decor
North America Wood Flooring Market
Furniture & Home Decor
India Modular Kitchen Market
Furniture & Home Decor
Global Mattress Market
Furniture & Home Decor
Europe Bath and Shower Products Market
Furniture & Home Decor
Soundproof Door Market
Furniture & Home Decor
Saudi Arabia Carpet and Rugs Market
Furniture & Home Decor
Europe Vinyl Flooring Market
Furniture & Home Decor
USA Bed Pillow Market
Furniture & Home Decor
Europe Steam Room Market
Furniture & Home Decor
Organic Bed Linen Market