
 Fighting Games Market | 2026-2036
Fighting Games Market Size, Share, and Industry Trends Forecast 2026-2036
Fighting Games Market Insights
The capability gap between in-house engine ownership and licensed middleware reliance is bifurcating development economics across the sector. Capcom leverages its proprietary RE Engine to sustain margin control over iterative franchise releases. NetherRealm Studios anchors its competitive position through Warner Bros.' distribution infrastructure and cinematic production pipelines. Bandai Namco Entertainment differentiates via cross-media integration spanning anime licenses and toy-to-game conversions.
Fighting games constitute competitive video game software built around one-on-one or team-based melee combat systems, typically operating at 60 frames per second to ensure input responsiveness for combo execution and frame-data balancing. The primary commercial purpose centers on repeatable player engagement through ranked online infrastructure, seasonal content cycles, and sanctioned tournament circuits that extend software lifespans beyond traditional retail windows. The 2D segment retains structural dominance through lower asset production costs and established esports viewership, while the Mobile platform represents the fastest-expanding margin pool as touch-control refinements and cloud-streaming reduce hardware barriers. Digital Download distribution channels now command the primary revenue share, though Subscription Services are reshaping player acquisition economics by bundling legacy catalogs with day-one releases.
The ESRB rating system in the United States and PEGI framework in Europe govern content classification for violent combat mechanics, directly influencing platform access policies and marketing channel availability. China's NPPA approval process and play-time restrictions for minors impose structural constraints on release timing and monetization architecture for publishers targeting that territory. Japan's CERO ratings similarly shape domestic arcade-to-console porting strategies. Stakeholders must monitor evolving platform-holder fee structures and regional content compliance timelines as determinants of effective market entry sequencing.
Market Dynamics
Unreal Engine 5 adoption is compressing production timelines and redistributing competitive advantage from proprietary engine holders to middleware-dependent studios across the fighting games sector.
Growth Catalysts
- Cloud-streaming infrastructure:Microsoft's Xbox Cloud Gaming and Sony's PlayStation Plus reduce hardware barriers for touch-control fighting game access in emerging markets.
- Japan's tournament circuit density:Tokyo and Osaka host year-round Evo Japan, Battle Arena Melbourne qualifiers, and domestic arcade-to-console migration events that sustain software lifespans.
- Cross-media IP licensing:Anime-to-game conversions leverage established fanbases to reduce player acquisition costs for new fighting game releases.
Market Restraints
- Input latency from cloud infrastructure:Frame-data precision requirements at 60 frames per second create technical barriers for competitive play over streaming protocols.
- Platform-holder fee structures:Apple App Store and Google Play Store revenue splits compress margins for mobile fighting game monetization.
- China's NPPA approval backlog:Release timing uncertainty for imported titles delays revenue recognition from the world's largest gaming population.
Strategic Opportunities
- India's underpenetrated esports infrastructure:Low-cost smartphone penetration and 5G rollout create first-mover potential for localized fighting game tournaments.
- Subscription service bundling:Xbox Game Pass and PlayStation Plus catalog inclusions shift player acquisition from unit sales to recurring revenue pools.
- AI-assisted training modes:Machine learning replay analysis and combo optimization tools differentiate premium-tier releases from standard editions.
Industry Challenges
- Netcode engineering talent scarcity:Rollback netcode implementation requires specialized networking expertise that concentrates in Japanese and North American studios.
- Seasonal content pipeline scaling:Live-service operation demands continuous character balancing, stage releases, and cosmetic DLC that strain post-launch development teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fighting Games Market |
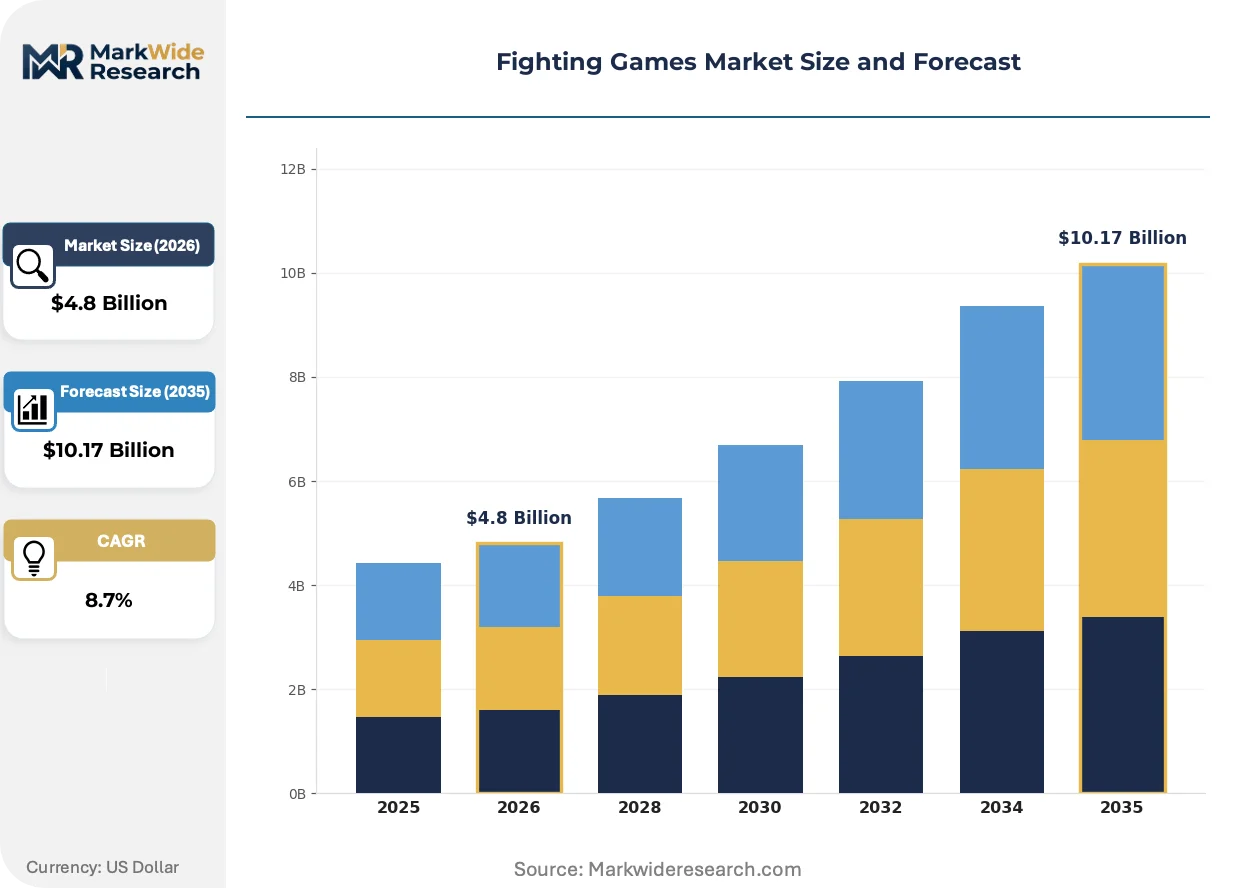
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: 2D, 3D, Arena, Tag Team Platform: Console, PC, Mobile, Arcade Distribution Channel: Digital Download, Retail, Subscription Services, Free-to-Play Competitive Format: Online Tournaments, Local Tournaments, Championships, Exhibition Matches |
| Companies Covered | Arc System Works, Sega, Capcom, Project Soul, Bandai Namco Entertainment, Namco, SNK Playmore, Koei Tecmo, NetherRealm Studios, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fighting Games Market Trends and Innovations
Three forces are restructuring how fighting games are produced, distributed, and monetized: engine technology migration, regional regulatory fragmentation, and player engagement model evolution.
Rollback netcode is supplanting delay-based netcode as the industry standard for online competitive integrity. Japanese developers at Arc System Works and Bandai Namco Entertainment have retrofitted legacy titles with GGPO-derived implementations. The technology is compressing the viable competitive window for titles lacking infrastructure investment.
Europe's Digital Services Act and GDPR enforcement are reshaping how publishers collect and monetize player behavioral data for matchmaking algorithms. Fighting game studios must now implement granular consent flows and data portability features. These requirements are most burdensome for mid-tier publishers lacking dedicated compliance infrastructure.
Season pass monetization is displacing traditional expansion pack releases as the dominant post-launch revenue architecture. Players now expect continuous character drops rather than discrete sequel purchases. This pattern is most visible in North American and Japanese markets where esports viewership correlates directly with roster freshness.
Fighting Games Market Segmentation
Fighting games require precise segmentation because frame-rate requirements and input latency tolerances vary dramatically across hardware platforms. Regulatory content classifications and distribution channel economics further fragment addressable markets by territory.
Game Type:
Regulatory differentiation shapes development economics across dimensional formats, with ESRB and PEGI violence descriptors applying stricter scrutiny to photorealistic 3D combat than stylized 2D animation.
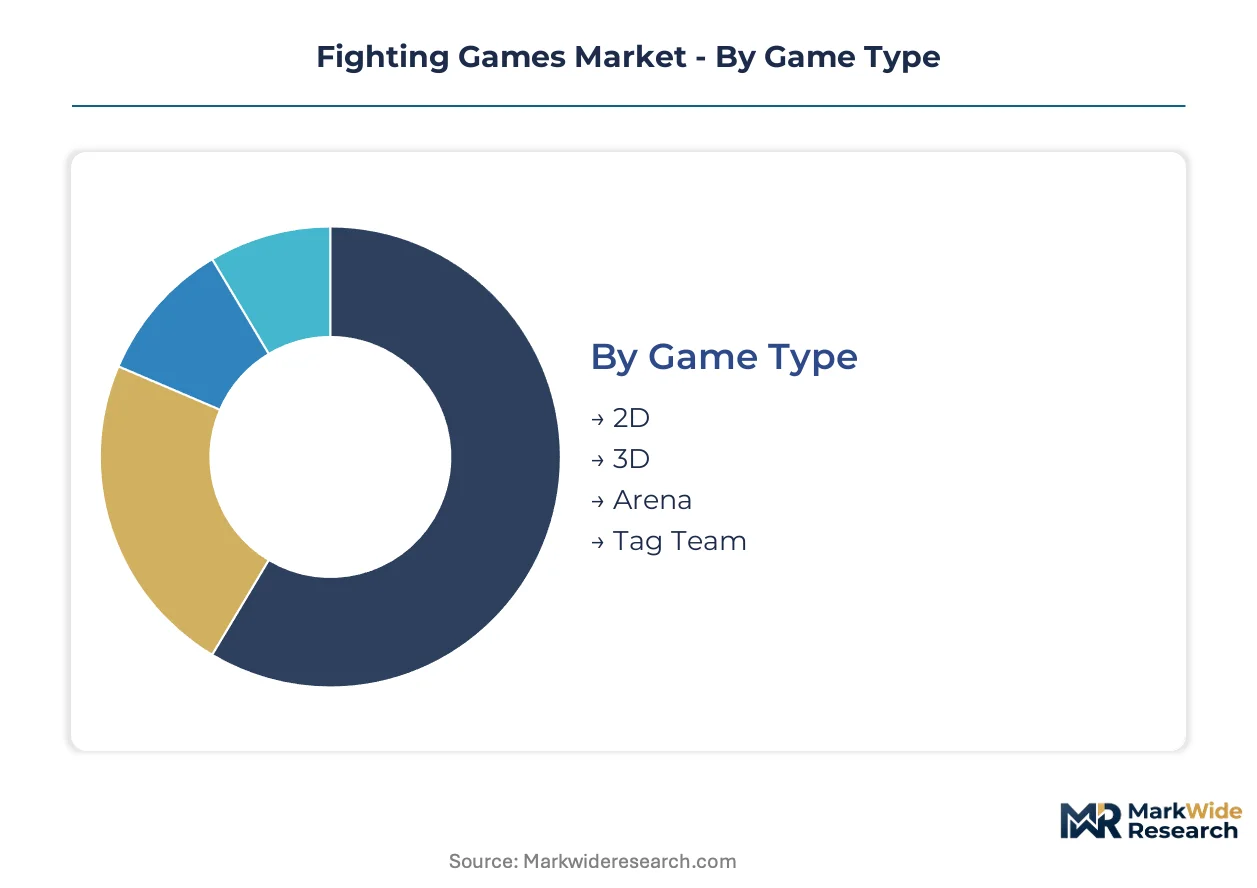
- 2D:Sprite-based or hand-drawn animation pipelines operate at lower asset production costs while maintaining 60 frames per second responsiveness. Japanese developers in Tokyo and Osaka sustain concentrated tournament viewership through legacy franchises that reduce player acquisition expenses.
- 3D:Photorealistic character models and dynamic camera systems demand higher polygon budgets and motion-capture infrastructure. Studios leveraging Unreal Engine 5 compress production timelines against proprietary engine holders, redistributing competitive advantage across North American and European middleware-dependent developers.
- Arena:Multi-directional movement systems and environmental hazard integration distinguish this format from traditional plane-locked combat.
- Tag Team:Character switching mechanics and assist-call systems expand combo complexity for dedicated competitive players.
2D handles the majority of throughput; Arena is the fastest mover on share.
Platform:
Cost tier stratification separates premium hardware investments from accessible entry points, with cloud-streaming infrastructure compressing this divide in emerging markets.
- Console:Dedicated gaming hardware from Sony, Microsoft, and Nintendo delivers standardized 60 frames per second performance with controller-optimized input latency. Japan's domestic market maintains disproportionate concentration here due to arcade-to-console migration patterns and legacy publisher IP ownership.
- Mobile:Touch-control refinements and 5G rollout reduce hardware barriers for competitive access. India's underpenetrated esports infrastructure creates first-mover potential as low-cost smartphone penetration accelerates.
- PC:Modular hardware configurations and rollback netcode implementation attract dedicated competitive players.
- Arcade:Location-based physical cabinets sustain concentrated tournament circuits in Japanese urban centers.
Console handles the majority of throughput; Mobile is expanding most quickly.
Distribution Channel:
Margin concentration shifts from unit sales toward recurring revenue pools as platform-holder fee structures reshape publisher economics.
- Digital Download:Direct-to-consumer storefronts from Sony, Microsoft, Valve, and Nintendo command primary revenue share by eliminating physical manufacturing and retail margin extraction. Platform-holder 30% revenue splits compress net margins compared to first-party storefront alternatives.
- Subscription Services:Xbox Game Pass and PlayStation Plus catalog inclusions shift player acquisition from upfront purchases to recurring revenue pools. This model concentrates in North American and Western European markets where bundled access reduces trial friction for new releases.
- Retail:Physical disc and cartridge sales persist in collector markets and regions with limited broadband infrastructure.
- Free-to-Play:Cosmetic monetization and season pass architectures extend software lifespans without entry price barriers.
Digital Download handles the majority of throughput; Subscription Services is climbing the fastest.
Competitive Format:
Geographic clustering determines infrastructure investment returns, with tournament circuit density varying dramatically by metropolitan region.
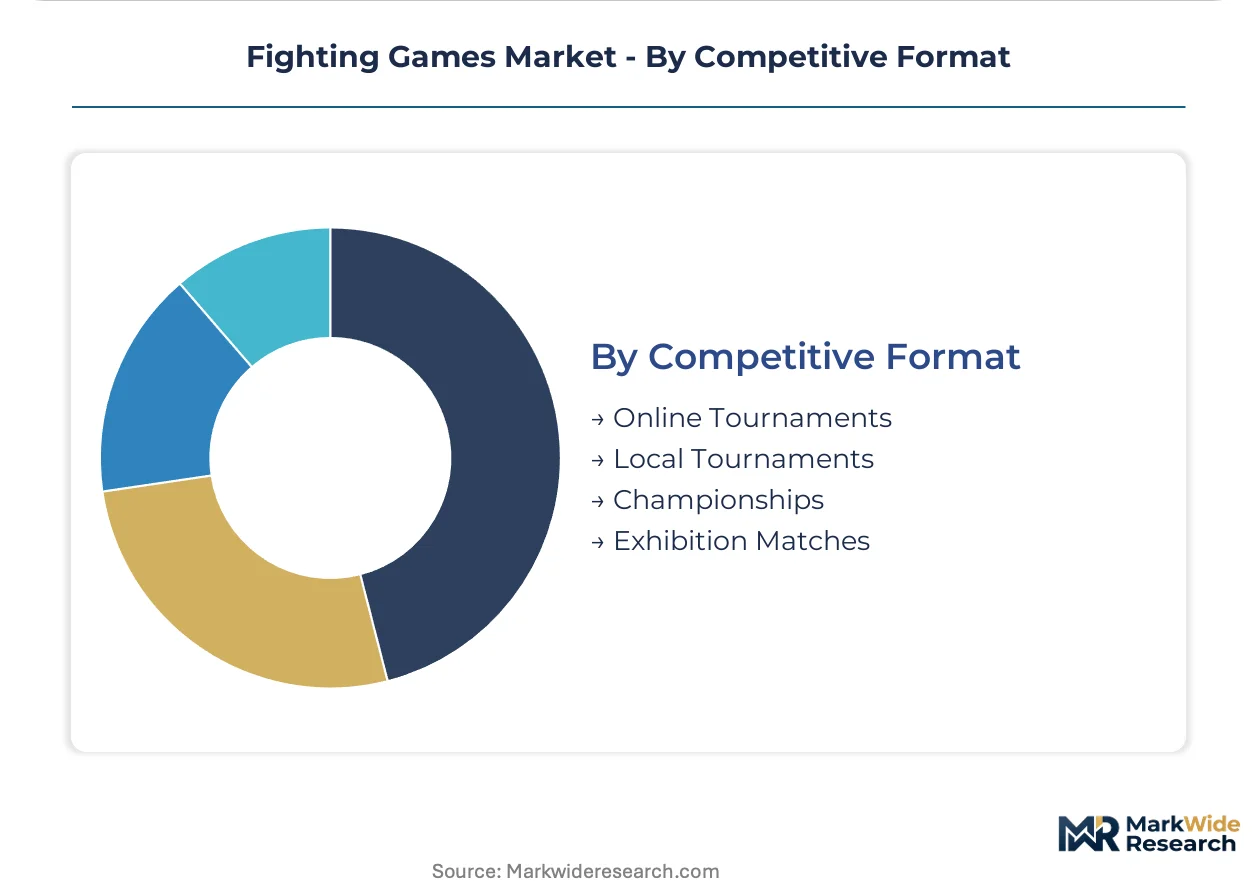
- Online Tournaments:Rollback netcode implementation enables cross-territory competition without physical travel requirements. Netcode engineering talent scarcity concentrates this capability in Japanese and North American studios, compressing the viable competitive window for titles lacking infrastructure investment.
- Championships:Evo, Capcom Cup, and Tekken World Tour anchor sanctioned circuits with substantial prize pools and broadcast distribution. Japan's year-round event density in Tokyo and Osaka sustains software lifespans through continuous player engagement.
- Local Tournaments:Regional community events and arcade gatherings maintain grassroots competitive ecosystems.
- Exhibition Matches:Promotional showmatches and character reveal events drive marketing visibility outside competitive rankings.
Online Tournaments handles the majority of throughput; Championships is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese metropolitan clusters where tournament infrastructure density commands premium licensing terms, while emerging mobile markets in South Asia operate on compressed unit economics driven by platform-holder fee structures.
Japan
Tokyo and Osaka sustain year-round tournament circuits including Evo Japan qualifiers and domestic arcade-to-console migration events that extend software lifespans. CERO ratings govern violent content classification and directly shape domestic release timing strategies. Kanto and Kansai regions host concentrated development studios leveraging proprietary engine ownership for margin control.
United States
Rollback netcode engineering talent concentrates in California and Texas development clusters, creating competitive barriers for studios lacking specialized networking expertise. ESRB violence descriptors influence platform access policies and marketing channel availability for major releases. Los Angeles and Austin anchor esports production infrastructure that drives championship broadcast distribution.
South Korea
PC bang culture and 5G infrastructure penetration create favorable conditions for low-latency competitive play adoption. MFDS content classification applies to imported titles with violent combat mechanics, affecting release sequencing. Seoul Capital Area development studios specialize in live-service operation and seasonal content pipeline scaling.
China
NPPA approval backlogs impose structural constraints on release timing and monetization architecture for imported fighting game titles. Dual carbon goals and play-time restrictions for minors reshape publisher market entry calculations. Shanghai and Shenzhen development clusters focus on mobile-first touch-control refinements for domestic smartphone penetration.
India
Low-cost smartphone penetration and 5G rollout create first-mover potential for localized tournament infrastructure in underpenetrated esports markets. TRAI telecommunications regulations shape cloud-streaming service availability for touch-control fighting game access. Maharashtra and Karnataka metropolitan areas emerge as early concentration points for grassroots competitive event organization.
Fighting Games Market Competitive Landscape
Concentration sits with legacy Japanese publishers maintaining proprietary engine ownership and concentrated intellectual property portfolios. The competitive structure bifurcates between in-house technology holders and middleware-dependent studios leveraging Unreal Engine 5 adoption. Three archetypes dominate: integrated engine-owning publishers, cross-media licensors with anime-to-game conversion capabilities, and cinematic production specialists anchored to major distribution infrastructure. Rollback netcode retrofitting and seasonal content pipeline scaling constitute the dominant competitive moves reshaping post-launch development economics.
Within the integrated engine-owning tier, Capcom and Bandai Namco Entertainment exemplify publishers sustaining margin control through proprietary technology ownership and iterative franchise release strategies. Arc System Works occupies a position representing specialized 2D animation pipeline expertise with concentrated tournament viewership loyalty. NetherRealm Studios anchors the cinematic production specialist archetype through Warner Bros. distribution infrastructure access.
| Leading Market Players |
|---|
| Arc System Works |
| Sega |
| Capcom |
| Project Soul |
| Bandai Namco Entertainment |
| Namco |
| SNK Playmore |
| Koei Tecmo |
| NetherRealm Studios |
| Others |
Pricing and Supply Chain Analysis
Unreal Engine 5 licensing is displacing proprietary engine ownership across Japanese and North American studios, simultaneously compressing development cost structures and redistributing pricing power from integrated publishers to middleware-dependent developers.
Pricing Analysis
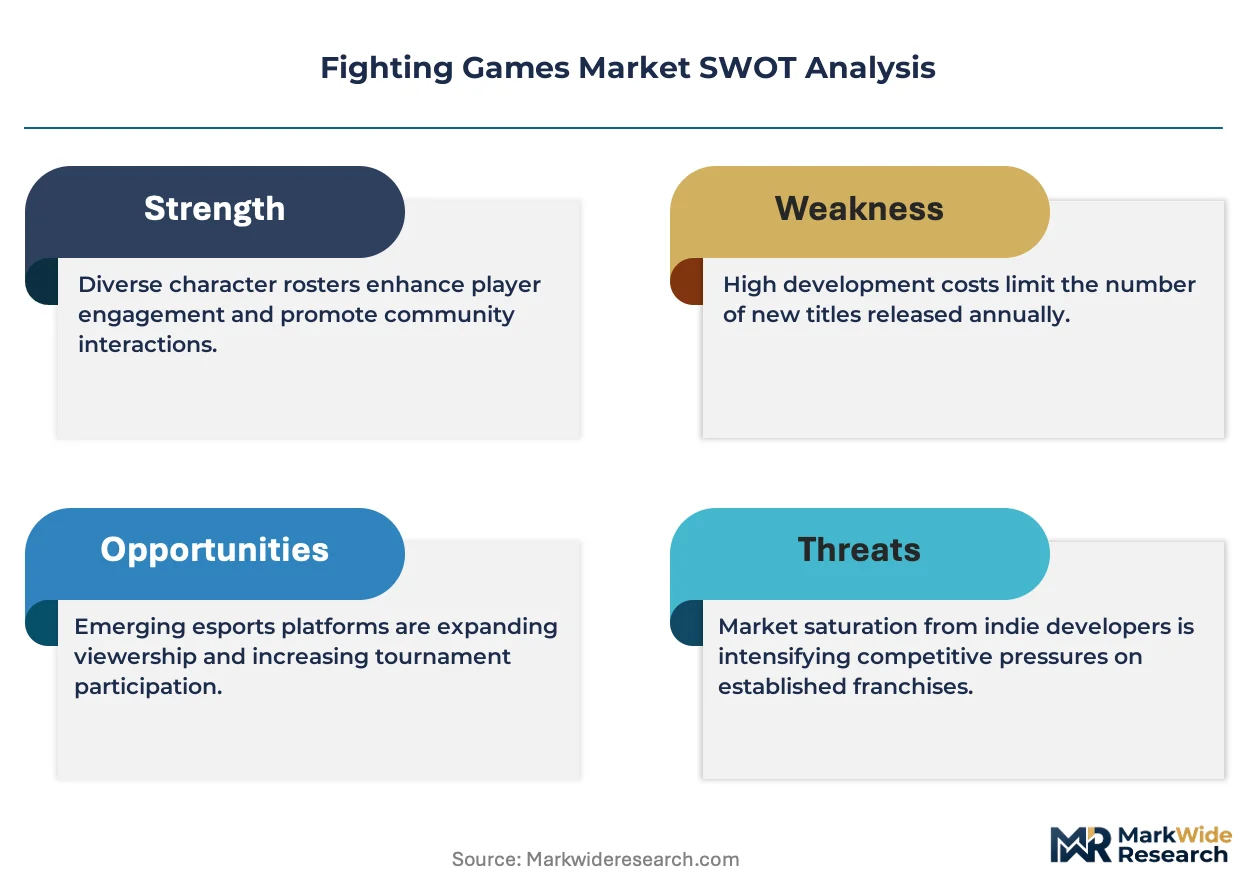
The customization-premium spread between standard digital releases and collector's editions with season pass bundles commands substantial margin differentiation. Three-tier pricing structure across premium, standard, and economy levels reflects content depth and tournament infrastructure access rather than hardware performance tiers. Pricing pressure stems from subscription service bundling that shifts player acquisition from unit sales to recurring revenue pools. Mobile platform buyers exhibit highest price sensitivity due to platform-holder fee structures, while championship-tier esports participants accept premium pricing for rollback netcode performance and tournament eligibility.
Supply Chain Analysis
Port congestion on transpacific trade lanes from Shanghai and Shenzhen to Los Angeles has elevated inbound logistics costs for arcade cabinet components and specialized controller hardware. Development talent concentrates in Japan, South Korea, and the United States, with animation pipelines drawing from outsourced studios in Vietnam and the Philippines. Raw material dependencies span motion-capture infrastructure, cloud server capacity, and semiconductor components for arcade hardware. Single-source vulnerability sits with rollback netcode engineering expertise concentrated in Tokyo and Austin development clusters. Distribution runs through platform-holder storefronts from Sony, Microsoft, Valve, and Nintendo with standardized revenue splits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fighting games market sits at a cyclical recovery phase driven by cloud-streaming infrastructure maturation that reduces hardware barriers for competitive access.
For Market Incumbents: Compound tournament infrastructure investment in Tokyo and Osaka to extend software lifespans beyond traditional retail windows. Secure exclusive rollback netcode engineering talent against middleware-dependent entrants leveraging Unreal Engine 5 adoption. Vertical integration into cross-media IP licensing reduces player acquisition costs for iterative franchise releases. For New Entrants and Emerging Players: Differentiate on AI-assisted training modes and machine learning replay analysis that premium-tier publishers have underinvested in. Target India's underpenetrated esports infrastructure where low-cost smartphone penetration and 5G rollout create first-mover potential for localized tournament circuits. Pursue direct-to-consumer distribution through first-party storefronts to bypass platform-holder fee compression. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors middleware-dependent studios with Unreal Engine 5 production capabilities over proprietary engine holders facing rising maintenance costs. Long-term viability rests on seasonal content pipeline scaling expertise and cross-media IP portfolio breadth. Watch rollback netcode retrofitting announcements as the inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Rollback Netcode Retrofitting | GGPO-derived implementations from Arc System Works and Bandai Namco compress viable competitive windows for legacy titles lacking infrastructure investment. |
| Cross-Media IP Licensing | Anime-to-game conversions from concentrated Japanese publishers leverage established fanbases to reduce player acquisition costs for new releases. |
| Cloud-Streaming Partnership | Microsoft's Xbox Cloud Gaming and Sony's PlayStation Plus reduce hardware barriers for touch-control fighting game access in emerging South Asian markets. |
| Season Pass Monetization Architecture | Continuous character drops displace discrete sequel purchases in North American and Japanese markets where esports viewership correlates with roster freshness. |
| AI-Assisted Training Mode Development | Machine learning replay analysis and combo optimization tools differentiate premium-tier releases from standard editions for dedicated competitive players. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with game development executives, esports tournament organizers, platform-holder partnership leads, and netcode engineering specialists; and secondary validation against SEC filings from Warner Bros. Discovery and Capcom, Steam player concurrency databases, Evo championship viewership metrics, and CERO content classification records. Bottom-up triangulation across individual title revenue models and top-down validation against publisher segment disclosures anchored volume and value estimates.
Across the projection horizon, the analytical framework modeled game type segmentation by dimensional format, platform tier by hardware performance and input latency tolerance, distribution channel economics by margin structure, and competitive format by geographic circuit density. CAGRs derived from historical release cadence analysis, seasonal content attach rates, and tournament viewership correlation with software lifespan extension. Forecast inputs incorporated Unreal Engine 5 adoption curves, rollback netcode implementation timelines, and mobile platform penetration rates in underpenetrated South Asian markets.
Forecasts assume regulatory continuity in Japan's CERO classification regime, the United States ESRB framework, and China's NPPA approval processes; material policy shifts in content restrictions or play-time limitations would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness
Move to Earn Fitness Apps Market
Sports & Fitness
Medicine Balls Market
Sports & Fitness
Sports Equipment Market
Sports & Fitness
GPS Watches for Kids Market
Sports & Fitness
Volleyball Shoes Market
Sports & Fitness
Portable Basketball Hoops Market
Sports & Fitness
3D Motion Capture Market
Sports & Fitness
Belt Trainers Market
Sports & Fitness
Ski Gear and Equipment Market
Sports & Fitness
Spain Artificial Turf Market
Sports & Fitness
Rubber Fitness Flooring Market
Sports & Fitness
Smart Fitness Device Market
Sports & Fitness
Smart Gym Equipment Market
Sports & Fitness
Branched Chain Amino Acid Supplements Market
Sports & Fitness
UK Sports Promoters Market
Sports & Fitness
Kayak Market