
 Feed Packaging Market | 2026-2036
Feed Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Packaging Market Analysis
Agricultural supply cooperatives is reconfiguring procurement standards for feed packaging across North America and Latin America. Amcor plc leverages its global film extrusion network to supply high-barrier structures for aquaculture feed producers. Mondi Group anchors European demand through kraft paper-based solutions certified under EU sustainability frameworks. Huhtamaki Oyj competes in emerging markets with localized flexible packaging lines tailored to tropical storage conditions.
Feed packaging encompasses engineered containment systems designed to protect compound feed, premixes, and nutritional additives from moisture ingress, oxidation, and pest contamination during distribution cycles. Multi-layer coextruded films incorporating ethylene vinyl alcohol barrier layers maintain oxygen transmission rates below 0.5 cc/m²/day to preserve lipid-rich formulations. Flexible bags dominate volume throughput in bulk grain and pelleted feed distribution, while pouches capture expanding margin pools in specialty premixes and probiotic additives where precise dosing and resealability command premium positioning. Rigid containers retain structural importance in mineral supplement packaging where stack strength and forklift handling durability outweigh unit cost considerations.
The EPA regulates volatile organic compound emissions from solvent-based printing processes used in feed bag manufacturing, pushing converters toward water-based ink systems. The EU Green Deal and REACH compliance requirements restrict certain phthalate plasticizers in films contacting animal nutrition products. Stakeholders must monitor evolving extended producer responsibility frameworks that will determine cost allocation between packaging manufacturers and integrated protein companies across key production geographies.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing material substitution across European compound feed supply chains while integrated protein producers in Brazil and Vietnam simultaneously upgrade specifications for tropical storage performance.
Growth Catalysts
- Poultry feed volume expansion:Integrated operations in Brazil and Thailand are commissioning multi-layer barrier pouches for lipid-rich broiler formulations requiring oxygen transmission below 0.5 cc/m²/day.
- REACH compliance migration:ECHA restrictions on phthalate plasticizers are accelerating converter adoption of bio-based polyesters and water-based ink systems for direct-contact feed films.
- Aquaculture feed premiumization:Norwegian and Chilean salmon producers are specifying ethylene vinyl alcohol barrier structures to preserve omega-3 stability through extended distribution cycles.
Market Restraints
- Ethylene vinyl alcohol supply concentration:Barrier resin production clusters in Japan and South Korea create vulnerability for European and Latin American converters lacking backward integration into polymer supply.
- Solvent-based printing phase-out costs:EPA volatile organic compound regulations are imposing capital burdens on mid-tier US converters without water-based ink infrastructure.
- Recyclability-versus-performance tradeoff:Mono-material polyethylene structures meeting EU Green Deal circularity targets sacrifice oxygen barrier performance required for high-fat aquaculture formulations.
Strategic Opportunities
- Vietnamese aquaculture packaging upgrade:Shrimp feed producers in the Mekong Delta lack access to certified high-barrier structures, creating white space for localized extrusion partnerships.
- Extended producer responsibility frameworks:Emerging EU member state implementations of packaging waste cost allocation will favor converters with established mechanical recycling streams.
- Digital printing convergence with track-and-trace:Integration of inkjet variable data with GS1-compliant serialization is enabling lot-specific probiotic additive verification for premium premix channels.
Industry Challenges
- Multi-layer film recycling infrastructure gap:Collection and sorting systems for coextruded EVOH-polyethylene structures remain underdeveloped across key European markets.
- Legacy extrusion asset reconfiguration:Converters must retool cast film lines for water-based ink compatibility without interrupting supply to agricultural cooperatives with seasonal procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Packaging Market |
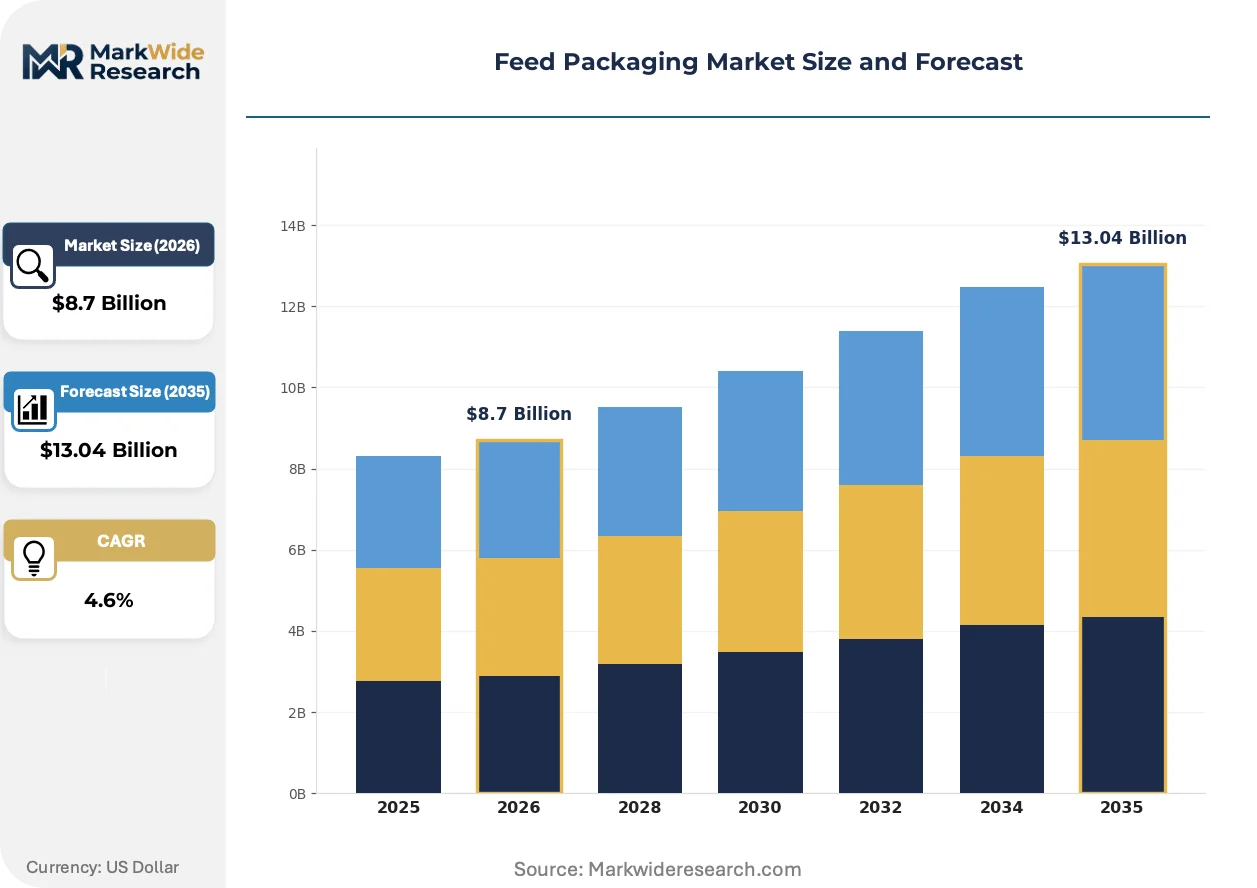
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Bags, Rigid Containers, Pouches, Foil Bags Material: Plastic, Paper, Aluminum, Composites End User: Agriculture, Animal Feed Producers, Retailers, Distributors Closure Type: Zipper, Heat Seal, Screw Cap, Twist Tie |
| Companies Covered | Amcor plc, Mondi Group, Huhtamaki Oyj, ProAmpac, LC Packaging, El Dorado Packaging, Sonoco Products Company, Winpak Ltd., Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Packaging Market Emerging Trajectories
Material science advances and regulatory stringency are compressing development cycles for feed packaging, with sustainability certification now functioning as a gatekeeping mechanism for supplier qualification at major protein integrators.
Digital twin platforms for packaging line optimization are virtualizing quality control protocols across flexible film converting operations. Brazilian and Thai compound feed producers are deploying these systems to reduce setup waste and accelerate changeover between poultry and aquaculture product runs. The technology is virtualizing traditional inspection-dependent release processes, compressing time-to-market for seasonal feed formulations.
The EU Green Deal's packaging waste reduction targets are mandating minimum recycled content thresholds for plastic packaging placed on member state markets. Feed bag converters serving Dutch and Danish agricultural cooperatives are reformulating polyethylene structures to incorporate post-industrial film scrap without compromising weld strength. Pelleted feed distribution channels face the steepest compliance burden due to volume exposure and thin margin structures.
Consolidation among North American agricultural supply cooperatives is compressing supplier rosters and extending contract durations for qualified packaging vendors. Procurement teams at these entities now require third-party sustainability certification as a baseline qualification, displacing price-only sourcing for bulk grain and mineral supplement applications. The shift is most visible in the US Midwest, where regional cooperative mergers have reduced active converter relationships by half over recent procurement cycles.
Feed Packaging Market Segmentation
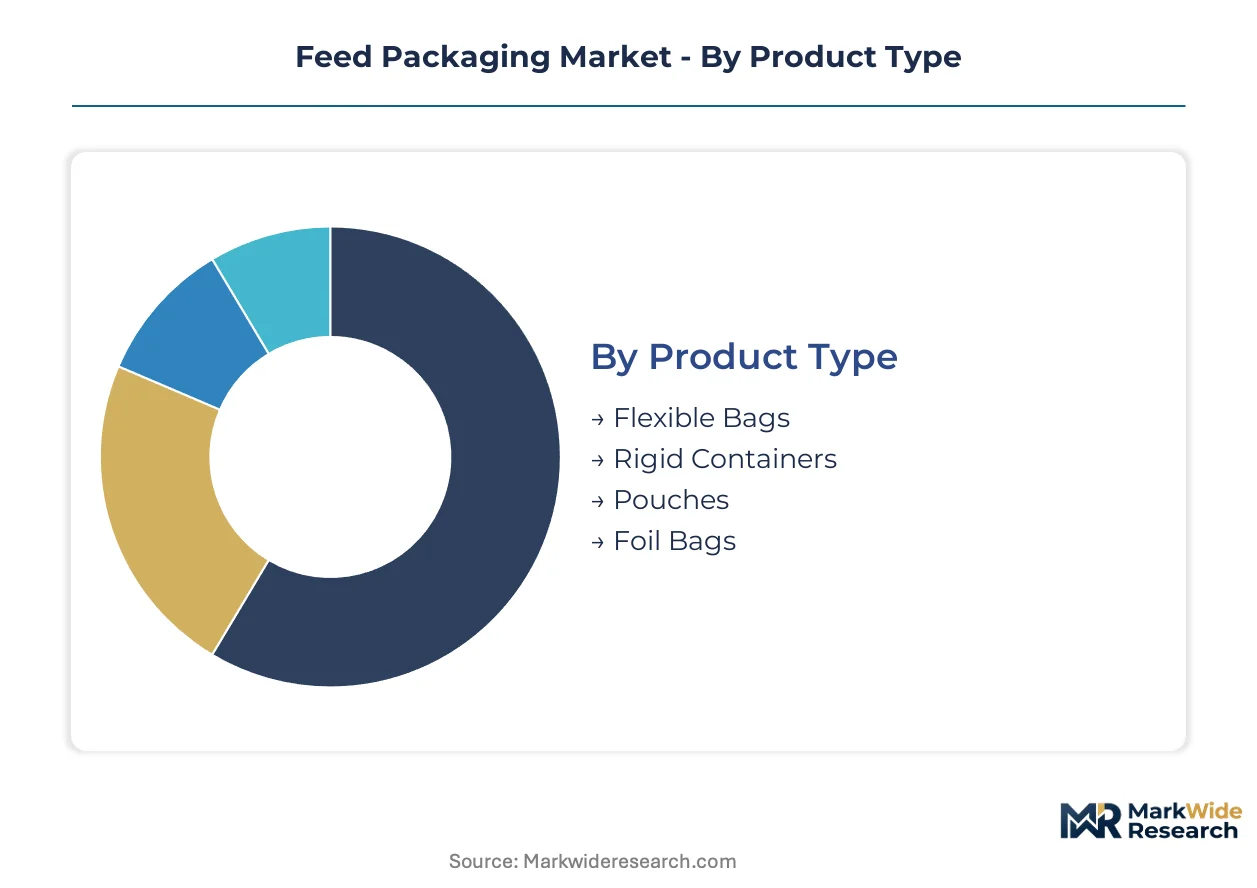
Feed packaging segmentation reveals divergent procurement rhythms across product categories, with flexible formats turning over weekly at agricultural cooperatives while rigid containers cycle quarterly through mineral supplement channels. Material specifications and closure mechanisms further stratify replacement frequencies, creating distinct margin pools for converters aligned to each velocity tier.
Product Type:
Flexible bags rotate through compound feed operations in under fourteen days during peak poultry seasons, whereas rigid containers remain in service for months across mineral supplement distribution. Pouches and foil bags occupy intermediate cycle positions driven by specialty additive shelf-life requirements.
- Flexible Bags:Multi-layer polyethylene structures dominate bulk grain and pelleted feed throughput, with Brazilian integrated protein producers specifying 25-50 kg formats for automated filling lines. Agricultural cooperatives in the US Midwest consolidate procurement around welded-bottom designs that withstand pallet stacking stress.
- Pouches:Stand-up configurations with resealable closures capture premium positioning in probiotic and enzyme additive channels where precise dosing and oxygen barrier performance command price premiums. Norwegian aquaculture feed producers specify these for omega-3 lipid preservation through extended cold-chain distribution.
- Rigid Containers:High-density polyethylene drums and intermediate bulk containers serve mineral premix and trace element formulations requiring forklift handling durability and stack strength exceeding flexible alternatives.
- Foil Bags:Aluminum-laminated structures provide maximum moisture and light protection for veterinary medicated feeds regulated under FDA Center for Veterinary Medicine guidelines, with extended shelf-life requirements driving specification.
Flexible bags anchor the volume base while pouches gain share at the steepest rate.
Material:
Cost tier stratification separates commodity polyethylene from certified sustainable alternatives, with compliance premiums widening spreads between virgin and recycled-content specifications. Paper and aluminum occupy specialty positions where functional requirements override unit economics.
- Plastic:Polyethylene and polypropylene films constitute the dominant cost tier, with EU Green Deal recycled content mandates forcing reformulation investments at Dutch and Danish converters serving agricultural cooperatives.
- Composites:Ethylene vinyl alcohol barrier layers coextruded with polyethylene maintain oxygen transmission below 0.5 cc/m²/day for lipid-rich aquaculture formulations, though recycling infrastructure gaps persist across European collection systems.
- Paper:Kraft paper-based solutions certified under EU sustainability frameworks serve pelleted feed channels where breathability and moisture management balance protection needs, with Mondi Group anchoring European supply.
- Aluminum:Foil laminates command the premium cost tier for light-sensitive and high-fat formulations, with Japanese and South Korean resin supply concentration creating vulnerability for converters lacking backward integration.
Plastic structures retain the dominant volume position while composites climb the fastest amid aquaculture feed premiumization.
End User:
Customer type determines specification stringency and contract duration, with integrated protein producers driving barrier performance upgrades while distributors prioritize logistics compatibility over material sophistication.
- Animal Feed Producers:Integrated operations in Brazil and Thailand commission multi-layer barrier specifications for broiler and aquaculture formulations, with third-party sustainability certification now baseline for vendor qualification.
- Agriculture:Supply cooperatives consolidate procurement rosters and extend contract durations, displacing price-only sourcing for bulk grain applications across North American mergers.
- Distributors:Logistics-focused buyers prioritize pallet cube efficiency and automated handling compatibility over barrier performance, with seasonal procurement windows compressing converter response requirements.
- Retailers:Small-format packaging for companion animal feeds drives resealability and shelf-appeal specifications distinct from bulk agricultural channels.
Animal feed producers anchor the volume base while agriculture sector consolidation accelerates specification upgrading.
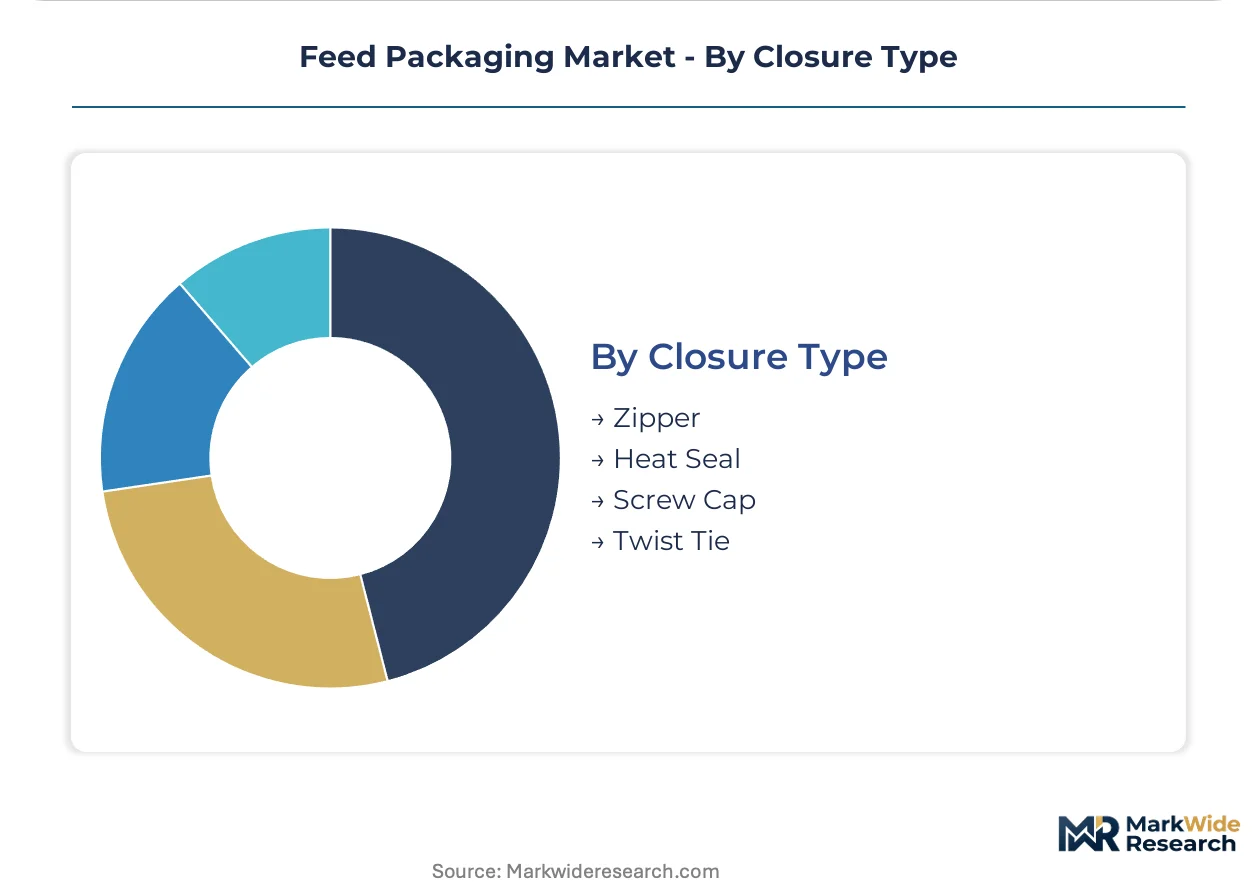
Closure Type:
Application maturity separates established heat-seal infrastructure from emerging resealable technologies, with zipper adoption concentrated in premium additive channels where dosing precision justifies incremental cost.
- Heat Seal:Dominant closure for bulk flexible bags, with water-based ink compatibility requirements under EPA volatile organic compound regulations forcing line reconfiguration at mid-tier US converters.
- Zipper:Press-to-close and slider mechanisms enable repeated access for specialty premixes, with digital printing convergence enabling lot-specific serialization for probiotic verification.
- Twist Tie:Lowest-cost closure for commodity grain and pelleted feed, with high-speed application compatibility sustaining volume despite limited resealability.
- Screw Cap:Rigid container standard for intermediate bulk formats, with tamper-evident features required for medicated feed regulatory compliance.
Heat seal closures anchor the volume base while zipper formats expand most quickly through premium additive channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging converters in Germany command pricing premiums exceeding Brazilian suppliers by double-digit margins, reflecting the cost burden of EU Green Deal compliance versus tropical-market specification requirements.
Brazil
Integrated protein producers in São Paulo state are expanding compound feed output and commissioning multi-layer barrier pouches for lipid-rich broiler formulations. ANVISA oversight of veterinary medicated feeds drives specification stringency for packaging contacting regulated products. Campinas industrial cluster hosts extrusion partnerships serving aquaculture feed producers upgrading from commodity polyethylene to ethylene vinyl alcohol barrier structures.
Germany
Dutch and Danish agricultural cooperatives source kraft paper-based solutions through German converters certified under EU sustainability frameworks. ECHA restrictions on phthalate plasticizers are accelerating adoption of bio-based polyesters and water-based ink systems. North Rhine-Westphalia packaging corridor anchors European supply for pelleted feed channels requiring breathability and moisture management balance.
United States
Midwest agricultural supply cooperatives are consolidating procurement rosters and extending contract durations for qualified packaging vendors. EPA volatile organic compound regulations are imposing capital burdens on mid-tier converters without water-based ink infrastructure. Iowa-Illinois corridor mergers have reduced active converter relationships by half over recent procurement cycles.
Vietnam
Shrimp feed producers in the Mekong Delta lack access to certified high-barrier structures, creating white space for localized extrusion partnerships. The country's national food safety regulator is aligning veterinary feed packaging standards with ASEAN harmonization protocols. Ho Chi Minh City industrial zone concentration is attracting flexible packaging investments targeting aquaculture export channels.
Norway
Salmon producers are specifying ethylene vinyl alcohol barrier structures to preserve omega-3 stability through extended cold-chain distribution cycles. REACH compliance migration is forcing material substitution across Nordic compound feed supply chains. Bergen-Stavanger packaging corridor serves North Sea aquaculture operations with oxygen transmission specifications below 0.5 cc/m²/day.
Feed Packaging Market Vendor Landscape
Integrated multinational converters and regional flexible packaging specialists split the market between premium barrier specification channels and commodity bulk grain applications. The vendor base concentrates around three strategic archetypes: global film extrusion networks supplying high-barrier structures, kraft paper-based solution providers certified under EU sustainability frameworks, and localized flexible packaging lines tailored to tropical storage conditions. Dominant competitive moves include geographic expansion through extrusion asset partnerships and portfolio diversification into digital printing convergence with track-and-trace serialization capabilities.
Within the integrated multinational tier, Amcor plc and Mondi Group occupy positions reflecting distinct material technology anchors. Amcor leverages global film extrusion network coverage to serve aquaculture feed producers requiring oxygen barrier performance. Mondi anchors European demand through paper-based solutions aligned with circular economy frameworks. Huhtamaki Oyj exemplifies the emerging-market specialization archetype, with localized production positioning targeting tropical storage performance requirements in Southeast Asian protein production corridors.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi Group |
| Huhtamaki Oyj |
| ProAmpac |
| LC Packaging |
| El Dorado Packaging |
| Sonoco Products Company |
| Winpak Ltd. |
| Berry Global |
| Others |
Supply Flow & Price Mechanics
The Campinas industrial cluster in São Paulo state anchors South American extrusion capacity for multi-layer barrier films, with its output concentration granting converters leverage over integrated protein producers during peak poultry feed procurement cycles. Brazilian converters command premium positioning against Southeast Asian suppliers due to ANVISA certification requirements and tropical storage performance specifications that commodity producers cannot match.
Pricing Analysis
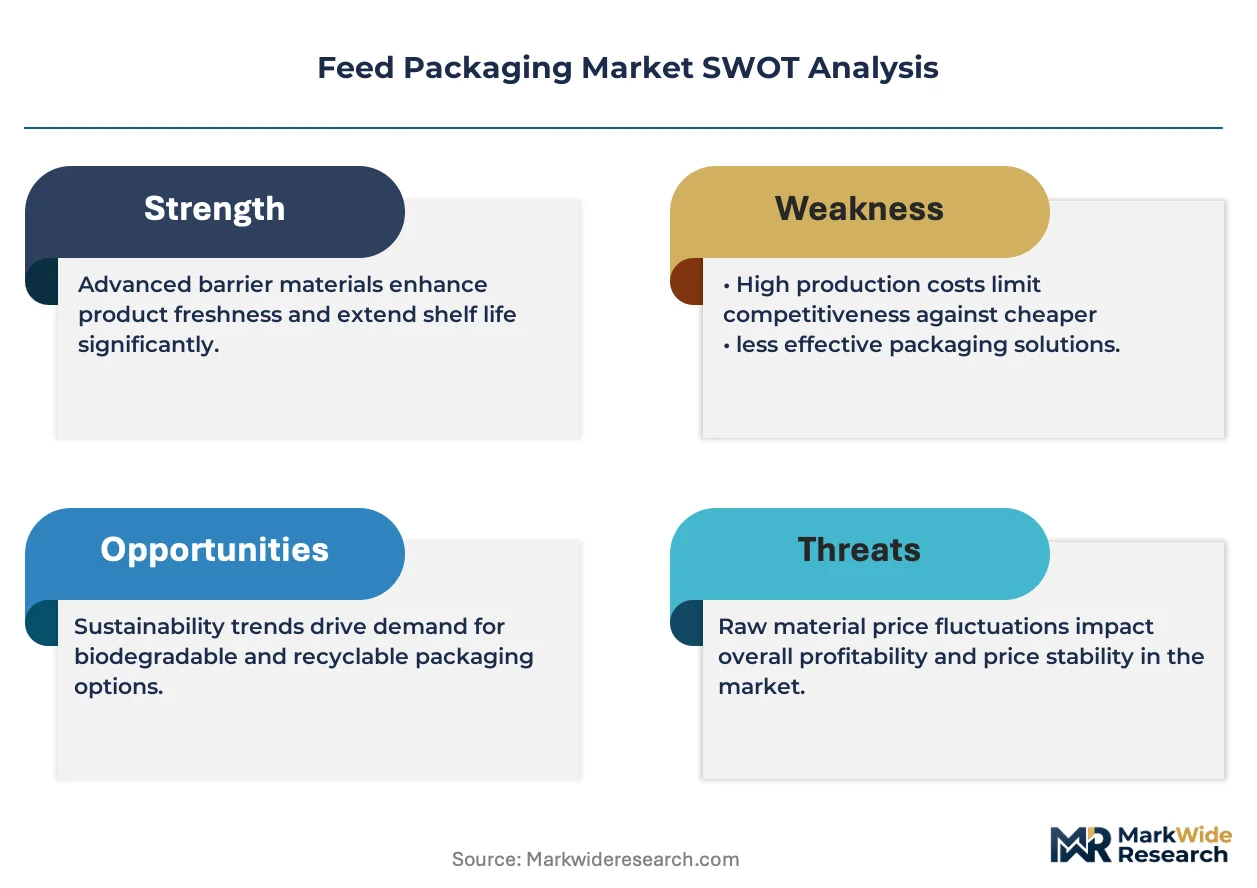
Configured-to-order pricing for EVOH-barrier pouches runs 35-50% above standard polyethylene bag rates, with the spread widening where REACH-compliant bio-based polyesters replace phthalate plasticizers. Three-tier pricing structure across premium barrier, standard multi-layer, and economy polyethylene levels reflects oxygen transmission performance and certification grade. Pricing pressure stems from EU Green Deal recycled content mandates forcing reformulation investments without corresponding buyer willingness to absorb cost pass-through. Agricultural supply cooperatives exhibit highest price sensitivity due to consolidated procurement rosters and thin margin structures, while Norwegian aquaculture producers show lowest sensitivity given omega-3 stability requirements.
Supply Chain Analysis
Contract manufacturing concentration rests with Amcor plc's global film extrusion network, Mondi Group's European kraft paper operations, and Huhtamaki Oyj's localized Southeast Asian lines. Geographic supply concentration draws from Germany, Brazil, and Vietnam as primary extrusion hubs. Raw material dependencies hinge on ethylene vinyl alcohol barrier resins from Japan and South Korea, polyethylene feedstocks from Gulf Coast petrochemical complexes, and kraft pulp from Nordic forestry operations. Single-source vulnerability in EVOH resin supply creates disruption risk for European and Latin American converters lacking backward integration into polymer production. Distribution runs through agricultural cooperative procurement channels in North America, integrated protein producer direct contracts in Brazil, and aquaculture feed specialist networks in Norway and Chile.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The feed packaging market is recovering from a cyclical trough driven by poultry feed volume expansion in Brazil and Thailand, with integrated protein producers resuming specification upgrades deferred during margin compression periods.
For Market Incumbents: Insulate barrier technology positions by securing captive EVOH resin supply through long-term offtake agreements with Japanese and South Korean producers, eliminating exposure to supply concentration risk. Extend sustainability certification moats through EU Green Deal compliance investments that mid-tier converters cannot replicate, particularly water-based ink infrastructure and mechanical recycling stream integration. Prioritize capacity addition in Vietnam's Ho Chi Minh City industrial zone to capture shrimp feed packaging upgrade demand before localized competitors establish extrusion partnerships.
For New Entrants and Emerging Players: The Mekong Delta's certified high-barrier supply gap offers immediate white-space access for extrusion partnerships targeting Vietnamese aquaculture export channels. Digital printing convergence with GS1-compliant serialization represents a penetrable premium additive segment where incumbent asset bases lack inkjet variable data integration. A go-to-market angle anchored to probiotic additive verification protocols bypasses direct competition with established bulk grain suppliers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial packaging parents with underoptimized feed-specific assets lacking barrier technology depth or sustainability certification positioning. Long-term viability over a five-to-ten year window favors converters with demonstrated EU regulatory compliance migration capability and established relationships with consolidating agricultural cooperatives. Monitor extended producer responsibility framework implementations across EU member states as the inflection signal determining cost allocation winners between packaging manufacturers and protein integrators.
| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Technology Partnership | EVOH supply agreements with Japanese resin producers secure oxygen transmission performance below 0.5 cc/m²/day for aquaculture formulations. |
| Water-Based Ink Infrastructure | EPA VOC compliance investments displace solvent-dependent mid-tier US converters from agricultural cooperative supply rosters. |
| Mechanical Recycling Integration | Post-industrial film scrap incorporation meets EU Green Deal thresholds without compromising weld strength for pelleted feed bags. |
| Digital Printing Convergence | GS1-compliant serialization enables lot-specific probiotic verification for premium premix channels demanding traceability. |
| Localized Extrusion Partnership | Vietnamese asset deployment captures shrimp feed packaging upgrade demand in the Mekong Delta before incumbent regionalization. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from packaging converters, EU regulatory impact assessments, and agricultural cooperative procurement disclosures. Primary interviews engaged plant managers at extrusion facilities, procurement leads at Brazilian integrated protein producers, regulatory affairs specialists navigating ECHA compliance, and distribution channel partners serving North American grain cooperatives. Bottom-up volume estimates derived from compound feed production statistics triangulate against top-down packaging spend analysis from protein integrator financial disclosures.
Forecast inputs incorporate material substitution rates under REACH phthalate restrictions, poultry feed volume trajectories from Brazilian and Thai operations, and aquaculture premiumization adoption curves in Norway and Chile. Segmentation dimensions modeled span product type, material composition, end-user category, and closure mechanism across the projection horizon. CAGRs were derived from regression analysis of historical packaging intensity ratios against feed production volumes, with adjustments for regulatory-driven specification upgrades and sustainability certification penetration.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian resin producers or accelerated EU packaging waste cost allocation would shift outcomes beyond modeled ranges. Quarterly review of EVOH resin pricing spreads, agricultural cooperative merger activity, and ANVISA veterinary feed packaging standard updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging
Indonesia Plastic Food Tray Market
Packaging
MENA Thermoform Plastic Packaging Market
Packaging
Bagasse Bowls Market
Packaging
Blister Packaging Equipment Market
Packaging
Egg Packaging Market
Packaging
Pharmaceutical Plastic Bottles Market
Packaging
Direct Thermal Printing Films Market
Packaging
Medical Implants Sterile Packaging Market
Packaging
Old Corrugated Containers (OCC) Market
Packaging
Thermal Insulated Bubble Wrap Market
Packaging
Coding and Marking Systems Market
Packaging
India Pouch Packaging Market
Packaging
Protective Wrapping Paper Market
Packaging
Corrugated Wraps Market
Packaging
Healthcare and Laboratory Labels Market
Packaging
Isotropic Film Market