
 Fast-Food Reusable Market | 2026-2036
Fast-Food Reusable Market Size, Share, and Industry Trends Forecast 2026-2036
Fast-Food Reusable Market Foresight
European food packaging manufacturers is consolidating around circular production models for quick-service chains. Amcor leverages its film-to-film recycling infrastructure to supply closed-loop container systems for major burger chains. Huhtamaki anchors Nordic markets through fiber-based reusable bowl platforms integrated with restaurant logistics. Loop Industries specializes in chemically recycled PET engineered for hundreds of wash cycles in commercial dishwashing environments.
Fast-food reusable packaging denotes container systems designed for minimum fifty use cycles, typically manufactured from food-grade silicone, stainless steel, or tempered borosilicate glass with leak-proof sealing mechanisms and standardized dimensions for automated washing. These systems replace single-use items across dine-in, takeaway, and delivery formats in quick-service and fast-casual food operations. Containers lead material deployment due to higher unit economics and brand visibility, while metal straws occupy premium positioning through durability claims. Silicone bags represent the fastest-expanding category as cold-chain delivery formats multiply across third-party platforms.
The EU Single-Use Plastics Directive and REACH chemical standards jointly mandate migration testing for reusable food contact materials, compelling suppliers to certify alternative polymers. FDA food contact notification requirements in the United States impose parallel compliance burdens for imported silicone and stainless steel systems. Stakeholders must monitor evolving extended producer responsibility schemes across jurisdictions to anticipate deposit infrastructure investments and packaging-as-a-service model viability.
Market Dynamics
Deposit-return infrastructure for food-contact containers is restructuring capital allocation across quick-service supply chains, compelling suppliers to integrate reverse logistics capabilities alongside forward manufacturing.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory reduction targets for disposable foodware accelerate silicone and stainless steel substitution across member states.
- Third-party delivery platforms:Cold-chain logistics expansion creates pull for leak-proof silicone bag systems rated for fifty-plus wash cycles.
- German municipal composting networks:Dense collection infrastructure validates reusable container economics through standardized deposit schemes.
Market Restraints
- Food-grade silicone feedstock volatility:Petrochemical-derived precursors expose margins to polymer price swings without long-term supply contracts.
- Commercial dishwasher certification bottlenecks:NSF International testing protocols create twelve-to-eighteen month approval timelines for new container geometries.
- Stainless steel import tariffs:Section 232 duties in the United States elevate landed costs for Asian-origin metal systems.
Strategic Opportunities
- Untapped French provincial markets:Paris-adjacent deposit schemes remain unextended to secondary cities, creating first-mover whitespace.
- RFID-integrated inventory tracking:Convergence of polymer molding with embedded sensor technology enables real-time container fleet management.
- United Kingdom extended producer responsibility:Pending packaging waste regulations will mandate producer-funded collection infrastructure.
Industry Challenges
- Polymer migration testing expertise:REACH-compliant food contact certification requires scarce analytical chemistry talent.
- Legacy POS integration:Deposit tracking demands API connectivity with restaurant payment systems lacking standardized protocols.
- Cross-contamination protocols:Allergen-specific washing procedures complicate multi-brand container pooling arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fast-Food Reusable Market |
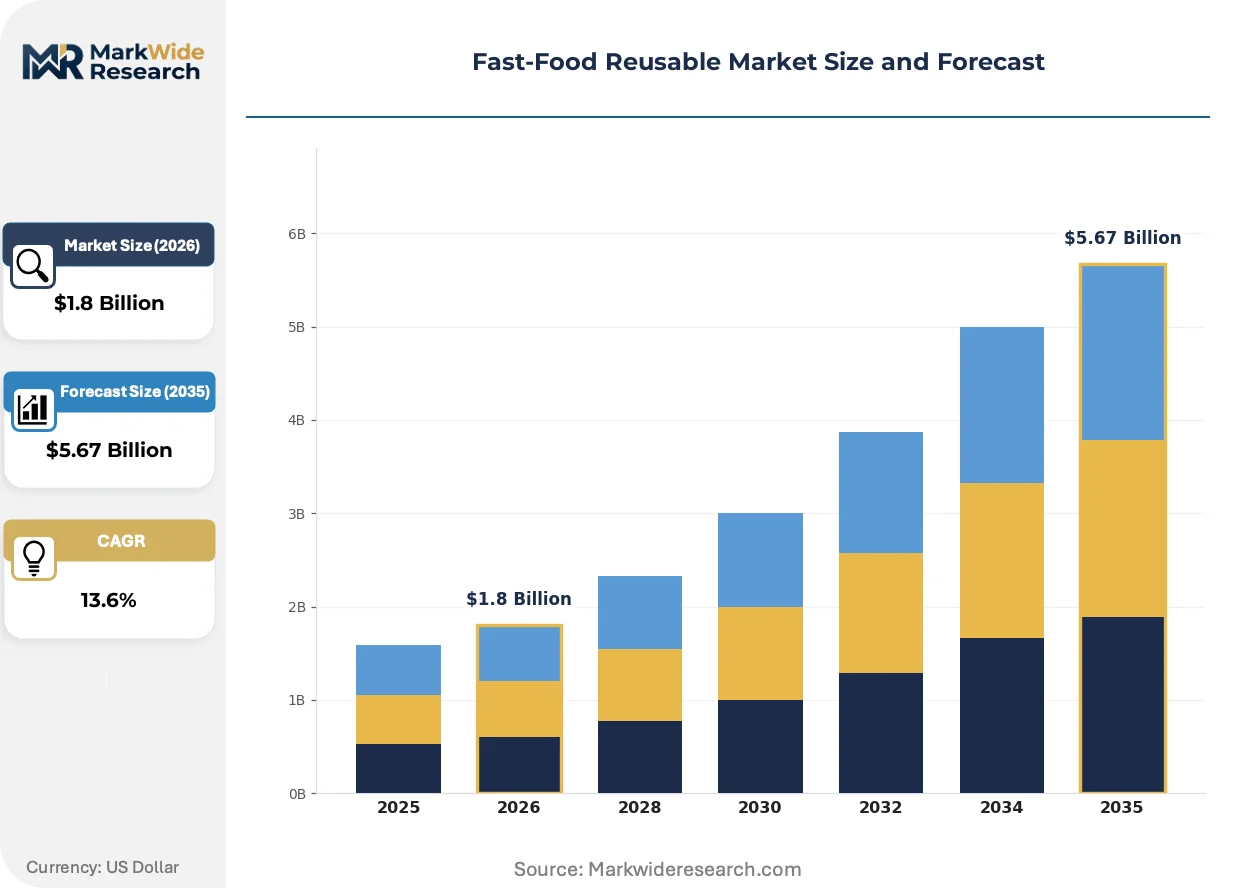
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.67 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Containers, Cutlery, Straws Material: Plastic, Silicone, Glass, Metal End User: Restaurants, Cafés, Food Trucks, Catering Services Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Tetra Pak, Amcor, Huhtamaki, DS Smith, Sealed Air, Eco-Products, Loop Industries, Ball Corporation, TerraCycle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fast-Food Reusable Market Shifts & Advancements
Smart material engineering and regulatory chemistry standards are redefining durability benchmarks for food-contact reusables, compressing replacement cycles while elevating performance verification requirements.
Tempered borosilicate glass with molded silicone sealing rings is converging with automated high-temperature washing systems to enable container reuse exceeding two hundred cycles in quick-service environments. Burger chains in Germany and France are piloting these hybrid systems for dine-in formats. This convergence is compressing total cost of ownership calculations against single-use alternatives.
REACH chemical standards now mandate exhaustive migration testing for silicone oligomers and metal ion leaching in reusable food contact materials. ECHA enforcement has compelled suppliers to reformulate polymer catalysts and document batch-level compliance. Stainless steel systems face the steepest retesting burden, with Nordic markets demanding supplemental nickel release documentation.
Restaurant procurement is fragmenting toward packaging-as-a-service contracts that bundle container supply, washing logistics, and deposit management under per-use fees. Third-party platform aggregators are displacing direct supplier relationships for mid-size fast-casual chains. This shift concentrates contract value in Germany, where municipal washing cooperatives already operate at scale.
Fast-Food Reusable Market Segmentation
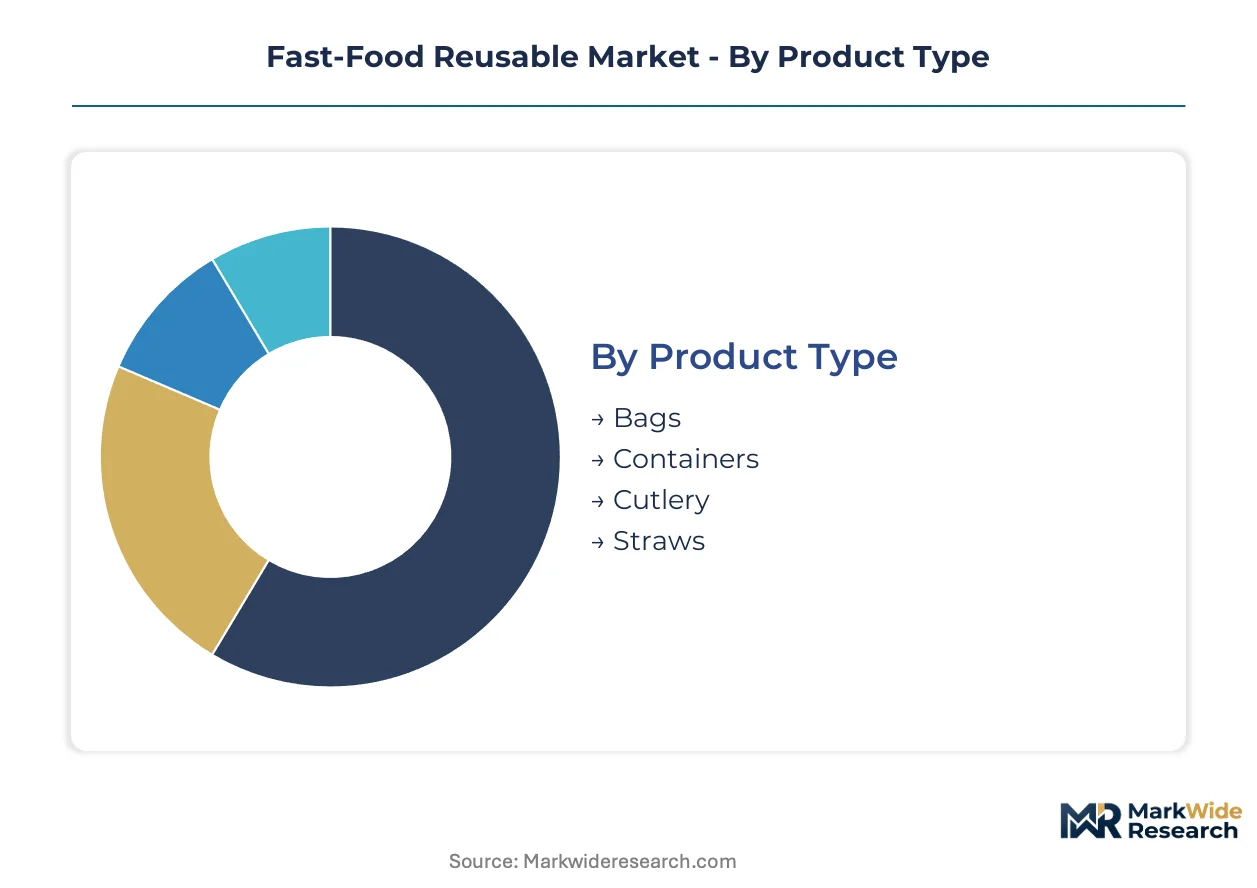
Segmentation in the fast-food reusable market reveals how deposit-return logistics and washing infrastructure reshape procurement patterns across container formats and supply channels. Distinct material-performance tiers and end-use operational models determine contract structures and fleet management economics.
Product Type:
Standalone container systems dominate capital deployment, while embedded cutlery and straw programs operate as compliance-driven add-ons within broader packaging contracts.
- Containers:Engineered from food-grade silicone, stainless steel, or tempered borosilicate glass with standardized dimensions for automated commercial washing. Burger chains in Germany and France pilot hybrid glass-silicone systems exceeding two hundred use cycles, driven by EU Single-Use Plastics Directive reduction mandates and visible brand placement at dine-in formats.
- Bags:Leak-proof silicone constructions rated for fifty-plus wash cycles, optimized for cold-chain third-party delivery logistics. Third-party platform expansion across Nordic markets pulls demand for these systems as delivery format standardization accelerates.
- Cutlery:Stainless steel and bamboo-fiber composite utensils distributed through deposit-return schemes at quick-service salad chains. Municipal washing cooperative integration in German cities validates per-use fee economics.
- Straws:Metal and silicone alternatives occupying premium positioning through durability claims, though unit economics lag container systems due to lower replacement frequency and theft rates.
Containers lead volumes today; bags are gaining share fastest.
Material:
Cost tier stratification separates petrochemical-derived feedstocks from engineered polymers and mineral-based alternatives, with certification burden concentrated in metal and silicone categories.
- Silicone:Platinum-cured food-grade formulations dominating cold-chain delivery applications due to temperature resilience and leak-proof molding. REACH migration testing requirements for silicone oligomers impose batch-level documentation burdens that favor suppliers with in-house analytical chemistry capabilities.
- Metal:304 and 316 stainless steel systems facing steepest regulatory retesting under ECHA enforcement, with Nordic markets demanding supplemental nickel release documentation. Section 232 tariffs in the United States elevate landed costs for Asian-origin supply.
- Glass:Tempered borosilicate with molded silicone sealing rings converging with high-temperature automated washing. German and French dine-in pilots validate total cost of ownership compression against single-use alternatives.
- Plastic:Chemically recycled PET engineered for commercial dishwashing environments, though consumer perception challenges limit quick-service brand adoption relative to silicone and metal visibility.
Silicone leads volumes today; glass is gaining share fastest.
End User:
Operational scale and deposit infrastructure access determine contract structure, with municipal washing network proximity differentiating urban restaurant economics from mobile foodservice constraints.
- Restaurants:Quick-service chains with direct supplier relationships or packaging-as-a-service contracts bundling container supply, washing logistics, and deposit management. German municipal washing cooperatives concentrate contract value for mid-size fast-casual operators.
- Cafés:Smaller-format operators relying on third-party platform aggregators for container fleet management, with API connectivity challenges to legacy POS systems constraining deposit tracking integration.
- Food Trucks:Mobile operators facing reverse logistics constraints due to dispersed operating locations and limited washing infrastructure access, compressing reusable adoption to high-frequency urban routes.
- Catering Services:Event-based demand with concentrated return windows, enabling batch washing economics but requiring allergen-specific protocols that complicate multi-brand container pooling arrangements.
Restaurants lead volumes today; cafés are gaining share fastest.
Distribution Channel:
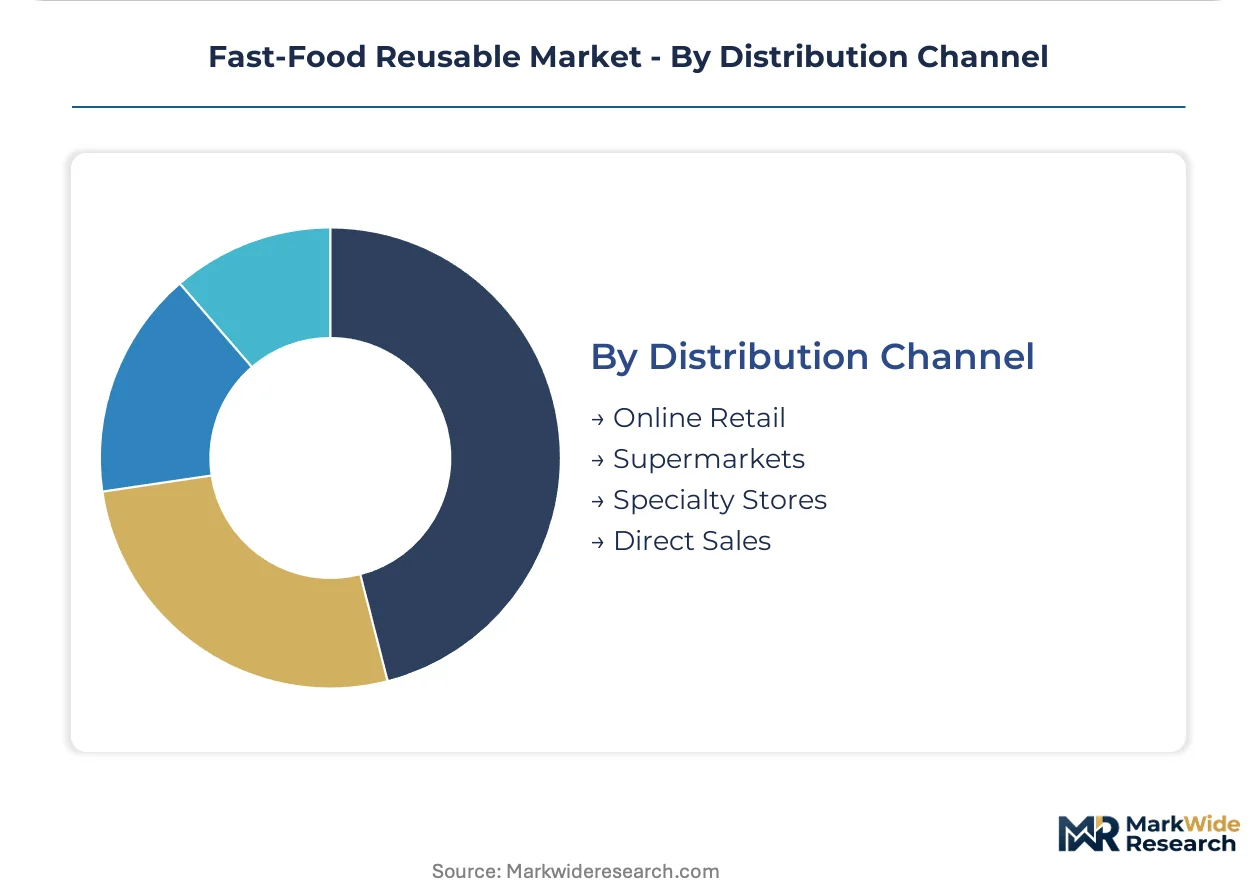
Customer type and order scale reshape channel mix, with direct sales concentrating among large chains and specialty stores capturing compliance-driven independent operator demand.
- Direct Sales:Packaging-as-a-service contracts displacing traditional procurement for quick-service chains, with per-use fee structures bundling supply, logistics, and deposit management. Third-party platform aggregators intermediate for mid-size operators lacking internal fleet management capabilities.
- Specialty Stores:Independent restaurant and café operators sourcing certified container systems with REACH-compliant documentation, serving compliance-driven demand in French and UK markets ahead of extended producer responsibility implementation.
- Online Retail:Small-format operators and pilot programs accessing standardized container geometries with NSF International pre-certification, though commercial dishwasher approval timelines create twelve-to-eighteen month bottlenecks for new geometries.
- Supermarkets:Limited penetration due to mismatch between retail packaging formats and commercial washing system specifications, with occasional presence in home-use crossover segments rather than foodservice-grade supply.
Direct sales lead volumes today; specialty stores are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as suppliers migrate toward jurisdictions with established deposit infrastructure and lower compliance-certification costs. France and Germany offer template-ready washing cooperative networks that compress per-unit economics for reusable container systems. The United States presents fragmented adoption due to municipal-level policy variation and dishwasher certification bottlenecks.
Germany
Municipal washing cooperatives in Berlin, Hamburg, and Munich validate packaging-as-a-service economics through standardized deposit schemes. The EU Single-Use Plastics Directive mandates reduction targets that accelerate silicone and stainless steel substitution across quick-service chains. Bavaria's dense logistics infrastructure supports reverse logistics pilots for burger chains exceeding two hundred use cycles per container.
France
Paris-adjacent deposit schemes create first-mover whitespace as provincial cities await infrastructure extension. ANSM enforces REACH-compliant migration testing for silicone oligomers, compelling batch-level documentation from suppliers. The Île-de-France region concentrates pilot programs for tempered borosilicate glass systems with molded silicone sealing rings.
United Kingdom
Pending extended producer responsibility regulations will mandate producer-funded collection infrastructure across England, Scotland, and Wales. The Environment Agency coordinates with municipal networks to standardize washing protocols. Greater London hosts third-party platform aggregators that intermediate container fleet management for mid-size fast-casual operators.
United States
FDA food contact notification requirements impose twelve-to-eighteen month approval timelines for imported silicone and stainless steel systems. Section 232 tariffs elevate landed costs for Asian-origin metal containers. California and New York lead state-level deposit legislation, while Texas and Florida markets lag due to limited municipal washing infrastructure.
Netherlands
The Randstad urban corridor integrates RFID-embedded container tracking with automated high-temperature washing systems. Dutch municipal networks supply template logistics for cross-border expansion into Belgium and Luxembourg. Eindhoven-region polymer molders specialize in platinum-cured silicone formulations for cold-chain delivery applications.
Fast-Food Reusable Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue packaging-as-a-service contracts and embedded sensor integration. Market structure concentrates around three capability clusters: film-to-film recycling infrastructure, fiber-based logistics platforms, and chemically recycled PET engineering. Strategic archetypes include closed-loop system integrators, municipal washing cooperative partners, and cold-chain delivery specialists. Competitive moves center on reverse logistics capability acquisition and per-use fee contract structuring.
Within the packaging-as-a-service tier, Loop Industries and TerraCycle exemplify circular production models for quick-service chains. Amcor anchors film-to-film recycling infrastructure for closed-loop container supply. Huhtamaki occupies a position among Nordic-market fiber-based platform providers integrated with restaurant logistics. These three companies represent distinct archetypes: chemical recycling engineering, reverse logistics aggregation, and regional cooperative partnership.
| Leading Market Players |
|---|
| Tetra Pak |
| Amcor |
| Huhtamaki |
| DS Smith |
| Sealed Air |
| Eco-Products |
| Loop Industries |
| Ball Corporation |
| TerraCycle |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between REACH-compliant silicone systems and uncertified commodity alternatives splits pricing power across the fast-food reusable container market, with premium tiers commanding margin protection through batch-level migration documentation while economy suppliers compete on raw polymer cost. This bifurcation concentrates supply chain investment in Germany and the Netherlands, where analytical chemistry capabilities support regulatory documentation, while Asian-origin metal systems face tariff-adjusted pricing pressure.
Pricing Analysis
Distributor margins for packaging-as-a-service contracts absorb the steepest compression as third-party platform aggregators intermediate fleet management for mid-size fast-casual chains. Three-tier pricing structure across premium, standard, and economy levels separates platinum-cured silicone with full REACH documentation from industrial-grade alternatives and uncertified imports. Cost compression in the metal tier intensifies because Section 232 tariffs elevate landed costs for Asian-origin stainless steel systems. Quick-service chains with direct supplier relationships exhibit the lowest price sensitivity, while independent cafés relying on specialty store procurement face acute margin pressure.
Supply Chain Analysis
Dual-sourcing requirements for food-grade silicone precursors compel quick-service chains to qualify both German and Dutch polymer molders alongside Asian suppliers, mitigating petrochemical feedstock volatility. Geographic supply concentration centers on Germany, the Netherlands, and China, with Eindhoven-region specialists anchoring platinum-cured formulation capacity. Raw material dependencies rest on petrochemical-derived siloxane monomers, platinum catalysts, and 304/316 stainless steel feedstock. Single-source vulnerability in NSF International certification capacity creates twelve-to-eighteen month bottlenecks for new container geometries. Distribution runs through direct packaging-as-a-service contracts, specialty stores serving compliance-driven independents, and third-party platform aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate where EU REACH compliance costs in France and Germany diverge from pending UK extended producer responsibility implementation timelines, rewarding early infrastructure positioning ahead of regulatory harmonization.
For Market Incumbents: Anticipate displacement risk from packaging-as-a-service aggregators by securing exclusive municipal washing cooperative partnerships in German cities before provincial French markets extend deposit infrastructure. Prioritize backward integration into platinum-cured silicone formulation capacity to capture margin currently lost to Dutch polymer specialists. Certification investment in supplemental nickel release documentation for Nordic markets defends position against lower-cost Asian metal competitors facing retesting burdens. For New Entrants and Emerging Players: French provincial cities beyond Paris-adjacent deposit schemes represent the most penetrable whitespace, with ANSM enforcement creating compliance-driven demand for REACH-documented container systems ahead of infrastructure extension. Food trucks operating high-frequency urban routes in London and Berlin offer a concentrated pilot segment with batch return economics. Go-to-market execution should anchor on API connectivity solutions for legacy POS deposit tracking, addressing the integration bottleneck constraining café adoption. For Investors and Strategic Acquirers: Consolidation pressure builds where municipal washing cooperative scale advantages concentrate contract value in Germany, squeezing mid-size operators lacking reverse logistics capabilities. Long-term viability over the next decade hinges on embedded sensor technology convergence with polymer molding, enabling real-time fleet management differentiation. Acquisition targets should screen for in-house analytical chemistry capabilities supporting REACH batch documentation. The signal to watch is UK extended producer responsibility implementation pace, which will mandate producer-funded collection infrastructure and reshape competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| Reverse Logistics Capability Acquisition | Municipal washing cooperative partnerships in Berlin and Hamburg compress per-use economics below single-use alternatives. |
| RFID-Embedded Container Development | Convergence with automated high-temperature washing systems enables real-time fleet tracking for third-party delivery platforms. |
| REACH-Compliant Silicone Formulation Investment | In-house analytical chemistry capabilities support batch-level migration documentation demanded by ECHA enforcement. |
| Provincial French Market Expansion | First-mover positioning ahead of deposit scheme extension captures compliance-driven demand from independent operators. |
| API Connectivity Platform Launch | Legacy POS integration solutions address deposit tracking bottlenecks constraining café and food truck adoption. |
Research Methodology
Direct dialogue with quick-service procurement directors, municipal washing cooperative managers, silicone polymer chemists, and third-party delivery platform aggregators grounded qualitative assessment, cross-referenced with EU Single-Use Plastics Directive implementation tracking, ECHA migration testing protocol documentation, FDA food contact notification filings, and German municipal deposit scheme operational data. Bottom-up container fleet economics modeling and top-down regulatory impact assessment were triangulated against secondary trade data and customs records.
Bottom-up volume builds aggregated per-use fee contract values across packaging-as-a-service tiers, while top-down analysis calibrated regulatory mandate penetration rates across EU member states. Segmentation dimensions spanned product type, material grade, end-user operational scale, and distribution channel structure, with additional granularity on municipal washing infrastructure proximity. CAGRs were derived from logistic curve fitting to deposit scheme adoption patterns, with inputs including cold-chain delivery format expansion rates and commercial dishwasher certification pipeline capacity.
Underlying measurement precision varies by segment; German municipal cooperative markets carry tighter precision than emerging provincial French pilots due to operational data availability. Forecasts reflect assumptions around REACH enforcement consistency and UK extended producer responsibility implementation timing, with revision risk from petrochemical feedstock price volatility and tariff policy shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Processed Fruit Bases Market
Processed Foods
Yogurt Dip Market
Processed Foods
Low Calorie Rice Pudding Market
Processed Foods
Potato Soup Market
Processed Foods
Mashed Potatoes Market
Processed Foods
North America Ice Cream Market
Processed Foods
Global Dried Processed Food Market
Processed Foods
Soup & Broth Market
Processed Foods
Middle East and Africa Processed Meat Market
Processed Foods
Butter Crisco Market
Processed Foods
Egg Powder Market
Processed Foods
Instant Curry Market
Processed Foods
Apple Butter Market
Processed Foods
Europe Egg Powder Market
Processed Foods
Instant Cooking Food Market
Processed Foods
Ready to Cook Market