
 Europe Private Equity Market | 2026-2036
Europe Private Equity Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Private Equity Market Analysis
Healthcare services is decoupling from traditional industrial buyouts as the dominant deployment target across European funds. Ardian leverages its infrastructure-to-healthcare crossover platform to capture specialized deal flow. Permira sustains its technology franchise through concentrated software and fintech positions. CVC Capital Partners anchors its European presence with dominant consumer and financial services portfolios.
Private equity denotes negotiated investments in non-publicly traded companies through structured vehicles holding equity or hybrid securities, typically employing leverage ratios of three to six times EBITDA and holding periods of four to seven years to engineer operational improvements and financial restructuring before exit. Growth capital and buyout strategies command the deepest capital pools, with venture capital segments showing accelerated deployment velocity. Mega funds and large cap vehicles concentrate fee generation, while mid cap specialists occupy the most competitive bidding terrain for founder-owned businesses.
EU Green Deal taxonomy requirements, CSRD sustainability disclosures, and ESG-related fiduciary standards from national regulators in Germany and France are elevating environmental due diligence to a deal-breaker threshold. The European Securities and Markets Authority sharpens transparency mandates for fund marketing and investor reporting across the bloc. Stakeholders must monitor how regulatory fragmentation between EU-level directives and member state implementation timelines affects cross-border fundraising efficiency and portfolio compliance costs.
Market Dynamics
The EU Green Deal and CSRD disclosure rules are compressing due diligence timelines while elevating ESG compliance to a deal-breaker threshold, forcing sponsors to restructure portfolio company operations before exit windows materialize.
Growth Catalysts
- CSRD Mandates:The Corporate Sustainability Reporting Directive requires granular emissions disclosures across portfolio companies. Sponsors with integrated ESG data infrastructure capture premium valuations from institutional limited partners prioritizing Article 8 and Article 9 fund classifications.
- Germany:Industrial Mittelstand owners face succession crunches without family heirs. Founder-owned manufacturers in Baden-Württemberg and Bavaria generate concentrated deal flow for mid-cap buyout specialists with operational improvement capabilities.
- Healthcare Technology:Digital health platforms and clinical workflow software attract capital reallocation from traditional industrial targets. Telemedicine infrastructure and patient data analytics command premium multiples versus legacy healthcare services.
Market Restraints
- Interest Rate Compression:ECB policy rates above pre-2022 levels constrain leverage availability. Debt-dependent buyout structures face reduced headroom for value creation through financial engineering rather than operational transformation.
- Nordic Banking Concentration:Regional lenders dominate acquisition financing for Scandinavian targets. Sponsor dependence on Stockholm and Copenhagen-based credit committees creates pricing asymmetry and covenant rigidity during volatile periods.
- Valuation-Entry Tension:Auction processes for quality assets in France and Germany push entry multiples to levels where traditional holding-period returns require aggressive EBITDA expansion assumptions.
Strategic Opportunities
- Nordic Corridor:Denmark, Sweden, and Norway host specialized technology subsectors with limited local capital depth. Software and life sciences ventures in Copenhagen and Stockholm clusters offer underexploited growth equity deployment potential.
- EU AI Act:Compliance requirements for high-risk AI applications create advisory and implementation service demand. Portfolio companies with regulatory technology capabilities capture recurring revenue from enterprises navigating conformity assessment obligations.
- Secondaries Market:Limited partner portfolio rebalancing generates GP-led continuation vehicle and LP stake sale volume. Specialists in tail-end fund restructuring access liquidity solutions for aging European buyout vintages.
Industry Challenges
- ESG Data Integration:Portfolio companies lack standardized carbon accounting systems. Sponsors must build internal capabilities or acquire specialized providers to meet CSRD-aligned investor reporting demands across multi-jurisdictional holdings.
- Cross-Border Regulatory Friction:Member state implementation timelines for EU directives create compliance complexity. Funds operating across German, French, and Nordic jurisdictions navigate divergent national interpretations of fiduciary ESG standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Private Equity Market |
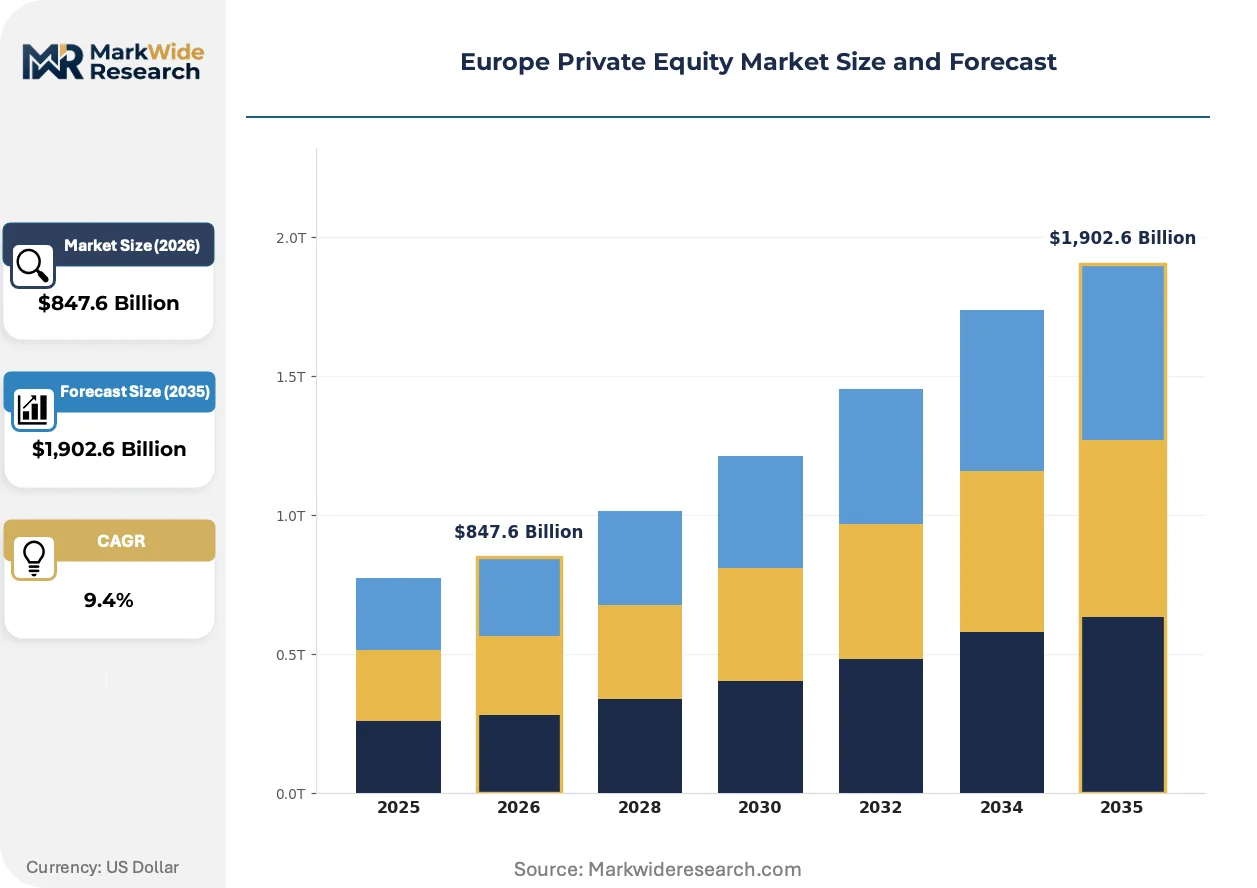
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $1,902.6 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Strategy: Growth Capital, Buyouts, Venture Capital, Mezzanine Fund Size: Small Cap, Mid Cap, Large Cap, Mega Fund Industry Vertical: Technology, Healthcare, Consumer Goods, Financial Services Investor Type: Institutional Investors, High Net Worth Individuals, Family Offices, Funds of Funds |
| Companies Covered | Permira, Ardian, CVC Capital Partners, Advent International, TPG, KKR, Apax Partners, Warburg Pincus, EQT, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Private Equity Market Emerging Trajectories
Technology-enabled operational value creation is displacing financial engineering as the primary return driver, while regulatory technology and sustainability data infrastructure emerge as distinct investment themes.
Artificial intelligence-driven due diligence platforms are electrifying transaction execution timelines. Mid-cap sponsors in France and Germany deploy natural language processing tools to analyze regulatory filings and contract databases. Automated risk identification compresses preliminary assessment phases from weeks to days, reallocating senior partner attention toward relationship-intensive sourcing and portfolio transformation.
The EU AI Act establishes conformity requirements for automated decision systems in financial services and healthcare applications. Private equity-backed software vendors must embed algorithmic audit trails and human oversight mechanisms into product architectures. German and French portfolio companies in credit scoring and diagnostic imaging face accelerated compliance investment to maintain market access.
Institutional limited partners now mandate sustainability-linked capital commitments with verified impact metrics. Danish and Swedish pension funds condition allocations on granular Scope 3 emissions tracking across underlying holdings. Sponsors respond by embedding ESG operating partners into portfolio company boards and linking management incentives to CSRD-aligned KPI disclosure.
Europe Private Equity Market Segmentation
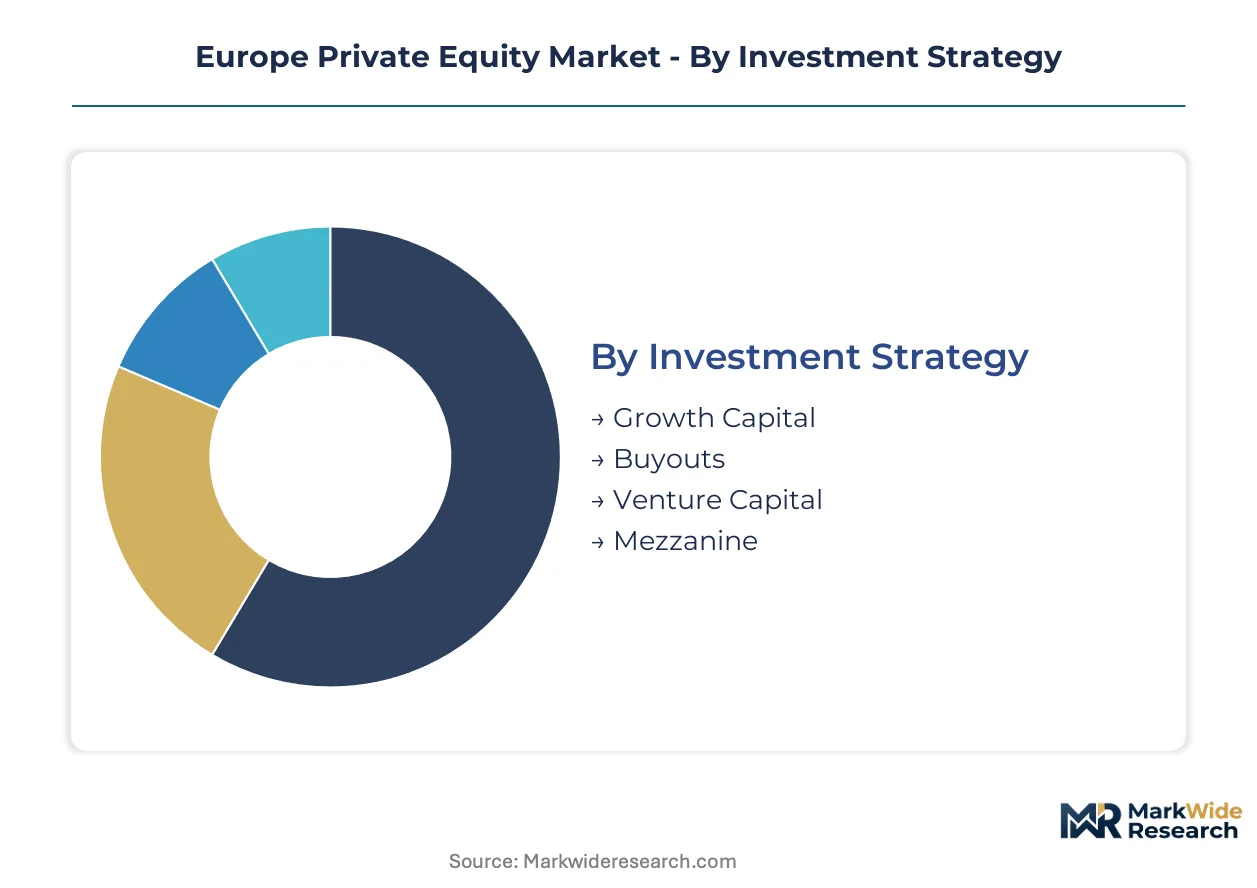
Investment strategy segmentation determines capital deployment velocity and risk-return profiles across European private equity. Fund size categories dictate fee structures and competitive positioning in auction processes. Industry vertical and investor type dimensions shape due diligence protocols and LP reporting requirements under CSRD mandates.
Investment Strategy:
Standardization dominates growth capital and buyouts with templated due diligence playbooks, while venture capital and mezzanine demand bespoke structuring expertise.
- Buyouts:Majority or full control acquisitions of mature companies using leverage ratios of three to six times EBITDA. German Mittelstand manufacturers in Baden-Württemberg and Bavaria generate concentrated deal flow as founder succession crunches accelerate.
- Growth Capital:Minority investments in expansion-stage companies without full control premiums. Nordic software clusters in Copenhagen and Stockholm attract deployment as local capital depth remains thin relative to opportunity quality.
- Venture Capital:Early-stage equity in unproven business models with higher failure rates. Deep tech and life sciences ventures in France and Germany command specialized GP expertise.
- Mezzanine:Subordinated debt with equity participation features filling capital structure gaps. Mid-cap buyouts in fragmented sectors deploy mezzanine to optimize senior lender relationships.
Most installed capacity flows through Buyouts. Expansion is steepest in Growth Capital.
Fund Size:
Fee generation concentrates in mega funds and large cap vehicles, while competitive intensity peaks in mid cap segments serving founder-owned businesses.
- Mega Fund:Vehicles raising capital commitments exceeding five billion euros. Institutional LPs in Denmark and Sweden prioritize these for core private equity allocations with streamlined due diligence.
- Large Cap:Funds targeting billion-euro plus commitments with diversified sector coverage. Technology buyouts in France and Germany dominate deployment as multiples compress auction dynamics.
- Mid Cap:Specialists in five hundred million to one billion euro ranges. German industrial Mittelstand auctions attract the most competitive bidding terrain across Europe.
- Small Cap:Sub-five hundred million euro vehicles focusing on regional or niche opportunities. Operational improvement capabilities differentiate winners in fragmented local markets.
Fee income pools heaviest in Mega Fund structures. Capital formation is climbing fastest in Mid Cap vehicles.
Industry Vertical:
Technology and healthcare command premium entry multiples with standardized valuation frameworks, while consumer goods and financial services retain more bespoke diligence requirements.
- Technology:Software, fintech, and regulatory technology platforms. EU AI Act compliance requirements for high-risk applications create recurring revenue opportunities for portfolio companies with audit capabilities.
- Healthcare:Digital health platforms and clinical workflow software. Telemedicine infrastructure in France and Germany attracts capital reallocation from legacy healthcare services.
- Consumer Goods:Branded products and retail distribution networks. ESG data integration challenges elevate due diligence costs under CSRD disclosure mandates.
- Financial Services:Specialty lending, insurance distribution, and payment infrastructure. German and French regulatory frameworks require localized compliance expertise.
Technology captures the deepest capital pools. Healthcare is gaining share fastest.
Investor Type:
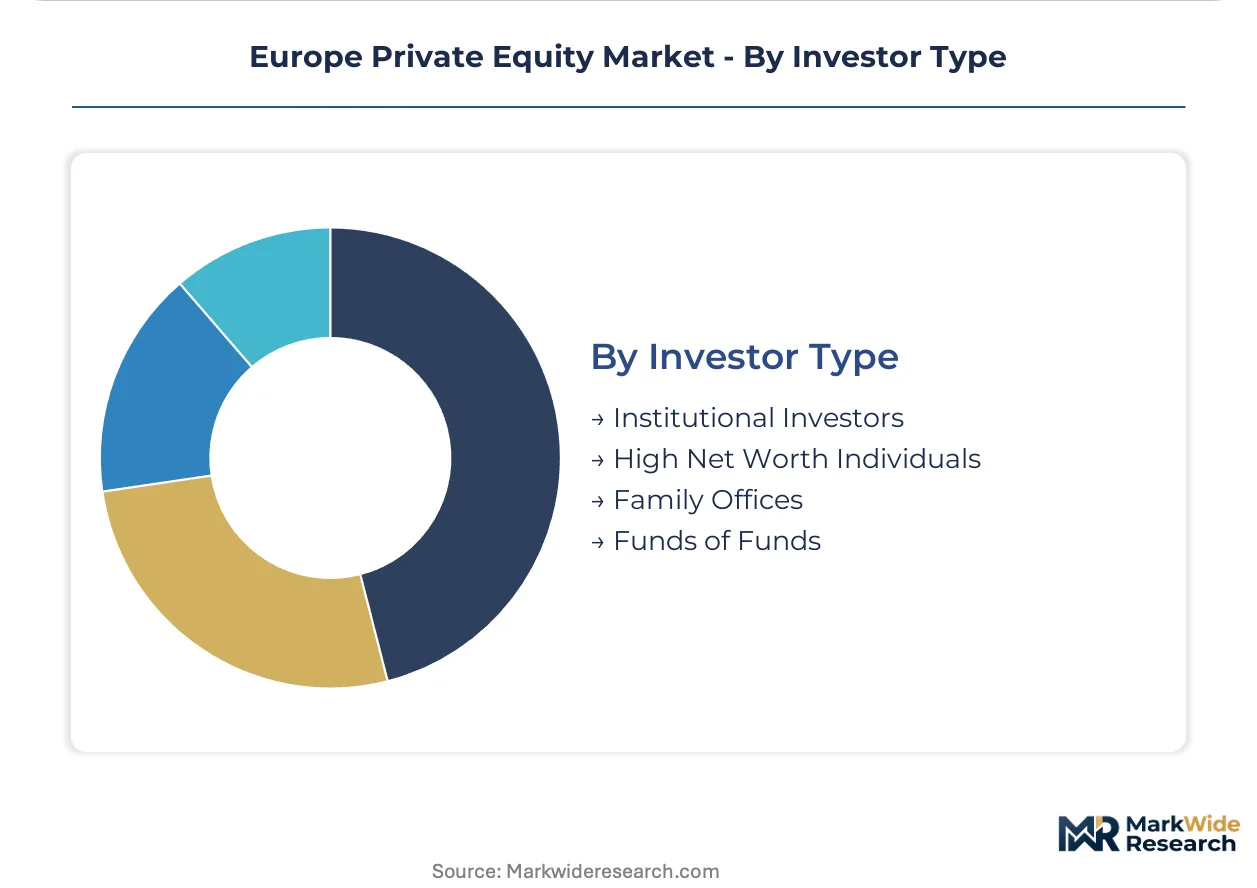
Institutional investors drive standardization through mandate uniformity, while family offices and HNWIs demand customized terms and co-investment rights.
- Institutional Investors:Pension funds, insurance companies, and sovereign wealth vehicles. Danish and Swedish pension funds condition allocations on granular Scope 3 emissions tracking across underlying holdings.
- Family Offices:Single and multi-family wealth vehicles with flexible horizons. Direct co-investment appetite reduces fee drag on large commitments.
- High Net Worth Individuals:Retail-style access through feeder structures or fund-of-funds wrappers. Regulatory marketing restrictions vary across German, French, and Nordic jurisdictions.
- Funds of Funds:Diversified exposure vehicles for investors lacking direct GP relationships. Secondary market activity generates portfolio rebalancing volume for tail-end fund restructuring.
Institutional Investors anchor the capital base. Family Offices are expanding commitments most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting fund domiciliation toward jurisdictions with streamlined compliance frameworks. The EU Green Deal and CSRD mandates create cost-of-compliance gaps that sponsors exploit through Luxembourg and Irish structuring vehicles. Capital deployment patterns increasingly track regulatory implementation timelines rather than pure economic fundamentals.
Germany
Industrial Mittelstand succession crunches generate concentrated buyout deal flow in Baden-Württemberg and Bavaria. The KBA enforces stringent automotive compliance that elevates due diligence costs for manufacturing targets. Munich and Stuttgart clusters host specialized operational improvement boutiques serving founder-owned manufacturers.
France
Healthcare technology and fintech ventures attract capital reallocation from traditional industrial targets. ANSM and CNIL impose layered regulatory requirements on digital health and data-intensive business models. Paris-based growth equity specialists concentrate on clinical workflow software and regulatory technology platforms.
United Kingdom
Post-Brexit regulatory divergence creates structuring complexity for cross-border fundraises. The FCA maintains distinct transparency mandates for fund marketing that differ from EU-level ESMA standards. London retains dominance in secondaries trading and GP-led continuation vehicle structuring.
Sweden
Nordic pension fund capital concentrates in domestic technology and life sciences ventures. Stockholm's software clusters attract growth capital deployment despite thin local banking depth for acquisition financing. The Swedish Financial Supervisory Authority sharpens sustainability disclosure requirements for institutional limited partners.
Netherlands
Pension capital from Dutch institutional investors drives demand for Article 8 and Article 9 fund classifications. The AFM enforces marketing transparency rules that exceed baseline EU directives. Amsterdam hosts specialized ESG data infrastructure providers serving pan-European sponsor compliance needs.
Europe Private Equity Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with mega funds capturing fee generation concentration while mid-cap vehicles dominate competitive auction terrain. The vendor base organizes around three archetypes: scale-driven buyout platforms with operational improvement engines, growth equity specialists in technology subsectors, and diversified multi-strategy houses with credit and secondaries capabilities. M&A activity concentrates on bolt-on acquisitions for portfolio value creation, while strategic partnerships with regulatory technology providers address CSRD compliance infrastructure gaps.
Within the scale-driven tier, Permira and CVC Capital Partners exemplify concentrated sector-specialist positioning, while Ardian occupies a distinctive infrastructure-to-healthcare crossover niche. These firms anchor the European competitive landscape through differentiated sourcing relationships and limited partner mandate alignment. KKR and TPG represent US-origin platforms with substantial European deployment capacity, competing directly with indigenous sponsors for German Mittelstand and French technology targets.
| Leading Market Players |
|---|
| Permira |
| Ardian |
| CVC Capital Partners |
| Advent International |
| TPG |
| KKR |
| Apax Partners |
| Warburg Pincus |
| EQT |
| Others |
Supply Flow & Price Mechanics
Institutional limited partner mandates for Article 8 and Article 9 fund classifications are compressing fee structures and forcing general partners to absorb compliance infrastructure costs, reshaping how sponsors price management fees and carried interest across European fund structures.
Pricing Analysis
Management fee layering structures the economics of European private equity fundraising. Three-tier pricing stratifies across mega funds with sub-1.5% headline rates, mid-cap vehicles at 1.5-2.0%, and specialist boutiques commanding premium terms for sector expertise. Price differentiation hinges on track record vintage quality and ESG data infrastructure depth. Fee compression runs through mega fund tiers as Danish and Swedish pension funds consolidate allocations toward scale vehicles. Mid-cap specialists serving German Mittelstand owners retain the most pricing power due to operational improvement scarcity.
Supply Chain Analysis
Direct-to-institutional channels handle sovereign wealth fund and pension capital deployment, while placement agents and fund-of-funds intermediaries serve fragmented family office demand. Capital formation concentrates in Luxembourg, Ireland, and the Netherlands as regulatory arbitrage shapes domiciliation choices. Raw material dependencies include legal structuring expertise, ESG data infrastructure, and regulatory technology compliance tools. Single-source vulnerability sits with Nordic banking concentration for acquisition financing. Distribution runs through London for secondaries trading and GP-led continuation vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European private equity functions as a stable compounder anchored by structural capital reallocation from public markets and persistent Mittelstand succession demand across Germany and France.
For Market Incumbents: To counter fee compression from institutional LP consolidation, anchor pricing power through vertical integration into regulatory technology and ESG data infrastructure. Deepen operational improvement capabilities in Baden-Württemberg and Bavaria manufacturing clusters to differentiate auction positioning. For New Entrants and Emerging Players: Enter via Nordic software and life sciences growth equity where local capital depth remains thin relative to Copenhagen and Stockholm cluster quality. Target Danish and Swedish pension fund co-investment programs as the most penetrable LP segment. Lead with EU AI Act compliance advisory capabilities to capture recurring revenue from portfolio company mandates. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing integrated ESG operating platforms and German industrial sourcing relationships. Long-term viability frames around sponsors with proven CSRD-aligned value creation track records. Watch for inflection signals in secondaries market volume acceleration as aging European buyout vintages require liquidity solutions.| Strategic Initiative | Industry Significance |
|---|---|
| ESG Data Infrastructure Buildout | Integrated carbon accounting platforms satisfy Danish and Swedish pension fund Scope 3 tracking mandates. |
| Regulatory Technology Acquisition | EU AI Act compliance capabilities capture recurring revenue from French and German portfolio companies. |
| Nordic Growth Equity Expansion | Stockholm and Copenhagen software clusters offer underexploited deployment potential with limited local competition. |
| GP-Led Continuation Vehicle Structuring | Secondaries market liquidity solutions address aging European buyout vintage exit pressure. |
| Mittelstand Operational Improvement Platform | Specialized manufacturing expertise differentiates auction positioning in Bavaria and Baden-Württemberg succession deals. |
Methodological Framework
Multiple input streams — fund formation databases, regulatory filing repositories, and LP mandate disclosure records — were reconciled against primary interviews with fund managers, institutional limited partners, placement agents, and regulatory compliance officers. Secondary validation drew from ESMA transparency reports, national financial regulator disclosures, and European fund domiciliation statistics. Bottom-up capital commitment tracking and top-down AUM estimation were triangulated to anchor market sizing.
Data-stream reconciliation across the projection horizon employed segment-level modeling by investment strategy, fund size category, and industry vertical. Growth capital deployment velocity, buyout leverage availability, and venture capital exit window timing were tracked as industry-specific forecast inputs. CAGRs were derived from vintage-level cash flow pattern analysis and forward commitment pipeline assessment.
Inputs from regulatory disclosure filings and LP mandate documents were available through the study window; gaps in private fund performance data introduce uncertainty bands around return assumptions. Forecasts reflect base-case assumptions regarding ECB policy trajectory and CSRD implementation timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Investment Analysis and Financial Strategies
Cash Management System Market
Investment Analysis and Financial Strategies
Peer to Peer Insurance Market
Investment Analysis and Financial Strategies
Europe Online Insurance Market
Investment Analysis and Financial Strategies
Singapore Neobanking Market
Investment Analysis and Financial Strategies
Private Passenger Auto Insurance Market
Investment Analysis and Financial Strategies
Power Bank Sharing Services Market
Investment Analysis and Financial Strategies
Wireless POS Terminals Market
Investment Analysis and Financial Strategies
Europe Banking-As-A-Service Market
Investment Analysis and Financial Strategies
Certificates Market
Investment Analysis and Financial Strategies
Saudi Arabia POS Terminal Market
Investment Analysis and Financial Strategies
EMV Card Market
Investment Analysis and Financial Strategies
USA Home Loan Market
Investment Analysis and Financial Strategies
Asia-Pacific Electronic Gadgets Insurance Market
Investment Analysis and Financial Strategies
Global Retail Core Banking Systems Market
Investment Analysis and Financial Strategies
Cardless ATM Market
Investment Analysis and Financial Strategies
Global Energy Trading and Risk Management (ETRM) Market