
 Europe Pet Insurance Market | 2026-2036
Europe Pet Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pet Insurance Market Analysis
Lifetime coverage tiers with unlimited annual condition limits is redrawing competitive boundaries across Europe. Petplan (Allianz) leverages its pan-European license network to sustain cross-border policy portability. ManyPets anchors its growth in direct-to-consumer digital underwriting, while Agria Pet Insurance dominates breed-specific risk pricing through decades of actuarial data.
Europe pet insurance constitutes a risk-transfer mechanism covering veterinary treatment costs, mortality, and third-party liability for companion animals, typically underwritten through annual renewable contracts with co-payment structures ranging from ten to thirty percent. The product's commercial purpose centers on absorbing unpredictable veterinary expenditure spikes that otherwise trigger euthanasia decisions or financial distress among households. Lifetime policies command the deepest margin pools due to renewal stickiness and premium escalation clauses, while accident-only coverage occupies a shrinking niche among price-sensitive buyers. Distribution through online channels is displacing broker intermediation fastest in Nordic markets, though pet shops retain residual traction for first-policy attachment at point of adoption.
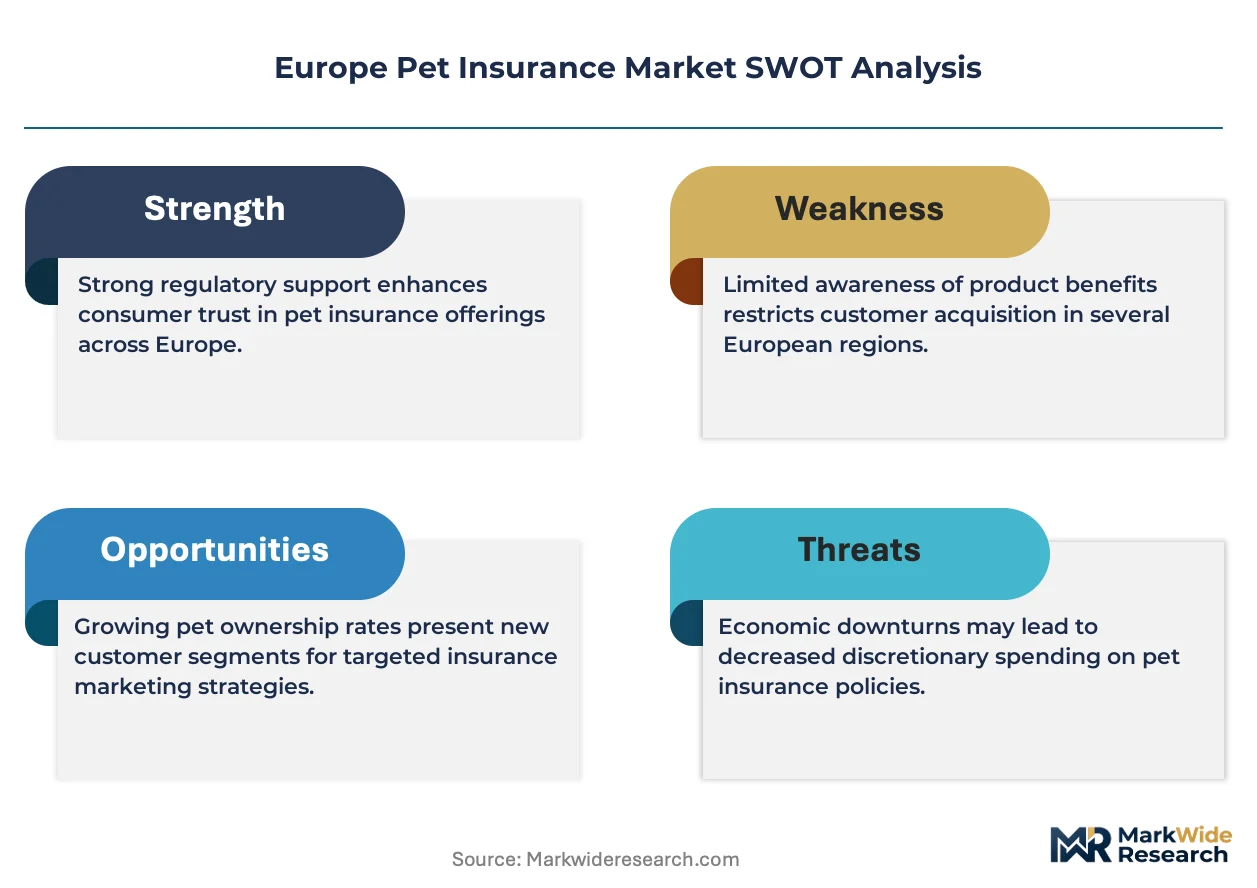
EIOPA's insurance distribution directives and national regulators such as Germany's BaFin and the UK's FCA shape solvency requirements and consumer disclosure standards that determine market access across member states. The EU Green Deal's indirect pressure on veterinary pharmaceutical pricing cascades into premium rate calculations and coverage exclusions. Stakeholders must monitor how national veterinary fee deregulation and telemedicine authorization frameworks alter claims frequency and severity assumptions.
Market Dynamics
EIOPA's insurance distribution directives are compressing cross-border licensing timelines while veterinary fee deregulation across Germany, France, and Sweden is forcing insurers to reprice condition-specific coverage tiers.
Growth Catalysts
- Telemedicine authorization:Germany's national veterinary chamber has cleared remote consultation billing codes, enabling insurers to package virtual triage into base policies.
- Lifetime policy stickiness:United Kingdom households facing 12% annual veterinary inflation are upgrading from accident-only to unlimited annual condition coverage.
- EU Green Deal pharmaceutical pricing pressure:Cascading cost controls on veterinary antibiotics are narrowing claims severity variance for chronic condition underwriters.
Market Restraints
- Veterinary labor supply concentration:Specialist surgical capacity clusters in London, Paris, and Munich, creating regional claims cost asymmetry.
- Regulatory fragmentation:BaFin's consumer disclosure standards diverge from FCA requirements, raising compliance overhead for pan-European license holders.
- Co-payment ceiling compression:Sweden's price comparison aggregators are standardizing ten-percent co-pay expectations, squeezing margin on higher-tier products.
Strategic Opportunities
- Underpenetrated Southern Europe:Spain and Italy exhibit sub-5% household penetration rates against 25% in Sweden, offering raw expansion terrain.
- Breed-specific actuarial data monetization:Cross-referencing genomic markers with claims history enables precision pricing for hereditary condition clusters.
- Embedded distribution at adoption:Shelter and breeder partnership APIs are capturing first-policy attachment before price comparison site exposure.
Industry Challenges
- Veterinary claims adjudication talent scarcity:Qualified assessors who can distinguish pre-existing from acute presentations command 40% salary premiums.
- Legacy policy administration migration:Decades of paper-based renewal records resist digitization without manual reconciliation.
- GDPR-compliant pet health data sharing:Cross-border claims verification requires consent architectures that delay real-time pre-authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pet Insurance Market |
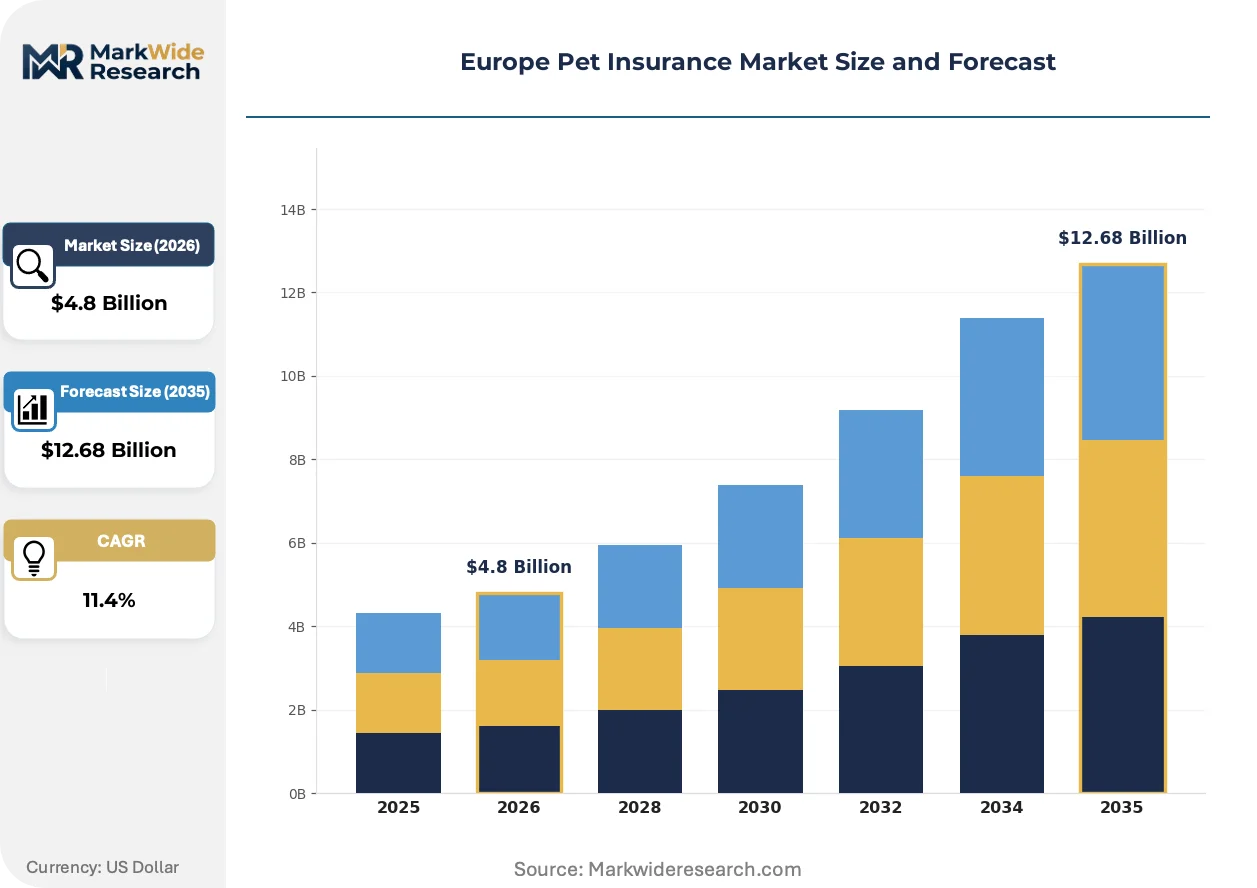
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Accident Only, Time-Limited, Lifetime, Maximum Benefit Animal Type: Dogs, Cats, Birds, Small Mammals Premium Range: Low, Medium, High, Variable Distribution Channel: Online, Brokers, Direct Sales, Pet Shops |
| Companies Covered | Deutsche Familienversicherung AG (DFV), Getsafe GmbH, Petplan (Allianz), Royal & Sun Alliance, ManyPets, Agria Pet Insurance, Direct Line, Lassie, Trupanion, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pet Insurance Market Emerging Trajectories
Digital underwriting engines and condition-specific pricing models are fragmenting the traditional annual renewable contract structure across European markets.
AI-powered claims triage is decomposing the role of veterinary invoice review clerks across Nordic insurers. Direct-to-consumer platforms in Denmark and Norway are deploying natural language processing to flag pre-existing conditions from unstructured clinical notes. This compression of assessment labor is enabling same-day claims settlement that previously required two-week manual review cycles.
CSRD sustainability reporting mandates are forcing insurers to disclose veterinary pharmaceutical procurement carbon footprints. The EU Green Deal's scope 3 emission tracking requirements are cascading into premium calculations for policies covering large-breed dogs with high medication intensity. French and German carriers are responding by partnering with compounding pharmacies to source lower-carbon alternative therapies.
Subscription-based wellness bundling is capturing pet owners who previously purchased insurance reactively post-diagnosis. Preventive care packages covering vaccination, dental scaling, and parasite screening are displacing traditional accident-only coverage in United Kingdom urban markets. This behavioral shift concentrates most visibly in London and Manchester, where veterinary practice consolidation enables insurer-practice revenue-sharing arrangements.
Europe Pet Insurance Market Segmentation
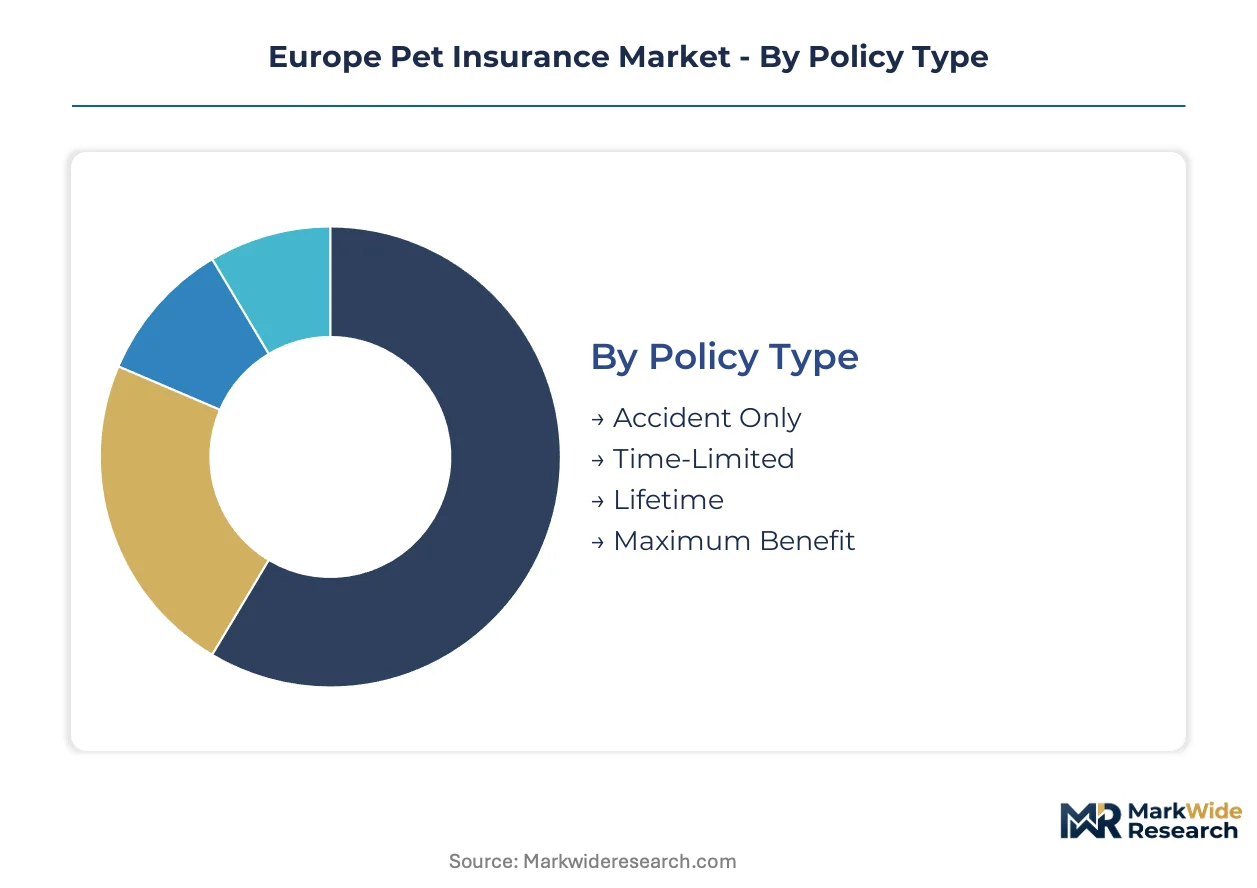
Segmentation in Europe pet insurance determines underwriting precision, distribution economics, and renewal stickiness. Insurers calibrate pricing engines and claims reserves differently across policy structures, species risk profiles, and channel acquisition costs.
Policy Type:
Lifetime policies flow predominantly through direct-to-consumer digital channels with embedded premium escalation clauses, while accident-only coverage concentrates in price-aggregating intermediaries.
- Lifetime:Unlimited annual condition limits with renewable coverage for chronic illnesses. United Kingdom households facing veterinary inflation above 10% annually are migrating toward this tier for predictable long-term cost control.
- Accident Only:Coverage restricted to trauma, poisoning, and acute injury excluding illness. Price-sensitive buyers in Southern Europe select this tier through comparison websites, though attachment rates are declining as lifetime products penetrate.
- Time-Limited:Condition-specific coverage expiring after 12 months or fixed monetary caps. Serves transitional policyholders in Germany upgrading from accident-only toward comprehensive protection.
- Maximum Benefit:Per-condition monetary ceilings without time restrictions. Retains residual demand among cat owners in France seeking middle-ground protection against common feline chronic conditions.
By volume, accident-only policies still lead across Southern Europe. By growth pace, lifetime coverage is gaining share fastest in Germany and the United Kingdom.
Animal Type:
Species-specific actuarial modeling drives divergent margin structures, with canine portfolios commanding the most sophisticated breed-risk stratification.
- Dogs:Premium pools scale with size, breed hereditary risk, and regional veterinary cost baselines. Large-breed policies in Sweden and the United Kingdom incorporate orthopedic condition riders reflecting hip dysplasia prevalence.
- Cats:Lower average premiums but higher policy density in urban French and German markets. Indoor-outdoor risk classification and feline infectious disease exposure shape territorial pricing.
- Birds:Avian veterinary capacity constraints limit product availability. Specialist exotic animal insurers in the Netherlands and Belgium dominate this thin segment.
- Small Mammals:Rabbits, ferrets, and rodents attract niche coverage through veterinary practice embedded distribution. Claims frequency is elevated relative to premium yield, compressing margins.
Canine policies generate the deepest premium pools. Feline coverage is climbing the fastest as urban household pet density rises.
Premium Range:
Pricing tiers align with co-payment structures and annual condition limits, creating distinct customer acquisition economics across channels.
- High:Zero co-payment options with unlimited annual reimbursement ceilings. Affluent households in London, Paris, and Stockholm purchase through direct insurer platforms, bypassing aggregator commissions.
- Medium:Standard 20% co-payment structures with moderate condition caps. Brokers in Germany intermediate this tier, bundling with household or motor portfolios.
- Low:Elevated co-payments and restricted provider networks. Price comparison aggregators in Sweden standardize this tier, eroding carrier margins through transparent premium ranking.
- Variable:Usage-based or wellness-linked pricing adjusting to claims history and preventive care compliance. Emerging in United Kingdom urban markets through insurer-veterinary practice partnerships.
Medium-premium policies dominate policy-in-force counts. Variable pricing is expanding most quickly among digitally native carriers.
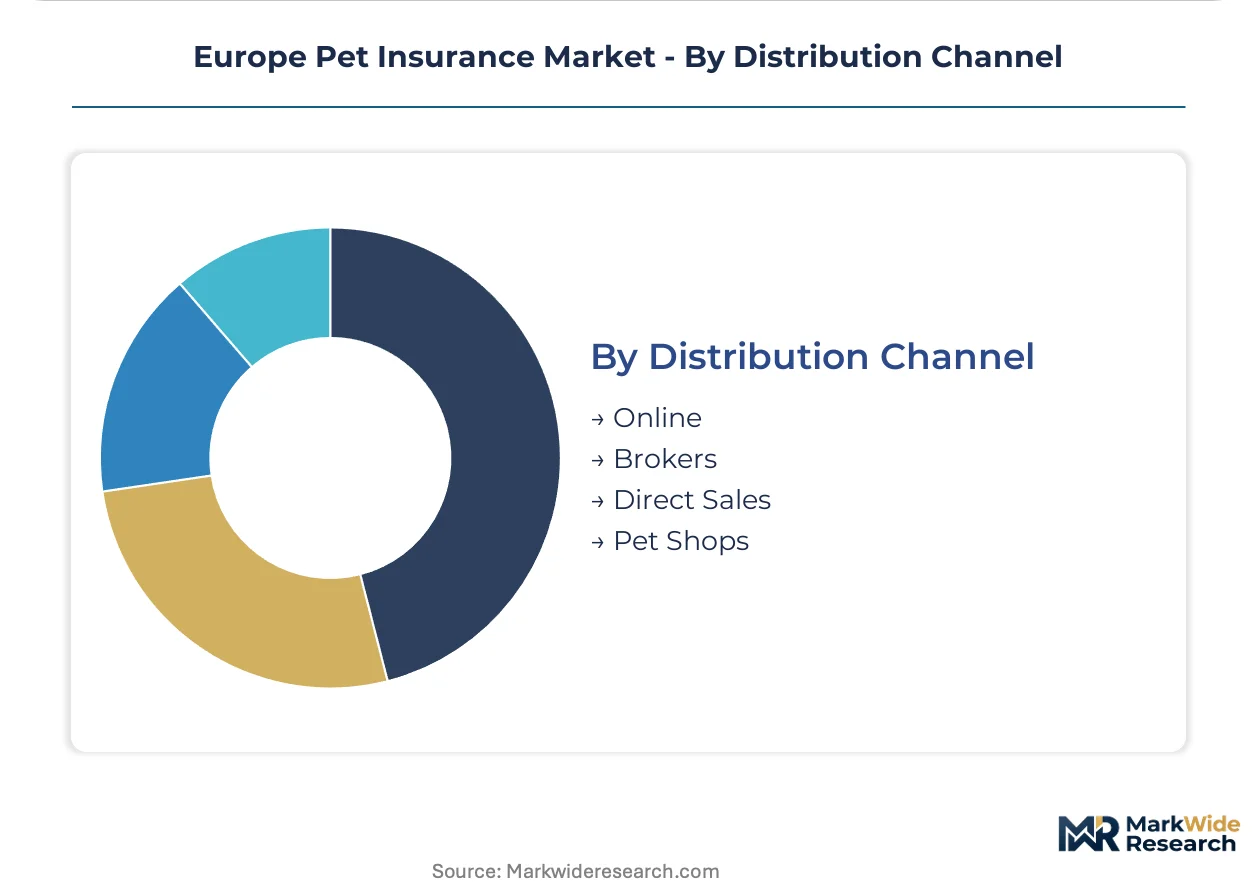
Distribution Channel:
Channel economics determine customer lifetime value, with embedded acquisition at veterinary practices or pet retailers outperforming aggregator-sourced policies on retention.
- Online:Direct-to-consumer platforms and price comparison aggregators. Nordic markets exhibit the highest digital penetration, with natural language processing enabling real-time pre-existing condition screening.
- Brokers:Independent intermediaries bundling pet coverage with personal lines. Retain residual importance in Germany and France for complex multi-pet household structuring.
- Direct Sales:Insurer proprietary channels including telemarketing and branch networks. Legacy carriers in the United Kingdom maintain this infrastructure for senior demographic segments.
- Pet Shops:Point-of-adoption attachment at breeders, shelters, and retail chains. Captures first-policy relationships before price comparison exposure, prevalent in United Kingdom puppy purchase pathways.
Online channels lead by volume across Northern Europe. Pet shop embedded distribution is gaining share fastest as shelter partnership APIs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Veterinary service capacity clusters in London, Paris, Munich, and Stockholm are driving premium rate divergence across national markets. Insurers calibrate pricing engines against regional fee schedules that vary by 40% or more for identical procedures. National regulatory frameworks compound these cost asymmetries through divergent consumer disclosure and solvency requirements.
United Kingdom
Lifetime policy penetration exceeds 25% of dog-owning households, with veterinary inflation at 12% annually forcing upgrades from accident-only coverage. The FCA's consumer duty rules mandate clear disclosure of premium escalation clauses and coverage exclusions. London's veterinary specialist corridor concentrates orthopedic and oncological surgical capacity, creating claims cost premiums 35% above national averages.
Germany
BaFin's stringent solvency requirements favor established carriers with diversified personal lines portfolios over pure-play pet insurers. The national veterinary chamber's authorization of telemedicine billing codes enables virtual triage packaging into base policies. Munich and Berlin host the densest specialist veterinary networks, with orthopedic surgery costs 28% above the federal median.
Sweden
Price comparison aggregators have standardized ten-percent co-payment expectations, compressing margins on higher-tier products despite 30% household penetration rates. GDPR-compliant health data sharing architectures delay real-time pre-authorization, creating friction in claims processing. Stockholm's veterinary consolidation enables insurer-practice revenue-sharing arrangements for wellness bundling.
France
ANSM pharmaceutical pricing oversight cascades into premium calculations for chronic condition coverage, particularly large-breed dogs with high medication intensity. The CSRD sustainability reporting mandate forces disclosure of veterinary pharmaceutical procurement carbon footprints. Paris concentrates 40% of national specialist surgical capacity, driving regional premium differentials.
Spain
Sub-5% household penetration offers raw expansion terrain for digital-first carriers with direct-to-consumer acquisition models. National veterinary fee deregulation remains incomplete, creating pricing opacity that favors established broker intermediaries. Barcelona and Madrid exhibit the fastest policy growth rates as urban household pet density rises.
Europe Pet Insurance Market Vendor Landscape
Concentration sits with pan-European licensed carriers and digitally native direct-to-consumer platforms. The market structure divides between legacy insurers leveraging diversified personal lines balance sheets and technology-driven entrants optimizing for acquisition cost efficiency. Three archetypes dominate: established multi-line insurers with veterinary claims expertise, insurtech platforms deploying AI-powered underwriting, and specialist pet carriers with decades of breed-specific actuarial data. Competitive moves center on shelter partnership API deployment for first-policy attachment and cross-border license utilization for policy portability.
Among Germany-based carriers, Deutsche Familienversicherung AG and Getsafe GmbH exemplify divergent strategic positions—one rooted in traditional multi-line infrastructure, the other in mobile-native distribution architecture. The United Kingdom hosts intense competition between Petplan, ManyPets, and Direct Line, each occupying distinct tier positions on digital sophistication and brand heritage. Agria Pet Insurance anchors the specialist tier with concentrated expertise in hereditary condition pricing.
| Leading Market Players |
|---|
| Deutsche Familienversicherung AG (DFV) |
| Getsafe GmbH |
| Petplan (Allianz) |
| Royal & Sun Alliance |
| ManyPets |
| Agria Pet Insurance |
| Direct Line |
| Lassie |
| Trupanion |
| Others |
Supply Flow & Price Mechanics
Specialist veterinary surgical capacity utilization above 85% in London, Paris, and Munich creates regional pricing power asymmetries that cascade into premium rate floors across national markets. Scale economies in consolidated veterinary practice groups enable insurer-practice revenue-sharing arrangements that reshape distribution economics and condition-specific coverage pricing.
Pricing Analysis
EIOPA's insurance distribution directives dictate the pricing tier structure across European markets, mandating transparent premium escalation clause disclosure that compresses opacity margins. Three-tier pricing structure across premium, standard, and economy levels separates zero co-payment unlimited coverage from twenty-percent co-pay condition-capped policies and restricted-network accident-only tiers. Price differentiation rests on co-payment percentage and annual condition limit generosity, with affluent urban households in Stockholm and London exhibiting lowest price sensitivity. Cost compression in standard-tier products is intensifying because Sweden's price comparison aggregators have standardized ten-percent co-pay expectations.
Supply Chain Analysis
Just-in-time claims adjudication dominates Nordic markets where AI-powered triage enables same-day settlement, while strategic stockpiling of veterinary claims assessor talent persists in Germany and the United Kingdom. Geographic supply concentration clusters in the United Kingdom, Germany, and Sweden, where qualified veterinary invoice reviewers command salary premiums. Raw material dependencies encompass pharmaceutical procurement carbon footprint tracking under CSRD mandates, telemedicine billing code authorization, and breed-specific actuarial data licensing. Single-source vulnerability sits with specialist surgical capacity concentration in capital cities. Distribution runs through direct-to-consumer digital platforms displacing broker intermediation fastest in Denmark and Norway.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe pet insurance sits in early-cycle expansion as sub-5% household penetration in Spain and Italy against 25-30% in Nordic markets creates runway for geographic arbitrage.
For Market Incumbents: Consolidate breed-specific actuarial data advantages through exclusive genomic database partnerships before insurtech platforms achieve parity. Lock in shelter partnership API exclusivity to capture first-policy attachment before price comparison site exposure erodes acquisition economics. Vertical integration into veterinary practice revenue-sharing arrangements in London and Paris defends margin position against pure-play digital entrants. For New Entrants and Emerging Players: Lead with embedded distribution at point of adoption in Spanish and Italian shelter networks where broker intermediation retains pricing opacity. Target sub-5% penetration Southern Europe with direct-to-consumer mobile-native underwriting that bypasses legacy policy administration infrastructure. White-space capture runs through wellness bundling subscription models displacing reactive post-diagnosis purchase behavior. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors carriers with proprietary breed-risk stratification databases and pan-European license portability. Long-term viability over a decade horizon hinges on telemedicine integration depth and GDPR-compliant health data architecture. Acquisition target archetype: specialist pet carriers with decades of hereditary condition claims history. The signal to watch is veterinary fee deregulation momentum across Germany, France, and Sweden as inflection indicator for premium repricing cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Shelter Partnership API Deployment | Captures first-policy relationships at adoption before price comparison aggregator exposure in United Kingdom and German markets. |
| Telemedicine Billing Integration | Germany's national veterinary chamber authorization enables virtual triage packaging into base policies with claims cost reduction. |
| Breed-Specific Genomic Data Licensing | Cross-referencing hereditary markers with claims history enables precision pricing for orthopedic condition clusters in large-breed portfolios. |
| GDPR-Compliant Health Data Architecture | Consent frameworks enabling real-time cross-border pre-authorization differentiate carriers in Nordic markets with highest digital penetration. |
| Veterinary Practice Revenue-Sharing | London and Manchester consolidation enables insurer-practice wellness bundling arrangements that displace traditional accident-only coverage. |
Methodological Framework
Operator-level perspectives from veterinary claims assessors, insurance distribution directors, shelter network managers, and regulatory affairs specialists anchored the qualitative base. Primary interview data combined with secondary validation from EIOPA solvency disclosures, national veterinary chamber fee schedules, and FCA consumer duty guidance documents. Bottom-up policy-in-force counts by country and segment triangulated against top-down premium pool estimates from carrier regulatory filings.
Sensitivity analysis across co-payment structure assumptions, veterinary inflation scenarios, and digital penetration rates shaped the analytical framework over the projection horizon. Segmentation dimensions modeled encompass policy type tier, animal species risk profile, premium range band, and distribution channel economics. CAGRs derived from historical policy growth trajectories adjusted for regulatory authorization timelines and telemedicine adoption curves. Forecast inputs incorporated veterinary fee deregulation momentum and EU Green Deal pharmaceutical pricing cascade effects.
The analysis sits within stated boundaries; outcomes outside sustained veterinary cost inflation above historical norms or accelerated telemedicine authorization timelines would require recalibration. Forecasts reflect documented assumptions about household penetration ceiling convergence and regulatory harmonization progress. Revision becomes warranted when GDPR-compliant health data sharing architecture deployment crosses thresholds enabling real-time cross-border claims verification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Investment Analysis and Financial Strategies
Asia Pacific Mobile Wallet Market
Investment Analysis and Financial Strategies
Data Analytics in Insurance Market
Investment Analysis and Financial Strategies
Cryptocurrency Hardware Wallet Market
Investment Analysis and Financial Strategies
Compliance As a Service Market
Investment Analysis and Financial Strategies
China Forensic Accounting Market
Investment Analysis and Financial Strategies
Life Reinsurance Market
Investment Analysis and Financial Strategies
Mexico Digital Wallet Market
Investment Analysis and Financial Strategies
US Banking-As-A-Service Market
Investment Analysis and Financial Strategies
Vietnam Payments Market
Investment Analysis and Financial Strategies
Global Real-Time Payments Market
Investment Analysis and Financial Strategies
GCC Payment Gateway Market
Investment Analysis and Financial Strategies
Japan Auto Loan Market
Investment Analysis and Financial Strategies
Loan Servicing Software Market
Investment Analysis and Financial Strategies
Global Gift Card Market
Investment Analysis and Financial Strategies
Road Assistance Insurance Market
Investment Analysis and Financial Strategies
In-Vehicle Payment System Market