
 Europe Factoring Services Market | 2026-2036
Europe Factoring Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Factoring Services Market Insights
Asset-light operating models and supply chain finance structures is tilting competitive dynamics toward non-bank specialists and platform-based providers. Deutsche Factoring Bank leverages its captive banking license to sustain pricing power in German mid-market segments. Société Générale S.A. anchors its position through integrated trade finance corridors spanning Southern Europe. Bibby Financial Services specializes in SME invoice cycles, competing on speed of advance rather than rate alone.
Europe factoring services encompass the purchase of trade receivables at a discount, with advance rates typically ranging from 70% to 90% of invoice value and credit protection layered through recourse or non-recourse structures. These instruments convert accounts receivable into immediate working capital, bridging cash flow gaps inherent in extended supplier payment terms across continental trade. Non-recourse factoring commands premium positioning as buyers absorb credit risk transfer, while invoice discounting retains fastest velocity among client segments seeking confidential financing without debtor notification. Manufacturing verticals dominate volume throughput due to elongated production-to-payment cycles, though logistics applications accelerate as just-in-time inventory models strain distributor liquidity.
European Banking Authority prudential standards and ECB collateral eligibility frameworks shape factoring market structure by determining which receivables qualify for central bank refinancing. GDPR data handling requirements and EU Anti-Money Laundering Directives impose operational compliance costs on automated invoice verification platforms, filtering smaller providers from scale contention. Stakeholders must monitor how the EU Green Deal taxonomy extends to sustainable supply chain finance, as environmental performance-linked factoring products emerge as a distinct margin pool.
Market Dynamics
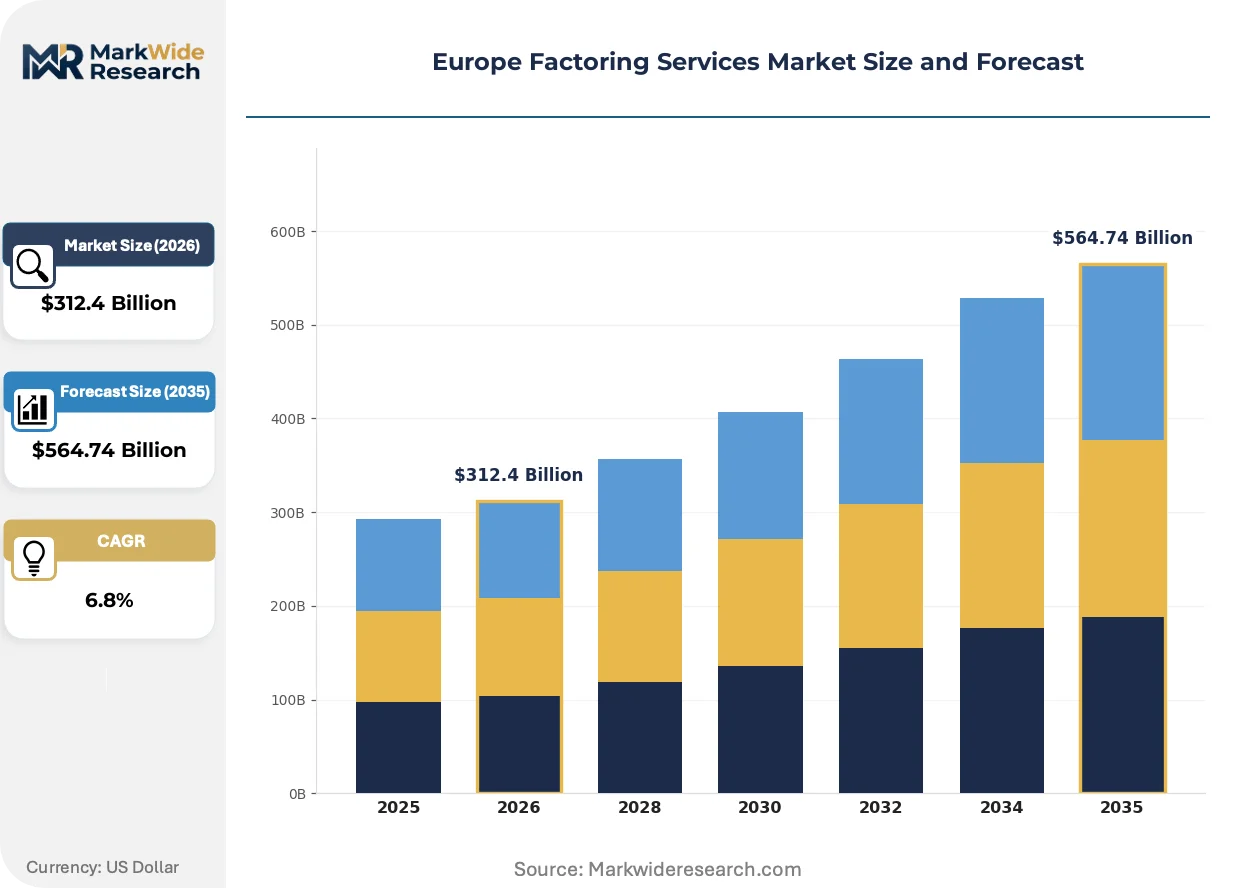
Basel III capital requirements are compressing traditional bank lending capacity across European SME segments, redirecting working capital demand toward non-bank factoring specialists and platform-based receivables purchasers.
Growth Catalysts
- Regulatory Capital Constraints:Basel III tiering rules tighten bank risk-weighted asset treatment of SME exposures. German and French mid-market borrowers face extended credit decision timelines, accelerating migration to independent factoring providers.
- Supply Chain Finance Ecosystem Maturation:Netherlands-based distributor networks deepen reverse factoring adoption. Integrated payables platforms connect buyer credit ratings directly to supplier advance pricing.
- Just-in-Time Inventory Pressures:Automotive and electronics manufacturing verticals elongate supplier payment terms to 90-120 days. Polish and Czech component manufacturers convert receivables to fund raw material procurement cycles.
Market Restraints
- GDPR Compliance Architecture:Automated invoice verification platforms face elevated operational costs from data handling restrictions. Cross-border receivables purchasing requires jurisdictional consent frameworks that slow onboarding velocity.
- Concentrated Banking Infrastructure:Central and Eastern European markets depend on correspondent banking relationships dominated by Frankfurt and Paris clearing networks. Local currency factoring faces euro-denominated settlement friction.
- Credit Insurance Capacity Limits:Non-recourse factoring structures rely on trade credit underwriters with restricted appetite for emerging market buyer exposures. Premium pricing compresses margin for Polish and Romanian portfolio originators.
Strategic Opportunities
- Green Supply Chain Finance Taxonomy:EU Green Deal classification frameworks extend to environmental performance-linked receivables purchasing. Sustainability-certified suppliers in Nordic manufacturing corridors access preferential advance rates.
- Embedded Finance Convergence:API-driven invoice financing integrates directly into enterprise resource planning systems. SAP and Oracle procurement modules now host native factoring origination workflows for German industrial clients.
- Baltic SME Penetration Gap:Estonian and Latvian markets show sub-15% factoring penetration versus 35% in established Western European corridors. Digital-native providers bypass branch infrastructure to capture unbanked receivables volume.
Industry Challenges
- Legacy System Integration Friction:Mid-market manufacturers operate on decades-old accounting platforms lacking open API architecture. Factoring providers absorb bespoke integration costs that erode unit economics on sub-€5 million annual turnover clients.
- Trade Credit Assessment Talent Scarcity:Specialized underwriters with cross-border buyer risk expertise command premium compensation. Warsaw and Prague operations centers compete with London and Zurich for bilingual analyst pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Factoring Services Market |
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $564.74 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Recourse Factoring, Non-recourse Factoring, Invoice Discounting, Asset-based Lending Client Type: SMEs, Large Enterprises, Startups, Corporates Industry Vertical: Manufacturing, Retail, Construction, Logistics Financing Model: Single Invoice, Bulk Financing, Fixed-rate Financing, Flexible Financing |
| Companies Covered | BNP Paribas, Barclays Bank PLC, Deutsche Factoring Bank, Société Générale S.A., UniCredit, ING Group, Bibby Financial Services, Aldermore, Eurobank, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Factoring Services Market Trends and Innovations
Distributed ledger infrastructure and artificial intelligence are restructuring how receivables are verified, priced, and traded across European correspondent networks.
Blockchain-based invoice tokenization is virtualizing receivables ownership transfer. Dutch logistics consortiums pilot programmable payment triggers linked to IoT-confirmed delivery events. Smart contract automation compresses settlement cycles from T+2 to near-real-time, eliminating manual reconciliation overhead in multi-party supply chains.
EU AI Act transparency mandates reshape automated credit scoring deployments. Factoring platforms must document algorithmic decision pathways for adverse action notifications. French and German regulators require human-in-the-loop overrides for AI-determined advance rate adjustments above €1 million exposure thresholds.
Buyer-led supply chain finance programs displace traditional seller-initiated factoring. German automotive OEMs now mandate reverse factoring participation across tier-1 and tier-2 supplier bases. Procurement departments treat extended payment terms as a working capital yield instrument, capturing spread between supplier financing costs and corporate cash yields.
Europe Factoring Services Market Segmentation
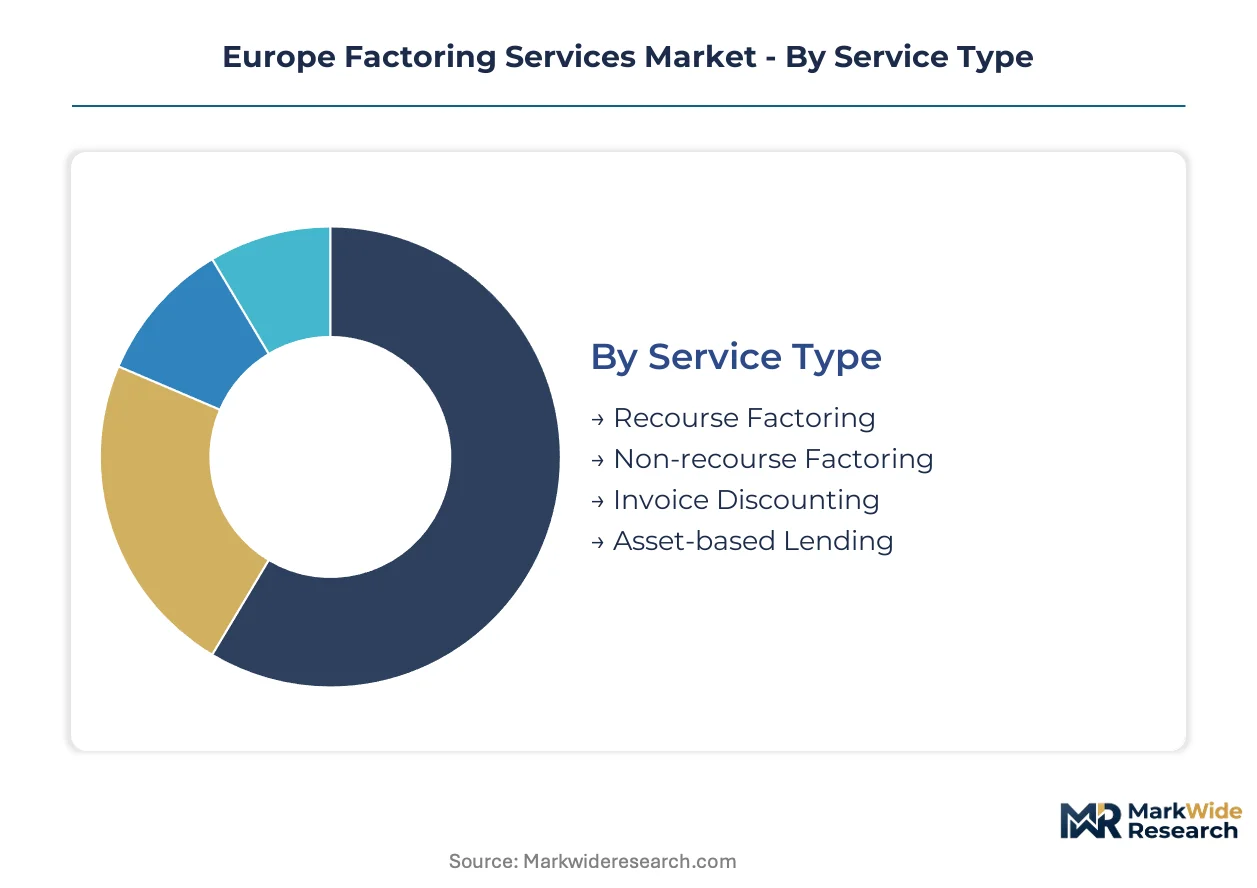
European factoring providers structure product portfolios around risk transfer mechanisms, client scale, and industry-specific cash flow patterns. Segmentation discipline determines pricing power, operational cost ratios, and regulatory capital treatment across the value chain.
Service Type:
Cost tier differentiation separates premium risk-absorbing products from rate-sensitive self-insured structures.
- Recourse Factoring:Sellers retain buyer default risk, enabling providers to offer advance rates at compressed spreads. German automotive suppliers favor this structure for predictable debtor portfolios with established payment histories.
- Non-recourse Factoring:Providers assume credit risk through captive insurance or third-party underwriters, commanding premium pricing. French exporters to Southern European markets absorb higher factoring fees to eliminate balance sheet contingency reserves.
- Invoice Discounting:Confidential financing without debtor notification preserves supplier-customer relationships. Dutch distributor networks deploy this for seasonal inventory builds.
- Asset-based Lending:Multi-asset collateral pools beyond receivables secure revolving credit facilities. Polish manufacturers leverage inventory-plus-receivables structures for raw material procurement cycles.
Recourse structures command the established base. The steepest expansion runs through non-recourse offerings as credit insurance markets deepen.
Client Type:
Customer scale determines onboarding economics, technology platform requirements, and relationship management intensity.
- SMEs:Fragmented invoice volumes and limited credit histories demand automated scoring engines. Central and Eastern European manufacturing subcontractors drive volume as Basel III constrains traditional bank overdraft facilities.
- Large Enterprises:Sophisticated treasury functions negotiate multi-currency programs with embedded FX hedging. German industrial conglomerates structure pan-European master agreements covering dozens of operating subsidiaries.
- Startups:Venture-backed growth companies trade equity dilution avoidance for receivables liquidity. Baltic fintech clusters show concentrated adoption.
- Corporates:Investment-grade parents guarantee subsidiary obligations, collapsing credit spreads to near-benchmark levels. Netherlands-based logistics holding companies centralize group-wide factoring arrangements.
Large enterprises anchor revenue concentration. SMEs generate the fastest portfolio expansion as digital origination platforms reduce unit acquisition costs.
Industry Vertical:
End-use application dictates payment term structures, invoice documentation standards, and seasonality patterns.
- Manufacturing:Elongated production-to-payment cycles spanning 60-120 days create structural working capital demand. Czech and Slovak automotive component suppliers convert receivables to fund just-in-time inventory obligations.
- Retail:High invoice velocity and seasonal peaks require flexible advance rate adjustments. German fashion distributors deploy factoring for pre-holiday inventory builds.
- Construction:Retention clauses and milestone-based billing complicate receivables verification. French public works contractors face extended payment terms from government procurement.
- Logistics:Freight forwarding and warehousing operations generate documentary-heavy invoices with delivery confirmation dependencies. Rotterdam port ecosystem participants leverage reverse factoring through buyer-led programs.
Manufacturing retains volume leadership. Logistics verticals climb fastest as e-commerce fulfillment networks strain distributor liquidity.
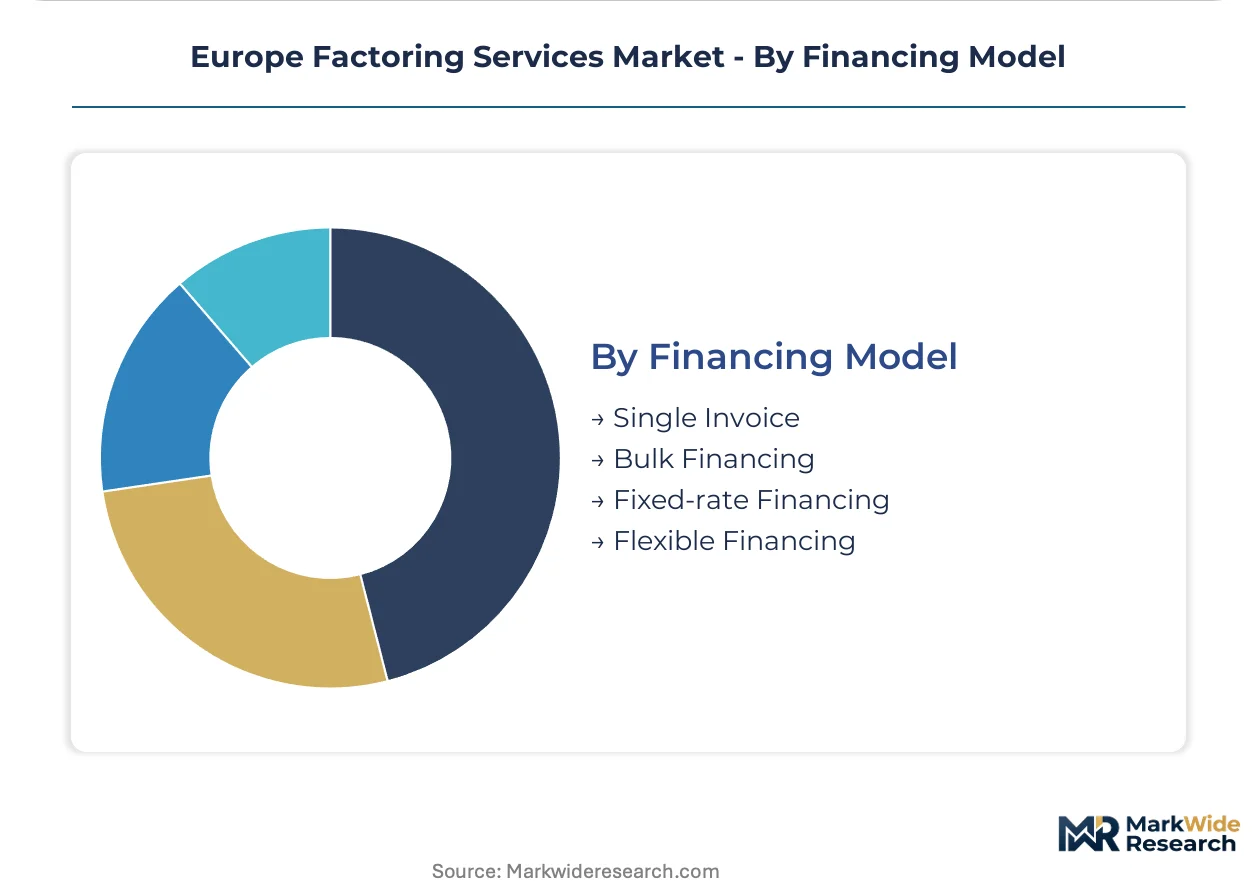
Financing Model:
Volume and pricing mechanics separate spot transactions from committed facility structures.
- Single Invoice:Spot purchasing of individual receivables without ongoing facility commitments. Spanish agricultural exporters deploy this for seasonal harvest receivables.
- Bulk Financing:Portfolio-level advances against entire debtor books with concentration limits. Italian textile manufacturers favor this for predictable cash flow smoothing.
- Fixed-rate Financing:Locked advance pricing across contract tenors hedges interest rate exposure. German mid-market borrowers prioritize budget certainty.
- Flexible Financing:Dynamic advance rates tied to real-time debtor risk scoring or seasonal fluctuations. Nordic seasonal goods importers adjust drawdowns to inventory cycles.
Bulk financing structures dominate committed relationships. Single invoice origination expands most quickly through API-integrated procurement platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade receivables liquidity demand tracks export-import intensity across European corridors. Germany, France, the Netherlands, and Poland anchor volume concentration as manufacturing supply chains elongate payment terms and Basel III compresses traditional bank credit availability.
Germany
Automotive OEMs and Mittelstand component suppliers drive non-recourse factoring adoption as 90-120 day payment terms strain liquidity. BaFin prudential standards shape capital treatment for bank-affiliated providers. Stuttgart and Munich industrial clusters anchor buyer-led reverse factoring programs across tiered supplier bases.
France
Export-oriented manufacturers absorb premium pricing for credit risk transfer on Southern European buyer exposures. Banque de France collateral frameworks determine ECB refinancing eligibility for assigned receivables. Lyon and Marseille logistics corridors deepen integrated payables platform deployment.
Netherlands
Rotterdam port ecosystem participants leverage distributor network density for reverse factoring scale. DNB oversight aligns with EU Anti-Money Laundering Directives on cross-border invoice verification. Eindhoven high-tech manufacturing clusters accelerate API-embedded financing origination.
Poland
Czech and Slovak component manufacturers convert receivables to fund raw material procurement amid just-in-time inventory pressures. Polish Financial Supervision Authority frameworks govern local currency factoring against euro settlement friction. Warsaw and Kraków operations centers compete for bilingual trade credit assessment talent.
United Kingdom
Post-Brexit trade finance fragmentation redirects receivables liquidity demand toward independent specialists. FCA conduct standards and GDPR data handling requirements elevate compliance architecture costs. London-based fintech platforms bypass legacy branch infrastructure to capture SME invoice volume.
Europe Factoring Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in discrete risk-transfer niches. The market structures around three tiers: universal banking groups with captive factoring arms, independent non-bank specialists, and emergent API-native platforms. Competitive dynamics concentrate on speed of advance execution, credit insurance integration depth, and ERP system connectivity. Dominant moves include M&A to acquire technology stacks and strategic partnerships embedding financing into procurement workflows.
Within the banking-affiliated tier, BNP Paribas, Société Générale S.A., and Deutsche Factoring Bank occupy positions shaped by their national regulatory licenses and correspondent network reach. These institutions exemplify the pricing power available to providers with ECB collateral eligibility and integrated trade finance corridors. Independent specialists such as Bibby Financial Services represent the velocity-focused archetype, competing on advance speed rather than rate compression. The competitive map tilts toward platform-based providers as embedded finance convergence accelerates.
| Leading Market Players |
|---|
| BNP Paribas |
| Barclays Bank PLC |
| Deutsche Factoring Bank |
| Société Générale S.A. |
| UniCredit |
| ING Group |
| Bibby Financial Services |
| Aldermore |
| Eurobank |
| Others |
Pricing and Supply Chain Analysis
Frankfurt and Paris clearing networks concentrate correspondent banking infrastructure, directing margin pools toward providers with ECB collateral eligibility and integrated trade finance corridors. Basel III tiering rules compress traditional bank lending capacity, elevating pricing power for non-bank specialists with alternative capital structures.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium non-recourse, standard recourse, and economy invoice discounting levels. Credit insurance integration and advance velocity differentiate tiers, with German automotive suppliers absorbing compressed spreads for predictable debtor portfolios while French exporters pay premiums for Southern European risk transfer. Pricing pressure stems from API-native platforms competing on speed rather than rate, squeezing margins for branch-dependent incumbents. SMEs exhibit highest price sensitivity, while investment-grade corporates negotiate near-benchmark spreads through parent guarantees.
Supply Chain Analysis
Third-party credit underwriters in London, Zurich, and Paris hold concentrated capacity for trade risk assessment. The ecosystem draws from data aggregators, automated scoring engines, and manual analyst pools for cross-border buyer evaluation. Single-source vulnerability runs through concentrated trade credit insurance markets with restricted appetite for emerging market exposures. Distribution runs through correspondent banking networks with euro-denominated settlement dominance across Central and Eastern European corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as Basel III redirects SME working capital demand from universal banks toward specialized providers. Digital origination platforms reduce unit acquisition costs, enabling scalable penetration of underserved segments.
For Market Incumbents: Harden defensive moats by deepening ERP integration partnerships with SAP and Oracle procurement modules, and by acquiring API-native technology stacks to match platform-based competitors on advance velocity. Regulatory capital advantages through ECB collateral eligibility must be leveraged before non-bank specialists build alternative funding structures. For New Entrants and Emerging Players: Baltic SME corridors in Estonia and Latvia represent the most penetrable entry point given sub-15% factoring penetration versus established Western European benchmarks. Central and Eastern European manufacturing subcontractors facing extended payment terms from German automotive OEMs offer concentrated origination volume. A direct API-embedded go-to-market approach bypasses legacy branch infrastructure entirely. For Investors and Strategic Acquirers: Capital is best deployed toward independent non-bank specialists with captive credit insurance relationships and scalable digital origination platforms. Long-term viability hinges on embedded finance convergence and sustainability-linked product differentiation. The signal to watch is EU Green Deal taxonomy extension to environmental performance-linked receivables purchasing as a distinct margin pool.| Strategic Initiative | Industry Significance |
|---|---|
| API-Driven ERP Integration | SAP and Oracle procurement modules now host native factoring origination workflows for German industrial clients. |
| Credit Insurance Partnership | Third-party underwriters in London and Zurich provide risk capacity for non-recourse structures on Southern European exposures. |
| Green Supply Chain Finance Launch | EU Green Deal classification frameworks enable preferential advance rates for sustainability-certified Nordic suppliers. |
| Baltic Market Expansion | Estonian and Latvian digital-native providers bypass branch infrastructure to capture unbanked receivables volume. |
| Reverse Factoring Program Scale | German automotive OEMs mandate supplier participation across tier-1 and tier-2 bases, capturing working capital yield spreads. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with factoring relationship managers, SME treasury directors, trade credit underwriters, and ERP platform integration specialists. Secondary validation drew from ECB collateral eligibility frameworks, EU Anti-Money Laundering Directive filings, BaFin and DNB prudential disclosures, and Basel Committee regulatory texts. Bottom-up receivables volume modeling triangulated against top-down banking sector flow-of-funds data.
Calibration anchored historical advance rate trends and credit loss experience against projected Basel III implementation timelines across the analysis window. Segmentation dimensions modeled include service type, client scale, industry vertical, and financing model structure, with regional regulatory cluster as an additional cross-cutting dimension. CAGRs derived from compounding annual advance volume growth adjusted for pricing compression and market share migration toward platform-based providers.
Practitioners should monitor ECB refinancing policy shifts and EU AI Act transparency mandate implementation for early signals of structural change. Forecasts reflect assumptions regarding regulatory capital treatment stability and trade credit insurance market depth. Quarterly review of SME lending survey data and factoring association volume reports is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Global Product Cost Management Market
Financial Services
United States Payroll Services Market
Financial Services
Broker Affiliate Programs Market
Financial Services
Billing and Revenue Management Market
Financial Services
Currency Management Market
Financial Services
Online Investment Platform Market
Financial Services
Capital Restructuring Services Market
Financial Services
Global Medical Equipment Financing Market
Financial Services
Source to Pay Market
Financial Services
North America B2C Legal Services Market
Financial Services
LAMEA Financial Services Software Market
Financial Services
Smart Finance Services Market
Financial Services
ATM Software Market
Financial Services
Australia Online Gambling Market
Financial Services
Italy Gift Card and Incentive Card Market
Financial Services
Africa Factoring Services Market