
 Esports Betting Market | 2026-2036
Esports Betting Market Size, Share, and Industry Trends Forecast 2026-2036
Esports Betting Market Insights
KYC and AML compliance certification is collapsing the barrier between traditional sportsbooks and esports-dedicated platforms. DraftKings leverages its daily fantasy infrastructure to anchor live betting liquidity across League of Legends and Counter-Strike tournaments. Betway specializes in endemic esports sponsorships that extend brand recognition into Southeast Asian markets. William Hill competes through odds-engine sophistication on first-person shooter matchups.
Esports betting comprises wagering on competitive video game outcomes through digital platforms that accept stakes on match results, player statistics, and in-game events. These systems integrate real-time data feeds from tournament servers to settle proposition bets within seconds of gameplay resolution. Live betting dominates transaction volume due to the rapid-fire nature of MOBA and fighting game rounds, while mobile apps capture the fastest-growing share of customer registrations by reducing friction for spectator-to-bettor conversion. Pre-match betting retains higher margin stability across sports simulation titles where historical performance data proves more predictive.
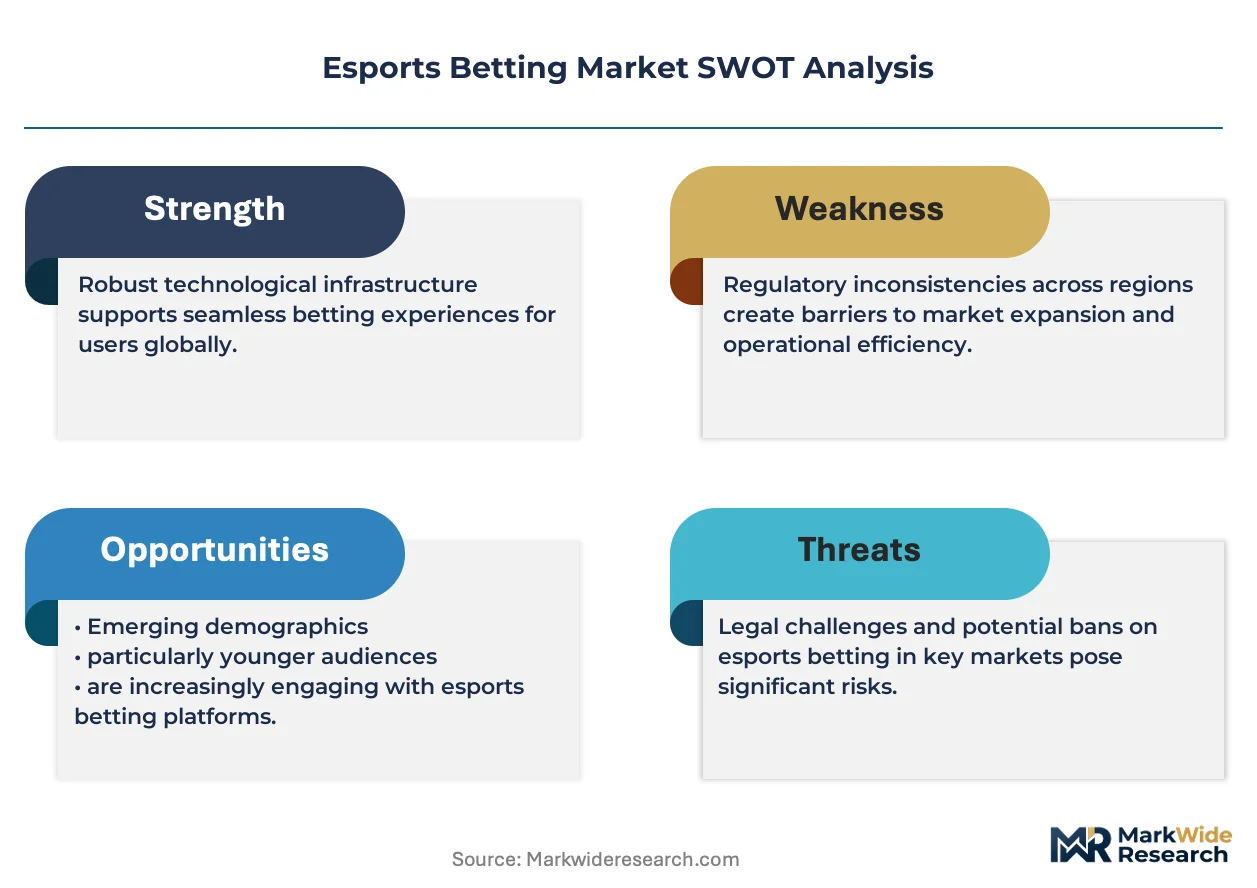
UK Gambling Commission licensing requirements shape product architecture by mandating affordability checks and cooling-off periods that increase operator compliance costs. Malta Gaming Authority frameworks influence platform technical standards for multi-jurisdictional European deployment. State gaming regulators in the United States impose divergent tax rates and integrity monitoring obligations that fragment market access. Stakeholders must track regulatory reciprocity negotiations between jurisdictions to anticipate where capital-light market entry remains viable versus where local partnership requirements escalate fixed costs.
Market Dynamics
Live betting infrastructure is compressing settlement latency from minutes to seconds, forcing operators to rebuild core platforms around real-time data pipelines rather than batch-processing architectures.
Growth Catalysts
- State-level legalization waves:New Jersey, Nevada, and Colorado gaming commissions have established licensing frameworks that validate esports as a regulated wagering category, creating precedent for neighboring jurisdictions.
- Mobile-first user acquisition:Native app deployment on iOS and Android platforms reduces friction for spectator-to-bettor conversion, particularly among 18-34 demographics.
- Affordability check mandates:UK Gambling Commission requirements for deposit limits and cooling-off periods are normalizing responsible gambling features that expand addressable user bases.
Market Restraints
- Integrity monitoring costs:Tournament data feed licensing and anti-corruption surveillance impose fixed operational burdens that scale poorly for smaller operators.
- Jurisdictional fragmentation:Divergent tax rates and partnership requirements across US state regulators fragment market access and escalate compliance overhead.
- Latency arbitrage risks:Sub-second data transmission advantages for co-located traders threaten retail bettor confidence in fair pricing.
Strategic Opportunities
- Brazilian regulatory opening:ANVISA and federal gaming framework discussions signal potential for Latin America's largest addressable digital population.
- Virtual reality spectator integration:Immersive viewing environments create natural insertion points for in-experience wagering interfaces.
- Artificial odds generation:Machine learning models trained on historical match data enable markets for emerging titles lacking established competitive circuits.
Industry Challenges
- Esports-specific trading talent scarcity:Quantitative analysts with simultaneous expertise in MOBA mechanics and probabilistic modeling command premium compensation.
- Legacy core system retrofitting:Traditional sportsbook architectures require fundamental redesign to handle micro-bet settlement velocities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Esports Betting Market |
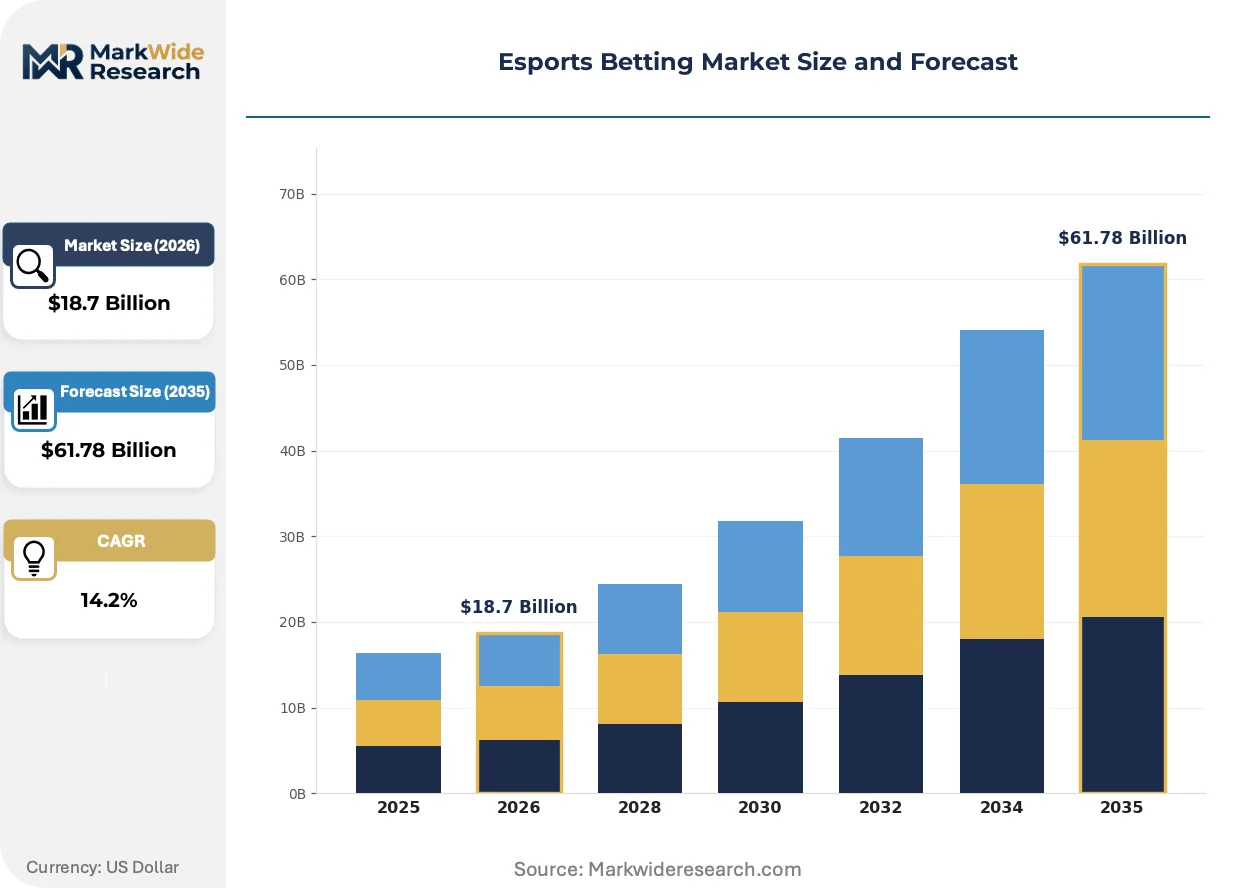
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Betting Type: Live Betting, Pre-Match Betting, Exchange Betting, Over/Under Betting Game Type: MOBA, First-Person Shooter, Sports Simulation, Fighting Platform Type: Mobile Apps, Web Platforms, Betting Shops, E-Sports Streaming Services Customer Group: Professional Gamers, Casual Enthusiasts, Spectators, Affiliates |
| Companies Covered | Bet365, DraftKings, Betway, Pinnacle, Unikrn, William Hill, 888 Holdings, Rivalry, Kindred Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Esports Betting Market Trends and Innovations
Real-time data infrastructure is redefining competitive advantage, with operators investing in direct server connections and proprietary latency reduction rather than marketing spend differentiation.
Blockchain-based settlement rails are supplanting conventional payment processors for high-velocity micro-transactions. Southeast Asian operators deploy these systems to circumvent correspondent banking delays. The structural compression of settlement friction is enabling bet types previously uneconomical at sub-dollar stakes.
EU AI Act transparency requirements are mandating algorithmic audit trails for odds-generation engines. Operators serving European markets must document model training data and decision boundaries. First-person shooter betting products face the steepest compliance redesign due to higher model complexity in player-performance prediction.
Social betting features embedded within streaming platforms are displacing standalone app downloads as the primary acquisition channel. Twitch and YouTube integrations allow wager placement without platform switching. This behavioral shift concentrates most visibly in North American markets where platform co-viewing rates exceed global averages.
Esports Betting Market Segmentation
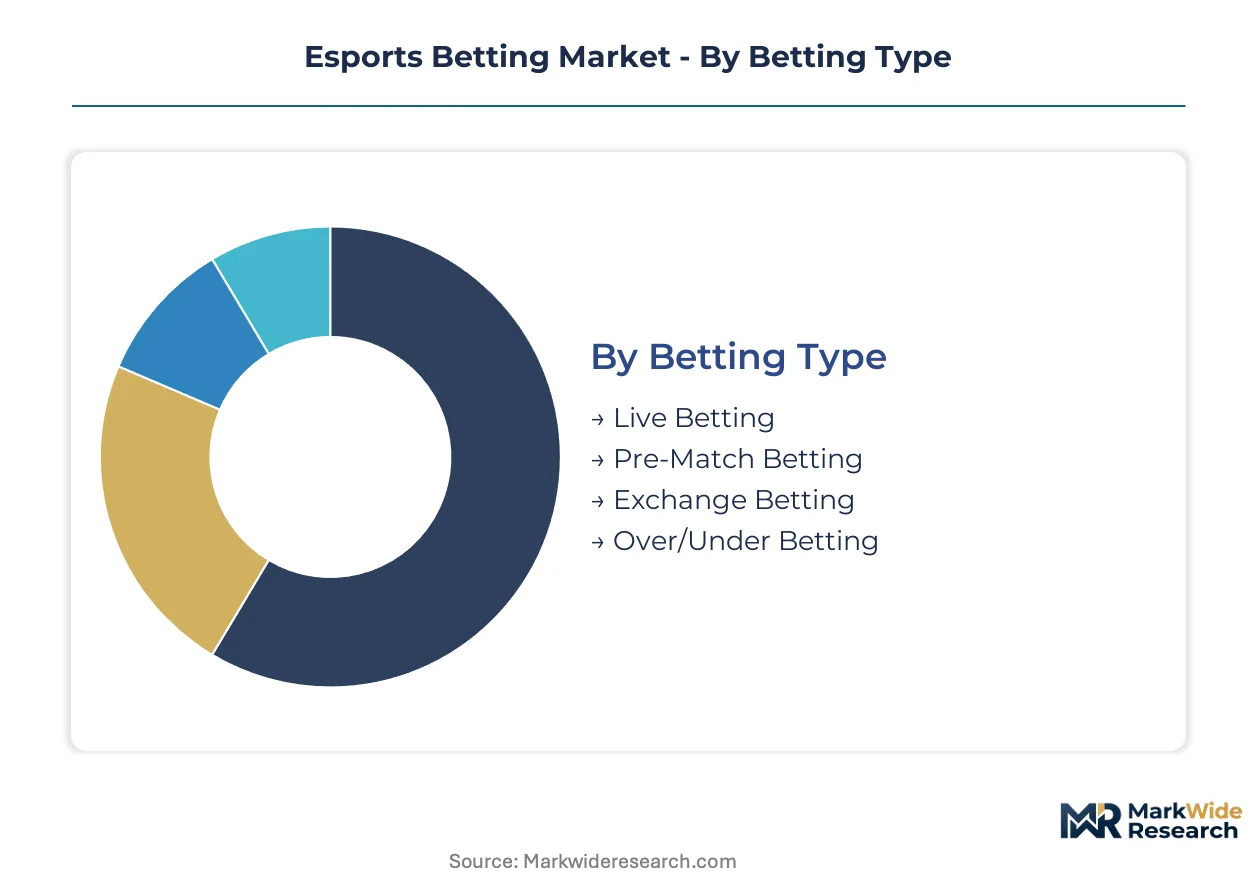
Esports betting segmentation reveals how distinct wagering behaviors, game mechanics, and platform preferences create divergent margin profiles and compliance burdens. Operators must align product architecture with specific segment velocity requirements rather than deploying uniform infrastructure.
Betting Type:
Live betting faces the most acute substitution pressure from exchange models that offer peer-to-peer pricing and reduced house-edge exposure.
- Live Betting:Real-time wagering settles on sub-second data feeds from tournament servers, with latency arbitrage risks compressing operator margins. Demand concentrates in MOBA and first-person shooter tournaments across Nevada and New Jersey where state regulators have approved in-play frameworks.
- Pre-Match Betting:Fixed-odds markets established before competition start retain higher margin stability through historical data predictability. Sports simulation titles drive volume here as performance metrics prove more reliable than volatile player form in battle royale formats.
- Exchange Betting:Peer-to-peer platforms eliminate traditional bookmaker risk by matching opposing positions directly.
- Over/Under Betting:Totals markets on kill counts, round durations, or map scores attract quantitative-oriented bettors.
Pre-match betting anchors the volume base while live betting gains share at the steepest rate.
Game Type:
Cost tier differentiation separates premium tournament circuits with dedicated integrity monitoring from grassroots competitions with higher match-fixing exposure.
- MOBA:Multiplayer online battle arenas like League of Legends and Dota 2 generate the highest live betting velocity through continuous teamfight action. Southeast Asian markets dominate volume as mobile-first MOBA titles such as Mobile Legends penetrate lower-income demographics.
- First-Person Shooter:Counter-Strike and Valorant rounds resolve in minutes, enabling rapid-fire micro-bet settlement that strains legacy sportsbook architectures. North American demand clusters around major tournament circuits with ESPN broadcast partnerships.
- Sports Simulation:FIFA and NBA 2K betting appeals to traditional sports bettors seeking familiar statistical frameworks.
- Fighting:Street Fighter and Tekken tournaments attract concentrated wagering from dedicated communities with deep mechanical knowledge.
First-person shooter competitions command the highest per-user betting frequency while MOBA tournaments deliver the broadest geographic reach.
Platform Type:
Volume concentration tilts heavily toward mobile-native deployments as customer acquisition economics favor reduced download friction over desktop sophistication.
- Mobile Apps:Native iOS and Android deployments capture the fastest-expanding user base through biometric authentication and push-notification engagement. UK Gambling Commission affordability check mandates have normalized responsible gambling features that expand addressable demographics.
- Web Platforms:Browser-based access retains importance for multi-account arbitrageurs and professional bettors requiring simultaneous market monitoring.
- Betting Shops:Physical retail presence persists in jurisdictions with restrictive online licensing.
- E-Sports Streaming Services:Twitch and YouTube embedded wagering interfaces displace standalone app downloads as primary acquisition channels.
Mobile apps anchor the volume base while streaming-integrated betting expands most quickly.
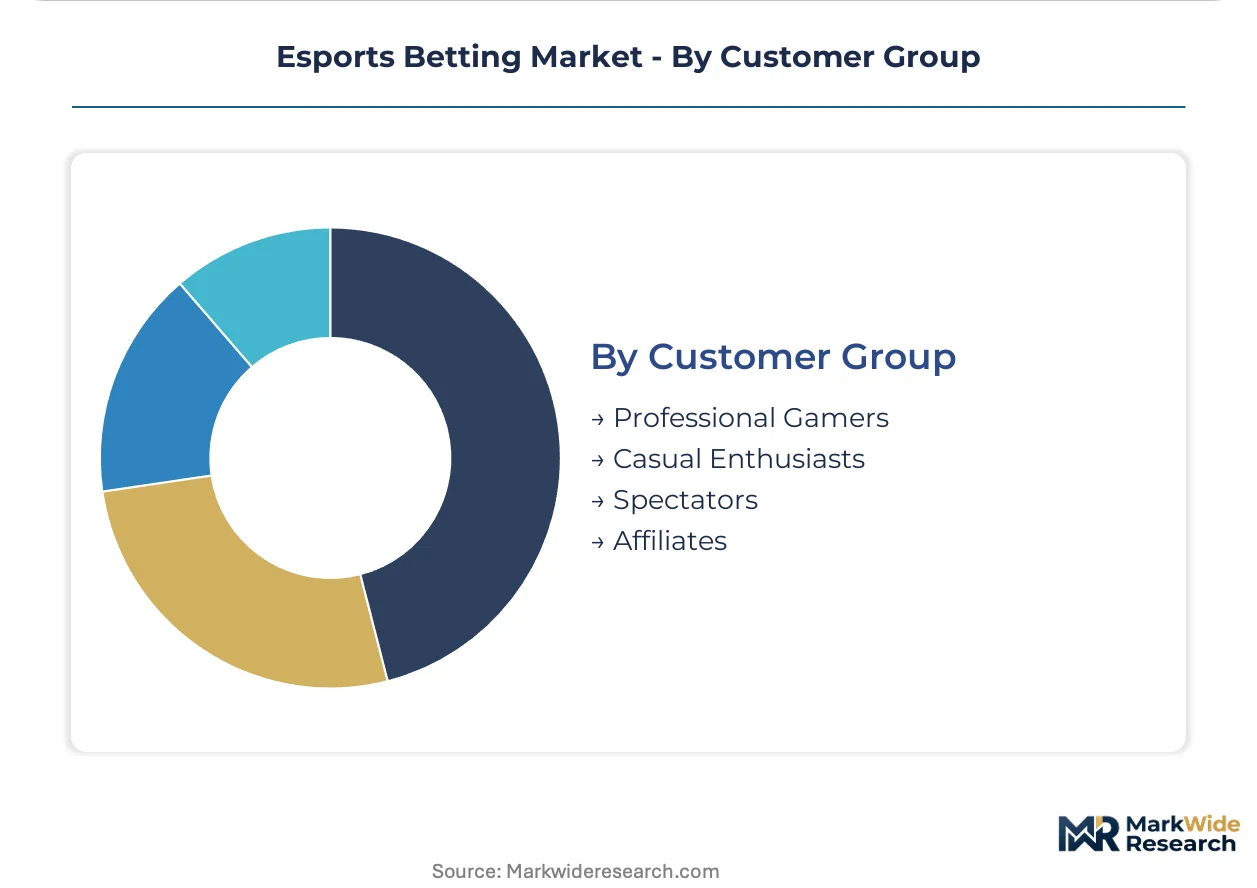
Customer Group:
Application maturity separates established professional segments with predictable lifetime value from emerging casual cohorts requiring higher education investment.
- Casual Enthusiasts:Spectator-to-bettor converts with limited wagering history drive mobile app download surges and social betting feature adoption. Colorado and Illinois state frameworks specifically target this demographic through deposit limit requirements and cooling-off period mandates.
- Professional Gamers:Elite competitors with direct tournament access face strict integrity prohibitions on self-betting but influence affiliate-driven referral volume.
- Spectators:Non-playing viewers constitute the largest addressable pool for conversion campaigns.
- Affiliates:Content creators and tipster communities generate cost-per-acquisition efficiency through trusted recommendation channels.
Spectators anchor the volume base while casual enthusiasts climb the fastest as legalization normalizes mainstream participation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level legalization frameworks in the United States have established regulatory templates that neighboring jurisdictions are rapidly adopting. Patchwork compliance requirements across federal systems are forcing operators to deploy modular platform architectures capable of rapid jurisdictional reconfiguration.
United States
New Jersey gaming commission approvals for League of Legends wagering created precedent that Colorado and Illinois regulators have extended to additional titles. State-by-state tax rate divergence between Nevada's established framework and newer entrants like Virginia fragments operator margin structures. The Las Vegas-Atlantic City corridor concentrates platform development talent and integrity monitoring infrastructure.
United Kingdom
UK Gambling Commission affordability mandates have normalized deposit limits and cooling-off periods that expand addressable demographics beyond problem-gambling risk profiles. Advertising Standards Authority restrictions on esports betting promotions during livestreams reshape customer acquisition economics. London-based trading floors anchor European liquidity for first-person shooter tournaments.
Germany
Interstate Treaty on Gambling harmonization efforts are creating federal clarity where previous state-level fragmentation impeded market entry. KBA oversight of advertising content restricts bonus-driven acquisition tactics that dominate less regulated markets. The Frankfurt-Rhine-Main cluster hosts data feed aggregators serving Central European tournament circuits.
South Korea
Game Industry Promotion Act amendments are clarifying boundaries between skill-based gaming and prohibited gambling that previously chilled operator investment. MFDS-aligned consumer protection standards influence platform design for younger demographic protections. Seoul's Gangnam district concentrates esports production facilities that generate real-time data for wagering infrastructure.
Brazil
Federal gaming framework discussions signal potential normalization of esports wagering within Latin America's largest digital population. ANVISA consultation processes on loot box mechanics indirectly shape regulatory sentiment toward probabilistic gaming mechanics. São Paulo's Pinheiros district hosts tournament production studios developing integrity monitoring partnerships with international operators.
Esports Betting Market Competitive Landscape
Player mix skews toward diversified gambling conglomerates with legacy sportsbook infrastructure repurposed for esports velocity requirements. Market structure exhibits tiered consolidation where daily fantasy operators, endemic esports specialists, and traditional bookmakers occupy distinct competitive positions. Strategic archetypes separate liquidity-anchoring platforms with broadcast partnerships, sponsorship-heavy endemic brands, and odds-engine specialists. Dominant competitive moves include direct server data feed exclusivity arrangements and mobile-native platform rebuilds replacing legacy batch-processing architectures.
Among UK-based gambling conglomerates, Bet365 and William Hill occupy positions exemplifying the diversified infrastructure archetype, leveraging established compliance frameworks across multiple regulatory jurisdictions. DraftKings represents the daily fantasy crossover segment, while Betway anchors the endemic sponsorship-heavy specialist tier. These three patterns illustrate how regulatory licensing breadth, content acquisition strategy, and technical architecture choices separate viable competitors from capital-constrained entrants.
| Leading Market Players |
|---|
| Bet365 |
| DraftKings |
| Betway |
| Pinnacle |
| Unikrn |
| William Hill |
| 888 Holdings |
| Rivalry |
| Kindred Group |
| Others |
Pricing and Supply Chain Analysis
Real-time data feed substitution for traditional batch-processing architectures is simultaneously redrawing supply geography toward server-co-located hubs and compressing pricing power at legacy sportsbook tiers. This infrastructure migration concentrates procurement leverage among operators with direct tournament server connections, while latency arbitrage risks force margin reinvestment into proprietary pipeline technology.
Pricing Analysis
Certification level creates the primary spread between UK Gambling Commission-licensed tiers and unregulated offshore alternatives. The dominant structure runs subscription-based SaaS tiers for platform access plus per-transaction revenue shares on wager volume. Price differentiation stems from integrity monitoring depth and KYC automation sophistication, with UKGC-mandated affordability checks commanding premium positioning. Cost compression in the mid-tier is intensifying because mobile-native entrants are undercutting legacy web-platform pricing. Casual enthusiasts show highest price sensitivity to deposit fees, while professional affiliates prioritize liquidity depth over commission rates.
Supply Chain Analysis
Trans-Pacific cable latency and Singapore port congestion are elevating inbound data costs for Southeast Asian operators seeking European tournament feeds. Geographic concentration centers on Malta for platform licensing infrastructure, the United Kingdom for trading talent pools, and South Korea for esports production facilities. Raw material dependencies encompass server-grade fiber connectivity, GPU clusters for odds-generation engines, and proprietary data feed licenses from tournament organizers. Single-source vulnerability runs through exclusive server-access agreements with major game publishers. Distribution runs through mobile app stores and embedded streaming platform integrations rather than direct-download channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Esports betting platforms represent a service-attach opportunity where real-time data infrastructure subscriptions and integrity monitoring services are expanding faster than core wagering revenue. Recurring technology licensing layers are capturing disproportionate value as operators outsource latency reduction and compliance automation.
For Market Incumbents: Consolidate through exclusive data feed arrangements with Riot Games and Valve Corporation that lock out challenger platforms from sub-second settlement capabilities. Acquire specialist odds-generation boutiques in London and Seoul to capture scarce quantitative talent before compensation inflation erodes margin structures. Regulatory fragmentation across US state lines threatens scale economics; modular platform architectures enable rapid jurisdictional reconfiguration without full rebuilds. For New Entrants and Emerging Players: Lead with blockchain-based settlement rails in Brazilian and Southeast Asian markets where correspondent banking delays create addressable friction. Brazil's federal gaming framework discussions offer the most penetrable regulatory opening in Latin America. Target mobile-first casual enthusiasts through TikTok-embedded wagering interfaces that bypass standalone app store acquisition costs entirely. For Investors and Strategic Acquirers: Secondary-cycle assets sit with daily fantasy crossover platforms that have exhausted sportsbook migration synergies but retain valuable state-level licensing footprints. Five-to-ten year viability hinges on regulatory reciprocity expansion rather than title-by-title legalization battles. Watch for UK Gambling Commission reciprocity negotiations with emerging European frameworks as the signal for capital-light market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Server Data Exclusivity | Sub-second latency advantages from Riot Games partnerships lock in liquidity leadership against exchange competitors. |
| Mobile-Native Platform Rebuild | iOS and Android-first architectures reduce spectator-to-bettor conversion friction below legacy web-platform economics. |
| Integrity Monitoring Partnership | ESIC-aligned surveillance investments satisfy Nevada and New Jersey regulatory mandates while deterring match-fixing exposure. |
| Blockchain Settlement Integration | Distributed ledger rails circumvent correspondent banking delays for high-velocity micro-transactions in Southeast Asian markets. |
| Streaming Platform Embedding | Twitch and YouTube native wagering interfaces displace standalone downloads as primary North American acquisition channels. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of UK Gambling Commission enforcement actions, state gaming regulator licensing databases, and tournament organizer data partnership disclosures. Primary interviews engaged platform engineering directors, esports trading desk heads, regulatory compliance officers, and integrity monitoring specialists across Malta, London, and Seoul. Secondary validation drew from SEC filings of listed gambling conglomerates, Nevada Gaming Control Board public records, and European Gaming and Betting Association white papers. Bottom-up segment sizing triangulates against top-down market value reconciliation.
Segmentation dimensions modeled encompass betting type, game genre, platform deployment mode, and customer sophistication tier across the analysis window. CAGRs derive from regression analysis against mobile adoption curves and state-level legalization trajectories. Forecast inputs incorporate tournament prize pool growth as proxy for wagering interest velocity and 5G penetration rates as mobile latency reduction driver.
Forecasts assume regulatory continuity in UK Gambling Commission and Nevada Gaming Control Board frameworks; material policy shifts would require re-modeling. Specific risks include US federal gambling prohibition revival, EU AI Act algorithmic audit enforcement escalation, and publisher data access revocation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Media and Entertainment
Digital Entertainment in the Home Market
Media and Entertainment
Global Programmatic Advertisement Market
Media and Entertainment
United Kingdom Public Relation Services Market
Media and Entertainment
Global Esports Market
Media and Entertainment
Europe Social Media Analytics Market
Media and Entertainment
Gaming Hardware Market
Media and Entertainment
Adtech Market
Media and Entertainment
Discography Market
Media and Entertainment
Digital Out of Home (OOH) Advertising Market
Media and Entertainment
Brazil Animation, VFX and Post Production Market
Media and Entertainment
Galgames Market
Media and Entertainment
Qatar OOH and DOOH Market
Media and Entertainment
North America Online Gambling Market
Media and Entertainment
Independent Music Publishing Market
Media and Entertainment
Asia Pacific Photography Service Market
Media and Entertainment
Philippines OOH and DOOH Market