
 English Learning for Children Market | 2026-2036
English Learning for Children Market Size, Share, and Industry Trends Forecast 2026-2036
English Learning for Children Market Insights
Subscription bundling is pivoting how parents evaluate English learning platforms, with all-in-one packages now combining live tutoring, AI chatbots, and progress dashboards into single household accounts. Duolingo leverages gamification mechanics to sustain engagement among early readers. Rosetta Stone anchors its position through immersive speech-recognition labs for intermediate learners. Lingokids specializes in character-driven storytelling modules that dominate the preschool segment.
English learning for children encompasses structured language acquisition programs designed for cognitive development stages from ages two through fourteen, typically incorporating spaced repetition algorithms, phonemic awareness sequencing, and adaptive difficulty scaling to match neuroplasticity windows. The primary commercial purpose is building communicative competence before critical language acquisition periods close. Interactive apps command the largest user base due to smartphone penetration in emerging economies, while hybrid learning captures the strongest margin pools by blending synchronous teacher contact with asynchronous AI drills. Physical books remain mature in Western Europe but face displacement from educational games in East Asian markets.
China's MIIT mandates real-name registration and content screening for all educational apps serving minors, creating compliance barriers for foreign platforms. India's TRAI data-localization expectations and BIS quality certification for imported digital content shape market entry strategies for international providers. GDPR in Europe restricts behavioral profiling of children under sixteen, limiting personalization depth that vendors can deploy. Stakeholders must weigh regulatory compliance costs against localization investments when selecting priority expansion markets.
Market Dynamics
Generative AI is compressing content production cycles for English learning platforms, enabling personalized curriculum generation at marginal cost near zero while forcing legacy providers to restructure their human tutor dependencies.
Growth Catalysts
- India's urban middle-class expansion:Tier-1 and Tier-2 cities demonstrate sustained appetite for premium subscription models bundling live instruction with asynchronous practice tools.
- MIIT content licensing mandates:China's enforcement of real-name registration and pre-screening requirements for educational apps serving minors has legitimized compliant foreign entrants while filtering speculative operators.
- Spaced repetition algorithms:Neuroplasticity-matched difficulty scaling now anchors product roadmaps for platforms targeting ages two through seven.
Market Restraints
- GDPR Article 8 restrictions:Europe's prohibition on behavioral profiling of children under sixteen caps personalization depth that vendors can deploy, compressing engagement metrics versus less regulated markets.
- Input cost volatility in cloud compute:GPU-intensive speech recognition and generative model inference face pricing pressure from concentrated hyperscaler supply.
- Substitution by informal content:YouTube and TikTok creator economies deliver zero-cost English exposure, eroding paid conversion for basic vocabulary acquisition tiers.
Strategic Opportunities
- Underpenetrated rural India:Low-cost, offline-capable Android applications with vernacular UI layers represent unclaimed addressable base outside metropolitan tutoring corridors.
- AI-human hybrid orchestration:Convergence of synchronous video tutoring with real-time generative feedback loops enables premium pricing tiers previously unsupported by either modality alone.
- BIS quality certification pathway:India's standards body creates defensible positioning for imported digital content meeting localized curriculum alignment requirements.
Industry Challenges
- Speech data annotation talent scarcity:Child-accented English corpora require specialized phonetic transcribers, creating recruitment bottlenecks for adaptive pronunciation features.
- Cross-border content localization capex:Curriculum alignment with India's NCERT, China's PEP, and individual US state standards demands parallel investment streams without guaranteed adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | English Learning for Children Market |
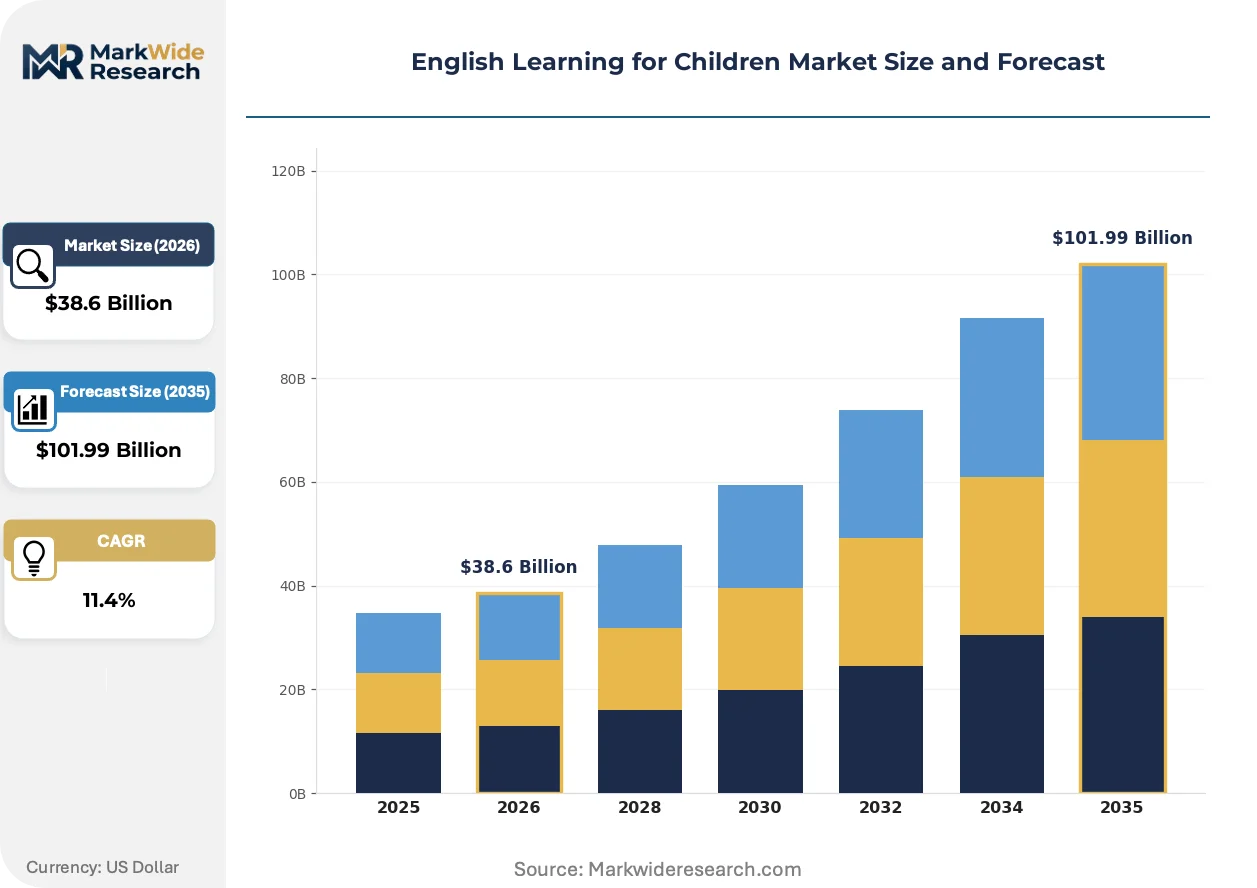
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interactive Apps, Online Courses, Physical Books, Educational Games Age Group: Preschoolers, Early Readers, Intermediate Learners, Advanced Learners Delivery Mode: Hybrid Learning, Virtual Classes, Face-to-Face Tutoring, Self-Paced Learning Content Type: Storytelling, Phonics, Vocabulary Building, Grammar Exercises |
| Companies Covered | Duolingo, Rosetta Stone, Memrise, Lingokids, Babbel, Busuu, Novakid, Studycat Limited, Helen Doron English, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
English Learning for Children Market Trends and Innovations
Adaptive learning infrastructure is shifting from rule-based engines to transformer-architecture personalization, compressing the feedback loop between learner error detection and remediation delivery from hours to milliseconds.
Multimodal large language models are electrifying interactive storytelling for early readers. Character-driven narrative engines now generate contextually appropriate vocabulary scaffolding in real-time. Preschool-focused platforms deploy these systems to sustain session duration metrics previously achievable only through human instructor presence. The structural consequence is collapsing the cost curve for immersive English exposure at the critical two-to-seven age window.
Europe's GDPR enforcement through national data protection authorities is hardening consent requirements for educational technology. Platforms must now demonstrate explicit parental authorization workflows before activating behavioral analytics. Vendors serving the UK, Germany, and France are responding by relocating inference processing to EU-based infrastructure and truncating data retention periods, elevating operational complexity against less regulated competitors.
Parental evaluation criteria are pivoting from content volume metrics to proficiency outcome guarantees. Subscription purchasers increasingly demand visible progress markers aligned with international standards such as CEFR or Cambridge Young Learners. This certification-driven preference shift is most visible in South Korea and Vietnam, where after-school English programs compete on measurable advancement rather than engagement hours alone.
English Learning for Children Market Segmentation
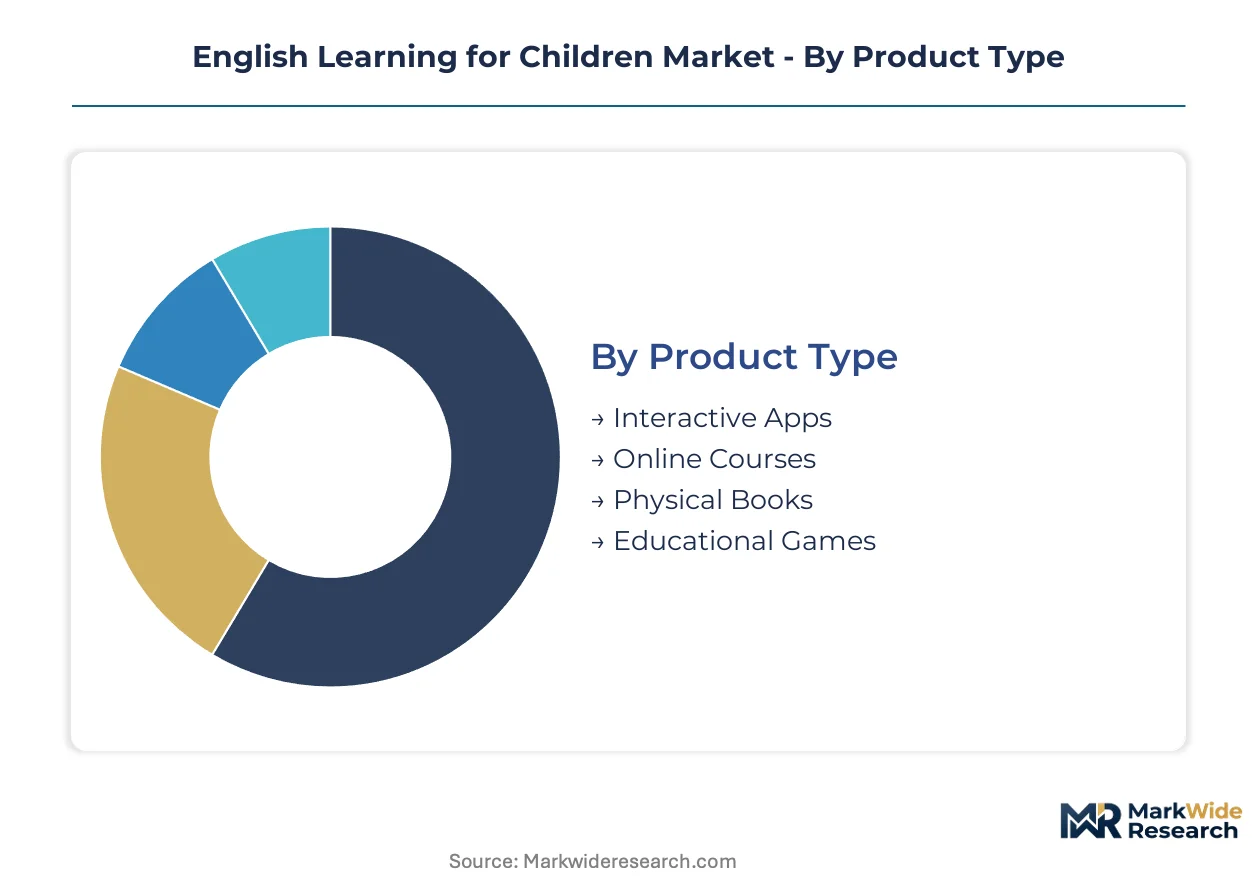
English learning providers face divergent technical requirements across cognitive development stages and parental purchasing patterns. Segment-specific product design determines conversion rates, session duration metrics, and lifetime value calculations in this $38.6 billion market.
Product Type:
Parental willingness-to-pay scales with perceived interactivity depth and real-time feedback capability.
- Interactive Apps:Smartphone-native platforms deploy spaced repetition algorithms and gamification mechanics to sustain engagement among early readers. Demand concentrates in India, where urban middle-class families purchase premium subscriptions bundling AI chatbots with progress dashboards.
- Online Courses:Structured curricula delivered through synchronous video instruction target intermediate learners seeking measurable proficiency outcomes. South Korean and Vietnamese households drive conversion through certification-driven purchasing criteria aligned with CEFR standards.
- Physical Books:Print-based phonics and vocabulary materials retain steady adoption in Western Europe despite displacement pressure from digital alternatives in East Asian markets.
- Educational Games:Character-driven narrative modules dominate preschool segments through immersive storytelling that collapses cost curves for English exposure at critical neuroplasticity windows.
Interactive Apps lead on scale; Educational Games lead on momentum.
Age Group:
Curriculum complexity and pricing tiers map directly to closing windows for critical language acquisition periods.
- Preschoolers:Platforms targeting ages two through five emphasize phonemic awareness sequencing and multimodal sensory engagement. China's MIIT content licensing mandates shape product architecture for foreign entrants serving this demographic.
- Early Readers:Structured literacy programs bridge pre-reading skills to independent comprehension, with adaptive difficulty scaling matched to individual pace.
- Intermediate Learners:Speech-recognition labs and grammar scaffolding dominate product roadmaps as children transition from decoding to fluent communication.
- Advanced Learners:Academic writing, debate formats, and standardized test preparation command premium pricing in competitive examination markets.
Early Readers captures the largest addressable base; Preschoolers shows the steepest expansion trajectory.
Delivery Mode:
Margin structure varies dramatically based on human instructor time allocation versus AI automation ratios.
- Hybrid Learning:Blended synchronous tutoring with asynchronous AI drills captures the strongest margin pools through premium household account pricing. India's Tier-1 and Tier-2 cities demonstrate sustained appetite for this bundled model.
- Virtual Classes:Group video instruction with real-time generative feedback loops enables cost-efficient delivery at intermediate scale points.
- Face-to-Face Tutoring:In-person instruction retains pricing power in high-density metropolitan corridors where parental trust in human presence persists.
- Self-Paced Learning:Fully automated pathways serve price-sensitive segments and rural penetration strategies requiring offline-capable Android deployment.
Hybrid Learning leads on margin contribution; Self-Paced Learning leads on geographic expansion potential.
Content Type:
Parental evaluation criteria increasingly prioritize visible progress markers over engagement hours alone.
- Storytelling:Narrative-driven vocabulary acquisition leverages transformer-architecture personalization to generate contextually appropriate scaffolding in real-time. GDPR Article 8 restrictions in Europe cap behavioral profiling depth for this content category.
- Phonics:Systematic sound-letter correspondence instruction anchors foundational literacy for early readers across all major markets.
- Vocabulary Building:Spaced repetition systems with child-accented speech recognition face annotation talent scarcity for adaptive pronunciation features.
- Grammar Exercises:Rule-based remediation and error detection now compress feedback loops from hours to milliseconds through generative AI deployment.
Vocabulary Building leads on user engagement frequency; Storytelling leads on session duration extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The English learning for children industry traces its modern commercial roots to North American edtech pioneers who digitized language pedagogy for mass-market distribution. Digital platforms now serve learners across diverse regulatory environments, with market maturity varying sharply by national income levels and government oversight intensity.
United States
Parental demand concentrates on proficiency outcome guarantees aligned with standardized testing frameworks. The Children's Online Privacy Protection Act enforces strict data collection limits for platforms serving users under thirteen. Silicon Valley and Austin host the densest clusters of venture-backed adaptive learning startups deploying generative AI for real-time feedback.
China
Urban middle-class households sustain premium spending on live tutoring despite regulatory compression of after-school training hours. MIIT mandates real-name registration and content pre-screening for all educational apps targeting minors. Beijing and Shanghai retain concentrated demand for hybrid learning models blending synchronous instruction with AI-powered drills.
India
Tier-1 and Tier-2 cities demonstrate sustained appetite for subscription bundles combining live tutoring with asynchronous practice tools. TRAI data-localization expectations and BIS quality certification for imported digital content shape market entry strategies for international providers. Bengaluru and Hyderabad emerge as hubs for vernacular-language platform localization serving rural penetration strategies.
Germany
CEFR-aligned certification requirements drive parental evaluation criteria toward measurable advancement metrics. GDPR Article 8 restrictions cap behavioral profiling depth for personalization engines serving children under sixteen. Berlin and Munich concentrate edtech development focused on privacy-preserving adaptive difficulty scaling.
South Korea
After-school English programs compete intensely on visible progress markers tied to international examination standards. The national curriculum alignment expectations from the Ministry of Education shape content localization investments for foreign platform entrants. Seoul's metropolitan corridor commands premium pricing for hybrid learning models with human instructor presence.
English Learning for Children Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the interactivity-real-time feedback dimension, with hybrid learning commanding household account pricing that self-paced applications cannot match. The vendor base fragments across gamified mobile platforms, immersive speech-recognition specialists, and character-driven preschool storytellers. Three archetypes dominate: AI-native challengers compressing content production cycles, legacy incumbents restructuring human tutor dependencies, and regional specialists navigating localized curriculum alignment. Competitive moves center on generative AI licensing partnerships and geographic expansion through regulatory compliance rather than speculative market entry.
Within the AI-native challenger tier, Duolingo and Lingokids exemplify divergent engagement architectures. Duolingo, a Pittsburgh-based entity, occupies a position anchored in gamification mechanics for sustained early-reader retention. Lingokids, a Spanish-originated platform, sits within the character-driven storytelling archetype dominating preschool segments through multimodal narrative engines. Rosetta Stone, a Virginia-based legacy incumbent, represents the immersive speech-recognition laboratory model targeting intermediate learners with premium pricing power.
| Leading Market Players |
|---|
| Duolingo |
| Rosetta Stone |
| Memrise |
| Lingokids |
| Babbel |
| Busuu |
| Novakid |
| Studycat Limited |
| Helen Doron English |
| Others |
Pricing and Supply Chain Analysis
GPU cloud compute pricing indices from hyperscalers cascade through English learning platform cost structures, compressing margins on AI-powered tutoring tiers while enabling premium pricing for hybrid human-AI bundles that offset infrastructure spend.
Pricing Analysis
Subscription bundling across household accounts anchors the dominant pricing architecture, with premium tiers commanding three-to-five-fold multiples over economy self-paced plans based on live instructor hours and generative AI feedback density. Price differentiation hinges on CEFR certification alignment and real-time speech recognition depth. Pricing pressure intensifies in basic vocabulary tiers as YouTube and TikTok creator economies deliver zero-cost substitutes. Rural Indian households exhibit highest price sensitivity; Seoul metropolitan corridor buyers demonstrate lowest.
Supply Chain Analysis
BIS quality certification and MIIT content licensing function as gating mechanisms that filter platform entrants and concentrate compliant supply among established providers with localization infrastructure. Cloud compute supply concentrates in the United States, Ireland, and Singapore. Child-accented English speech corpora and transformer model inference capacity constitute critical input dependencies. Single-source vulnerability runs through NVIDIA GPU allocation for generative AI features. Distribution runs through direct-to-consumer app stores and institutional licensing to K-12 districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in English learning platforms rests on generative AI collapsing content production costs while hybrid learning tiers sustain premium household pricing. AI-native challengers and legacy incumbents both capture this spread through divergent cost structures.
For Market Incumbents: Deepen vertical integration into child-accented speech data annotation to secure scarce phonetic transcription talent. Fortify hybrid learning margin pools by expanding synchronous instructor networks in India's Tier-1 cities while deploying generative AI for asynchronous drill automation. Defend against AI-native challengers by accelerating CEFR certification pathways that command parental trust.
For New Entrants and Emerging Players: Rural Indian households with vernacular-language Android devices represent the most penetrable white-space segment. Low-cost offline-capable applications bypass metropolitan tutoring corridor saturation. Target BIS quality certification as a go-to-market wedge to unlock institutional procurement channels.
For Investors and Strategic Acquirers: Asymmetric upside sits with AI-native challengers possessing transformer-architecture personalization engines and established speech recognition pipelines. Long-term viability favors platforms with demonstrated compliance navigation across MIIT, GDPR, and BIS regimes. Watch for inflection in parental demand for measurable proficiency guarantees versus engagement metrics.
| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Curriculum Engine Deployment | Compresses content production costs toward marginal zero while enabling real-time personalization at scale. |
| MIIT Compliance Infrastructure Buildout | Unlocks access to China's urban middle-class premium segment through real-name registration and pre-screening capabilities. |
| Hybrid Learning Tier Expansion | Captures strongest margin pools by blending synchronous video tutoring with AI-powered asynchronous drills. |
| BIS Certification Pathway Investment | Creates defensible positioning for imported digital content in India's institutional procurement channels. |
| Rural India Vernacular Localization | Addresses unclaimed addressable base outside metropolitan tutoring corridors through offline-capable Android deployment. |
Research Methodology
Direct dialogue with platform product managers, curriculum localization specialists, K-12 district procurement officers, and regulatory compliance consultants grounded qualitative findings. Secondary validation drew from MIIT filing disclosures, TRAI consultation papers, GDPR enforcement actions by national data protection authorities, and hyperscaler capex disclosures. Bottom-up and top-down triangulation cross-checked segment sizing against aggregate market estimates.
Bottom-up modeling aggregated platform subscription data, regional pricing surveys, and institutional licensing volumes across product type, age group, delivery mode, and content type dimensions. Top-down analysis calibrated aggregate market expansion against macro drivers including urban middle-class formation, smartphone penetration curves, and regulatory compliance cost burdens. CAGRs derived from segment-level growth rate convergence and cross-validation against edtech venture financing velocity.
Inputs from regulatory filing databases and platform usage metrics were available through the study window; gaps in rural penetration data and informal content substitution rates introduce uncertainty bands around price-sensitive segment forecasts. Forecasts reflect assumptions regarding MIIT enforcement consistency, GPU supply availability, and parental preference shifts toward certification-aligned purchasing. A model refresh is warranted upon material change in generative AI inference cost trajectories or GDPR Article 8 interpretation by European national authorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Language Learning and Training
Cloud Based Language Learning Market
Language Learning and Training
Language Learning Software Market
Language Learning and Training
Global Language Service Market
Language Learning and Training
English Learning App Market
Language Learning and Training
Language Learning Games Market
Language Learning and Training
Digital English Learning Market
Language Learning and Training
Online Language Learning Market
Language Learning and Training
Bilingual Education for Children Market
Language Learning and Training
Global Digital English Language Learning Market
Language Learning and Training
Vocational English Course Counselling Solution Market