
 Elevator and Escalator Market | 2026-2036
Elevator and Escalator Market Size, Share, and Industry Trends Forecast 2026-2036
Elevator and Escalator Market Intelligence
Capital-intensity divergence between full-service OEMs and component-reliant assemblers is redrawing competitive boundaries in vertical transportation. KONE Corporation leverages its in-house manufacturing of hoisting machinery to sustain margin control across service contracts. Otis anchors its position through extensive maintenance network density in North American urban corridors. Schindler Group differentiates via digital predictive maintenance platforms that reduce downtime for facility operators.
Elevators and escalators are electromechanical vertical transportation systems engineered to move passengers and freight between building floors, with traction systems employing steel ropes and counterweights rated for speeds exceeding 10 m/s in super-tall structures. Their primary commercial purpose centers on enabling safe, efficient circulation in structures where stair access proves impractical due to height, traffic volume, or accessibility requirements. Passenger elevators dominate installed base value across commercial buildings, while machine-room-less traction technology is displacing hydraulic systems in mid-rise construction due to reduced shaft footprint and energy consumption. Escalator demand concentrates in transportation terminals where bidirectional flow capacity determines infrastructure planning.
FAA guidelines govern vertical transportation in airport terminals, while OSHA lockout/tagout standards shape maintenance safety protocols for facility operators. The EU Machinery Directive and EN 81 standards enforce design and installation conformity across European member states, directly influencing product development cycles for manufacturers seeking CE marking. India's BIS certification mandates elevator safety testing before commercial deployment, creating compliance thresholds for imported equipment. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's building efficiency targets recalibrate specifications for regenerative drive systems and standby power consumption.
Market Dynamics
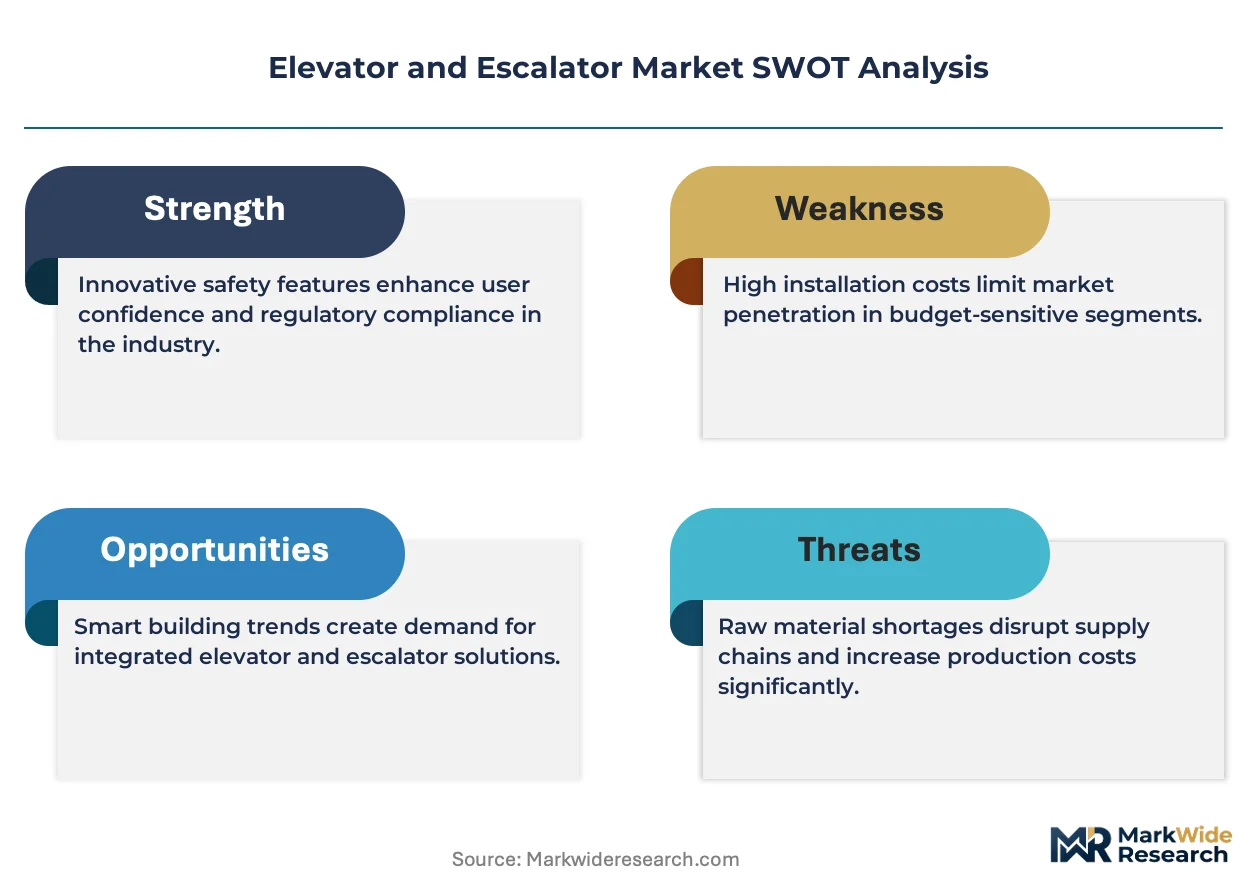
Machine-room-less traction technology is compressing shaft footprints in mid-rise construction, forcing hydraulic system manufacturers to defend position through price repositioning or exit. This displacement redistributes value capture toward permanent magnet motor suppliers and away from traditional pump-and-cylinder fabricators.
Growth Catalysts
- GB Standards Compliance:China's elevator energy efficiency mandates are accelerating regenerative drive retrofits in existing commercial building stock. Manufacturers must certify standby power consumption below 200 watts to access procurement channels.
- Airport Terminal Modernization:FAA guidelines for vertical transportation capacity are mandating redundant elevator banks in hub expansions. This specification pull concentrates demand for high-speed traction systems rated above 4 m/s.
- High-Rise Residential Density:Asia-Pacific megacities are zoning for 50+ floor residential towers. This building typology requires destination dispatch controls and double-deck configurations to manage peak-hour passenger volumes.
Market Restraints
- Steel Rope Supply Concentration:Specialty wire rope production for super-tall applications concentrates in German and Japanese mills. This geographic bottleneck creates 16-20 week lead times for OEMs outside captive supply arrangements.
- Certification Timeline Friction:India's BIS safety testing mandates 90-120 day approval windows for imported equipment. This regulatory lag disadvantages foreign suppliers bidding on fast-track commercial projects.
- Technical Speed Limitations:Hydraulic systems face absolute velocity caps around 1 m/s due to fluid dynamics constraints. This performance ceiling excludes the technology from buildings exceeding 15 floors regardless of cost advantage.
Strategic Opportunities
- Predictive Maintenance Convergence:IoT sensor networks and vibration analysis algorithms are converging into subscription-based uptime guarantees. Facility operators in North American urban corridors are unbundling service contracts from equipment purchase.
- EU Green Deal Alignment:Building efficiency targets are creating procurement preference for regenerative drives that return energy to grid. This regulatory tailwind favors suppliers with CE-marked regenerative product lines.
- Retrofit Channel Expansion:Controller modernization without full replacement is emerging as a distinct sales channel. Independent service providers are capturing this application through direct-to-building-owner marketing bypassing general contractors.
Industry Challenges
- Field Technician Scarcity:Traction system diagnostics and permanent magnet motor servicing require specialized training that outpaces vocational program output. OEMs are internalizing apprenticeship costs to secure installation and maintenance capacity.
- Legacy Controller Integration:Destination dispatch retrofits must interface with 20-30 year old relay-logic systems. This technical heterogeneity extends commissioning timelines and erodes margin on modernization contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elevator and Escalator Market |
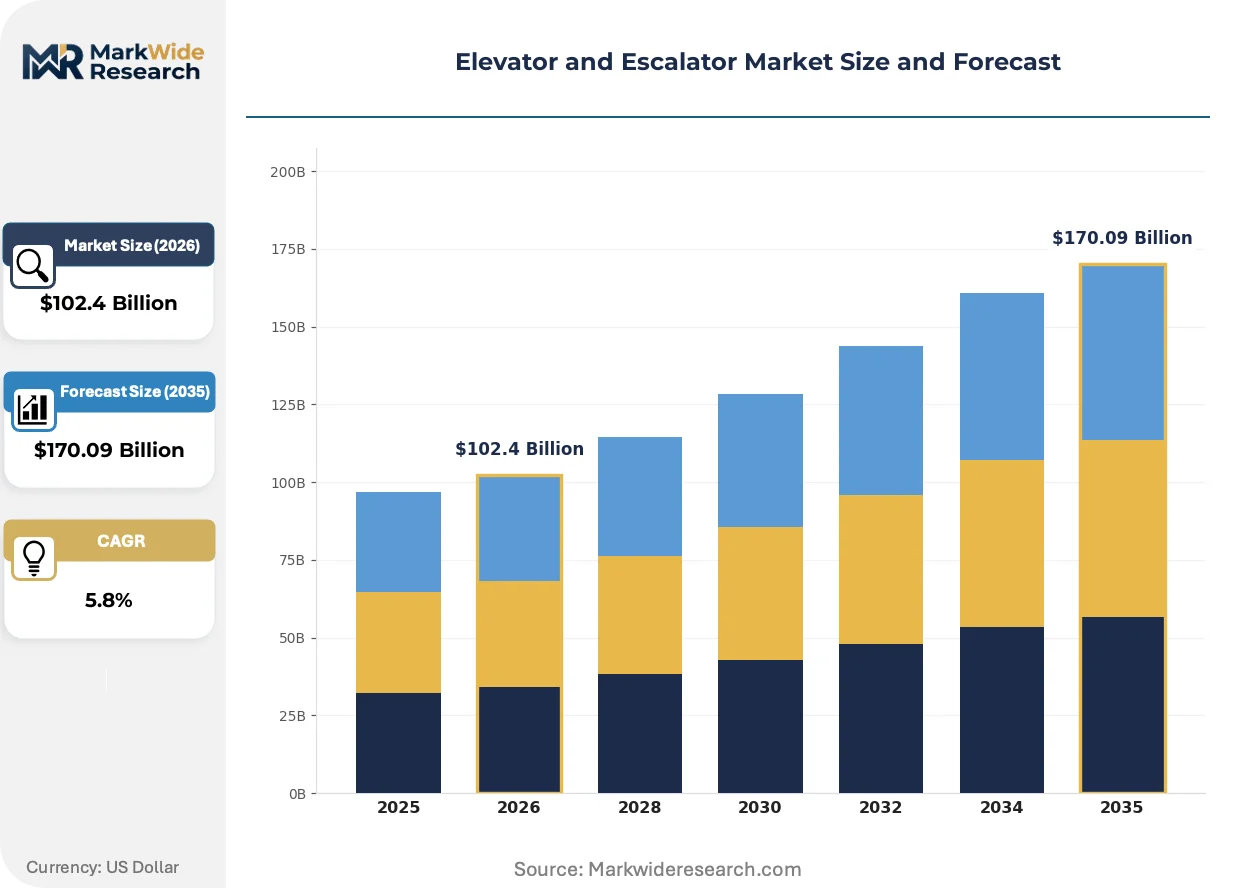
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $170.09 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Elevator, Freight Elevator, Escalator, Moving Walkway Technology: Hydraulic, Traction, Machine-Room-Less, Gearless, Drum Application: Commercial Buildings, Residential Complexes, Transportation Terminals, Hospitality Establishments End User Industry: Property Management, Facility Operators, Retail Chains, Educational Institutes |
| Companies Covered | TK Elevator, Hitachi Ltd., Otis, Fujitec, Hyundai Elevator, KONE Corporation, Mitsubishi Electric Corporation, Thyssenkrupp, Schindler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elevator and Escalator Market Strategic Shifts & Innovations
Digitalization of maintenance operations is restructuring how vertical transportation value is captured and delivered. Three distinct vectors are reshaping product development priorities and service model economics across the installed base.
Permanent magnet synchronous motor technology is bifurcating the traction system market. The technology eliminates gearbox maintenance and reduces energy consumption by 30-40% versus conventional induction motors. High-rise developers in Shanghai and Shenzhen are specifying PM gearless machines as baseline, compressing demand for geared alternatives to low-rise and budget segments.
China's GB 7588 safety standard revisions are mandating brake monitoring systems and door protection enhancements for all new installations. The industrial consequence is accelerated R&D spending on redundant braking architectures and 3D light curtain sensors. European manufacturers seeking CE marking reciprocity are pre-emptively incorporating these specifications into global product platforms.
Facility operators are unbundling maintenance contracts from original equipment purchase, compressing OEM service attach rates. Third-party service providers with multi-brand technical capability are capturing this disintermediation opportunity through outcome-based uptime agreements. This procurement model evolution is most visible in North American commercial office portfolios where property management firms centralize vertical transportation spend across multiple buildings.
Elevator and Escalator Market Segmentation
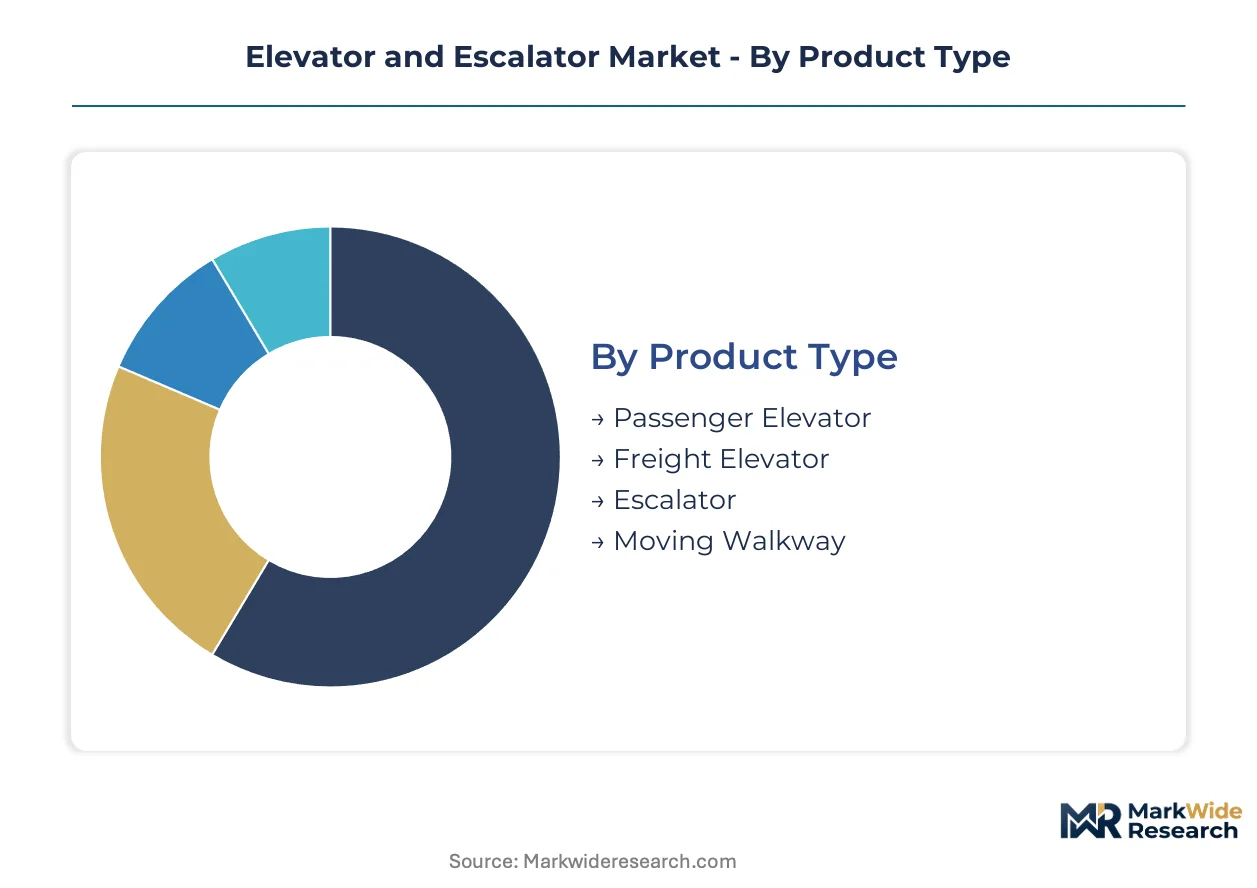
Vertical transportation procurement follows distinct technical and economic logics across building types and operational intensities. Segmentation clarity enables suppliers to align drive system specifications with duty cycle requirements and regulatory compliance thresholds.
Product Type:
Domestic demand concentrates in passenger-moving equipment for high-rise residential stock, while export-led growth tracks airport and retail infrastructure in emerging markets.
- Passenger Elevator:Traction systems with destination dispatch controls dominate installations above 20 floors. Demand concentrates in Shanghai, Shenzhen, and Mumbai residential towers where 50+ floor zoning mandates double-deck configurations.
- Freight Elevator:Heavy-duty traction machines rated for 5,000+ kg capacity serve logistics facilities and manufacturing plants. German and Japanese OEMs capture premium specifications for automated warehouse integration.
- Escalator:Inclined moving stairways with 30-degree slope angles handle bidirectional peak loads in transportation terminals.
- Moving Walkway:Horizontal or shallow-gradient conveyors span extended distances in airport concourses and large retail complexes.
Passenger elevators command the established base. The steepest expansion runs through escalators in transportation terminal modernization programs.
Technology:
Cost tiers separate premium permanent magnet systems from budget hydraulic alternatives, with mid-range traction equipment capturing volume in commercial retrofit channels.
- Hydraulic:Pump-and-cylinder systems with 1 m/s velocity ceiling serve low-rise buildings under 15 floors. Price positioning defends residual share against MRL displacement in budget residential construction.
- Traction:Conventional geared machines with induction motors retain installed base dominance. Demand concentrates in European commercial building stock where modernization cycles extend equipment life without full replacement.
- Machine-Room-Less:Permanent magnet motors eliminate separate machine room, reducing shaft footprint by 40% and energy consumption by 30-40%.
- Gearless:Direct-drive permanent magnet systems rated for super-tall applications above 400 meters.
- Drum:Winding drum mechanisms for specialized low-speed, low-rise applications with limited travel distance.
Traction systems command the established base. The steepest expansion runs through machine-room-less technology in Asia-Pacific mid-rise construction.
Application:
Volume scales separate high-unit residential deployments from low-unit, high-specification transportation terminal projects.
- Commercial Buildings:Class A office towers specify regenerative drives and predictive maintenance integration. Procurement in New York and Chicago corridors favors service unbundling from equipment purchase.
- Residential Complexes:High-rise towers above 30 floors require destination dispatch and double-deck configurations. China's GB standards mandate standby power below 200 watts for new installations.
- Transportation Terminals:Airports and rail hubs demand redundant elevator banks and high-speed traction above 4 m/s.
- Hospitality Establishments:Hotels prioritize aesthetic cab finishes and smooth ride quality over speed specifications.
Commercial buildings command the established base. The steepest expansion runs through residential complexes in Asia-Pacific megacities.
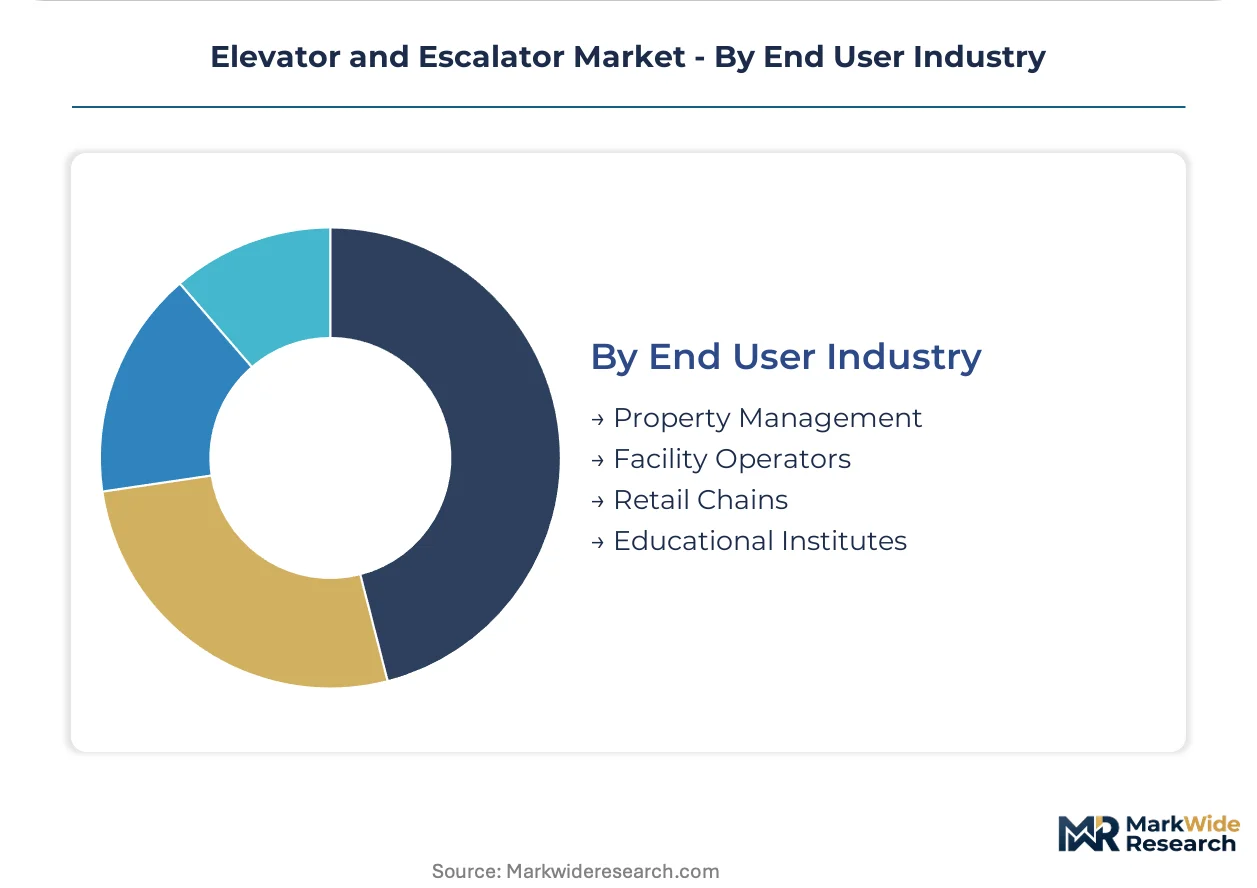
End User Industry:
Customer type determines contract structure, with centralized property managers driving standardization against fragmented retail procurement.
- Property Management:Portfolio-scale operators in North American urban corridors centralize vertical transportation spend across multiple buildings. Multi-brand service capability determines vendor selection.
- Facility Operators:Airport authorities and hospital systems prioritize uptime guarantees over capital cost minimization.
- Retail Chains:Big-box and mall operators specify escalator redundancy for peak traffic absorption.
- Educational Institutes:Universities and public school districts face extended procurement cycles driven by municipal funding authorization.
Property management commands the established base. The steepest expansion runs through facility operators adopting outcome-based maintenance agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese specialty steel mills serving super-tall construction, while Indian and Chinese assemblers compete on cost in mid-rise segments. This asymmetry redistributes margin capture upstream toward captive rope suppliers and downstream toward maintenance networks.
China
GB 7588 safety standard revisions mandate brake monitoring and door protection systems for all new installations. MIIT dual carbon goals accelerate regenerative drive retrofits in Shanghai and Shenzhen commercial towers. The Yangtze River Delta cluster dominates permanent magnet motor manufacturing for machine-room-less systems.
United States
FAA guidelines mandate redundant elevator banks in airport terminal expansions across Atlanta, Chicago, and Dallas-Fort Worth hubs. OSHA lockout/tagout standards shape maintenance safety protocols for facility operators. New York and Chicago urban corridors drive service contract unbundling from equipment purchase.
Germany
EU Machinery Directive and EN 81 standards enforce design conformity across European member states. REACH and RoHS regulations restrict hazardous substances in controller electronics. The Rhine-Ruhr industrial belt concentrates specialty wire rope production for super-tall applications.
India
BIS certification mandates 90-120 day safety testing windows for imported equipment. CEA building efficiency guidelines favor regenerative drive specifications in commercial retrofits. Mumbai and Bangalore residential towers above 30 floors require destination dispatch controls and double-deck configurations.
Japan
METI energy efficiency standards drive permanent magnet synchronous motor adoption in high-rise Tokyo and Osaka developments. JIS certification requirements maintain technical barriers for foreign suppliers. The Kanto region anchors gearless traction system manufacturing for buildings exceeding 400 meters.
Elevator and Escalator Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the vertical transportation value chain. The market structure consolidates around full-service OEMs with captive manufacturing, component-reliant assemblers, and independent service providers. Three strategic archetypes dominate: vertically integrated machinery producers, digital platform operators, and multi-brand maintenance specialists. Competitive moves concentrate on predictive maintenance platform development and controller modernization without full replacement.
Among European-integrated OEMs, KONE Corporation and Schindler Group occupy positions emphasizing in-house hoisting machinery and digital predictive platforms respectively. Otis anchors the North American maintenance network density archetype. TK Elevator represents the post-divestiture independent structure following Thyssenkrupp's elevator unit separation. These named entities exemplify how geographic origin and corporate structure shape strategic positioning rather than product-specific differentiation.
| Leading Market Players |
|---|
| TK Elevator |
| Hitachi Ltd. |
| Otis |
| Fujitec |
| Hyundai Elevator |
| KONE Corporation |
| Mitsubishi Electric Corporation |
| Thyssenkrupp |
| Schindler Group |
| Others |
Cost & Logistics Intelligence
Sixteen-to-twenty-week lead times for specialty wire rope in super-tall applications concentrate pricing power with German and Japanese mills, while mid-rise assemblers in India and China compete on component cost. This asymmetry rewards captive supply arrangements and compresses margins for non-integrated buyers.
Pricing Analysis
The customization-premium spread between configured-to-order traction systems and standard hydraulic packages runs wide. Project-based pricing dominates, with differentiation driven by CE certification tier and after-sales service bundling. Cost compression in the hydraulic tier is intensifying because machine-room-less technology captures mid-rise specification. Budget residential developers in India exhibit highest price sensitivity; airport authorities in the United States show least.
Supply Chain Analysis
Inventory cycles for permanent magnet motors and controller electronics stretch across 12-16 weeks in normal conditions. Supply concentrates in China for motors, Germany for specialty steel, and Japan for high-grade wire rope. The chain draws from copper windings, rare-earth magnets, and microprocessor controllers. Single-source vulnerability sits with Japanese rope mills serving buildings above 400 meters. Distribution runs through OEM direct sales for new installation and independent service providers for retrofit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent magnet synchronous motor displacement of geared traction systems constitutes a high-growth disruption, with China's GB 7588 brake monitoring mandates accelerating R&D investment cycles.
For Market Incumbents: Shield installed base service revenue from third-party disintermediation through predictive maintenance platform lock-in. Deepen backward integration into permanent magnet motor manufacturing to defend margin against component cost volatility. The threat of multi-brand service providers capturing unbundled contracts demands channel control investment. For New Entrants and Emerging Players: Lead with controller modernization without full replacement in North American commercial office portfolios. The retrofit channel offers lowest competitive density against entrenched OEMs. Direct-to-building-owner marketing bypassing general contractors provides the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-optimized elevator units. The five-to-ten year viability window favors service network density over manufacturing scale. Watch for BIS certification timeline compression in India as inflection indicator for foreign supplier competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | IoT sensor networks enable subscription-based uptime guarantees for facility operators. |
| Permanent Magnet Motor Manufacturing Scale-Up | Yangtze River Delta cluster expansion captures machine-room-less specification growth. |
| Controller Modernization Channel Buildout | Direct-to-owner marketing bypasses general contractor capture in retrofit segments. |
| Regulatory Certification Pre-Emption | CE marking reciprocity with China's GB 7588 accelerates global product platform convergence. |
| Multi-Brand Service Capability Acquisition | Technical breadth across OEM lines captures unbundled maintenance contract disintermediation. |
Research Approach
Operator-level perspectives from facility managers, maintenance directors, airport procurement officers, and property portfolio heads anchored the qualitative base. Primary field engagement combined with secondary validation from FAA guidelines, EU Machinery Directive filings, BIS certification records, and customs trade data. Bottom-up installation base modeling and top-down construction pipeline analysis provided cross-verification.
Sensitivity analysis tested demand elasticity across the projection horizon. Segmentation dimensions included building typology, technology tier, application intensity, and regional regulatory cluster. CAGRs derived from equipment replacement cycles and new construction absorption rates. Permanent magnet motor cost curves and steel rope supply constraints informed specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained urban vertical construction density or regulatory enforcement continuity would require recalibration. Forecasts reflect documented assumptions around technology substitution pace and certification timeline stability. Raw material concentration and field technician training pipeline represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Global Air Handling Units (AHU) Market
Construction and Engineering
Double Decker Roll Forming Machine Market
Construction and Engineering
Concrete Chain Saw Market
Construction and Engineering
Heat Moisture Exchanger Market
Construction and Engineering
Underground Mining Market
Construction and Engineering
Ceramic Wall Tiles Market
Construction and Engineering
Colombia Metal Fabrication Equipment Market
Construction and Engineering
Belgium Data Center Construction Market
Construction and Engineering
Saudi Arabia Roofing Market
Construction and Engineering
Logging Cable Market
Construction and Engineering
Offshore Pipeline Market
Construction and Engineering
Europe Stump Cutter/Grinder Market
Construction and Engineering
Borehole Equipment Market
Construction and Engineering
Ship-To-Shore Cranes Market
Construction and Engineering
Porcelain Tiles Market
Construction and Engineering
Gas Connectors and Gas Hoses Market