
 Education ERP Market | 2026-2036
Education ERP Market Size, Share, and Industry Trends Forecast 2026-2036
Education ERP Market Intelligence
The functional divide between institutional IT departments and academic faculty is collapsing as ERP platforms become central to pedagogy. Oracle Fusion Cloud ERP leverages its extensive enterprise background to serve large universities. In contrast, open-source solutions like ERPNext compete on customization for smaller institutions, while CSM Technologies specializes in government education projects in specific regions.
Education Enterprise Resource Planning systems are integrated software suites for managing an institution's administrative and academic functions. These platforms unify processes like admissions, billing, and scheduling into a single database with role-based access controls, aiming to streamline operations and enhance data-driven decisions. The market shows a clear preference for cloud-based deployments over on-premise solutions due to scalability. While the Student Information System module forms the foundational component, the higher education application segment represents the largest source of revenue.
Data privacy regulations fundamentally shape product development and deployment strategies for ERP vendors. Frameworks like Europe's GDPR and enforcement actions by the US FTC mandate stringent controls over student data processing. Consequently, vendor selection now prioritizes demonstrated compliance capabilities and transparent data governance tools for institutional clients.
Market Dynamics
The convergence of administrative and pedagogical functions is the central force shaping the education ERP market. Systems are evolving from back-office record-keeping tools into integrated platforms essential for student lifecycle management, driven by the capabilities of cloud computing and embedded analytics.
Growth Catalysts
- Digitalization Mandates:National policies, such as India's initiatives to digitize educational infrastructure, compel public and private institutions to adopt integrated management systems to improve administrative efficiency and data reporting.
- Cloud Platform Proliferation:The widespread availability of scalable, cloud-based ERP solutions lowers the barrier to entry for institutions, offering advanced analytics and AI features without the need for extensive on-premise hardware investment.
- Integrated Campus Demand:Higher education institutions require unified platforms to manage the entire student lifecycle, from admissions and enrollment to academic progress and alumni relations, driving demand for comprehensive ERP suites.
Market Restraints
- High Total Cost of Ownership:Significant upfront investment for implementation, customization, and training, coupled with ongoing subscription and maintenance fees, presents a substantial financial barrier for smaller or budget-constrained institutions.
- Legacy System Integration:The technical difficulty and expense of integrating new ERP platforms with pre-existing, often bespoke, legacy systems for functions like library management or research administration can delay or derail adoption projects.
- Data Privacy Compliance Burden:Stringent regulations like Europe's GDPR impose complex requirements for handling student data, increasing development costs for vendors and compliance risks for institutions.
Strategic Opportunities
- K-12 Sector Expansion:While higher education is the dominant segment, the K-12 school market remains comparatively underpenetrated, offering significant growth potential for vendors who can develop tailored, cost-effective solutions for school districts.
- AI-Powered Pedagogy:Integrating adaptive learning technologies and predictive analytics into ERP modules creates opportunities to offer personalized student support, identify at-risk students, and optimize curriculum delivery for better educational outcomes.
- Lifelong Learning Platforms:The growing focus on continuous education and professional development creates an opportunity for ERP systems to manage micro-credentials, certifications, and corporate training programs beyond traditional degree structures.
Industry Challenges
- Specialized Talent Scarcity:A shortage of IT professionals with dual expertise in both complex ERP system management and the specific administrative workflows of educational institutions hinders effective implementation and optimization.
- Faculty Adoption Resistance:Overcoming resistance to change from academic staff, who may be accustomed to disparate, legacy systems and perceive new platforms as an administrative burden, is a critical operational hurdle.
- Data Unification Complexity:Merging siloed data from various departments such as admissions, finance, and the registrar into a single, reliable source of truth within an ERP system is a technically and politically challenging process.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Education ERP Market |
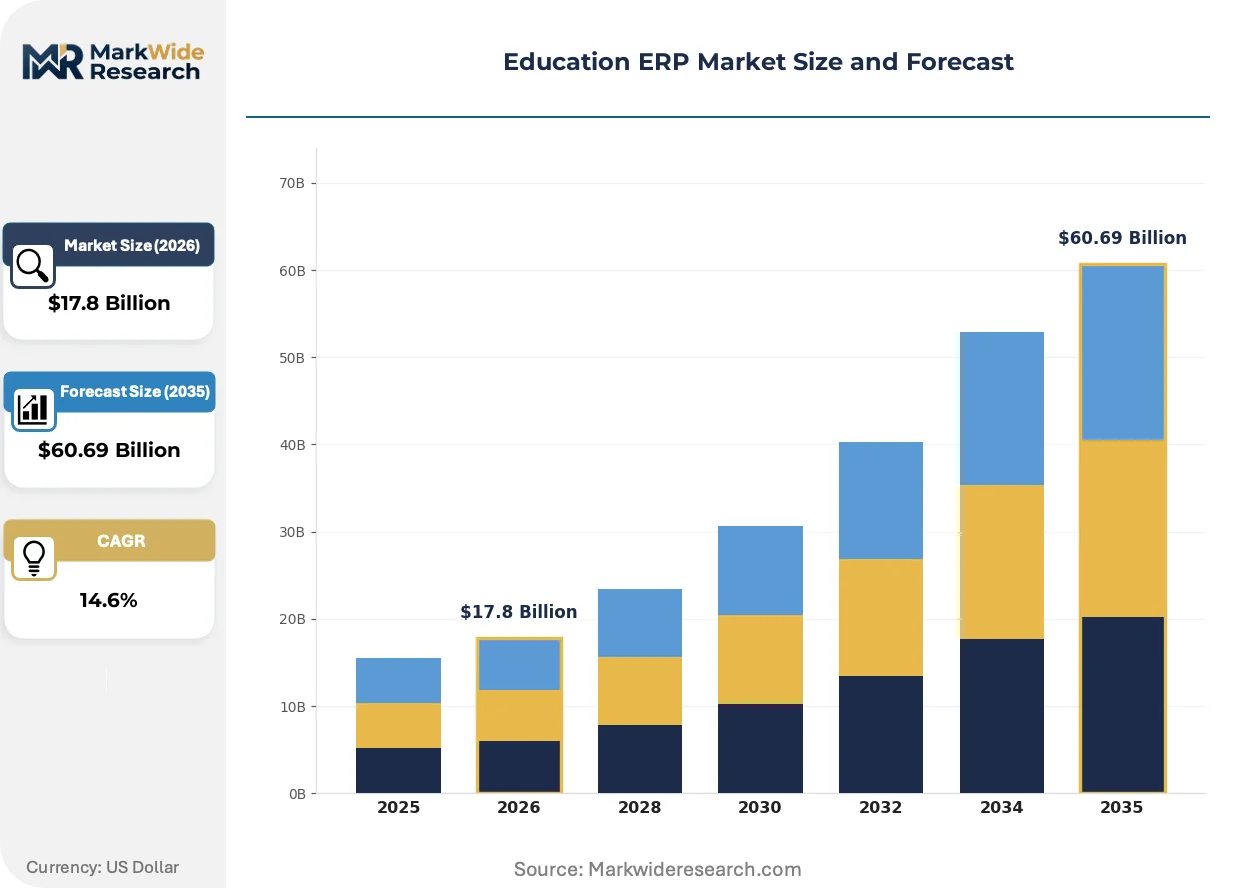
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $60.69 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Solution Type: Student Information System, Learning Management System, Financial Management, Human Resource Management, Library Management Application: K-12 Institutions, Higher Education, Vocational Training Centers, Professional Certification Bodies, E-Learning Providers End User: Public Schools, Charter Schools, Private Colleges, Technical Institutes, Online Academies |
| Companies Covered | Oracle Fusion Cloud ERP, Exalogic Consulting, Oracle NetSuite, CSM Technologies, AlphaBOLD, TallyPrime, Dean Infotech, inoday Inc, ERPNext, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Education ERP Market Strategic Shifts & Innovations
The market's evolution is defined by the ERP system's expanding role beyond administrative efficiency to become a core component of the educational mission itself. This shift is enabled by technologies that transform institutional data into actionable insights for improving student outcomes and engagement.
Artificial intelligence and machine learning modules are a primary focus of product evolution. These tools analyze vast datasets on student performance, engagement, and demographics to generate predictive insights for advisors and administrators. Higher education institutions are the principal adopters, using the technology to proactively manage student retention and personalize academic pathways. This analytical capability is decomposing the traditional, reactive model of student support into a continuous, data-informed process aimed at ensuring student success.
Data privacy regulations are fundamentally shaping ERP development and deployment. Frameworks like Europe's GDPR and enforcement priorities of the US FTC require vendors to engineer robust data governance and consent management tools into their platforms. This forces a "privacy by design" approach, impacting everything from data storage architecture to user access controls. Consequently, the higher education segment now heavily weighs a vendor's demonstrated compliance capabilities and data residency options during procurement.
A clear behavioral shift is occurring as institutions increasingly favor modular, cloud-based SaaS subscriptions over monolithic, on-premise license purchases. This disrupts the high-capital, long-cycle sales process, replacing it with a model based on recurring revenue and demonstrable value. The trend is most pronounced in the North American and European markets, where it allows smaller colleges and universities to access sophisticated ERP functionalities previously affordable only to large research institutions.
Education ERP Market Segmentation
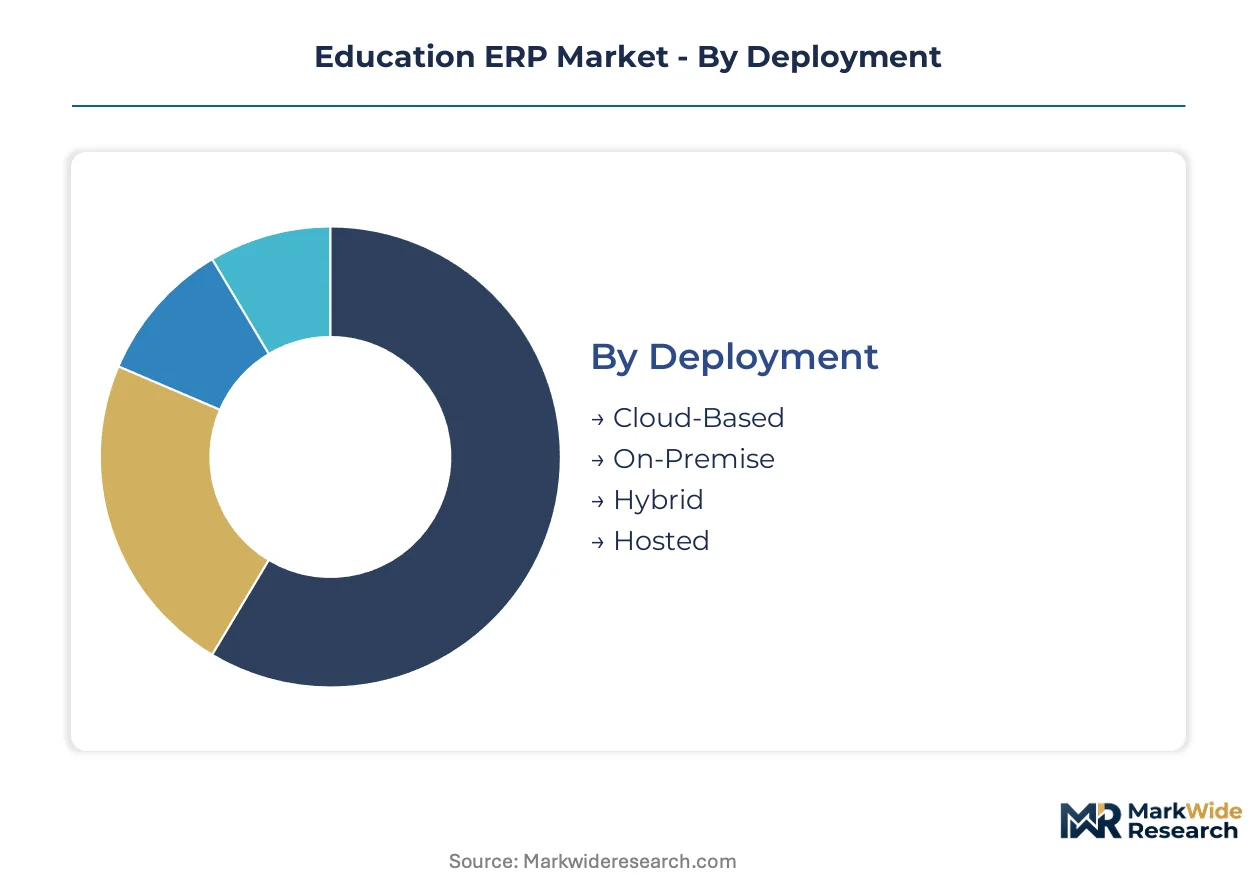
Understanding the segmentation within the Education ERP market is crucial for dissecting market dynamics and identifying specific growth vectors. This detailed breakdown reveals how diverse educational entities adopt and leverage these integrated platforms, offering insights into vendor specialization and targeted product development.
Deployment:
The deployment landscape for education ERP systems shows a clear bifurcation between models favored by domestic institutions versus those preferred for cross-border educational initiatives.
- Cloud-Based:This model involves software hosted on vendor servers and accessed via the internet, offering institutions significant scalability and reduced on-premise IT infrastructure overhead. Demand concentrates in regions like India, where national digitalization mandates compel rapid adoption of accessible, modern solutions.
- On-Premise:Institutions install and manage this software directly on their local servers, providing maximum control over data security and extensive customization capabilities. Demand persists among large, established universities in countries like Germany and the US with complex legacy systems and specific regulatory compliance needs.
- Hybrid:This approach combines elements of both on-premise and cloud-based deployments, allowing institutions to maintain sensitive data locally while leveraging cloud services for other functions.
- Hosted:A third-party provider manages the ERP software and infrastructure, typically on dedicated servers, offering a balance between control and outsourced management.
On-Premise solutions command the established base. The steepest expansion runs through Cloud-Based deployments.
Solution Type:
Solutions are differentiated by their core functional scope, addressing distinct administrative or pedagogical needs within educational environments.
- Student Information System:This foundational module manages all student-related data, including admissions, registration, academic records, and grading, serving as the central repository for student lifecycle management. It is indispensable for all educational institutions, from K-12 to higher education, ensuring comprehensive record-keeping.
- Learning Management System:Designed to manage educational courses, training programs, and learning content, this system facilitates online learning, student-teacher interaction, and assessment delivery. It is increasingly vital for e-learning providers and institutions adopting blended learning models across Europe and North America.
- Financial Management:This solution type handles an institution's budgeting, accounting, payroll, and procurement processes, ensuring fiscal transparency and operational efficiency.
- Human Resource Management:Focused on managing staff data, recruitment, performance, and professional development, this module optimizes workforce administration for educational employees.
- Library Management:This system organizes library resources, manages circulation, tracks acquisitions, and provides access to digital archives for academic institutions.
Student Information Systems form the foundational component, while Learning Management Systems are gaining traction due to evolving pedagogical requirements.
Application:
Market penetration varies significantly across institutional types, reflecting differing levels of digital maturity and budgetary capabilities.
- Higher Education:This segment includes universities and colleges, which require comprehensive ERP systems to manage complex academic programs, research administration, and extensive student services. This segment represents the largest revenue contributor, particularly in developed markets like the United States and the United Kingdom.
- K-12 Institutions:Comprising primary and secondary schools, this application segment focuses on student records, attendance tracking, and parent communication, often with a strong emphasis on ease of use and affordability. It exhibits significant underpenetration, offering substantial untapped growth potential for tailored, cost-effective solutions.
- Vocational Training Centers:These institutions provide specialized skill-based education, requiring ERP systems that can manage unique course structures and certification processes.
- Professional Certification Bodies:This segment utilizes ERP to manage credentialing, examination processes, and continuing education programs for specific industries and professions.
- E-Learning Providers:Entities delivering online courses and digital content rely on ERP systems for robust student management, content delivery, and billing functionalities.
Higher Education institutions represent the largest revenue contributor, with K-12 Institutions showing substantial untapped growth potential.
End User:
End-user segments are delineated by institutional funding models and organizational structures, influencing their specific ERP procurement priorities.
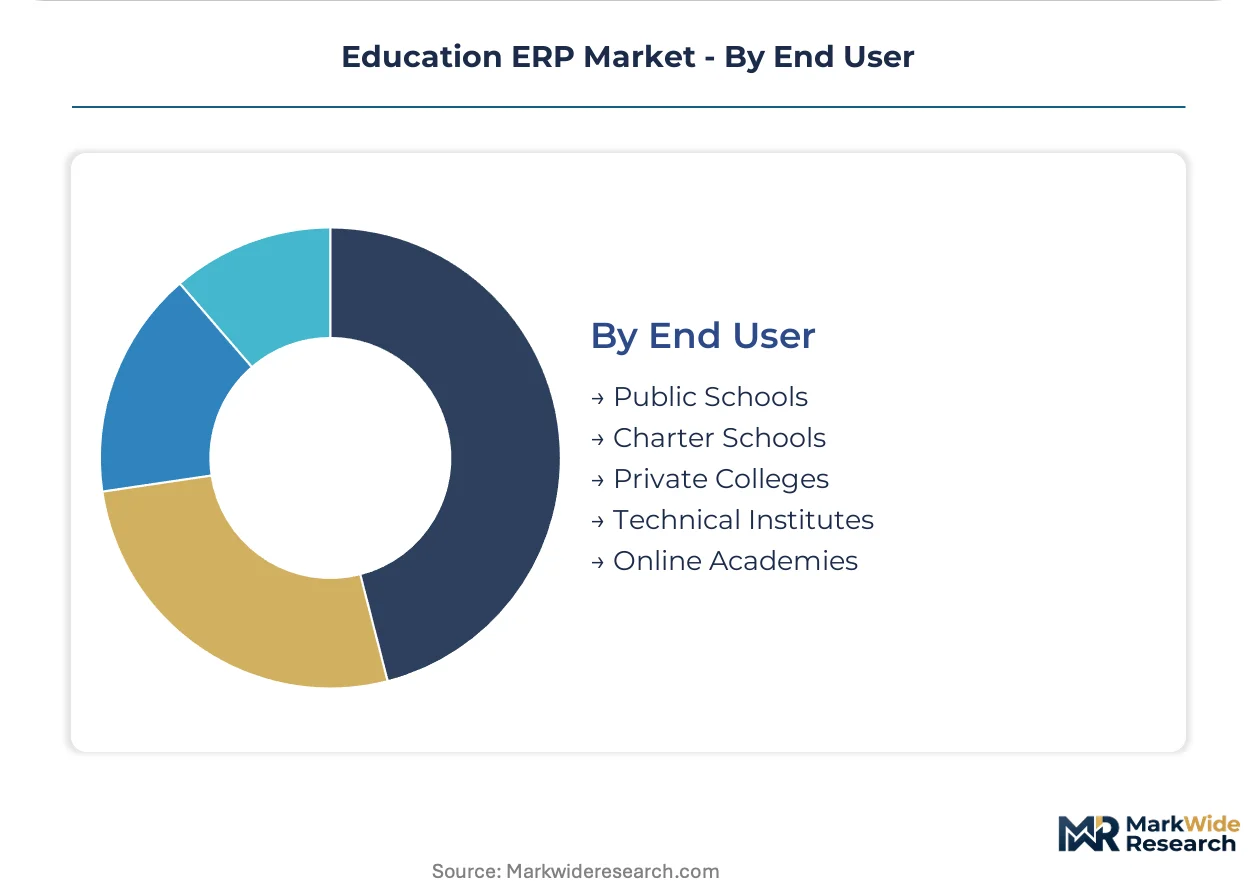
- Private Colleges:These privately funded institutions often prioritize advanced features, extensive customization, and robust student experience tools to attract and retain students. Demand for integrated platforms is consistently high across all administrative and academic functions within this segment.
- Public Schools:Government-funded K-12 institutions are often driven by cost-effectiveness, compliance with national education standards, and centralized data reporting mandates. Procurement is significantly influenced by national policies, such as India's initiatives to digitize educational infrastructure.
- Charter Schools:Publicly funded but independently operated schools seek flexible, scalable ERP solutions that can adapt to their unique governance and curriculum models.
- Technical Institutes:Focused on vocational training, these institutions require specific module integrations for managing practical courses, workshops, and industry placements.
- Online Academies:Fully digital learning environments emphasize robust cloud-based platforms and sophisticated Learning Management System capabilities for seamless virtual instruction and student support.
Public Schools constitute a significant volume segment, while Private Colleges often drive demand for advanced, integrated functionalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US FTC mandates stringent controls over student data processing, anchoring product development and deployment strategies across the Education ERP market. This regulatory environment drives demand for robust compliance capabilities and transparent data governance tools for institutional clients. Regional dynamics reflect varied digital maturity and policy landscapes.
United States
Higher education institutions in the United States require comprehensive ERP systems for managing complex academic programs and extensive student services. The US FTC mandates stringent controls over student data processing, influencing vendor selection and compliance capabilities. Major university hubs like Boston and Silicon Valley drive innovation in EdTech integration, focusing on advanced analytics.
India
India's national initiatives to digitize educational infrastructure compel public and private institutions to adopt integrated management systems. Government policies promote cloud-based solutions to improve administrative efficiency and data reporting across the country. Technology clusters in Bangalore and Hyderabad are centers for EdTech development, facilitating rapid ERP implementation.
Germany
Large, established universities in Germany often maintain preferences for on-premise solutions due to complex legacy systems and specific regulatory needs. GDPR imposes strict requirements for handling student data, influencing deployment choices and vendor data governance features. University cities like Munich and Berlin maintain strong preferences for local data management solutions, ensuring maximum control.
United Kingdom
Higher education institutions in the United Kingdom prioritize comprehensive ERP systems to manage complex academic programs and student services. The UK's data protection laws, aligned with GDPR principles, heavily influence vendor compliance capabilities during procurement. London and other university cities are increasingly adopting modular, cloud-based SaaS models for enhanced scalability.
Canada
Canadian institutions seek unified platforms to manage the entire student lifecycle, from admissions to academic progress and alumni relations. Provincial and federal privacy laws, similar to PIPEDA, guide data governance and security practices for educational data. Educational technology hubs in Toronto and Vancouver are exploring AI-powered pedagogical tools to optimize curriculum delivery.
Education ERP Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive structure of the Education ERP market. This tiered landscape features large enterprise solution providers, alongside open-source customizers and regional specialists. Dominant competitive moves include geographic expansion into underserved markets and portfolio diversification through AI integration.
Within the enterprise solution tier, Oracle Fusion Cloud ERP exemplifies a strategy of leveraging extensive enterprise background to serve large universities. In contrast, ERPNext represents the open-source segment, competing on customization and affordability for smaller institutions. These players anchor distinct market approaches, with some focusing on comprehensive, integrated platforms and others on flexible, adaptable solutions to meet diverse institutional needs.
| Leading Market Players |
|---|
| Oracle Fusion Cloud ERP |
| Exalogic Consulting |
| Oracle NetSuite |
| CSM Technologies |
| AlphaBOLD |
| TallyPrime |
| Dean Infotech |
| inoday Inc |
| ERPNext |
| Others |
Cost & Logistics Intelligence
Scale economies in software development and cloud infrastructure provision drive supply concentration among large vendors, establishing price floors for comprehensive integrated platforms. This dynamic influences both the affordability of advanced solutions and the competitive landscape for smaller providers.
Pricing Analysis
Geographic price spreads show higher average contract values in North America and Europe compared to India and other emerging markets. Pricing models predominantly follow a SaaS subscription structure, often tiered by institutional size, user count, or specific module access. Price differentiation stems from the level of customization, after-sales support bundles, and vendor brand premium. Downward pricing pressure originates from open-source alternatives and budget constraints within public education sectors. K-12 institutions and public schools consistently demonstrate the highest price sensitivity.
Supply Chain Analysis
Talent scarcity in specialized IT professionals and education ERP workflow experts represents a significant inbound logistics cost. Geographic supply concentration for core development resides heavily in the United States, India, and the United Kingdom. Solution providers depend on cloud infrastructure services from a few hyperscale providers and specialized development talent for their core components. Structural supply chain risk arises from this talent scarcity and potential vendor lock-in with cloud providers. Distribution runs through direct sales teams, strategic partner channels, and cloud marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Education ERP is a service-attach market, where recurring SaaS subscriptions and analytics services generate more value than initial software licensing. Post-implementation support and AI-driven insights expand revenue streams beyond core platform sales.
For Market Incumbents:
Consolidate market share by acquiring niche AI-powered pedagogy solutions to counter specialized EdTech threats. Oracle Fusion Cloud ERP should integrate advanced predictive analytics faster, mitigating margin pressure from open-source competitors. Invest in compliance certification for evolving data privacy regulations like GDPR and US FTC mandates to maintain client trust.
For New Entrants and Emerging Players:
Anchor in the underpenetrated K-12 sector by offering tailored, cost-effective cloud-based solutions. Focus on ease of use and rapid deployment for public schools in India, leveraging national digitalization mandates. A freemium model for basic administrative functions could attract initial adoption, paving the way for premium feature upgrades.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors specialized AI/ML EdTech firms with proven student outcome improvements over the next 5-10 years. Target acquisition archetypes include companies offering adaptive learning platforms or robust data governance tools. Watch for significant shifts in national education policy towards personalized learning and micro-credentialing as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch | Introduce AI-powered student retention modules to enhance pedagogical value. |
| Strategic Partnership | Collaborate with cloud infrastructure providers for enhanced data residency options. |
| Geographic Expansion | Enter K-12 markets in India, driven by government digitalization initiatives. |
| Acquisition of Specialist Firm | Acquire a company specializing in lifelong learning micro-credential management. |
| Platform Integration | Unify disparate data sources into a single, comprehensive student lifecycle view. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with university CIOs, K-12 administrators, EdTech solution architects, and government education officials; and secondary data from academic journals, government reports on digitalization, and market intelligence databases. Bottom-up and top-down triangulation validated market sizing and growth projections, ensuring robust data integrity.
The forecasting framework established market boundaries across the analysis window, segmenting by deployment, solution type, application, and end-user. CAGRs were derived from historical growth trends and anticipated technology adoption rates across the modeling period. Key inputs included educational enrollment projections and national digital infrastructure investment levels.
Underlying assumptions cover stable regulatory environments and continued investment in educational digitalization, with deviation risk concentrated in unforeseen data privacy legislation changes or significant shifts in government funding. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
Child Care Services Market
Education & Training
K-12 Education Market
Education & Training
Firefighter Simulator Training Services Market
Education & Training
Global Learning Management Systems (LMS) Market
Education & Training
Digital Educational Publishing Market
Education & Training
Global Social and Emotional Learning (SEL) Market
Education & Training
Flipped Classroom Market
Education & Training
North America IT Training Market
Education & Training
North America Digital Education Market
Education & Training
GCC Private K12 Education Market
Education & Training
Virtual Reality in Education Market
Education & Training
Corporate Training Software Market
Education & Training
Language Learning Games Market
Education & Training
Edutainment Market
Education & Training
Online Tutoring Market
Education & Training
Digital Course Recorder Market