
 Dyes and Pigments Market | 2026-2036
Dyes and Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Dyes and Pigments Market Analysis
Specialty pigment formulation revenue is reshaping margin distribution between commodity dye production and high-performance colorant development. BASF SE leverages its integrated pigment precursor network across Ludwigshafen and Antwerp to control input costs for automotive coatings. Clariant AG anchors its position through R&D intensity in halogen-free organic pigments for plastics and electronics applications. Sudarshan Chemical Industries Limited dominates India's domestic pigment supply while extending export reach into Southeast Asian coatings markets.
Dyes and pigments comprise synthetic and natural colorants classified by chromophore structure, particle size distribution, and lightfastness ratings, serving to impart visible color, opacity, or functional properties to substrates. Manufacturing routes span azo coupling, phthalocyanine synthesis, and high-temperature calcination of inorganic metal oxides, with particle engineering determining performance in target media. Organic pigments command premium pricing in plastics and automotive coatings where thermal stability and regulatory compliance restrict substitution, while reactive dyes maintain volume leadership in textile processing due to covalent fiber bonding chemistry. Powder forms retain cost advantages in bulk industrial applications, though liquid dispersions are capturing share in automated coatings lines where metering precision reduces waste.
EPA oversight of VOC emissions from coatings operations and REACH restrictions on cadmium and lead compounds are forcing reformulation investments across North American and European supply chains. China's MEE enforcement of wastewater discharge limits at dye manufacturing clusters is raising compliance costs for azo dye producers serving export markets. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and qualify alternative chemistries before compliance deadlines tighten.
Market Dynamics
Waterborne coating formulations are displacing solvent-based systems across automotive OEM lines, forcing pigment suppliers to reengineer dispersion stability and compatibility with lower-VOC resin matrices. This transition concentrates procurement power with coatings formulators capable of qualifying new colorant chemistries at scale.
Growth Catalysts
- EU Green Deal heavy-metal restrictions:Cadmium and lead compound bans under REACH Annex XVII are redirecting formulation R&D toward organic and high-performance inorganic alternatives in plastics and electronics coloration.
- China textile cluster upgrades:Government-mandated environmental retrofits at Shaoxing and Guangdong dye houses are pulling investment into wastewater-compliant reactive dye systems.
- Automotive waterborne coatings:OEM paint shops are converting to low-VOC basecoat systems, expanding procurement of surface-treated organic pigments with enhanced humidity resistance.
Market Restraints
- Crude oil derivative volatility:Naphtha and benzene feedstock costs swing pigment precursor economics, compressing margins on azo and phthalocyanine chemistries.
- China supply concentration:Intermediate manufacturing clusters around Zhejiang and Jiangsu provinces create geographic risk for global dye and pigment availability.
- Natural dye performance ceiling:Lightfastness and wash-fastness limitations restrict substitution of synthetic colorants in technical textile applications.
Strategic Opportunities
- India domestic market expansion:PLI scheme incentives for textile and plastics manufacturing are building captive demand for local pigment production.
- Bio-based pigment platforms:Algal and bacterial-derived colorants from fermentation processes are opening regulatory-compliant pathways for food-contact and cosmetic applications.
- Digital printing inkjet integration:Pigment dispersion technology convergence with drop-on-demand printheads is creating new specification requirements for narrow particle distribution.
Industry Challenges
- Color matching automation:Spectrophotometric formulation systems require retraining of technical service teams away from empirical tinting methods.
- Multi-jurisdiction registration:Separate dossier requirements for EPA TSCA, REACH, and China MEE new chemical notifications extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dyes and Pigments Market |
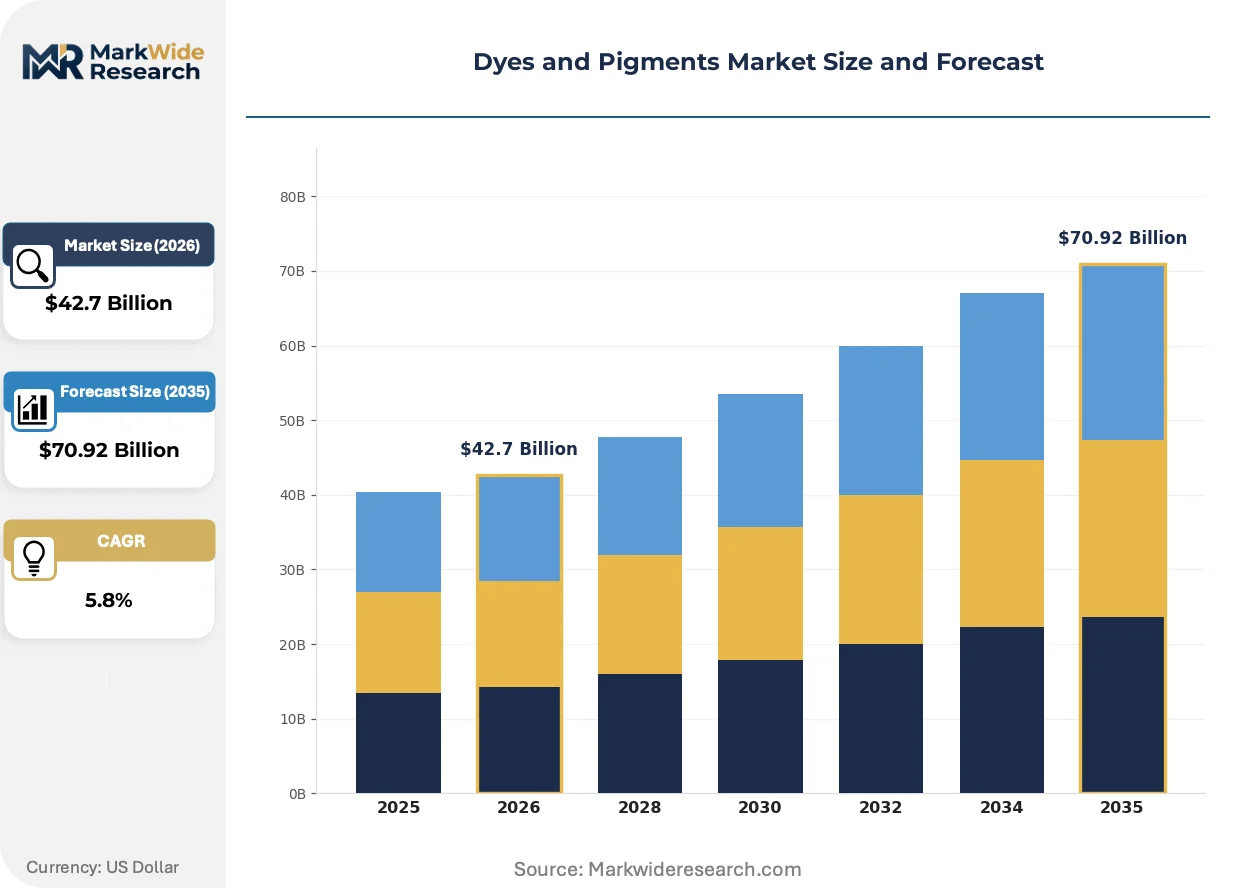
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $70.92 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Azo Dyes, Acid Dyes, Reactive Dyes, Organic Pigments End User: Textiles, Plastics, Coatings, Paper Form: Powder, Liquid, Granular, Paste Application: Automotive, Construction, Consumer Goods, Art Supplies |
| Companies Covered | BASF SE, Clariant AG, DIC Corporation, Lanxess AG, Sudarshan Chemical Industries Limited, Huntsman International LLC, Sun Chemical Corporation, Heubach GmbH, Archroma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dyes and Pigments Market Emerging Trajectories
Particle engineering and dispersion technology are converging to enable thinner coating films with equivalent hiding power, reducing material intensity across automotive and industrial applications. These advances are compressing the performance gap between commodity and specialty grade colorants.
Encapsulated pigment technology with silica or polymer shells is migrating from premium automotive coatings into architectural and industrial maintenance applications. Tier-two coatings formulators in Southeast Asia are adopting these systems to match OEM durability specifications without proprietary dispersion equipment. This migration from high-end to mid-market segments is standardizing performance baselines and eroding historical premium tiers.
REACH authorization requirements for chromium VI compounds in corrosion-resistant pigments are forcing reformulation of coil coatings and aerospace primers. ECHA sunset date enforcement is compressing qualification timelines for alternative inorganic complexes. Western European steel coil coaters are accelerating validation of phosphate-modified organic pigments to maintain supply chain continuity.
Automotive OEM color styling cycles have compressed from 36 to 18 months, forcing pigment suppliers to maintain larger shade libraries on speculative inventory. Tier-one coatings manufacturers are consolidating supplier panels to three preferred partners per chemistry family, transferring inventory carrying cost upstream. This concentration is most visible in Germany and Japan, where just-in-time sequencing dominates assembly plant supply chains.
Dyes and Pigments Market Segmentation
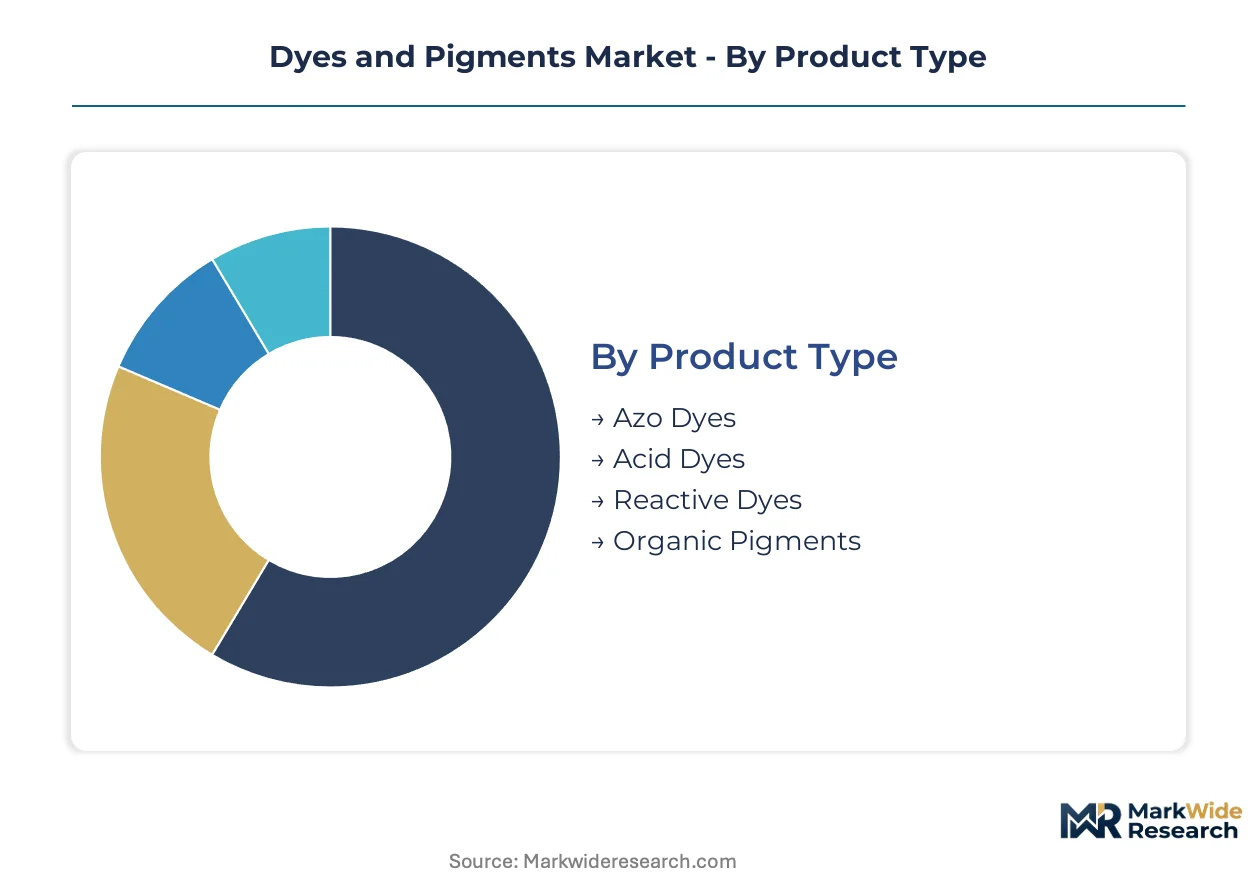
Colorant specifications diverge sharply across end-use applications, with thermal stability requirements in automotive coatings contrasting against wash-fastness demands in textile processing. Segment boundaries reflect formulation complexity tiers rather than simple chemical classifications.
Product Type:
Chromophore architecture determines substitution economics and regulatory exposure across industrial applications.
- Reactive Dyes:These colorants form covalent bonds with cellulose fibers through nucleophilic substitution reactions, delivering superior wash-fastness compared to direct alternatives. Shaoxing textile clusters in China absorb the highest procurement volumes as government-mandated wastewater retrofits force upgrades from older azo chemistries.
- Organic Pigments:Insoluble particulate colorants with engineered particle size distributions provide thermal stability above 200°C required for polyolefin masterbatch processing. Automotive OEM specifications for exterior body panels drive qualification timelines and premium pricing tiers.
- Azo Dyes:Nitrogen-nitrogen double bond chromophores dominate volume production through cost-efficient diazotization coupling reactions.
- Acid Dyes:Anionic structures optimized for protein and polyamide fiber affinity serve wool and nylon carpet markets.
Established volume favors azo dye commodity production; emerging adoption favors organic pigment specialty grades.
End User:
Customer concentration patterns split between specification-driven OEM supply chains and price-sensitive commodity procurement.
- Textiles:Fiber substrate diversity—cotton, polyester, wool, silk—demands formulation portfolios spanning reactive, disperse, and acid dye chemistries. Guangdong province dye houses are consolidating supplier relationships to three preferred partners per chemistry family to reduce qualification overhead.
- Coatings:Film-forming applications require pigment dispersion stability across solvent-borne, water-borne, and powder coating resin matrices. REACH Annex XVII restrictions on cadmium and lead compounds are accelerating reformulation toward high-performance organic alternatives in architectural and industrial segments.
- Plastics:Polymer compatibility and heat stability specifications govern masterbatch and compounder procurement decisions.
- Paper:Brightness and opacity requirements in packaging and printing grades drive commodity dye absorption.
Textile procurement maintains volume leadership; coatings applications are climbing the fastest on regulatory substitution demand.
Form:
Physical presentation determines handling economics, dispersion equipment requirements, and shelf stability profiles.
- Powder:Dry particulate forms retain cost advantages in bulk industrial applications where on-site dispersion equipment is available. Zhejiang province pigment manufacturing clusters supply powder grades to Southeast Asian coatings formulators seeking lower unit costs.
- Liquid:Predispersed concentrates eliminate dust exposure and reduce metering variability in automated coating lines. Water-borne automotive basecoat conversions are expanding specification requirements for humidity-stable liquid pigment preparations.
- Granular:Low-dust agglomerated forms balance flow properties with reduced inhalation risk in manual handling operations.
- Paste:High-solids dispersions serve niche applications requiring precise viscosity control in ink and coating formulations.
Powder forms dominate commodity volume; liquid dispersions are gaining share fastest in automated OEM coating operations.
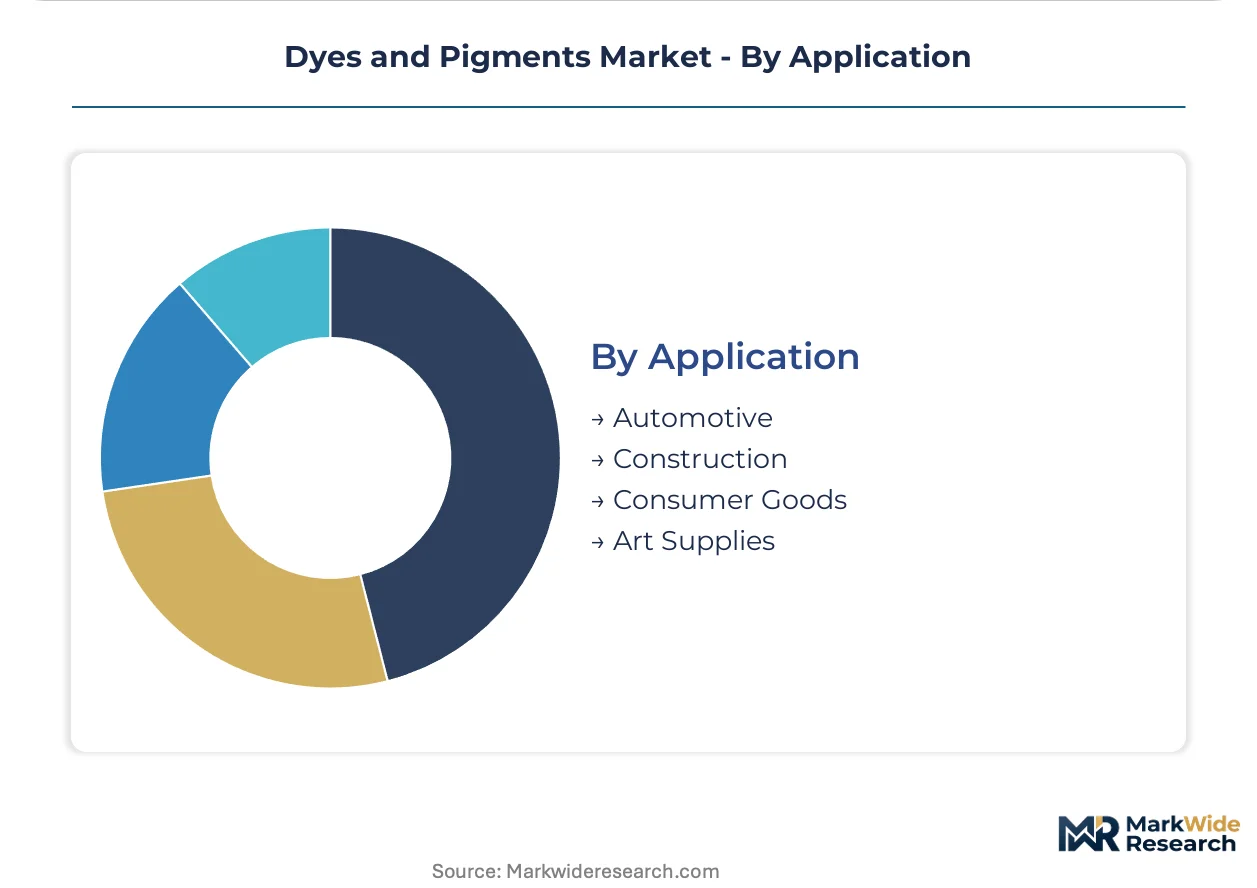
Application:
Durability specifications and color styling cycles create divergent margin structures across end-use markets.
- Automotive:Exterior body panel applications demand 10-year weathering performance with gloss retention under UV exposure and acid rain conditions. OEM paint shops in Germany and Japan have compressed color styling cycles from 36 to 18 months, forcing pigment suppliers to maintain larger speculative shade libraries.
- Construction:Architectural coatings and concrete coloration prioritize cost efficiency over extreme durability in most geographic markets. ECHA sunset date enforcement for chromium VI compounds is compressing qualification timelines for coil coating alternatives in Western Europe.
- Consumer Goods:Packaging, appliances, and electronics housings balance aesthetic requirements with regulatory compliance for food contact and toy safety standards.
- Art Supplies:Lightfastness ratings and non-toxicity certifications govern professional and educational product formulations.
Automotive specifications command premium tier pricing; construction applications represent the broadest volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity on commodity azo dyes, while automotive OEMs in Germany and Japan absorb premium pricing for organic pigments with minimal demand elasticity.
China
Shaoxing and Guangdong textile clusters drive reactive dye procurement volumes as MEE wastewater enforcement raises compliance costs. The dual carbon goals framework is accelerating closure of small dye houses lacking effluent treatment capacity. Zhejiang province pigment manufacturers supply powder grades to Southeast Asian coatings formulators seeking lower unit costs.
Germany
Automotive OEM paint shops in Stuttgart and Munich have compressed color styling cycles from 36 to 18 months. ECHA sunset date enforcement for chromium VI compounds is compressing qualification timelines for coil coating alternatives. BASF SE leverages its Ludwigshafen integrated pigment precursor network to control input costs for regional automotive coatings supply.
India
PLI scheme incentives for textile and plastics manufacturing are building captive demand for local pigment production. Sudarshan Chemical Industries Limited dominates domestic supply while extending export reach into Southeast Asian coatings markets. Maharashtra and Gujarat industrial corridors are consolidating dye house operations under stricter CPCB wastewater norms.
United States
EPA oversight of VOC emissions from coatings operations is forcing reformulation investments across North American supply chains. Automotive assembly plants in Michigan and Tennessee are converting to waterborne basecoat systems. Huntsman International LLC maintains technical service operations to support color matching automation for regional OEM specifications.
Japan
Automotive OEMs in Toyota City and Yokohama demand 10-year weathering performance with gloss retention under UV exposure. METI chemical substance regulations align with REACH restrictions on heavy-metal content. DIC Corporation anchors regional supply through dispersion technology integration with drop-on-demand printhead specifications.
Dyes and Pigments Market Vendor Landscape
Capability concentration sits with integrated chemical majors possessing precursor synthesis networks; scale advantage sits with regional specialists serving single-country demand pools. The market structures around three tiers: multinational diversified chemical conglomerates, mid-cap pigment specialists with R&D intensity, and commodity dye houses competing on unit cost. Dominant competitive moves include backward integration into pigment precursor production and consolidation of technical service teams to support color matching automation.
Within the integrated chemical conglomerate tier, BASF SE and Lanxess AG exemplify players controlling captive supply of phthalocyanine intermediates. Among mid-cap pigment specialists, Clariant AG occupies a position emphasizing halogen-free organic pigment development, while Sudarshan Chemical Industries Limited represents the regional scale-driven archetype serving domestic Indian demand with export extension. Heubach GmbH sits within the specialty coating pigment segment focusing on high-performance applications.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| DIC Corporation |
| Lanxess AG |
| Sudarshan Chemical Industries Limited |
| Huntsman International LLC |
| Sun Chemical Corporation |
| Heubach GmbH |
| Archroma |
| Others |
Supply Flow & Price Mechanics
Commodity naphtha and benzene feedstock volatility compresses margins across azo and phthalocyanine chemistries, forcing simultaneous tier compression in pigment pricing and geographic consolidation in precursor sourcing toward Zhejiang and Jiangsu manufacturing clusters.
Pricing Analysis
Long-term offtake agreements dominate procurement between automotive OEMs and integrated pigment suppliers, insulating premium organic pigment tiers from spot market swings while commodity azo dye transactions remain exposed to benzene derivative fluctuations. Price differentiation rests on REACH compliance certification and thermal stability grade, with automotive exterior specifications commanding substantial premiums over packaging applications. Cost compression in reactive dye segments is intensifying because Shaoxing textile clusters consolidate supplier panels to three preferred partners. Tier-one coatings manufacturers exhibit minimal price sensitivity for humidity-resistant organic pigments, while Southeast Asian commodity formulators absorb acute pressure on unit costs.
Supply Chain Analysis
Tariff exposure between China and Western coatings markets dominates supply chain risk assessment for global pigment procurement strategies. Manufacturing gravity centers on China, India, and Germany, with Zhejiang province pigment producers feeding Southeast Asian coatings formulators. Precursor synthesis draws from naphtha crackers, aniline derivatives, and phthalic anhydride feedstocks. Single-source vulnerability concentrates in phthalocyanine intermediate production around Ludwigshafen and Antwerp. Distribution runs through coatings formulator technical service networks that qualify colorant chemistries at scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EPA, REACH, and China MEE jurisdictions fragments procurement standards, creating specialized niches for compliance-focused formulation capabilities that multinational commodity producers struggle to address uniformly.
For Market Incumbents: Entrench position through backward integration into phthalocyanine precursor production at Ludwigshafen-scale integrated sites and accelerated certification investment for halogen-free organic pigments ahead of ECHA sunset dates. Emerging bio-based pigment platforms from algal fermentation threaten premium tier positioning in food-contact applications. Channel control through technical service team consolidation defends against mid-cap specialists capturing digital printing inkjet specifications. For New Entrants and Emerging Players: Bio-based pigment platforms for food-contact and cosmetic applications represent the most penetrable entry point, with regulatory-compliant pathways opening where synthetic alternatives face REACH authorization barriers. India's PLI scheme textile corridors offer white-space demand for local reactive dye production serving export-oriented garment manufacturers. Drop-on-demand inkjet dispersion technology convergence creates specification entry angles through narrow particle distribution capabilities that incumbent commodity producers lack. For Investors and Strategic Acquirers: ECHA chromium VI sunset date enforcement reshapes the acquisition landscape toward phosphate-modified organic pigment specialists with validated coil coating qualifications. Five-to-ten year viability favors mid-cap players with R&D intensity in halogen-free chemistries over commodity azo dye houses facing margin compression. Signal to watch: automotive OEM panel consolidation to three preferred partners per chemistry family, indicating which technical service capabilities achieve preferred vendor status.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | Ludwigshafen-scale phthalocyanine intermediate production insulates BASF from naphtha volatility. |
| Green Manufacturing Transition | Algal-derived colorant fermentation opens REACH-compliant pathways for food-contact applications. |
| Long-term Supply Agreement | Automotive OEM offtake contracts lock in premium organic pigment volumes across compressed styling cycles. |
| Joint Venture | India PLI scheme partnerships build captive pigment demand for textile export corridors in Maharashtra. |
| Capacity Expansion | Shaoxing wastewater-compliant reactive dye capacity captures government-mandated environmental upgrade procurement. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs/trade data, SEC 10-K filings, Cefic industry reports, and ECHA substance registration databases. Primary interviews engaged coatings formulator procurement leads, textile dye house plant managers, automotive OEM platform engineers, pigment technical R&D directors, and distribution channel partners across China, Germany, India, and the United States. Bottom-up segmentation modeling triangulates against top-down macroeconomic overlays to validate volume and value estimates.
Forecast inputs span product type chromophore architecture, end-use application durability specifications, physical form presentation, and regional regulatory compliance tier across the projection horizon. Segment-level CAGRs derive from elasticity-adjusted demand curves incorporating automotive styling cycle compression, textile cluster environmental retrofit timelines, and waterborne coating conversion rates. Industry-specific inputs include REACH authorization sunset enforcement schedules and China MEE wastewater discharge limit implementation trajectories.
Macroeconomic conditions sit as an overlay; deviation in crude oil derivative pricing, automotive production volumes, or textile export demand would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation timing and substitution elasticity between synthetic and bio-based colorant platforms. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Algal Pigments Market
Dyes and Pigments
Iron Oxide Pigments Market
Dyes and Pigments
Iridescent Pigments Market
Dyes and Pigments
Metallic Pigments Market
Dyes and Pigments
Brilliant Black BN Colors Market
Dyes and Pigments
Colorants Market
Dyes and Pigments
Photoluminescent Paints Market
Dyes and Pigments
Plastic Color Concentrates Market
Dyes and Pigments
Middle East and Africa Hair Colorants Market
Dyes and Pigments
Pearlescent Pigments Market
Dyes and Pigments
Titanium Dioxide Color Market
Dyes and Pigments
Brilliant Blue FCF Colors Market
Dyes and Pigments
Methylene Blue Market
Dyes and Pigments
Phosphorescent Pigments Market
Dyes and Pigments
Fluorescent Pigments Market
Dyes and Pigments
North America Hair Colorants Market