
 Disposable Lab Coat Market | 2026-2036
Disposable Lab Coat Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Lab Coat Market Insights
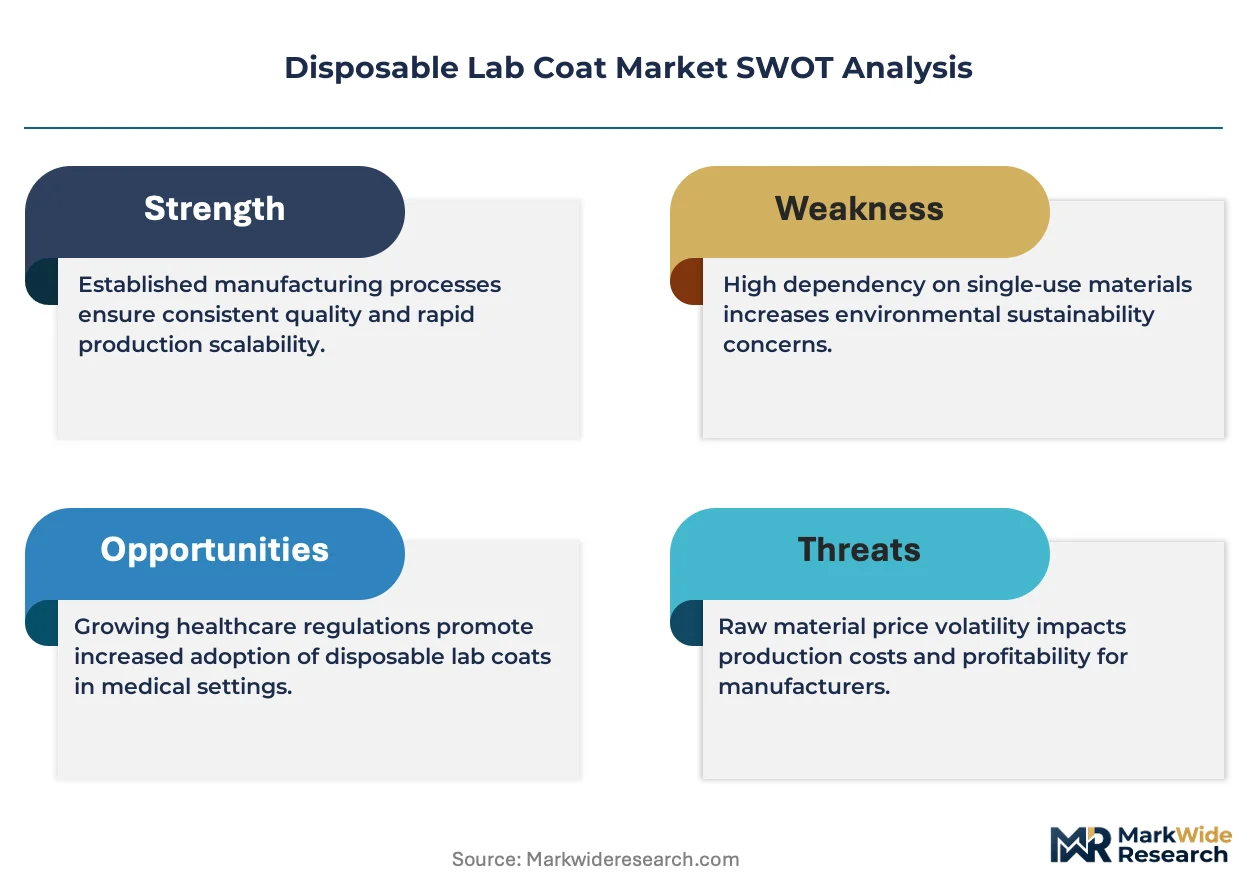
The divergence between premium and commodity tiers is hardening as healthcare systems split procurement between ISO-certified cleanroom garments and basic splash-resistant coats for general laboratory use. DuPont leverages its Tyvek material science heritage to dominate high-barrier applications in pharmaceutical aseptic processing. Kimberly-Clark sustains volume leadership through extensive hospital supply contracts and direct distribution networks across North America.
A disposable lab coat is a single-use protective garment engineered from non-woven synthetic substrates, typically polypropylene spunbond-meltblown-spunbond laminates measuring 30–60 gsm, designed to shield wearers from particulate contamination and minor chemical splash in controlled work environments. The non-woven segment anchors the majority of volume due to its breathability-to-cost ratio, while polypropylene occupies the fastest-expanding niche as manufacturers develop multilayer constructions with enhanced static-dissipative properties. Healthcare facilities represent the most mature demand pool with predictable replacement cycles, whereas pharmaceutical companies concentrate margin pools through validated supply agreements and custom sizing protocols.
FDA enforcement of 21 CFR Part 211 gowning requirements and OSHA's Bloodborne Pathogens Standard collectively elevate barrier-performance specifications for domestic manufacturers. The EU Medical Device Regulation and REACH chemical compliance frameworks shape export-market access for Asian producers seeking European distribution. Stakeholders must monitor how evolving cleanroom classification standards and sustainability mandates for single-use plastics will force material substitutions and supply-chain recertification investments.
Market Dynamics
Pharmaceutical cleanroom expansion is compressing procurement cycles as manufacturers validate single-use garments against tightening aseptic processing standards. This structural pull is forcing material suppliers to recertify barrier-performance specifications ahead of regulatory deadlines.
Growth Catalysts
- FDA 21 CFR Part 211 Enforcement:The agency's intensified inspection focus on sterile compounding gowning protocols is compelling US facilities to upgrade from reusable to disposable garments with documented barrier integrity.
- India's Contract Research Expansion:Bangalore and Hyderabad-based CROs are scaling ISO 14644-1 classified cleanroom capacity to serve global pharmaceutical outsourcing contracts.
- Spunbond-Meltblown-Spunbond Lamination:Advanced SMS constructions with electrostatically charged meltblown layers are delivering sub-micron filtration efficiency previously requiring woven alternatives.
Market Restraints
- Polypropylene Feedstock Volatility:Propylene monomer prices tied to naphtha cracking economics expose converters to margin compression during petrochemical cycle peaks.
- Asian Supply Concentration:Non-woven fabric production clusters in Zhejiang and Guangdong provinces create single-point vulnerability for Western garment assemblers.
- Biodegradation Performance Gap:PLA and starch-based alternatives fail to match polypropylene's tensile strength and liquid penetration resistance at equivalent basis weights.
Strategic Opportunities
- Brazil's ANVISA Modernization:The regulator's alignment with PIC/S pharmaceutical manufacturing standards is opening validated garment demand among domestic generic producers.
- Radioactive Material Handling:Nuclear medicine compounding facilities require specialized static-dissipative disposable coats with documented particulate shedding rates.
- Direct Hospital Contracting:Bypassing distributor markups through GPO-negotiated direct agreements is capturing 8-12 point margin expansion for volume manufacturers.
Industry Challenges
- Cleanroom Garment Certification Lag:ISO 16603 synthetic blood penetration and ASTM F1671 viral barrier testing timelines extend 14-18 months, delaying new product commercialization.
- Legacy ERP Integration:Hospital procurement systems require EDI compliance and lot-level traceability that smaller garment converters lack capital to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Lab Coat Market |
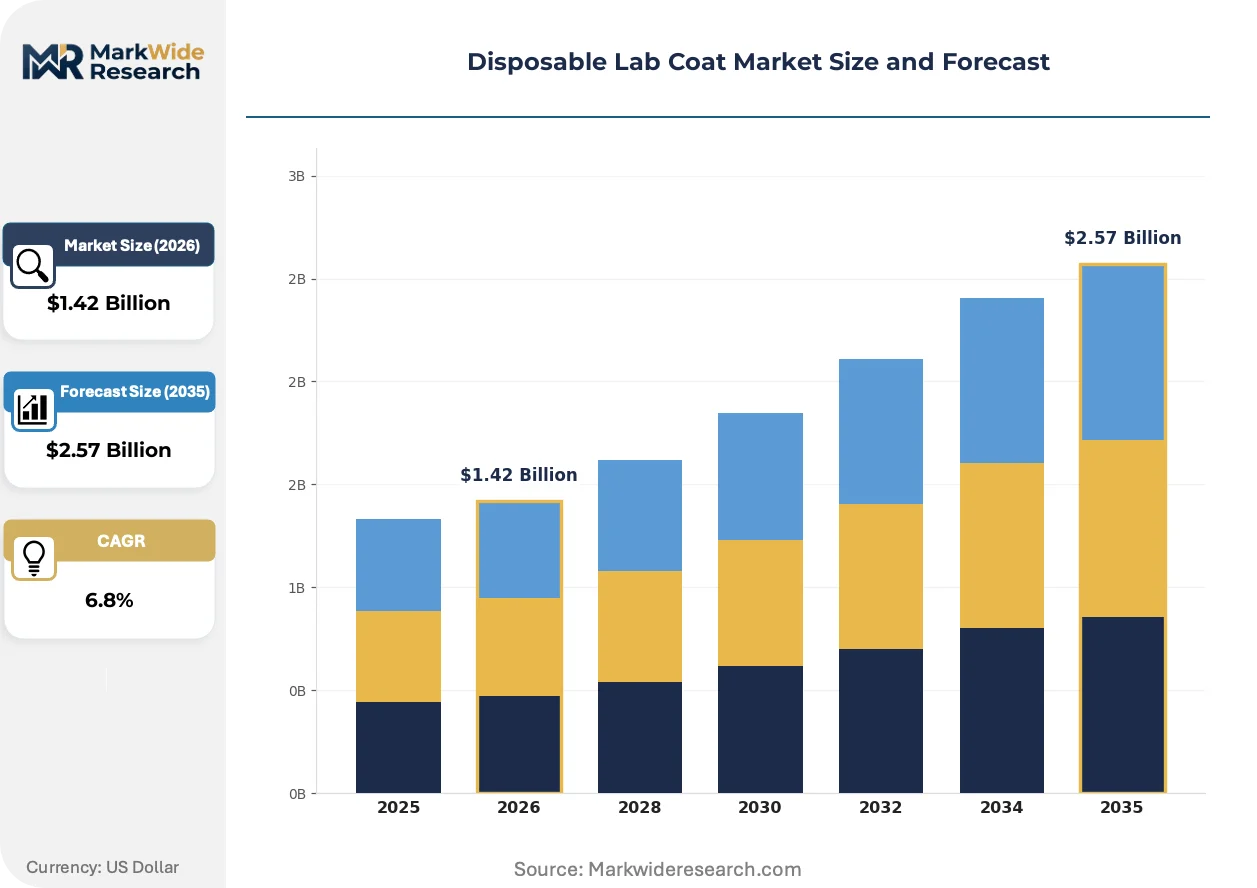
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Woven, Polypropylene, Polyester, PVC End User: Healthcare Facilities, Laboratories, Pharmaceutical Companies, Food Processing Distribution Channel: Online Retailers, Medical Supply Stores, Direct Sales, Wholesale Size: Small, Medium, Large, Extra Large |
| Companies Covered | DuPont, Kimberly-Clark, 3M, Medline Industries, Cardinal Health, Ansell, Alpha Pro Tech, Lakeland Industries, Henry Schein, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Lab Coat Market Trends and Innovations
Barrier-performance validation is displacing commodity purchasing as the primary selection criterion across pharmaceutical and healthcare procurement functions. This shift is elevating material science capabilities above pure manufacturing scale in competitive positioning.
Antimicrobial surface treatments using silver-ion or quaternary ammonium compound finishes are integrating into spunbond outer layers to reduce bioburden accumulation during extended cleanroom operations. Aseptic processing facilities in Ireland and Singapore are specifying these enhanced garments for fill-finish isolator operations. The technology is integrating quality assurance protocols previously managed through separate sterile wipes and surface disinfection cycles.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are compelling European manufacturers to reformulate durable water-repellent chemistries used in chemical-resistant lab coat lines. The ECHA's 2023 PFAS restriction proposal is accelerating fluorine-free alternatives based on hyperbranched polymers and silicone microemulsions. German and Swiss pharmaceutical exporters are front-loading inventory to hedge against supply discontinuities during formulation transitions.
Consolidated purchasing through integrated delivery networks is compressing supplier bases as hospital systems centralize PPE procurement under single-source agreements. IDN supply chain executives in Texas and Florida are mandating vendor-managed inventory programs with automated replenishment triggers. This concentration is most visible in the southeastern United States where HCA and Tenet facility clusters dominate regional demand pools.
Disposable Lab Coat Market Segmentation
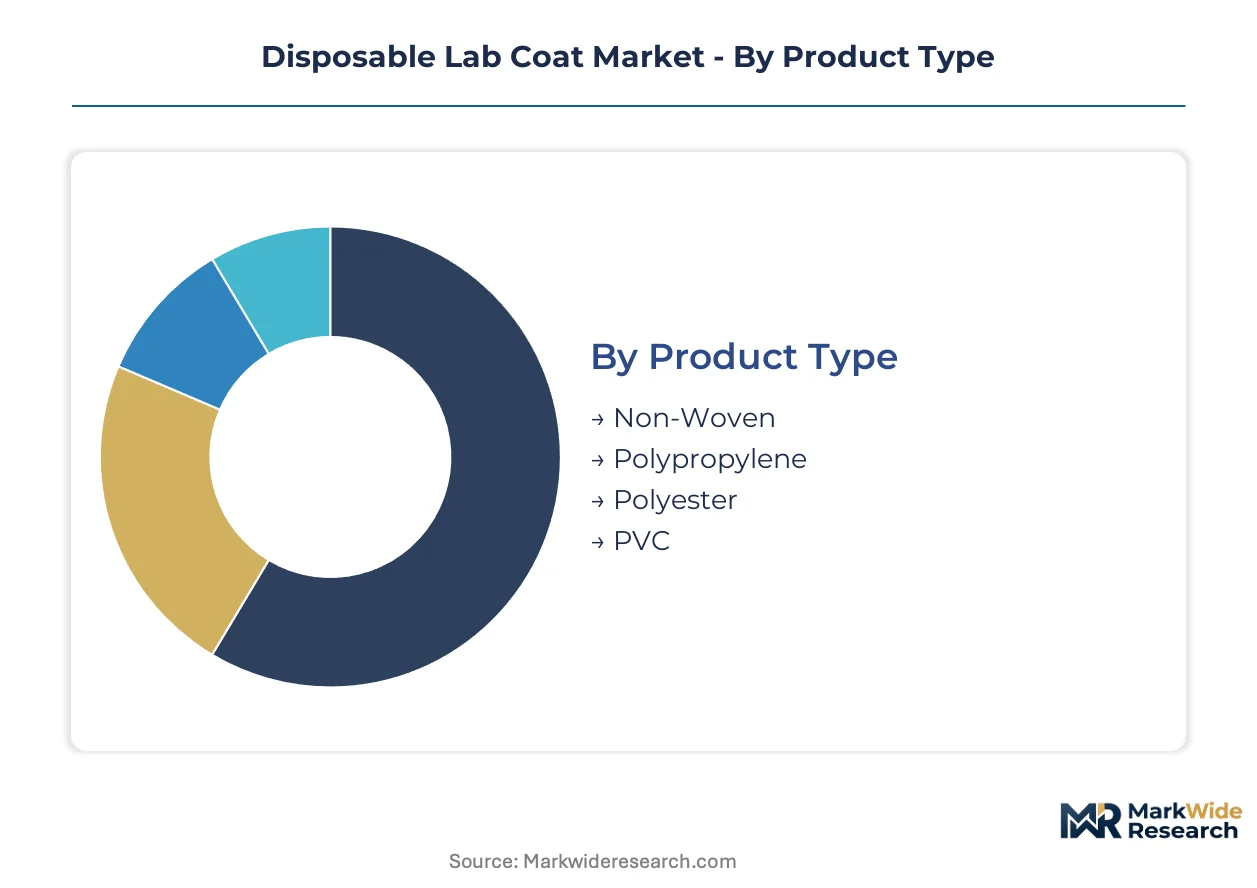
Disposable lab coat procurement splits sharply between validated cleanroom environments demanding certified barrier performance and general laboratory settings prioritizing cost efficiency. Material specifications, end-use contamination risks, and distribution economics create distinct margin pools across segment boundaries.
Product Type:
Buyers differentiate primarily by breathability-to-barrier tradeoffs and regulatory certification requirements rather than unit cost alone.
- Non-Woven:Spunbond-meltblown-spunbond laminates at 30–60 gsm deliver the breathability-to-cost ratio that anchors hospital and routine laboratory procurement. Healthcare facilities in Texas and Florida concentrate volume here through consolidated purchasing agreements with automated replenishment triggers.
- Polypropylene:Multilayer constructions with electrostatically charged meltblown layers achieve sub-micron filtration efficiency. Pharmaceutical cleanroom expansion in India and Ireland is compressing procurement cycles for these enhanced specifications.
- Polyester:Woven synthetic base with limited liquid penetration resistance serves educational and light industrial applications where splash protection requirements remain minimal.
- PVC:Impermeable film construction blocks chemical splash entirely but sacrifices worker comfort during extended wear periods in chemical handling operations.
Volume sits with Non-Woven; growth tilts toward Polypropylene.
End User:
Contamination risk tolerance and regulatory scrutiny intensity separate procurement behaviors across buyer categories.
- Healthcare Facilities:Predictable replacement cycles and standardized sizing dominate hospital system purchasing through GPO-negotiated agreements. HCA and Tenet facility clusters in the southeastern United States mandate vendor-managed inventory programs.
- Pharmaceutical Companies:Validated supply agreements with custom sizing protocols and documented barrier integrity capture the premium tier. FDA 21 CFR Part 211 enforcement is compelling upgrades from reusable to disposable garments with certified synthetic blood penetration.
- Laboratories:Research institutions balance splash resistance against budget constraints, often splitting procurement between ISO-certified garments for sensitive work and basic coats for general use.
- Food Processing:HACCP compliance requirements drive demand for particulate-shedding control in meat and dairy handling environments.
Revenue concentrates with Pharmaceutical Companies; expansion accelerates fastest in Healthcare Facilities procurement consolidation.
Distribution Channel:
Channel selection reflects order scale, traceability requirements, and margin capture priorities among buyers.
- Direct Sales:Volume manufacturers bypass distributor markups through GPO-negotiated direct agreements, capturing 8-12 point margin expansion. EDI compliance and lot-level traceability requirements favor established converters with capitalized ERP systems.
- Medical Supply Stores:Regional distributors serve mid-tier laboratories and smaller healthcare facilities with immediate availability and flexible order quantities.
- Online Retailers:E-commerce platforms capture spot purchasing from research institutions and educational facilities with non-standard sizing needs.
- Wholesale:Bulk aggregators supply commodity-tier garments to price-sensitive industrial and food processing buyers.
Margin pools concentrate in Direct Sales; channel shift momentum favors Online Retailers for fragmented demand.
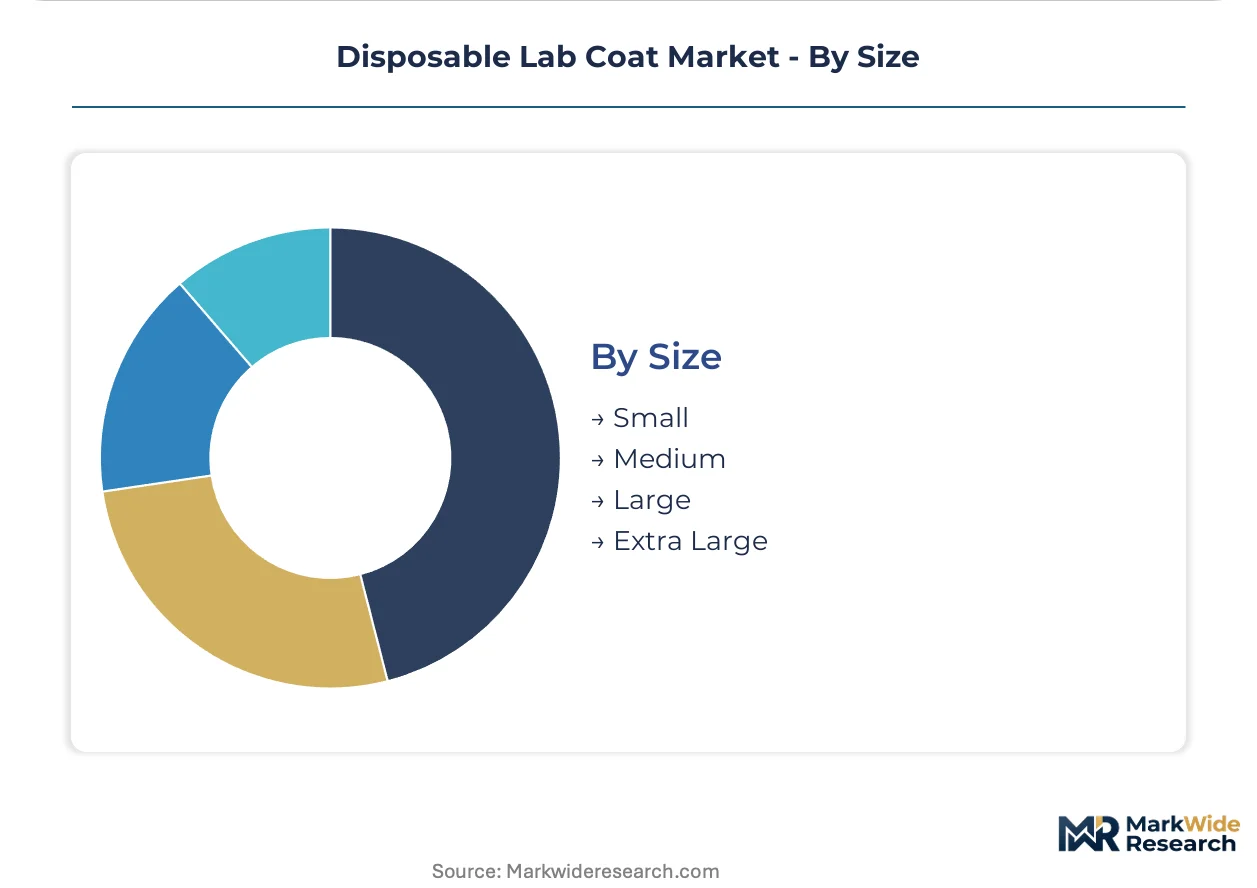
Size:
Fit standardization versus customization requirements create procurement friction across buyer types.
- Medium:Standardized dimensions match the largest addressable worker population in North American and European facilities.
- Large:Slight oversizing accommodates layering requirements in climate-controlled cleanroom environments.
- Small:Niche demand from pharmaceutical operations in Asia-Pacific markets with different anthropometric distributions.
- Extra Large:Custom sizing protocols in validated pharmaceutical agreements address specialized workforce needs.
Procurement volume clusters at Medium; specification complexity rises fastest in Extra Large custom agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangalore and Hyderabad anchor pharmaceutical cleanroom expansion in India, where contract research organizations are scaling ISO-certified operations to serve global outsourcing contracts. This corridor concentrates the fastest procurement cycle compression for barrier-validated garments.
United States
FDA enforcement of 21 CFR Part 211 gowning protocols is compelling sterile compounding facilities to upgrade from reusable to disposable garments with documented synthetic blood penetration certification. OSHA's Bloodborne Pathogens Standard elevates barrier-performance specifications for domestic manufacturers. Texas and Florida facility clusters dominate southeastern procurement consolidation through vendor-managed inventory programs.
Germany
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of durable water-repellent chemistries in chemical-resistant lab coat lines. The ECHA's PFAS restriction proposal accelerates fluorine-free alternatives. Pharmaceutical exporters in Baden-Württemberg are front-loading inventory to hedge against supply discontinuities during formulation transitions.
India
Bangalore and Hyderabad-based contract research organizations are scaling ISO 14644-1 classified cleanroom capacity to serve global pharmaceutical outsourcing contracts. CDSCO alignment with international manufacturing standards tightens garment validation requirements. Domestic generic drug manufacturers in Gujarat and Maharashtra are expanding single-use garment procurement to minimize cross-contamination risks.
Brazil
ANVISA modernization aligned with PIC/S pharmaceutical manufacturing standards is opening validated garment demand among domestic generic producers. The regulator's enforcement focus on aseptic processing environments compels facility upgrades. São Paulo-based pharmaceutical manufacturers are compressing procurement cycles for barrier-certified disposable garments.
Disposable Lab Coat Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the disposable lab coat market. Integrated material-science conglomerates with captive non-woven fabric production anchor the premium tier, while garment converters without upstream polymer capabilities populate the commodity segment. Three archetypes dominate: Tyvek-material heritage players, hospital supply contract aggregators, and regional non-woven converters. Capacity expansion in SMS lamination and strategic partnerships for electrostatic meltblown sourcing represent the dominant competitive moves.
Within the material-science heritage tier, DuPont leverages its Tyvek substrate dominance to anchor high-barrier pharmaceutical applications. Kimberly-Clark sustains volume leadership through extensive hospital supply contracts and direct distribution networks across North America. 3M occupies a position bridging industrial safety and healthcare segments with cross-category PPE expertise.
| Leading Market Players |
|---|
| DuPont |
| Kimberly-Clark |
| 3M |
| Medline Industries |
| Cardinal Health |
| Ansell |
| Alpha Pro Tech |
| Lakeland Industries |
| Henry Schein |
| Others |
Pricing and Supply Chain Analysis
Spunbond-meltblown-spunbond lamination specialists in Zhejiang province anchor production cost structures, with labor-cost differentials between coastal China and inland manufacturing zones widening the spread between ISO-certified pharmaceutical-grade garments and basic hospital procurement tiers.
Pricing Analysis
Barrier-performance validation tied to synthetic blood penetration certification anchors value-based pricing for pharmaceutical cleanroom applications. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated garments with documented lot traceability from basic splash-resistant coats for general laboratory use. Price differentiation hinges on certification grade and volume scale, with GPO-negotiated direct agreements capturing margin expansion for high-volume manufacturers. Cost compression in commodity non-woven tiers is intensifying because polypropylene feedstock volatility exposes converters to margin pressure during petrochemical cycle peaks.
Supply Chain Analysis
Ocean freight rate volatility between Shanghai and Rotterdam directly impacts landed costs for European pharmaceutical manufacturers sourcing validated garments. Non-woven fabric production clusters in Zhejiang and Guangdong provinces feed garment assembly operations, with propylene monomer supply resting on naphtha cracking economics. Single-source vulnerability concentrates in electrostatically charged meltblown layer sourcing. Distribution runs through integrated delivery networks with vendor-managed inventory programs dominating hospital system procurement in the southeastern United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The disposable lab coat market is transitioning from commodity procurement to barrier-performance-specified supply agreements, with electrostatically charged SMS constructions displacing basic spunbond alternatives in pharmaceutical cleanroom applications.
For Market Incumbents: Deepen captive control over meltblown layer production to secure electrostatic filtration capacity ahead of ISO 16603 recertification timelines. Add SMS lamination capacity in India to serve Bangalore and Hyderabad CRO expansion. Certification investment in ASTM F1671 viral barrier testing represents the critical defensive lever against Asian converters with faster regulatory approval cycles. For New Entrants and Emerging Players: E-commerce platforms serving research institutions with non-standard sizing needs offer the most penetrable entry vector. Target Brazilian generic drug manufacturers upgrading facilities for ANVISA PIC/S alignment with fluorine-free water-repellent formulations. Direct-to-laboratory digital channels bypass entrenched GPO relationships and capture spot purchasing demand from fragmented academic buyers. For Investors and Strategic Acquirers: Re-rating potential sits with regional non-woven converters with validated cleanroom garment capabilities given FDA enforcement tightening across sterile compounding facilities. Long-term viability favors asset-light designers with material science partnerships over capital-heavy integrated producers exposed to polypropylene feedstock cycles. Watch CDSCO alignment with international manufacturing standards as the inflection indicator for Indian contract research outsourcing velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Electrostatic Meltblown Capacity Expansion | DuPont and Kimberly-Clark are securing sub-micron filtration efficiency previously requiring woven alternatives. |
| Fluorine-Free DWR Formulation Transition | German pharmaceutical exporters are hedging against ECHA PFAS restriction supply discontinuities. |
| Direct Hospital Contracting Bypass | Volume manufacturers capture 8-12 point margin expansion through GPO-negotiated agreements with EDI compliance. |
| Indian Cleanroom Garment Localization | Domestic generic producers in Gujarat and Maharashtra minimize cross-contamination risks with single-use procurement. |
| Antimicrobial Surface Treatment Integration | Silver-ion finishes reduce bioburden accumulation during extended fill-finish isolator operations in Ireland and Singapore. |
Research Methodology
Multi-period observation of FDA inspection enforcement patterns and CDSCO regulatory alignment milestones anchored the trend analysis, supplemented by interviews with cleanroom operations managers, pharmaceutical procurement directors, GPO contracts managers, and non-woven fabric technical directors. Secondary validation drew from FDA 483 observation databases, ISO 14644-1 certification registries, ECHA restriction proposal documentation, and ANVISA pharmaceutical manufacturing inspection reports. Bottom-up facility-level procurement modeling and top-down polymer feedstock demand triangulation cross-checked volume estimates.
Input-output matrices mapped spunbond-meltblown-spunbond lamination capacity to end-use cleanroom classification requirements across the projection horizon. Segmentation dimensions included material substrate tier, end-user contamination risk tolerance, distribution channel traceability requirements, and regional regulatory cluster stringency. CAGRs were derived from facility expansion pipelines and validated supply agreement renewal rates. Forecast inputs incorporated propylene monomer price elasticity and pharmaceutical outsourcing contract velocity.
Inputs from hospital procurement databases and GPO contract repositories were available through the study window; gaps in real-time inventory positioning data introduce uncertainty bands around short-term demand spikes. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and polymer feedstock cycle positioning. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals & Materials
North America Biocides Market
Chemicals & Materials
Calcite Market
Chemicals & Materials
Global Blow Molding Resins Market
Chemicals & Materials
Global Vinyl Chloride Monomer Market
Chemicals & Materials
Amino Acid Chelates Market
Chemicals & Materials
Europe Soda Ash Market
Chemicals & Materials
Sodium Dicyanamide Market
Chemicals & Materials
EPDM Waterproofing Membrane Market
Chemicals & Materials
United States Graphite Electrodes Market
Chemicals & Materials
Transparent Polyamides Market
Chemicals & Materials
Rubber Plated Hose Market
Chemicals & Materials
Glass Adhesive Market
Chemicals & Materials
EPDM Sealing Strip Market
Chemicals & Materials
LAMEA Metal Biocides Market
Chemicals & Materials
Global Penicillin Drug Market
Chemicals & Materials
Large Molecule Drug Substance CDMO Market