
 Direct to Customer Outsourced Fulfillment Market | 2026-2036
Direct to Customer Outsourced Fulfillment Market Size, Share, and Industry Trends Forecast 2026-2036
Direct to Customer Outsourced Fulfillment Market Insights
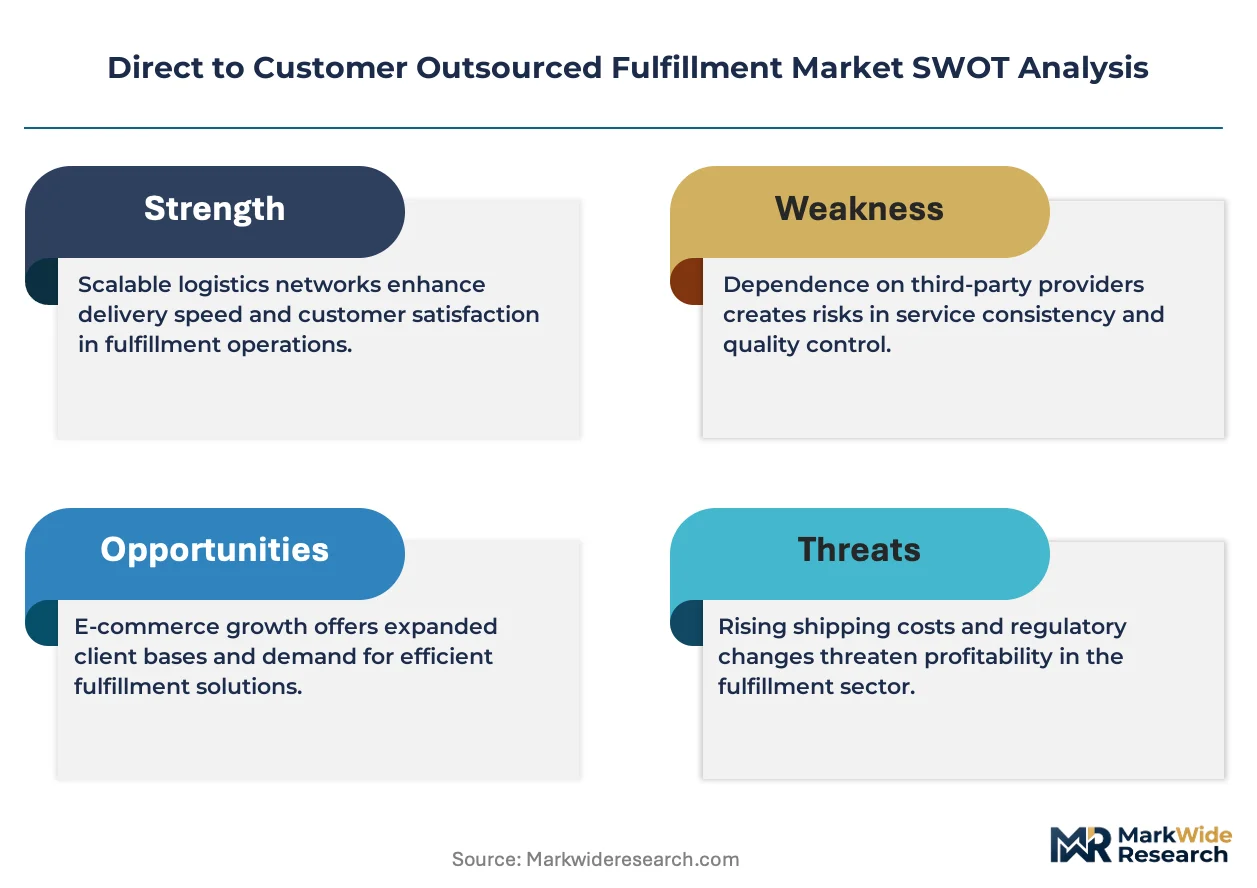
Last-mile delivery margin pools is narrowing as brands shift fulfillment risk to specialized operators. FedEx Fulfillment leverages its integrated transportation network to offer end-to-end visibility. ShipBob anchors its position through distributed micro-fulfillment centers near major metropolitan demand clusters. DHL Fulfillment competes on cross-border regulatory expertise and customs-clearance automation.
Direct to customer outsourced fulfillment encompasses third-party logistics services that manage inventory storage, order processing, packaging, and delivery on behalf of brands selling directly to consumers, typically operating through multi-tenant warehouses with cloud-based warehouse management systems achieving same-day or next-day dispatch targets. Its primary commercial purpose is converting fixed logistics overhead into variable costs while accelerating delivery speed to match consumer expectations. Order fulfillment commands the largest service-type revenue pool, though same-day delivery represents the fastest-expanding delivery mode as urban density enables economical rapid dispatch. E-commerce retailers dominate the customer-type mix, while subscription services generate higher inventory-predictability premiums that improve warehouse utilization rates.
FDA oversight of dietary supplement and cosmetic fulfillment imposes lot-tracking and temperature-documentation requirements on providers handling regulated consumer goods. EPA hazardous-material shipping regulations and OSHA warehouse safety standards shape facility design, staffing protocols, and carrier selection across the fulfillment network. FCC rules governing electronic device labeling and documentation create compliance layers for technology product fulfillment. Stakeholders must monitor how evolving state-level delivery-worker classification laws and emerging carbon-disclosure mandates reshape cost structures and provider liability frameworks.
Market Dynamics
Warehouse robotics and cloud-native warehouse management systems are compressing labor costs while forcing legacy operators into accelerated capital refresh cycles. The shift from fixed-asset ownership to variable-cost outsourcing is redistributing margin pools across the fulfillment value chain.
Growth Catalysts
- Same-Day Delivery Mandates:Urban consumer expectations for sub-24-hour dispatch are compelling brands to abandon in-house logistics. Micro-fulfillment networks near metropolitan demand clusters enable economical rapid fulfillment.
- FDA Lot-Tracking Requirements:Dietary supplement and cosmetic brands face escalating compliance burdens for temperature documentation and traceability. Third-party providers with validated cold-chain infrastructure capture regulated verticals.
- Subscription Commerce Proliferation:Predictable replenishment cycles improve warehouse utilization rates and inventory turns. Fulfillment operators command premium pricing for subscription-specific kitting and customization services.
Market Restraints
- Last-Mile Labor Cost Volatility:State-level delivery-worker classification laws in California and New York are reclassifying independent contractors as employees. Wage compression and benefits obligations erode unit economics for rapid delivery promises.
- Industrial Real Estate Concentration:Prime fulfillment space within 50 miles of major demand centers commands scarcity premiums. Limited developable land near Chicago, Dallas, and Atlanta constrains network expansion.
- Cross-Border Customs Friction:De minimis threshold reductions and enhanced inspection protocols at US ports are slowing international parcel clearance. Regulatory fragmentation between customs regimes adds processing latency.
Strategic Opportunities
- Reverse Logistics Monetization:Returns processing represents untapped margin pools as e-commerce return rates exceed 20%. Specialized refurbishment and resale channels transform cost centers into revenue streams.
- Carbon-Disclosure Compliance Services:Emerging Scope 3 emissions reporting mandates create demand for fulfillment providers with verified carbon-accounting infrastructure. Early certification unlocks preferential vendor status with sustainability-conscious brands.
- Healthcare-Direct Fulfillment:Remote patient monitoring devices and prescription wellness products require HIPAA-aligned handling protocols. Providers with healthcare logistics credentials access high-margin regulated verticals.
Industry Challenges
- Warehouse Automation Talent Scarcity:Integration of autonomous mobile robots and robotic picking systems demands mechatronics specialists and WMS engineers. Compensation inflation for technical roles outpaces operational budget growth.
- Multi-Tenant Security Architecture:Co-located inventory across competing brands elevates data segregation and physical access control requirements. Cyber insurance carriers are tightening coverage terms for shared-environment operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct to Customer Outsourced Fulfillment Market |
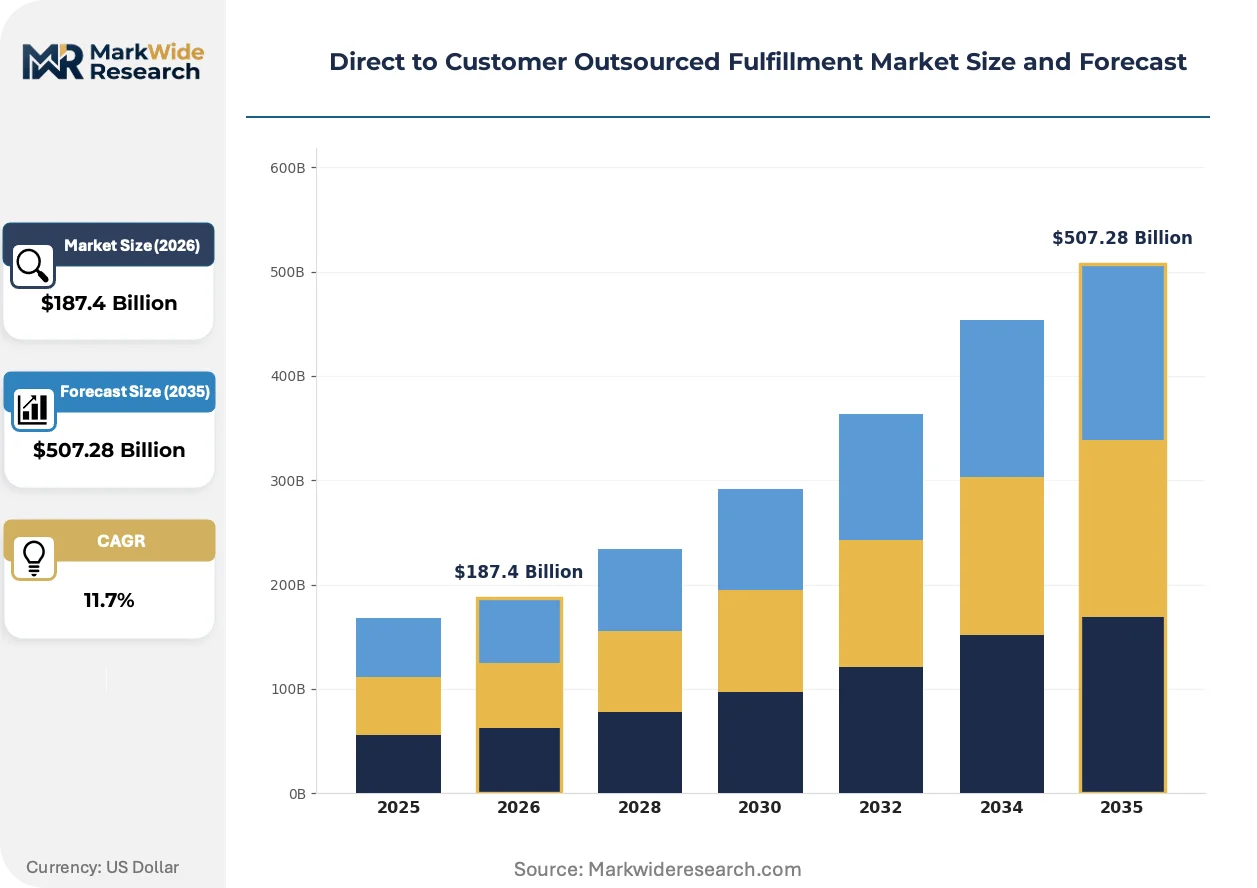
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Order Fulfillment, Inventory Management, Packaging, Shipping Customer Type: E-commerce Retailers, Subscription Services, Marketplaces, Brands Technology: Automation Solutions, Cloud Software, Warehouse Management Systems, Tracking Tools Delivery Mode: Standard Shipping, Same-Day Delivery, Next-Day Delivery, International Shipping |
| Companies Covered | FedEx Fulfillment, ShipBob, ShipMonk, Red Stag Fulfillment, Walmart Fulfillment, DCL Logistics, WareIQ, DHL Fulfillment, Whiplash, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct to Customer Outsourced Fulfillment Market Trends and Innovations
Artificial intelligence and edge-computing sensors are reconfiguring fulfillment operations from reactive cost centers into predictive demand-matching engines. Three developments are compressing competitive timelines across the sector.
Autonomous mobile robots equipped with computer vision and dynamic pathfinding algorithms are rendering obsolete static conveyor-based sortation systems. Mid-market e-commerce retailers are deploying these fleets at 200-400 unit scales within 18-month implementation windows. The technology is compressing order cycle times from hours to minutes while reducing warehouse labor headcount by 30-50%.
The EPA's evolving hazardous-material shipping regulations and OSHA warehouse safety standards are mandating automated chemical segregation and real-time air quality monitoring. Fulfillment providers handling lithium batteries, aerosols, and flammable cosmetics must retrofit facilities with sensor networks and automated containment systems. Operators in California, Texas, and New Jersey are front-loading capital expenditure to preempt enforcement actions.
Brand procurement of fulfillment services is fragmenting from single-provider contracts toward modular best-of-breed sourcing. Direct-to-consumer labels are unbundling storage, packaging, and delivery across specialized operators rather than accepting bundled service tiers. This pattern concentrates in apparel and home goods verticals where seasonal volatility demands flexible capacity arrangements.
Direct to Customer Outsourced Fulfillment Market Segmentation
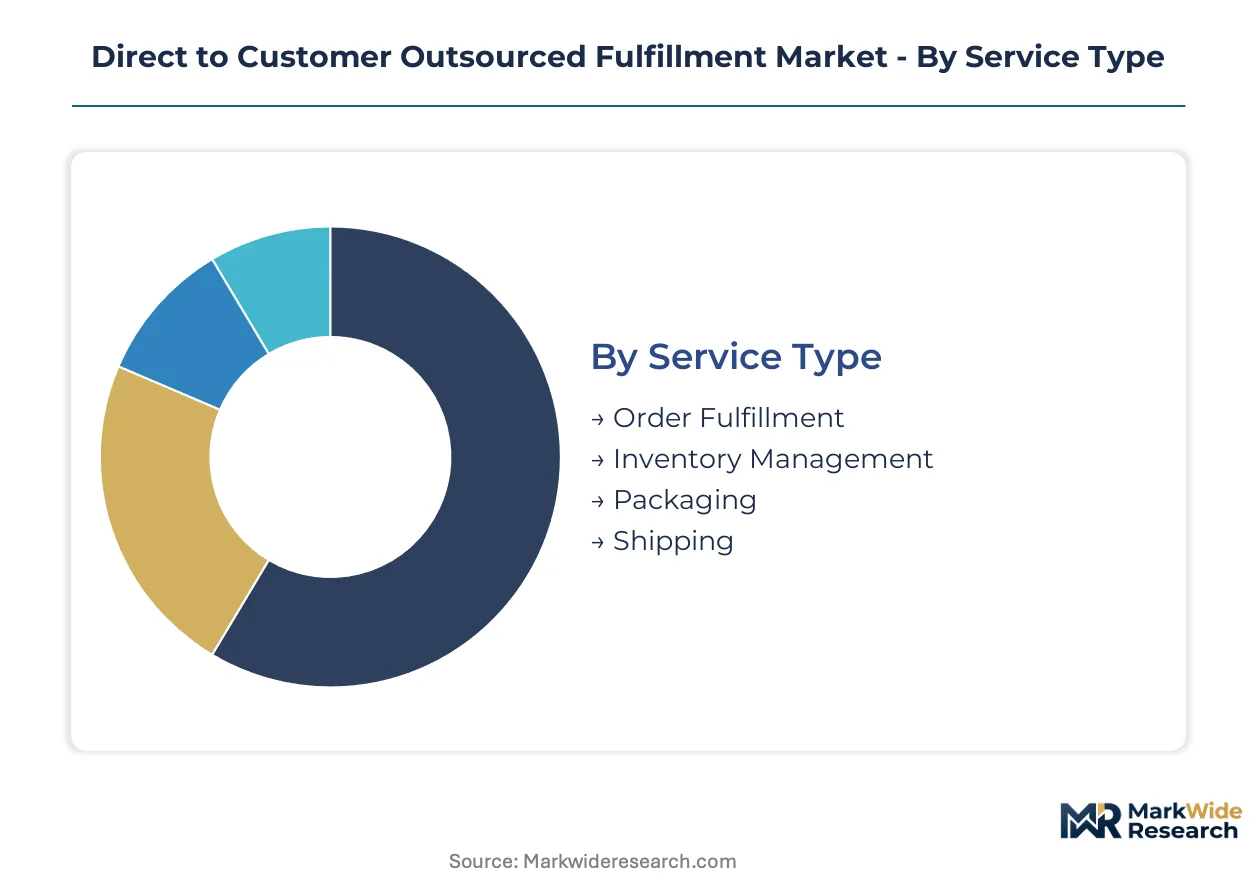
Segmentation in direct to customer outsourced fulfillment reveals how specialized capabilities command premium positioning. Service breadth, customer sophistication, technology intensity, and delivery speed requirements each create distinct operational and pricing architectures.
Service Type:
Cost tier determines margin structure across fulfillment services, with labor-intensive functions competing against capital-heavy automated alternatives.
- Order Fulfillment:End-to-end processing from pick-pack to carrier handoff dominates revenue pools. E-commerce retailers in the United States drive volume concentration as same-day mandates compress cycle times.
- Inventory Management:Demand forecasting and replenishment optimization commands premium pricing. Subscription services generate predictable stock rotation that improves warehouse utilization rates.
- Packaging:Custom kitting and branded unboxing experiences differentiate DTC brands. Cosmetic and wellness verticals require FDA-compliant lot-tracking documentation on every outbound shipment.
- Shipping:Carrier selection and rate negotiation aggregates purchasing power across multi-tenant facilities. Cross-border regulatory expertise separates tier-one providers from commodity brokers.
Order Fulfillment holds installed capacity. Inventory Management is rotating up the share rankings.
Customer Type:
Application complexity varies sharply across customer archetypes, with replenishment predictability enabling fundamentally different warehouse economics.
- E-commerce Retailers:Seasonal volatility and promotional surges demand elastic capacity contracts. Apparel and home goods brands in California and New York fragment procurement across modular specialists rather than single-source bundles.
- Subscription Services:Fixed replenishment cycles transform inventory from speculative risk into scheduled throughput. Beauty and pet supply verticals generate the highest predictability premiums in the customer mix.
- Marketplaces:Multi-seller aggregation platforms require real-time inventory visibility across dispersed vendor bases. Third-party sellers on these platforms outsource logistics to maintain Prime-equivalent delivery promises.
- Brands:Direct-to-consumer manufacturers prioritize control over customer experience and data capture. Electronics brands face FCC documentation requirements that specialized fulfillment operators handle at scale.
E-commerce Retailers anchor current volume. Subscription Services are climbing the fastest as replenishment models proliferate.
Technology:
Technology intensity separates capital-efficient operators from legacy competitors facing accelerated refresh cycles.
- Automation Solutions:Autonomous mobile robots and robotic picking systems compress labor headcount by 30-50%. Mid-market retailers deploy 200-400 unit fleets within 18-month implementation windows.
- Cloud Software:Native SaaS architectures enable real-time inventory visibility across distributed fulfillment nodes. API-first platforms integrate directly with Shopify, WooCommerce, and marketplace seller portals.
- Warehouse Management Systems:Modern WMS platforms orchestrate multi-tenant operations with dynamic slotting algorithms. Mechatronics specialists and WMS engineers command compensation premiums that outpace operational budget growth.
- Tracking Tools:Edge-computing sensors and predictive analytics transform fulfillment from reactive cost centers into demand-matching engines. Last-mile visibility APIs reduce customer service inquiry volumes.
Cloud Software holds installed capacity. Automation Solutions are gaining share fastest as robotics deployment accelerates.
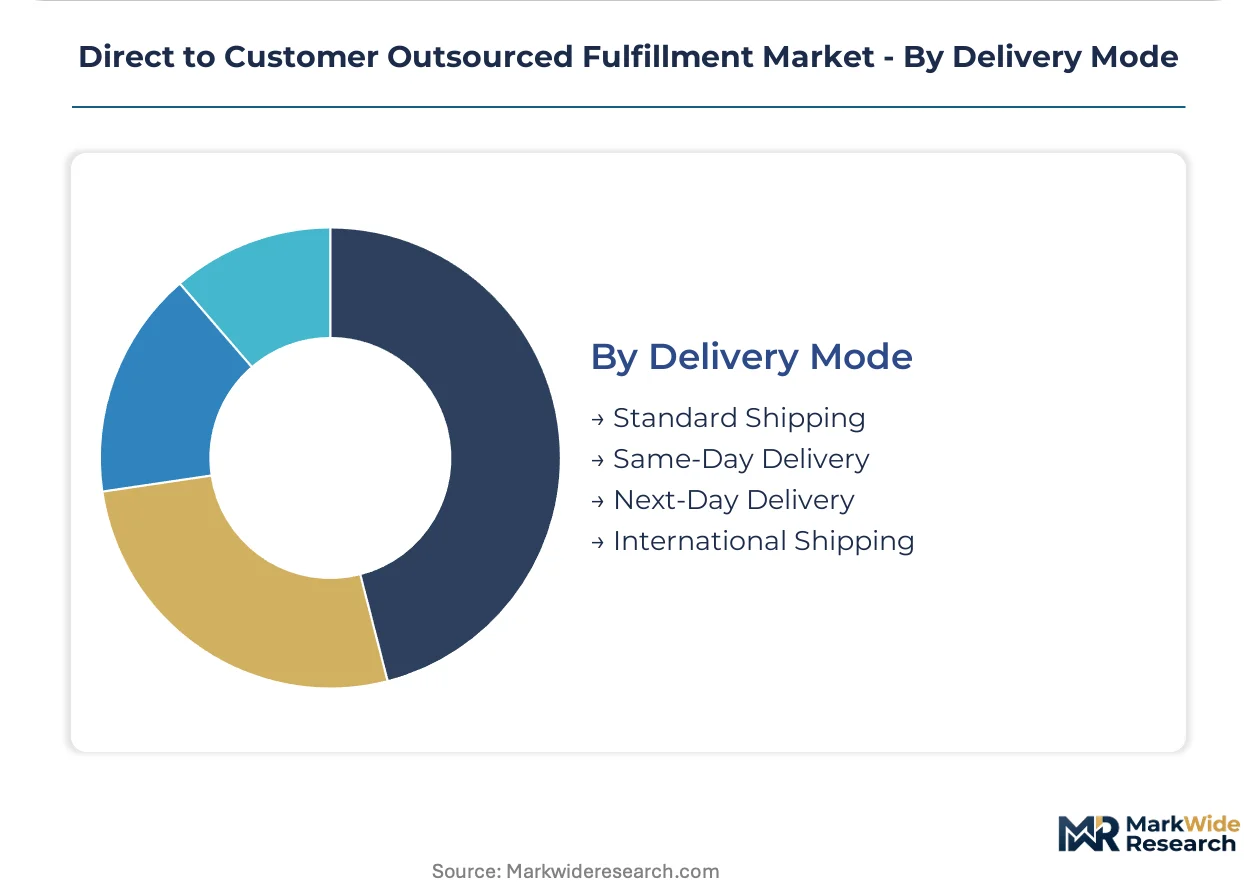
Delivery Mode:
Geography dictates delivery economics, with urban density enabling rapid fulfillment that suburban and rural networks cannot replicate profitably.
- Standard Shipping:Three-to-five-day ground delivery remains the cost-optimized default for non-urgent purchases. Rural zip codes and oversized items concentrate in this tier.
- Same-Day Delivery:Sub-24-hour dispatch mandates compel brands to abandon in-house logistics. Micro-fulfillment networks within 50 miles of Chicago, Dallas, and Atlanta demand scarcity premiums for prime real estate.
- Next-Day Delivery:Overnight promises require distributed inventory positioning and premium carrier contracts. East Coast corridor density from Boston to Washington DC enables economical next-day coverage.
- International Shipping:Cross-border fulfillment faces de minimis threshold reductions and enhanced inspection protocols at US ports. DHL and specialized operators compete on customs-clearance automation and regulatory expertise.
Standard Shipping holds installed capacity. Same-Day Delivery is rotating up the share rankings as urban consumer expectations harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies, with US brands absorbing premium pricing for same-day speed while Indian and Southeast Asian retailers prioritize cost-optimized standard delivery tiers.
United States
Dense last-mile infrastructure and elevated consumer delivery expectations sustain premium pricing power for rapid fulfillment services. FDA lot-tracking mandates for dietary supplements and cosmetics impose validated cold-chain requirements on third-party providers. The Chicago-Dallas-Atlanta triangle concentrates micro-fulfillment investment as scarcity premiums for prime industrial real estate reshape network economics.
Germany
Cross-border e-commerce penetration and stringent delivery reliability standards anchor demand for precision logistics services. REACH chemical safety regulations and CE marking requirements for electronics create compliance layers that specialized operators handle at scale. The Rhine-Ruhr industrial corridor hosts automated fulfillment campuses serving pan-European distribution networks.
China
Domestic e-commerce volume and super-app integration sustain the world's most intensive same-day delivery infrastructure. SAMR consumer protection rules and GB standards for product labeling mandate traceability systems that cloud-native operators deploy. The Yangtze River Delta clusters automated warehouses serving Shanghai-Nanjing-Hangzhou metropolitan demand.
United Kingdom
Subscription commerce proliferation and premium unboxing expectations drive demand for customized kitting services. GDPR data localization requirements and emerging carbon-disclosure mandates reshape provider selection criteria. The Midlands logistics golden triangle concentrates national distribution capacity within four-hour reach of major population centers.
India
E-commerce penetration in tier-two cities and cash-on-delivery preferences sustain cost-optimized fulfillment networks. FSSAI food safety regulations and BIS electronics certification create compliance entry barriers for international operators. The Mumbai-Pune and Delhi-NCR corridors anchor third-party logistics investment as infrastructure investment accelerates.
Direct to Customer Outsourced Fulfillment Market Competitive Landscape
Integrated transportation networks and specialized pure-play operators split the market between bundled service portfolios and modular best-of-breed sourcing. The vendor base concentrates around three strategic archetypes: asset-heavy carriers with captive last-mile infrastructure, technology-native platforms with distributed micro-fulfillment networks, and vertically integrated retailers monetizing excess capacity. Competitive dynamics center on M&A-driven geographic expansion and automation capital deployment cycles that compress labor-dependent cost structures.
Within the asset-heavy carrier tier, FedEx Fulfillment and DHL Fulfillment exemplify integrated network operators leveraging captive transportation infrastructure for end-to-end visibility. ShipBob anchors the technology-native platform segment, representing distributed micro-fulfillment specialists that position inventory within fifty miles of metropolitan demand clusters to enable economical same-day dispatch.
| Leading Market Players |
|---|
| FedEx Fulfillment |
| ShipBob |
| ShipMonk |
| Red Stag Fulfillment |
| Walmart Fulfillment |
| DCL Logistics |
| WareIQ |
| DHL Fulfillment |
| Whiplash |
| Others |
Pricing and Supply Chain Analysis
The Chicago-Dallas-Atlanta industrial triangle concentrates micro-fulfillment capacity within fifty miles of major demand clusters, creating scarcity premiums that flow downstream into same-day delivery pricing power for third-party operators.
Pricing Analysis
Returns processing and refurbishment services drive lifetime value expansion faster than base fulfillment fees. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated cold-chain handling from ambient storage and basic pick-pack operations. Cost compression in standard tiers intensifies as warehouse automation spreads and labor headcounts fall. Subscription services exhibit lowest price sensitivity due to inventory predictability premiums, while seasonal e-commerce retailers negotiate aggressively on per-unit transactional rates.
Supply Chain Analysis
Tariff exposure between China and the United States dominates cross-border fulfillment risk as de minimis threshold reductions slow parcel clearance. Component sourcing draws from Chinese automated equipment manufacturers, South Korean sensor suppliers, and German conveyor systems providers. Single-source vulnerability concentrates in cloud-native warehouse management software licensing. Distribution runs through multi-tenant facilities with dynamic slotting algorithms serving competing brands under shared roofs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct to customer outsourced fulfillment functions as a service-attach opportunity where reverse logistics and carbon-accounting compliance layers expand faster than core storage and shipping revenue pools.
For Market Incumbents: Pre-empt modular unbundling by acquiring specialized operators in returns refurbishment and healthcare-direct verticals. Defend against technology-native platforms by accelerating autonomous mobile robot deployment in the Chicago-Dallas-Atlanta corridor. Certification investment in FDA lot-tracking and HIPAA-aligned handling protocols preserves premium positioning against commodity brokers. For New Entrants and Emerging Players: Mid-market subscription brands in beauty and pet supply verticals represent the most penetrable entry point given their predictable replenishment cycles and willingness to pay utilization premiums. Carbon-disclosure compliance services for Scope 3 emissions reporting offer a second white-space target as sustainability mandates harden. Go-to-market positioning as a verified carbon-accounting partner unlocks preferential vendor status with ESG-conscious procurement teams. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified logistics conglomerates monetizing non-core fulfillment divisions as e-commerce growth strains captive capacity. Long-term viability hinges on automation capital deployment cycles that compress labor-dependent cost structures against technology-native competitors. Watch warehouse automation talent scarcity as an inflection signal—compensation inflation for mechatronics specialists and WMS engineers indicates which operators face accelerated margin pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Network Expansion | Positions inventory within fifty miles of Chicago, Dallas, and Atlanta demand clusters to enable economical same-day dispatch. |
| Healthcare Logistics Certification | Unlocks high-margin regulated verticals through HIPAA-aligned handling protocols for remote patient monitoring devices. |
| Reverse Logistics Monetization | Transforms returns processing from cost center into revenue stream through specialized refurbishment and resale channels. |
| Carbon-Accounting Infrastructure | Captures emerging Scope 3 emissions reporting demand with verified measurement systems for sustainability-conscious brands. |
| Autonomous Mobile Robot Deployment | Compresses order cycle times from hours to minutes while reducing warehouse labor headcount through computer vision fleets. |
Research Methodology
Desk research of customs filings, industrial real estate transaction databases, and carrier rate tariff disclosures preceded structured interviews with warehouse operations directors, third-party logistics procurement managers, e-commerce supply chain executives, and automation systems integrators. Primary fieldwork with fulfillment center operators and brand-side logistics strategists combined with secondary validation against EPA enforcement records and FDA inspection databases. Bottom-up capacity modeling and top-down revenue triangulation anchored market size estimation.
Assumptions held fixed include prevailing regulatory frameworks for delivery-worker classification and current de minimis thresholds for cross-border parcel clearance. Segmentation modeling spanned service type, customer archetype, technology intensity, and delivery mode across the projection horizon. CAGRs derived from elasticity-adjusted volume projections and pricing trajectory analysis. Forecast inputs incorporated warehouse automation deployment curves and industrial real estate vacancy rates near major metropolitan demand clusters.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending patterns or commercial real estate financing costs would shift the trajectory. Material shifts in FDA enforcement posture for dietary supplement lot-tracking or state-level delivery-worker reclassification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Global Software Outsourcing Market
Business Process Outsourcing (BPO)
Back Office Outsourcing Market
Business Process Outsourcing (BPO)
UAE Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Payroll Outsourcing Services Market
Business Process Outsourcing (BPO)
Customer Relationship Management (CRM) Outsourcing Market
Business Process Outsourcing (BPO)
Business Process Management (BPM) Market
Business Process Outsourcing (BPO)
IT Outsourcing Market
Business Process Outsourcing (BPO)
Procurement Outsourcing Services Market
Business Process Outsourcing (BPO)
Employment Screening Services Market
Business Process Outsourcing (BPO)
BFSI BPO Services Market
Business Process Outsourcing (BPO)
Indonesia Business Process Outsourcing Services Market
Business Process Outsourcing (BPO)
Middleoffice BPO Services Market
Business Process Outsourcing (BPO)
Cloud Based BPO Market
Business Process Outsourcing (BPO)
Business Process Re-Engineering Market
Business Process Outsourcing (BPO)
Global Knowledge Process Outsourcing Market
Business Process Outsourcing (BPO)
Public Cloud Business Process Services Market