
 Digital Fitness Coaches Market | 2026-2036
Digital Fitness Coaches Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Fitness Coaches Market Insights
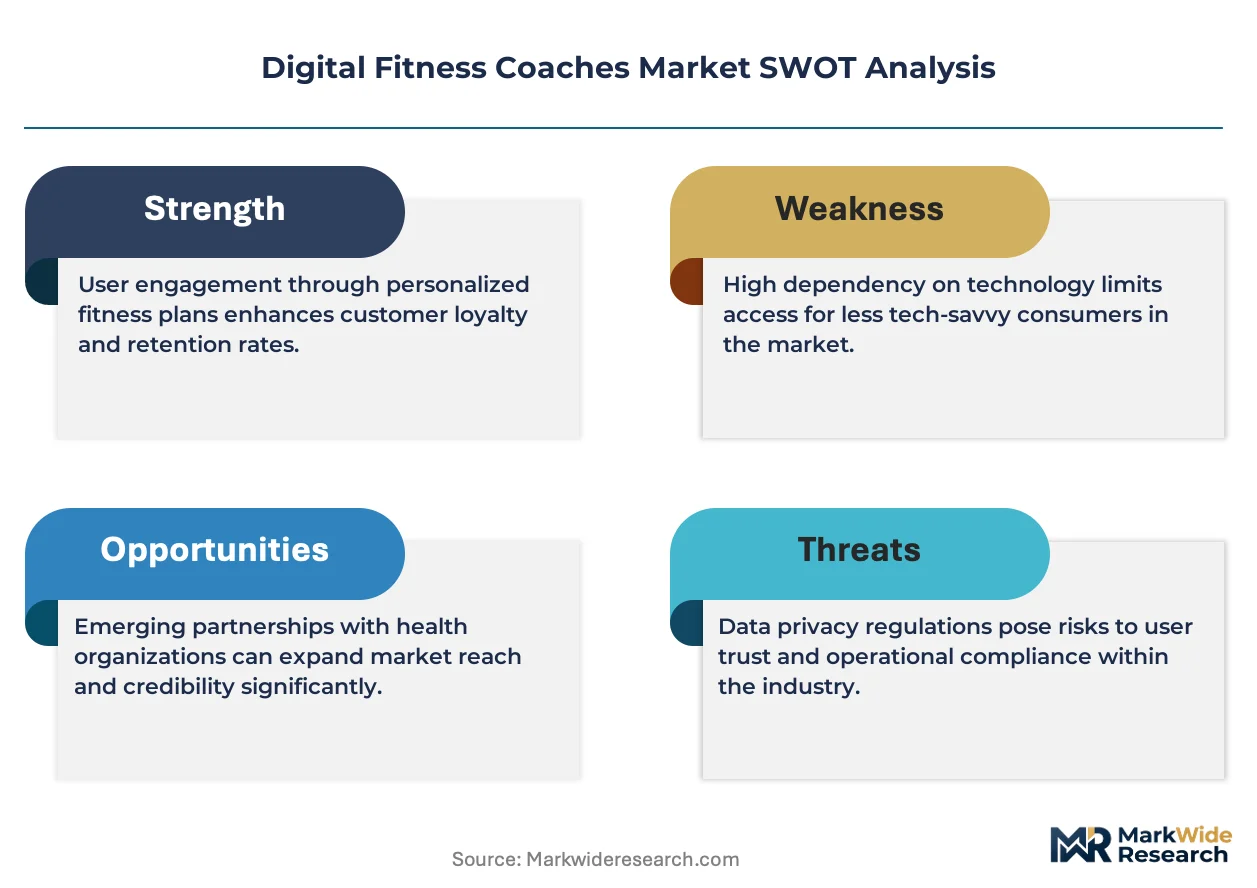
The EU AI Act is rebalancing how AI-driven fitness applications deploy recommendation engines across European markets. Peloton leverages its vertically integrated hardware-software ecosystem to sustain premium positioning in connected fitness. Tonal anchors strength in AI-powered resistance training through proprietary electromagnetic resistance technology. Zwift competes in virtual cycling by controlling immersive multiplayer environments that extend user retention cycles.
Digital fitness coaches are software-enabled platforms that deliver personalized exercise instruction, biometric feedback, and adaptive programming through mobile applications, wearable integrations, and cloud-based analytics, typically processing heart rate variability, motion capture, and recovery metrics to optimize training prescriptions. Mobile applications dominate engagement volume due to low friction onboarding and minimal hardware requirements. AI-driven solutions capture disproportionate R&D investment as platforms seek to automate program personalization and reduce human coach dependency. Wearable devices represent the fastest-growing technology segment as sensor accuracy improves and OEM partnerships expand distribution reach.
FDA oversight of software-as-medical-device claims intersects with FCC certification requirements for wearable radio transmitters in the United States, creating dual compliance pathways that filter market entrants by regulatory sophistication. The EU AI Act's risk classification framework imposes documentation and human oversight obligations on algorithmic coaching systems deployed in European markets. Stakeholders must monitor evolving jurisdictional definitions of wellness versus medical claims, as regulatory reclassification would trigger premarket authorization requirements and reshape competitive economics for platform providers.
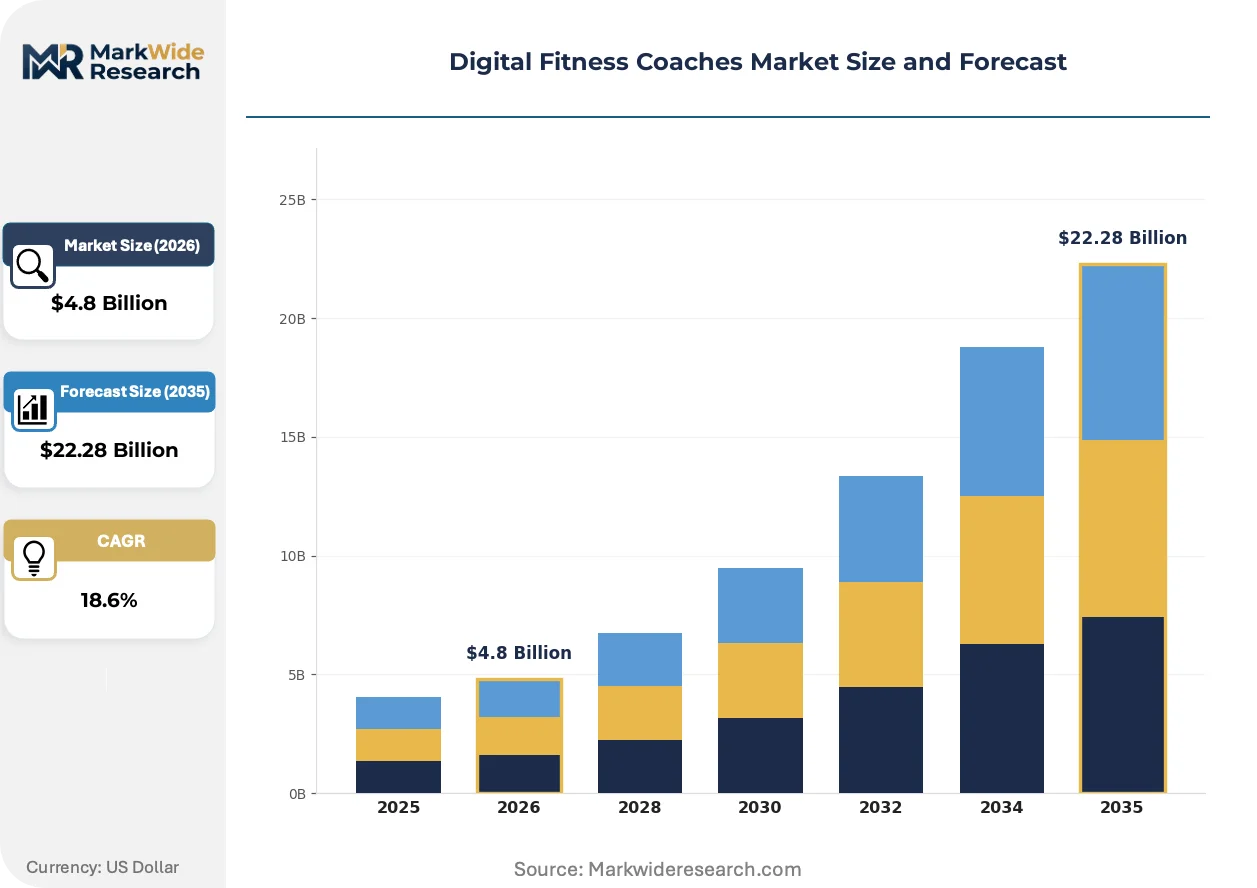
Market Dynamics
The EU AI Act is forcing algorithmic transparency mandates onto AI-driven coaching platforms, compelling providers to restructure recommendation engines and documentation workflows ahead of enforcement deadlines.
Growth Catalysts
- Corporate wellness mandates:Large employers in the United States are integrating digital coaching into benefits packages to reduce insurance premiums and absenteeism costs.
- Wearable sensor convergence:Photoplethysmography and accelerometer advances enable continuous biometric streaming without dedicated hardware purchases.
- EU AI Act compliance services:Risk classification frameworks for algorithmic health recommendations create consulting and platform retrofit demand among European providers.
Market Restraints
- Dual certification burden:FDA software-as-medical-device pathways intersect with FCC radio transmitter approvals, filtering entrants by regulatory sophistication.
- Cloud infrastructure concentration:AWS, Google Cloud, and Microsoft Azure control the majority of compute resources for real-time biometric processing.
- Substitution by human coaching:High-net-worth individuals and rehabilitation patients prefer in-person instruction for accountability and form correction.
Strategic Opportunities
- Medicare Advantage penetration:United States insurers are expanding supplemental benefit coverage to include digital fitness programs for aging populations.
- Electromyography integration:Convergence of surface EMG sensors with resistance training hardware enables real-time muscle activation feedback.
- Employer channel bypass:Direct-to-consumer subscription models with annual billing cycles reduce customer acquisition costs versus B2B sales cycles.
Industry Challenges
- Exercise physiologist scarcity:Platforms struggle to hire credentialed professionals for algorithm training and content validation at scale.
- Interoperability fragmentation:Proprietary data formats from Apple Health, Google Fit, and Garmin limit seamless user experience across device ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Fitness Coaches Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Personal Training, Nutritional Coaching, Group Classes, Wellness Programs Technology: Mobile Applications, Wearable Devices, Online Platforms, AI-Driven Solutions Customer Type: Individuals, Corporates, Fitness Enthusiasts, Beginners Engagement Model: Subscription-Based, Pay-Per-Session, Free Trial, Partnerships |
| Companies Covered | Peloton, Tonal, Technogym, Life Fitness, Nautilus Inc, Zwift, Trainerize, ClassPass Inc., eGym GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Fitness Coaches Market Trends and Innovations
Biometric feedback loops are compressing the latency between sensor data and coaching intervention, reshaping how platforms architect real-time personalization engines and user retention mechanics.
Computer vision form analysis is absorbing smartphone camera capabilities for movement assessment without specialized hardware. Boutique fitness studios and physical therapy chains are adopting this technology to reduce staff-to-client ratios. The capability is absorbing market share from wearable-dependent solutions by eliminating upfront hardware costs.
The EU AI Act's high-risk system classification imposes human oversight requirements on algorithmic coaching recommendations that process biometric data. European providers must maintain technical documentation and conformity assessments for market access. Germany and France are seeing the earliest enforcement activity, with national regulators requesting algorithmic impact assessments from platform operators.
Subscription fatigue among digital health consumers is shortening trial-to-commitment windows and raising churn sensitivity. Annual billing with installment flexibility is displacing monthly-only plans in direct-to-consumer channels. This pattern is most visible in the United States, where credit-based financing integrations reduce sticker-price resistance.
Digital Fitness Coaches Market Segmentation
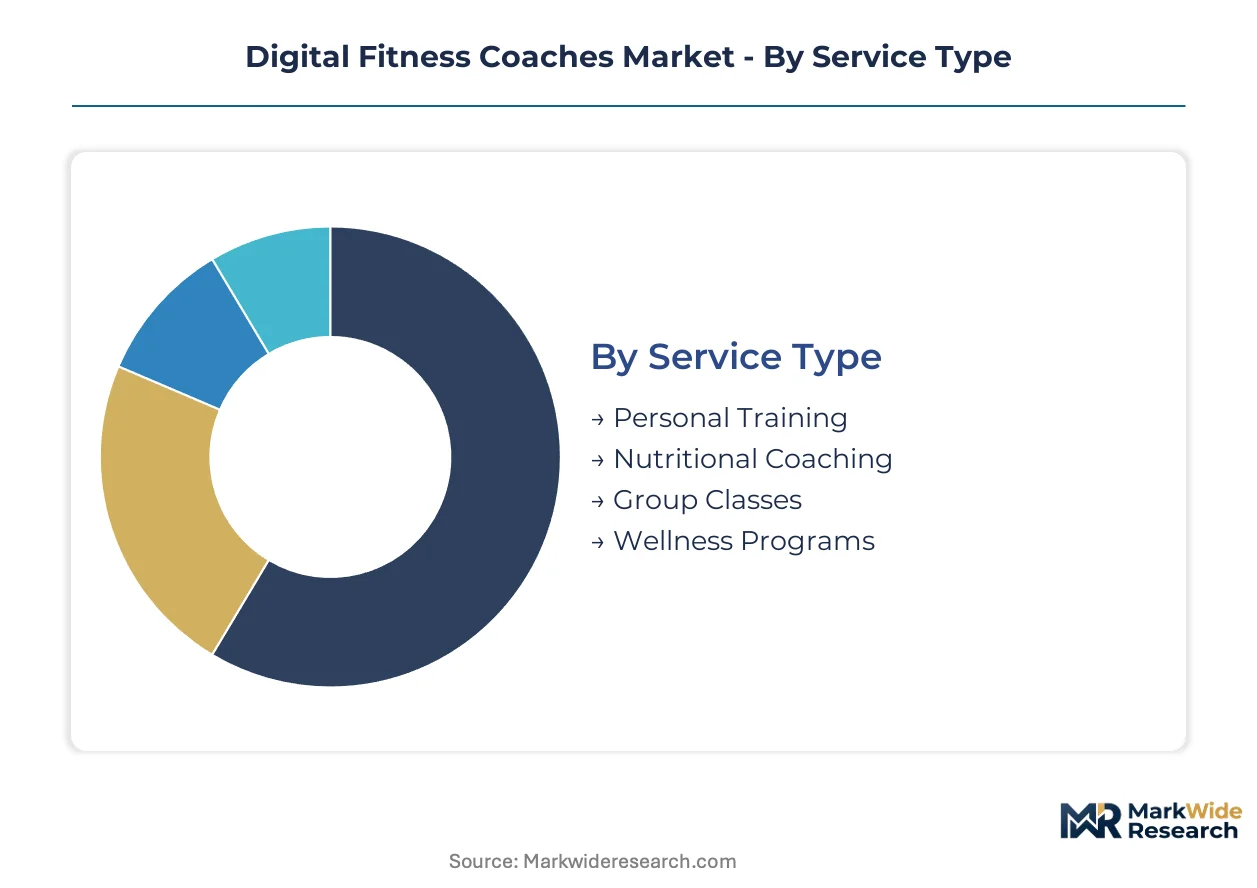
Segmentation in digital fitness coaching reveals how value pools distribute across integration architectures. Standalone mobile applications compete against embedded systems within corporate benefits stacks and hardware ecosystems.
Service Type:
Standalone coaching services operate through direct consumer relationships, while embedded wellness programs integrate into employer benefits and insurance platforms.
- Personal Training:One-on-one video coaching with real-time form correction and program customization. Demand concentrates among United States urban professionals seeking accountability without gym commutes, constrained by exercise physiologist scarcity for algorithm training.
- Nutritional Coaching:AI-generated meal planning integrated with biometric feedback from wearables. Adoption is accelerating in Germany and France as EU AI Act transparency requirements reshape how automated dietary recommendations deploy.
- Group Classes:Synchronous virtual sessions with community features and leaderboard mechanics.
- Wellness Programs:Holistic packages combining fitness, nutrition, and mental health modules for employer-sponsored deployment.
Personal training leads volumes today; nutritional coaching is gaining share fastest.
Technology:
Cost tiers separate minimal-friction mobile entry from premium hardware-software bundles requiring capital expenditure.
- Mobile Applications:Software-only delivery through iOS and Android with cloud-based program storage. Volume concentrates in direct-to-consumer United States markets where low onboarding friction drives trial conversion, though subscription fatigue shortens commitment windows.
- Wearable Devices:Sensor-integrated hardware capturing heart rate variability, accelerometry, and sleep metrics. Adoption is expanding most quickly through OEM partnerships with Apple, Garmin, and Samsung as photoplethysmography accuracy improves.
- Online Platforms:Browser-based coaching portals with video libraries and progress dashboards.
- AI-Driven Solutions:Algorithmic program generation with adaptive difficulty scaling and injury risk prediction.
Mobile applications lead volumes today; wearable devices are climbing the fastest.
Customer Type:
Application maturity varies across customer sophistication, from novice users needing guided onboarding to enterprises requiring administrative controls.
- Individuals:Direct subscribers purchasing through app stores or brand websites. Demand clusters in United States metropolitan areas with highest smartphone penetration and credit-based financing availability.
- Corporates:Employer-sponsored wellness benefits integrated with HR systems and insurance premium reductions. United States large employers are expanding adoption fastest to reduce absenteeism costs.
- Fitness Enthusiasts:Performance-oriented users seeking advanced analytics and periodization tools.
- Beginners:Entry-level users requiring simplified interfaces and progressive skill scaffolding.
Individuals lead volumes today; corporates are expanding most quickly.
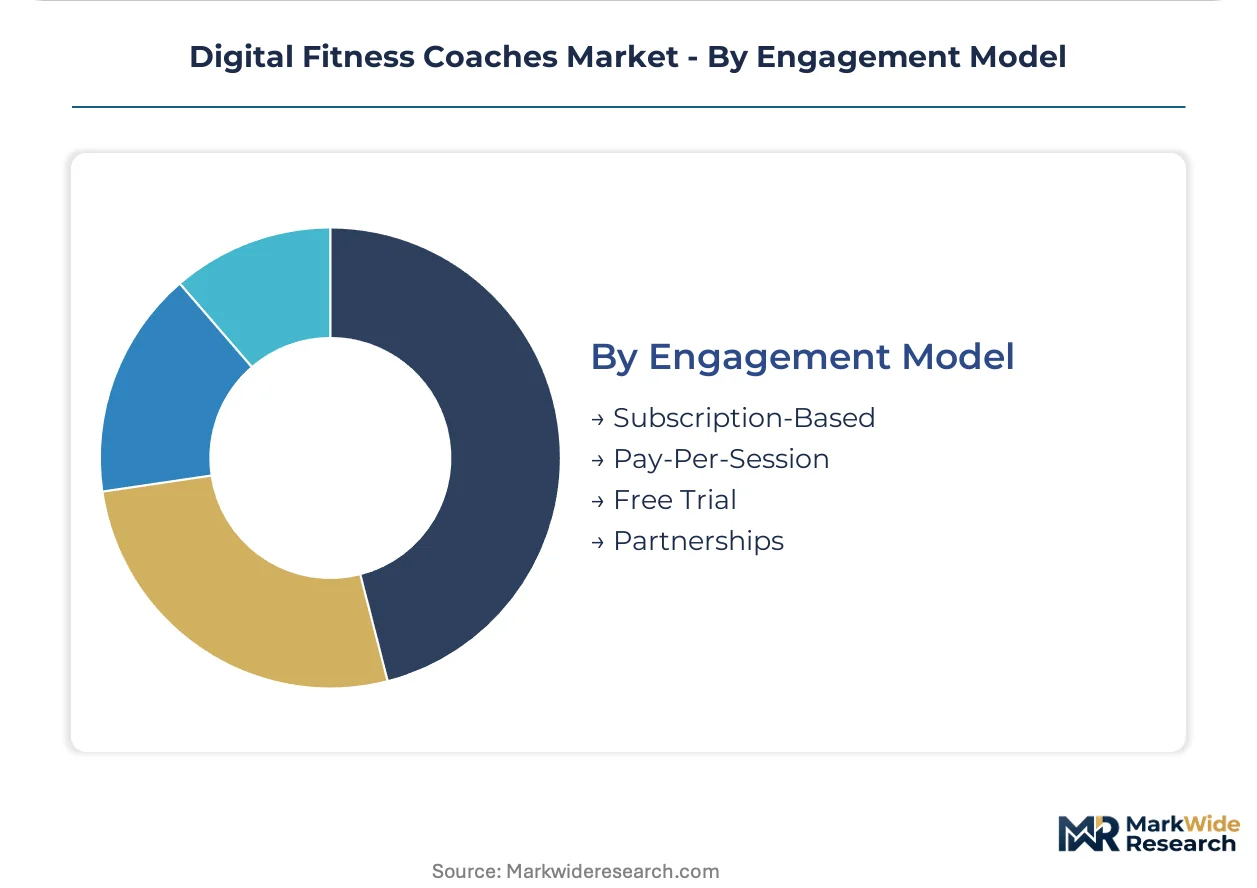
Engagement Model:
Margin structure differs fundamentally between recurring subscription revenue and transactional session economics.
- Subscription-Based:Monthly or annual recurring billing with unlimited platform access. United States providers are shifting toward annual billing with installment flexibility to reduce churn sensitivity.
- Pay-Per-Session:Single-session purchases for live coaching or premium content unlocks. Demand concentrates among rehabilitation patients and high-net-worth individuals preferring human accountability.
- Free Trial:Time-limited access converting to paid tiers through usage-based triggers.
- Partnerships:B2B2C distribution through gyms, insurance carriers, and healthcare providers.
Subscription-based leads volumes today; partnerships are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The digital fitness coaching industry traces its commercial origins to Silicon Valley's 2010s app economy, where venture capital first scaled subscription-based wellness platforms before hardware-software integration migrated toward European and Asian manufacturing clusters.
United States
Employer-sponsored wellness benefits and Medicare Advantage supplemental coverage are accelerating platform adoption among aging populations and corporate workforces. FDA software-as-medical-device oversight intersects with FCC certification for wearable transmitters, creating dual compliance pathways that favor established providers. The San Francisco Bay Area and New York Metro anchor venture funding concentration and talent pipelines for AI coaching development.
Germany
Corporate health insurance mandates and Betriebskrankenkassen wellness budgets are expanding B2B platform procurement. The EU AI Act's high-risk system classification imposes documentation obligations on algorithmic coaching recommendations, with Germany's national regulator requesting early impact assessments. Berlin and Munich host the densest clusters of fitness technology startups adapting to transparency requirements.
United Kingdom
Private health insurance integration and NHS digital health pilot programs are creating reimbursement pathways for preventive fitness interventions. GDPR biometric data processing rules constrain how platforms handle heart rate variability and motion capture from UK subscribers. London's fintech infrastructure supports credit-based annual billing models that reduce subscription fatigue.
Japan
Aging demographics and METI's Society 5.0 healthy longevity initiatives are driving demand for home-based coaching among seniors. The Pharmaceutical and Medical Devices Act creates regulatory boundaries between wellness claims and medical device classification that platforms must navigate carefully. Tokyo and Osaka concentrate hardware partnerships with domestic electronics OEMs integrating coaching software.
Australia
Private health fund rebate eligibility for digital wellness programs is expanding employer and individual adoption. The Therapeutic Goods Administration monitors software claims that encroach on therapeutic purpose thresholds. Sydney and Melbourne host regional headquarters for global platforms targeting Asia-Pacific market expansion.
Digital Fitness Coaches Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in the digital fitness coaching market. Hardware-integrated platforms absorb substantial upfront manufacturing costs and inventory risk, while pure-software providers scale through cloud infrastructure without physical supply chains. Three archetypes dominate: vertically integrated hardware-software ecosystems, AI-native coaching platforms, and corporate wellness aggregators. M&A activity concentrates on talent acquisition for exercise physiologists and algorithm engineers, while strategic partnerships with wearable OEMs expand distribution reach without capital expenditure.
Among hardware-integrated specialists, Peloton and Tonal exemplify the premium-tier ecosystem archetype through proprietary equipment tied to subscription content. Zwift occupies a position within the immersive multiplayer segment, leveraging virtual environment control to extend user retention cycles. eGym GmbH represents the European B2B equipment-software convergence model, embedding coaching capabilities directly into commercial gym infrastructure.
| Leading Market Players |
|---|
| Peloton |
| Tonal |
| Technogym |
| Life Fitness |
| Nautilus Inc |
| Zwift |
| Trainerize |
| ClassPass Inc. |
| eGym GmbH |
| Others |
Pricing and Supply Chain Analysis
Cloud compute spot pricing indices cascade through digital fitness coaching platforms into tiered subscription economics, compressing margins for AI-heavy providers while hardware-integrated ecosystems absorb sensor component volatility through captive manufacturing partnerships in Taiwan and Shenzhen.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by hardware bundling intensity and algorithm sophistication. Premium tiers command substantial markups through proprietary electromagnetic resistance hardware and real-time biometric feedback, while economy tiers compete on mobile-only delivery with minimal sensor integration. Cost compression in the mid-market intensifies as AWS Reserved Instance commitments mature and platforms pass through compute savings to retain subscribers. Corporate wellness buyers exhibit lowest price sensitivity due to insurance premium reduction offsets, whereas direct-to-consumer segments face acute churn pressure from subscription fatigue.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Singapore anchor hub-and-spoke fulfillment for wearable hardware, with final assembly concentrated in China, Vietnam, and Mexico to optimize tariff exposure and logistics costs. Photoplethysmography sensors, accelerometer modules, and lithium-polymer batteries constitute critical component dependencies, with supply continuity tethered to Apple, Garmin, and Samsung OEM allocation decisions. Single-source vulnerability in advanced biometric chipsets from Taiwan-based foundries poses structural risk for real-time coaching platforms dependent on continuous heart rate variability streaming. Distribution runs through direct-to-consumer e-commerce channels and B2B enterprise procurement portals, with corporate wellness aggregators consolidating purchasing power across employer benefits stacks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital fitness coaching market functions as a geographic-arbitrage play where EU AI Act compliance costs in Germany and France run substantially higher than FDA software-as-medical-device pathways in the United States, creating divergent margin structures for platforms operating across both regulatory environments.
For Market Incumbents: Deploy algorithmic transparency tooling ahead of enforcement deadlines to preempt EU AI Act documentation demands and human oversight requirements. Consolidate exercise physiologist talent pools through acquisition of boutique physical therapy chains, countering scarcity-driven wage inflation for credentialing professionals. Deepen backward integration into sensor hardware design to reduce dependency on Apple HealthKit and Google Fit interoperability fragmentation. For New Entrants and Emerging Players: Computer vision form analysis offers a technology-first wedge into rehabilitation and physical therapy white space, eliminating upfront wearable hardware costs while absorbing smartphone camera capabilities for movement assessment. Medicare Advantage supplemental benefit coverage in the United States represents the most penetrable reimbursement pathway, with aging populations underserved by current platform demographics. Pursue direct-to-consumer annual billing with credit-based financing integrations to reduce customer acquisition costs versus extended B2B sales cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-native coaching platforms possessing proprietary training datasets and algorithmic personalization engines, particularly those with established FDA software-as-medical-device predicates enabling rapid EU MDR adaptation. Long-term viability hinges on sustained R&D intensity through venture funding dry spells and corporate wellness contract renewals. Watch for inflection in employer channel bypass rates as direct-to-consumer annual billing displaces B2B procurement, signaling platform margin recovery independent of enterprise sales cycle elongation.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Transparency Compliance | EU AI Act documentation investments secure market access across Germany, France, and Netherlands regulatory clusters. |
| Exercise Physiologist Acquisition | Boutique physical therapy chain purchases address credentialing scarcity for algorithm training and content validation. |
| Medicare Advantage Partnership | Supplemental benefit coverage expansion targets aging United States populations with preventive fitness interventions. |
| Computer Vision Product Launch | Smartphone camera-based form analysis eliminates hardware costs and absorbs market share from wearable-dependent competitors. |
| Annual Billing Model Transition | Credit-based financing integrations reduce subscription fatigue churn in direct-to-consumer United States channels. |
Research Methodology
Direct dialogue with platform engineering leads, corporate wellness benefits directors, exercise physiologists, and wearable OEM partnership managers grounded qualitative insights in operational reality. Secondary validation drew from FDA software-as-medical-device filings, EU AI Act impact assessments, SEC 10-K disclosures from listed fitness technology firms, and App Annie mobile engagement metrics. Bottom-up and top-down triangulation reconciled subscriber counts, average revenue per user estimates, and hardware shipment data against aggregate market value projections.
Bottom-up modeling segmented volume and value across service type, technology platform, customer archetype, and engagement model dimensions, with CAGRs derived from regression analysis of historical adoption curves and elasticity-adjusted price trajectories. Top-down validation cross-checked against venture funding deployment patterns, corporate wellness budget growth, and Medicare Advantage supplemental benefit expansion rates. Photoplethysmography sensor shipment forecasts and cloud infrastructure capex disclosures from hyperscalers informed technology segment sizing across the projection horizon.
The model holds under stable regulatory classification of wellness versus medical device claims; deviation in FDA or EU MDR reclassification triggers would shift premarket authorization requirements and reshape competitive economics. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness
Active Passive Trainer Market
Sports & Fitness
Japan Fitness Ring Market
Sports & Fitness
Global Stand-Up Paddleboard Market
Sports & Fitness
Global Golf Training Aids Market
Sports & Fitness
Hiking Backpacks Market
Sports & Fitness
India Fantasy Sports Market
Sports & Fitness
Sports Fishing Equipment Market
Sports & Fitness
France Artificial Turf Market
Sports & Fitness
China Gym Accessories Market
Sports & Fitness
Weight Management Supplements Market
Sports & Fitness
Motorized Pool Tube Market
Sports & Fitness
Europe Health and Wellness Market
Sports & Fitness
Fitness and Recreational Sports Centers Market
Sports & Fitness
Fitness Ball Market
Sports & Fitness
Smart Sports Wearables Market
Sports & Fitness
Gear Bicycle Market