
 Digital Distribution Market | 2026-2036
Digital Distribution Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Distribution Market Analysis
GDPR's extraterritorial reach is realigning how platforms architect data flows and consent mechanisms. DistroKid leverages automated royalty splits to sustain creator loyalty across fragmented streaming ecosystems. CD Baby anchors physical-digital hybrid catalog management for legacy artists navigating rights complexity. UnitedMasters competes by offering direct brand partnership pipelines that bypass traditional label intermediation.
Digital distribution encompasses the electronic delivery of software, video, music, and e-books through internet-connected infrastructure, utilizing content delivery networks with sub-100ms latency thresholds and adaptive bitrate protocols to ensure seamless end-user experience. Its primary commercial purpose eliminates physical manufacturing and retail intermediation, enabling instantaneous global availability with near-zero marginal unit cost. Streaming dominates revenue generation across music and video segments, while subscription delivery models capture the most predictable recurring revenue pools. Download-based distribution retains relevance in enterprise software and high-resolution audio niches where offline permanence commands premium positioning.
The EU Digital Services Act and the US Digital Millennium Copyright Act shape platform liability frameworks, while the WIPO Copyright Treaty harmonizes cross-border enforcement standards. Content creators and distributors must monitor evolving mechanical royalty rate proceedings and platform-specific licensing renegotiations. Stakeholders should prioritize transparent royalty reporting infrastructure and preemptive rights-clearance workflows before regulatory mandates harden compliance costs.
Market Dynamics
Platform liability obligations under the EU Digital Services Act are forcing distributors to rebuild content moderation infrastructure and audit algorithms for systemic risk, diverting engineering resources from product innovation toward compliance architecture.
Growth Catalysts
- Independent Creator Monetization:Direct-to-fan tools enable musicians and podcasters to bypass traditional label structures. Royalty automation sustains platform loyalty across fragmented streaming ecosystems.
- GDPR Extraterritorial Enforcement:Consent mechanism standardization creates competitive moats for platforms with robust data governance. Privacy-compliant architectures attract enterprise licensing deals.
- Adaptive Bitrate Protocols:Sub-100ms latency thresholds expand addressable markets into live interactive formats. CDN infrastructure investments unlock real-time creator-audience engagement.
Market Restraints
- Mechanical Royalty Rate Volatility:Copyright Royalty Board proceedings in the United States create revenue uncertainty. Platforms face retroactive liability exposure from rate recalculations.
- Supply-Side Platform Concentration:Three dominant streaming services control access to subscriber bases. Distributor margins compress during licensing renegotiations.
- Legacy Rights Complexity:Physical-digital hybrid catalogs require manual clearance workflows. Estate management for deceased artists blocks catalog digitization.
Strategic Opportunities
- Enterprise SaaS Distribution:Offline-permanent software delivery retains premium pricing in regulated industries. High-resolution audio niches command subscription premiums.
- Brand Partnership Pipelines:Direct creator-brand matching bypasses label intermediation. United States-based influencer infrastructure enables scalable sponsorship automation.
- EU AI Act Compliance Services:Transparency mandates for algorithmic recommendation systems create advisory revenue streams. Distributors can monetize audit and documentation tools.
Industry Challenges
- Royalty Reporting Talent Scarcity:Data engineering expertise for multi-territorial rights accounting commands premium compensation. Platforms compete for specialists with music publishing backgrounds.
- Cross-Border IP Disputes:WIPO Copyright Treaty harmonization remains incomplete. Territorial licensing conflicts delay content availability windows.
- Preemptive Rights-Clearance Capex:Automated clearance workflows require upfront investment in machine learning training data. Smaller distributors lack capital for competitive infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Distribution Market |
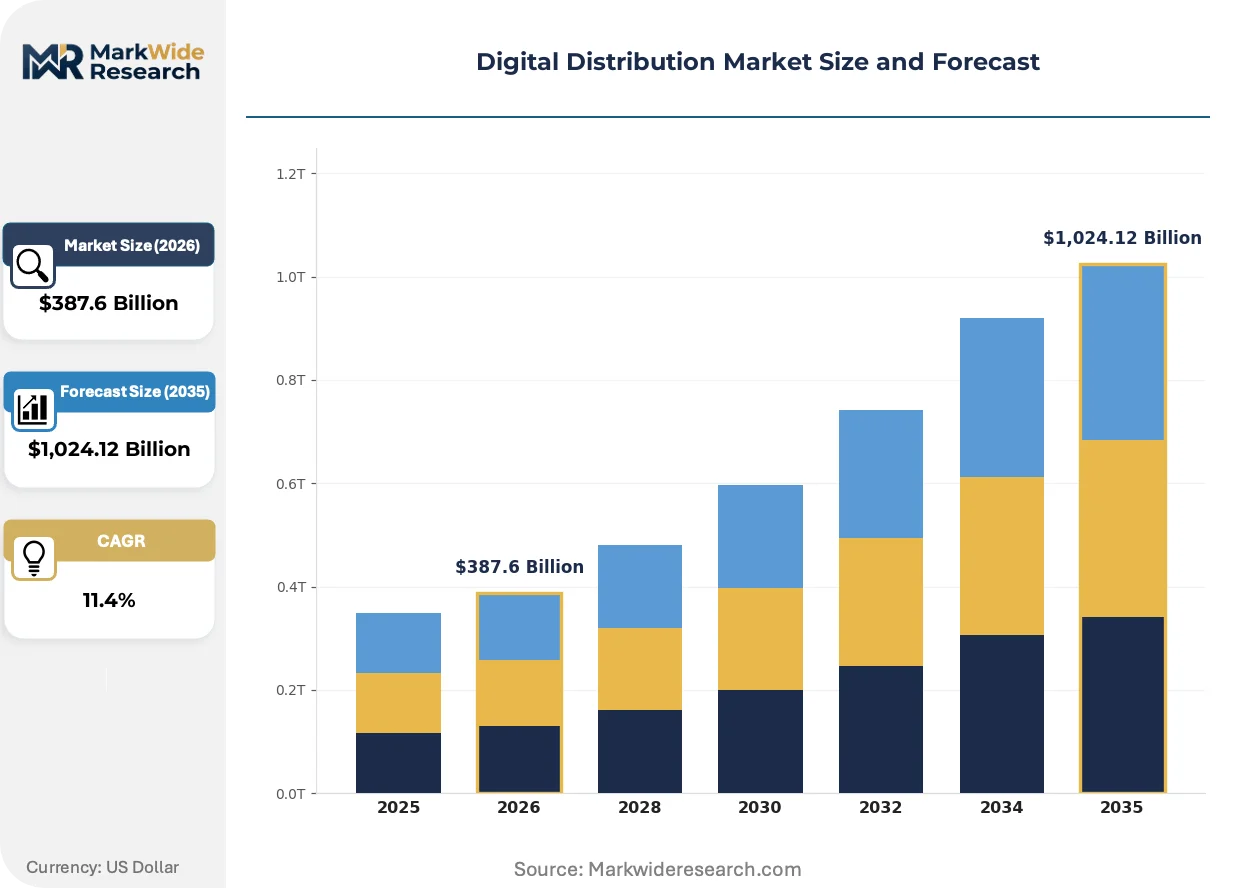
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Video, Music, E-books Delivery Model: Streaming, Download, Subscription, On-Demand Customer Type: Individual Consumers, Businesses, Educational Institutions, Content Creators Platform: Mobile Apps, Websites, Desktop Applications, Social Media |
| Companies Covered | LANDR, Ditto Music, DistroKid, Songtradr, Amuse, TuneCore, UnitedMasters, ONErpm, CD Baby, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Distribution Market Emerging Trajectories
Blockchain-based royalty tracking and algorithmic content moderation are reconfiguring trust architectures between creators, platforms, and rights holders. These shifts compress settlement timelines while expanding compliance surface areas.
Smart contract protocols for automated royalty splits are decentralizing payment verification away from centralized platform accounting. Independent musicians in the United States and Europe are adopting these tools to reduce payment latency from quarters to days. This architecture is decentralizing trust relationships between creators and distributors, enabling direct fan funding models that bypass traditional advance structures.
The EU Digital Services Act's systemic risk audit mandates are reshaping platform engineering roadmaps. Large online platforms must now maintain algorithmic transparency registers and external audit trails. Music and video distributors serving EU audiences are rebuilding recommendation engines to satisfy documentation requirements, prioritizing explainability over engagement optimization.
Creator procurement of distribution services now emphasizes ownership retention over upfront advances. Musicians and podcasters in North America and Western Europe are selecting platforms based on master rights preservation and data portability. This behavior is fragmenting distributor market positions, as loyalty shifts toward tools that enable direct audience relationships rather than exclusive catalog control.
Digital Distribution Market Segmentation
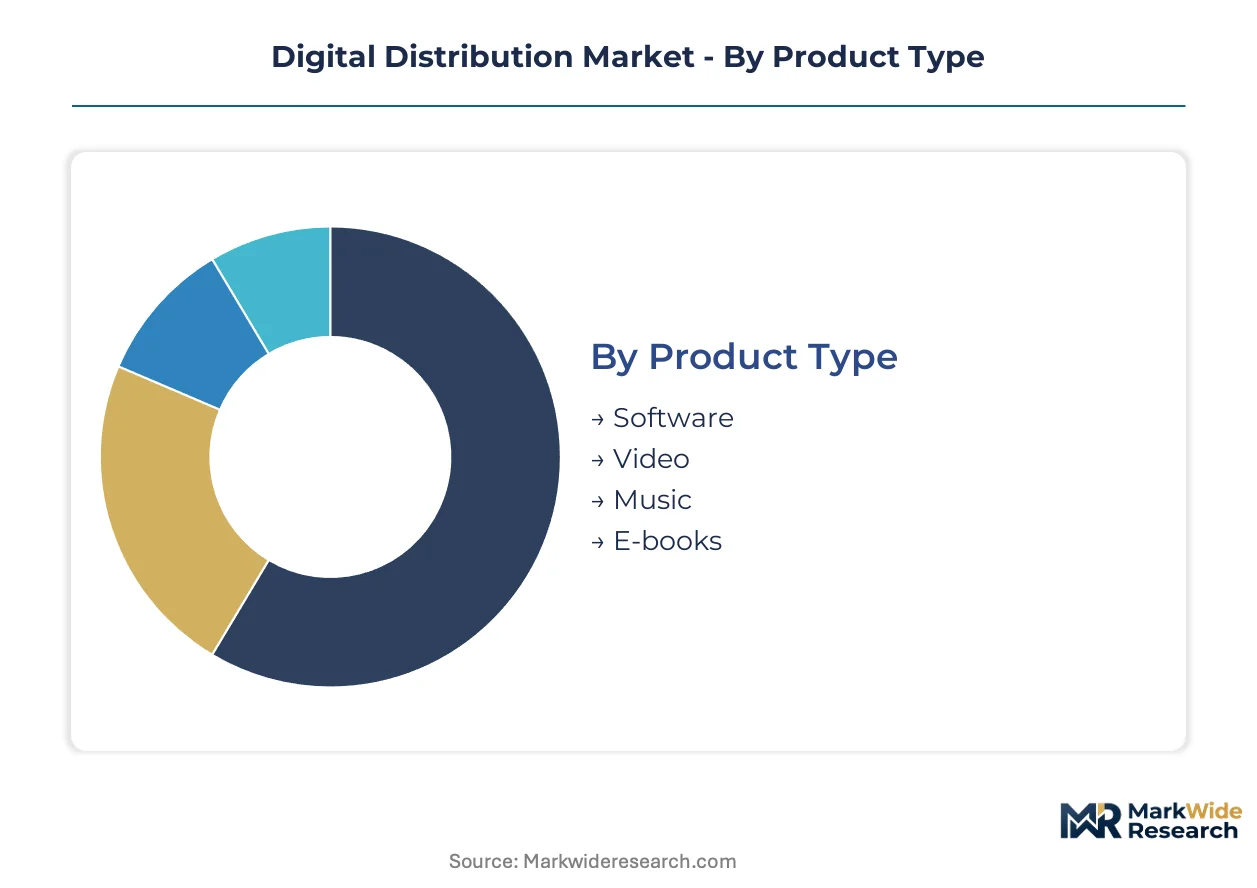
Segmentation in digital distribution reveals how infrastructure investments and monetization architectures diverge across content formats and access modes. Understanding these splits illuminates where latency requirements, rights complexity, and customer acquisition costs concentrate capital deployment.
Product Type:
Customization versus standardization tension runs deepest here, with software demanding tailored enterprise deployment against music's universal codec standardization.
- Software:Enterprise SaaS packages require modular API architectures and offline-permanent licensing for regulated industries like healthcare and finance. Deployment in the United States concentrates around HIPAA-compliant and SOX-audited workflows, with procurement teams prioritizing security certification over unit cost. Compliance overhead sustains premium pricing tiers absent in consumer segments.
- Video:Adaptive bitrate protocols with sub-100ms latency thresholds enable live interactive formats from esports to telemedicine. Demand clusters in metropolitan United States markets with fiber-dense CDN backbones, where 4K and 8K resolution tiers command subscription premiums. Rights windowing complexity fragments catalog availability across territories.
- Music:Lossless and hi-res audio codecs serve audiophile niches with permanent download options. Mechanical royalty rate volatility in the United States creates pricing uncertainty for streaming bundles.
- E-books:Reflowable EPUB dominates mass-market fiction while fixed-layout PDF retains textbook and technical documentation segments. Educational procurement in North America drives institutional licensing volume.
Most installed capacity flows through Video. Expansion is steepest in Software.
Delivery Model:
Cost tier stratification separates capital-intensive streaming infrastructure from lightweight download margins.
- Streaming:CDN edge nodes with real-time transcoding consume the majority of platform infrastructure spend. North American and Western European markets absorb the highest per-subscriber acquisition costs due to saturated competition among three dominant services.
- Subscription:Recurring revenue predictability attracts enterprise SaaS and premium audio tiers. United States-based creator-economy infrastructure enables scalable sponsorship automation bundled with distribution access.
- Download:Offline permanence retains relevance in enterprise software and high-resolution audio niches. Margins compress against streaming alternatives but regulatory requirements sustain demand.
- On-Demand:Transactional video and single-track purchases serve non-subscriber audiences. Catalog depth limitations restrict growth against unlimited streaming alternatives.
Subscription captures the majority of recurring revenue pools. Streaming climbs the fastest as live interactive formats expand addressable markets.
Customer Type:
Volume concentration versus margin extraction divides individual mass markets from negotiated enterprise procurement.
- Individual Consumers:Mobile-first access patterns dominate, with app store distribution fees capturing 15-30% of transaction value. Churn management consumes platform marketing resources disproportionately.
- Businesses:Volume licensing and SSO integration requirements extend sales cycles but reduce per-seat support costs. Procurement in the United States emphasizes SOC 2 and ISO 27001 compliance documentation.
- Educational Institutions:Site-wide access agreements for e-books and video courseware bundle assessment tools. Budget cycles tied to academic calendars create predictable seasonal demand.
- Content Creators:Direct-to-fan monetization tools and automated royalty splits sustain platform loyalty. Independent musicians and podcasters in North America and Western Europe prioritize ownership retention over upfront advances.
Individual Consumers generate the highest transaction volume. Content Creators gain share fastest as distribution platforms compete for creator loyalty.
Platform:
Supply concentration in mobile app stores constrains margin autonomy against open web alternatives.
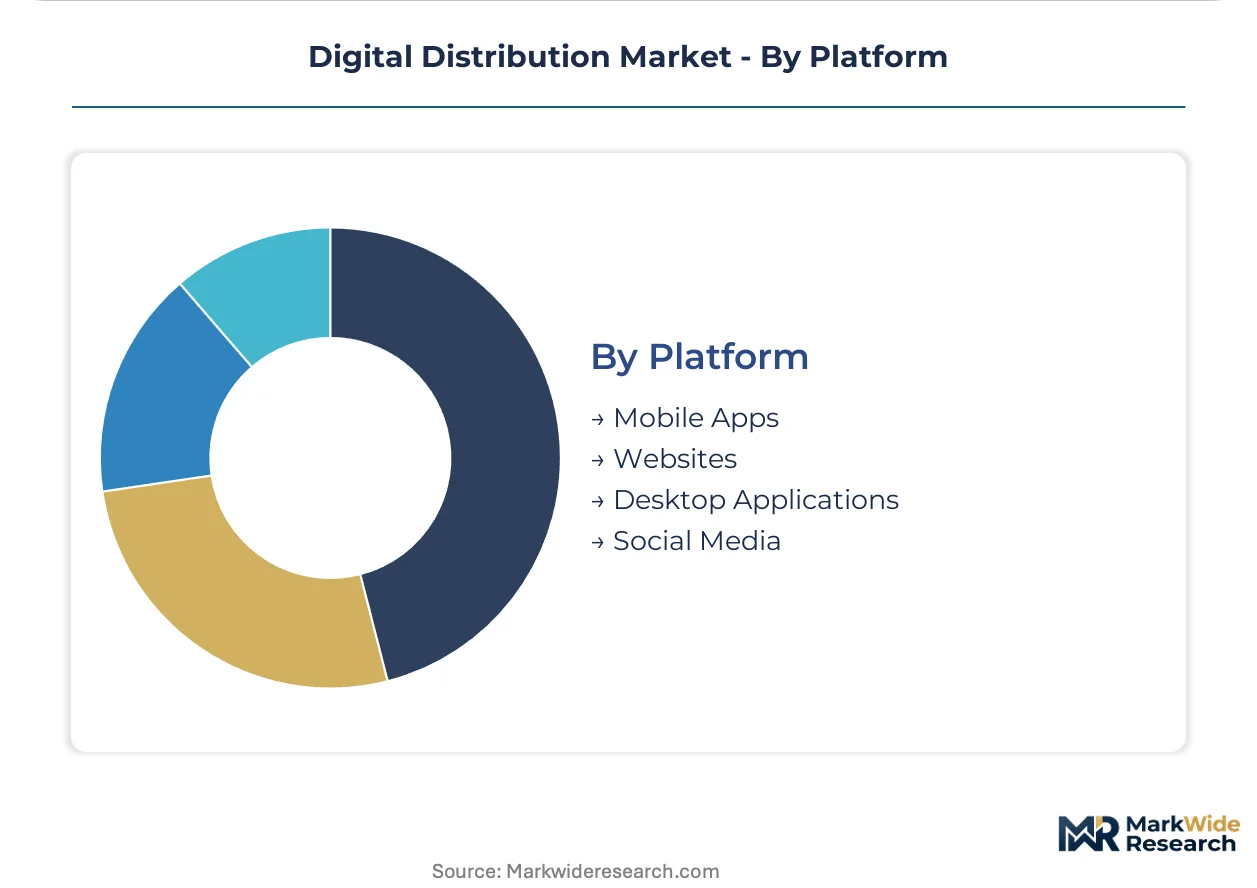
- Mobile Apps:iOS and Android duopoly enforces 15-30% revenue shares with strict content moderation obligations under the EU Digital Services Act. Discovery algorithm dependence raises customer acquisition costs.
- Websites:Direct distribution bypasses platform fees but requires proprietary payment processing and fraud prevention infrastructure. GDPR-compliant consent mechanisms create competitive moats for privacy-forward architectures.
- Desktop Applications:Enterprise software and creative tools retain native performance requirements. Auto-update pipelines and silent installation permissions reduce IT support burden.
- Social Media:Embedded video and music players leverage existing engagement graphs. Algorithmic recommendation transparency mandates under the EU AI Act reshape content surfacing strategies.
Mobile Apps anchor the majority of consumer transactions. Websites expand most quickly as creators seek fee reduction and data ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The digital distribution industry traces its commercial origins to the United States, where streaming infrastructure and creator-economy tooling first achieved scale during the 2010s platform consolidation wave.
United States
Creator-economy infrastructure and streaming penetration sustain the deepest demand concentration. The Digital Millennium Copyright Act shapes platform liability frameworks. Los Angeles and Nashville anchor music distribution clusters where independent artists negotiate direct-to-fan monetization terms.
Germany
Hi-res audio adoption and enterprise SaaS procurement drive premium segment growth. The EU Digital Services Act imposes systemic risk audit obligations on large platforms. Berlin's startup ecosystem houses multiple distributor headquarters serving Central European markets.
United Kingdom
Podcast creator density and independent label culture sustain platform competition. GDPR consent mechanism enforcement creates compliance differentiation among distributors. London's Soho district concentrates rights management and royalty accounting specialist firms.
Japan
Physical-digital hybrid catalog preservation and high-fidelity audio niches retain commercial relevance. METI guidelines on platform transparency influence distributor disclosure practices. Tokyo's Shibuya and Shinjuku districts host legacy artist estate management operations.
South Korea
K-pop global export infrastructure and fan-platform engagement tools accelerate adoption. The country's personal information protection commission enforces data localization for streaming services. Seoul's Gangnam district anchors entertainment company headquarters negotiating direct distribution deals.
Digital Distribution Market Vendor Landscape
The competitive structure tilts toward creator-facing service platforms with automated royalty infrastructure. Market positions fragment across dozens of regional and global operators rather than consolidating around a handful of dominant players. Three archetypes define the field: royalty-automation specialists, brand-partnership intermediaries, and physical-digital hybrid catalog managers. M&A activity concentrates on data analytics capabilities and regional artist network acquisitions.
Within the royalty-automation tier, DistroKid and TuneCore exemplify platforms competing on payment velocity and split-management tools. CD Baby occupies a position representing legacy artists navigating rights complexity. UnitedMasters anchors the brand-partnership vector, connecting creators directly to sponsorship pipelines. These three entities collectively illustrate how distributor differentiation now centers on ownership retention and direct audience relationship tools rather than exclusive catalog control.
| Leading Market Players |
|---|
| LANDR |
| Ditto Music |
| DistroKid |
| Songtradr |
| Amuse |
| TuneCore |
| UnitedMasters |
| ONErpm |
| CD Baby |
| Others |
Supply Flow & Price Mechanics
CDN bandwidth pricing indices cascade through digital distribution supply chains, compressing margins for streaming-heavy platforms while rewarding those with captive server infrastructure and direct peering agreements.
Pricing Analysis
Subscription-tiered pricing with creator-facing freemium entry points dominates revenue architecture. Price differentiation hinges on royalty transparency tooling and data portability guarantees, with premium tiers commanding multiples for direct brand partnership pipelines. Cost compression in the independent musician segment is intensifying because DistroKid and TuneCore automate royalty splits at scale. Individual creators exhibit highest price sensitivity, while enterprise SaaS distributors in regulated industries show lowest elasticity due to compliance bundling.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler cloud infrastructure concentrated in the United States, Ireland, and Singapore. Raw material dependencies center on submarine fiber cable capacity, GPU clusters for transcoding, and lithium for edge server backup power. Tariff exposure on Chinese-manufactured networking hardware threatens CDN expansion timelines. Distribution runs through platform-agnostic APIs for enterprise segments, while consumer-facing delivery remains tethered to iOS and Android app store duopolies with fixed revenue shares.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where creator procurement now prioritizes ownership retention and data portability over upfront advances, elevating platforms with transparent royalty infrastructure.
For Market Incumbents: Acquire machine learning training datasets for automated rights-clearance workflows. Defend against blockchain-based royalty tracking startups by embedding smart contract compatibility into existing payment rails. Deepen backward integration into CDN edge node ownership to reduce bandwidth cost volatility. For New Entrants and Emerging Players: Enter via white-label compliance-as-a-service for EU AI Act algorithmic transparency mandates. Target mid-tier podcast networks in Germany and the United Kingdom lacking in-house data governance. Lead with audit-documentation tools that monetize regulatory overhead rather than competing on distribution fees. For Investors and Strategic Acquirers: Asymmetric upside sits with royalty-automation specialists possessing multi-territorial rights accounting infrastructure. Long-term viability favors platforms enabling direct creator-audience relationships over those dependent on exclusive catalog control. Watch for Copyright Royalty Board mechanical rate proceedings as inflection indicators for streaming margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Contract Royalty Infrastructure | Decentralized payment verification reduces settlement latency from quarters to days for independent musicians. |
| EU DSA Compliance Services | Algorithmic transparency registers create recurring advisory revenue from large platform audit mandates. |
| Direct Brand Partnership Pipelines | Bypassing label intermediation captures sponsorship automation margins in United States creator economy. |
| Hi-Res Audio Codec Licensing | Lossless tier subscriptions command premium positioning in Japan and German audiophile segments. |
| Educational Institution Site Licensing | Academic calendar procurement cycles generate predictable seasonal demand for e-book and courseware bundles. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged digital distribution platform executives, independent musician rights managers, podcast network operators, and CDN infrastructure procurement leads. Secondary validation drew from SEC filings of listed streaming services, EU Digital Services Act implementation guidance, Copyright Royalty Board proceeding transcripts, and app store revenue disclosure patterns. Bottom-up subscriber and transaction modeling triangulated against top-down market sizing from content delivery network capex disclosures.
Historical reference periods anchored volume and value trajectories across the projection horizon. The analytical framework modeled segmentation across content format, delivery model, customer type, and platform access mode. CAGRs derived from elasticity-adjusted adoption curves incorporating mechanical royalty rate volatility and platform licensing renegotiation cycles. Forecast inputs included CDN latency threshold investments and creator-economy tooling penetration rates by geography.
Inputs from platform financial disclosures and regulatory filing databases were available through the study window; gaps in private distributor transaction-level data introduce uncertainty bands around independent creator segment sizing. Forecasts reflect documented assumptions regarding streaming service concentration and EU compliance timeline adherence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Global Virtual Goods Market
Digital Media
Global Streaming Media Device Market
Digital Media
Online Art Market
Digital Media
3D Anaglyph Glasses Market
Digital Media
Japan Webtoons Market
Digital Media
Indonesia Digital Media Market
Digital Media
Professional Dubbing Services Market
Digital Media
Digital Media Switchers Market
Digital Media
Mobile Entertainment Market
Digital Media
Photography Services Market
Digital Media
Multichannel Network Market
Digital Media
Anime Merchandising Market
Digital Media
North America Online Gambling Market
Digital Media
Online Movie Market
Digital Media
Anime Derivatives Market
Digital Media
In Flight Entertainment Market