
 Diaper Rash Cream Market | 2026-2036
Diaper Rash Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Diaper Rash Cream Market Analysis
Retail pharmacy shelf space allocation is fragmenting between legacy zinc oxide formulations and botanical-based alternatives. Johnson & Johnson Services, Inc. leverages its hospital channel relationships to sustain institutional procurement contracts. Himalaya Wellness Company anchors its position through herbal formulation expertise developed in Indian botanical supply chains. Sebapharma GmbH competes on clinical positioning with pH-balanced emulsion technology.
Diaper rash cream denotes a topical dermatological preparation containing zinc oxide, petrolatum, or botanical extracts applied to infant perianal skin to prevent or treat irritant contact dermatitis from moisture, friction, and enzymatic breakdown. Manufacturing employs oil-in-water emulsification with particle size control below 50 microns to optimize barrier film formation and active ingredient dispersion. Barrier creams lead volume due to universal pediatrician recommendation, while herbal formulations represent the fastest-expanding margin pool as clean-label positioning commands premium shelf placement. Online retail channels are capturing share from pharmacies as subscription models reduce replenishment friction for recurring purchases.
The FDA regulates diaper rash creams as over-the-counter skin protectant monograph products requiring minimum zinc oxide concentrations for therapeutic claims. The EU Cosmetic Regulation through ECHA mandates safety assessments for preservative systems and fragrance allergens in infant topical products. REACH compliance for petrolatum sourcing adds supply chain documentation burdens for European manufacturers. Stakeholders must monitor evolving state-level restrictions on petrolatum derivatives and shifting pediatrician endorsement patterns between synthetic and plant-derived active ingredients.
Market Dynamics
Retail pharmacy shelf space allocation is fragmenting between legacy zinc oxide formulations and botanical-based alternatives, forcing manufacturers to recalibrate R&D budgets toward clean-label positioning while maintaining clinical efficacy standards demanded by pediatric dermatology networks.
Growth Catalysts
- Pediatric dermatology procurement expansion:Neonatal care units in the United States and Germany are standardizing barrier cream protocols for preterm infant skin protection, creating institutional volume anchors.
- REACH compliance documentation:European manufacturers investing in petrolatum supply chain traceability are capturing premium positioning as regulatory scrutiny intensifies under ECHA mandates.
- Subscription-based replenishment models:Direct-to-consumer platforms are virtualizing pharmacy foot traffic by locking parents into automated diaper rash cream delivery cycles.
Market Restraints
- API concentration volatility:Zinc oxide pricing fluctuates with Chinese smelter output, compressing margin predictability for mid-tier formulators dependent on spot market sourcing.
- Fragrance allergen restrictions:EU Cosmetic Regulation amendments through ECHA are forcing reformulation of legacy SKUs, straining inventory management across European distribution networks.
- Petrolatum substitution pressure:Clean-label positioning in German and Indian markets is displacing petroleum-derived bases before cost-parity plant alternatives achieve scale.
Strategic Opportunities
- Rural Indian pharmacy penetration:Ayurvedic formulation expertise from established domestic supply chains can unlock tier-2 and tier-3 city demand currently served by unbranded alternatives.
- FDA OTC monograph modernization:Anticipated updates to skin protectant concentration standards will reward early movers with compliant zinc oxide particle engineering capabilities.
- Telehealth pediatric consultation integration:Virtual dermatology platforms in the United States are creating prescription-adjacent recommendation channels for clinical-grade barrier creams.
Industry Challenges
- Particle engineering talent scarcity:Oil-in-water emulsification expertise with sub-50 micron control is concentrated among legacy cosmetic chemists approaching retirement.
- Cross-regulatory dossier complexity:Simultaneous FDA monograph compliance and EU Cosmetic Regulation safety assessments strain regulatory affairs bandwidth for mid-cap manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diaper Rash Cream Market |
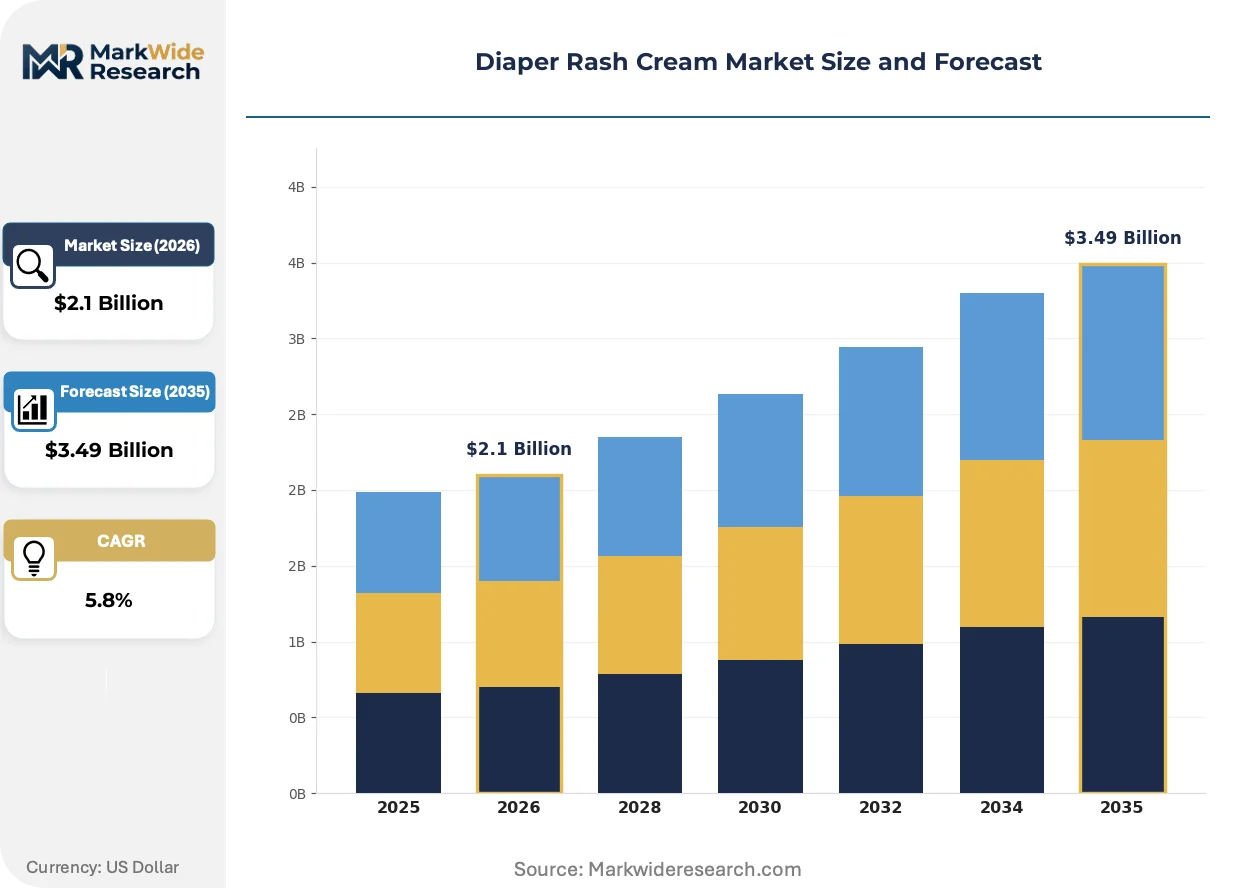
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barrier Creams, Zinc Oxide Creams, Aloe Vera Creams, Herbal Formulations End User: Parents, Caregivers, Hospitals, Daycare Centers Packaging Type: Tubes, Jars, Pump Bottles, Sachets Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores |
| Companies Covered | Himalaya Wellness Company, The Honest Company, Inc., Johnson & Johnson Services, Inc., Tubby Todd Bath Co., Sebapharma GmbH, Bayer AG, Unilever PLC, Earth Mama Angel Baby LLC, Beiersdorf AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diaper Rash Cream Market Emerging Trajectories
Digital shelf analytics and AI-driven formulation screening are compressing product development cycles while regulatory transparency mandates force disclosure of previously proprietary excipient sourcing.
Encapsulated zinc oxide delivery systems with pH-responsive release mechanisms are virtualizing traditional barrier film technology by enabling targeted active deposition only upon enzymatic irritation detection. Pediatric dermatology clinics in Germany are piloting these smart formulations for severe diaper dermatitis cases. The technology is compressing differentiation timelines as patent-protected particle architectures replace commodity zinc oxide in premium positioning.
EU Cosmetic Regulation amendments through ECHA are mandating expanded fragrance allergen labeling and preservative system safety dossiers for infant topical products. European manufacturers face 18-24 month reformulation windows to maintain market access. Clean-label specialists with pre-validated botanical preservative systems are capturing shelf space from legacy brands dependent on conventional paraben alternatives.
Parents in the United States are migrating from episodic pharmacy purchases to subscription-based replenishment tied to diaper consumption tracking apps. Direct-to-consumer platforms are disintermediating retail pharmacy margins by offering bundled dermatology consultations with product auto-shipment. This behavioral shift concentrates lifetime value capture among digitally native brands while eroding legacy shelf presence in mass retail channels.
Diaper Rash Cream Market Segmentation
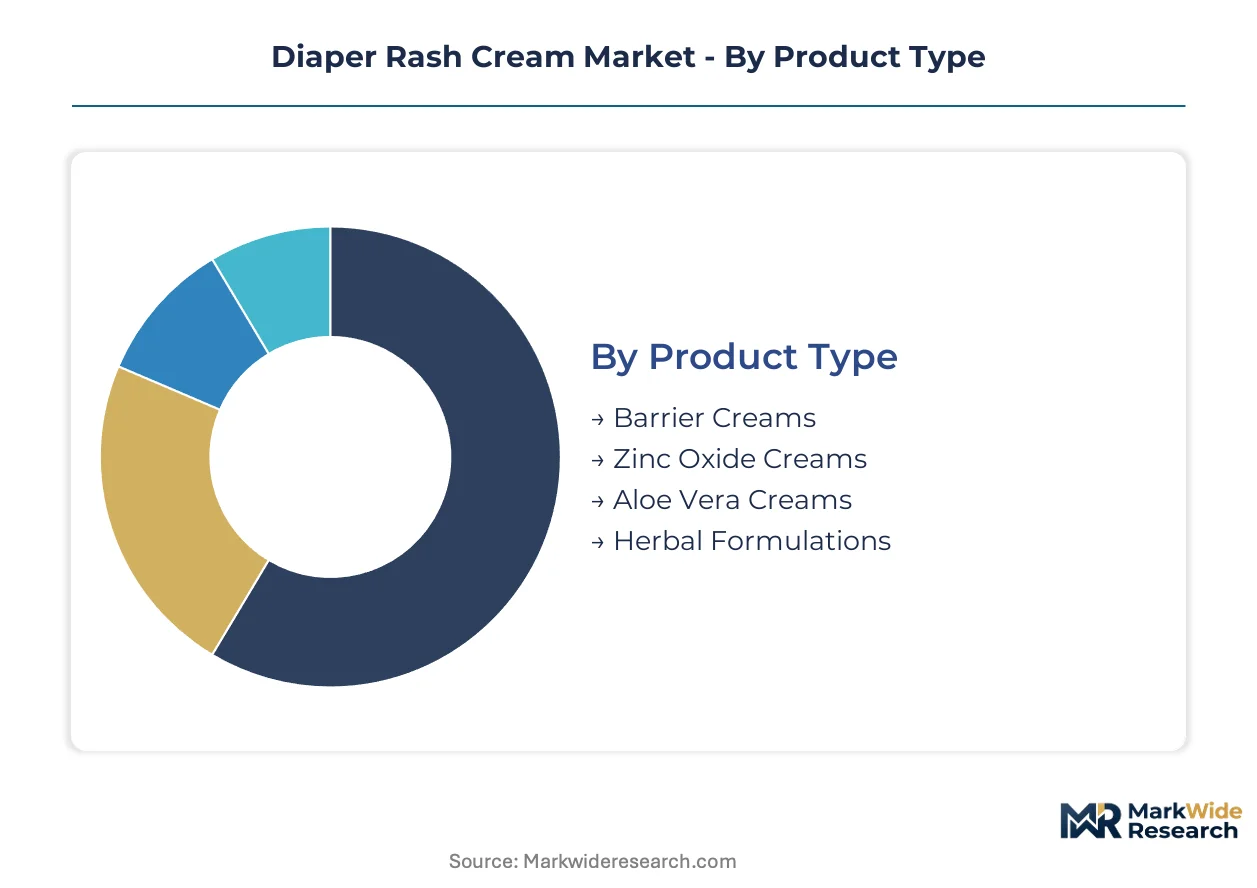
Segmentation in the diaper rash cream market reveals distinct procurement rhythms across product categories and channel structures. Purchase cycles vary from emergency pharmacy visits to automated subscription replenishment, creating divergent margin profiles and inventory velocity requirements for manufacturers.
Product Type:
Barrier creams turn over fastest through institutional channels with standardized reorder cycles, while herbal formulations move slowest due to premium positioning and selective consumer adoption.
- Barrier Creams:Petrolatum or zinc oxide-based films forming occlusive protection against moisture and enzymatic irritation. Neonatal intensive care units in the United States and Germany mandate these for preterm infant protocols, driving predictable bulk procurement through hospital purchasing cooperatives.
- Zinc Oxide Creams:Concentrated mineral active formulations meeting FDA OTC monograph standards for therapeutic skin protectant claims. Parents in India favor these for severe rash episodes where clinical efficacy overrides cost sensitivity, particularly in urban pharmacy channels.
- Aloe Vera Creams:Botanical soothing agents targeting mild irritation prevention with lighter texture profiles.
- Herbal Formulations:Ayurvedic and plant-derived compositions leveraging clean-label positioning in direct-to-consumer and specialty retail.
Barrier creams anchor the volume base while herbal formulations gain share at the steepest rate.
End User:
Cost tier stratification separates episodic individual purchasers from contracted institutional buyers with negotiated formulary access.
- Parents:Primary decision-makers responding to pediatrician recommendations and peer referral networks, with purchasing concentrated through retail pharmacy and subscription platforms.
- Caregivers:Professional and familial non-parental providers seeking mid-tier efficacy at accessible price points through supermarket and mass retail channels.
- Hospitals:Institutional procurement governed by clinical protocol standardization and group purchasing organization contracts, with zinc oxide concentration specifications tightly enforced.
- Daycare Centers:Licensed facilities requiring bulk supply resilience and documentation compliance for state health inspections, favoring pump dispensers and large-format packaging.
Parents generate the highest transaction frequency while hospitals deliver the most stable annual contract value.
Packaging Type:
Volume economics concentrate in portable formats for travel and diaper bag inclusion, while stationary dispensers dominate fixed-site institutional installations.
- Tubes:Collapsible aluminum or laminate containers enabling precise dose control and hygienic single-user application. German and Indian manufacturers favor this format for pharmacy shelf presence and export logistics efficiency.
- Jars:Wide-mouth rigid containers supporting spatula or finger application, common in premium positioning and gift-set bundling.
- Pump Bottles:Airless dispensing systems minimizing contamination risk in multi-user daycare and clinical environments.
- Sachets:Single-use foil pouches distributed as samples, travel amenities, and emergency backup units in hospital discharge kits.
Tubes maintain the broadest geographic penetration while pump bottles are climbing the fastest in institutional contract specifications.
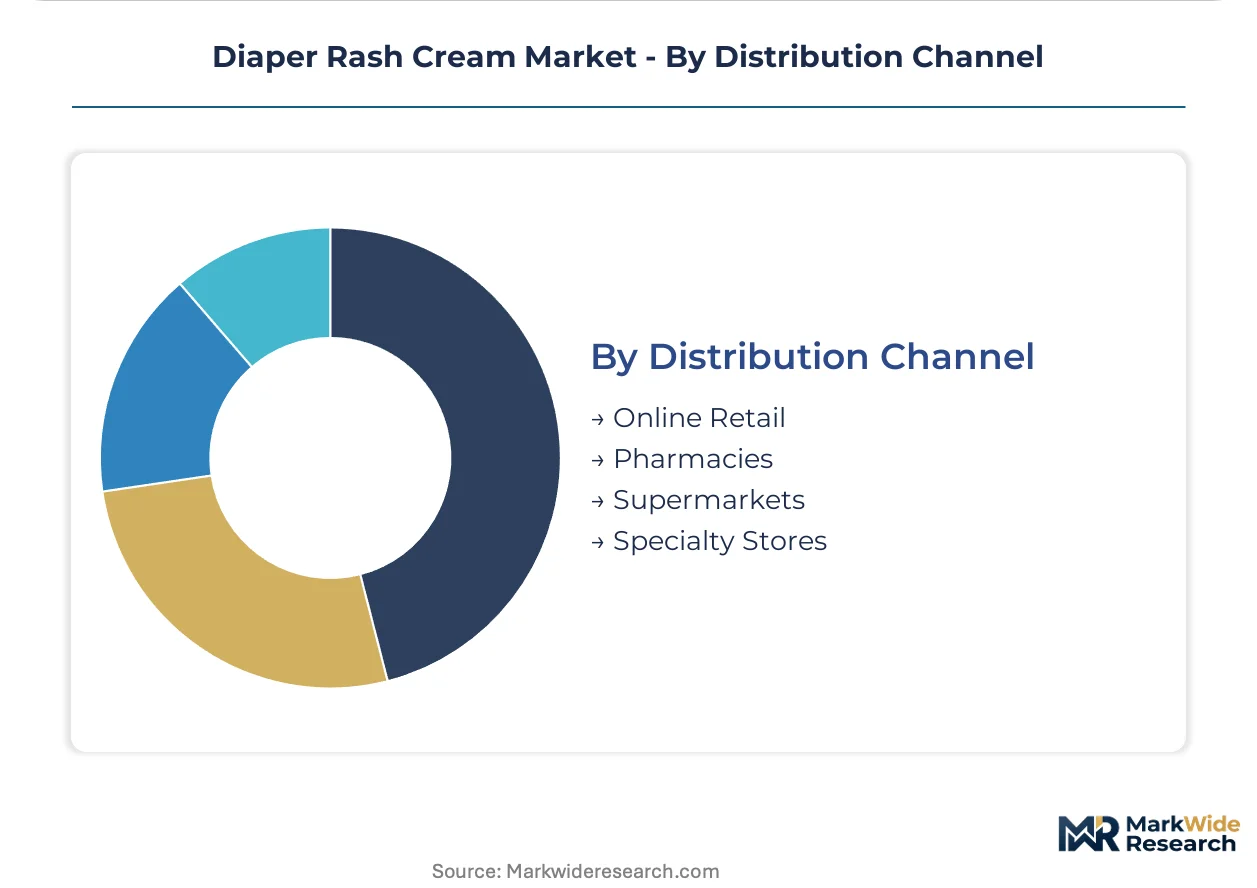
Distribution Channel:
Customer type fragmentation separates urgent need fulfillment from planned replenishment behaviors with divergent loyalty mechanics.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators capturing subscription-based auto-replenishment with diaper consumption tracking integration. United States parents demonstrate the strongest migration toward this channel for recurring purchases.
- Pharmacies:Brick-and-mortar drugstore chains and independent dispensaries retaining emergency purchase dominance and pediatrician referral capture.
- Supermarkets:Mass merchandisers leveraging diaper category adjacency and promotional bundling for routine basket-building.
- Specialty Stores:Natural product retailers and boutique baby shops curating clean-label and premium botanical assortments with educated staff consultation.
Pharmacies retain the highest transaction volume while online retail is expanding most quickly in subscription attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Parents in the United States favor subscription-based replenishment tied to diaper tracking apps, while Indian buyers prioritize Ayurvedic formulations through traditional pharmacy channels. German procurement concentrates in hospital purchasing cooperatives with strict zinc oxide concentration protocols.
United States
Neonatal intensive care units in Texas and California drive institutional volume through group purchasing organization contracts. FDA OTC monograph compliance for skin protectant claims shapes formulation standards nationwide. Direct-to-consumer platforms in the Pacific Northwest are virtualizing pharmacy foot traffic through automated replenishment cycles.
Germany
Pediatric dermatology clinics in Bavaria and North Rhine-Westphalia standardize barrier cream protocols for preterm infant skin protection. REACH compliance documentation through ECHA mandates petrolatum supply chain traceability for European market access. Manufacturing clusters around Hamburg specialize in pH-balanced emulsion technology for clinical-grade positioning.
India
Urban pharmacy channels in Maharashtra and Karnataka favor zinc oxide creams for severe rash episodes where efficacy overrides cost sensitivity. FSSAI labeling requirements and CDSCO cosmetic safety assessments govern botanical ingredient disclosure. Ayurvedic formulation expertise in Kerala and Tamil Nadu supply chains anchors herbal product expansion into tier-2 and tier-3 cities.
United Kingdom
Specialty baby retailers in London and the Southeast curate clean-label assortments with educated staff consultation. UK cosmetic regulations through the Office for Product Safety and Standards enforce fragrance allergen labeling stricter than baseline EU requirements. Manchester-based distribution hubs manage cross-border logistics for Irish and Nordic export markets.
Japan
Meticulous ingredient transparency expectations in the Kanto region drive demand for preservative-free and fragrance-minimal formulations. PMDA and Ministry of Health, Labour and Welfare guidelines for quasi-drug classification create regulatory barriers for therapeutic claims. Osaka-based cosmetic laboratories pioneer sub-50 micron particle engineering for premium barrier film performance.
Diaper Rash Cream Market Vendor Landscape
Capability concentration sits with mid-tier botanical specialists; scale advantage sits with diversified consumer health conglomerates. The vendor base stratifies across three tiers: legacy pharmaceutical incumbents with hospital channel relationships, clean-label specialists with validated herbal supply chains, and digital-native direct-to-consumer brands with subscription infrastructure. Dominant competitive moves include portfolio diversification into adjacent baby care categories and strategic partnerships with telehealth pediatric consultation platforms.
Within the herbal formulation archetype, Himalaya Wellness Company and Earth Mama Angel Baby LLC exemplify botanical-first positioning developed through region-specific supply chain integration. Johnson & Johnson Services, Inc. anchors the institutional procurement tier through hospital channel density and pediatrician endorsement networks. Sebapharma GmbH occupies a clinical-specialist position emphasizing pH-balanced emulsion technology for dermatology clinic formulary inclusion.
| Leading Market Players |
|---|
| Himalaya Wellness Company |
| The Honest Company, Inc. |
| Johnson & Johnson Services, Inc. |
| Tubby Todd Bath Co. |
| Sebapharma GmbH |
| Bayer AG |
| Unilever PLC |
| Earth Mama Angel Baby LLC |
| Beiersdorf AG |
| Others |
Supply Flow & Price Mechanics
Zinc oxide smelter concentration in Chinese industrial zones generates dual exposure for formulators, compressing margin predictability across premium and economy tiers while forcing supply chain restructuring toward multi-source mineral procurement and regional emulsification capacity.
Pricing Analysis
Contract-based long-term offtake agreements with Indian botanical suppliers anchor pricing stability for herbal formulations, while spot market zinc oxide sourcing in China creates volatility for barrier cream manufacturers. Three-tier pricing structure across premium, standard, and economy levels reflects zinc oxide concentration grade and FDA monograph certification status. Cost compression in the standard tier is intensifying because mid-tier formulators lack backward integration into mineral supply. Parents purchasing through subscription platforms demonstrate the lowest price sensitivity, while daycare centers procuring bulk formats exhibit the highest.
Supply Chain Analysis
Extended payment terms from German retail pharmacy chains are squeezing working capital for mid-tier manufacturers, accelerating adoption of supply-chain finance facilities. Active ingredient sourcing draws from China for zinc oxide, India for Ayurvedic botanicals, and Germany for pH-balanced emulsion bases. Petrolatum feedstock dependency on European refinery output creates single-source vulnerability under REACH documentation mandates. Distribution runs through hospital purchasing cooperatives for institutional volume, direct-to-consumer platforms for subscription replenishment, and traditional pharmacy networks for emergency purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Diaper rash cream demand sits in early-cycle expansion as subscription-based replenishment models penetrate parent purchasing behavior and telehealth pediatric consultations normalize clinical-grade product recommendations.
For Market Incumbents: Harden hospital channel relationships through neonatal care unit protocol standardization and preemptive zinc oxide particle engineering investments ahead of FDA OTC monograph updates. Deepen backward integration into Indian botanical supply chains to defend margin position against clean-label specialists with validated Ayurvedic sourcing. Capture formulary lock-in with pediatric dermatology networks before pH-responsive encapsulated delivery systems commoditize. For New Entrants and Emerging Players: Rural Indian tier-2 and tier-3 pharmacy networks offer the most penetrable white-space opportunity, currently served by unbranded alternatives with minimal clinical positioning. Ayurvedic formulation expertise from Kerala and Tamil Nadu supply chains enables differentiated clean-label entry with FSSAI compliance as barrier. Direct-to-consumer launch with diaper consumption tracking app integration captures subscription lifetime value ahead of legacy brand digital migration. For Investors and Strategic Acquirers: Botanical-first specialists with validated preservative systems and pre-submitted EU Cosmetic Regulation safety dossiers represent the most attractive acquisition target archetype. Long-term viability hinges on regulatory compliance bandwidth rather than manufacturing scale alone. Watch FDA OTC monograph modernization timing as inflection indicator for zinc oxide particle engineering capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulated Zinc Oxide Development | pH-responsive release mechanisms enable premium positioning in German dermatology clinics. |
| Subscription Platform Integration | Diaper tracking app partnerships lock United States parents into automated replenishment cycles. |
| Botanical Preservative Validation | Pre-submitted ECHA safety dossiers accelerate EU market access against paraben-dependent legacy brands. |
| Rural Pharmacy Network Penetration | Tier-2 and tier-3 Indian cities shift from unbranded alternatives to clinically positioned formulations. |
| Telehealth Partnership Structuring | Virtual pediatric consultation platforms create prescription-adjacent recommendation channels for barrier creams. |
Methodological Framework
Desk research of FDA OTC monograph filings, EU Cosmetic Regulation safety assessments, and Indian FSSAI labeling requirements preceded structured interviews with pediatric dermatologists, neonatal care unit procurement managers, retail pharmacy category buyers, and direct-to-consumer brand supply chain directors. Secondary validation drew from hospital purchasing cooperative contract databases, ECHA REACH registration dossiers, and customs trade data for zinc oxide and petrolatum feedstock flows. Bottom-up volume modeling across product types, end users, and distribution channels triangulated against top-down market sizing from regulatory filing aggregates.
Assumptions held fixed include FDA and ECHA regulatory frameworks in current form, zinc oxide concentration standards for therapeutic claims, and prevailing birth rate trajectories in the United States, Germany, and India. Variables tested across the projection horizon encompassed clean-label substitution rates, subscription platform penetration curves, and REACH compliance cost pass-through elasticity. Segmentation dimensions modeled covered barrier cream versus herbal formulation product types, parent versus hospital versus daycare center end users, and online retail versus pharmacy versus supermarket distribution channels. CAGRs derived from regression analysis of historical procurement volume against pediatric population cohorts and private-label penetration indices.
Macroeconomic conditions sit as an overlay; deviation in birth rates, zinc oxide commodity pricing, or cross-border tariff regimes would shift the trajectory. Forecasts reflect documented assumptions around regulatory stability and supply chain configuration. Technological disruption in encapsulated delivery systems, regulatory acceleration in fragrance allergen restrictions, or supply concentration changes in Chinese smelter output would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Global Cosmetic Shea Butter Market
Consumer Goods
Speakerphones Market
Consumer Goods
Liquid Soap Market
Consumer Goods
South Korea Baby Care Products Market
Consumer Goods
Press-To-Close Zippers Market
Consumer Goods
Hair Serums Ingredient Market
Consumer Goods
Cooler Connected to the Mains Market
Consumer Goods
Asia-Pacific Beauty and Personal Care Products Market
Consumer Goods
Luxury Eyewear Market
Consumer Goods
Shaving Pen Market
Consumer Goods
Japan Dog Food Market
Consumer Goods
Asia-Pacific Microwave Oven Market
Consumer Goods
Asia Pacific Pet Diet Market
Consumer Goods
Orbital Action Jigsaw Market
Consumer Goods
Sports Footwear Market
Consumer Goods
Baby Personal Care Market