
 Dehydrated Meat Products Market | 2026-2036
Dehydrated Meat Products Market Size, Share, and Industry Trends Forecast 2026-2036
Dehydrated Meat Products Market Analysis
A capital-intensity divergence between large-scale processors and artisanal specialists is rotating competitive dynamics across the dehydrated meat sector. JBS SA leverages its integrated cattle supply chain to dominate raw material access for dried beef production. Country Archer Provisions differentiates through small-batch positioning and direct-to-consumer channel control. Hormel Foods Corporation sustains broad retail distribution for jerky formats across conventional grocery.
Dehydrated meat products are protein-rich shelf-stable foods produced through controlled moisture reduction, typically achieving water activity levels below 0.85 to inhibit microbial growth without refrigeration. The process preserves myofibrillar structure while concentrating flavor compounds, serving commercial food manufacturers and retail snack channels requiring extended storage stability. Jerky occupies the largest volume position within product type segmentation due to established American snacking habits and convenience store penetration. Powder formats within the form dimension attract growing interest from snack makers reformulating protein-fortified packaged goods. Specialty shops represent the highest-margin distribution channel, though supermarkets still anchor total volume throughput for mainstream dried pork and biltong varieties.
USDA inspection protocols under the Federal Meat Inspection Act govern interstate commerce of dried beef and pork, while FDA oversight extends to jerky products incorporating non-meat additives. State-level cottage food laws create fragmented compliance terrain for small producers selling direct within single jurisdictions. Stakeholders must monitor evolving sodium reduction guidance from health regulators, as reformulation pressures threaten traditional curing processes that define category taste profiles.
Market Dynamics
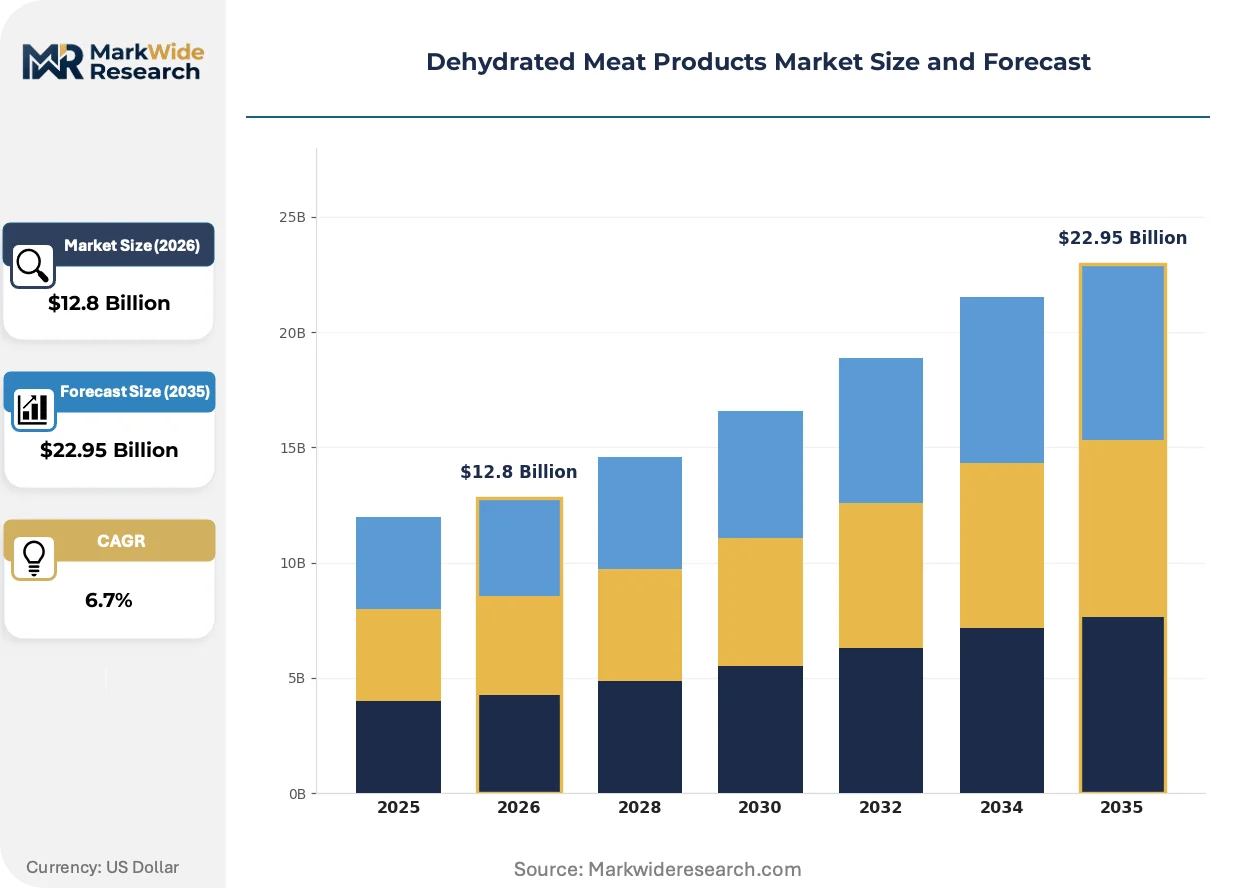
Capital intensity divergence between integrated meatpackers and artisanal specialists is fragmenting competitive dynamics across the dehydrated meat sector. JBS SA's cattle supply chain integration contrasts sharply with Country Archer Provisions' direct-to-consumer positioning.
Growth Catalysts
- Military procurement modernization:Defense agencies in the United States are expanding shelf-stable protein contracts for field rations and emergency stockpiles.
- FDA sodium reduction guidance:Reformulation pressures are accelerating clean-label curing process innovation among mid-tier processors.
- Snackification of meals:Convenience store penetration of jerky formats in the United States is converting traditional meal occasions into portable protein consumption.
Market Restraints
- USDA inspection mandates:Federal Meat Inspection Act compliance costs create structural barriers for new entrants seeking interstate distribution.
- Beef input volatility:Cattle cycle fluctuations concentrate margin pressure on processors without captive supply arrangements.
- Plant-based protein substitution:Mycoprotein and textured vegetable alternatives capture trial among flexitarian consumers in urban coastal markets.
Strategic Opportunities
- Powder format snack integration:Protein-fortified packaged goods manufacturers in the United States are sourcing dried meat powders for reformulation pipelines.
- Specialty shop channel expansion:Premium biltong positioning through curated retail formats captures margin expansion unavailable in conventional grocery.
- State cottage food law arbitrage:Direct-to-consumer producers leverage fragmented intrastate compliance to test formulations before USDA scale-up.
Industry Challenges
- Traditional curing expertise scarcity:Sodium reduction mandates threaten flavor profile continuity as veteran processors retire.
- Legacy equipment retrofit costs:Continuous dehydration systems require capital outlays that strain artisanal balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dehydrated Meat Products Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dried Beef, Dried Pork, Jerky, Biltong Form: Chunks, Strips, Powders, Slices Distribution Channel: Online Stores, Supermarkets, Convenience Stores, Specialty Shops End User: Retail Consumers, Foodservice Sector, Snack Makers, Outdoor Enthusiasts |
| Companies Covered | JBS SA, Pilgrim’s Pride Corporation, Cargill Incorporated, Jack Link’s Protein Snacks, Kraft Heinz Company, Hormel Foods Corporation, BRF SA, Country Archer Provisions, Tyson Foods Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dehydrated Meat Products Market Emerging Trajectories
Processing technology and distribution architecture are actively restructuring how dehydrated meat products reach end consumers. Three interconnected developments are compressing legacy operating models while opening white space for specialized positioning.
Radio-frequency drying is bifurcating the equipment landscape between batch and continuous processing architectures. Mid-scale processors in the United States are piloting RF systems to reduce thermal degradation of myofibrillar proteins. This technology is bifurcating quality tiers by enabling precise moisture control that legacy convection ovens cannot replicate.
USDA's evolving enforcement posture on imported beef traceability is tightening documentation requirements for dried protein sourcing. Interstate commerce compliance costs are rising for processors reliant on non-domestic cattle inputs. Small-batch producers in Texas and California are responding by marketing verified domestic supply chains as premium differentiation.
Subscription-based replenishment is displacing impulse purchasing in the direct-to-consumer channel. Specialty jerky curators are capturing recurring revenue through flavor-profile personalization algorithms. This behavioral shift concentrates most visibly in the United States, where urban professionals seek curated protein variety without retail friction.
Dehydrated Meat Products Market Segmentation
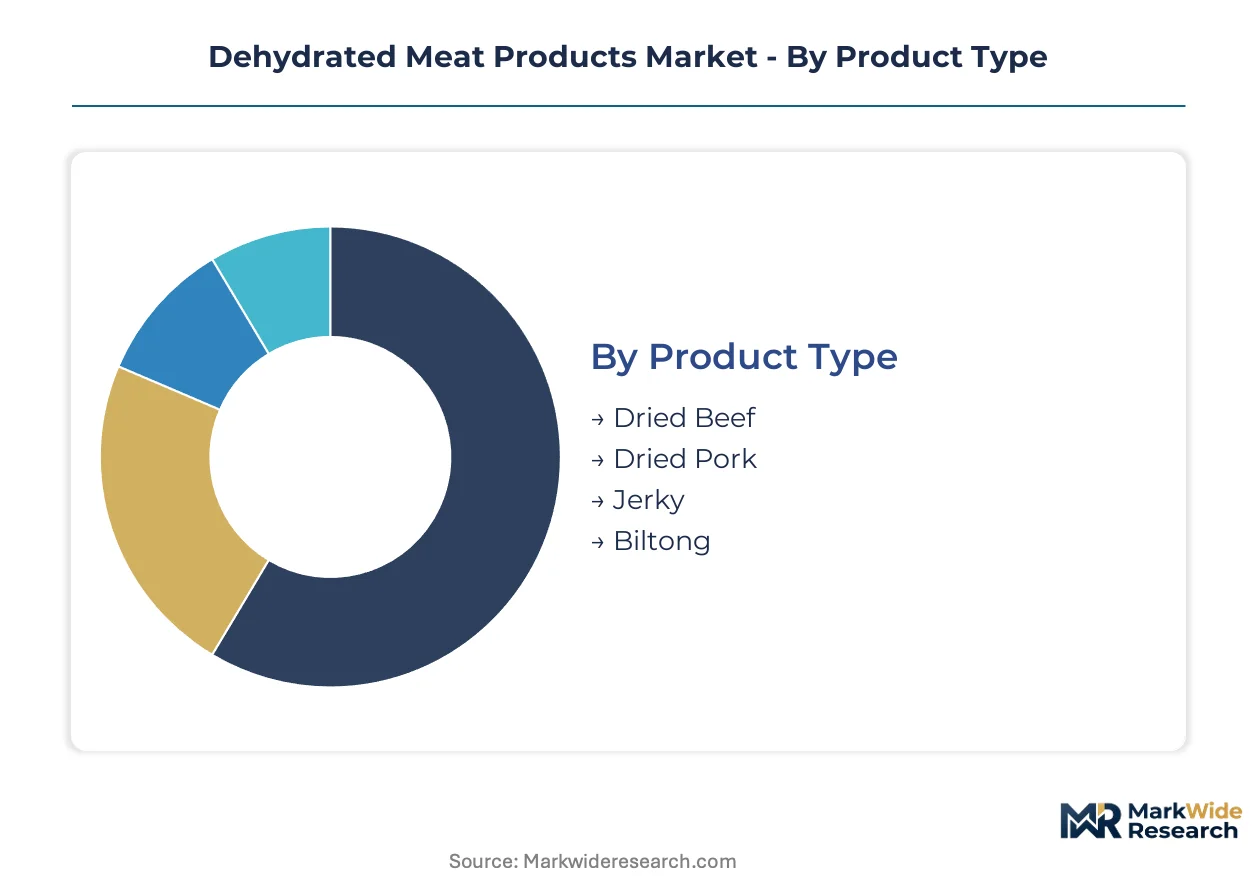
Dehydrated meat segmentation determines margin capture and regulatory exposure across distinct processing intensities and channel architectures. Product type and form selections directly dictate USDA inspection tier, shelf stability requirements, and substitution vulnerability from plant-based alternatives.
Product Type:
Jerky faces the most acute plant-protein substitution pressure due to its snack-format positioning and urban flexitarian trial rates, while biltong's artisanal curing heritage offers defensive differentiation.
- Jerky:Thin-sliced whole-muscle or restructured meat preserved through salt curing, smoking, and low-temperature dehydration to water activity below 0.85. Convenience store penetration in the United States drives volume, though sodium reduction guidance from FDA threatens traditional curing formulations.
- Dried Beef:Whole-muscle cuts dehydrated without the sugar-heavy marinades characteristic of jerky, yielding denser protein concentration per ounce. Military procurement contracts for shelf-stable field rations concentrate demand in United States defense logistics channels.
- Biltong:South African-origin air-dried beef cured with vinegar and coriander, bypassing thermal degradation entirely. Specialty shops in Texas and California command premium positioning through verified domestic sourcing claims.
- Dried Pork:Shoulder and belly cuts dehydrated for Asian culinary applications and American breakfast protein formats. State-level cottage food laws enable small-batch Texas producers to test formulations before USDA scale-up.
Jerky anchors the volume base while biltong gains share at the steepest rate.
Form:
Cost tier stratification separates commodity chunk formats from precision-engineered powders commanding reformulation premiums in packaged goods.
- Powders:Micronized dehydrated meat with particle size controlled for protein fortification integration. Snack makers in the United States source dried meat powders for clean-label reformulation pipelines replacing synthetic protein isolates.
- Strips:Uniform longitudinal cuts optimized for grab-and-go retail merchandising and controlled portioning. Convenience store channel expansion across the United States Midwest sustains volume throughput for mainstream positioning.
- Chunks:Irregular bite-sized pieces from trim and secondary cuts, minimizing waste in integrated processing operations. Foodservice sector procurement for salad toppers and bowl builds drives commercial demand.
- Slices:Thin planar cuts resembling traditional charcuterie presentation, enabling premium refrigerated and ambient shelf placement. Specialty shops leverage visual appetite appeal for curated gifting formats.
Strips dominate unit volume while powders expand most quickly through snack integration.
Distribution Channel:
Margin architecture varies dramatically: specialty shops capture 40-60 point gross margin premiums over conventional grocery, while online stores enable direct consumer data capture.
- Specialty Shops:Curated retail environments emphasizing provenance storytelling and flavor-profile experimentation. Premium biltong positioning through Texas and California specialty networks achieves margin expansion unavailable in mass retail.
- Supermarkets:Conventional grocery anchoring total volume throughput for dried pork and mainstream jerky varieties. JBS SA and Hormel Foods Corporation sustain broad retail distribution through slotting fee negotiations and promotional calendar integration.
- Convenience Stores:Impulse-oriented channel converting traditional meal occasions into portable protein consumption through single-serve packaging. United States interstate highway corridors and urban commuter nodes concentrate highest velocity.
- Online Stores:Direct-to-consumer infrastructure enabling subscription-based replenishment and flavor personalization algorithms. Country Archer Provisions leverages this channel for small-batch positioning outside conventional retail gatekeeping.
Supermarkets retain volume dominance while specialty shops claim the steepest margin expansion trajectory.
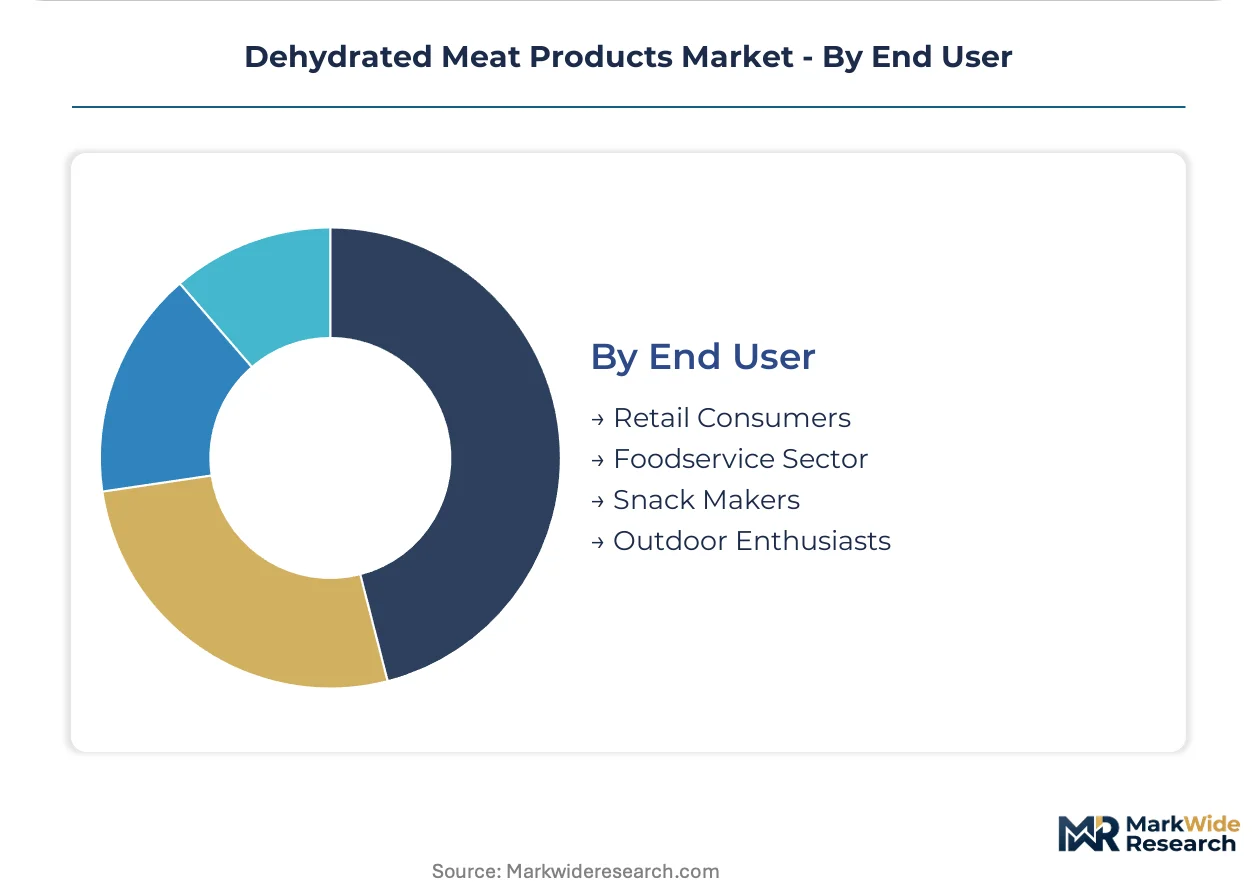
End User:
Application maturity separates established retail consumption from emerging foodservice integration and military specification requirements.
- Retail Consumers:Individual households purchasing for home pantry stocking and on-the-go protein needs. Mainstream American snacking habits sustain baseline demand across jerky and biltong formats.
- Snack Makers:Industrial purchasers integrating dehydrated meat inputs into composite packaged goods. Protein-fortified chip and cracker reformulation pipelines source dried meat powders for clean-label claims.
- Foodservice Sector:Commercial kitchens and prepared food manufacturers utilizing dehydrated meat as ingredient or topping. Salad chains and grain-bowl concepts in United States urban markets drive incremental chunk and strip demand.
- Outdoor Enthusiasts:Backpackers, hunters, and emergency preparedness consumers prioritizing weight-to-calorie ratio and shelf stability. Defense agency procurement modernization expands this segment through standardized field ration specifications.
Retail consumers anchor the volume base while snack makers gain share at the steepest rate through reformulation integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds Brazilian and South African benchmarks by substantial margins, reflecting divergent regulatory burdens and channel sophistication. Military procurement contracts and mainstream snack penetration sustain American premium positioning. Emerging producers in Latin America and Africa face compliance cost barriers that compress realized returns.
United States
Defense logistics agencies are expanding shelf-stable protein contracts for field rations, while convenience store penetration converts meal occasions into portable consumption. USDA inspection mandates under the Federal Meat Inspection Act elevate compliance costs for interstate distribution. Texas and California specialty shops command premium biltong positioning through verified domestic sourcing claims.
Brazil
Integrated beef processors leverage captive cattle supply to serve export markets with dried meat inputs. ANVISA oversees additive compliance for processed meat products destined for domestic retail. São Paulo industrial corridors anchor production scale, though infrastructure gaps limit cold-chain reliability for artisanal dehydration.
South Africa
Biltong's cultural heritage sustains domestic consumption while export growth targets European specialty channels. The country's national food safety regulator enforces pathogen standards for air-dried meat exports. Cape Town and Johannesburg clusters concentrate artisanal curing expertise threatened by emigration of veteran processors.
Germany
EFSA sodium reduction guidance pressures reformulation of dried pork snacks distributed through conventional retail. REACH compliance adds documentation burdens for processors utilizing imported spice additives. Bavarian meat-processing traditions support small-batch positioning, though scale constraints limit export competitiveness.
Australia
Outdoor recreation culture drives jerky demand among bushwalkers and emergency preparedness consumers. TGA-equivalent state food authorities govern meat product safety for interstate commerce. Queensland and New South Wales cattle regions supply raw material, with Sydney and Melbourne retail networks testing premium biltong formats.
Dehydrated Meat Products Market Vendor Landscape
Concentration sits with integrated meatpackers controlling upstream cattle supply and captive dehydration capacity. The vendor base spans three strategic tiers: multinational protein conglomerates with slotting fee leverage, mid-scale specialists commanding direct-to-consumer channels, and regional processors exploiting cottage food law arbitrage. Dominant competitive moves include backward integration into cattle supply and portfolio diversification across jerky, biltong, and powder formats.
Within the multinational tier, JBS SA and Tyson Foods Inc exemplify scale-driven positioning anchored by feedlot-to-retail supply chain control. Country Archer Provisions occupies a position among mid-scale specialists leveraging subscription infrastructure and flavor personalization algorithms outside conventional retail gatekeeping. Hormel Foods Corporation sits within the branded consumer goods archetype, sustaining broad distribution through promotional calendar integration and conventional grocery penetration.
| Leading Market Players |
|---|
| JBS SA |
| Pilgrim's Pride Corporation |
| Cargill Incorporated |
| Jack Link's Protein Snacks |
| Kraft Heinz Company |
| Hormel Foods Corporation |
| BRF SA |
| Country Archer Provisions |
| Tyson Foods Inc |
| Others |
Supply Flow & Price Mechanics
Plant-based protein substitution in urban coastal markets is simultaneously redrawing raw material sourcing geographies and compressing pricing power for conventional jerky processors, as flexitarian trial rates force traditional curing operations to absorb reformulation costs or surrender shelf space.
Pricing Analysis
Customization-premium spreads separate small-batch biltong curators from commodity jerky processors, with specialty shops in Texas and California commanding forty-to-sixty point gross margin premiums over conventional grocery. Three-tier pricing structure across premium, standard, and economy levels stratifies by verified domestic sourcing claims, sodium-reduction certification, and direct-to-consumer channel control. Cost compression in the standard tier is intensifying because cattle cycle volatility concentrates margin pressure on processors without captive supply arrangements. Military procurement agencies exhibit the lowest price sensitivity due to specification-driven field ration requirements, while convenience store operators demonstrate acute sensitivity to per-unit wholesale movements.
Supply Chain Analysis
Inbound logistics costs from Brazilian feedlot regions through Port of Santos congestion have elevated landed costs for non-integrated processors reliant on South American cattle inputs. Geographic supply concentration centers on the United States, Brazil, and Australia, with Queensland and New South Wales regions feeding Asian export demand. Raw material dependencies rest on cattle procurement, vinegar curing inputs, and coriander spice sourcing from Indian agricultural regions. Single-source vulnerability concentrates in veteran curing expertise scarcity as sodium reduction mandates threaten flavor profile continuity. Distribution runs through integrated meatpacker networks for conventional grocery penetration, while specialty shops and online stores enable disintermediation for artisanal producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment algorithms are transforming this market into a platform-economics inflection, where direct-to-consumer data capture enables flavor-profile personalization that conventional retail gatekeeping cannot replicate.
For Market Incumbents: Compound slotting fee leverage through promotional calendar integration with conventional grocery partners while accelerating backward integration into verified domestic cattle supply chains. Sodium reduction guidance from FDA threatens traditional curing formulations, requiring clean-label process innovation investment to defend shelf space against plant-based substitutes. Captive dehydration capacity in Texas and California production clusters provides defensive moat against input volatility.
For New Entrants and Emerging Players: Subscription infrastructure gaps among multinational conglomerates create white-space opportunity for curated flavor-profile personalization and recurring revenue capture. State cottage food law arbitrage in Texas enables direct-to-consumer formulation testing before USDA scale-up, with specialty shop channel expansion offering the most penetrable margin architecture. Go-to-market execution should prioritize verified domestic sourcing storytelling to differentiate from import-dependent competitors.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale specialists commanding direct-to-consumer channel control and subscription-based replenishment infrastructure. Long-term viability over the five-to-ten year window hinges on regulatory compliance scalability and clean-label curing process patents. Watch for inflection in military procurement contract awards to shelf-stable protein suppliers as modernization programs accelerate.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cattle Supply | JBS SA's feedlot-to-retail control secures raw material access against cycle volatility. |
| Direct-to-Consumer Channel Launch | Country Archer Provisions leverages subscription algorithms outside conventional retail gatekeeping. |
| Premium Biltong Tier Introduction | Specialty shops in Texas command margin expansion unavailable in mass grocery distribution. |
| Clean-Label Curing Process Investment | FDA sodium reduction guidance accelerates reformulation pipeline development among mid-tier processors. |
| Verified Domestic Sourcing Certification | USDA traceability enforcement tightens documentation requirements for dried protein inputs. |
Methodological Framework
Initial hypotheses were tested against primary input from meat processing plant managers, specialty shop buyers, military procurement officers, and regulatory compliance leads, and refined through secondary validation against USDA inspection protocols, FDA guidance documents, ANVISA additive compliance filings, and customs trade data for beef and pork inputs. Bottom-up triangulation across processor capacity utilization rates and top-down reconciliation against retail scanner data established volume baselines.
Variance decomposition across product type, form, distribution channel, and end user segmentation dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic protein consumption trends. Industry-specific forecast inputs included cattle cycle positioning, military procurement contract award velocity, and plant-based protein substitution trial rates in urban coastal markets.
Underlying assumptions cover sustained FDA sodium reduction guidance enforcement and stable military procurement modernization trajectories, with deviation risk concentrated in cattle price volatility spikes and accelerated plant-based protein technological substitution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Meat Ingredients Market
Meat Products
Organic Meat Market
Meat Products
Rendered Poultry Products Market
Meat Products
Europe Animal Protein Market
Meat Products
Organic Lamb Market
Meat Products
Western Europe Ready-To-Eat Meat Market
Meat Products
Bacon Market
Meat Products
Reconstituted Meat Market
Meat Products
Canned Beef Market
Meat Products
Beef Bone Broth Market
Meat Products
North America Processed Pork Meat Market
Meat Products
Blended Meat Market
Meat Products
Europe Canned Meat Market
Meat Products
Mechanically Separated Meat Market
Meat Products
Binders and Scaffolders for Meat and Meat Substitutes Market
Meat Products
GCC Edible Meat Market