
 Czech Republic POS Terminals Market | 2026-2036
Czech Republic POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Czech Republic POS Terminals Market Outlook
Multi-source procurement among Czech merchants is consolidating around domestic software-integrated hardware bundles. KB SmartPay leverages its banking parentage to anchor merchant relationships across mid-sized retail chains. ComGate Payments competes on transaction fee transparency and API openness for e-commerce integrations. Dotypos specializes in Android-based terminals tailored to hospitality workflows in Prague and Brno.
A POS terminal constitutes an electronic device combining secure payment processing hardware with embedded software to authenticate and settle card-based, mobile wallet, or contactless transactions at the point of sale. Units typically incorporate PCI-certified encryption modules, EMV chip readers, and NFC antennas operating at 13.56 MHz to process payments within two seconds while maintaining end-to-end tokenization. Contactless technology leads transaction volume in Czech urban retail due to speed and hygiene preferences accelerated during pandemic-era behavior shifts. Cloud-based deployment captures fastest growth among multi-location hospitality operators seeking centralized reporting and remote firmware management. Small businesses remain the largest addressable size segment, though margin pools concentrate in medium enterprises willing to pay for integrated inventory and accounting modules.
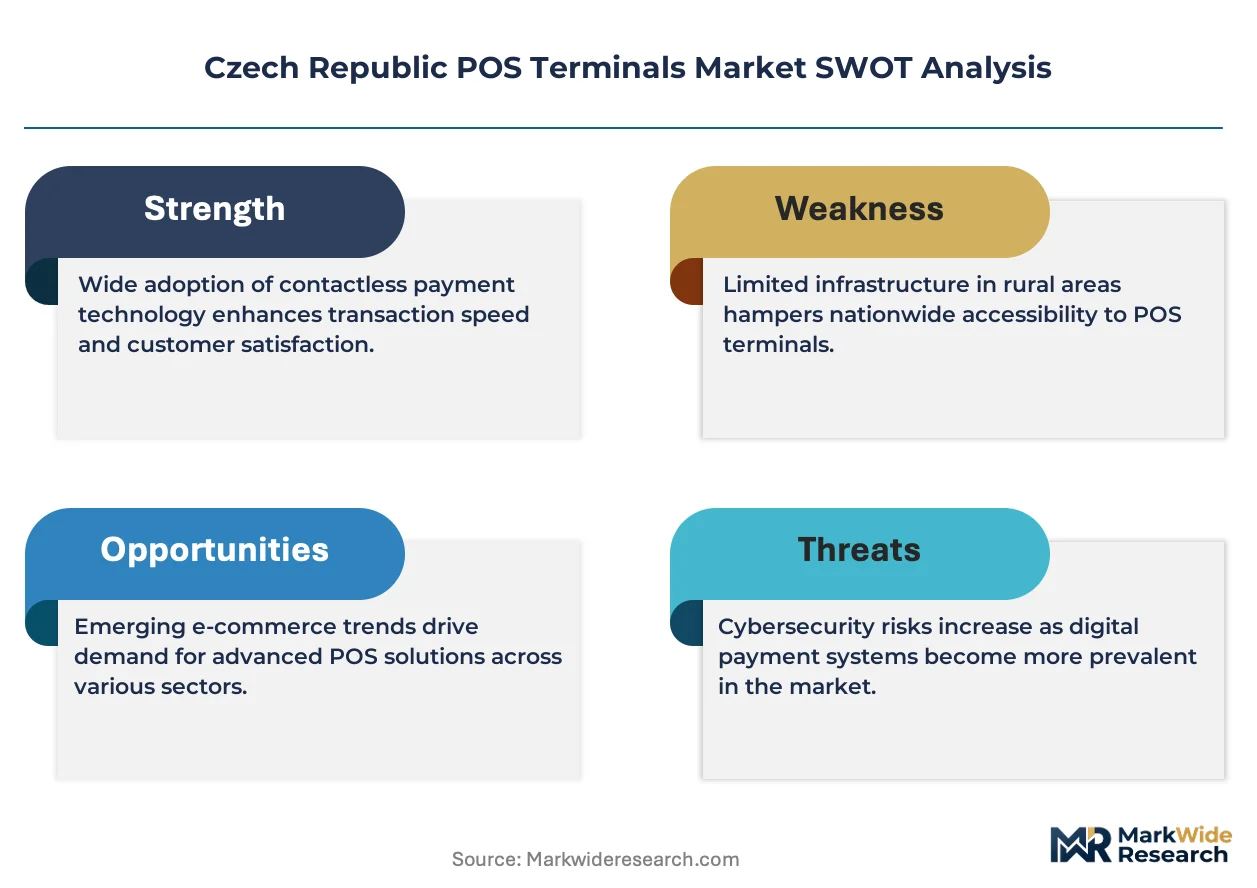
Czech National Bank supervision governs payment service provider licensing and capital reserves, while PCI DSS compliance mandates shape terminal hardware security architectures for any vendor processing card data. GDPR requirements enforce transaction data minimization and consumer consent protocols, adding software complexity for cross-border payment routing. Stakeholders must monitor whether Czech transposition of EU digital euro legislation reshapes terminal certification requirements and merchant upgrade cycles.
Market Dynamics
Contactless transaction velocity is compressing hardware refresh cycles across Czech retail and hospitality, forcing terminal vendors to prioritize NFC antenna reliability and sub-two-second processing guarantees over legacy EMV-only architectures.
Growth Catalysts
- GDPR Data Minimization Mandates:Transaction data reduction requirements are accelerating cloud-native terminal deployments that tokenize payment flows at the edge, reducing merchant compliance burden.
- Hospitality Chain Expansion:Prague and Brno restaurant groups are consolidating procurement around Android-based terminals with integrated inventory modules, driving bundled hardware-software contracts.
- Czech National Bank Licensing Framework:Electronic money institution oversight is standardizing security baselines, creating competitive moats for compliant terminal vendors against unlicensed imports.
Market Restraints
- Semiconductor Component Concentration:NFC controller and secure element sourcing depends on Asian foundry capacity, exposing Czech terminal assemblers to lead-time volatility.
- PCI DSS Certification Friction:Hardware security module validation timelines extend 8-14 months, freezing product roadmaps for vendors awaiting certification renewals.
- Smartphone Tap-to-Pay Substitution:SoftPOS applications on merchant-owned devices are eroding addressable demand for dedicated terminal hardware among micro-merchants.
Strategic Opportunities
- Regional Tourism Corridors:Karlovy Vary and Český Krumlov hospitality clusters remain underpenetrated by integrated POS-terminal ecosystems, presenting first-mover expansion potential.
- EU Digital Euro Readiness:Offline-capable terminal specifications under proposed ECB frameworks will mandate hardware upgrades, creating a mandated replacement wave.
- API-First Distribution:Embedded finance platforms are white-labeling terminal hardware through SaaS marketplaces, opening indirect channels beyond traditional bank-led sales.
Industry Challenges
- Firmware Integration Complexity:Multi-acquirer routing configurations require vendor engineering resources that Czech terminal distributors lack in-house.
- EMV Kernel Licensing Delays:Proprietary chip authentication IP negotiations with international scheme owners extend time-to-market for domestic terminal designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Czech Republic POS Terminals Market |
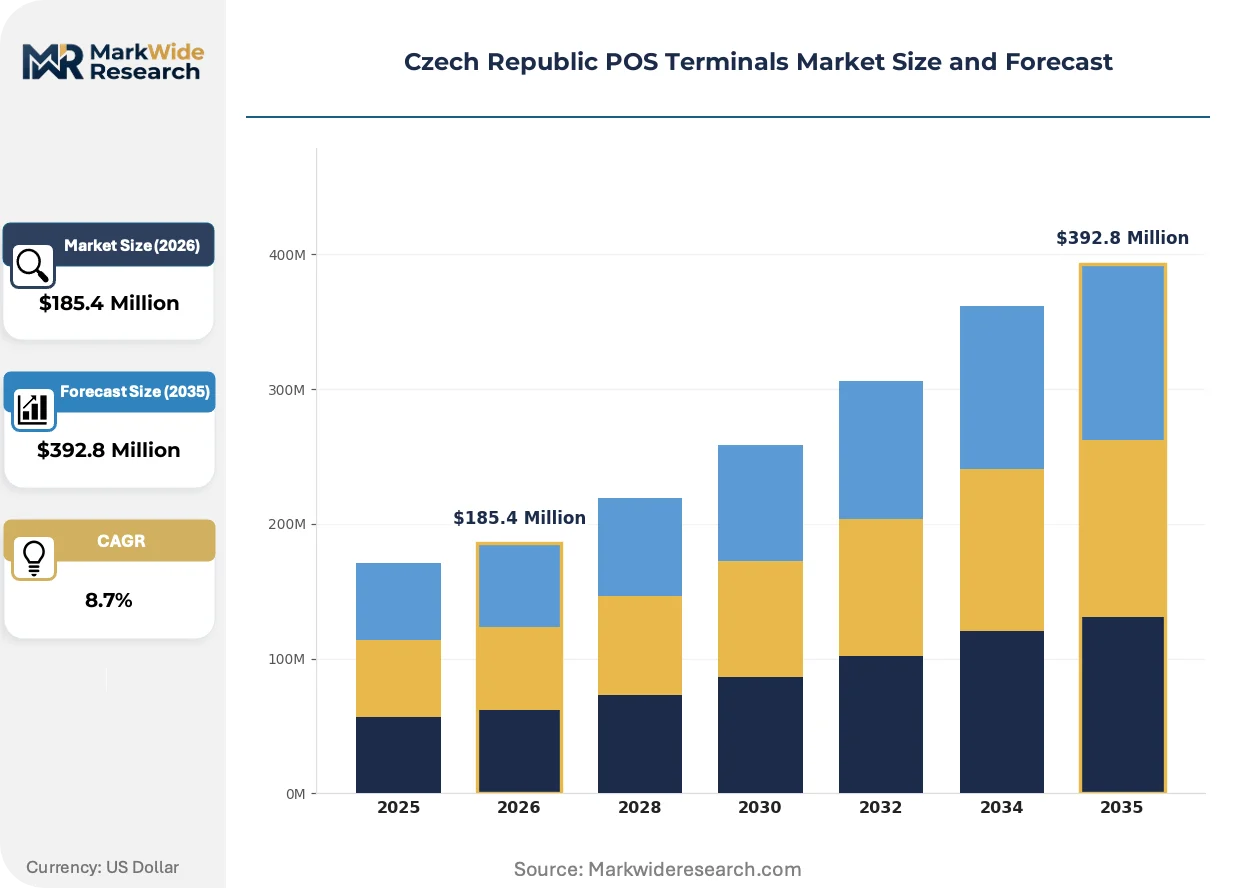
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $392.8 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Contactless, Chip & PIN, Magnetic Stripe, Mobile Payment Deployment: On-Premises, Cloud-Based, Hybrid, Offline End User: Retail, Hospitality, Transportation, Healthcare Size: Small Businesses, Medium Enterprises, Large Corporations, Enterprises |
| Companies Covered | UNICODE SYSTEMS, CircleBlue, KB SmartPay, Kevin, Dotypos, ASW Systems, ComGate Payments, Exorigo-Upos, Global Payments, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Czech Republic POS Terminals Market Strategic Shifts
Terminal architecture is fragmenting from monolithic all-in-one devices toward componentized systems where merchants mix hardware origins with software layers, compressing vendor margin pools while expanding buyer flexibility.
Android-based payment terminals is modularizing hardware from payment application logic, enabling Czech hospitality operators to swap acquirer apps without physical device replacement. Mid-sized retail chains in Prague are piloting this separation aggressively. The structural consequence is collapsing the traditional 5-7 year terminal replacement cycle toward 2-3 year software-driven refreshes.
GDPR transaction data minimization rules are forcing terminal firmware architects to embed consent management and automatic data purging at the point of capture. Hardware vendors serving Czech e-commerce merchants must now certify dual-use terminals for both in-store and unattended kiosk deployments under unified privacy baselines. The compliance burden falls heaviest on smaller terminal importers lacking dedicated data protection officers.
Merchant procurement of terminal-plus-software bundles is displacing standalone hardware purchases, with Czech retail cooperatives negotiating multi-year service contracts that embed equipment costs into per-transaction fees. Bank-led distribution channels are losing share to independent software vendors offering vertical-specific hospitality workflows. This shift concentrates in Prague's food service clusters where integrated reservation-payment systems dominate competitive tenders.
Czech Republic POS Terminals Market Segmentation
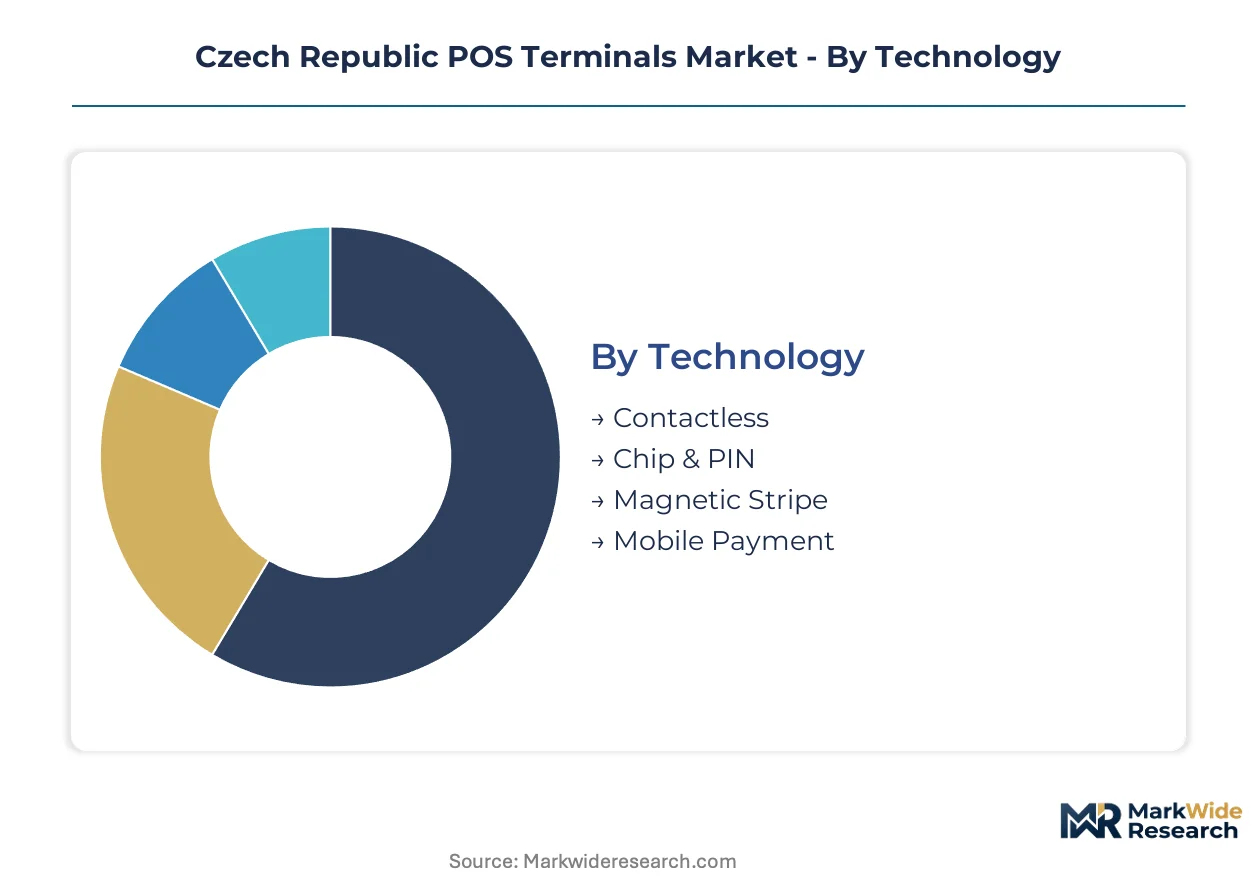
Czech terminal procurement patterns diverge sharply across technology maturity and operational scale. Segmentation reveals where vendor margin pools concentrate versus where volume commoditization pressures hardware pricing.
Technology:
Standardization dominates at the payment protocol layer while customization proliferates at the antenna and firmware integration tiers.
- Contactless:NFC-enabled terminals operating at 13.56 MHz with sub-two-second processing guarantees. Prague retail corridors and hospitality clusters drive concentration, with hygiene-persistent consumer preferences cementing this as the default transaction mode.
- Chip & PIN:EMV-certified devices with embedded secure elements and hardware encryption modules. Medium enterprises in Brno's retail districts anchor demand, balancing fraud liability reduction against per-terminal certification costs.
- Magnetic Stripe:Legacy swipe readers retained for tourist-facing merchants handling non-EMV foreign cards. Karlovy Vary hospitality operators maintain limited deployments for international visitor compatibility.
- Mobile Payment:SoftPOS-enabled smartphones and dedicated mPOS peripherals. Micro-merchants in secondary cities adopt these for zero upfront hardware commitment.
Most installed capacity flows through Contactless. Expansion is steepest in Mobile Payment.
Deployment:
Cost tier stratification separates capital-intensive on-premises installations from variable-cost cloud subscriptions.
- On-Premises:Dedicated server infrastructure with local transaction storage and batch settlement protocols. Large retail chains in Prague maintain these for latency-sensitive high-volume environments.
- Cloud-Based:Remote firmware management with centralized reporting dashboards and API-native acquirer switching. Multi-location hospitality groups across Moravia lead adoption, prioritizing real-time visibility across distributed outlets.
- Hybrid:Edge transaction processing with cloud backup and intermittent synchronization. Regional retail cooperatives favor this for resilience against connectivity outages in rural Czech corridors.
- Offline:Store-and-forward terminals with delayed settlement and local encryption key storage. Seasonal tourism operators in Český Krumlov deploy these for peak-season reliability.
Cloud-Based captures the steepest expansion trajectory as hospitality chains consolidate procurement. On-Premises retains the largest installed base among legacy retail incumbents.
End User:
Application-specific workflows dictate terminal form factor and software integration requirements.
- Retail:Integrated inventory-scanning terminals with barcode compatibility and loyalty program APIs. Supermarket chains and fashion retailers in Prague's commercial districts concentrate procurement volume.
- Hospitality:Tableside payment devices with tipping interfaces and split-bill functionality. Restaurant groups in Brno and Prague drive bundled hardware-software contract growth.
- Transportation:Ruggedized mobile terminals for ticket validation and fare collection. Municipal transit authorities and private coach operators maintain specialized durability requirements.
- Healthcare:HIPAA-aligned terminals with patient billing integration and insurance card reading. Private clinics in urban centers anchor this niche segment.
Retail commands the largest addressable base. Hospitality is gaining share fastest as integrated reservation-payment systems displace standalone hardware.
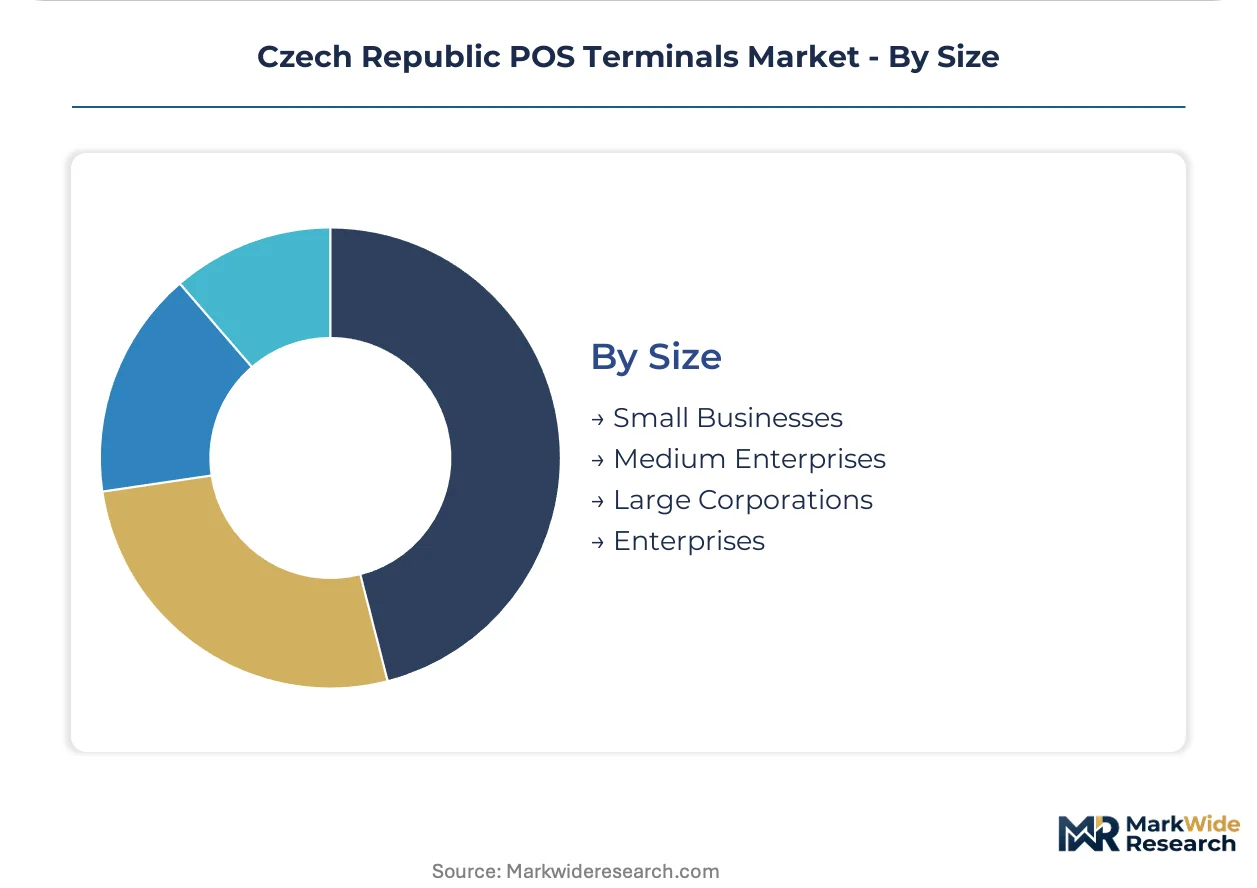
Size:
Customer type determines willingness to pay for bundled services versus bare hardware procurement.
- Small Businesses:Single-terminal deployments with minimal software integration and pay-as-you-go transaction pricing. Street merchants and sole proprietors across Czech secondary cities dominate this volume tier.
- Medium Enterprises:Multi-terminal estates with inventory modules and accounting software connectors. Regional retail chains and hospitality groups represent the primary margin concentration for vendors.
- Large Corporations:Customized terminal fleets with dedicated support SLAs and centralized procurement negotiations. National retail banners and hotel chains drive enterprise-grade requirements.
- Enterprises:Fully integrated payment ecosystems with proprietary software stacks and captive acquirer relationships. Banking-led merchant service divisions and multinational hospitality operators occupy this tier.
Small Businesses generate the highest terminal shipment volumes. Medium Enterprises yield the strongest per-unit profitability for integrated solution vendors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prague's retail and tourism corridors concentrate terminal deployment volume, with secondary urban clusters in Brno and Ostrava expanding contactless infrastructure to match capital-region transaction velocity.
Prague
Tourism-dependent hospitality operators and fashion retail chains drive NFC terminal density along Wenceslas Square and Old Town corridors. Czech National Bank electronic money institution licensing shapes vendor qualification requirements for merchants in the capital. Prague's food service clusters are consolidating procurement around Android-based terminals with integrated reservation systems.
Brno
Regional retail chains and restaurant groups anchor demand for multi-terminal estates with inventory modules. GDPR transaction data minimization mandates accelerate cloud-native deployments among Moravian hospitality operators. The Brno technology district hosts pilot programs for SoftPOS-enabled merchant devices targeting micro-business adoption.
Ostrava
Industrial zone logistics operators and wholesale merchants sustain demand for ruggedized mobile terminals with offline store-and-forward capability. Czech transposition of EU payment service directives standardizes security baselines for terminal vendors serving the region. Ostrava's retail cooperatives favor hybrid deployment models balancing edge processing with cloud backup.
Plzeň
Brewery tourism and manufacturing supply chain merchants generate specialized terminal requirements for seasonal transaction peaks. PCI DSS certification timelines constrain hardware refresh cycles for regional distributors serving Plzeň's hospitality clusters. The city's retail corridors maintain magnetic stripe compatibility for international visitor card acceptance.
Liberec
Border-crossing retail and ski resort hospitality operators demand terminals with multi-currency settlement and cross-border payment routing. GDPR consent management protocols add software complexity for vendors serving Liberec's tourism-dependent merchants. The Jizera Mountains corridor remains underpenetrated by integrated POS-terminal ecosystems relative to Prague benchmarks.
Czech Republic POS Terminals Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue API-first distribution and embedded finance integration. The vendor base stratifies across banking-led merchant service divisions, independent software vendors, and payment infrastructure specialists. Three archetypes dominate: domestic software-integrated hardware bundlers, transaction-fee-transparent acquirer-agnostics, and Android-based hospitality workflow specialists. Competitive moves concentrate on strategic partnerships with SaaS marketplaces and geographic expansion into underpenetrated regional tourism corridors.
Within the domestic banking-anchored tier, KB SmartPay leverages its parent institution's merchant relationships across mid-sized retail chains. ComGate Payments occupies a position exemplifying fee-transparency and API openness for e-commerce integrations. Dotypos represents the Android-native hospitality specialization archetype, with deployment concentration in Prague and Brno food service clusters.
| Leading Market Players |
|---|
| UNICODE SYSTEMS |
| CircleBlue |
| KB SmartPay |
| Kevin |
| Dotypos |
| ASW Systems |
| ComGate Payments |
| Exorigo-Upos |
| Global Payments |
| Others |
Value Chain & Pricing Dynamics
NFC controller chip spot prices from Taiwan Semiconductor Manufacturing Company cascade through Czech terminal assemblers into three distinct hardware tiers, compressing margins for vendors lacking long-term foundry contracts while amplifying pricing power for banking-anchored distributors with captive supply agreements.
Pricing Analysis
Input-cost pass-through from secure element and antenna module suppliers stratifies terminal pricing across certification-grade tiers. PCI DSS Level 1 certification commands premium positioning against uncertified imports, while volume-scale procurement by Prague hospitality chains extracts per-unit discounts through multi-year service bundling. Price erosion runs through the small-business tier as SoftPOS applications eliminate upfront hardware commitment. Medium enterprises exhibit lowest price sensitivity, prioritizing integrated inventory-accounting modules over bare hardware acquisition.
Supply Chain Analysis
Reverse-logistics flows for terminal refurbishment and secure element recovery remain underdeveloped in the Czech market, with end-of-life devices typically routed to Polish recycling facilities rather than domestic remanufacturing. Component sourcing draws from Taiwan, China, and South Korea for NFC controllers, encryption modules, and Android processing chipsets. Single-source vulnerability in EMV kernel IP licensing from international scheme owners creates certification bottlenecks. Distribution runs through banking-led merchant service divisions and independent software vendor marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Czech Republic POS Terminals Market functions as a geographic-arbitrage play between Prague's saturated contactless infrastructure and Moravian regional clusters where GDPR-compliant cloud deployment costs run 15-20 percent below capital-region benchmarks.
For Market Incumbents: To counter SoftPOS substitution eroding micro-merchant hardware demand, KB SmartPay and ComGate Payments should deepen backward integration into Android firmware development and secure exclusive distribution rights with emerging SaaS marketplace channels. PCI DSS certification investment creates defensive moats against unlicensed terminal imports.
For New Entrants and Emerging Players: Capture the underpenetrated Karlovy Vary and Český Krumlov hospitality corridors where integrated reservation-payment systems remain scarce. API-first distribution through embedded finance platforms offers the most penetrable go-to-market angle, bypassing entrenched bank-led sales relationships.
For Investors and Strategic Acquirers: Asymmetric upside sits with Android-native hospitality workflow specialists possessing vertical-specific software integration capabilities. Long-term viability hinges on EU Digital Euro readiness and offline-capable terminal specifications. Monitor Czech National Bank electronic money institution licensing announcements as inflection indicators for vendor consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Distribution Partnership | Embedded finance platforms in Prague open indirect sales channels beyond traditional banking relationships. |
| GDPR-Compliant Cloud Deployment | Moravian hospitality operators accelerate adoption of tokenized edge-processing architectures. |
| Regional Tourism Corridor Expansion | Karlovy Vary and Český Krumlov clusters present first-mover integrated terminal ecosystem opportunities. |
| EMV Kernel Licensing Negotiation | Domestic terminal designs require proprietary chip authentication IP agreements with international scheme owners. |
| EU Digital Euro Hardware Readiness | Offline-capable terminal specifications under ECB frameworks mandate replacement upgrade cycles. |
Study Parameters
Coverage spans Prague, Brno, Ostrava, and secondary Czech urban clusters, with primary inputs from each region combined with secondary validation. Terminal vendor executives, hospitality procurement managers at restaurant groups, Czech National Bank regulatory affairs specialists, and independent software vendor integration engineers provided structured interview inputs. Secondary sources include PCI Security Standards Council certification databases, Czech National Bank electronic money institution licensing registers, EU payment service directive transposition documents, and hospitality industry trade association deployment surveys. Bottom-up terminal shipment estimates triangulate against top-down market value reconstruction.
Rate-of-change decomposition separates hardware replacement cycle compression from cloud-subscription revenue acceleration across the analysis window. Segmentation dimensions modeled include technology protocol, deployment architecture, end-use application, and customer size tier. CAGRs derive from fitted growth curves applied to vendor-reported shipment data and merchant procurement survey responses. Industry-specific inputs incorporate NFC transaction velocity trends and GDPR compliance cost burden estimates.
Semiconductor foundry capacity allocation shifts, Czech transposition timing of EU digital euro legislation, and SoftPOS adoption rates among micro-merchants are the dominant revision risks to modeled forecasts. Forecasts reflect documented assumptions regarding hardware refresh cycle duration and cloud-native deployment penetration trajectories. Practitioners should monitor foundry utilization reports, ECB terminal specification releases, and merchant device substitution patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
South Africa Real Time Payments Market
Payments
Mobile Card Reader Market
Payments
India Forex Cards Market
Payments
Nigeria Mobile Money Market
Payments
Transaction Monitoring Market
Payments
United Kingdom Real Time Payments Market
Payments
Retail Cash Management Market
Payments
Cash Management System Market
Payments
Europe Payments Market
Payments
In Vehicles Payment Market
Payments
United States Clearing Houses and Settlements Market
Payments
Norway POS Terminals Market
Payments
Middle East & North Africa Digital Payments Market
Payments
Asia-Pacific Digital Remittance Market
Payments
Europe Payment Gateways Market
Payments
United Arab Emirates Payment Market