
 Czech Republic Container Glass Market | 2026-2036
Czech Republic Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Czech Republic Container Glass Market Outlook
Czech glassworks in the Vysočina region is broadening specialty container output for pharmaceutical and craft spirits clients. Vetropack Moravia Glass leverages vertical integration from raw material processing to finished bottle distribution across Central European markets. Sklárny Moravia anchors traditional hand-blown production for premium cosmetic and gift segments. O-I Czech Republic sustains high-volume automated lines serving major brewery contracts.
Container glass comprises hollow-ware formed from molten silica-soda-lime or borosilicate formulations, typically exhibiting wall thickness of 2–5 mm and thermal shock resistance to 150°C for pharmaceutical and food-grade applications. Amber glass segments dominate pharmaceutical packaging where UV-blocking properties protect light-sensitive formulations. Soda-lime bottles lead food and beverage volumes through cost-efficient mass production. Borosilicate jugs command premium margins in laboratory and high-temperature household applications.
BIS certification requirements for imported pharmaceutical packaging materials and EU REACH chemical safety standards constrain raw material sourcing flexibility for Czech producers. The country's environmental ministry enforces extended producer responsibility schemes that elevate recycled glass feedstock utilization thresholds. Stakeholders must monitor impending EU packaging and packaging waste regulation revisions that will mandate minimum recycled content rates and reshape competitive positioning across material categories.
Market Dynamics
The Czech container glass sector confronts tightening EU packaging waste mandates that force furnace-level recalibration and feedstock reconfiguration. Extended producer responsibility schemes now bind Moravian and Bohemian producers to quantified cullet recovery targets.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Minimum recycled content thresholds for glass containers create guaranteed offtake for domestic cullet processors. Czech environmental ministry enforcement accelerates furnace retrofits.
- Plzeň brewing corridor expansion:Premium lager and craft ale bottling volumes sustain amber and flint glass demand. Brewery packaging contracts anchor high-volume production runs.
- Borosilicate lightweighting:Specialty spirits and pharmaceutical clients adopt thinner-walled high-strength bottles. Thermal shock resistance specifications enable wall thickness reduction without breakage penalties.
Market Restraints
- Natural gas cost volatility:Furnace operations depend on pipeline gas pricing indexed to TTF benchmarks. Energy input swings compress margin predictability for soda-lime mass producers.
- Recycled glass feedstock quality variance:Cullet contamination from ceramic and leaded glass sources disrupts furnace chemistry. Sorting infrastructure gaps in Central European collection networks constrain high-grade supply.
- Plastic substitution in beverage packaging:PET bottle cost advantages in water and soft drink segments displace glass volumes. Lightweight plastic barrier technologies erode glass's premium positioning in mid-market categories.
Strategic Opportunities
- Prague pharmaceutical packaging cluster:Injectable and biologic drug formulation growth drives demand for Type I borosilicate vials. Sterile filling line compatibility requirements favor regional glass sourcing.
- Carbon border adjustment mechanism:EU CBAM phase-in penalizes imported container glass from carbon-intensive production. Czech furnace electrification pilots position domestic output for compliance advantage.
- Direct-to-craft distillery channels:Small-batch spirits producers seek customized bottle shapes with shorter lead times. Digital printing and modular mold systems enable micro-run economics.
Industry Challenges
- Furnace rebuild capex cycles:Regenerative furnace campaigns require 30-50 million euro commitments at 10-15 year intervals. Financing availability constrains smaller Vysočina region operators.
- REACH chemical compliance timelines:Substance of very high concern screenings for colorants and surface treatments delay new product introductions. ECHA dossier preparation extends development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Czech Republic Container Glass Market |
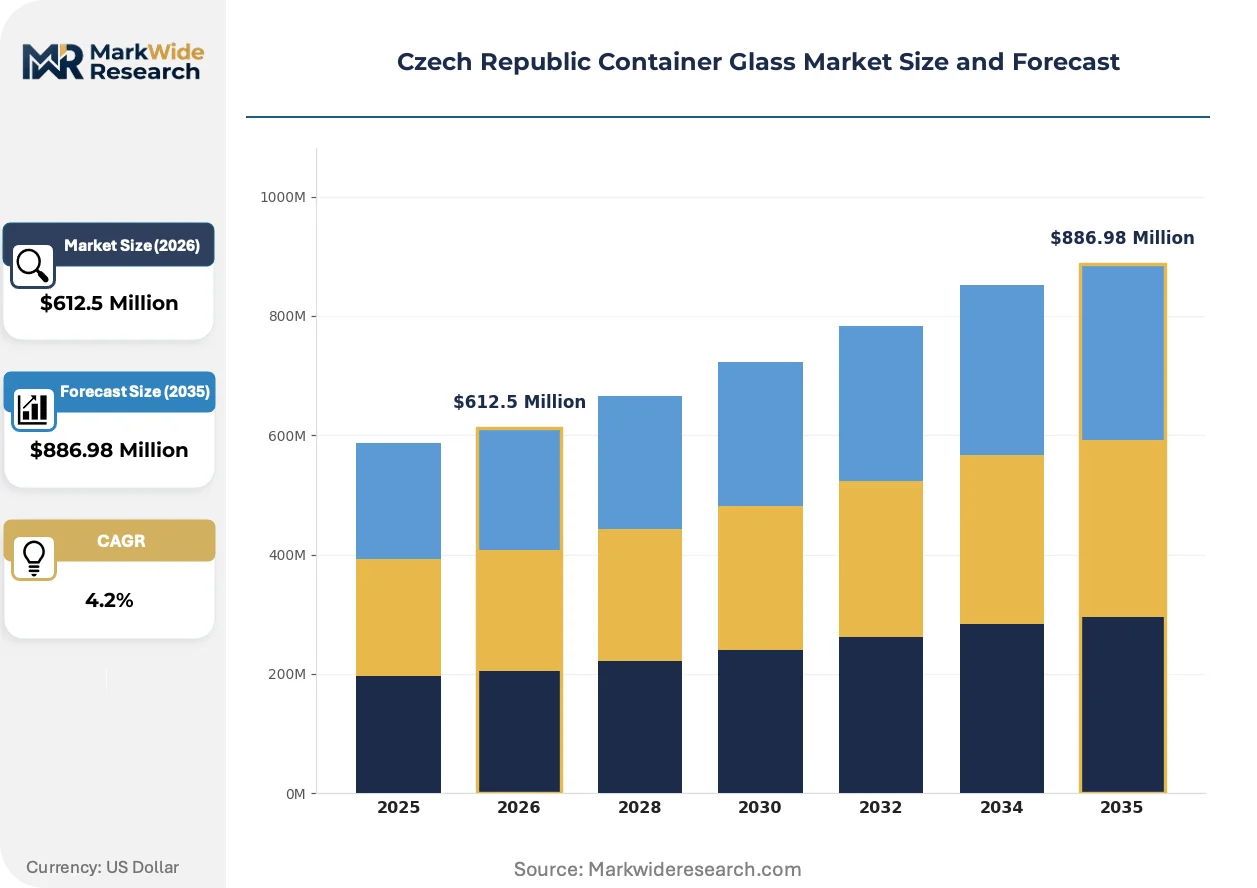
| Market Size in 2026 | $612.5 Million |
| Market Size in 2035 | $886.98 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Tumblers Application: Food & Beverage, Pharmaceuticals, Cosmetics, Household End User: Manufacturers, Retailers, Distributors, Wholesalers Material: Recycled Glass, Soda-Lime Glass, Borosilicate Glass, Amber Glass |
| Companies Covered | Vetropack Moravia Glass, Sklárny Moravia, O-I Czech Republic, Stoelzle Union, GLASSABRASIV, Bohemia Jihlava, ADPACK group, Galapack, ARTMIX Glass Atelier, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Czech Republic Container Glass Market Strategic Shifts
Digital furnace control and cullet beneficiation technologies are compressing energy intensity benchmarks. Regulatory pressure on carbon emissions fuses with buyer specifications for lower-footprint packaging.
Electrified melting technology is absorbing capital allocation across Czech glassworks. Hybrid and all-electric furnace designs cut Scope 1 emissions by 60-80 percent versus conventional regenerative systems. Sklárny Nižbor and Vetropack Moravia pilot oxy-fuel and electrode configurations. The technology is absorbing regulatory compliance costs into capital structure rather than operational expenditure.
EU Green Deal industrial emissions standards tighten furnace NOx and particulate thresholds. Czech producers face 2030 benchmarks requiring flue gas treatment retrofits or fuel switching. The Plzeň brewing corridor's major bottling contracts now specify supplier carbon disclosure, pressuring glassworks to document furnace-level emissions.
Consolidated brewery procurement desks centralize container purchasing decisions. Pilsner Urquell and Budweiser Budvar parent entities negotiate multi-year supply agreements with volume commitments and sustainability riders. Direct supplier relationships displace distributor intermediaries for standardized bottle formats. The shift concentrates negotiation leverage with three major brewing groups operating in the Czech market.
Czech Republic Container Glass Market Segmentation
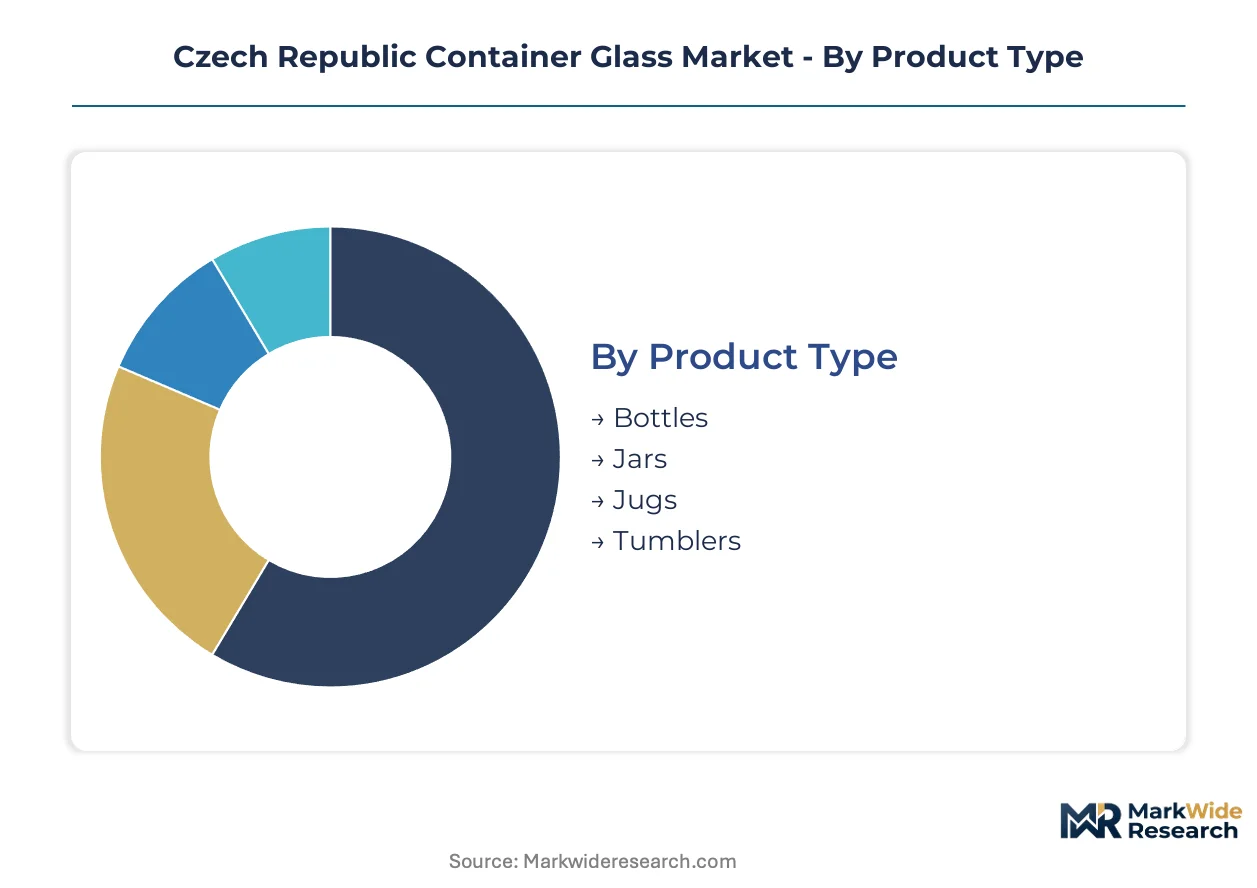
Glass composition and forming technology dictate furnace configuration, energy intensity, and end-use certification requirements across Czech production facilities. Segment boundaries align with distinct regulatory pathways: pharmaceutical packaging demands Type I borosilicate compliance, while beverage containers prioritize lightweighting and recycled content thresholds.
Product Type:
Forming method and neck finish geometry differentiate container categories, with press-blow versus blow-blow processes determining wall thickness tolerance and production speed.
- Bottles:Narrow-neck hollow-ware dominates beverage and pharmaceutical volumes, with lightweight borosilicate variants gaining traction in premium spirits. The Plzeň brewing corridor anchors high-volume amber and flint bottle contracts.
- Jars:Wide-mouth containers serve food preservation and cosmetic cream segments. Screw-cap compatibility requirements drive standardized neck finish specifications across Moravian glassworks.
- Jugs:Large-format vessels concentrate in laboratory and high-temperature household applications. Thermal shock resistance specifications command premium positioning over commodity soda-lime alternatives.
- Tumblers:Stemless drinking glasses and candle vessels round out specialty output. Hand-blown production in Vysočina region serves gift and hospitality segments.
Mature deployment sits with bottles. Newer deployment is concentrated in lightweight jug formats for laboratory applications.
Application:
End-use certification requirements fragment demand into distinct quality tiers, with pharmaceutical and food-grade specifications imposing divergent testing protocols on shared production assets.
- Food & Beverage:Amber and flint containers protect beer, wine, and preserves from oxidation and light degradation. EU packaging waste directives mandate minimum recycled content for this volume-leading segment.
- Pharmaceuticals:Type I borosilicate vials and ampoules meet USP and EP chemical durability standards. The Prague pharmaceutical packaging cluster drives demand for sterile filling line compatibility.
- Cosmetics:Decorative flint and colored glass differentiate premium skincare and fragrance positioning. Sklárny Moravia anchors hand-finished output for luxury brand clients.
- Household:Storage and tableware applications tolerate wider dimensional tolerances than commercial segments. Price sensitivity here exposes producers to import competition from Polish and Slovak glassworks.
Food and beverage applications absorb the majority of furnace capacity. Pharmaceutical demand is climbing the fastest on per-unit margin expansion.
End User:
Procurement scale and technical specification authority determine supplier relationship structures, with consolidated buyers extracting volume commitments and sustainability disclosures.
- Manufacturers:Brand-owning brewers, distillers, and drug formulators specify container performance directly. Pilsner Urquell and Budweiser Budvar parent entities negotiate multi-year supply agreements with carbon disclosure riders.
- Retailers:Private-label food and beverage chains source standardized formats through consolidated procurement desks. Aldi and Lidl Central European operations impose uniform specification sheets across national glassworks.
- Distributors:Intermediary stocking roles diminish as brewery procurement centralizes. Remaining distributors concentrate on craft spirits micro-runs and imported specialty glass.
- Wholesalers:Bulk resale to smaller food processors and regional beverage brands survives in fragmented segments. Price competition from PET and metal alternatives compresses margins in this channel.
Direct manufacturer relationships command priority furnace allocation. Distributor intermediation is retreating toward niche and import-dependent segments.
Material:
Chemical composition determines thermal expansion coefficient, chemical resistance, and recycling pathway compatibility, with furnace campaigns locking facilities into specific glass families for extended production runs.
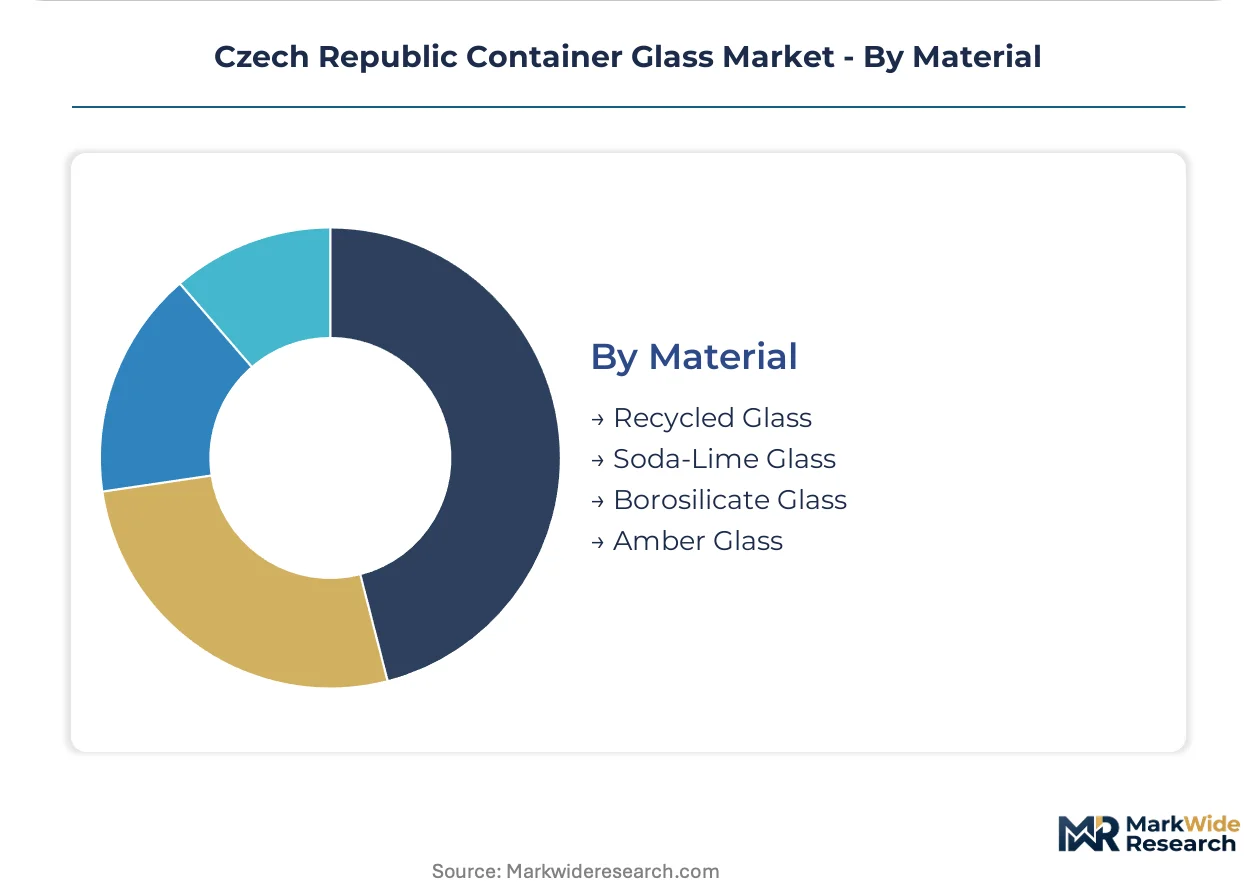
- Recycled Glass:Cullet feedstock reduces energy consumption and virgin raw material demand. Extended producer responsibility schemes now bind Czech producers to quantified recovery targets enforced by the environmental ministry.
- Soda-Lime Glass:Silica-soda-lime formulations dominate mass-market beverage and food containers through cost-efficient furnace economics. Natural gas price volatility indexed to TTF benchmarks squeezes margin predictability for this volume base.
- Borosilicate Glass:Low thermal expansion coefficient enables thin-walled, high-strength designs for pharmaceutical and laboratory applications. Premium spirits brands in Bohemia adopt lightweight borosilicate bottles for differentiation.
- Amber Glass:Iron and sulfur colorants block UV transmission below 450 nanometers, protecting light-sensitive pharmaceuticals and beers. UV-blocking properties command persistent demand despite higher cullet sorting costs.
Soda-lime formulations anchor established furnace infrastructure. Borosilicate expansion is gaining share fastest on pharmaceutical and premium beverage specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silica sand deposits in the Střední Čechy region anchor Czech container glass production, feeding furnace operations across Moravia and Bohemia with high-purity feedstock.
Plzeň Region
Pilsner Urquell and Budweiser Budvar bottling contracts sustain amber glass furnace campaigns. The Czech environmental ministry enforces extended producer responsibility schemes that mandate cullet recovery thresholds. Brewery procurement desks in Plzeň city centralize multi-year supply agreements with carbon disclosure riders.
Vysočina Region
Hand-blown specialty output serves premium cosmetic and gift segments through smaller glassworks operations. EU packaging waste directives reshape material sourcing requirements for regional producers. Jihlava anchors traditional production methods while digital furnace control pilots reduce energy intensity benchmarks.
Prague Metropolitan Area
Injectable and biologic drug formulation growth drives demand for Type I borosilicate vials. ECHA REACH chemical safety standards constrain raw material sourcing flexibility for pharmaceutical packaging suppliers. The Prague pharmaceutical packaging cluster concentrates sterile filling line compatibility requirements.
South Moravian Region
Vetropack Moravia Glass leverages vertical integration from raw material processing to finished bottle distribution. EU Green Deal industrial emissions standards tighten furnace NOx thresholds requiring flue gas treatment retrofits. Brno serves as the logistics hub for Central European market distribution.
Czech Republic Container Glass Market Competitive Environment
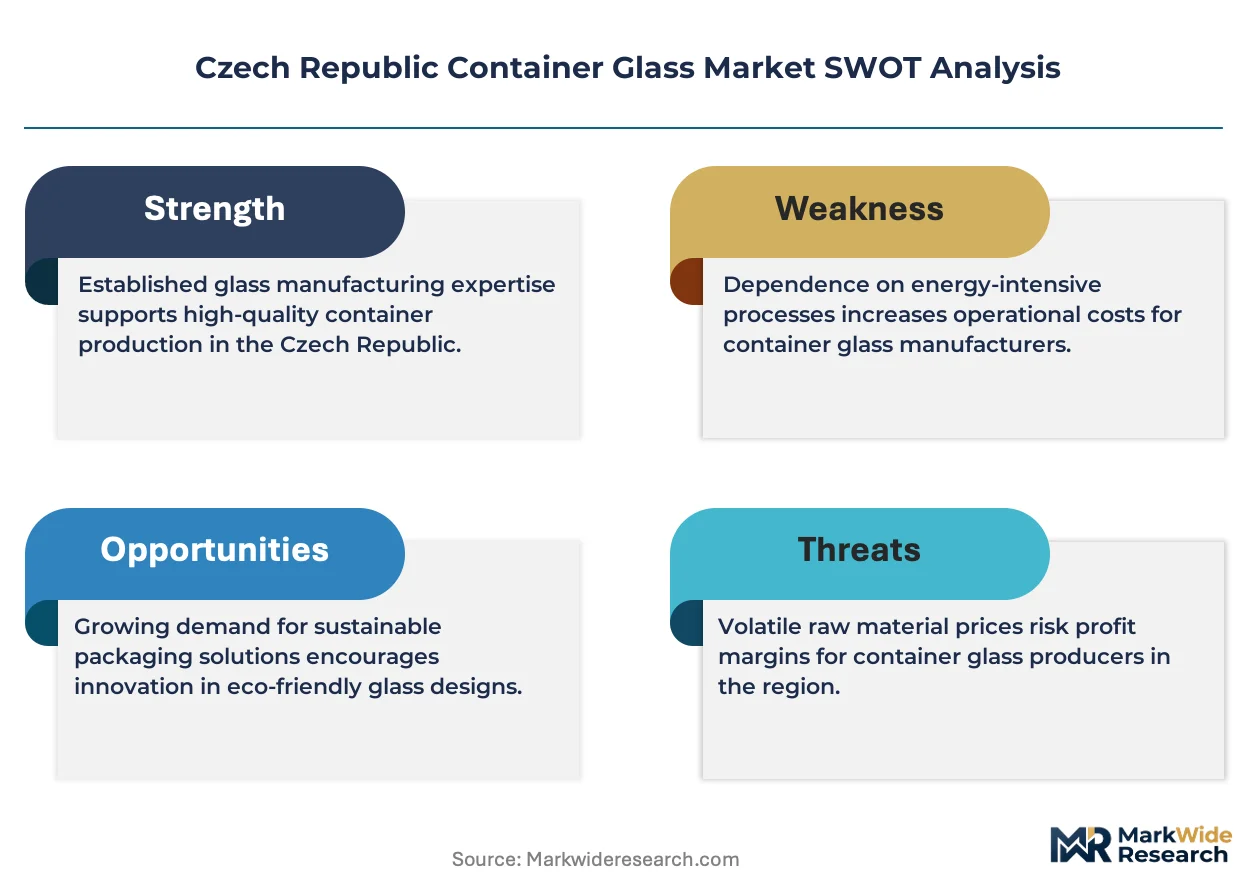
Global majors compete with regional champions across furnace technology and procurement contract structures. The Czech container glass sector exhibits tiered concentration, with high-volume automated lines serving consolidated brewery buyers alongside specialized hand-blown output for premium segments. Three archetypes dominate: integrated multinational operators, regional specialty glassworks, and craft-focused artisan producers. Competitive dynamics center on furnace electrification investments and direct-to-manufacturer procurement relationships that displace distributor intermediaries.
Among Moravian and Bohemian producers, Vetropack Moravia Glass, Sklárny Moravia, and O-I Czech Republic occupy distinct strategic positions. Vetropack Moravia Glass exemplifies the vertically integrated archetype spanning raw material processing through distribution. Sklárny Moravia represents specialty craft production anchored in hand-finished techniques. O-I Czech Republic sits within the high-volume automated tier serving standardized beverage contracts. Each anchors a different competitive vector without direct overlap in furnace configuration or buyer relationships.
| Leading Market Players |
|---|
| Vetropack Moravia Glass |
| Sklárny Moravia |
| O-I Czech Republic |
| Stoelzle Union |
| GLASSABRASIV |
| Bohemia Jihlava |
| ADPACK group |
| Galapack |
| ARTMIX Glass Atelier |
| Others |
Value Chain & Pricing Dynamics
Electrified furnace retrofits across Moravian and Bohemian glassworks compress energy cost differentials while concentrating production among capital-rich operators capable of financing 30-50 million euro rebuild cycles. This technology transition simultaneously elevates fixed cost structures and reduces marginal energy exposure, reshaping how pricing power distributes between furnace operators and consolidated brewery procurement desks.
Pricing Analysis
Extended warranty and technical service bundling distinguishes premium furnace output from commodity spot transactions, with Vetropack Moravia and O-I Czech Republic embedding multi-year maintenance commitments into long-term supply agreements. Three-tier pricing structure across premium borosilicate pharmaceutical grades, standard amber beverage bottles, and economy soda-lime household ware reflects certification intensity and thermal performance specifications. Pricing pressure stems from PET substitution in water and soft drink segments, compressing mid-market glass margins. Retailers and private-label chains exhibit highest price sensitivity, while pharmaceutical formulators prioritize sterile filling line compatibility over unit cost.
Supply Chain Analysis
EU REACH chemical safety certifications and BIS import requirements gate raw material sourcing for pharmaceutical-grade output, constraining colorant and surface treatment supplier pools to pre-qualified vendors. Czech production draws from domestic Střední Čechy silica sand deposits, German soda ash supply, and Ukrainian natural gas feedstock before pipeline diversification. Single-source vulnerability concentrates in TTF-indexed natural gas pricing for furnace operations. Distribution runs through Brno logistics hubs serving Central European brewery and pharmaceutical clusters, with direct-to-manufacturer contracts displacing distributor intermediaries for standardized bottle formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where furnace electrification and captive cullet processing determine cost position. Players are pursuing backward integration into raw material beneficiation and recycled glass sorting infrastructure to secure feedstock quality and compliance margins.
For Market Incumbents: Acquire cullet beneficiation and sorting assets to secure high-grade recycled feedstock against contamination variance risks. Anchor furnace allocation through multi-year carbon-disclosure contracts with Pilsner Urquell and Budweiser Budvar parent entities, insulating volume base from PET substitution pressure. For New Entrants and Emerging Players: Enter via direct-to-craft distillery channels offering digital-printed micro-runs with sub-10,000 unit minimums and modular mold systems. Target Vysočina region specialty segments where hand-blown cosmetic and gift applications command premium positioning outside automated volume competition. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated packaging conglomerates seeking Central European furnace capacity and EU Green Deal compliance positioning. Long-term viability hinges on electrification capex completion and carbon border adjustment mechanism advantage crystallization. Monitor EU packaging waste regulation recycled content threshold enforcement as inflection signal for cullet processor valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Electrification Investment | Hybrid and all-electric designs cut Scope 1 emissions 60-80 percent versus regenerative systems. |
| Backward Integration into Cullet Processing | Captive sorting infrastructure secures high-grade recycled feedstock against ceramic contamination risks. |
| Direct-to-Manufacturer Procurement Contracts | Carbon disclosure riders with Plzeň brewing groups anchor multi-year volume commitments. |
| Pharmaceutical Certification Investment | Type I borosilicate USP/EP compliance opens Prague injectable and biologic drug formulation demand. |
| Digital Printing and Modular Mold Systems | Micro-run economics enable craft spirits customization with shortened lead times. |
Study Parameters
Document review covered EU packaging waste directive filings, Czech environmental ministry extended producer responsibility enforcement records, and ECHA REACH substance dossiers, complemented by interviews with glassworks plant managers, brewery procurement directors, pharmaceutical packaging engineers, and cullet processor operations leads. Secondary validation drew from furnace technology supplier technical specifications, Central European customs trade data, and SEC filings of multinational packaging parents. Bottom-up volume modeling triangulated against top-down industry association capacity estimates.
Historical furnace campaign data cross-referenced against panel input from Moravian and Bohemian production directors established baseline capacity utilization assumptions across the projection horizon. Segmentation modeling incorporated glass composition tiers, forming technology distinctions, and end-use certification requirements as core dimensions. CAGRs derived from weighted average of demand elasticity estimates for beverage, pharmaceutical, and cosmetic application clusters, with natural gas price volatility and recycled content mandate timelines as scenario variables.
Revisions become necessary when EU packaging waste regulation thresholds accelerate, TTF natural gas benchmarks destabilize furnace economics, or PET barrier technology breakthroughs accelerate beverage substitution beyond modeled rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Spain Container Glass Market
Glass Packaging
Ukraine Container Glass Market
Glass Packaging
Guatemala Container Glass Market
Glass Packaging
Glass Veil Market
Glass Packaging
Bangladesh Container Glass Market
Glass Packaging
Middle East and Africa Glass Packaging Market
Glass Packaging
North America Glass Packaging Market
Glass Packaging
Germany Container Glass Market
Glass Packaging
Global Container Glass Market
Glass Packaging
Angola Container Glass Market
Glass Packaging
Europe Glass Bottles and Containers Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
Mason Jars Market
Glass Packaging
Asia - Pacific Glass Bottles and Containers Market
Glass Packaging
Chile Container Glass Market