
 Credit Default Swap Market | 2026-2036
Credit Default Swap Market Size, Share, and Industry Trends Forecast 2026-2036
Credit Default Swap Market Analysis
Project finance securitization is reconfiguring which institutions can originate and distribute credit protection, as asset-light structuring enables non-bank entrants to compete without balance-sheet intensity. Citigroup leverages its global corporate lending franchise to originate single-name CDS tied to investment-grade borrowers. Deutsche Bank anchors European sovereign and financial reference entity trading through its Frankfurt and London sales desks. JPMorgan Chase & Co. sustains leadership in index CDS market-making via its rates and credit hybrid desk infrastructure.
A credit default swap constitutes a bilateral derivative contract where the protection buyer makes periodic premium payments to the seller in exchange for a contingent payment upon a credit event affecting a specified reference obligation; ISDA master agreements standardize documentation while upfront margin and variation margin requirements govern collateral flows under central clearing mandates. Single-name contracts dominate notional outstanding but index CDS captures disproportionate trading velocity, with CDX and iTraxx indices serving as the primary vehicles for macro credit positioning. Hedge funds and institutional buyers concentrate in index products for liquidity, while insurance companies and corporations utilize single-name and basket structures for tailored risk transfer against specific counterparty exposures.
The Commodity Futures Trading Commission and Securities and Exchange Commission enforce US swap dealer registration, margin rules, and real-time reporting under Dodd-Frank Title VII, while the European Securities and Markets Authority implements MiFID II transaction reporting and EMIR clearing obligations for EU-domiciled entities. Basel III endgame proposals on standardized credit risk weights are reshaping bank capital treatment of uncleared CDS positions, directly affecting dealer willingness to warehouse risk. Stakeholders must monitor whether regional divergence in clearing mandates fragments liquidity pools or drives further concentration into CME and ICE clearinghouses.
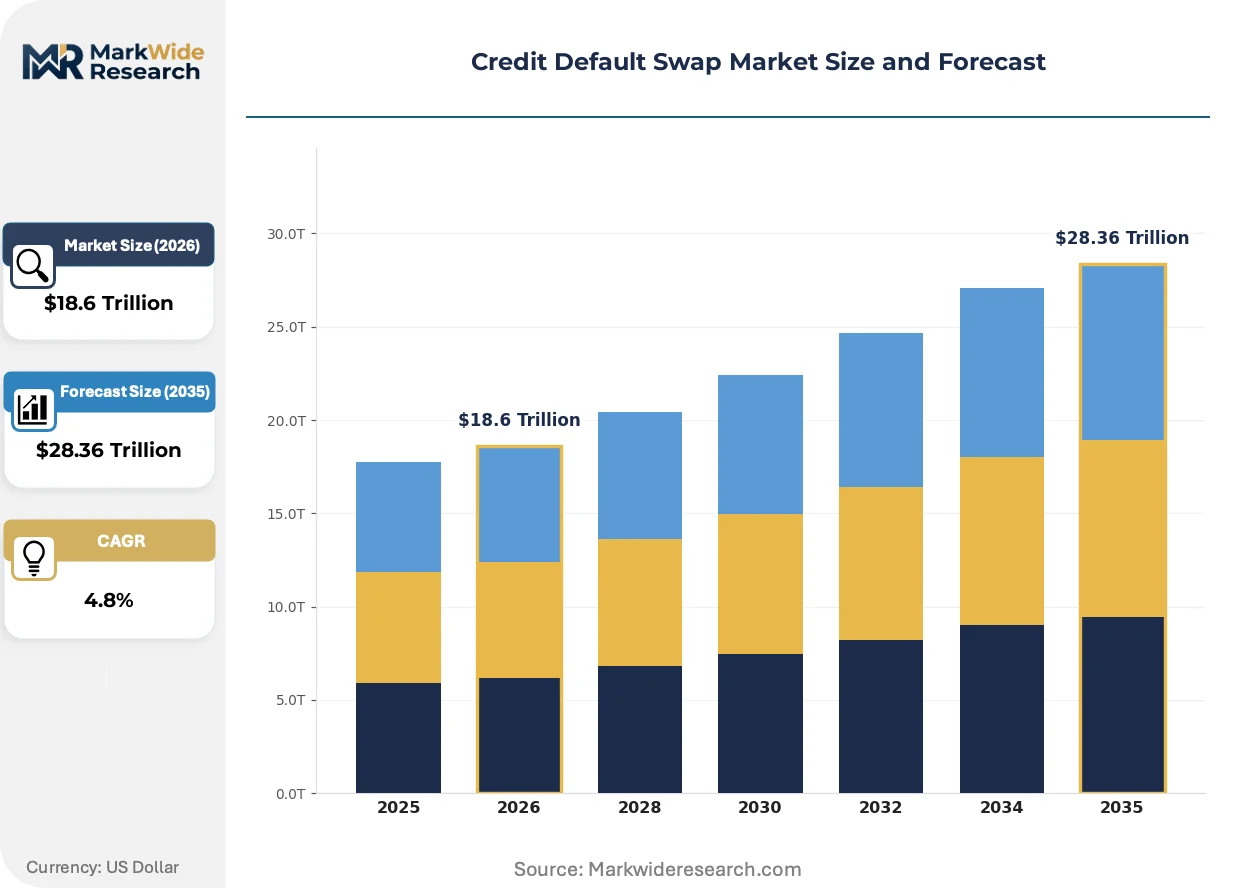
Market Dynamics
Central clearing mandates under EMIR and Dodd-Frank Title VII are restructuring dealer economics and concentrating liquidity into CME Group and ICE clearinghouses, compressing uncleared bilateral activity while elevating collateral velocity as the defining operational metric.
Growth Catalysts
- Basel III endgame standardized risk weights:Banks face escalating capital charges on uncleared CDS positions, accelerating migration toward cleared index products and amplifying demand for central counterparty infrastructure.
- Pension fund liability-driven investment strategies:UK and Dutch pension schemes expand CDS usage for credit spread hedging against long-duration fixed-income portfolios, creating structural demand for investment-grade single-name protection.
- Climate transition finance:Green bond issuers and sustainability-linked loan underwriters deploy CDS to isolate carbon-intensive reference entities, embedding credit protection into environmental risk transfer frameworks.
Market Restraints
- Collateral liquidity requirements:Central clearing mandates demand high-grade sovereign bonds and cash as initial margin, constraining dealer balance sheet capacity during Treasury market stress episodes.
- Reference entity concentration:North American investment-grade corporates dominate CDX.IG composition, limiting diversification benefits when sectoral credit cycles synchronize.
- Sovereign CDS market fragmentation:EMIR and SEC reporting divergence creates documentation friction for European sovereign protection, suppressing liquidity relative to corporate indices.
Strategic Opportunities
- Asia-Pacific sovereign and quasi-sovereign underpenetration:Australian and Japanese provincial government bond issuers lack liquid single-name CDS markets, presenting structuring opportunities for regional dealers.
- Tokenized collateral mobility:Distributed ledger infrastructure for margin tokenization is hybridizing with traditional repo markets, enabling intraday collateral velocity for cleared derivatives.
- EU SFDR Article 8 and 9 fund mandates:Sustainable finance disclosure requirements incentivize ESG-screened CDS indices, creating product development white space for reference baskets excluding carbon-intensive sectors.
Industry Challenges
- Quantitative credit analyst scarcity:Sell-side desks struggle to recruit professionals proficient in both stochastic default modeling and regulatory capital optimization, compressing pricing precision for bespoke structures.
- Legacy portfolio compression:Bilateral single-name positions accumulated pre-cleared mandate require costly tear-up negotiations, trapping operational resources and obscuring net risk exposures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Credit Default Swap Market |
| Market Size in 2026 | $18.6 Trillion |
| Market Size in 2035 | $28.36 Trillion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Contract Type: Single Name, Index, Basket, Sovereign Buyer Type: Institutional Investors, Hedge Funds, Insurance Companies, Corporations Reference Entity Type: Corporates, Financials, Sovereigns, Supranationals Settlement Method: Cash Settlement, Physical Settlement, Auction-Based, Market-Standard |
| Companies Covered | Citigroup, Deutsche Bank, JPMorgan Chase & Co., UBS, BNP Paribas, Goldman Sachs Group, Barclays, HSBC, Morgan Stanley, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Credit Default Swap Market Emerging Trajectories
Credit derivatives infrastructure is converging with real-time risk analytics and automated collateral management, compressing settlement cycles while elevating data granularity as a competitive differentiator among execution venues.
Machine learning-driven credit scoring is hybridizing with traditional structural models, enabling dynamic spread forecasting that incorporates alternative data feeds from supply chain monitoring and satellite imagery. Hedge funds and systematic credit funds deploy these hybrid models for index arbitrage strategies, compressing the latency between signal generation and position execution. The technology is displacing static rating-based approaches in proprietary trading desks, forcing incumbents to restructure quant research functions.
The European Securities and Markets Authority is tightening EMIR REFIT reporting standards for derivatives transactions, mandating enhanced granularity in counterparty identification and valuation methodology. Buy-side firms face operational restructuring to consolidate fragmented trade repositories and reconcile reporting timestamps across multiple jurisdictions. Asset managers with EU-domiciled funds are responding by centralizing compliance functions in Dublin and Luxembourg, concentrating regulatory technology vendor selection among established middleware providers.
Buyers are unbundling execution from clearing and collateral management, fragmenting service provider relationships that historically consolidated through prime brokerage arrangements. Pension funds and insurance companies now separately appoint swap execution facilities, clearing members, and tri-party agents, compressing bundled fee structures. This disintermediation is most visible in the United States, where CFTC swap dealer rules have eroded traditional prime broker dominance over credit derivatives workflows.
Credit Default Swap Market Segmentation
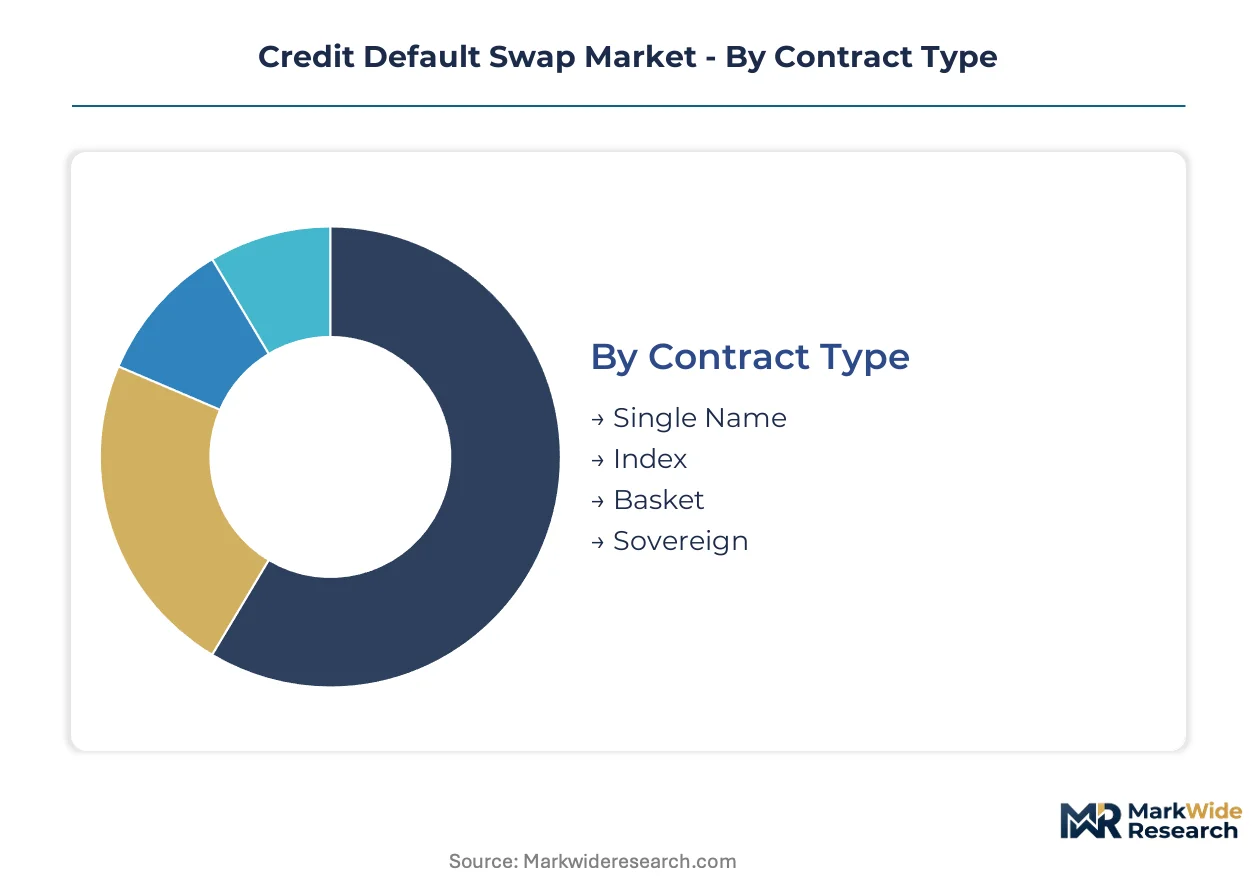
CDS segmentation reveals how contract design, participant motivation, and reference entity characteristics fragment liquidity across execution venues. Distinct buyer profiles drive divergent product preferences, from macro index positioning to bespoke single-name hedging.
Contract Type:
Cost tier differentiation separates standardized index products from premium-priced bespoke structures.
- Single Name:Bilateral contracts reference one specific obligor, offering precise counterparty risk transfer for loan portfolios. Corporate treasury desks in the United States concentrate demand here for supplier credit exposure management.
- Index:Multi-name baskets like CDX.IG and iTraxx Main enable efficient macro credit positioning through standardized terms. Hedge funds dominate trading velocity here, drawn by tight bid-ask spreads and deep CME and ICE clearing liquidity.
- Basket:Customized multi-obligor structures combine 5-10 reference entities for tailored sector exposure. Demand concentrates among insurance companies seeking granular risk selection.
- Sovereign:Contracts reference national government debt, with EMIR reporting friction suppressing European sovereign liquidity relative to corporate alternatives.
Single-name contracts command the established notional base. The steepest expansion runs through index products as central clearing mandates compress bilateral economics.
Buyer Type:
Application-driven segmentation maps protection demand to distinct portfolio functions and regulatory constraints.
- Institutional Investors:Pension funds and asset managers deploy CDS for duration-matched credit spread hedging against fixed-income holdings. UK liability-driven investment strategies amplify investment-grade single-name demand.
- Hedge Funds:Systematic credit funds exploit index basis trades and curve arbitrage through rapid position turnover. Machine learning-driven signal generation compresses latency between credit event detection and execution.
- Insurance Companies:Life insurers utilize long-dated single-name protection for counterparty exposure in private placement portfolios.
- Corporations:Non-financial firms purchase protection against key supplier or customer default, embedding CDS into supply chain risk frameworks.
Institutional investors anchor the current premium flow. The fastest volume gains are emerging through hedge fund systematic strategies.
Reference Entity Type:
Volume concentration varies sharply across obligor categories, with corporate issuers dominating cleared activity.
- Corporates:Investment-grade industrial and utility issuers populate CDX.IG, offering deep liquidity for macro positioning. North American obligor concentration limits diversification when sectoral credit cycles synchronize.
- Financials:Bank and insurance reference entities carry complex capital structure interactions between senior and subordinated debt. Basel III endgame capital charges reshape dealer willingness to warehouse financial sector exposure.
- Sovereigns:Government debt references span developed and emerging markets, with EMIR-SEC documentation divergence fragmenting European sovereign liquidity.
- Supranationals:Multilateral development banks and agency borrowers offer quasi-sovereign risk profiles with limited default history.
Corporate reference entities hold the dominant share of outstanding notional. Financials are gaining share fastest as bank resolution frameworks reshape subordinated debt risk pricing.
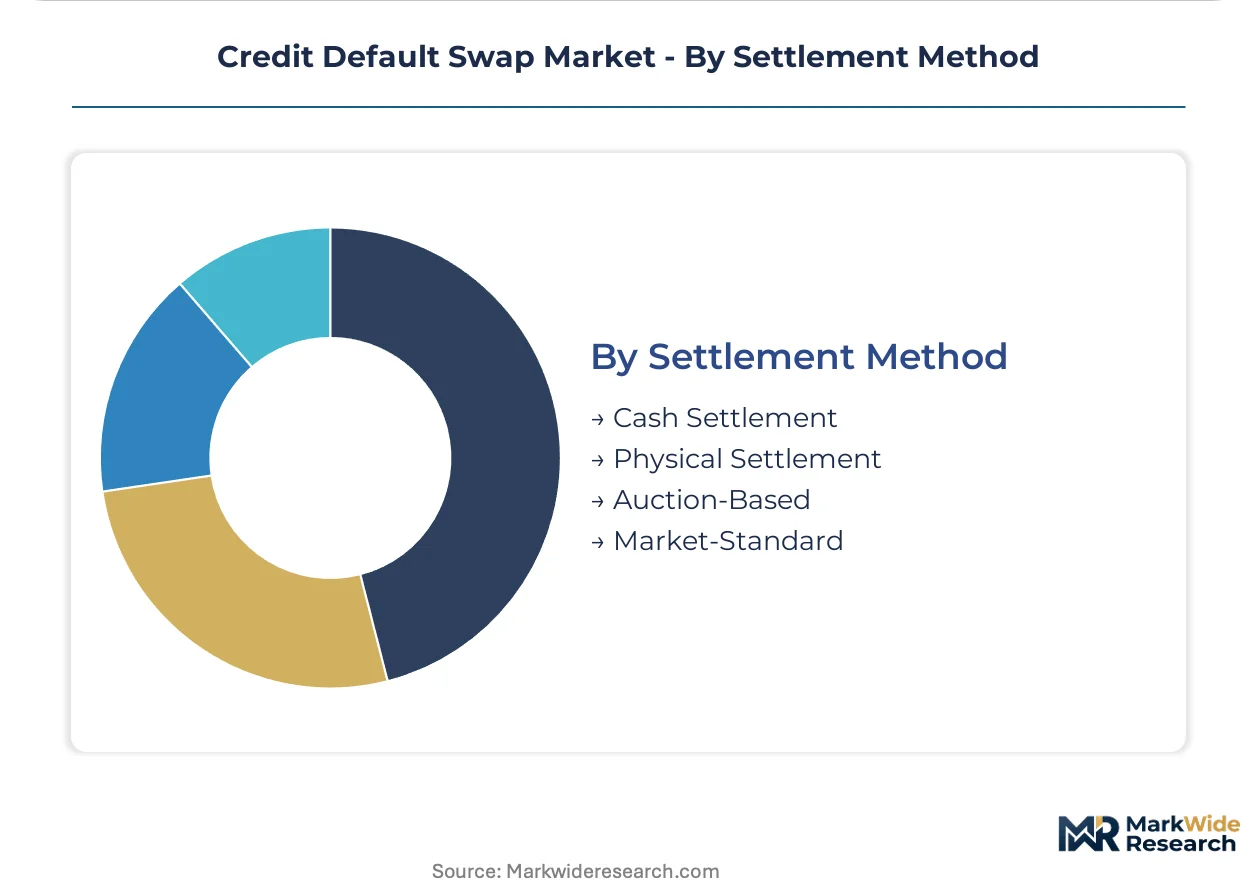
Settlement Method:
Maturity-stage differentiation separates legacy physical settlement from auction-based protocols now standard for index products.
- Cash Settlement:Fixed payments upon credit event avoid physical bond delivery, reducing operational complexity for index positions. CME and ICE clearinghouses mandate cash settlement for standardized contracts.
- Physical Settlement:Protection buyers deliver defaulted bonds for par, creating squeeze risk when deliverable supply concentrates. Single-name bilateral contracts retain physical settlement options for bespoke negotiation.
- Auction-Based:ISDA-administered credit event auctions establish recovery values through competitive bidding, now standard for CDX and iTraxx constituents.
- Market-Standard:Hybrid protocols combining auction recovery with cash top-up dominate recent index documentation.
Auction-based settlement commands index market practice. Cash settlement protocols are expanding most quickly as central clearing standardization progresses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in New York and London, where CME Group and ICE clearinghouses dictate margin terms and execution standards that regional venues in Singapore and Frankfurt must reference. Dealers in Asian financial centers absorb spread compression as they compete for flow back to these dominant clearing nodes.
United States
Pension funds and asset managers in Boston and New York drive demand for investment-grade single-name protection against corporate bond portfolios. The SEC enforces Dodd-Frank Title VII swap dealer registration and real-time reporting requirements. Chicago anchors central clearing infrastructure, with CME Group processing the majority of standardized index CDS compression.
United Kingdom
LDI strategies among UK pension schemes amplify demand for long-dated credit spread hedging against gilt and corporate holdings. The Bank of England oversees systemic risk in derivatives clearing through its financial stability mandate. London's Square Mile concentrates dealer sales desks and buy-side credit trading operations, sustaining deep liquidity in iTraxx Main execution.
Germany
Insurance companies in Munich and Frankfurt purchase bespoke basket structures for granular sector exposure selection. BaFin implements EMIR clearing obligations and margin rules for EU-domiciled entities. The Frankfurt trading cluster anchors European sovereign and financial reference entity pricing, with Deutsche Bank maintaining sales infrastructure there.
Japan
Regional banks and life insurers in Tokyo seek credit protection against concentrated domestic corporate lending exposures. The Financial Services Agency supervises derivatives trading and clearing member standards. The Tokyo financial district lacks liquid single-name markets for provincial government issuers, creating structural gaps that international dealers occasionally bridge.
Singapore
Wealth management platforms and family offices deploy CDS for tail risk hedging across Asia-Pacific fixed-income allocations. The Monetary Authority of Singapore regulates derivatives dealers and promotes the city-state as a regional booking center. The Marina Bay financial hub hosts regional sales coverage for Australian and Southeast Asian reference entities.
Credit Default Swap Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in origination and structuring. The market concentrates around global dealer banks with clearing membership and balance-sheet capacity, compressing margins for regional players without CME or ICE access. Three archetypes dominate: universal banks with corporate lending franchises, pure trading houses with quantitative infrastructure, and custody banks with collateral management specialization. Competitive moves center on prime brokerage unbundling and technology partnerships for real-time risk analytics.
Within the universal bank tier, Citigroup, Deutsche Bank, and JPMorgan Chase & Co. occupy positions defined by geographic origination strength and clearing infrastructure access. Citigroup represents the corporate lending-anchored archetype, Deutsche Bank exemplifies European sovereign and financial reference entity specialization, and JPMorgan Chase & Co. anchors index market-making through hybrid rates-credit desk integration.
| Leading Market Players |
|---|
| Citigroup |
| Deutsche Bank |
| JPMorgan Chase & Co. |
| UBS |
| BNP Paribas |
| Goldman Sachs Group |
| Barclays |
| HSBC |
| Morgan Stanley |
| Others |
Supply Flow & Price Mechanics
CME Group and ICE clearinghouse infrastructure concentration in Chicago and London anchors margin pool capture downstream, compressing regional dealer economics as liquidity gravitates toward central counterparties with balance-sheet scale.
Pricing Analysis
The customization-premium spread separates standardized index CDS from bespoke single-name structures. Three-tier pricing stratifies across cleared index products, uncleared bilateral contracts, and tailored basket structures, with hedge funds driving compression in the index tier through velocity-based execution. Pricing pressure stems from central clearing mandates elevating collateral velocity requirements, squeezing dealer warehousing economics. Asset managers exhibit highest price sensitivity for cleared index execution, while corporate treasuries absorb premium pricing for supplier-specific protection.
Supply Chain Analysis
Tri-party agent concentration at BNY Mellon, JPMorgan, and State Street dominates collateral mobility infrastructure. Geographic supply concentration centers on the United States, United Kingdom, and Germany for dealer sales desk coverage and clearing membership access. Raw material dependencies include high-grade sovereign bonds for initial margin, cash reserves for variation margin, and repo market liquidity for intraday funding. Single-source vulnerability runs through CME and ICE clearinghouse concentration. Distribution feeds from prime brokerage unbundling toward fragmented swap execution facility and tri-party agent relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Credit derivatives face substitution pressure from credit-linked notes and total return swaps that replicate synthetic exposure without ISDA documentation complexity, forcing incumbents to defend clearing infrastructure moats.
For Market Incumbents: Harden clearing membership advantages by deepening collateral velocity capabilities through tokenized margin infrastructure partnerships. Fortify index market-making positions against systematic credit fund entrants through hybrid rates-credit desk integration. Prioritize regulatory capital optimization expertise recruitment to maintain pricing precision for bespoke structures. For New Entrants and Emerging Players: Pursue Asia-Pacific sovereign and quasi-sovereign underpenetration, specifically Australian provincial government and Japanese regional issuer markets lacking liquid single-name coverage. Target ESG-screened index product development for EU SFDR Article 8 and 9 fund mandates as the most penetrable white space. Deploy regional sales coverage models anchored through Singapore booking centers. For Investors and Strategic Acquirers: Capital is best deployed toward custody banks with collateral management specialization and regulatory technology middleware providers consolidating EU trade repository compliance functions. Long-term viability rests on infrastructure capture rather than flow trading margins. Monitor CFTC-EMIR regulatory divergence resolution as the signal for clearinghouse concentration stability.| Strategic Initiative | Industry Significance |
|---|---|
| Clearing Infrastructure Investment | CME and ICE membership expansion captures margin pool concentration as uncleared activity migrates. |
| Regulatory Technology Acquisition | EMIR REFIT compliance middleware consolidation addresses fragmented trade repository reconciliation demand. |
| Tokenized Collateral Partnership | Distributed ledger integration with tri-party agents enables intraday margin velocity for cleared derivatives. |
| ESG Index Product Launch | SFDR Article 8 and 9 fund mandates create reference basket white space excluding carbon-intensive sectors. |
| Asia-Pacific Sales Expansion | Singapore and Tokyo coverage bridges structural gaps in Australian and Japanese provincial issuer markets. |
Methodological Framework
Initial hypotheses were tested against primary input from credit trading desk heads, collateral management officers, pension fund liability-driven investment strategists, and regulatory compliance leads at EU-domiciled asset managers and refined through secondary validation. Sources included DTCC trade repository disclosures, CFTC swap dealer registration filings, EMIR REFIT transaction reports, and central clearinghouse volume statistics. Bottom-up position data triangulated with top-down macro credit positioning estimates across the analysis window.
Demand-supply balance framing anchored the forecast framework, modeling contract type segmentation by single-name, index, basket, and sovereign structures alongside buyer type, reference entity category, and settlement method dimensions. CAGRs derived from historical notional outstanding trajectories, clearing mandate implementation timelines, and Basel III endgame capital charge phase-in schedules. Index trading velocity and collateral velocity served as industry-specific forecast inputs throughout the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in sovereign bond market stress episodes, central bank policy rate trajectories, or corporate default cycle synchronization would shift the trajectory. Forecasts reflect assumptions around regulatory implementation adherence and clearinghouse infrastructure stability. Quarterly review of CFTC-EMIR rule convergence progress, Treasury market liquidity indicators, and dealer balance sheet capacity metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Investment Analysis and Financial Strategies
Europe Mandatory Motor Third-Party Liability Insurance Market
Investment Analysis and Financial Strategies
Outdoor Payment Terminal Market
Investment Analysis and Financial Strategies
Global Compliance Management Software Market
Investment Analysis and Financial Strategies
Compliance As a Service Market
Investment Analysis and Financial Strategies
Canada POS Terminal Market
Investment Analysis and Financial Strategies
Disclosure Management Market
Investment Analysis and Financial Strategies
India Property & Casualty Insurance Market
Investment Analysis and Financial Strategies
United States Commercial Insurance Market
Investment Analysis and Financial Strategies
China Mortgage/Loan Brokers Market
Investment Analysis and Financial Strategies
Smart Wealth Management Market
Investment Analysis and Financial Strategies
Transaction Monitoring Market
Investment Analysis and Financial Strategies
Asia-Pacific Insurtech Market
Investment Analysis and Financial Strategies
Reverse Factoring Market
Investment Analysis and Financial Strategies
Global Financial Planning Software Market
Investment Analysis and Financial Strategies
Foreign Exchange Services Market
Investment Analysis and Financial Strategies
South Africa Forensic Accounting Market