
 Continuing Medical Education (CME) Market | 2026-2036
Continuing Medical Education (CME) Market Size, Share, and Industry Trends Forecast 2026-2036
Continuing Medical Education (CME) Market Intelligence
Maintenance of Certification (MOC) requirements from the American Board of Medical Specialties is bifurcating the competitive landscape into accredited and non-accredited content tiers. Harvard Medical School leverages its institutional brand to anchor premium live-course offerings. OasisLMS competes through specialized learning management infrastructure tailored to hospital system compliance tracking.
Continuing Medical Education comprises structured educational activities designed to maintain, develop, or increase knowledge, skills, and professional performance of healthcare providers, typically delivered through accredited formats meeting minimum contact-hour thresholds and subject to peer-review validation. Its primary commercial purpose is satisfying licensure renewal and board recertification obligations that gate clinical practice privileges. Online delivery mode leads in scalability and margin contribution, while hybrid formats represent the fastest-growing structural category as health systems blend asynchronous modules with live skills verification. Clinical guidelines content commands the deepest engagement from physicians facing quality-reporting thresholds.
The Accreditation Council for Continuing Medical Education (ACCME) and state medical boards including the Texas Medical Board and New York State Education Department jointly shape content standards, delivery format acceptability, and hour-counting methodologies that determine market access for providers. FDA guidance on off-label promotion further constrains pharmaceutical-sponsored programming, redirecting commercial investment toward independently accredited platforms. Stakeholders must monitor evolving state reciprocity agreements and emerging AI-generated content review protocols as the next determinants of competitive positioning.
Market Dynamics
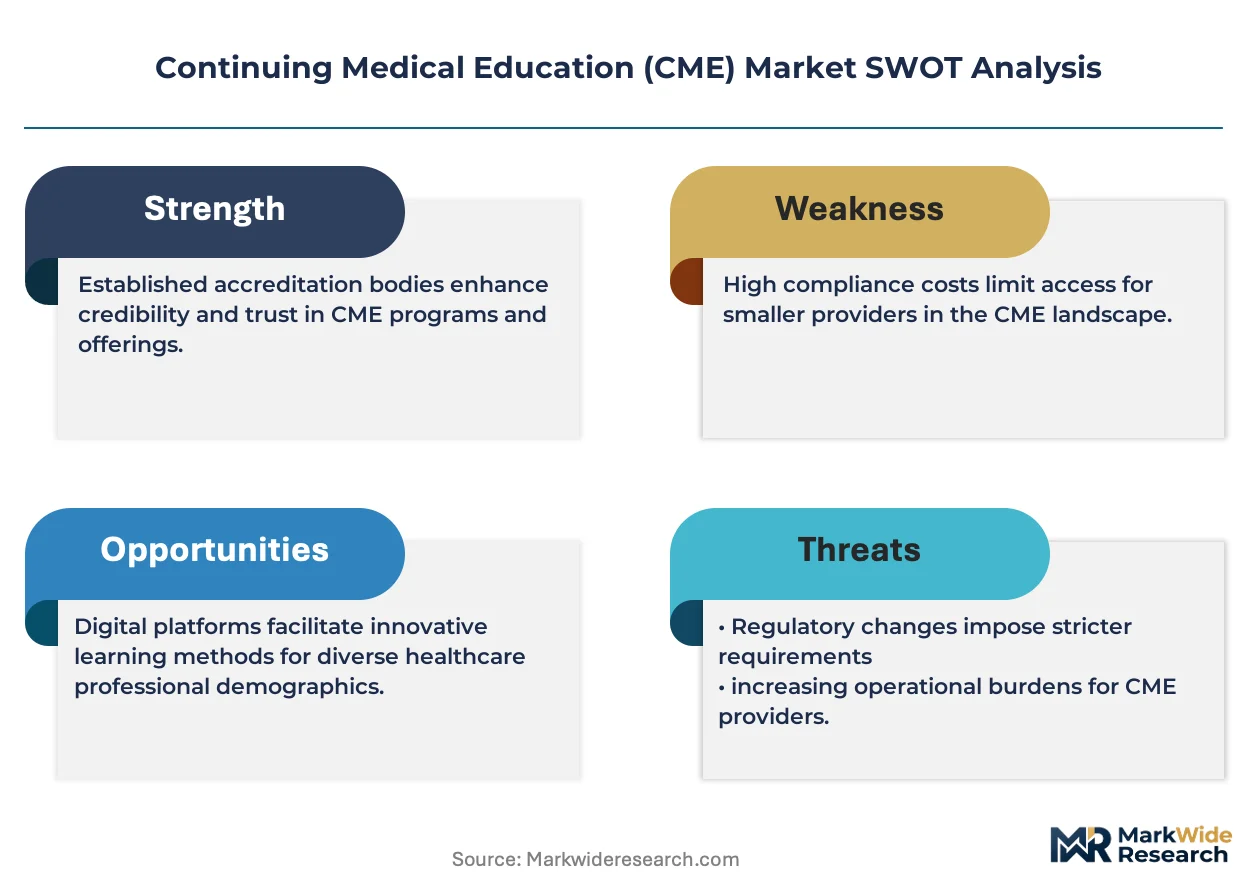
State medical boards are tightening hour-counting methodologies and reciprocity standards, forcing content providers to rebuild accreditation infrastructure around jurisdiction-specific compliance tracking rather than national portability.
Growth Catalysts
- Maintenance of Certification mandates:The American Board of Medical Specialties requires periodic knowledge assessments and practice improvement activities, creating recurring demand for structured CME modules that integrate MOC credit eligibility.
- Hospital system consolidation:Integrated delivery networks now mandate enterprise-wide CME tracking through unified learning management systems, concentrating procurement volume among platforms with multi-state accreditation coverage.
- Clinical quality reporting thresholds:Physicians face Medicare reimbursement penalties tied to performance metrics, driving enrollment in guideline-based CME that directly addresses quality measure gaps.
Market Restraints
- Accreditation cost escalation:The Accreditation Council for Continuing Medical Education imposes rising annual fees and activity reporting burdens that squeeze margins for smaller independent providers.
- Content development lag:Peer-review validation cycles for clinical guidelines content extend 8-14 months, creating inventory gaps when treatment protocols update faster than CME curricula refresh.
- Platform switching friction:Hospital IT departments lock learning management contracts into 3-5 year cycles, freezing out innovative delivery formats until renewal windows open.
Strategic Opportunities
- AI-generated content review protocols:The ACCME and state boards are drafting standards for machine-learning-assisted curriculum development, creating first-mover advantage for platforms that validate automated peer-review pipelines.
- Rural physician access gaps:Underserved counties in Texas, Mississippi, and Alaska lack live-course proximity, opening demand for synchronous virtual skills verification with proctored assessment.
- Interprofessional education mandates:Joint Commission requirements for team-based training create cross-licensure CME products serving physicians, nurse practitioners, and physician assistants through unified modules.
Industry Challenges
- Instructional design talent scarcity:Platforms compete for limited specialists who combine clinical subject expertise with adult learning pedagogy and ACCME outcome-documentation requirements.
- Legacy LMS integration complexity:Hospital systems running decade-old Oracle or Epic learning infrastructure resist API migrations, forcing content providers to maintain parallel delivery tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuing Medical Education (CME) Market |
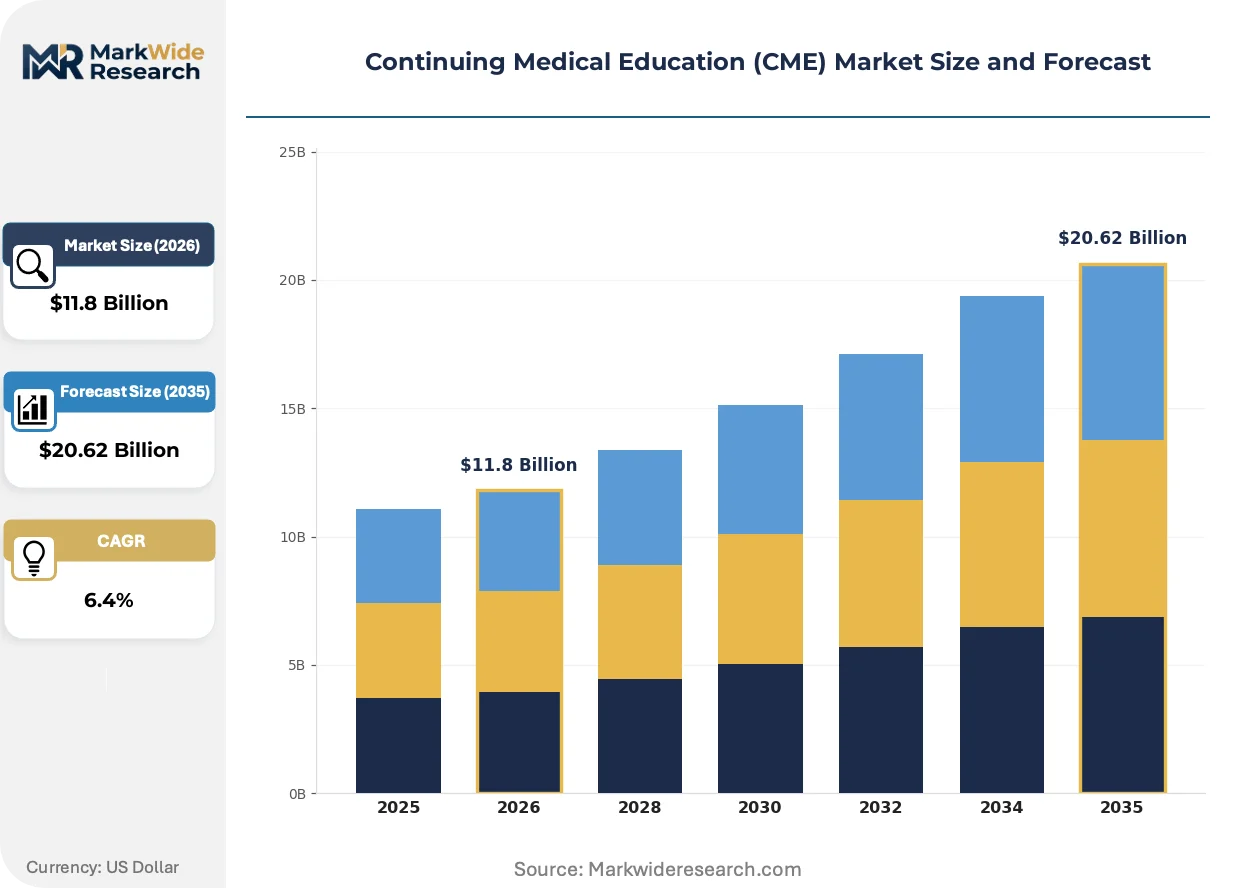
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Mode: Online, In-Person, Hybrid, Webinar Content Type: Clinical Guidelines, Case Studies, Interactive Modules, Workshops Healthcare Professional Type: Physicians, Nurses, Pharmacists, Allied Health Industry Vertical: Healthcare Providers, Pharmaceutical Companies, Medical Associations, Academic Institutions |
| Companies Covered | Continuing Education Company, ACEA, Harvard Medical School, Cengage/ed2go, Providence Health & Services, AudioDigest, OasisLMS, MOCingbird, American Academy of Family Physicians (AAFP), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuing Medical Education (CME) Market Strategic Shifts & Innovations
Adaptive learning algorithms are reshaping how physicians consume accredited content, replacing static module sequences with competency-driven pathways that compress time-to-credit while improving knowledge retention metrics.
Spaced repetition platforms leveraging granular performance analytics are supplanting traditional block-scheduled CME binges. Early adopters include academic medical centers and large multi-specialty groups seeking to distribute learning across clinical schedules. The technology compresses total contact-hour requirements by targeting individual knowledge gaps rather than uniform content exposure.
The FDA's 2023 guidance on independent medical education funding is tightening firewalls between pharmaceutical sponsors and accredited providers. Commercial supporters must now route grants through third-party intermediaries with no content influence. ACCME-accredited platforms serving oncology and cardiology verticals are restructuring sponsorship workflows to maintain revenue while documenting editorial independence.
Physicians are fragmenting their CME procurement across multiple channels rather than relying on single hospital-mandated catalogs. Individual practitioners now self-fund niche subspecialty modules from independent platforms while employers cover generalist requirements. This bifurcation is most pronounced in California and New York, where state-mandated topic requirements exceed employer-provided inventory depth.
Continuing Medical Education (CME) Market Segmentation
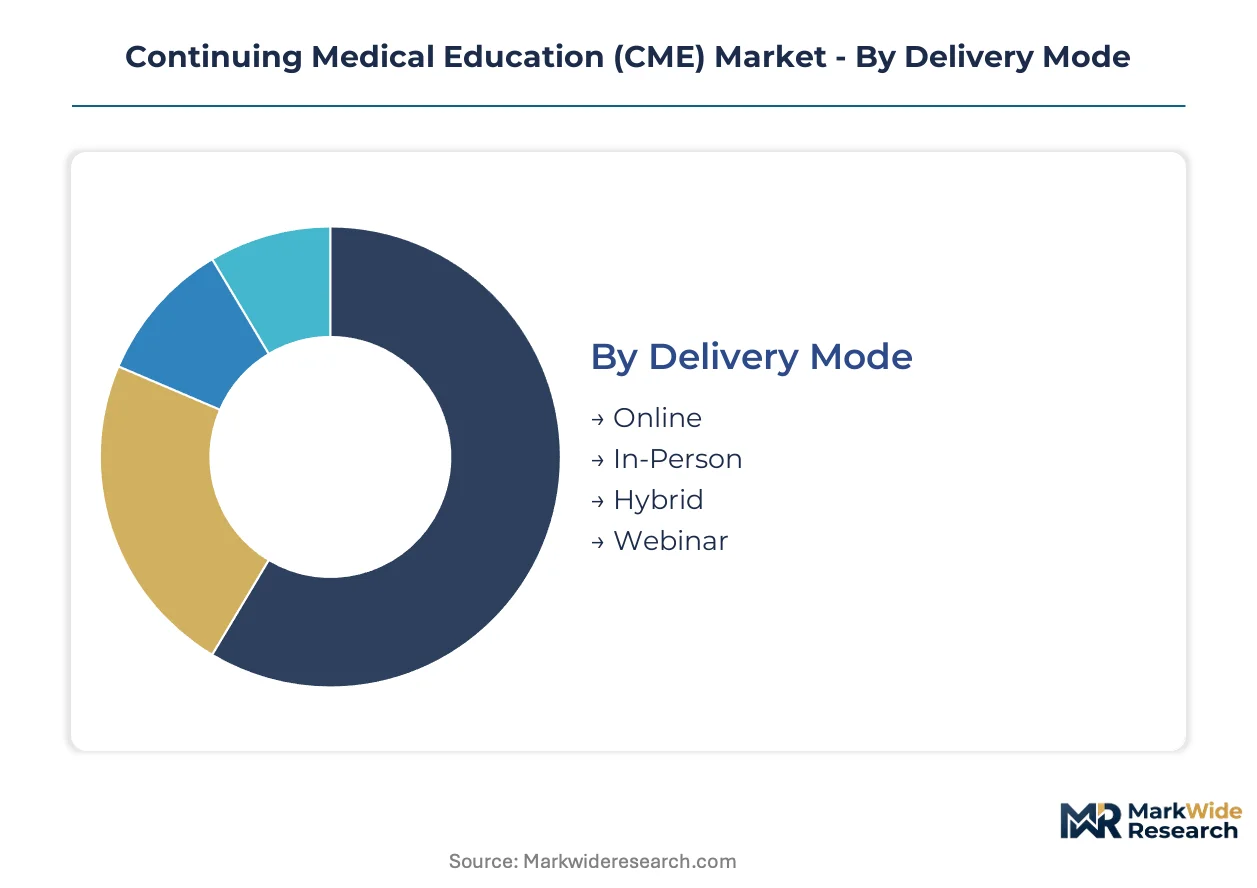
Segmentation in CME markets determines accreditation pathways, pricing tiers, and platform infrastructure requirements. Delivery mode selection directly shapes compliance tracking complexity for hospital systems managing multi-state licensure portfolios.
Delivery Mode:
Channel mix varies sharply by credentialing urgency and state reciprocity rules, with synchronous formats commanding premium positioning where live verification is mandated.
- Online:Asynchronous modules hosted on ACCME-accredited platforms enable self-paced completion across time zones. Hospital systems in Texas and Florida concentrate procurement here for generalist credit fulfillment, driven by 24/7 accessibility and automated compliance documentation.
- Hybrid:Blended formats combine asynchronous knowledge transfer with proctored skills validation sessions. Academic medical centers in California and New York are expanding hybrid catalogs fastest, constrained only by limited instructional design capacity for synchronized scheduling.
- In-Person:Live conference formats retain dominance for subspecialty networking and hands-on procedural training.
- Webinar:Synchronous virtual delivery supports urgent guideline updates without travel overhead.
By volume, Online leads. By growth pace, Hybrid is expanding most quickly.
Content Type:
Development cost tiers separate peer-reviewed clinical guidelines from rapidly deployable case study formats, with validation cycles determining margin structure.
- Clinical Guidelines:Evidence-based curricula undergo 8-14 month peer-review cycles per ACCME standards, embedding citation requirements from specialty society publications. Medicare quality-reporting thresholds in the United States drive concentrated demand from physicians facing reimbursement penalties.
- Interactive Modules:Adaptive learning algorithms with embedded assessment branching enable personalized knowledge gap targeting. Large multi-specialty groups in Illinois and Ohio prioritize these for Maintenance of Certification efficiency, though platform licensing fees strain smaller practice budgets.
- Case Studies:Scenario-based learning accelerates protocol adoption through anonymized patient narratives.
- Workshops:Skills-intensive formats dominate procedural specialties requiring hands-on verification.
By revenue contribution, Clinical Guidelines dominates. By adoption velocity, Interactive Modules is gaining share fastest.
Healthcare Professional Type:
Licensure renewal cycles and credit-hour thresholds create distinct procurement patterns across credential categories, with Joint Commission team-training mandates blurring traditional boundaries.
- Physicians:Board-certified specialists require MOC-eligible content meeting American Board of Medical Specialties specifications, with state medical boards enforcing topic-specific mandates in California, New York, and Massachusetts. Hospital credentialing departments track completion through unified LMS platforms.
- Nurses:Continuing education requirements vary by state board of nursing, with compact license holders seeking multi-jurisdiction portability. Health systems in Texas and Arizona are consolidating nurse CME procurement alongside physician programming for interprofessional education compliance.
- Pharmacists:Accreditation Council for Pharmacy Education standards govern content acceptance, with immunization certification driving seasonal demand spikes.
- Allied Health:Physical therapists, respiratory therapists, and medical technologists operate under fragmented state regulatory frameworks.
By spending concentration, Physicians leads. By procurement consolidation opportunity, Nurses shows the steepest expansion trajectory.
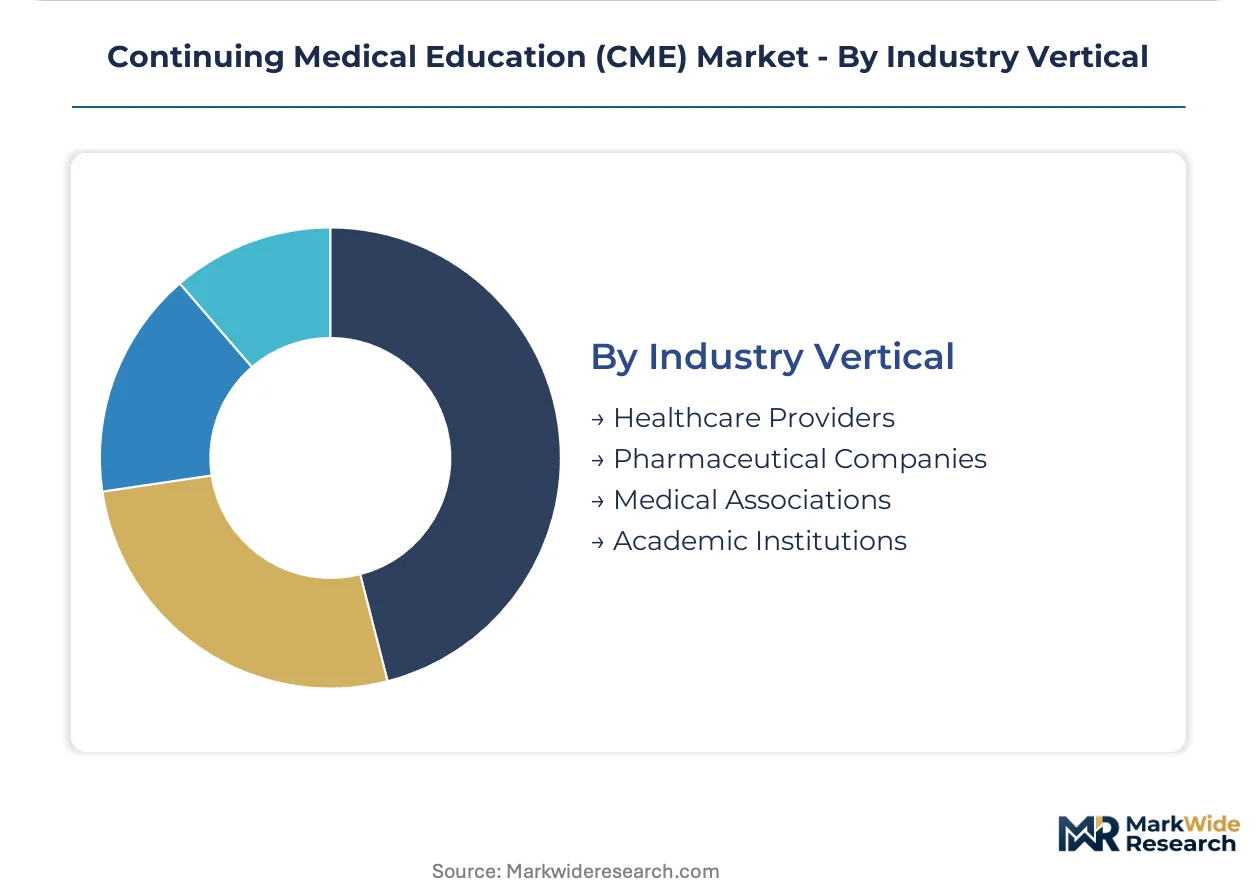
Industry Vertical:
End-user sophistication around accreditation compliance separates enterprise hospital systems from association-funded programming, with pharmaceutical sponsorship facing heightened FDA firewall requirements.
- Healthcare Providers:Integrated delivery networks mandate enterprise-wide CME tracking through unified learning management systems, concentrating volume among platforms with multi-state accreditation coverage. Hospital systems in Florida and Pennsylvania are locking 3-5 year LMS contracts that freeze competitive switching.
- Academic Institutions:Medical schools and teaching hospitals anchor premium live-course offerings through institutional brand leverage, with Harvard Medical School and similar entities commanding price premiums for specialty board review.
- Pharmaceutical Companies:Commercial supporters must route grants through third-party intermediaries with no content influence per FDA guidance, restructuring sponsorship workflows in oncology and cardiology verticals.
- Medical Associations:Specialty societies control guideline publication pipelines that feed accredited content development.
By contract value, Healthcare Providers dominates. By margin pressure, Pharmaceutical Companies faces the most acute regulatory constraint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State medical boards in the United States enforce the strictest continuing education mandates, while hospital system consolidation in Canada and emerging accreditation frameworks in Western Europe concentrate procurement among platforms with multi-jurisdiction compliance coverage.
United States
The Texas Medical Board and New York State Education Department enforce divergent hour-counting methodologies that fragment national portability. Maintenance of Certification requirements from the American Board of Medical Specialties create recurring demand for structured modules. Academic medical centers in California and Massachusetts anchor premium live-course offerings through institutional brand leverage.
Canada
Provincial regulatory colleges in Ontario and British Columbia coordinate continuing competency frameworks that align with U.S. reciprocity standards. Health Canada guidance on independent medical education shapes pharmaceutical sponsorship firewalls. Toronto and Vancouver hospital networks are consolidating procurement through unified learning management systems.
Germany
The German Medical Association's CME mandates concentrate demand in Bavaria and North Rhine-Westphalia. EMA-aligned accreditation standards enable cross-border curriculum recognition. Berlin-based academic medical centers are expanding English-language programming to capture international physician enrollment.
United Kingdom
The General Medical Council's revalidation requirements drive structured CME uptake across NHS trusts. GMC-approved providers in London and the Southeast command premium positioning for specialty board preparation. Royal College guidelines feed peer-review validation pipelines that extend content development cycles.
Australia
The Medical Board of Australia's continuing professional development standards mandate minimum hours across registration categories. TGA oversight of pharmaceutical-sponsored education redirects commercial investment toward independently accredited platforms. Melbourne and Sydney teaching hospitals are piloting hybrid delivery formats with proctored skills verification.
Continuing Medical Education (CME) Market Key Industry Players
Player mix skews toward institutional academic anchors and specialized learning management infrastructure providers. Market structure bifurcates into accredited content tiers governed by ACCME standards and non-accredited professional development programming. Two strategic archetypes dominate: heritage medical schools leveraging brand equity for premium pricing, and compliance-focused platforms embedding multi-state tracking tools. Competitive moves concentrate on accreditation infrastructure expansion and hospital system LMS integration partnerships.
Within the institutional anchor tier, Harvard Medical School exemplifies heritage academic positioning, while OasisLMS occupies a specialized infrastructure role in hospital compliance tracking. Among association-backed providers, the American Academy of Family Physicians represents the specialty society archetype that controls guideline publication pipelines feeding accredited content development. These three entities collectively illustrate the market's segmentation between brand-driven premium offerings and utility-driven compliance solutions.
| Leading Market Players |
|---|
| Continuing Education Company |
| ACEA |
| Harvard Medical School |
| Cengage/ed2go |
| Providence Health & Services |
| AudioDigest |
| OasisLMS |
| MOCingbird |
| American Academy of Family Physicians (AAFP) |
| Others |
Cost & Logistics Intelligence
Pharmaceutical grant intermediation replacing direct sponsor-provider contracting simultaneously redraws procurement geography toward third-party compliance hubs and compresses margin structures across content tiers. Hospital system LMS consolidation in Texas and Florida aggregates buyer power, forcing accredited platforms to absorb accreditation fee escalation or cede share to institutional anchors.
Pricing Analysis
Cost-plus contracts with ACCME annual fee indexation dominate enterprise procurement between hospital systems and multi-state accredited platforms. Three-tier pricing structure across premium live courses, standard asynchronous modules, and economy webinar formats separates Harvard Medical School's brand-premium positioning from OasisLMS's compliance-utility tier. Pricing pressure stems from instructional design talent scarcity elevating content development costs. Independent practitioners in California and New York show highest price sensitivity, while integrated delivery networks prioritize accreditation coverage over unit cost.
Supply Chain Analysis
ACCME peer-review validation bottlenecks in the United States constrain content throughput for clinical guidelines curricula. Content development draws from specialized instructional designers, clinical subject experts, and ACCME outcome documentation specialists. Single-source vulnerability concentrates in legacy Oracle and Epic LMS infrastructure that resists API migration. Distribution runs through hospital system procurement committees, GPO contracts, and direct platform licensing to academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection is concentrating procurement among unified learning management systems that embed multi-state compliance tracking, with interoperability mandates from Joint Commission team-training requirements accelerating ecosystem consolidation.
For Market Incumbents: Shield accreditation infrastructure investments by deepening proprietary peer-review validation pipelines ahead of AI-generated content protocol finalization. Fortify hospital system LMS integration partnerships to extend contract renewal cycles and freeze switching windows. Vertical integration into instructional design talent pools addresses the scarcest capability constraint. For New Entrants and Emerging Players: Rural physician access gaps in Texas, Mississippi, and Alaska represent the most penetrable white-space where live-course proximity constraints persist. Synchronous virtual skills verification with proctored assessment offers a direct go-to-market angle that bypasses incumbent platform switching friction. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors compliance-focused infrastructure platforms over content-only providers. Long-term viability hinges on embeddedness within hospital system procurement workflows. Watch AI-generated content review protocol finalization as the inflection signal that separates validated automation leaders from legacy peer-review dependents.| Strategic Initiative | Industry Significance |
|---|---|
| AI Content Review Pipeline Validation | ACCME protocol alignment secures first-mover positioning in automated peer-review accreditation. |
| Hospital System LMS Integration Partnership | Epic and Oracle infrastructure lock-in extends contract renewal cycles and freezes competitive switching. |
| Multi-State Accreditation Coverage Expansion | Texas Medical Board and New York State Education Department reciprocity enables national portability. |
| Rural Virtual Skills Verification Deployment | Proctored synchronous delivery captures underserved counties lacking live-course proximity. |
| Joint Commission Interprofessional Education Module Development | Team-based training mandates create cross-licensure products serving physicians and nurse practitioners. |
Research Approach
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in documented compliance frameworks. Conversations with ACCME accreditation officers, hospital CME directors, state medical board administrators, and pharmaceutical grants compliance officers combined with FDA guidance documents, ACCME annual reports, and hospital procurement database analysis. Bottom-up platform revenue triangulation against top-down market sizing validates segment-level estimates.
Sensitivity analysis across delivery mode, content type, healthcare professional category, and industry vertical dimensions shapes the analytical framework. CAGRs derive from accredited activity volume trends, hospital system consolidation patterns, and MOC mandate expansion trajectories. Modeling incorporates state reciprocity agreement evolution and AI content protocol development timelines across the projection horizon.
Material uncertainties — regulatory protocol shifts, hospital IT migration cycles, and pharmaceutical sponsorship firewall restructuring — sit outside the modeled envelope. Forecasts reflect assumptions about accreditation cost trajectories and instructional design capacity expansion. Practitioners should keep alternative scenarios live as AI-generated content review standards and state reciprocity frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare
Viral Conjunctivitis Pipeline Drugs Market
Healthcare
Drainage Bottles Market
Healthcare
Nephrogenic Systemic Fibrosis (NSF) Treatment Market
Healthcare
Acute Viral Rhinosinusitis Treatment Market
Healthcare
Assisted Walking Devices Market
Healthcare
Global Preventive Vaccines Market
Healthcare
Liquid Oxygen Devices Market
Healthcare
Mosquito-Borne Diseases Treatment Market
Healthcare
Netherlands Respiratory Devices Market
Healthcare
Spinal Implants and Devices Market
Healthcare
Cranial Implants Treatment Market
Healthcare
Idiopathic Hypersomnia (IH) Treatment Market
Healthcare
Europe Veterinary Antibiotics Market
Healthcare
Asia-Pacific Wearable Medical Devices Market
Healthcare
Bone and Joint Health Supplements Market
Healthcare
Culture Media Preparators Market