
 Composite Film Market | 2026-2036
Composite Film Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Film Market Analysis
Asset-light leasing models for coextrusion lines are reshaping competitive entry in composite film manufacturing. Toray Industries leverages captive polymer supply to sustain margin control across nylon and polypropylene film grades. Uflex anchors South Asian supply through integrated resin-to-roll operations. Avery Dennison Corporation differentiates via adhesive-coating specialization that extends film functionality into pressure-sensitive applications.
Composite film denotes engineered multilayer substrates combining polymers, metallized coatings, or biodegradable matrices through coextrusion or lamination, typically achieving thicknesses of 12-150 micrometers with tailored oxygen transmission rates below 0.1 cc/m²/day for barrier applications. These structures serve critical functions in shelf-life extension, electromagnetic shielding, and weight reduction across transport and consumer goods. Polypropylene films lead in food packaging margins due to clarity and sealability, while biodegradable material grades represent the fastest-expanding segment as EU packaging regulations harden. Nylon films occupy premium industrial and medical applications where puncture resistance and thermal stability command price premiums over standard polyethylene alternatives.
FDA food-contact substance notifications and EPA toxics release requirements govern US film composition and plant emissions, while REACH and the EU Green Deal's packaging waste directives are accelerating substitution toward biodegradable and recycled-content substrates in European markets. China's SAMR enforces GB standards for food-contact plastics that restrict specific additive chemistries in imported composite films. Stakeholders must monitor evolving extended producer responsibility frameworks and polymer recycling infrastructure buildout to align product portfolios with compliance timelines.
Market Dynamics
Coextrusion technology maturation is compressing barrier film thickness tolerances below 5 micrometers while EU F-Gas Regulation and REACH compliance force fluoropolymer substitution, creating simultaneous performance pressure and chemistry displacement across aerospace and packaging supply chains.
Growth Catalysts
- EU F-Gas Regulation phase-down:Hydrofluorocarbon restrictions are accelerating procurement of non-fluorinated high-barrier films for aerospace thermal management applications.
- China's electronics clusters:Shenzhen and Suzhou manufacturing corridors are expanding metallized film consumption for 5G electromagnetic shielding in smartphone and tablet assemblies.
- Coextrusion line leasing:Asset-light equipment financing is lowering entry barriers for mid-scale producers seeking multi-layer barrier capability without capital intensity.
Market Restraints
- Polypropylene resin volatility:Propylene feedstock price swings tied to naphtha cracking economics compress margin predictability for clarity-grade film producers.
- German automotive corridor concentration:OEM specification power in Stuttgart-Munich corridor limits supplier pricing leverage for interior trim and battery enclosure films.
- Biodegradable performance gap:PLA and PHA matrices currently fail oxygen transmission benchmarks below 0.5 cc/m²/day required for retort packaging.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic polymer film manufacturing incentives are attracting coextrusion investment for pharmaceutical blister packaging.
- Solventless adhesive lamination:UV-curing and hot-melt technologies are converging to eliminate VOC emissions while maintaining bond strength in high-barrier structures.
- Battery enclosure films:Electric vehicle thermal runaway protection is opening specification windows for ceramic-coated polyimide composites.
Industry Challenges
- Multi-layer delamination expertise:Coextrusion die design and interlayer adhesion chemistry require specialized process engineering talent scarce outside Japan and Germany.
- REACH SVHC compliance timelines:Substance of Very High Concern candidate list expansion forces 18-month reformulation cycles for adhesive and coating chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Film Market |
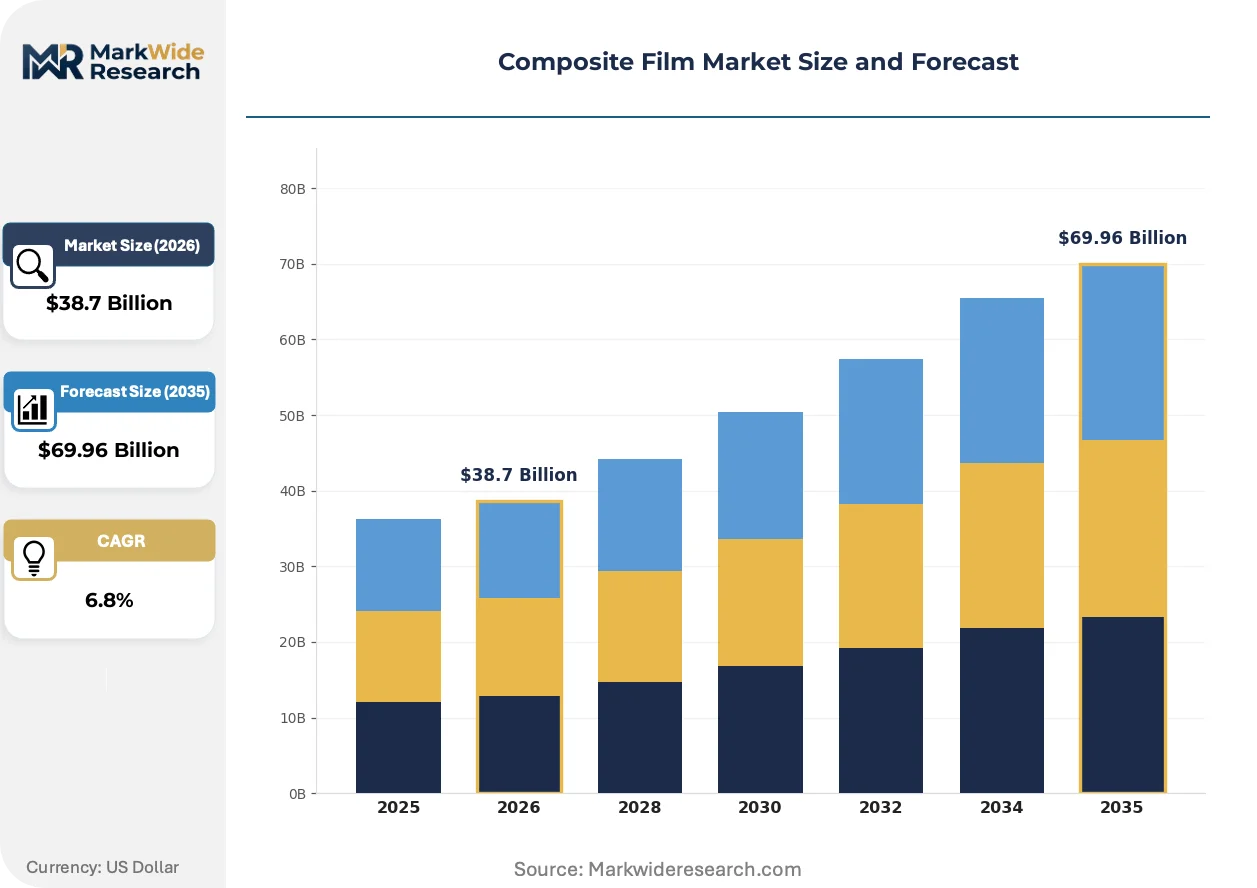
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Nylon, Others End User: Packaging, Automotive, Electronics, Aerospace Material: Plastic, Metalized, Biodegradable, Glass Application: Food, Medical, Industrial, Agricultural |
| Companies Covered | Jindal Films, Polyplex Corporation, Cosmo Films, Avery Dennison Corporation, 3M Company, Toray Industries, Taghleef Industries, DuPont, Uflex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Film Market Emerging Trajectories
Real-time thickness monitoring and machine-learning process control are digitizing quality assurance, while regulatory chemistry restrictions and circular economy mandates force material substitution at unprecedented velocity across barrier film portfolios.
Inline spectroscopic gauging combined with edge-compute feedback loops is digitizing micron-level thickness uniformity control. Aerospace OEMs in Toulouse and Hamburg are mandating digital batch records for traceability. This capability compression is eliminating manual sampling delays and reducing specification drift claims.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing fluoropolymer film reformulation across medical and industrial barrier applications. ECHA's 2023 PFAS restriction proposal covers over 10,000 substances. German chemical suppliers are accelerating silicon dioxide and aluminum oxide vapor-deposited alternatives.
Specification authority is consolidating at tier-one packaging converters with in-house metallization and lamination capability. Brand owners in France and the Netherlands are bypassing merchant film distributors for direct mill relationships. This channel compression is most visible in fresh protein and ready-meal packaging where shelf-life liability concentrates at the converter level.
Composite Film Market Segmentation
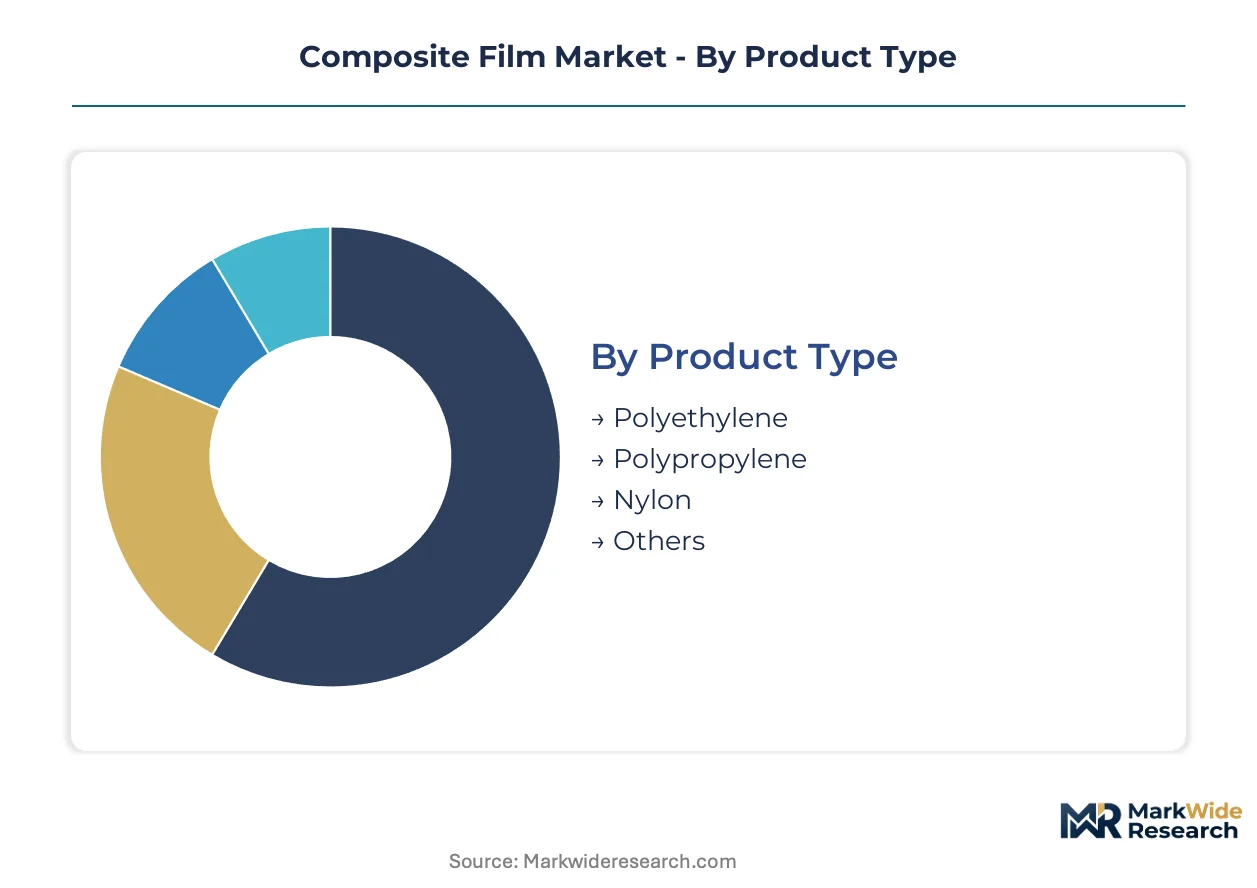
Composite film manufacturers align product portfolios against four intersecting dimensions: polymer chemistry, end-use performance requirements, substrate material class, and application-specific barrier specifications. Each segmentation axis carries distinct margin profiles and regulatory exposure.
Product Type:
Cost tier stratification across polymer families determines margin capture and capital intensity for coextrusion line operators.
- Polyethylene:Linear low-density and metallocene grades dominate volume production through blown film extrusion. Demand concentrates in medical sterile barrier systems where FDA 21 CFR compliance and gamma sterilization compatibility drive specification rigor.
- Polypropylene:Biaxially oriented structures achieve optical clarity below 20 micrometers with seal initiation temperatures optimized for high-speed form-fill-seal lines. Food packaging converters in Germany's Ruhr corridor specify cast PP for ready-meal lidding where hot-fill resistance commands premium pricing over polyethylene alternatives.
- Nylon:PA6 and PA66 coextrusions deliver puncture resistance and thermal stability for retort pouches and automotive under-hood applications.
- Others:Polyimide and fluoropolymer films serve aerospace thermal management despite REACH-driven chemistry substitution pressures.
Polypropylene commands the established base. The steepest expansion runs through biodegradable polymer formulations displacing conventional plastics under EU packaging waste directives.
End User:
Application maturity and specification authority vary sharply across customer industries, with packaging converters holding consolidated procurement power.
- Packaging:Flexible food and pharmaceutical formats absorb the majority of metallized and high-barrier coextrusion output. Extended producer responsibility frameworks in France and the Netherlands are forcing converters to specify recycled-content substrates.
- Automotive:Battery enclosure films and interior trim laminates require flame-retardant certification under ECE R118 and thermal runaway containment specifications from Stuttgart-Munich OEMs.
- Electronics:Metallized PET and PEN films provide electromagnetic interference shielding for 5G smartphone assemblies in Shenzhen manufacturing clusters.
- Aerospace:Polyimide and fluoropolymer composites face F-Gas Regulation phase-down pressures driving substitution toward ceramic-coated alternatives for thermal management.
Packaging maintains volume dominance. Electronics is climbing the fastest as 5G device proliferation accelerates metallized film consumption.
Material:
Substrate class selection determines barrier performance ceiling, end-of-life pathway, and regulatory compliance burden.
- Plastic:Multilayer coextrusions combining polyolefins, nylons, and EVOH achieve oxygen transmission rates below 0.1 cc/m²/day for shelf-life extension.
- Metalized:Aluminum oxide and silicon dioxide vapor-deposited layers provide transparent barrier alternatives to metallization, with German chemical suppliers accelerating non-fluorinated deposition chemistry development.
- Biodegradable:PLA and PHA matrices currently fail oxygen transmission benchmarks below 0.5 cc/m²/day required for retort packaging, limiting penetration to fresh produce and dry goods formats.
- Glass:Thin glass laminates serve specialized pharmaceutical and electronics applications where dimensional stability and hermetic sealing outweigh flexibility requirements.
Plastic substrates retain the installed base. Biodegradable materials are gaining share fastest as EU Green Deal packaging mandates harden substitution timelines.
Application:
Performance specification intensity and regulatory scrutiny intensify from agricultural through medical end-uses.
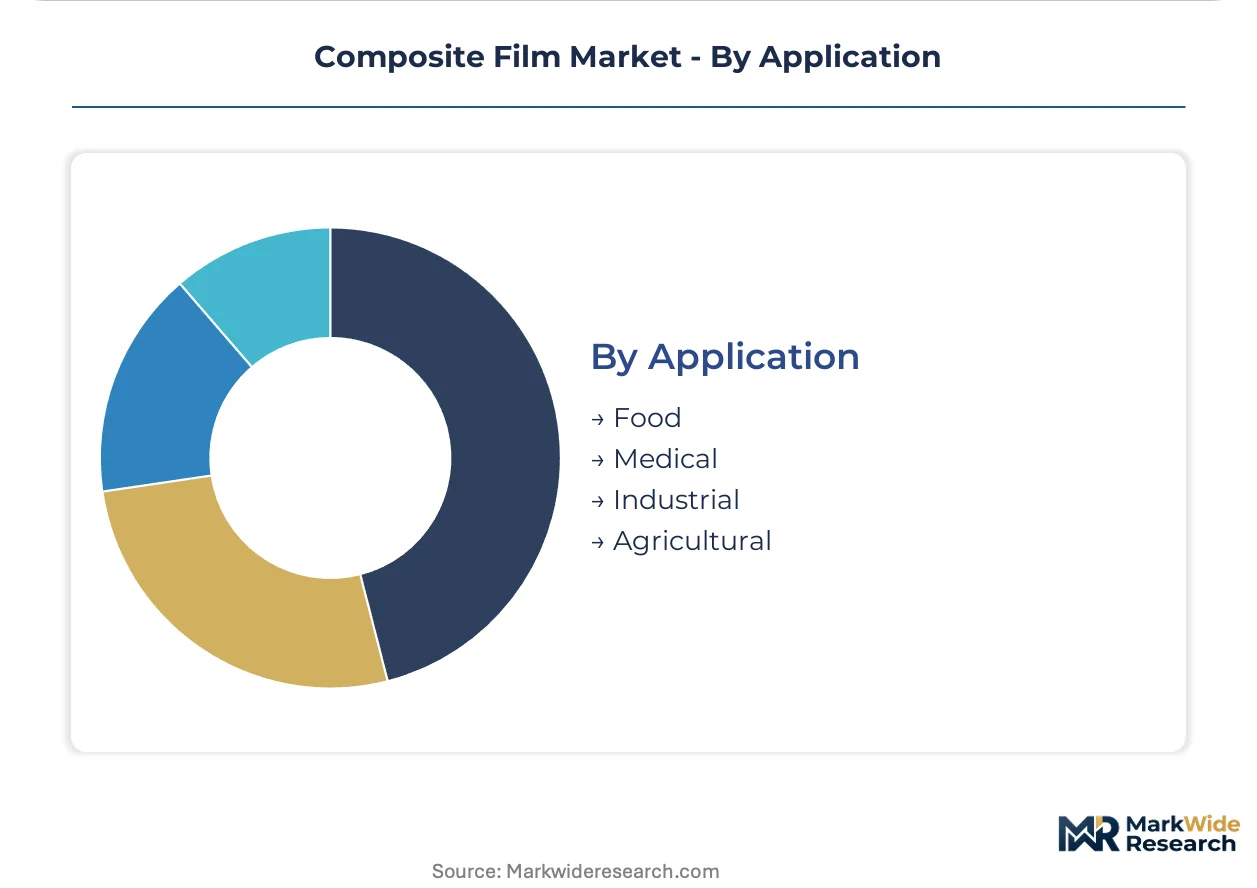
- Food:Modified atmosphere packaging and vacuum skin formats demand tailored oxygen and moisture barriers across fresh protein, dairy, and ready-meal segments. Brand owners in France are bypassing distributors for direct mill relationships to manage shelf-life liability.
- Medical:Sterile barrier systems for devices and pharmaceutical blisters require compliance with FDA 21 CFR, EU MDR, and ISO 11607 validation protocols.
- Industrial:Protective films and release liners serve manufacturing processes where silicone coating adhesion and die-cutting compatibility determine specification.
- Agricultural:Mulch films and greenhouse covers prioritize UV stabilization and mechanical durability over barrier performance, with biodegradable alternatives addressing soil contamination concerns.
Food applications anchor volume demand. Medical is expanding most quickly as sterile barrier complexity and regulatory validation requirements deepen supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation phase-down and India's PLI scheme for specialty chemicals are redirecting composite film investment toward non-fluorinated barrier technologies and domestic pharmaceutical packaging capacity. Germany's automotive corridor and China's electronics clusters anchor regional demand concentration.
United States
Aerospace OEMs in Seattle and Wichita are expanding procurement of ceramic-coated polyimide composites for thermal management applications. FDA 21 CFR food-contact substance notifications and EPA toxics release requirements govern film composition and plant emissions. The Southeast manufacturing belt is attracting coextrusion investment for medical sterile barrier systems.
Germany
OEM specification power in the Stuttgart-Munich automotive corridor drives demand for battery enclosure films and interior trim laminates. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing fluoropolymer film reformulation. The Ruhr corridor's food packaging converters specify cast polypropylene for ready-meal lidding where hot-fill resistance commands premium pricing.
China
Shenzhen and Suzhou manufacturing corridors are expanding metallized film consumption for 5G electromagnetic shielding in smartphone and tablet assemblies. SAMR enforces GB standards for food-contact plastics that restrict specific additive chemistries in imported composite films. Yangtze River Delta chemical suppliers are accelerating silicon dioxide vapor-deposited alternatives to fluoropolymer barriers.
India
Domestic polymer film manufacturing incentives under the PLI scheme are attracting coextrusion investment for pharmaceutical blister packaging. BIS standards and CDSCO regulations govern medical device packaging validation. Maharashtra and Gujarat are emerging as integrated resin-to-roll production hubs serving South Asian export markets.
Japan
METI industrial policy supports advanced coextrusion die design and interlayer adhesion chemistry development. JIS standards and PMDA regulations shape pharmaceutical and medical film specifications. The Chubu region around Nagoya maintains concentrated expertise in multi-layer delamination process engineering.
Composite Film Market Vendor Landscape
On the supply side, the industry is consolidating around integrated resin-to-roll operators and adhesive-coating specialists with in-house metallization capability. Three strategic archetypes dominate: captive polymer suppliers leveraging backward integration into film extrusion, merchant converters with direct brand owner relationships, and equipment-leasing platforms enabling asset-light market entry. Dominant competitive moves include solventless adhesive lamination technology licensing and geographic expansion through coextrusion line leasing partnerships.
Among Asia-Pacific integrated producers, Toray Industries and Uflex exemplify the captive supply archetype, while Avery Dennison Corporation occupies a position among adhesive-coating specialists extending film functionality into pressure-sensitive applications. These three companies represent distinct competitive vectors—polymer backward integration, regional supply anchoring, and functional coating specialization—that define the industry's strategic segmentation.
| Leading Market Players |
|---|
| Jindal Films |
| Polyplex Corporation |
| Cosmo Films |
| Avery Dennison Corporation |
| 3M Company |
| Toray Industries |
| Taghleef Industries |
| DuPont |
| Uflex |
| Others |
Supply Flow & Price Mechanics
The Ruhr corridor's cast polypropylene capacity concentration grants German converters leverage over lidding film pricing for ready-meal applications. Downstream brand owners in France and the Netherlands are consolidating procurement power through direct mill relationships, compressing distributor margins and forcing specification transparency.
Pricing Analysis
Certification level creates the primary spread across the market, with FDA 21 CFR and EU MDR compliance tiers commanding substantial premiums over standard industrial grades. Three-tier pricing structure across premium, standard, and economy levels reflects oxygen transmission performance, with sub-0.1 cc/m²/day barrier films capturing the top tier. Cost compression in clarity-grade polypropylene is intensifying because propylene feedstock volatility tied to naphtha cracking economics erodes margin predictability. Small-scale regional converters exhibit the highest price sensitivity, while aerospace OEMs in Toulouse and Hamburg prioritize performance over unit cost.
Supply Chain Analysis
Coextrusion contract manufacturing concentrates among German and Japanese equipment operators with specialized die design expertise. Supply draws from Germany, China, and Japan for multilayer film production, with resin supply anchored in Saudi Arabia, South Korea, and the US Gulf Coast for polypropylene and nylon feedstocks. Single-source vulnerability in ceramic-coated polyimide substrates for battery enclosure films presents structural risk as electric vehicle demand accelerates. Distribution runs through tier-one packaging converters with in-house metallization capability, bypassing traditional merchant film distributors in fresh protein and ready-meal segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite film markets are approaching a platform-economics inflection as digital batch records and real-time thickness monitoring create interoperability standards that favor integrated operators over fragmented merchant converters.
For Market Incumbents: Insulate margin position through captive polymer supply and solventless adhesive lamination technology licensing. Toray Industries exemplifies backward integration into nylon and polypropylene resin production that sustains cost control across film grades. Coextrusion line leasing partnerships in India and Southeast Asia defend against asset-light entrants while expanding geographic footprint without capital intensity. For New Entrants and Emerging Players: Mid-scale pharmaceutical blister packaging producers in India represent the most penetrable entry point under the PLI scheme's domestic manufacturing incentives. Solventless lamination capability for VOC-compliant high-barrier structures offers differentiation against incumbent fluoropolymer-dependent portfolios. Target coextrusion equipment financing partnerships rather than outright capacity purchases to preserve capital flexibility. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because REACH SVHC compliance timelines and EU F-Gas phase-downs are forcing 18-month reformulation cycles that favor acquirers with in-house adhesion chemistry expertise. Acquisition targets should display integrated resin-to-roll operations or specialized coating capabilities extending film functionality into pressure-sensitive applications. Watch for ceramic-coated polyimide qualification wins with Stuttgart-Munich automotive OEMs as inflection signals for battery enclosure film substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Solventless Adhesive Lamination Licensing | UV-curing and hot-melt technologies eliminate VOC emissions while maintaining bond strength in high-barrier structures. |
| Coextrusion Line Leasing Partnerships | Asset-light equipment financing lowers entry barriers for mid-scale producers seeking multi-layer barrier capability. |
| Ceramic-Coated Polyimide Development | Electric vehicle thermal runaway protection opens specification windows with Stuttgart-Munich automotive OEMs. |
| Backward Integration into Polymer Supply | Captive resin production sustains margin control across nylon and polypropylene film grades. |
| Digital Batch Record Implementation | Aerospace OEMs in Toulouse and Hamburg mandate traceability systems that eliminate manual sampling delays. |
Methodological Framework
A spread of perspectives from coextrusion plant managers, packaging converter procurement leads, aerospace OEM specification engineers, and pharmaceutical regulatory affairs directors converged on the working assumptions for this analysis. Primary fieldwork combined with secondary validation from customs and trade data, SEC 10-K filings, and ECHA regulatory submissions established the baseline. Bottom-up segment sizing and top-down macroeconomic cross-checks triangulated volume and value estimates.
Demand-supply balance dynamics across polymer chemistry, end-use performance requirements, and application-specific barrier specifications anchored the analytical framework. Segmentation dimensions modeled include product type, end user industry, substrate material class, and geographic production hub. CAGRs were derived from regression analysis against historical capacity additions and regulatory compliance cost trajectories. Feedstock price volatility indices and extended producer responsibility framework implementation timelines served as industry-specific forecast inputs.
Practitioners should monitor REACH SVHC candidate list expansions, EU F-Gas Regulation phase-down schedules, and ceramic-coated polyimide qualification milestones for early signals of chemistry substitution acceleration. Forecasts reflect assumptions about coextrusion technology maturation and biodegradable polymer performance gap closure. Quarterly review of propylene feedstock spreads, OEM battery enclosure specifications, and PLI scheme disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals & Materials
Aromatic Ketone Polymer Market
Chemicals & Materials
Fosfomycin Trometamol Powder Market
Chemicals & Materials
Acrylic Colors Market
Chemicals & Materials
Sodium Sulphate Market
Chemicals & Materials
Phenothiazine Market
Chemicals & Materials
Thermoplastic Polyolefin Membranes Market
Chemicals & Materials
FKM Elastomers Market
Chemicals & Materials
Glycolide Polymers Market
Chemicals & Materials
North America Potassium Formate Market
Chemicals & Materials
Africa Collagen Market
Chemicals & Materials
Polysiloxane Coatings Market
Chemicals & Materials
Coating Agents for Synthetic Leather Market
Chemicals & Materials
Composite Pipes Market
Chemicals & Materials
Fiber Reinforced Plastic (FRP) Panels and Sheets Market
Chemicals & Materials
Terephthalic Aldehyde Market
Chemicals & Materials
Synthetic and Bio Emulsion Polymers Market