
 Cognitive Assessment and Training Market | 2026-2036
Cognitive Assessment and Training Market Size, Share, and Industry Trends Forecast 2026-2036
Cognitive Assessment and Training Market Intelligence
The capital-intensity divergence between cloud-native platforms and hardware-dependent assessment suites is bifurcating competitive dynamics across the sector. Cambridge Cognition Ltd anchors its position through regulated clinical trial endpoints that command premium pricing in pharmaceutical research. CogniFit Inc leverages direct-to-consumer channels to sustain recurring revenue from brain fitness subscribers. Cogstate Ltd dominates specialized neuropsychological testing for sports concussion protocols, a niche with high switching costs.
Cognitive assessment and training encompasses standardized protocols, adaptive algorithms, and neuropsychological instruments designed to measure, monitor, and improve mental functions including memory, attention, and executive processing. These systems employ reaction-time thresholds, normative databases, and machine-learning personalization to deliver quantified cognitive profiles for clinical, educational, and occupational applications. Software Platforms and Mobile Applications capture the dominant share of investment as SaaS delivery models reduce per-assessment marginal costs and accelerate deployment across Educational Institutions. Virtual Reality Modules represent the fastest-expanding product category, with immersive environments enabling ecologically valid assessments that flat-screen tools cannot replicate for Executive Function Improvement protocols.
FDA digital health pre-certification and HIPAA security standards govern product design for US clinical deployments, while EMA medical device classification under the EU MDR determines market access timelines for European neurology clinics. ISO 13485 quality management and IEC 62304 software lifecycle standards further constrain development processes for regulated cognitive tools. Stakeholders must monitor evolving FDA software-as-medical-device determinations and corresponding CE marking transitions under MDR amendments to anticipate which product categories face heightened compliance burdens versus streamlined pathways.
Market Dynamics
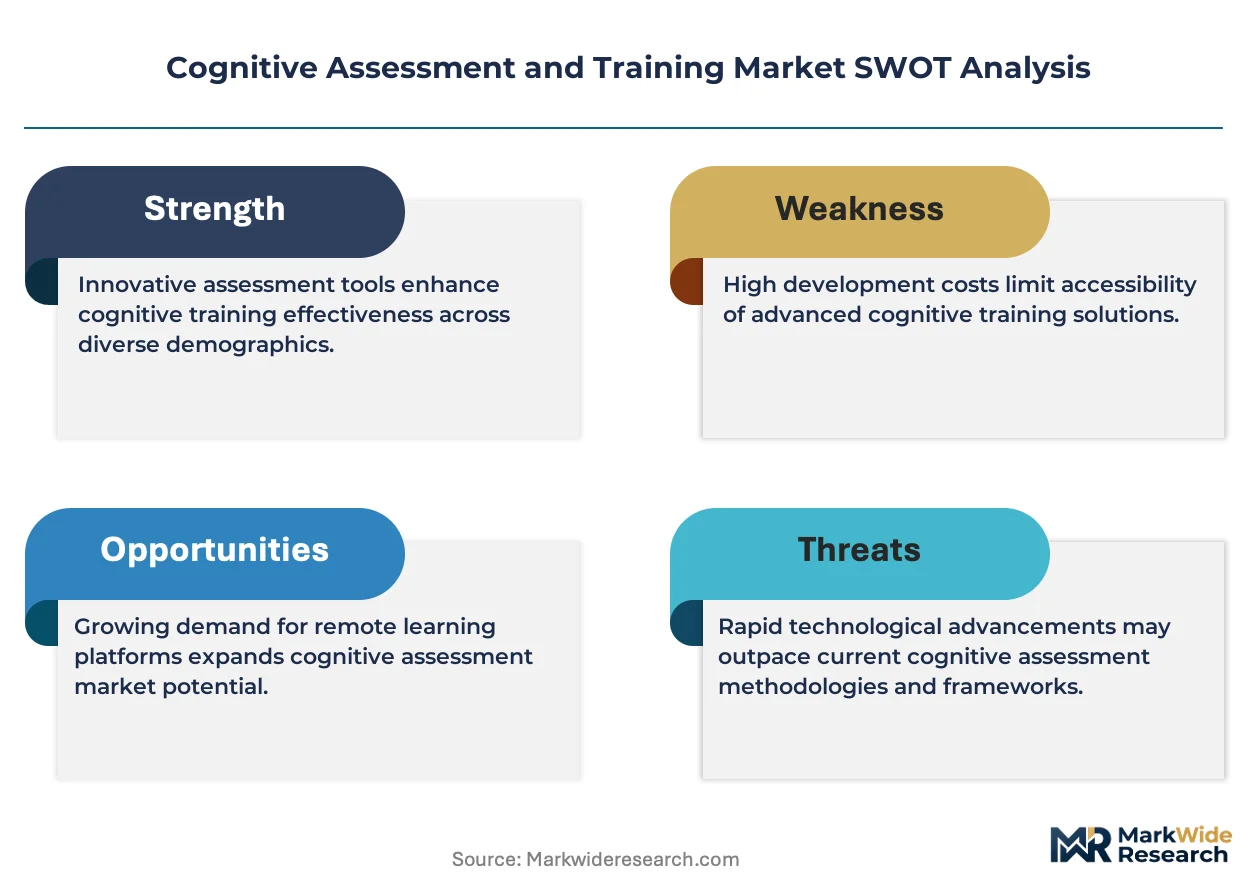
Cloud-native delivery architectures are fragmenting competitive moats that hardware-dependent assessment suites once defended, forcing incumbents to rebuild value propositions around data network effects rather than instrument lock-in.
Growth Catalysts
- FDA Pre-Certification Pilot:Streamlined software-as-medical-device pathways accelerate deployment timelines for neurology clinics seeking reimbursable cognitive endpoints.
- Japan's Super-Aged Society:METI-funded dementia prevention programs expand institutional procurement of memory training platforms across municipal health centers.
- Adaptive Algorithm Personalization:Machine learning models that adjust task difficulty in real time improve engagement retention in educational deployments.
Market Restraints
- EU MDR Classification Delays:CE marking timelines under amended medical device regulations extend market access by 18-24 months for European neurology software vendors.
- Semiconductor Supply Concentration:VR headset processors sourced from Taiwan and South Korea expose hardware-dependent assessment platforms to allocation volatility.
- Clinical Validation Burden:Normative database construction requires multi-site trials that consume 40-60% of early-stage R&D budgets.
Strategic Opportunities
- Germany's Digital Care Act:Reimbursement codes for digital health applications create a direct payment pathway for prescribed cognitive training in statutory insurance.
- Occupational Concussion Protocols:Sports leagues and logistics employers are adopting baseline testing mandates that expand enterprise subscription volumes.
- VR-Eye Tracking Convergence:Integrated gaze analytics enable attention assessment without verbal response, opening access to aphasic and pediatric populations.
Industry Challenges
- Neuropsychologist Talent Scarcity:Protocol design and norm validation require specialized expertise that outpaces graduate program output in the United States and Germany.
- HIPAA Technical Safeguards:Encryption and access control implementations for cloud platforms demand security engineering headcount that strains mid-cap development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cognitive Assessment and Training Market |
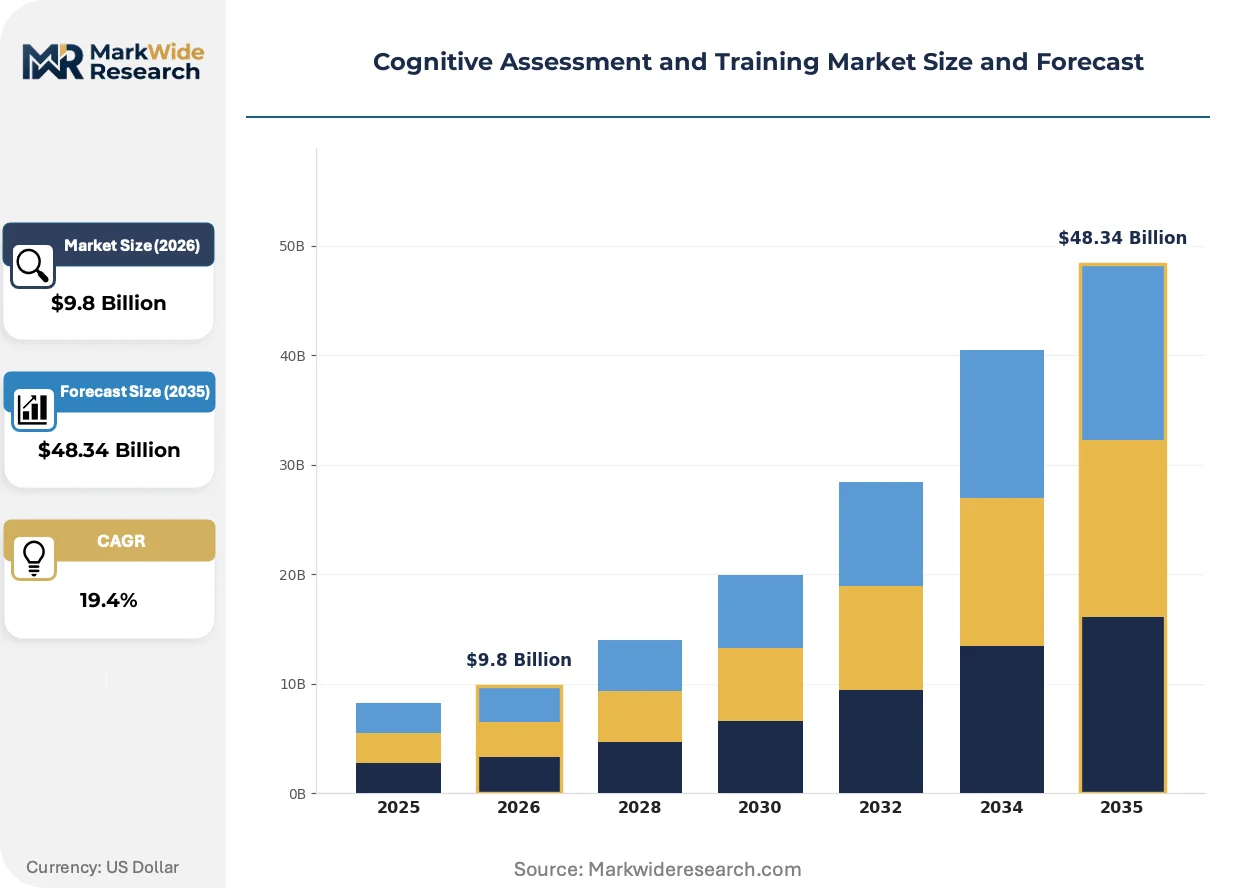
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $48.34 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
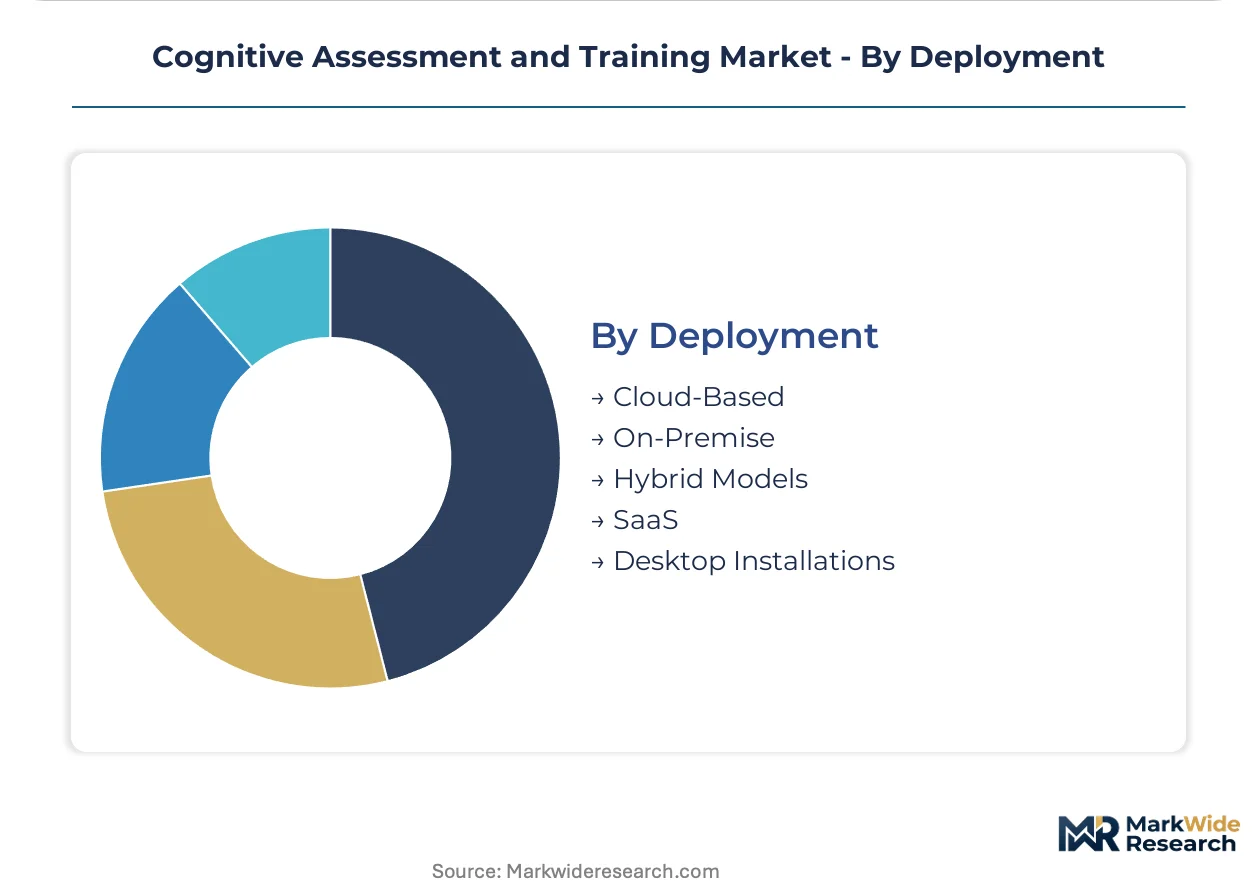
| Segmentation | Product Type: Software Platforms, Mobile Applications, Customized Solutions, Web-Based Tools, Virtual Reality Modules Application: Memory Enhancement, Attention Training, Executive Function Improvement, Problem Solving Skills, Language Development End User: Neurology Clinics, Educational Institutions, Geriatric Care Centers, Rehabilitation Facilities, Research Organizations Deployment: Cloud-Based, On-Premise, Hybrid Models, SaaS, Desktop Installations |
| Companies Covered | Cambridge Cognition Ltd, CogniFit Inc, Cogstate Ltd, Pearson Clinical Assessment Group, BrainCheck, Inc., Cognetivity Neurosciences, Lumos Labs, Inc., Posit Science, Signant Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cognitive Assessment and Training Market Strategic Shifts & Innovations
Immersive assessment modalities and algorithmic personalization are compressing the gap between laboratory precision and real-world cognitive measurement, redefining what constitutes a valid clinical endpoint.
Virtual reality environments with embedded eye-tracking sensors are decomposing the monopoly of traditional paper-and-pencil neuropsychological batteries. Neurology departments in the United States and Japan are piloting these systems for executive function assessment. The technology is decomposing the historical trade-off between ecological validity and measurement standardization that has constrained flat-screen digital tools.
The EU AI Act's risk classification framework is reclassifying adaptive cognitive training algorithms as high-risk systems requiring conformity assessment. Developers must now document training data provenance and algorithmic explainability for CE marking. German and French neurology clinics are delaying procurement decisions until vendor compliance certifications are published.
Employer-sponsored brain fitness subscriptions are displacing individual consumer purchases as the dominant revenue channel for direct-to-access platforms. Corporate wellness departments in the United States and Japan negotiate enterprise licenses that bundle assessment access with productivity analytics. This shift concentrates buyer power and compresses price points for standardized cognitive training modules.
Cognitive Assessment and Training Market Segmentation
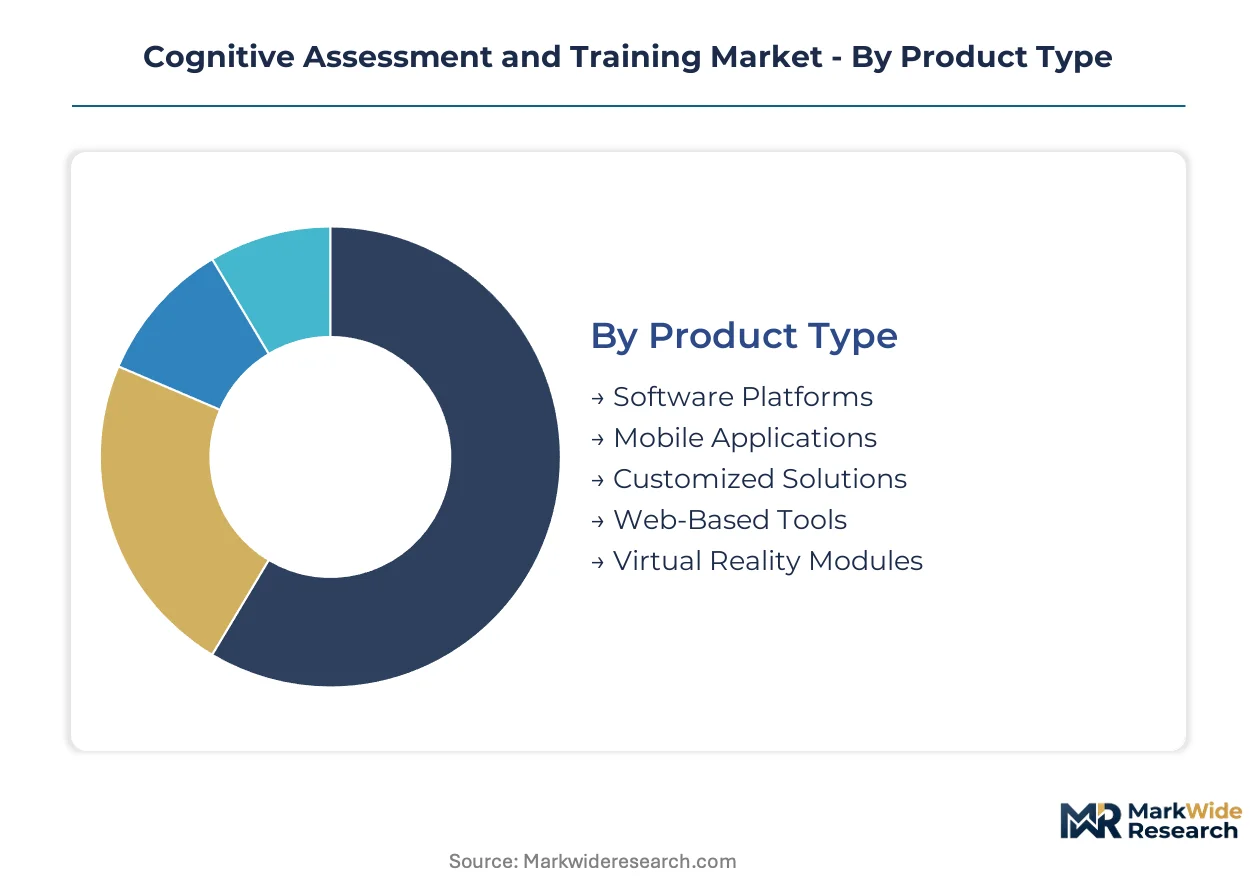
Segmentation in cognitive assessment and training reveals how regulatory pathways, reimbursement structures, and clinical validation requirements reshape competitive positioning across delivery models and end-use environments. Understanding these divisions exposes where capital efficiency concentrates and where compliance burdens create defensive moats.
Product Type:
FDA software-as-medical-device determinations and EU MDR classification timelines differentiate commercial trajectories across hardware-dependent and cloud-native delivery formats.
- Software Platforms:Enterprise-grade systems with HIPAA-compliant architecture and ISO 13485 quality management certification. Neurology clinics in the United States prioritize these for reimbursable clinical endpoints, though EMA medical device classification under EU MDR extends European market access timelines by 18-24 months.
- Virtual Reality Modules:Immersive environments integrating eye-tracking sensors for ecologically valid executive function assessment. Japanese METI-funded dementia prevention programs and German neurology departments are piloting these systems, though semiconductor supply concentration in Taiwan and South Korea exposes hardware platforms to allocation volatility.
- Mobile Applications:Direct-to-consumer distribution with adaptive algorithm personalization for engagement retention.
- Customized Solutions:Bespoke protocol development for pharmaceutical research endpoints commanding premium pricing.
- Web-Based Tools:Browser-delivered assessment suites reducing per-evaluation marginal costs for educational deployments.
Established volume favors Software Platforms; emerging adoption favors Virtual Reality Modules.
Application:
Clinical validation requirements and normative database construction costs concentrate investment in applications with clearest reimbursement pathways and pharmaceutical research demand.
- Memory Enhancement:Standardized protocols targeting episodic and working memory decline. Japan's super-aged society and municipal health centers across Germany are expanding institutional procurement, though multi-site trials for normative database construction consume 40-60% of early-stage R&D budgets.
- Executive Function Improvement:Assessment and training of planning, inhibition, and cognitive flexibility. VR-enabled ecological validity is decomposing the historical trade-off between laboratory precision and real-world measurement that constrained flat-screen tools in United States and Japanese neurology departments.
- Attention Training:Sustained and selective attention protocols with real-time difficulty adjustment.
- Problem Solving Skills:Adaptive algorithms for fluid reasoning assessment in educational and occupational contexts.
- Language Development:Verbal fluency and comprehension training with pediatric and aphasic applications.
Reimbursement concentration favors Memory Enhancement; technology disruption favors Executive Function Improvement.
End User:
Buyer power and procurement sophistication vary sharply across clinical, educational, and research environments, compressing price points where enterprise licensing dominates.
- Neurology Clinics:Specialized clinical settings requiring FDA-cleared endpoints and HIPAA technical safeguards. These facilities anchor demand for regulated assessment tools in the United States, though neuropsychologist talent scarcity constrains protocol design capacity.
- Educational Institutions:K-12 and higher education deployments prioritizing engagement metrics and adaptive personalization. Machine learning models adjusting task difficulty in real time improve retention, though procurement concentrates buyer power and compresses margins for standardized modules.
- Geriatric Care Centers:Long-term care and assisted living facilities targeting dementia prevention.
- Rehabilitation Facilities:Post-acute and occupational therapy settings integrating cognitive training into recovery protocols.
- Research Organizations:Pharmaceutical and academic research demanding validated endpoints for clinical trials.
Regulatory premium favors Neurology Clinics; volume scaling favors Educational Institutions.
Deployment:
Cloud-native architectures are fragmenting competitive moats that hardware-dependent and on-premise installations once defended, forcing value proposition rebuilding around data network effects.
- Cloud-Based:SaaS delivery with encrypted data transmission and access control implementations. HIPAA security standards and encryption engineering headcount strain mid-cap development budgets, though reduced marginal costs accelerate deployment across Educational Institutions.
- SaaS:Subscription licensing models with recurring revenue structures. Corporate wellness departments in the United States and Japan negotiate enterprise licenses bundling assessment access with productivity analytics, displacing individual consumer purchases as the dominant channel.
- Hybrid Models:Mixed cloud and local processing for sensitive data retention.
- On-Premise:Local server installation for institutions with restrictive data sovereignty requirements.
- Desktop Installations:Legacy single-license software with limited interoperability.
Recurring revenue concentration favors SaaS; compliance flexibility favors Hybrid Models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across geographies, with educational institutions in Asia-Pacific demanding low per-seat licensing while pharmaceutical research budgets in Western Europe absorb premium endpoints without elasticity.
United States
FDA pre-certification pilots and HIPAA-mandated technical safeguards drive procurement decisions among neurology clinics and hospital systems. The Digital Health Pre-Certification Program accelerates software-as-medical-device pathways, compressing deployment timelines for reimbursable cognitive endpoints. Boston and San Francisco anchor concentrated development clusters where neuropsychologist talent scarcity constrains protocol design capacity.
Germany
The Digital Care Act establishes direct reimbursement codes for prescribed cognitive training applications within statutory health insurance. EU MDR classification timelines extend market access by 18-24 months, forcing vendors to front-load compliance investments. Munich and Heidelberg host neurology departments piloting VR-enabled executive function assessments for ecological validity.
Japan
METI-funded dementia prevention programs expand institutional procurement across municipal health centers in response to super-aged demographic pressures. PMDA software guidance aligns with international harmonization efforts, streamlining pathways for cognitive assessment platforms. Tokyo and Osaka concentrate pilot deployments integrating eye-tracking sensors for attention assessment without verbal response requirements.
United Kingdom
NHS Digital Technology Assessment Criteria shape procurement specifications for cognitive tools entering clinical pathways, emphasizing interoperability and evidence standards. MHRA recognition of FDA-cleared endpoints accelerates parallel market entry for US-developed platforms. London and Cambridge anchor research organization demand for validated pharmaceutical trial endpoints commanding premium pricing.
Canada
Health Canada medical device guidance for software-based cognitive tools creates alignment pressures with FDA determinations, reducing regulatory friction for cross-border vendors. Provincial health authority procurement varies in digital health adoption speed, creating patchwork demand patterns. Toronto and Vancouver concentrate academic medical center pilots for immersive assessment modalities.
Cognitive Assessment and Training Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with regulated clinical trial endpoint developers commanding premium pricing while direct-to-consumer platforms compete on subscriber acquisition efficiency. The vendor base stratifies across three tiers: pharmaceutical research specialists, clinical deployment incumbents, and consumer-facing brain fitness platforms. Archetypes include regulated endpoint developers, SaaS-native assessment providers, and hardware-integrated immersive system builders. Dominant competitive moves center on M&A for normative database assets and strategic partnerships with neurology clinic networks for real-world evidence generation.
Within the regulated clinical research tier, Cambridge Cognition Ltd and Cogstate Ltd exemplify endpoint developers whose pharmaceutical trial positioning anchors premium revenue structures. CogniFit Inc occupies the direct-to-consumer archetype, with subscription models targeting individual brain fitness users and corporate wellness departments. These three companies represent distinct competitive vectors—regulated research services, clinical deployment tools, and mass-market accessibility—rather than overlapping market contestation.
| Leading Market Players |
|---|
| Cambridge Cognition Ltd |
| CogniFit Inc |
| Cogstate Ltd |
| Pearson Clinical Assessment Group |
| BrainCheck, Inc. |
| Cognetivity Neurosciences |
| Lumos Labs, Inc. |
| Posit Science |
| Signant Health |
| Others |
Cost & Logistics Intelligence
Cloud-native SaaS delivery displacing hardware-dependent assessment suites redraws procurement geography toward software engineering clusters while collapsing per-evaluation marginal costs that once sustained premium pricing for instrument-locked vendors. This substitution simultaneously fragments Taiwan-South Korea semiconductor concentration risks and compresses subscription pricing across educational and enterprise segments.
Pricing Analysis
After-sales revenue from enterprise license renewals and normative database updates drives lifetime value for clinical assessment platforms. SaaS-tiered subscription models dominate, with pricing stratifying across FDA-cleared clinical endpoints, ISO 13485-certified diagnostic tools, and unregulated consumer brain fitness tiers. Cost compression in direct-to-consumer tiers intensifies as corporate wellness departments concentrate buyer power through bundled enterprise licensing. Educational institutions exhibit highest price sensitivity; pharmaceutical research organizations show least elasticity for validated trial endpoints.
Supply Chain Analysis
Inbound logistics costs for VR headset processors through transpacific lanes expose hardware-integrated platforms to container allocation volatility and port congestion at Long Beach and Busan. Semiconductor fabrication concentrates in Taiwan and South Korea; cloud infrastructure draws from hyperscaler data center networks across the United States, Germany, and Japan. Single-source vulnerability in gaze-tracking sensor modules creates procurement risk for immersive assessment developers. Distribution runs through direct enterprise sales for clinical deployments and app store marketplaces for consumer applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cognitive assessment market operates as a defensive-moat story where regulatory entrenchment through FDA pre-certification and EU MDR conformity creates years-long lead times that insulate validated endpoint developers from SaaS-native challengers.
For Market Incumbents: Fortify data network effects by deepening normative database assets through multi-site clinical partnerships that compound switching costs for neurology clinics. Accelerate ISO 13485 certification investments ahead of EU MDR amendments to capture extended CE marking timelines that freeze out undercapitalized competitors. Prioritize backward integration into eye-tracking sensor supply to offset Taiwan semiconductor allocation volatility.
For New Entrants and Emerging Players: Anchor in occupational concussion protocols where baseline testing mandates across sports leagues and logistics employers create procurement urgency without entrenched vendor relationships. Target German municipal health centers under Digital Care Act reimbursement codes where statutory insurance payment pathways reduce enterprise sales friction. Pursue white-label platform licensing to corporate wellness departments seeking productivity analytics bundling.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed SaaS assessment providers whose subscriber acquisition costs are rising amid corporate wellness channel saturation. Five-to-ten year viability favors regulated clinical trial endpoint developers with pharmaceutical research revenue concentration. Monitor FDA software-as-medical-device determination timelines as inflection signal for which product categories face heightened compliance burdens versus streamlined pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| Normative Database Acquisition | Multi-site clinical data assets command premium valuation from pharmaceutical trial endpoint developers. |
| FDA Pre-Certification Pathway | Streamlined software-as-medical-device determinations compress deployment timelines for reimbursable cognitive tools. |
| VR-Eye Tracking Integration | Immersive gaze analytics open aphasic and pediatric populations previously excluded from verbal-response protocols. |
| Corporate Wellness Partnership | Enterprise licensing bundles displace individual subscriptions as dominant revenue channel in United States and Japan. |
| EU MDR Compliance Investment | Front-loaded conformity assessment capital creates defensive moat against challengers facing 18-24 month CE marking delays. |
Research Approach
Initial hypotheses were tested against primary input from neurology clinic directors, pharmaceutical trial coordinators, biomedical engineers, and corporate wellness procurement officers and refined through secondary validation against FDA 510(k) filings, EMA medical device registrations, ClinicalTrials.gov endpoint specifications, and hospital GPO contract databases. Bottom-up assessment of deployment volumes across software platforms, VR modules, and mobile applications triangulated with top-down expenditure analysis from METI program budgets and German statutory insurance reimbursement data.
Variance decomposition across the projection horizon isolates segment-level contributions from memory enhancement, executive function improvement, and attention training applications. Modeled dimensions span product type, clinical versus consumer end-use, cloud versus on-premise deployment, and regional regulatory cluster. CAGRs derive from installed base growth rates and average revenue per user trajectories calibrated against historical pharmaceutical research spending patterns and aging demographic projections.
Material uncertainties — FDA software classification determinations, EU AI Act algorithmic risk reclassifications, and semiconductor supply allocation volatility — sit outside the modeled envelope. Forecasts reflect assumptions regarding reimbursement pathway stability and clinical validation burden continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Professional Development and Training
US Life Coaching Market
Professional Development and Training
Leadership Development Program Market
Professional Development and Training
Business Coaching Service Market
Professional Development and Training
North America IT Training Market
Professional Development and Training
Firefighter Simulator Training Services Market
Professional Development and Training
Global Virtual Training and Simulation Market
Professional Development and Training
GCC Soft Skills Training Market
Professional Development and Training
Global Mechatronics and Robotics Courses Market
Professional Development and Training
HR Professional Services Market
Professional Development and Training
Personal Development Market
Professional Development and Training
United States Soft Skills Training Market
Professional Development and Training
Human Resource Professional Services Market
Professional Development and Training
Coding Bootcamp Market
Professional Development and Training
Global Soft Skills Training Market
Professional Development and Training
Global Social and Emotional Learning (SEL) Market
Professional Development and Training
RPA Platform Training Market