
 Cloud Based Language Learning Market | 2026-2036
Cloud Based Language Learning Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Based Language Learning Market Analysis
Corporate procurement fragmentation across mid-sized employers and educational institutions is realigning vendor priorities away from mass-consumer acquisition toward institutional licensing contracts. Duolingo leverages its freemium user base to convert enterprise leads through branded proficiency certifications. Rosetta Stone anchors its position in government and defense language training through long-term institutional partnerships. Babbel competes on European market share with localized curriculum development and GDPR-compliant data architecture.
Cloud based language learning denotes software platforms that deliver structured language instruction through internet-hosted infrastructure, typically incorporating speech recognition APIs, spaced repetition algorithms, and adaptive assessment engines that adjust difficulty in real time based on learner performance metrics. The primary commercial purpose centers on scalable workforce language competency development without physical classroom infrastructure. Self-paced learning modules command the widest user base due to scheduling flexibility, while interactive courses capture higher per-user revenue through live tutor integration and synchronous speaking practice. Mobile learning represents the fastest structural expansion as smartphone-first learners in emerging markets bypass desktop adoption entirely.
The EU AI Act imposes transparency obligations on algorithmic tutoring systems deployed across European member states, compelling platforms to document automated decision-making in proficiency scoring. In the United States, FERPA governs educational records for K-12 and university deployments, while COPPA restricts data collection from users under thirteen. Stakeholders must monitor divergence between regional AI governance frameworks and sector-specific educational privacy laws when architecting cross-border platform deployments.
Market Dynamics
Corporate procurement teams now mandate GDPR-compliant data architecture and algorithmic transparency documentation before signing institutional contracts, forcing platforms to reengineer backend systems for European and North American enterprise sales cycles.
Growth Catalysts
- EU AI Act transparency mandates:European employers require documented decision-making trails for automated proficiency scoring, creating procurement pull for compliant platform vendors.
- Workforce mobility prioritization:Multinational employers redirect training budgets toward scalable English upskilling without physical classroom infrastructure.
- Speech recognition API maturation:Cloud-hosted pronunciation engines now deliver real-time feedback quality sufficient for defense and government certification requirements.
Market Restraints
- Input cost concentration:Premium speech-to-text and natural language processing APIs rely on concentrated hyperscaler infrastructure, creating margin pressure during compute price spikes.
- Regulatory fragmentation:Divergence between FERPA educational record rules in the United States and GDPR data minimization principles in Europe forces redundant compliance architecture.
- Substitution by open-source models:Self-hosted large language models threaten recurring subscription economics for standardized curriculum providers.
Strategic Opportunities
- India smartphone-first learners:Mobile-only user acquisition in tier-2 and tier-3 Indian cities bypasses desktop infrastructure entirely, opening volume markets with lower customer acquisition costs.
- Convergence of adaptive assessment with live tutoring:Platforms blending algorithmic difficulty adjustment with synchronous human conversation capture premium pricing tiers.
- US defense language training contracts:National security agencies maintain dedicated budgets for critical language competency development with multi-year procurement horizons.
Industry Challenges
- Computational linguist talent scarcity:Platform engineering teams struggle to hire specialists capable of building low-resource language models for less commonly taught languages.
- Legacy LMS integration complexity:Enterprise sales cycles extend when procurement requires bidirectional data exchange with entrenched learning management systems from incumbent software vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Based Language Learning Market |
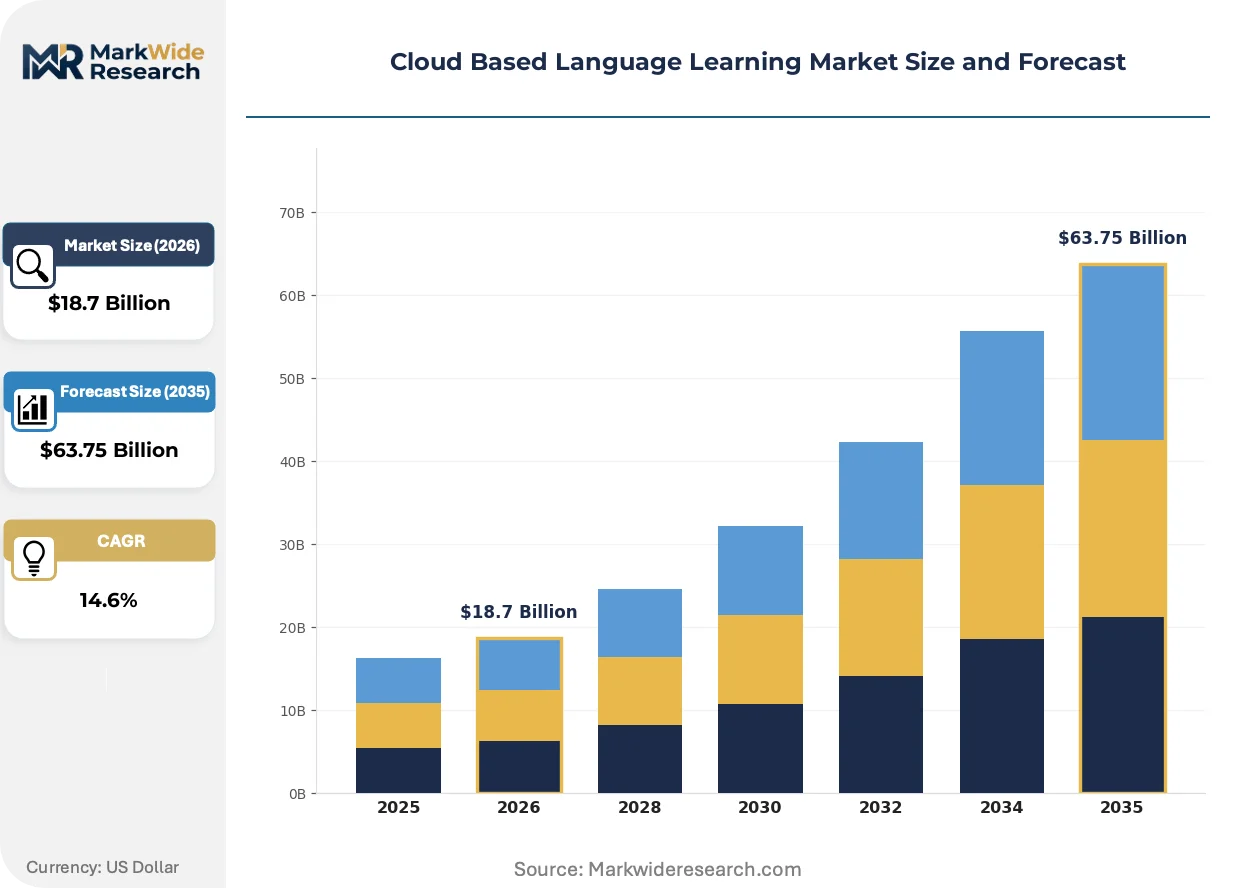
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Model: Video Conferencing, Self-Paced Learning, Interactive Courses, Mobile Learning Target Audience: Students, Professionals, Corporates, Travelers Language Offered: English, Spanish, Mandarin, French Subscription Type: Monthly, Annual, Freemium, Pay-Per-Course |
| Companies Covered | Duolingo, Rosetta Stone, Babbel, EF Education First, Busuu, Sanako Corporation, Memrise, Voxy, Open English, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Based Language Learning Market Emerging Trajectories
Generative AI capabilities are compressing content production timelines and enabling personalized curriculum generation at scale, while regulatory pressure on algorithmic transparency is reshaping how platforms document and disclose tutoring decisions to institutional buyers.
Adaptive assessment engines that adjust difficulty in real time based on learner performance metrics are expanding into high-stakes certification preparation for regulated professions. Medical licensing boards and aviation authorities in Germany and the United States now accept platform-generated proficiency documentation for credentialing purposes. This expansion is compressing the addressable market for traditional in-person testing centers.
The EU AI Act imposes documentation obligations on algorithmic tutoring systems deployed across European member states, compelling platforms to maintain technical files explaining automated proficiency scoring. Industrial consequence includes extended sales cycles as legal teams review compliance attestations. Government and defense segments in France and Germany are most affected, with procurement now requiring third-party algorithmic audits before contract execution.
Enterprise buyers increasingly unbundle live tutor access from base platform subscriptions, purchasing self-paced modules at volume while negotiating separate per-hour rates for synchronous speaking practice. This unbundling disrupts the all-in-one subscription model that dominated consumer marketing. The pattern is most visible in United States corporate training departments, where procurement teams separately evaluate content libraries and human service tiers.
Cloud Based Language Learning Market Segmentation
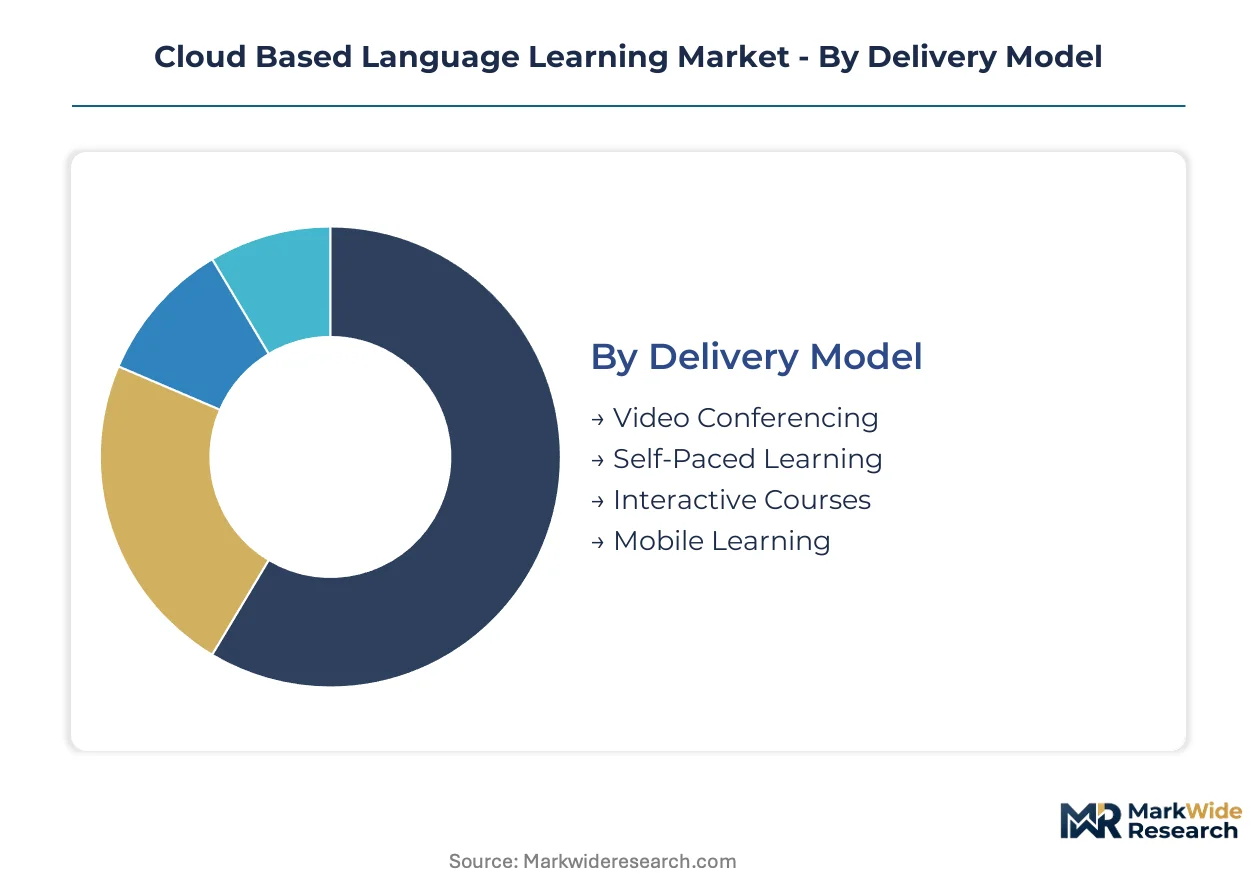
Cloud-based language learning platforms segment across four structural dimensions that determine pricing architecture, customer acquisition costs, and retention economics. Procurement teams evaluate these categories when unbundling content libraries from human service tiers in enterprise contracts.
Delivery Model:
Customization intensity varies from fully automated self-paced modules to synchronous human-tutor integration requiring real-time orchestration infrastructure.
- Video Conferencing:Live synchronous sessions with human instructors demand low-latency infrastructure and scheduling coordination. Corporate training departments in the United States negotiate separate per-hour rates for this tier, unbundling it from base platform subscriptions.
- Self-Paced Learning:Asynchronous modules with spaced repetition algorithms and automated assessment. Demand concentrates among working professionals seeking scheduling flexibility without live coordination overhead.
- Interactive Courses:Blended formats combining pre-recorded content with periodic live checkpoints. Aviation authorities in Germany and medical licensing boards in the United States now accept platform-generated proficiency documentation from this format.
- Mobile Learning:Smartphone-first delivery bypassing desktop infrastructure entirely. Tier-2 and tier-3 Indian cities drive volume acquisition with lower customer acquisition costs.
Leading the category by volume: Self-Paced Learning. Expanding most quickly: Mobile Learning.
Target Audience:
Revenue concentration shifts from mass-consumer acquisition toward institutional licensing as procurement teams mandate GDPR-compliant architecture.
- Students:K-12 and university deployments governed by FERPA educational record rules in the United States. Platforms must architect bidirectional data exchange with entrenched learning management systems.
- Professionals:Individual subscribers seeking credentialing for regulated occupations. Medical and aviation sectors in Germany and the United States accept platform proficiency documentation for licensing.
- Corporates:Enterprise contracts with multi-year procurement horizons and dedicated training budgets. National security agencies maintain critical language competency development programs.
- Travelers:Casual learners prioritizing conversational proficiency over certification. Lower lifetime value but higher conversion velocity from freemium tiers.
Corporate contracts generate the highest per-user revenue. Fastest climb: Professionals segment.
Language Offered:
Curriculum development costs scale with linguistic complexity and regulatory acceptance of proficiency documentation.
- English:Dominant demand driver for workforce mobility programs. Multinational employers redirect training budgets toward scalable upskilling without physical classroom infrastructure.
- Spanish:Second-language priority for United States corporate training and government defense contracts. Platforms compete on speech recognition API quality for pronunciation feedback.
- Mandarin:Critical language designation for national security procurement. Computational linguist talent scarcity constrains low-resource model development.
- French:EU AI Act transparency mandates most visible in French government and defense segments. Procurement requires third-party algorithmic audits before contract execution.
English commands premium subscription volumes. Steepest expansion trajectory: Mandarin.
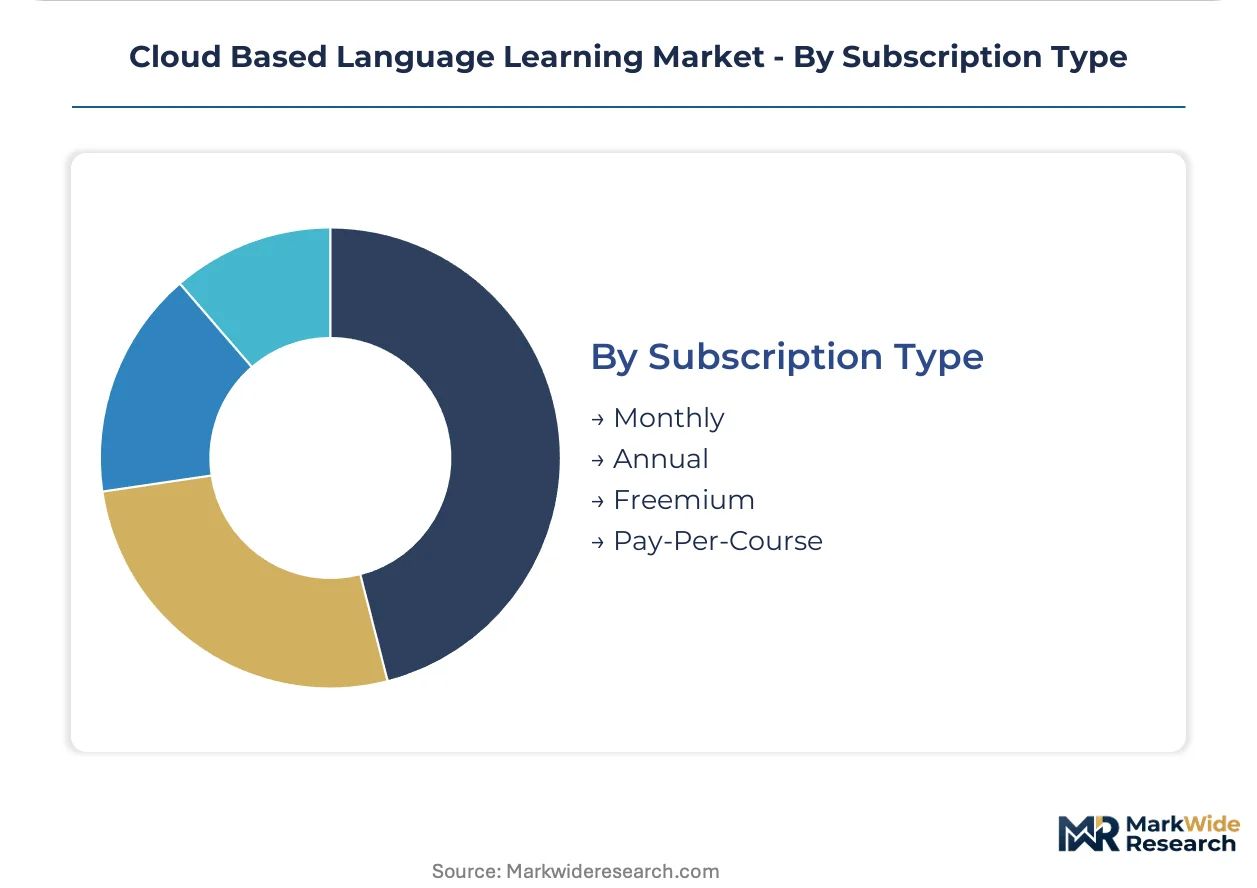
Subscription Type:
Pricing architecture determines customer lifetime value and enterprise sales cycle length.
- Monthly:Short-commitment entry point with higher churn risk. Consumer marketing emphasizes conversion velocity over retention.
- Annual:Prepaid commitment improving cash flow predictability. Enterprise procurement teams prefer this structure for budget planning.
- Freemium:Loss-leader acquisition engine converting enterprise leads through branded proficiency certifications. Duolingo leverages this model for institutional pipeline development.
- Pay-Per-Course:Modular purchasing for specific certification preparation. Medical and aviation credentialing candidates prefer this structure.
Annual subscriptions dominate enterprise procurement. Gaining share fastest: Freemium-to-enterprise conversion pathway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement of English upskilling programs concentrates in the United States, where multinational employers redirect training budgets toward scalable workforce mobility solutions without physical classroom infrastructure.
United States
Federal defense agencies and aviation authorities maintain dedicated budgets for critical language competency development with multi-year procurement horizons. FERPA governs educational records for K-12 and university deployments, while COPPA restricts data collection from users under thirteen. Corporate training departments in Texas and California unbundle live tutor access from base platform subscriptions, negotiating separate per-hour rates for synchronous speaking practice.
Germany
Medical licensing boards and aviation authorities now accept platform-generated proficiency documentation for credentialing purposes, compressing demand for traditional in-person testing centers. The EU AI Act imposes transparency obligations on algorithmic tutoring systems, compelling platforms to document automated decision-making in proficiency scoring. Government and defense segments in Bavaria require third-party algorithmic audits before contract execution.
India
Smartphone-first learners in tier-2 and tier-3 cities bypass desktop infrastructure entirely, opening volume markets with lower customer acquisition costs. The central bank's digital payment infrastructure supports mobile subscription models. Edtech clusters in Bangalore and Hyderabad drive platform localization for regional language instruction beyond English.
United Kingdom
Corporate procurement teams mandate GDPR-compliant data architecture before signing institutional contracts, forcing platforms to reengineer backend systems for enterprise sales cycles. The Information Commissioner's Office enforces algorithmic transparency documentation for automated tutoring recommendations. London-based financial services firms prioritize workforce mobility programs for emerging market expansion.
France
CNIL oversight of AI transparency documentation creates extended sales cycles as legal teams review compliance attestations for government and defense procurement. The EU AI Act mandates technical files explaining automated proficiency scoring for platforms deployed across member states. Paris-based multinational employers prioritize English upskilling for intra-European workforce mobility.
Cloud Based Language Learning Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-native personalization and low-resource language coverage. The vendor base distributes across three maturity tiers: freemium-to-enterprise converters, institutional licensing specialists, and mobile-first volume players. Strategic archetypes include algorithmic assessment developers, live tutor marketplaces, and defense certification providers. Competitive moves concentrate on GDPR-compliant architecture reengineering and unbundled service tiering for enterprise procurement.
Within the freemium-to-enterprise tier, Duolingo leverages branded proficiency certifications to convert institutional leads. Rosetta Stone anchors government and defense positioning through long-term procurement relationships. Babbel exemplifies European market specialization with localized curriculum development and GDPR-compliant data architecture.
| Leading Market Players |
|---|
| Duolingo |
| Rosetta Stone |
| Babbel |
| EF Education First |
| Busuu |
| Sanako Corporation |
| Memrise |
| Voxy |
| Open English |
| Others |
Supply Flow & Price Mechanics
Hyperscaler compute costs for speech-to-text APIs flow downstream through three distinct pricing tiers, with premium live-tutor integrations absorbing margin compression while self-paced modules transfer cost volatility to annual subscription structures. European GDPR compliance architecture and US defense certification requirements add fixed-cost layers that institutional buyers negotiate against volume-based discounts.
Pricing Analysis
Volume concentrates in self-paced annual subscriptions with compressed margins, while premium tiers combining adaptive assessment with synchronous human instruction capture pricing power through unbundled per-hour rates. Price differentiation hinges on certification grade for regulated professions and customization depth for enterprise LMS integration. Pricing pressure stems from open-source large language models threatening standardized curriculum economics. Individual travelers exhibit highest price sensitivity, whereas US defense agencies and multinational corporate procurement show lowest sensitivity due to multi-year budget commitments.
Supply Chain Analysis
India's domestic-content mandates for educational technology procurement are reshaping platform localization requirements, forcing curriculum adaptation for regional language instruction. Upstream cloud infrastructure concentrates in the United States, Ireland, and Singapore, with speech recognition API development anchored in California and Tel Aviv. Raw material dependencies span hyperscaler compute capacity, computational linguist talent pools, and mobile device distribution networks. Single-source vulnerability runs through concentrated natural language processing API providers. Distribution runs through direct-to-consumer app stores and enterprise procurement channels with extended legal review cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational linguist talent scarcity constrains low-resource language model development, propping pricing for Mandarin and critical language certification tiers above mass-market English instruction.
For Market Incumbents: Anchor defense and government positioning through long-term institutional partnerships with multi-year procurement horizons, while investing in backward integration into proprietary speech recognition engines to reduce hyperscaler API dependency. Open-source large language models pose substitution threats to standardized curriculum economics; counter through certification-grade assessment engines accepted by medical licensing boards and aviation authorities. For New Entrants and Emerging Players: Mobile network operators in tier-2 and tier-3 Indian cities offer channel partnerships with pre-integrated subscription billing, bypassing customer acquisition cost barriers that constrain desktop-first platforms. White-space targets include smartphone-first learners in emerging markets and blended adaptive-live formats for professional certification. Pursue regulatory sandbox positioning under EU AI Act transparency frameworks to accelerate enterprise sales cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor algorithmic assessment developers with existing certification acceptance in Germany and the United States, where medical and aviation credentialing creates defensive moats. Long-term viability hinges on platforms combining GDPR-compliant architecture with defense procurement relationships. Watch for hyperscaler compute price spikes as margin compression inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with Enterprise LMS | Bidirectional data exchange with SAP and Oracle systems compresses sales cycles for corporate procurement teams. |
| Acquisition of Computational Linguist Talent | Low-resource Mandarin and Arabic model development requires specialized expertise concentrated in Tel Aviv and Bangalore clusters. |
| Strategic Partnership with Mobile Network Operators | Pre-integrated billing in Indian tier-2 cities reduces customer acquisition costs below desktop-first competitor benchmarks. |
| Geographic Expansion into Defense Certification | US national security agency contracts provide multi-year revenue visibility with algorithmic audit requirements. |
| Product Launch of Unbundled Service Tiers | Separate pricing for self-paced modules and live tutor access aligns with corporate procurement unbundling patterns. |
Methodological Framework
Multi-period observation of enterprise procurement cycles, mobile subscription conversion rates, and defense contract award patterns anchored the trend analysis, supplemented by interviews with platform engineering directors, corporate training procurement managers, computational linguists, and regulatory compliance officers. Secondary validation drew from SEC filings of publicly traded edtech platforms, EU AI Act implementation guidance documents, FERPA compliance attestations, and hyperscaler capex disclosures. Bottom-up triangulation across subscription revenue models and top-down validation against institutional licensing contract values converged on segment-level estimates.
Input-output matrices mapped speech recognition API costs, computational linguist salary benchmarks, and mobile customer acquisition spend against subscription tier pricing and enterprise contract values across the projection horizon. Segmentation dimensions modeled include delivery model automation intensity, target audience regulatory exposure, language complexity tier, and subscription commitment structure. CAGRs were derived from trend extrapolation of procurement cycle lengths and mobile penetration curves, with sensitivity testing against open-source model substitution scenarios and hyperscaler pricing volatility.
Caveats apply where EU AI Act enforcement intensity, US defense budget reallocation, or open-source large language model capability jumps could materially shift the outlook. Forecasts reflect assumptions about certification authority acceptance rates and enterprise procurement unbundling velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Language Learning and Training
Digital English Learning Market
Language Learning and Training
Language Learning Games Market
Language Learning and Training
Vocational English Course Counselling Solution Market
Language Learning and Training
Language Learning Software Market
Language Learning and Training
Online Language Learning Market
Language Learning and Training
Global Digital English Language Learning Market
Language Learning and Training
English Learning for Children Market
Language Learning and Training
Global Language Service Market
Language Learning and Training
Bilingual Education for Children Market
Language Learning and Training
English Learning App Market