
 China Smart Building Market | 2026-2036
China Smart Building Market Size, Share, and Industry Trends Forecast 2026-2036
China Smart Building Market Analysis
China's dual carbon goals are restructuring demand across the built environment, forcing developers to embed energy management systems and IoT-enabled infrastructure from project conception. Johnson Controls leverages its deep portfolio of building automation hardware to anchor premium commercial contracts in tier-one cities. Huawei Technologies competes through proprietary edge-computing platforms that integrate 5G connectivity with real-time environmental monitoring. Siemens differentiates by controlling the full digital twin workflow from design through operations, sustaining repeat engagement with state-owned developers.
China smart buildings integrate sensor networks, automated environmental controls, and digital management platforms to optimize energy consumption, occupant comfort, and operational security across commercial, residential, and industrial structures. The systems typically operate through centralized building management platforms processing data from distributed IoT endpoints with response latencies under 100 milliseconds for critical climate and safety functions. Cloud-based deployment captures the fastest expansion as municipal governments prioritize centralized oversight of public building portfolios, while building automation technology leads current revenue contribution due to mature HVAC control markets. Energy management systems represent the emerging margin pool as time-of-use electricity pricing spreads across Chinese provinces and tenants demand utility transparency.
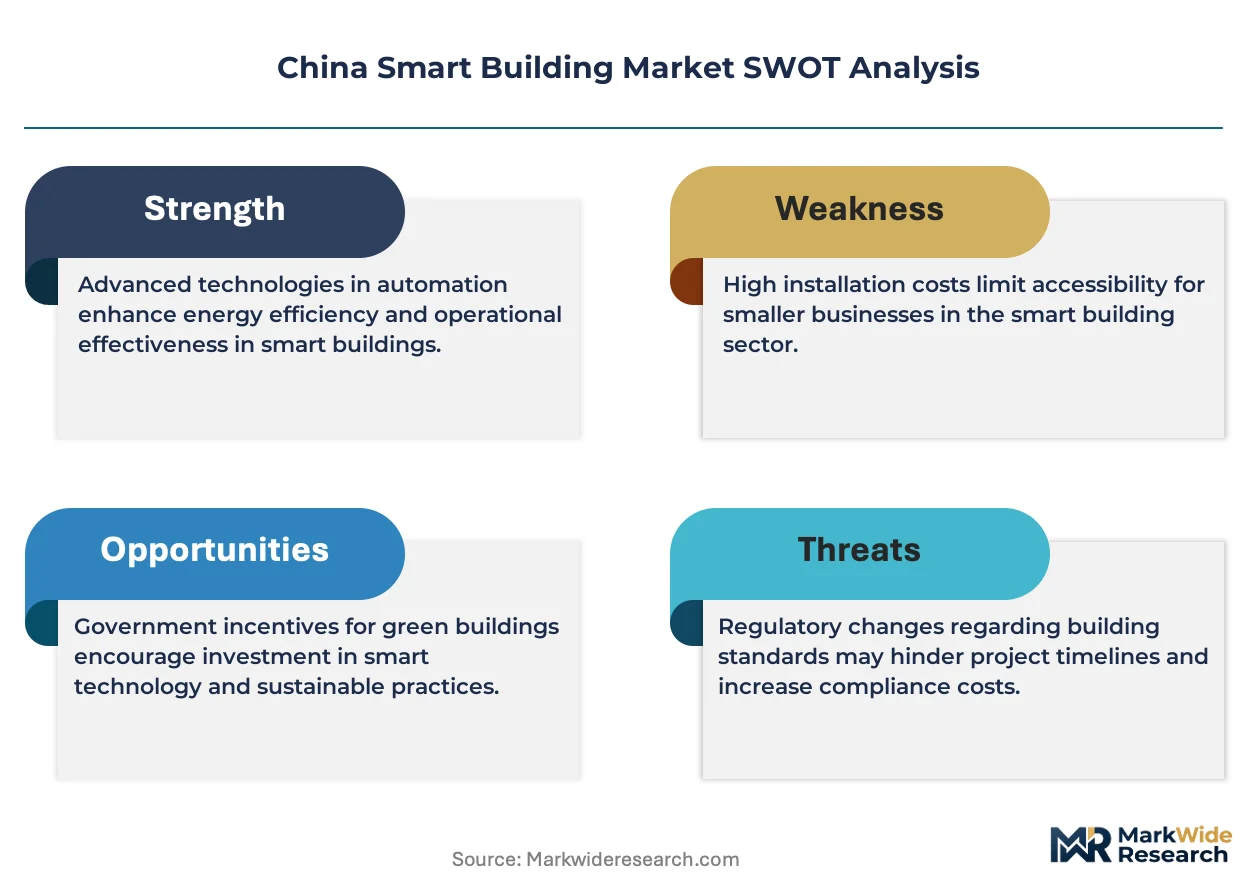
China's Ministry of Ecology and Environment enforces carbon intensity benchmarks that directly shape building retrofit timelines and new construction permit approvals, while MIIT's GB standards mandate interoperability protocols for connected building devices. The national dual carbon framework is tightening compliance windows, forcing equipment suppliers to certify against evolving efficiency tiers or face exclusion from state-funded projects. Stakeholders must monitor how municipal implementation variance between Beijing, Shanghai, and Shenzhen creates fragmented procurement requirements that favor locally certified system integrators over standardized national offerings.
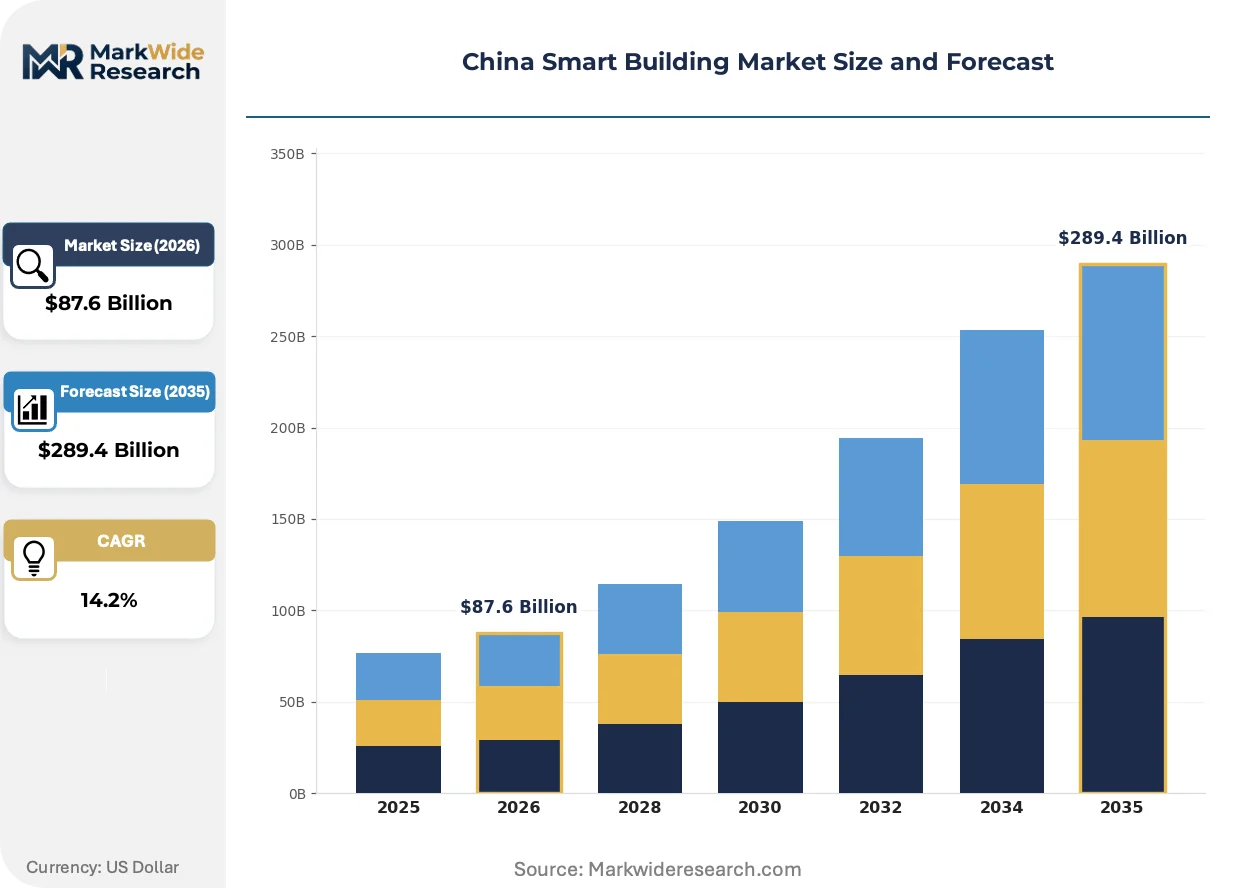
Market Dynamics
China's dual carbon framework is compressing retrofit timelines and forcing building automation vendors to recertify equipment against escalating efficiency tiers before state-funded project eligibility expires.
Growth Catalysts
- MIIT GB Standards Mandate:Interoperability protocols for connected building devices now required in all new commercial construction permits across tier-one municipalities.
- Time-of-Use Electricity Pricing:Provincial grid reforms in Jiangsu and Guangdong create immediate payback visibility for energy management system investments by commercial landlords.
- Shanghai Green Building Certification:Municipal mandates require LEED-equivalent ratings for developments exceeding 20,000 square meters, embedding IoT infrastructure from architectural conception.
Market Restraints
- Semiconductor Input Volatility:Edge-computing controllers and sensor microcontrollers face supply concentration risk from Taiwan and South Korea foundries, compressing hardware margins.
- Legacy HVAC Integration Friction:Existing pneumatic control systems in pre-2010 commercial stock require costly gateway retrofitting, slowing upgrade cycles in secondary cities.
- Local Certification Fragmentation:Beijing, Shanghai, and Shenzhen maintain non-harmonized testing requirements for building automation products, forcing vendors to maintain three parallel compliance tracks.
Strategic Opportunities
- Chengdu-Chongqing Corridor:Western China infrastructure investment is accelerating smart building deployment in logistics hubs and data centers underserved by tier-one system integrators.
- Digital Twin Convergence:BIM-to-operations platform integration enables predictive maintenance contracts that extend vendor engagement beyond construction completion.
- Carbon Trading Linkage:Shanghai and Shenzhen emissions exchanges allow verified building efficiency gains to generate tradeable credits, creating new revenue streams for facility managers.
Industry Challenges
- Systems Integration Talent Gap:Shortage of engineers certified across HVAC, electrical, and IT disciplines delays commissioning timelines and inflates implementation costs.
- Multi-Vendor Cybersecurity Certification:MIIT's evolving network security assessments for IoT devices create compliance backlogs, particularly for imported sensor hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Smart Building Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $289.4 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Technology: IoT Devices, Energy Management Systems, Building Automation, Security Solutions End User: Residential, Commercial, Industrial, Government Service Type: Consulting, Integration, Maintenance, Training |
| Companies Covered | Johnson Controls, ABB, Huawei Technologies, IBM, Cisco, Siemens, Honeywell International, Hitachi, Schneider Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Smart Building Market Emerging Trajectories
Edge-native architectures are displacing cloud-dependent building management, slashing response latencies for climate control while municipal oversight demands retain centralized data aggregation.
Digital twin technology is integrating real-time sensor feeds with thermal simulation models, enabling predictive HVAC load balancing. State-owned developers in Beijing and Shenzhen are mandating twin handover protocols for all new commercial projects above 50,000 square meters. This convergence is compressing commissioning timelines and locking automation vendors into decade-long service contracts.
China's Ministry of Ecology and Environment is tightening carbon intensity benchmarks for commercial building operations, directly linking permit renewals to verified emissions reductions. Property managers in Shanghai must now submit quarterly efficiency audits or face lease registration suspensions. The policy is accelerating replacement of pneumatic controls with direct digital control systems in Class A office stock.
Facility management procurement is consolidating under integrated service contracts that bundle hardware, software, and energy optimization guarantees. Large commercial landlords in Shenzhen and Guangzhou are shifting from capital expenditure models to performance-based agreements where vendors retain equipment ownership. This restructuring favors automation suppliers with captive financing capabilities and long-term balance sheet capacity.
China Smart Building Market Segmentation
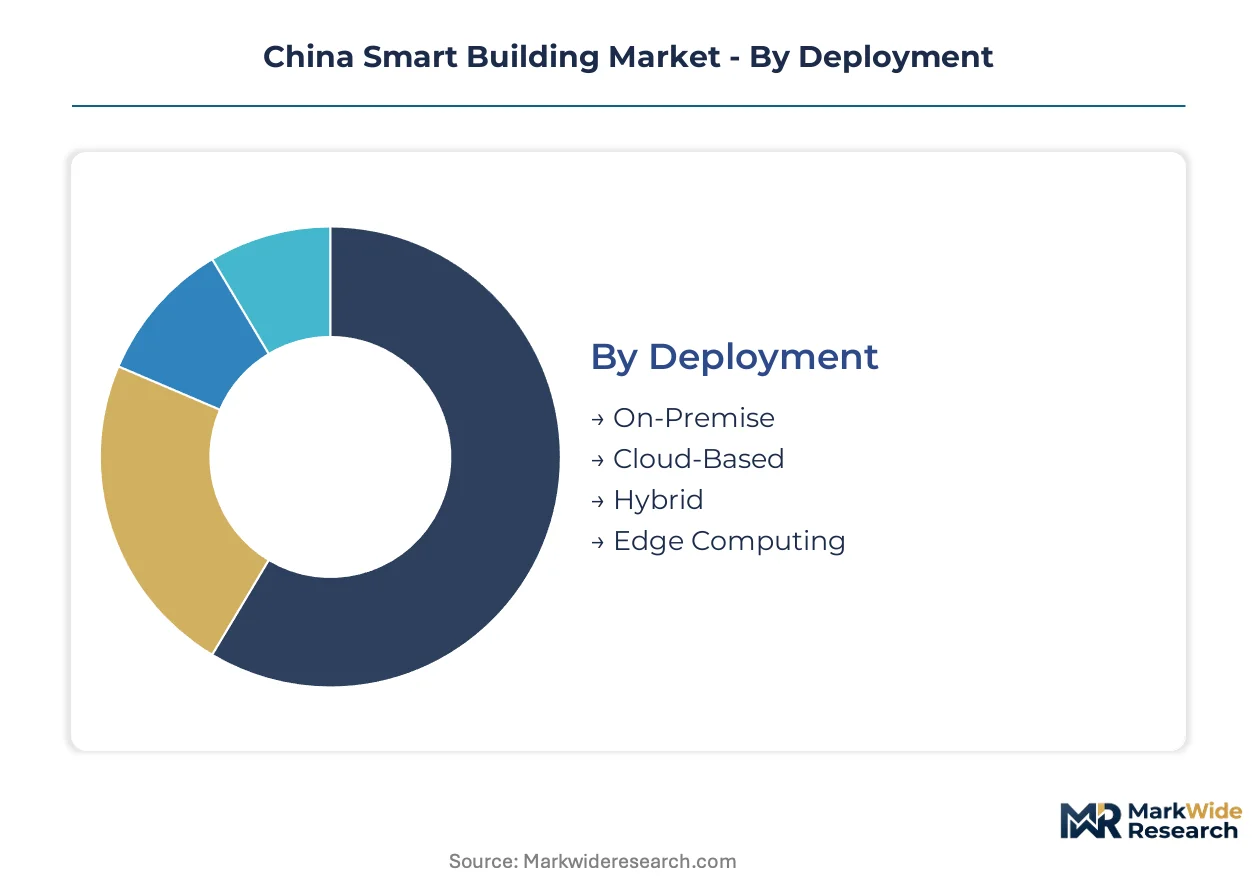
Smart building procurement in China fragments across deployment architectures, technology stacks, end-use verticals, and service models. Understanding these axes clarifies where MIIT GB standards apply, how dual carbon compliance costs distribute, and which vendor capabilities align with municipal mandates in tier-one cities.
Deployment:
Deployment architecture determines latency performance, data sovereignty compliance, and capital intensity for building operators across Shanghai, Beijing, and Shenzhen.
- Cloud-Based:Centralized data aggregation platforms enable municipal governments to monitor public building portfolios through unified dashboards. Shanghai's urban management bureau mandates cloud connectivity for all new commercial developments exceeding 50,000 square meters to enable real-time carbon intensity tracking.
- Edge Computing:On-site processing nodes slash response latencies below 100 milliseconds for critical climate and safety functions. Shenzhen's data center operators are deploying edge-native building management to support AI-driven cooling optimization without cloud dependency.
- On-Premise:Legacy server installations persist in government facilities with strict data localization requirements under China's cybersecurity law.
- Hybrid:Architectures combining local processing with cloud analytics serve commercial landlords seeking operational autonomy alongside centralized reporting capabilities.
Cloud-based deployment leads on scale; edge computing leads on momentum.
Technology:
Technology segments map directly to efficiency tier certifications and retrofit incentive eligibility under MEE carbon intensity benchmarks.
- Building Automation:HVAC control systems, lighting management, and access control hardware constitute the revenue foundation. Mature markets in Shanghai and Beijing concentrate demand for direct digital control retrofits replacing pre-2010 pneumatic systems in Class A office stock.
- Energy Management Systems:Software platforms optimizing consumption against time-of-use electricity pricing capture expanding margins as Jiangsu and Guangdong provincial grids reform rate structures. Commercial landlords in Guangzhou now require tenant-level utility transparency.
- IoT Devices:Sensor networks and connected endpoints feed data streams to centralized platforms. MIIT GB standards mandate interoperability protocols for all new commercial construction permits.
- Security Solutions:Integrated surveillance, access control, and cybersecurity hardening address multi-vendor IoT certification requirements under evolving network security assessments.
Building automation leads on scale; energy management systems lead on momentum.
End User:
End-user verticals concentrate procurement authority differently, shaping vendor engagement models and contract structures.
- Commercial:Office towers, retail complexes, and hospitality assets drive premium system integration. State-owned developers in Beijing mandate digital twin handover protocols for projects above 50,000 square meters.
- Government:Public facilities and municipal buildings face the strictest cloud connectivity mandates for centralized oversight. Procurement favors locally certified system integrators.
- Industrial:Manufacturing facilities and logistics hubs in the Chengdu-Chongqing corridor deploy smart building technology for energy-intensive process cooling and environmental controls.
- Residential:High-rise apartment complexes integrate basic automation for property management efficiency, though retrofit penetration lags commercial stock.
Commercial leads on scale; government leads on momentum.
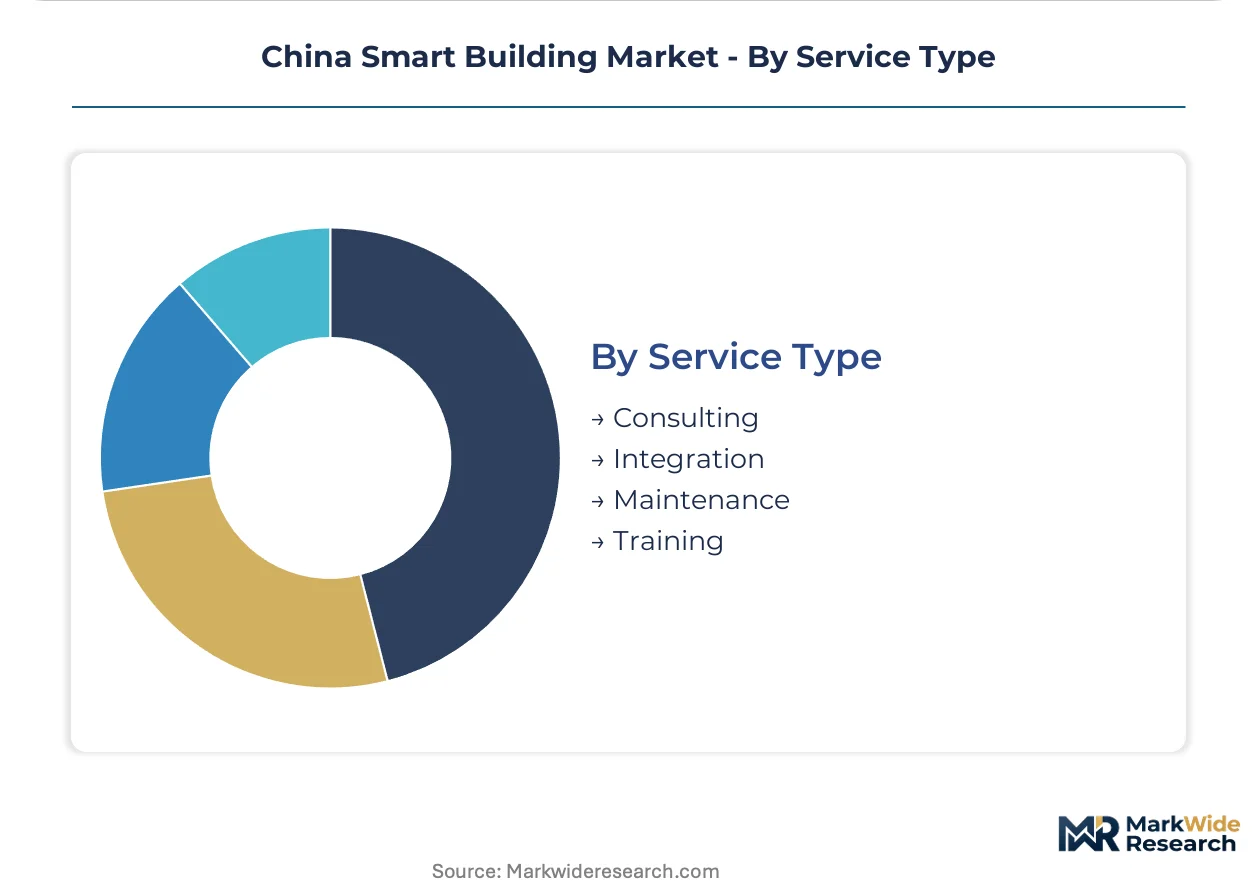
Service Type:
Service models are restructuring from capital expenditure to performance-based contracts, altering vendor balance sheet requirements.
- Integration:System commissioning and multi-vendor coordination commands premium pricing due to certified engineer scarcity across HVAC, electrical, and IT disciplines.
- Maintenance:Long-term service contracts extend vendor engagement beyond construction completion, particularly for digital twin-enabled predictive maintenance offerings.
- Consulting:Advisory services guide developers through green building certification processes and carbon trading linkage strategies in Shanghai and Shenzhen emissions exchanges.
- Training:Knowledge transfer programs address talent gaps in building operations, though procurement typically bundles this within larger integration contracts.
Integration leads on scale; maintenance leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's smart building industry originated in the Yangtze River Delta during the early 2000s, when Shanghai developers first integrated imported building automation systems into Class A commercial towers. The sector now distributes across five distinct economic clusters, each shaped by municipal carbon mandates and local certification requirements.
Yangtze River Delta
Shanghai anchors the nation's largest smart building procurement volume, driven by municipal green building mandates for developments exceeding 20,000 square meters. The Shanghai Municipal Commission of Housing and Urban-Rural Development enforces LEED-equivalent certification standards that embed IoT infrastructure from architectural conception. Suzhou and Hangzhou secondary cities are replicating Shanghai's cloud connectivity requirements for public building portfolios.
Pearl River Delta
Shenzhen and Guangzhou concentrate demand for edge-computing building management in data centers and logistics facilities. Guangdong Provincial Development and Reform Commission's time-of-use electricity pricing reforms create immediate payback visibility for energy management system investments. The Shenzhen emissions exchange allows verified building efficiency gains to generate tradeable carbon credits for facility managers.
Beijing-Tianjin-Hebei
State-owned developers in Beijing mandate digital twin handover protocols for commercial projects above 50,000 square meters. Beijing Municipal Ecology and Environment Bureau enforces carbon intensity benchmarks that directly shape building retrofit timelines and new construction permit approvals. Tianjin's port logistics hubs are deploying smart environmental controls for cold chain warehouses.
Sichuan-Chongqing
Western China infrastructure investment is accelerating smart building deployment in manufacturing facilities and data centers underserved by tier-one system integrators. Chongqing Municipal Commission of Economy and Information Technology offers retrofit incentives for industrial building automation upgrades. Chengdu's expanding airport logistics zone requires integrated building management for temperature-sensitive cargo facilities.
Shandong Peninsula
Qingdao and Jinan municipal governments are extending green building certification requirements to mid-scale commercial developments following tier-one precedents. Shandong Provincial Energy Bureau mandates energy management system installation in public buildings exceeding 10,000 square meters. Weihai's marine equipment manufacturing clusters are adopting process cooling automation to meet provincial efficiency tiers.
China Smart Building Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across China's smart building sector. The vendor base organizes into three tiers: multinational conglomerates with full building automation portfolios, domestic technology groups leveraging proprietary edge-computing platforms, and specialized system integrators certified to municipal compliance tracks. Strategic differentiation centers on digital twin workflow control and long-term service contract capture. Competitive moves concentrate on vertical integration into financing capabilities and geographic expansion into western corridor infrastructure projects.
Within the multinational tier, Johnson Controls and Siemens occupy positions anchored by decades of building automation hardware deployment in tier-one commercial towers. Huawei Technologies exemplifies the domestic technology archetype, competing through integrated 5G-edge computing platforms that reduce climate control response latencies. Schneider Electric and ABB sit within the European industrial automation tradition, sustaining engagement with state-owned developers through certification alignment with evolving MIIT GB standards.
| Leading Market Players |
|---|
| Johnson Controls |
| ABB |
| Huawei Technologies |
| IBM |
| Cisco |
| Siemens |
| Honeywell International |
| Hitachi |
| Schneider Electric |
| Others |
Supply Flow & Price Mechanics
Captive integration into sensor microcontroller production anchors both supply security and pricing power for building automation vendors serving tier-one Chinese municipalities. Johnson Controls and Huawei Technologies maintain in-house fabrication partnerships that insulate margins against Taiwan foundry volatility while MIIT GB certification costs flow through to premium-tier contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates LEED-equivalent certified systems from basic automation packages. Price differentiation centers on MIIT GB interoperability certification and digital twin capability bundling. Cost compression in economy-tier HVAC retrofits is intensifying because legacy pneumatic gateway requirements inflate implementation labor. State-owned developers in Beijing show least price sensitivity; secondary-city commercial landlords in Shandong Peninsula exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for edge-computing controllers and sensor microcontrollers. Raw material dependencies span silicon wafers, rare earth magnets for motor drives, and copper for power distribution infrastructure. Tariff exposure on imported semiconductor components creates procurement timing risk for project-based contracts. Distribution runs through municipal-certified system integrators who maintain parallel compliance tracks across Beijing, Shanghai, and Shenzhen testing protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China smart building market reads as a late-cycle quality story where municipal green building mandates are compressing procurement toward LEED-equivalent specifications and digital twin handover protocols.
For Market Incumbents: Lock in long-term service contracts through predictive maintenance offerings that extend vendor engagement beyond construction completion. Deepen backward integration into edge-computing controller production to offset Taiwan foundry concentration risk. Certification investment in evolving MIIT GB standards represents the critical defensive lever against emerging domestic technology competitors. For New Entrants and Emerging Players: Capture white-space opportunity in Chengdu-Chongqing corridor logistics hubs where tier-one system integrator presence remains thin. The Sichuan-Chongqing industrial building automation segment shows lowest competitive density and highest retrofit incentive availability. Go-to-market through provincial equipment financing partnerships unlocks performance-based contract structures without captive balance sheet requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where systems integration talent scarcity inflates commissioning timelines and implementation costs. Five-to-ten-year viability favors vendors with integrated financing capabilities and municipal certification breadth across multiple tier-one cities. Watch Shanghai emissions exchange trading volume as inflection indicator for carbon-credit-linked facility management contract proliferation.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Enables predictive maintenance contracts that lock vendors into decade-long service engagements with state-owned developers. |
| MIIT GB Certification Investment | Mandates interoperability protocols for all new commercial construction permits across tier-one municipalities. |
| Edge-Computing Controller Production | Reduces climate control response latencies below 100 milliseconds while insulating margins against Taiwan foundry volatility. |
| Performance-Based Contract Expansion | Aligns vendor revenue with verified energy savings as landlords shift from capital expenditure to operational expenditure models. |
| Chengdu-Chongqing Geographic Expansion | Captures western China infrastructure investment in logistics hubs and data centers underserved by established tier-one integrators. |
Methodological Framework
Direct dialogue with building automation hardware engineers, municipal procurement officers in Shanghai and Shenzhen, facility management directors at commercial landlords, and systems integration specialists informed qualitative grounding. Secondary validation drew from MIIT GB standard filings, Shanghai Municipal Commission of Housing and Urban-Rural Development permit databases, China Securities Regulatory Commission disclosures from listed construction firms, and provincial energy bureau retrofit incentive records. Bottom-up project pipeline analysis triangulated against top-down municipal construction permit forecasts.
Segment-level projections across deployment architecture, technology stack, end-use vertical, and service model dimensions were generated through the analytical framework. CAGRs were derived from fitted adoption curves against historical green building certification penetration rates and time-of-use electricity pricing reform implementation timelines. Model inputs included municipal carbon intensity benchmark tightening schedules and semiconductor supply lead time assumptions.
MEE regulatory enforcement variance, Taiwan semiconductor supply disruptions, and municipal certification harmonization delays are the dominant revision risks. Forecasts reflect assumptions about continued dual carbon policy commitment and tier-one city green building mandate expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Germany Manufactured Homes Market
Real Estate
E House Market
Real Estate
Asia-Pacific Self Storage Market
Real Estate
ASEAN Condominiums and Apartments Market
Real Estate
Mexico Residential Real Estate Market
Real Estate
Asia Pacific Flexible Office Market
Real Estate
Japan Condominiums and Apartments Market
Real Estate
Vietnam Facility Management Market
Real Estate
South Africa Residential Real Estate Market
Real Estate
Australia Facility Management Market
Real Estate
North America Coworking Spaces Market
Real Estate
Latin America Residential Real Estate Market
Real Estate
Bahrain Facility Management Market
Real Estate
Spain Residential Real Estate Market
Real Estate
Luxury-Minded Retirement Residences Market
Real Estate
Asia Pacific Facility Management Market